
 Radio Frequency Integrated Circuit (RFIC) Market | 2026-2036
Radio Frequency Integrated Circuit (RFIC) Market Size, Share, and Industry Trends Forecast 2026-2036
Radio Frequency Integrated Circuit (RFIC) Market Analytics
Market Context with Strategic Players
Foundry capacity in Taiwan and South Korea is restructuring the competitive map for RFIC sourcing. Qualcomm Technologies Inc. leverages its modem-RF platform integration to dominate premium smartphone slots. Qorvo Inc. anchors defense and aerospace programs with GaN process leadership. Broadcom Inc. sustains Wi-Fi 6E and 7 front-end module share through captive design rules.
Technical Definition and Structural Segments
Radio Frequency Integrated Circuits are monolithic or multi-chip assemblies that process signals from 3 kHz to 300 GHz, typically fabricated on GaAs, GaN, SiGe, or advanced CMOS nodes with feature sizes below 7nm for consumer-grade transceivers. These devices perform amplification, frequency conversion, filtering, and oscillation in wireless communication chains from cellular handsets to phased-array radar. Power Amplifiers command the largest revenue pool due to thermal and linearity requirements in 5G macro infrastructure, while GaN-on-SiC technology is displacing legacy LDMOS in base station transmitters. Consumer Electronics applications remain volume-heavy though margin-diluted, whereas Automotive radar RFICs are emerging as a high-growth pocket driven by 77-81 GHz sensor proliferation.
Regulatory Frame and Forward Outlook
FCC spectrum auctions in the United States, EU Radio Equipment Directive compliance mandates, and China's MIIT 5G mid-band allocation rules are collectively tightening emission mask and power efficiency requirements. REACH substance restrictions and RoHS lead-free solder directives in Europe are forcing material transitions in packaging and die-attach metallurgy. Stakeholders must monitor foundry node roadmaps against spectrum reallocation timelines to avoid stranded capacity commitments.
Market Dynamics
Foundry consolidation in Taiwan and South Korea is compressing RFIC supply elasticity, while 3nm process migration at TSMC and Samsung Foundry is absorbing disproportionate capex allocations from fabless designers.
Growth Catalysts
- MIIT 5G Mid-Band Allocation:China's spectrum releases are accelerating base station buildouts and GaN-on-SiC power amplifier procurement for macro infrastructure.
- Automotive Radar Proliferation:77-81 GHz sensor mandates in advanced driver-assistance systems are pulling silicon-germanium and CMOS beamforming chips into high-volume production.
- REACH Material Transitions:European substance restrictions are forcing packaging metallurgy shifts that favor advanced laminate substrates over legacy ceramic.
Market Restraints
- GaN Substrate Scarcity:Limited 6-inch SiC wafer supply from Wolfspeed and Coherent concentrates power amplifier sourcing risk.
- Dual-Use Export Controls:US Bureau of Industry and Security restrictions on GaN HEMT technology are fragmenting defense-qualified supplier bases.
- LDMOS Stranded Capacity:Legacy silicon LDMOS fab lines face utilization collapse as base station OEMs migrate transmit chains to wide-bandgap semiconductors.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for telecom equipment are attracting RFIC packaging and test investments to Gujarat and Tamil Nadu clusters.
- Satellite Direct-to-Device:L-band and S-band RF front-ends for low-earth orbit connectivity represent unpenetrated volume for multi-mode transceiver suppliers.
- EU CSRD Reporting:Corporate sustainability disclosure requirements are creating preference premiums for foundries with verified carbon accounting.
Industry Challenges
- Millimeter-Wave Test Capacity:Automated probe stations for 28 GHz and 39 GHz characterization face 18-month lead times, throttling new product introduction cycles.
- IP Licensing Thickets:Essential patent pools for 5G NR modulation schemes are elevating royalty stacks for integrated modem-RF platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radio Frequency Integrated Circuit (RFIC) Market |
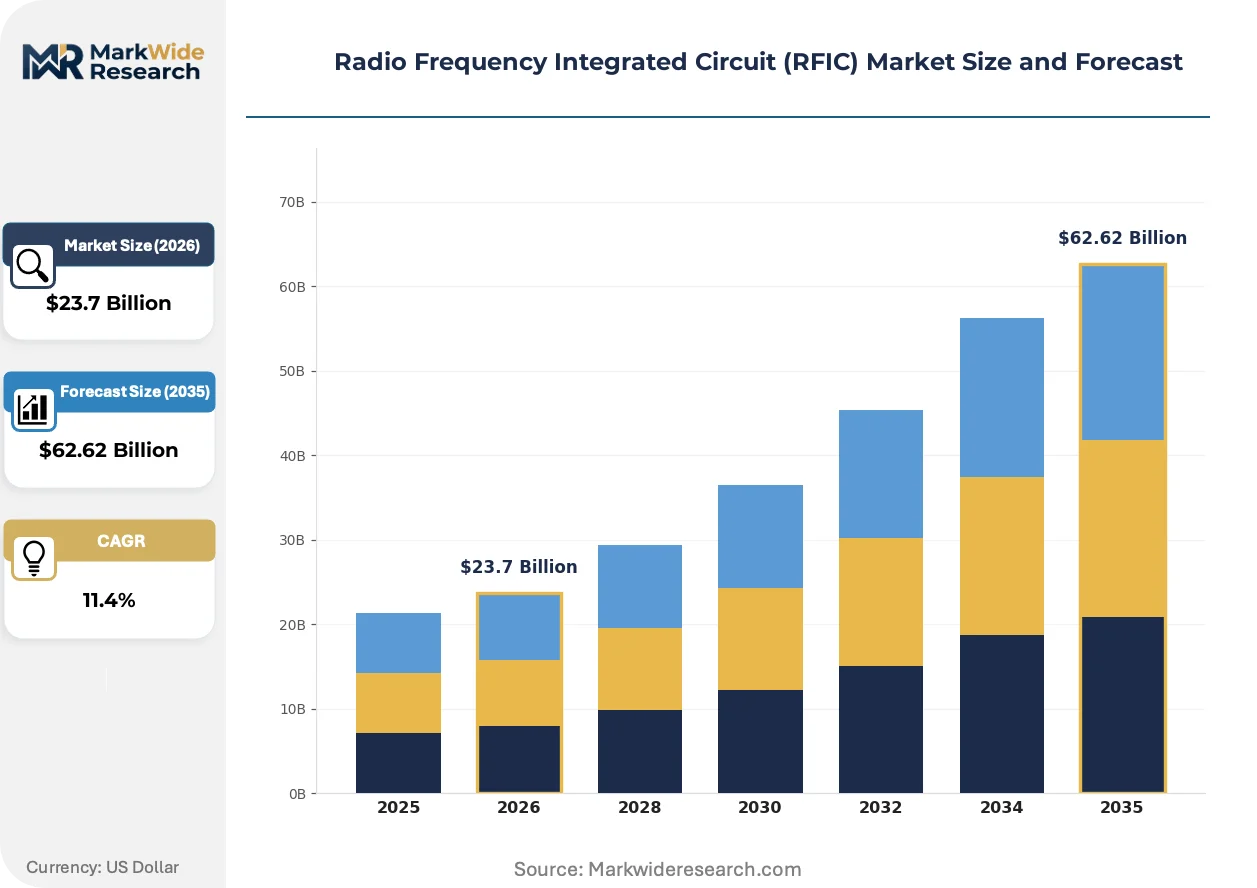
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Amplifiers, Low Noise Amplifiers, Mixers, Oscillators Technology: GaN, GaAs, CMOS, SiGe Application: Telecommunications, Consumer Electronics, Automotive, Aerospace End User: Telecom Operators, Electronics Manufacturers, Automotive OEMs, Defense Contractors |
| Companies Covered | Infineon Technologies AG, Murata Manufacturing Co., Ltd., Qualcomm Technologies Inc., Analog Devices Inc., NXP Semiconductors, Broadcom Inc., Qorvo Inc., STMicroelectronics, Skyworks Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radio Frequency Integrated Circuit (RFIC) Market Evolving Landscape
Process-node compression and spectrum reallocation are forcing simultaneous redesigns of die architecture and packaging, collapsing traditional development timelines.
Silicon-germanium BiCMOS is absorbing mid-band 5G massive MIMO slot demand from compound semiconductors through cost-optimized 16-element beamformer integration. Base station OEMs in Europe and North America are qualifying SiGe for sub-6 GHz arrays. This migration is absorbing share from GaAs pHEMT in applications below 7 GHz.
EU RoHS recast directives are tightening cadmium and lead exemptions in high-reliability RF modules, forcing die-attach material substitutions. Aerospace and defense contractors face qualification retesting for space-qualified hybrids. Suppliers are responding with gold-tin and sintered silver interconnects to maintain thermal cycling performance.
Consolidated procurement by tier-one smartphone OEMs is compressing RF front-end vendor margins through annual price-down mandates and exclusive supply agreements. Module suppliers are responding with design-win bundling across low-band, mid-band, and ultra-wideband channels. China-based handset makers are driving the most aggressive consolidation of qualified vendor lists.
Radio Frequency Integrated Circuit (RFIC) Market Segmentation
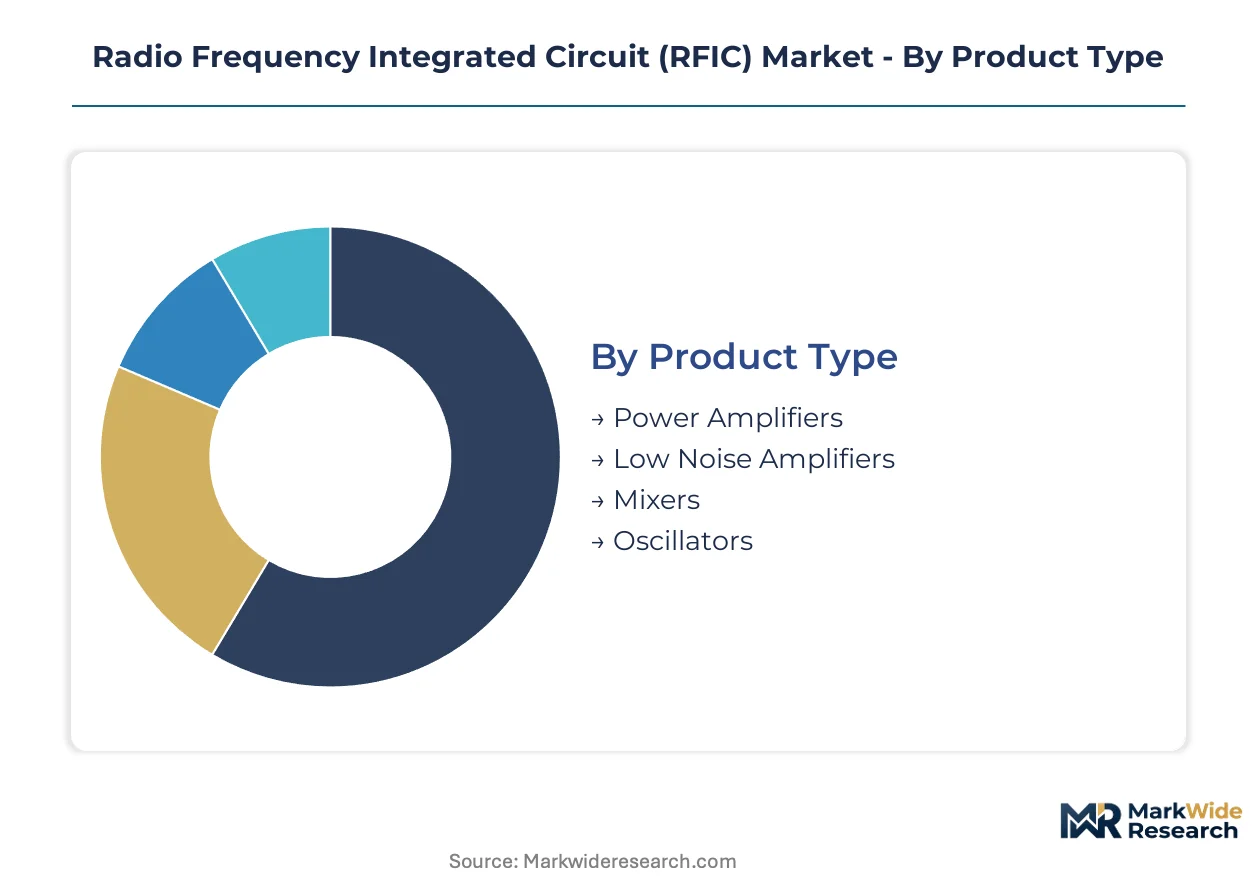
RFIC procurement patterns diverge sharply across product architectures, foundry technologies, and end-use reliability requirements. Segmentation reveals where GaN-on-SiC commands premium positioning versus where silicon CMOS achieves cost dominance through scale.
Product Type:
Standardization dominates in high-volume handset slots while customization concentrates in base station transmit chains and defense phased arrays.
- Power Amplifiers:GaN HEMT and LDMOS architectures handle watt-level output in macro infrastructure, with thermal management dictating package selection. China MIIT 5G mid-band buildouts are absorbing elevated volumes of GaN-on-SiC variants for 64T64R massive MIMO arrays, constrained by Wolfspeed and Coherent 6-inch substrate availability.
- Low Noise Amplifiers:pHEMT and SiGe BiCMOS designs achieve sub-1 dB noise figures for receive chains in radar and satellite terminals. Automotive 77-81 GHz sensor proliferation is pulling silicon-germanium variants into high-volume production for ADAS front-ends, displacing GaAs below 7 GHz.
- Mixers:Gilbert-cell and passive ring architectures perform frequency conversion in transceiver chains.
- Oscillators:VCO and PLL-integrated designs provide reference timing for cellular and Wi-Fi modems.
Leading the category by volume: Power Amplifiers. Growing fastest: Low Noise Amplifiers.
Technology:
Process selection trades frequency ceiling against unit economics, with compound semiconductors defending performance frontiers and silicon nodes capturing integration density.
- GaN:Wide-bandgap HEMT devices on SiC substrates deliver breakdown voltages above 100V for base station and radar transmitters. US Bureau of Industry and Security dual-use export controls are fragmenting defense-qualified supplier bases for GaN HEMT technology, concentrating sourcing risk among domestic foundries.
- CMOS:Sub-7nm FinFET nodes from TSMC and Samsung Foundry integrate complete transceivers for smartphone modems, with 3nm migration absorbing disproportionate capex allocations. Qualcomm leverages this node leadership for modem-RF platform integration in premium handset slots.
- GaAs:pHEMT and HBT processes maintain share in handset switch and LNA applications.
- SiGe:BiCMOS platforms achieve mmWave performance at silicon cost structures for automotive radar.
Widest deployment: CMOS. Steepest expansion trajectory: GaN.
Application:
Volume concentration in consumer handsets contrasts with margin capture in infrastructure and defense programs.
- Telecommunications:5G macro base stations and small cells demand linearity and thermal efficiency in sub-6 GHz and mmWave bands. FCC spectrum auctions and EU Radio Equipment Directive compliance mandates are tightening emission mask requirements, forcing simultaneous redesigns of die architecture and packaging.
- Consumer Electronics:Wi-Fi 6E/7 front-end modules and UWB connectivity chips ship in billion-unit volumes. Consolidated procurement by tier-one smartphone OEMs compresses vendor margins through annual price-down mandates and exclusive supply agreements.
- Automotive:77-81 GHz radar sensors for ADAS mandate AEC-Q100 qualification and functional safety.
- Aerospace:Space-qualified hybrids and phased-array radar demand hermetic packaging and radiation tolerance.
Highest revenue concentration: Telecommunications. Gaining share fastest: Automotive.
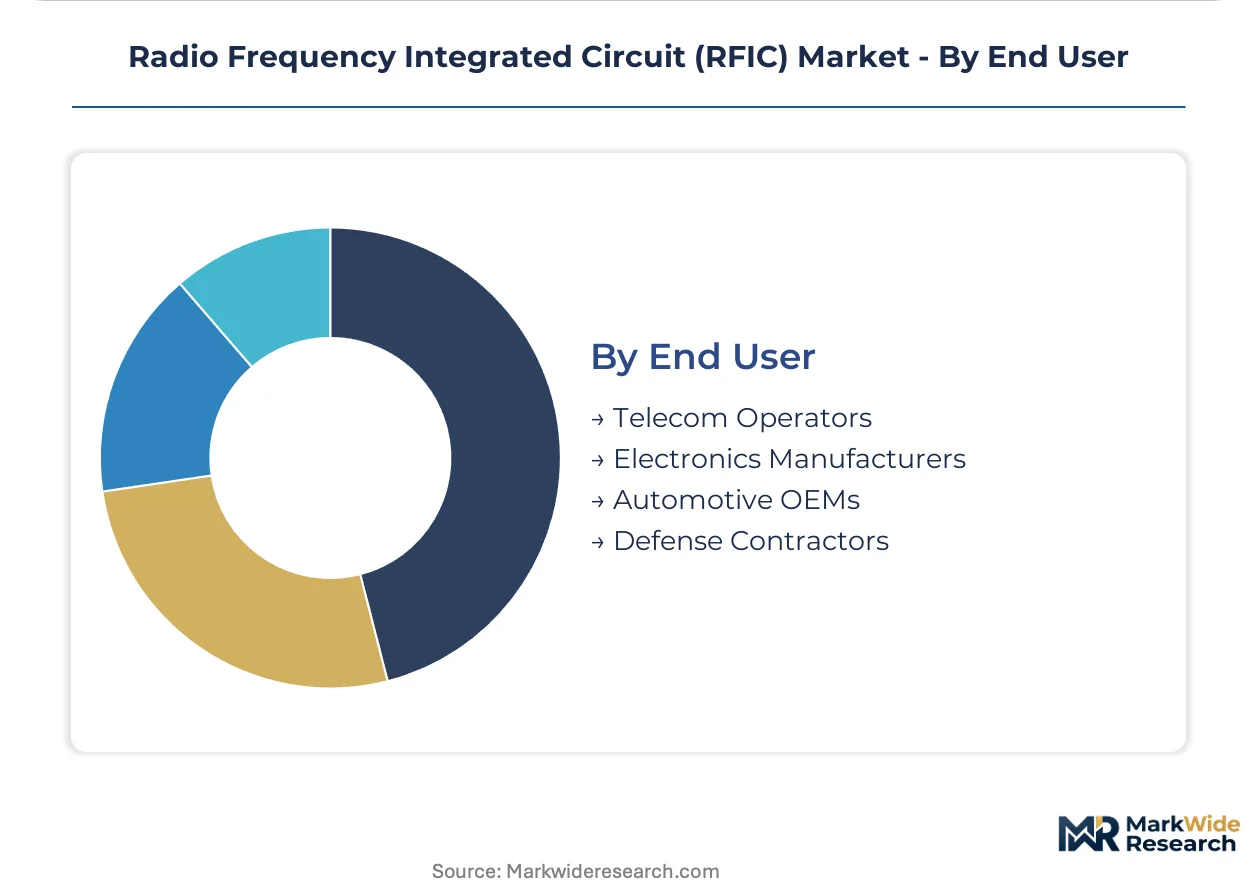
End User:
Procurement sophistication separates defense qualification rigor from consumer electronics volume velocity.
- Telecom Operators:Carrier procurement of base station equipment drives RFIC specifications through 3GPP release roadmaps and Open RAN interoperability mandates. India PLI scheme production-linked incentives are attracting packaging and test investments to Gujarat and Tamil Nadu clusters for telecom equipment supply chains.
- Defense Contractors:Aerospace programs demand ITAR compliance and trusted foundry accreditation for GaN and GaAs devices. EU RoHS recast directives tightening cadmium and lead exemptions force die-attach material substitutions with gold-tin and sintered silver interconnects for space-qualified hybrids.
- Electronics Manufacturers:ODM and EMS procurement of handset RF front-ends prioritizes module integration and time-to-market.
- Automotive OEMs:Tier-1 radar module suppliers qualify RFICs against AEC-Q100 and ISO 26262 functional safety standards.
Dominant procurement volume: Telecom Operators. Expanding most quickly: Defense Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon carbide substrate production anchors RFIC supply geography, with Wolfspeed's North Carolina fabrication and Coherent's New York facilities feeding GaN-on-SiC amplifier demand worldwide. Country-level procurement patterns diverge sharply based on spectrum allocation timelines and defense qualification requirements.
United States
Defense phased-array programs and FCC mmWave auctions drive GaN HEMT consumption for radar and 5G infrastructure. Bureau of Industry and Security export controls fragment defense-qualified supplier bases, accelerating domestic foundry investments. Wolfspeed's Mohawk Valley fab in New York expands 6-inch SiC wafer supply for base station power amplifiers.
China
MIIT 5G mid-band allocations accelerate macro base station buildouts absorbing elevated GaN-on-SiC volumes. Domestic baseband and mmWave programs concentrate procurement among state-directed equipment vendors. Yangtze River Delta clusters in Shanghai and Suzhou host packaging and test investments for telecom RFIC supply chains.
South Korea
Samsung Foundry's 3nm process migration absorbs disproportionate capex for smartphone modem-RF integration. MFDS spectrum coordination aligns 28 GHz small cell deployments with foundry node roadmaps. Seoul Capital Area concentration of fabless designers drives advanced CMOS transceiver procurement.
Germany
Automotive OEMs mandate 77-81 GHz radar sensors for ADAS, pulling SiGe BiCMOS beamforming chips into high-volume production. EU RoHS recast directives tighten cadmium exemptions, forcing gold-tin die-attach substitutions for space-qualified hybrids. Bavaria's Munich-Stuttgart corridor hosts tier-1 radar module qualification centers.
India
TRAI spectrum harmonization supports 5G mid-band infrastructure rollout by domestic telecom operators. PLI scheme production-linked incentives attract RFIC packaging and test investments to Gujarat and Tamil Nadu clusters. Electronics manufacturing services in Chennai and Ahmedabad qualify for telecom equipment supply chain preferences.
Radio Frequency Integrated Circuit (RFIC) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue satellite direct-to-device and automotive radar front-ends. The vendor base compresses around three structural tiers: integrated platform vendors with captive modem-RF design, compound semiconductor specialists with GaN process leadership, and silicon-scale foundry partners. Consolidation pressure intensifies through annual price-down mandates from tier-one smartphone OEMs and exclusive supply agreement demands. Dominant competitive moves include design-win bundling across multi-band front-end modules and strategic partnerships for Open RAN interoperability qualification.
Within the integrated platform tier, Qualcomm Technologies Inc. and Broadcom Inc. exemplify modem-RF convergence strategies, while Qorvo Inc. anchors the compound semiconductor specialist position for defense and aerospace GaN programs. These three entities represent divergent sourcing archetypes: fabless platform integration, captive design-rule enforcement, and wide-bandgap process leadership respectively. Their positioning reflects how RFIC procurement splits between consumer electronics volume velocity and infrastructure margin capture.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Murata Manufacturing Co., Ltd. |
| Qualcomm Technologies Inc. |
| Analog Devices Inc. |
| NXP Semiconductors |
| Broadcom Inc. |
| Qorvo Inc. |
| STMicroelectronics |
| Skyworks Solutions Inc. |
| Others |
Value Network & Pricing Analysis
GaN-on-SiC process migration from 6-inch to 8-inch substrates simultaneously compresses die economics and concentrates sourcing leverage among Wolfspeed and Coherent wafer suppliers. This dual compression reshapes procurement negotiations across base station amplifier tiers.
Pricing Analysis
Warranty-bundled qualification support separates defense-grade GaN HEMT contracts from commercial spot transactions. Pricing stratifies across ITAR-trusted foundry premiums, automotive AEC-Q100 certified tiers, and consumer CMOS economy batches. Cost compression in handset RF front-end modules is intensifying because tier-one smartphone OEMs mandate annual price-downs through exclusive supply agreements. Consumer electronics manufacturers exhibit highest price sensitivity; defense contractors accept premiums for trusted foundry accreditation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale telecom operator demand while distribution partners serve mid-tier automotive radar module suppliers. Taiwan, South Korea, and the United States anchor foundry capacity for advanced CMOS and GaN processes. The supply chain draws from Wolfspeed SiC substrates, TSMC 3nm FinFET wafers, and Qorvo GaN HEMT epitaxy. Single-source vulnerability concentrates in 6-inch SiC wafer supply. Distribution runs through authorized component distributors and direct foundry relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFIC vendor consolidation accelerates as annual price-down mandates from smartphone OEMs force margin compression on sub-scale competitors. GaN process leadership and modem-RF platform integration represent the primary survival thresholds.
For Market Incumbents: Anticipate SiGe BiCMOS displacement of GaAs below 7 GHz by accelerating 16-element beamformer roadmaps. Defend GaN-on-SiC market position through captive substrate agreements with Wolfspeed or Coherent. Vertical integration into 8-inch SiC wafer production offers cost leverage against emerging Chinese substrate entrants.
For New Entrants and Emerging Players: Launch via satellite direct-to-device RF front-end modules targeting L-band and S-band multi-mode transceiver gaps. White-space concentration sits with automotive 77-81 GHz radar sensors requiring AEC-Q100 qualification. India PLI scheme packaging investments in Gujarat clusters offer geographic differentiation from Taiwan-South Korea foundry concentration.
For Investors and Strategic Acquirers: Re-rating potential sits with GaN process specialists given US Bureau of Industry and Security export control fragmentation. Long-term viability favors vendors with ITAR-trusted foundry accreditation and Open RAN interoperability qualification. Monitor Wolfspeed 8-inch SiC substrate yield ramps as inflection indicator for GaN HEMT cost curves.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Capacity Expansion | Wolfspeed Mohawk Valley fab output determines base station amplifier supply elasticity. |
| Modem-RF Platform Integration | Qualcomm leverages TSMC 3nm nodes for premium smartphone socket consolidation. |
| Open RAN Interoperability Qualification | Telecom operators mandate O-RAN compliance for 5G macro infrastructure procurement. |
| Automotive Radar Certification Investment | AEC-Q100 and ISO 26262 compliance unlocks Tier-1 ADAS module supplier status. |
| Trusted Foundry Accreditation | ITAR compliance enables defense phased-array program participation against export-controlled competitors. |
Research Methodology
Independent corroboration across foundry capex disclosures, telecom operator procurement databases, and defense contractor qualification records underwrites the qualitative findings. Primary interviews with RFIC design engineers, base station OEM procurement leads, and semiconductor test equipment specialists combined with secondary validation from FCC spectrum auction filings, MIIT 5G allocation notices, and EU RoHS directive amendments. Bottom-up unit demand modeling and top-down foundry revenue triangulation anchored segmentation outputs.
Rate-of-change decomposition across the projection horizon separates volume drivers from price-mix effects. Segmentation dimensions modeled include product architecture, process technology node, end-use reliability tier, and geographic regulatory cluster. CAGRs derived from foundry capacity expansion schedules against 3GPP release roadmaps. Forecast inputs incorporated GaN substrate yield curves and mmWave test capacity lead times.
Spectrum reallocation delays, SiC substrate yield shortfalls, and dual-use export control expansions are the dominant revision risks. Forecasts reflect assumptions regarding foundry node migration timelines and defense qualification backlogs. Practitioners should monitor Wolfspeed substrate output, TSMC 3nm allocation priorities, and Bureau of Industry and Security rulemaking for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Digital Phase Shifter Market
RF Components
RF Tester Market
RF Components
Digital Radio Frequency Market
RF Components
LTCC Power Dividers Market
RF Components
RF Interconnect Market
RF Components
RF Front End Module Market
RF Components
Analog Phase Shifter Market
RF Components
RF Over Fiber (Rfof) Market
RF Components
Phase Shifters Market
RF Components
US RFID Tags Market
RF Components
Multi-Mode Receiver Market
RF Components
Europe Small Signal Transistor Market
RF Components
GPS Low Noise Amplifier Market
RF Components
High-Power Microwave Source Market
RF Components
Wi-Fi Module Market
RF Components
RF Power Detector Market