
 Wrist Blood Pressure Monitors Market | 2026-2036
Wrist Blood Pressure Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Wrist Blood Pressure Monitors Market Analytics
Aftermarket service revenue is fragmenting across calibration, warranty extension, and data subscription tiers as manufacturers seek recurring income beyond hardware sales. Omron Healthcare leverages its clinical validation partnerships to sustain premium positioning in pharmacy channels. Microlife anchors European market access through CE-marked oscillometric platforms. A&D Medical specializes in precision sensor manufacturing that extends component reliability cycles.
Wrist blood pressure monitors are wearable diagnostic instruments employing oscillometric or aneroid pressure sensing with digital signal processing, typically featuring cuff inflation systems integrated into wristband form factors operating at measurement ranges of 0-300 mmHg with accuracy margins of ±3 mmHg. Digital monitors dominate unit volume while smart watches capture fastest-growing demand as Apple and Samsung ecosystem integration normalizes passive cardiovascular tracking. Bluetooth connectivity reshapes distribution economics by enabling direct-to-consumer online retail bypassing traditional medical supply stores. Home users represent the mature installed base as healthcare providers and clinics drive replacement cycles through remote patient monitoring programs.
FDA 510(k) clearance requirements and EMA Medical Device Regulation compliance shape product development timelines and market access barriers for non-validated entrants. ISO 81060-2:2018 standards for non-invasive sphygmomanometers define accuracy protocols that manufacturers must satisfy for clinical credibility. Stakeholders must monitor evolving reimbursement codes for remote physiological monitoring as payer policies increasingly determine whether wrist-based devices qualify for prescription coverage or remain consumer-discretionary purchases.
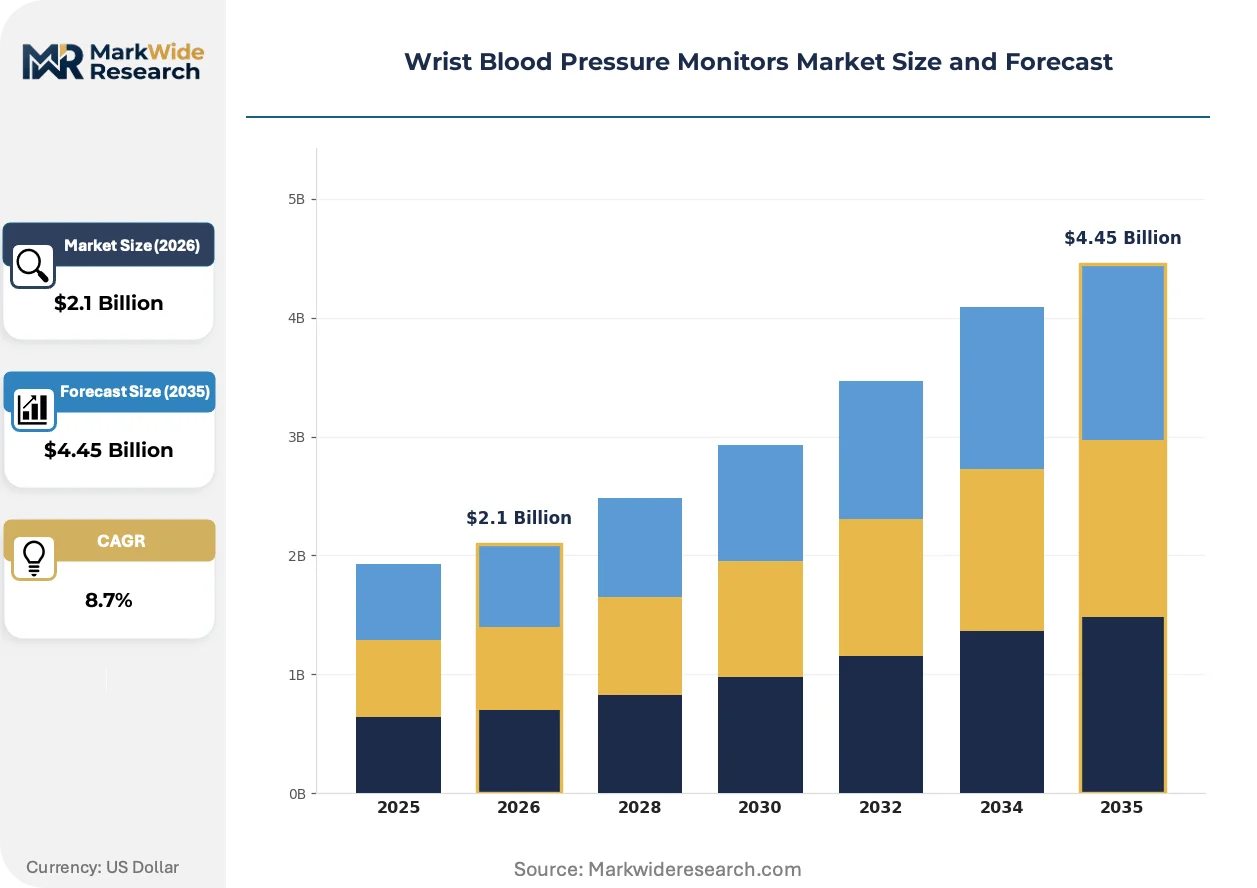
Market Dynamics
Bluetooth-enabled oscillometric wrist monitors are compressing replacement cycles as home users upgrade from aneroid legacy units, while FDA 510(k) clearance timelines extend development costs for non-validated entrants seeking clinical credibility.
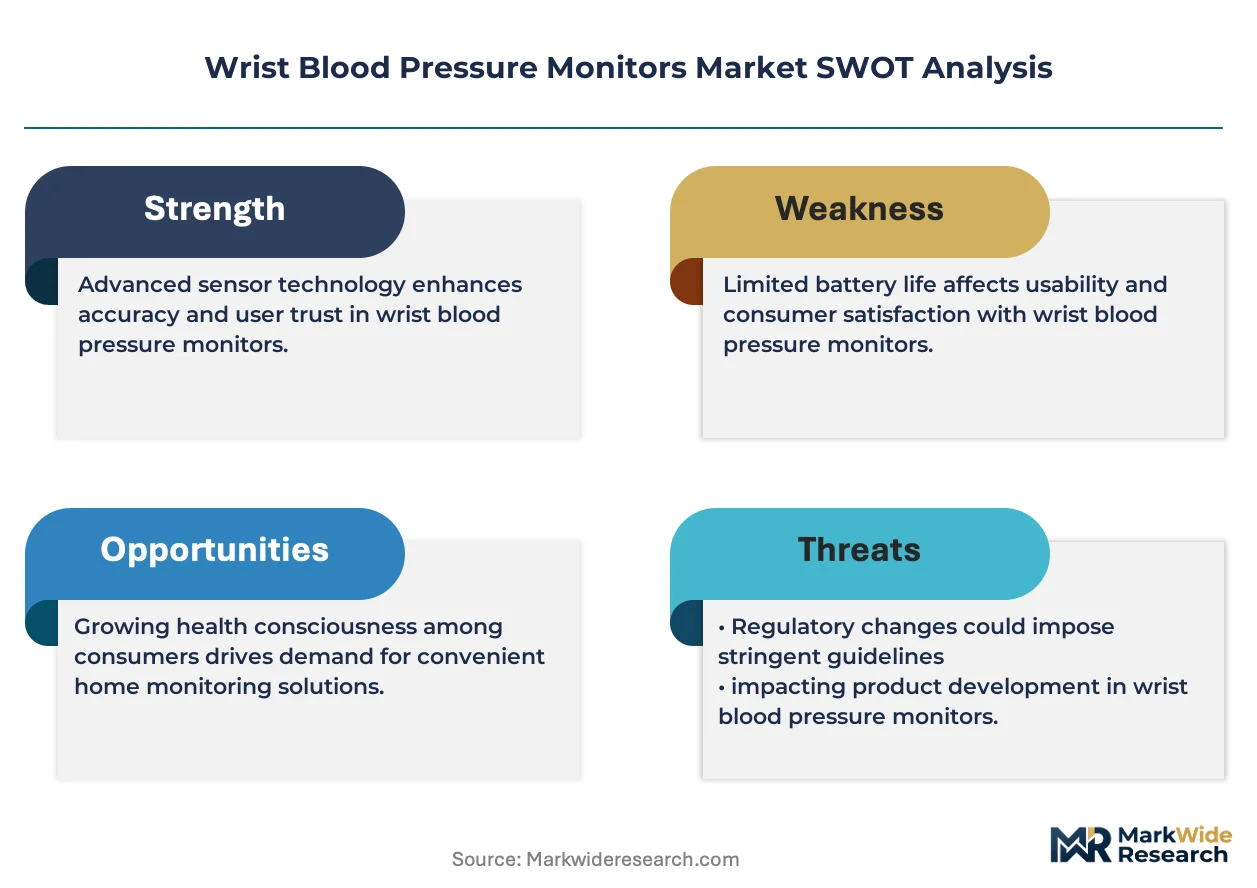
Growth Catalysts
- EMA Medical Device Regulation:CE-marked oscillometric platforms gain automatic mutual recognition across European Economic Area member states, accelerating pharmacy channel access for validated manufacturers.
- Remote patient monitoring programs:Healthcare providers in Germany and Japan are deploying wrist-based devices for post-discharge cardiovascular tracking, creating institutional procurement pull.
- Sensor miniaturization:MEMS pressure transducers enable cuff inflation systems below 80 grams, expanding wearable comfort thresholds for aging demographics.
Market Restraints
- ISO 81060-2:2018 validation costs:Third-party accuracy certification for non-invasive sphygmomanometers requires 18-24 month testing protocols that freeze smaller entrants from clinical segments.
- Semiconductor concentration:Precision analog-to-digital converters for pressure sensing concentrate among Taiwanese foundries, exposing supply continuity to geopolitical friction.
- Optical PPG substitution:Smartwatch photoplethysmography arrays from consumer electronics ecosystems threaten standalone wrist monitor volumes in fitness-oriented segments.
Strategic Opportunities
- Reimbursement code expansion:CMS remote physiological monitoring codes in the United States are extending coverage to prescription-grade wrist devices, converting consumer-discretionary purchases into reimbursable clinical tools.
- Data subscription tiers:Cloud-based cardiovascular trend analytics represent recurring revenue streams beyond hardware margins, with HIPAA-compliant architectures enabling provider-facing SaaS models.
- East Asian metropolitan corridors:Tokyo, Seoul, and Shanghai healthcare networks are piloting wrist monitor integration into hypertension management protocols, creating reference sites for regional expansion.
Industry Challenges
- Firmware validation timelines:FDA software-as-medical-device guidance requires documentation of algorithm updates, complicating agile development cycles for Bluetooth connectivity stacks.
- Calibration technician scarcity:Field service networks for oscillometric sensor recalibration remain underdeveloped outside major urban clusters, degrading measurement accuracy over device lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wrist Blood Pressure Monitors Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Monitors, Analog Monitors, Smart Watches, Hybrid Devices End User: Home Users, Healthcare Providers, Athletes, Clinics Technology: Oscillometric, Aneroid, Hybrid Technology, Bluetooth Connectivity Distribution Channel: Online Retail, Pharmacies, Direct Sales, Medical Supply Stores |
| Companies Covered | Omron Healthcare, Microlife, A&D Medical, Withings, Garmin, Beurer GmbH, iHealth Labs, Qardio, HoMedics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wrist Blood Pressure Monitors Market Evolving Landscape
Digital signal processing architectures are converging with consumer electronics supply chains, compressing component costs while elevating accuracy expectations from clinical validation frameworks.
Multi-wavelength photoplethysmography is hybridizing with traditional oscillometric pressure sensing in hybrid wrist monitors, enabling simultaneous pulse waveform analysis and absolute pressure measurement. Cardiology clinics in the United States are piloting these dual-mode devices for arrhythmia screening protocols. The technology is hybridizing diagnostic categories, blurring boundaries between consumer wellness and prescription-grade monitoring.
REACH restrictions on mercury-containing aneroid sphygmomanometers are accelerating phase-out timelines across European Union member states, with ECHA substance restrictions taking full effect in clinical procurement channels. Manufacturers with CE-marked digital alternatives are capturing replacement volume from hospital supply contracts. German pharmacy chains are responding by consolidating shelf space behind validated oscillometric units.
Direct-to-consumer online retail is disintermediating traditional medical supply stores as Bluetooth connectivity enables smartphone app ecosystems that bypass clinical channel gatekeepers. Amazon and specialized health platforms are capturing unit volume from regional distributors in North American markets. This channel rotation is most visible among tech-savvy demographics aged 45-65 who self-initiate cardiovascular monitoring without physician referral.
Wrist Blood Pressure Monitors Market Segmentation
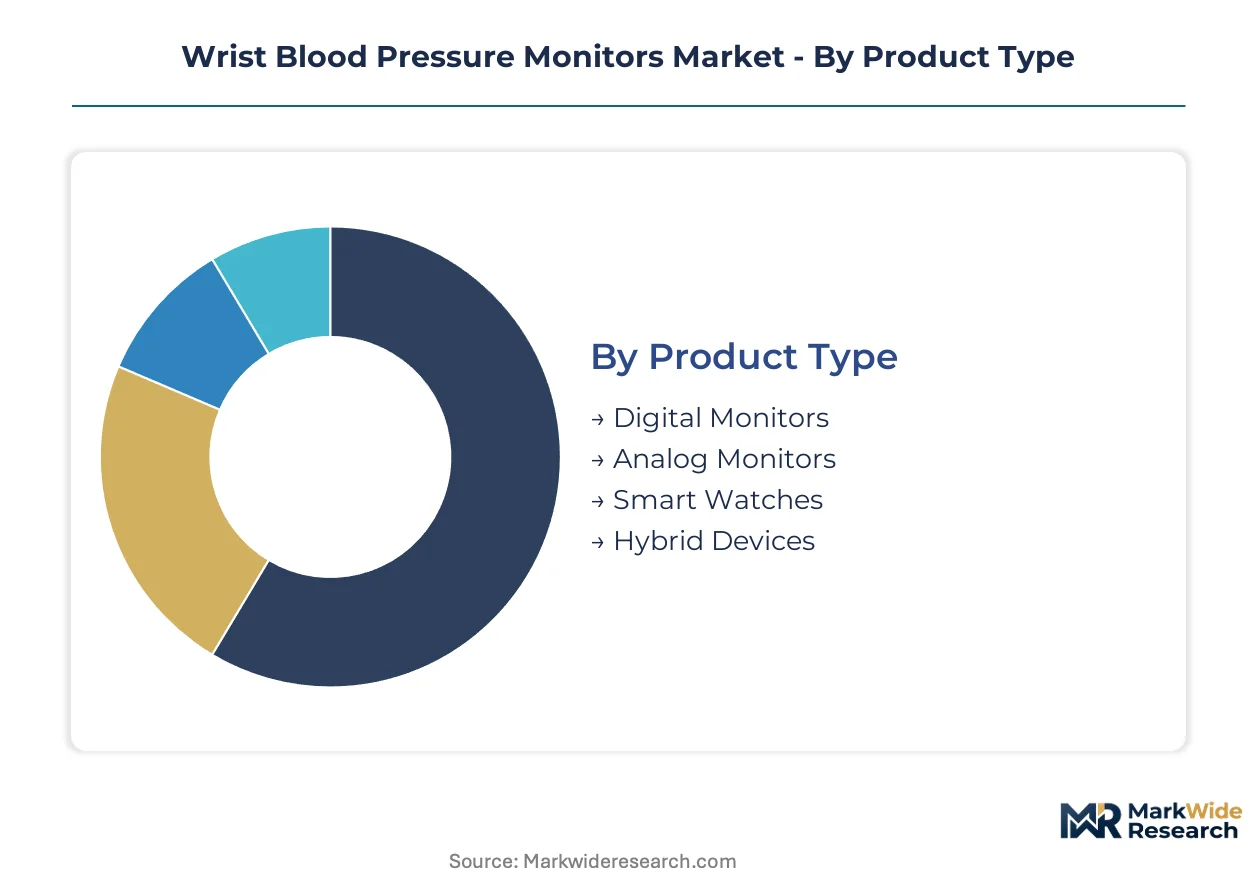
Segmentation in wrist blood pressure monitors determines calibration frequency, warranty structures, and subscription attach rates. Manufacturers design service tiers around usage intensity rather than hardware specifications alone.
Product Type:
After-sales-service intensity varies dramatically across product categories, with smart ecosystems demanding continuous firmware updates while analog units require only periodic mechanical calibration.
- Digital Monitors:Oscillometric measurement engines with LCD displays and onboard memory for 60-100 readings dominate pharmacy channel volume. Home users in Germany and Japan drive replacement demand as aging populations prioritize cardiovascular self-monitoring.
- Smart Watches:Photoplethysmography arrays integrated with Apple and Samsung ecosystems normalize passive tracking for fitness-oriented demographics. Athletes and tech-savvy consumers aged 45-65 are expanding this segment most quickly through direct-to-consumer online channels.
- Analog Monitors:Aneroid gauge mechanisms with manual inflation bulbs face REACH-mandated phase-out across European Union member states.
- Hybrid Devices:Dual-mode oscillometric-PPG architectures enable simultaneous pressure measurement and pulse waveform analysis for arrhythmia screening protocols.
By volume, digital monitors lead. By growth pace, smart watches are ahead.
End User:
Customer type dictates purchasing authority, reimbursement eligibility, and data integration requirements.
- Home Users:Self-directed consumers operating without clinical supervision represent the mature installed base. Bluetooth-enabled devices with smartphone app pairing are displacing legacy aneroid units in North American metropolitan corridors.
- Healthcare Providers:Hospital systems and physician practices deploying wrist monitors for remote patient monitoring programs require FDA 510(k) clearance and HIPAA-compliant data architectures. Institutional procurement in the United States is accelerating as CMS reimbursement codes extend coverage to prescription-grade devices.
- Athletes:Fitness enthusiasts seeking continuous cardiovascular tracking during training sessions favor smartwatch form factors with optical PPG substitution.
- Clinics:Outpatient cardiology practices in Tokyo, Seoul, and Shanghai pilot hybrid device integration into hypertension management protocols.
Home users generate the highest unit volume. Healthcare providers command the steepest expansion trajectory.
Technology:
Underlying sensing mechanisms determine accuracy certification requirements and supply chain exposure.
- Oscillometric:Cuff inflation systems with MEMS pressure transducers measuring arterial oscillations during deflation define clinical-grade accuracy. ISO 81060-2:2018 validation protocols freeze smaller entrants from segments requiring third-party certification.
- Aneroid:Mechanical gauge systems with mercury-free designs face ECHA substance restrictions eliminating procurement from European hospital supply contracts.
- Hybrid Technology:Combined pressure sensing and optical pulse analysis enables dual diagnostic outputs for arrhythmia detection.
- Bluetooth Connectivity:Wireless data transmission to smartphone ecosystems reshapes distribution economics by enabling direct-to-consumer retail bypass.
Oscillometric platforms anchor current revenue. Bluetooth connectivity is climbing the fastest as channel rotation accelerates.
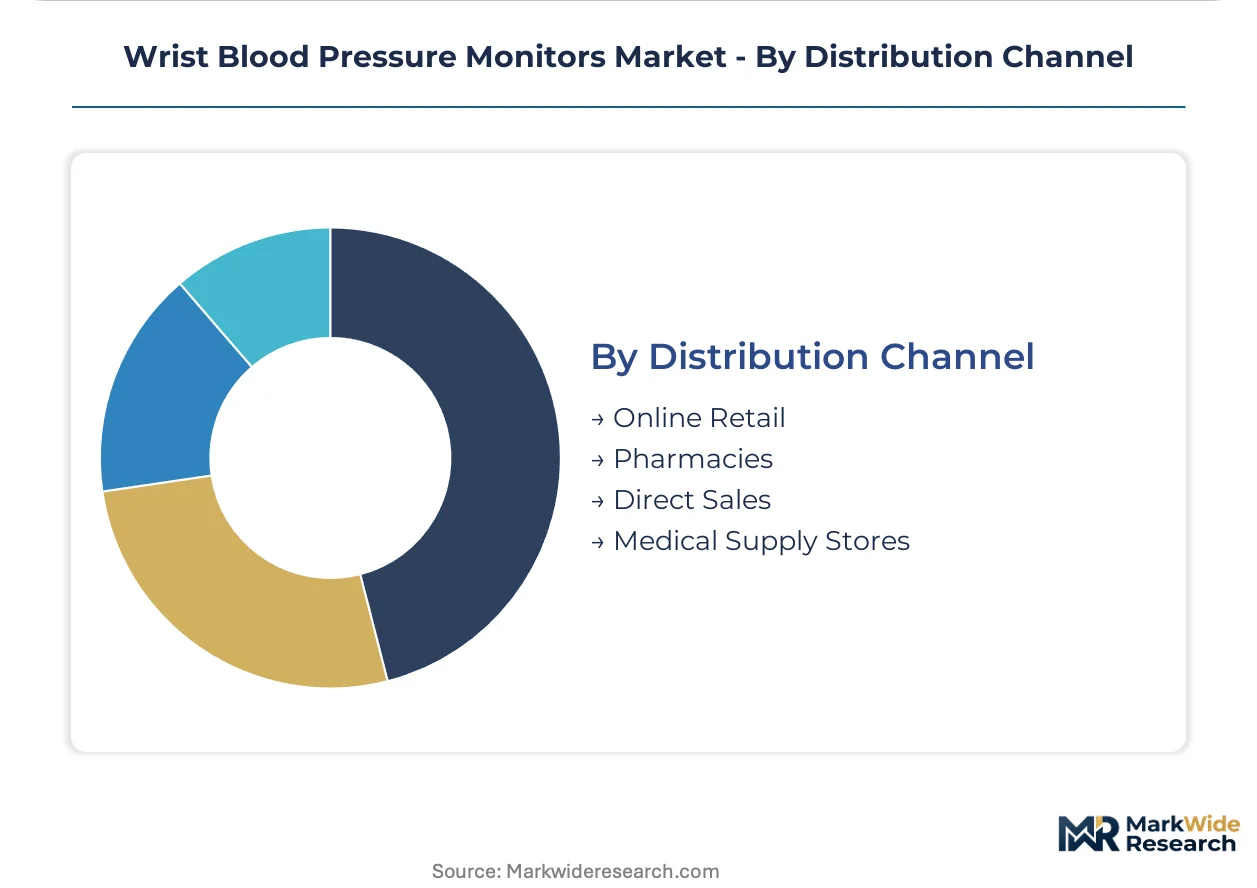
Distribution Channel:
Channel selection determines margin structure, customer acquisition cost, and service attach potential.
- Online Retail:Amazon and specialized health platforms capture volume from regional distributors as smartphone app ecosystems eliminate clinical gatekeepers. Tech-savvy demographics aged 45-65 self-initiate monitoring without physician referral.
- Pharmacies:German pharmacy chains consolidate shelf space behind CE-marked oscillometric units following EMA Medical Device Regulation harmonization.
- Direct Sales:Manufacturer-controlled channels serve institutional procurement for remote patient monitoring programs with customized data subscription tiers.
- Medical Supply Stores:Traditional distributors face disintermediation pressure as Bluetooth connectivity enables ecosystem bypass.
Pharmacies maintain the highest current throughput. Online retail is gaining share fastest among replacement purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German and Japanese buyers absorb premium validated devices, while emerging markets favor lower-cost oscillometric units without third-party certification.
United States
Remote patient monitoring programs drive institutional procurement of FDA-cleared wrist devices. CMS reimbursement code expansion for remote physiological monitoring converts consumer purchases into reimbursable clinical tools. The Boston-Cambridge healthcare corridor hosts pilot deployments of hybrid oscillometric-PPG monitors in cardiology clinics.
Germany
Aging demographics prioritize cardiovascular self-monitoring with pharmacy-validated devices. EMA Medical Device Regulation harmonization accelerates CE-marked oscillometric platform access across German pharmacy chains. The Rhine-Ruhr metropolitan zone concentrates replacement demand as REACH-mandated aneroid phase-outs complete.
Japan
Post-discharge cardiovascular tracking programs deploy wrist monitors through healthcare provider networks. METI standards for home medical devices shape accuracy expectations and procurement protocols. Tokyo's healthcare networks pilot wrist monitor integration into hypertension management reference sites for regional expansion.
South Korea
Tech-savvy demographics aged 45-65 self-initiate monitoring through direct-to-consumer online channels. MFDS medical device clearance requirements parallel FDA timelines for clinical-grade market access. Seoul metropolitan healthcare corridors concentrate smartwatch ecosystem adoption for passive cardiovascular tracking.
China
Domestic manufacturers compete on cost for unvalidated oscillometric units serving price-sensitive home users. NMPA Class II medical device registration creates compliance barriers for international entrants seeking clinical segments. Shanghai healthcare networks pilot prescription-grade wrist monitor procurement for hypertension management protocols.
Wrist Blood Pressure Monitors Market Competitive Landscape
Capability concentration sits with clinical-validation specialists; scale advantage sits with consumer electronics ecosystems. The market structures around three tiers: oscillometric precision manufacturers, smartwatch platform integrators, and hybrid diagnostic developers. Consolidation pressures favor validated incumbents with FDA 510(k) portfolios over unvalidated cost competitors. Dominant competitive moves include calibration-service bundling and data-subscription tiering to capture recurring revenue beyond hardware margins.
Among clinically validated specialists, Omron Healthcare, Microlife, and A&D Medical occupy positions reflecting distinct capability anchors. Omron Healthcare exemplifies the pharmacy-channel validation archetype through clinical partnership networks. Microlife represents European market access specialization with CE-marked platform concentration. A&D Medical sits within precision sensor manufacturing, extending component reliability cycles for oscillometric systems. These three anchors demonstrate how regulatory clearance portfolios separate sustainable positioning from commodity competition.
| Leading Market Players |
|---|
| Omron Healthcare |
| Microlife |
| A&D Medical |
| Withings |
| Garmin |
| Beurer GmbH |
| iHealth Labs |
| Qardio |
| HoMedics |
| Others |
Value Network & Pricing Analysis
Taiwanese foundry capacity for precision analog-to-digital converters anchors component pricing power, with MEMS pressure transducer sourcing concentrated in East Asian manufacturing corridors that feed downstream oscillometric assembly. Calibration service bundling and data subscription tiers now determine lifetime value capture as hardware margins compress.
Pricing Analysis
Data subscription tiers and extended warranty contracts now drive lifetime value beyond unit sales, with three-tier pricing structure across premium, standard, and economy levels separating FDA-cleared clinical devices from consumer-grade alternatives. Price differentiation hinges on ISO 81060-2:2018 certification status and Bluetooth ecosystem integration depth. Cost compression in unvalidated consumer segments is intensifying because optical PPG substitution from smartwatch ecosystems erodes standalone monitor volumes. Home users exhibit highest price sensitivity; healthcare providers absorb premium pricing for prescription-grade validation.
Supply Chain Analysis
Export controls on semiconductor manufacturing equipment to Chinese foundries are reshaping component sourcing strategies for pressure sensing chips. Supply draws from Taiwan, South Korea, and Japan for MEMS transducers, precision ADCs, and Bluetooth connectivity modules. Raw material dependencies include silicon wafers, rare-earth magnets for micro-pumps, and medical-grade polymers for cuff inflation bladders. Single-source vulnerability concentrates in Taiwanese precision converter foundries. Distribution runs through direct-to-consumer online platforms and pharmacy channel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical photoplethysmography substitution from consumer electronics ecosystems threatens standalone wrist monitor volumes, forcing incumbents to defend through clinical validation moats and service-tier differentiation.
For Market Incumbents: Harden FDA 510(k) clearance portfolios against smartwatch ecosystem encroachment by accelerating hybrid oscillometric-PPG development. Deepen backward integration into MEMS pressure sensor manufacturing to secure component supply continuity. Anchor pharmacy channel control through calibration service bundling that locks replacement cycles. For New Entrants and Emerging Players: Build out white-space positions in remote patient monitoring data analytics and HIPAA-compliant cloud architectures serving healthcare provider networks. The most penetrable segment lies in subscription-tier cardiovascular trend analytics for post-discharge hypertension management programs. Pursue direct-to-consumer online launch with smartphone app ecosystems bypassing clinical gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clinical-validation specialists with regulatory clearance backlogs over unvalidated hardware competitors. Long-term viability rests on recurring revenue attachment rates from data subscriptions and calibration services. Acquisition target archetypes include precision sensor manufacturers and cloud analytics platforms. The signal to watch is CMS reimbursement code expansion converting consumer purchases into reimbursable clinical tools.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Clinical credibility barrier protects premium positioning against consumer electronics substitution. |
| CE Marking Acceleration | EMA Medical Device Regulation harmonization unlocks pharmacy channel access across German and European markets. |
| Hospital System Partnership | Institutional procurement for remote patient monitoring programs converts hardware sales into recurring data subscriptions. |
| Software Companion Development | HIPAA-compliant smartphone ecosystems enable direct-to-consumer retail bypass of traditional medical supply stores. |
| Reimbursement Strategy | CMS remote physiological monitoring code alignment transforms consumer-discretionary purchases into prescription-covered clinical tools. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and pharmacy chain category buyers. Secondary validation drew from FDA 510(k) filings, EMA CE marking databases, CMS reimbursement code updates, and hospital procurement contract records. Bottom-up unit shipment estimates triangulated against top-down market sizing across oscillometric, PPG, and hybrid technology segments.
Calibration against historical validation timelines and regulatory approval trajectories anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end user archetype, sensing technology, and distribution channel structure. CAGRs were derived from fitted growth curves incorporating replacement cycle compression from Bluetooth-enabled upgrades and remote patient monitoring program adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by consumer electronics ecosystems or regulatory accelerations would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
Europe Patient Monitoring Devices Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
Heart Beat Monitor and Sensor Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
Cardiac Patch Monitor Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Global Heart Rate Monitor Market
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
Multi-Item Patient Monitor Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Global Hemodynamic Monitoring System Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
Infusion Rate Monitoring Market