
 Wireless Fetal Monitoring Systems Market | 2026-2036
Wireless Fetal Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Fetal Monitoring Systems Market Analytics
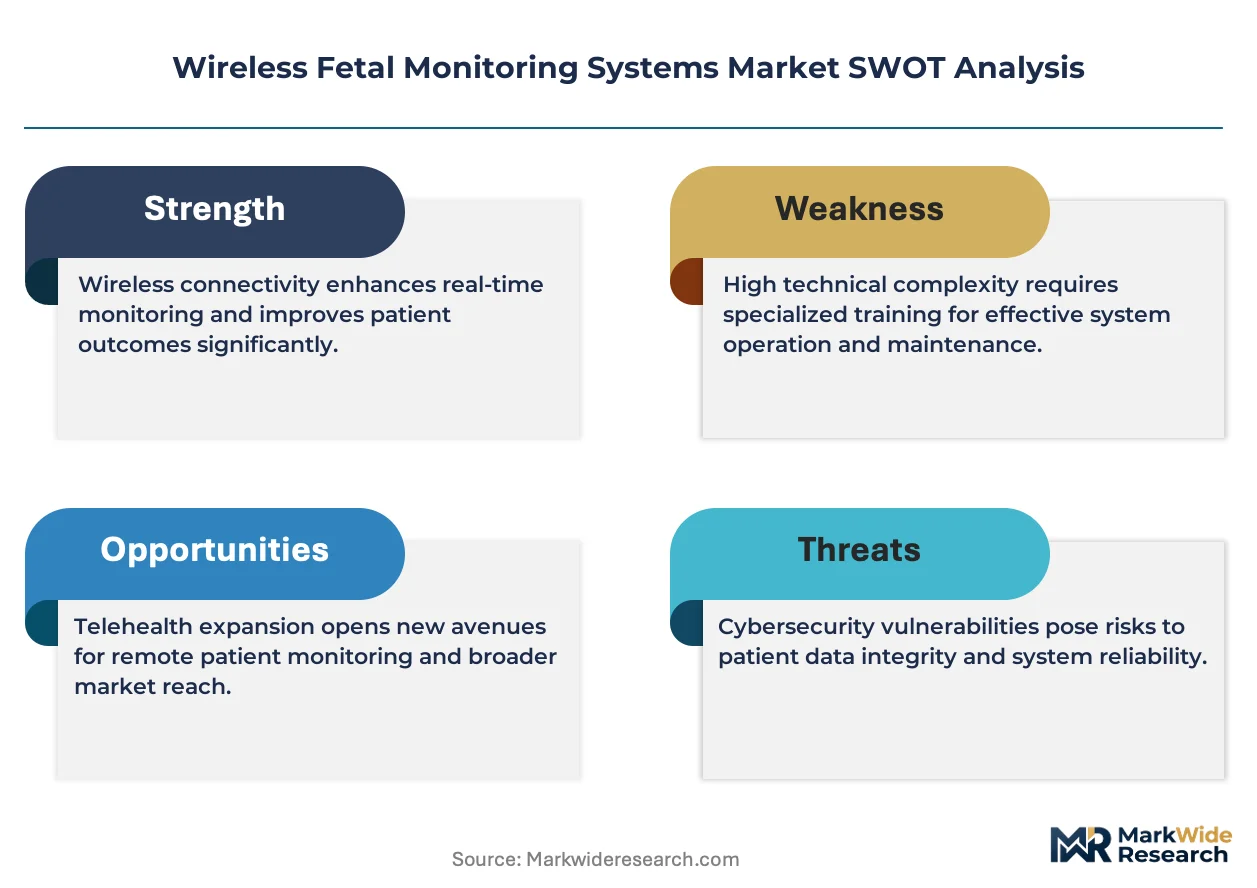
The gap between premium wireless telemetry suites and basic wearable patch monitors is realigning procurement strategies across maternity care networks. GE Healthcare leverages its installed base of hospital monitoring infrastructure to sustain recurring telemetry revenue streams. Koninklijke Philips N.V. anchors its competitive position through integrated maternal-fetal platforms that span antenatal through labor and delivery workflows. Siemens Healthineers differentiates via advanced signal processing algorithms that reduce false alarm rates in ambulatory settings.
Wireless fetal monitoring systems encompass portable, cable-free devices that capture fetal heart rate, uterine activity, and maternal vital signs through ultrasound Doppler, electrocardiography, or optical photoplethysmography, transmitting data via Bluetooth or Wi-Fi to central nursing stations or cloud platforms for real-time clinical review. These systems eliminate physical tethering during labor, enabling maternal mobility while maintaining continuous surveillance of fetal well-being. Wearable monitors command the largest revenue share due to their deployment flexibility across hospital wards and birthing centers, whereas telemetry-enabled platforms represent the fastest-expanding segment as health systems pursue centralized remote surveillance of multiple patients. Monitoring apps are gaining traction in home care channels, though reimbursement limitations constrain their near-term revenue contribution relative to hardware-intensive categories.
FDA 510(k) premarket notification requirements and EU MDR conformity assessments shape product development timelines and clinical evidence burdens for manufacturers seeking multi-region commercialization. HIPAA in the United States and GDPR in Europe impose stringent data governance obligations on cloud-connected monitoring platforms, influencing vendor architecture decisions and hospital procurement criteria. Stakeholders must weigh regulatory compliance investments against the pace of wireless technology refresh cycles as clinical evidence standards tighten for algorithm-driven diagnostic outputs.
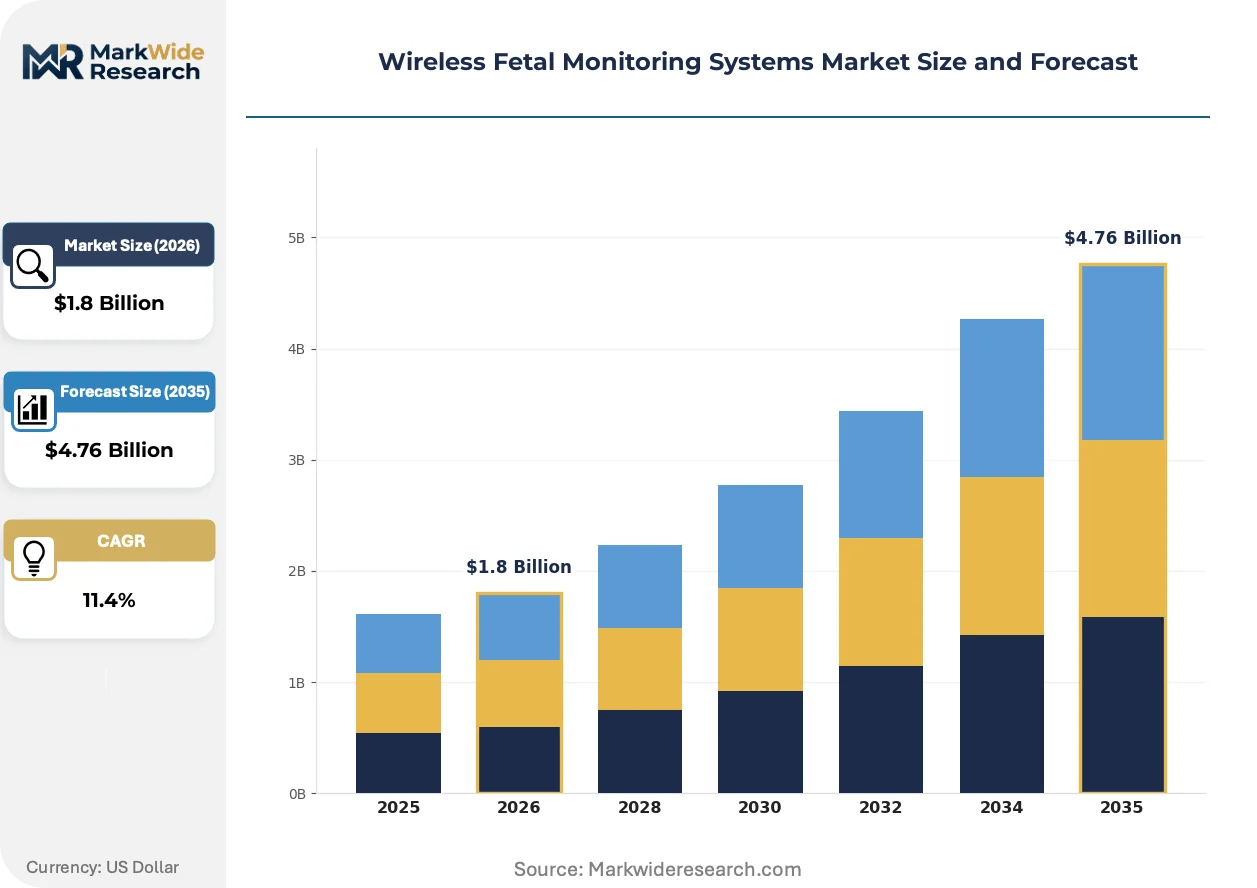
Market Dynamics
Clinician staffing shortages across maternity wards are forcing hospital systems to prioritize centralized remote surveillance architectures over bedside-only monitoring configurations. This structural pressure is compressing procurement cycles for telemetry-enabled platforms while elevating algorithmic false-alarm reduction to a primary vendor selection criterion.
Growth Catalysts
- FDA 510(k) clearance acceleration:Streamlined premarket notification pathways for wearable fetal monitors are shortening time-to-revenue for manufacturers targeting US hospital networks.
- Bluetooth Low Energy transmission protocols:Reduced power consumption and improved signal stability are enabling continuous ambulatory monitoring during active labor without tethering constraints.
- Germany's perinatal care infrastructure investments:Federal reimbursement reforms favoring wireless telemetry over wired systems are driving replacement demand across university hospital maternity networks.
Market Restraints
- Semiconductor component volatility:Supply concentration for specialized ultrasound transducer chips in East Asian foundries creates input cost instability for device manufacturers.
- EU MDR clinical evidence burdens:Expanded conformity assessment requirements for algorithm-driven diagnostic outputs are extending product development timelines by 18-24 months.
- Wired monitoring system installed base:Capital depreciation schedules and nurse training investments in legacy telemetry infrastructure delay wireless upgrade cycles.
Strategic Opportunities
- Home-based antenatal monitoring channels:Reimbursement pathway evolution for remote patient monitoring codes is opening direct-to-patient revenue streams outside traditional hospital procurement.
- Photoplethysmography-ultrasound sensor fusion:Convergence of optical and acoustic signal modalities is enabling single-patch form factors that reduce maternal skin irritation complaints.
- China's tier-two city hospital expansion:Provincial healthcare infrastructure programs in Sichuan and Hubei are funding wireless telemetry adoption in newly constructed maternity centers.
Industry Challenges
- Biomedical signal processing expertise scarcity:Shortage of engineers capable of developing artifact-resistant fetal heart rate extraction algorithms is constraining R&D throughput.
- HIPAA-GDPR dual compliance architecture:Cloud platform vendors must engineer separate data residency and encryption frameworks for US and European deployments, doubling infrastructure complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Fetal Monitoring Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Non-invasive Devices, Implantable Sensors, Monitoring Apps Technology: Ultrasound, Electrocardiography, Optical Sensors, Telemetry End User: Hospitals, Birthing Centers, Home Care Providers, Clinics Application: High-risk Pregnancies, Routine Monitoring, Labor and Delivery, Fetal Assessment |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Siemens Healthineers, Mindray Medical International Ltd, Huntleigh Healthcare Limited, OBMedical Company, Medtronic, FUJIFILM Sonosite, Inc., Shenzhen Jumper Medical Equipment Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Fetal Monitoring Systems Market Evolving Landscape
Signal processing automation and decentralized data architectures are restructuring competitive advantage around software-enabled differentiation rather than hardware specifications alone. Vendors that integrate machine learning inference at the edge are capturing preference from health systems prioritizing real-time clinical decision support.
Photoplethysmography-based fetal heart rate detection is electrifying wearable monitor design by eliminating ultrasonic gel application requirements and reducing maternal skin heating concerns. Birthing centers and midwifery-led units in the Netherlands and Scandinavia are adopting these optical-first platforms for low-risk pregnancies. This technology is electrifying market segmentation by creating a distinct ambulatory monitoring tier between home-based consumer devices and hospital-grade telemetry suites.
The EU Medical Device Regulation's expanded clinical evidence requirements for software-as-a-medical-device are forcing manufacturers to conduct prospective validation studies for algorithm updates. Siemens Healthineers and Philips have restructured their European regulatory affairs teams to manage continuous compliance documentation. Wearable monitor vendors with cloud-based diagnostic outputs face the steepest evidence generation burdens under this framework.
Hospital procurement committees are unbundling after-sales service contracts from device capital purchases, creating standalone recurring revenue streams for technical support and algorithm updates. This pattern is most visible in US integrated delivery networks negotiating multi-hospital telemetry deployments. Vendors that resist service unbundling are losing competitive positioning to specialists offering modular subscription pricing.
Wireless Fetal Monitoring Systems Market Segmentation
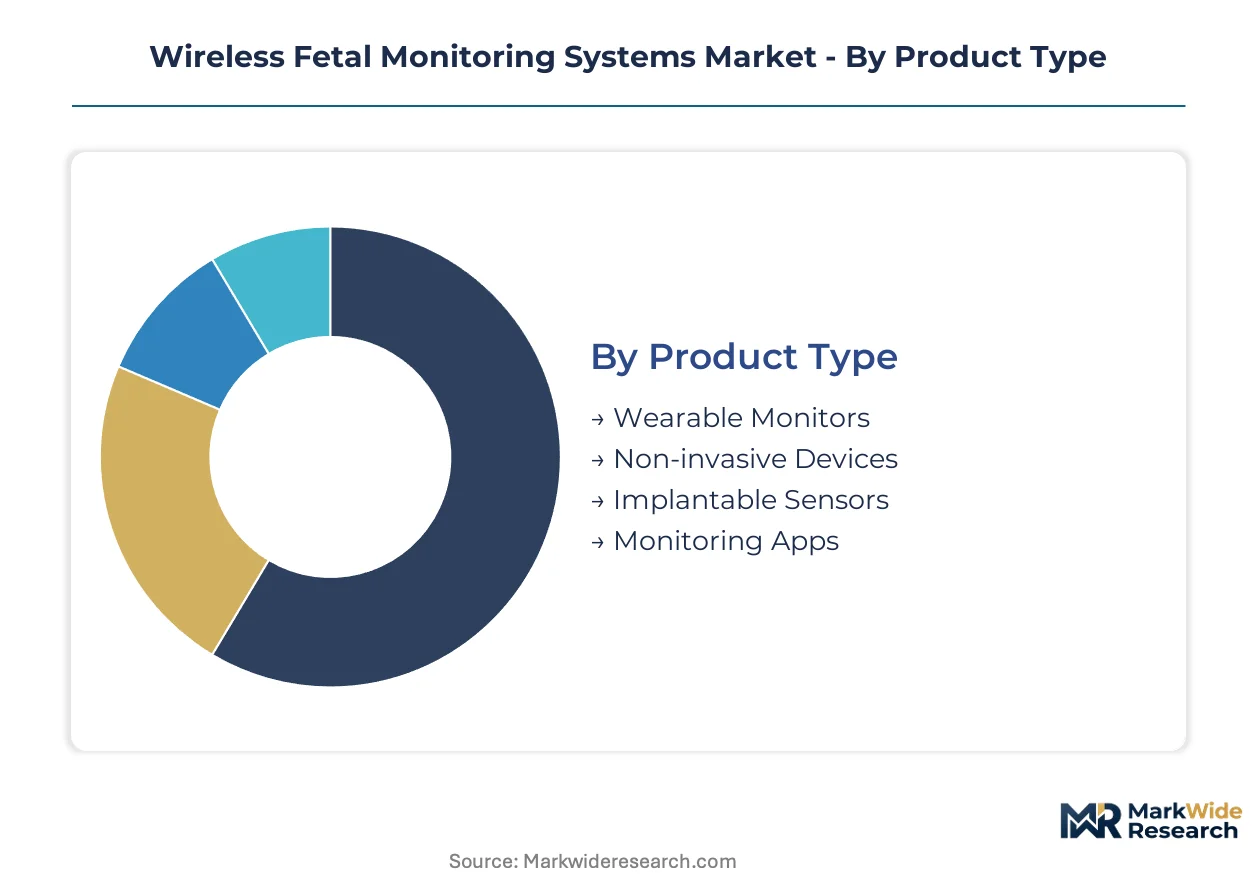
Wireless fetal monitoring systems fragment across hardware form factors, signal acquisition methods, and care settings. Procurement committees evaluate these segments against capital budgets, clinical workflow integration, and reimbursement eligibility. Understanding segment boundaries clarifies where telemetry infrastructure investments concentrate versus where wearable alternatives displace traditional bedside systems.
Product Type:
Wearable monitors capture volume leadership through deployment flexibility across antenatal and intrapartum settings. Premium positioning belongs to implantable sensors where invasive placement justifies specialized reimbursement.
- Wearable Monitors:Cable-free patches and belts integrate ultrasound Doppler or optical photoplethysmography for continuous fetal heart rate and uterine activity capture. Hospital maternity wards in the United States and Germany prioritize these for ambulatory labor monitoring, driven by clinician staffing constraints that demand centralized remote surveillance architectures.
- Non-invasive Devices:Handheld or belt-mounted systems eliminate transabdominal catheterization while maintaining signal fidelity equivalent to wired telemetry. Demand clusters in birthing centers across the Netherlands and Scandinavia where low-intervention birth protocols favor maternal mobility without sacrificing fetal surveillance.
- Implantable Sensors:Subcutaneous fetal electrocardiography electrodes deliver signal clarity in high BMI pregnancies where transabdominal acoustic attenuation degrades conventional monitoring.
- Monitoring Apps:Smartphone-integrated platforms leverage consumer device cameras or connected peripherals for intermittent fetal heart rate assessment. Home care channels in Germany pilot these under remote patient monitoring reimbursement pilots, though hardware-centric revenue models currently dominate.
Mature deployment sits with wearable monitors. Newer deployment is concentrated in monitoring apps.
Technology:
Ultrasound dominates unit economics through established transducer supply chains and clinician familiarity. Telemetry commands premium pricing through infrastructure integration requirements.
- Ultrasound:Pulsed-wave Doppler systems transmit 1-2 MHz acoustic energy through maternal abdominal wall to detect fetal cardiac wall motion. Hospital procurement in China favors these for tier-two city maternity center expansions where capital constraints prioritize proven technology with local service support.
- Electrocardiography:Maternal abdominal surface electrodes capture composite maternal-fetal cardiac electrical signals, requiring adaptive filtering algorithms to isolate fetal QRS complexes. High-risk pregnancy units in university hospitals deploy these for arrhythmia detection where waveform morphology carries diagnostic weight.
- Optical Sensors:Photoplethysmography detects volumetric blood flow changes through near-infrared light absorption, eliminating acoustic gel application and thermal tissue exposure concerns.
- Telemetry:Wireless transmission protocols—Bluetooth Low Energy and proprietary radio frequency—enable centralized nursing station surveillance of multiple patients. This segment is expanding most quickly as integrated delivery networks in the United States consolidate monitoring infrastructure across distributed maternity units.
Established clinical validation sits with ultrasound. Algorithmic innovation is concentrated in optical sensors.
End User:
Hospitals absorb capital equipment through depreciation schedules and enterprise procurement frameworks. Home care channels remain reimbursement-constrained despite technology readiness.
- Hospitals:Acute care maternity wards with labor-and-delivery suites and antepartum testing units represent the primary installed base for telemetry-enabled platforms. Federal reimbursement reforms in Germany specifically favor wireless telemetry over wired systems in university hospital networks, accelerating replacement cycles.
- Birthing Centers:Midwifery-led facilities prioritize portable, non-invasive monitors that support ambulation and hydrotherapy during labor. Scandinavian regulatory frameworks for low-risk pregnancy settings accommodate reduced monitoring intensity compared to hospital protocols.
- Home Care Providers:Remote patient monitoring vendors supply leased wearable devices for high-risk antenatal surveillance outside institutional settings.
- Clinics:Outpatient obstetric practices utilize handheld Doppler devices for intermittent fetal assessment during scheduled prenatal visits.
Capital concentration sits with hospitals. Reimbursement pathway development is concentrated in home care providers.
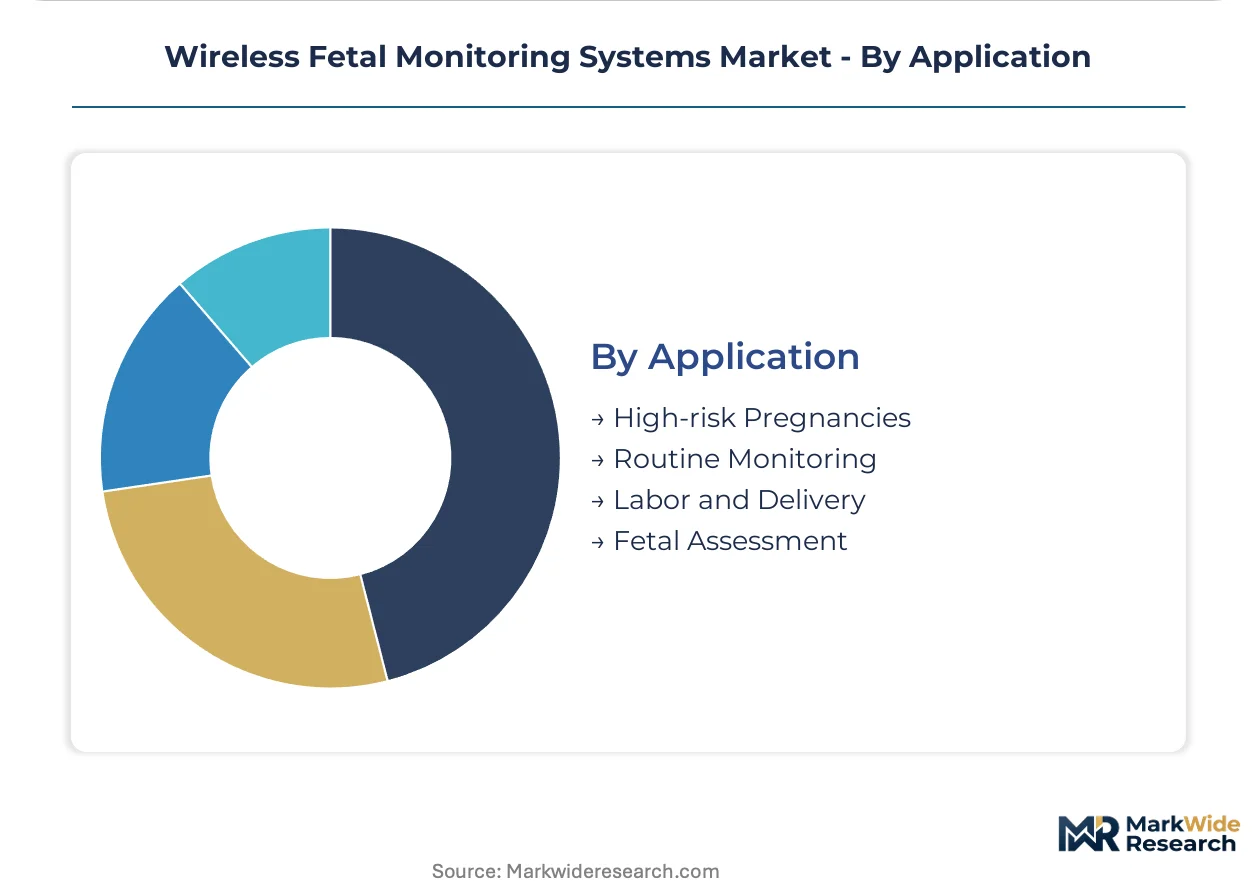
Application:
High-risk pregnancies justify premium monitoring intensity through perinatal morbidity reduction incentives. Routine monitoring offers volume scale through standard pregnancy populations.
- High-risk Pregnancies:Maternal diabetes, hypertension, and fetal growth restriction indications demand continuous or frequent intermittent surveillance with documented biophysical profiles. Tertiary care centers in the United States deploy telemetry-enabled platforms for antepartum inpatient management of these cases.
- Routine Monitoring:Low-risk pregnancies require periodic fetal heart rate assessment during scheduled prenatal visits and intermittent surveillance during uncomplicated labor. Birthing centers in the Netherlands leverage optical sensor wearables to satisfy monitoring obligations without constraining maternal movement.
- Labor and Delivery:Intrapartum fetal heart rate pattern recognition drives decisions on operative intervention timing.
- Fetal Assessment:Non-stress tests and biophysical profile scoring rely on extended monitoring periods to evaluate fetal well-being.
Established clinical protocols sit with fetal assessment. Workflow redesign is concentrated in labor and delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors the highest concentration of wireless fetal monitoring innovation, with Massachusetts General Hospital and Brigham and Women's Hospital driving early adoption of telemetry-enabled platforms for centralized maternity ward surveillance.
United States
FDA 510(k) clearance pathways and clinician staffing shortages across hospital maternity wards are accelerating procurement of remote surveillance architectures. HIPAA compliance requirements shape cloud platform vendor selection criteria. The Boston-Cambridge medical technology corridor hosts multiple device manufacturers and clinical validation sites.
Germany
Federal reimbursement reforms favoring wireless telemetry over wired systems are driving replacement demand across university hospital maternity networks. EU MDR conformity assessments extend product development timelines for algorithm-driven diagnostic outputs. The Munich-Stuttgart medical device cluster concentrates regulatory affairs expertise and manufacturing capabilities.
China
Provincial healthcare infrastructure programs in Sichuan and Hubei are funding wireless telemetry adoption in newly constructed tier-two city maternity centers. NMPA registration requirements and GB standards compliance shape domestic product development. Shenzhen hosts contract manufacturers supplying ultrasound transducer components to global device makers.
Netherlands
Midwifery-led birthing centers prioritize portable, non-invasive monitors supporting ambulation and hydrotherapy during labor. National regulatory frameworks for low-risk pregnancy settings accommodate reduced monitoring intensity. The Eindhoven-Utrecht corridor concentrates photoplethysmography sensor development for optical-first wearable platforms.
Japan
PMDA approval timelines and aging obstetrician workforce demographics are elevating centralized remote surveillance priorities in tertiary care centers. METI funding programs support next-generation maternal-fetal monitoring technology development. The Osaka-Kobe medical device manufacturing belt supplies precision ultrasound transducers to regional and global markets.
Wireless Fetal Monitoring Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across signal processing sophistication and regulatory compliance depth. The market structure consolidates around three tiers: diversified medical technology conglomerates with installed telemetry infrastructure, specialized maternal-fetal monitoring vendors with workflow-integrated platforms, and regional device manufacturers competing on capital cost. Strategic archetypes include telemetry suite providers leveraging hospital relationships, wearable patch specialists targeting ambulatory settings, and algorithm-focused vendors differentiating through false-alarm reduction. Dominant competitive moves encompass service contract unbundling to capture recurring revenue and photoplethysmography-ultrasound sensor fusion for single-patch form factors.
Within the diversified conglomerate tier, GE Healthcare and Koninklijke Philips N.V. occupy positions anchored by hospital monitoring infrastructure and integrated maternal-fetal platform portfolios. Siemens Healthineers exemplifies the algorithm-centric archetype through advanced signal processing capabilities. Shenzhen Jumper Medical Equipment Co., Ltd. represents the regional specialist segment with China-based manufacturing and tier-two city hospital expansion focus.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Mindray Medical International Ltd |
| Huntleigh Healthcare Limited |
| OBMedical Company |
| Medtronic |
| FUJIFILM Sonosite, Inc. |
| Shenzhen Jumper Medical Equipment Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Photoplethysmography-ultrasound sensor fusion is compressing component counts while concentrating procurement leverage among East Asian foundries capable of hybrid optical-acoustic module fabrication. This dual-technology convergence simultaneously elevates R&D amortization burdens for premium-tier vendors and creates cost barriers for entrants lacking scale in transducer supply negotiations.
Pricing Analysis
Value-based pricing anchors on per-patient monitoring throughput and false-alarm reduction guarantees negotiated with integrated delivery networks. Three-tier pricing structure across premium telemetry suites, standard wearable patches, and economy handheld units reflects FDA 510(k) clearance tiering and algorithmic sophistication gradients. Cost compression in the economy tier intensifies because Shenzhen-based contract manufacturers are absorbing margin erosion to secure hospital procurement contracts. Birthing centers exhibit highest price sensitivity due to capital constraints and midwifery-led budget autonomy, while tertiary care centers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns serving hospital networks with 48-hour replenishment commitments for consumable patches. Specialized ultrasound transducer chips draw from Taiwan Semiconductor Manufacturing and South Korean foundries, while optical photodiodes rest on Japanese component specialists. Single-source vulnerability concentrates in pulsed-wave Doppler transducers where two East Asian suppliers command 70% of medical-grade output. Distribution runs through manufacturer-direct sales teams for telemetry infrastructure and medical device distributors for wearable disposables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR clinical evidence burdens are forcing algorithm-driven diagnostic vendors toward acquisition by diversified conglomerates with regulatory affairs scale, compressing viable independent players to under a dozen.
For Market Incumbents: Cement installed base retention by unbundling after-sales service contracts into standalone algorithm-update subscriptions, neutralizing wearable patch specialists competing on capital cost alone. Deepen backward integration into ultrasound transducer fabrication through captive supply agreements with Taiwan-based foundries, insulating margin structures from semiconductor volatility that threatens tier-two competitors.
For New Entrants and Emerging Players: Capture home-based antenatal monitoring channels where reimbursement pilots in Germany and remote patient monitoring code evolution create first-mover windows outside hospital procurement gatekeepers. Target midwifery-led birthing centers in the Netherlands and Scandinavia with optical-first platforms emphasizing maternal mobility and hydrotherapy compatibility, bypassing telemetry infrastructure requirements that favor entrenched vendors.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical technology conglomerates seeking algorithmic differentiation for maternal-fetal platforms, with IPO viability constrained by EU MDR documentation burdens and extended validation timelines. Acquisition target archetype: specialized vendors with FDA 510(k) cleared photoplethysmography platforms and proprietary artifact-resistant signal processing IP. Watch for NMPA registration acceleration in China as inflection indicator for tier-two city hospital expansion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Development | Photoplethysmography-ultrasound convergence reduces maternal skin irritation complaints while enabling single-patch hospital-grade monitoring. |
| EU MDR Regulatory Affairs Restructuring | Continuous compliance documentation capabilities separate viable vendors from acquisition targets unable to fund prospective validation studies. |
| Service Contract Unbundling | Standalone technical support and algorithm update subscriptions create recurring revenue streams decoupled from capital purchase cycles. |
| Home Care Reimbursement Strategy | Remote patient monitoring code capture in Germany and United States opens direct-to-patient revenue outside traditional hospital procurement. |
| East Asian Foundry Partnership | Captive supply agreements for ultrasound transducer chips insulate margin structures from semiconductor input cost volatility. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, EU MDR conformity assessment records, and hospital procurement contract disclosures, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at maternal-fetal monitoring vendors. Secondary validation drew from CMS Medicare reimbursement data, German Federal Joint Committee (G-BA) procedure catalogs, and China NMPA registration filings. Bottom-up segmentation modeling triangulated against top-down market sizing from installed base estimates and replacement cycle analysis.
Historical shipment data cross-referenced against clinician panel input on procurement priority shifts anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, signal acquisition technology, end-user facility tier, and application intensity. CAGRs derived from weighted average of technology diffusion curves and reimbursement pathway evolution timelines, with specific inputs including Bluetooth Low Energy protocol adoption rates and EU MDR implementation compliance costs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply stability and reimbursement code expansion velocity for remote patient monitoring. Outputs reflect documented assumptions on clinician staffing constraint persistence and wireless telemetry infrastructure depreciation schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Digital Patient Monitoring Systems Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Bedside Monitors Market
Patient Monitoring
Pain Monitoring Devices Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Global Smart Pulse Oximeters Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
South America Fetal and Neonatal Monitoring Market
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
Global Intrapartum Monitoring Devices Market