
 Fetal and Neonatal Heart Monitor Market | 2026-2036
Fetal and Neonatal Heart Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Fetal and Neonatal Heart Monitor Market Analysis
Equipment leasing and pay-per-use financing is fragmenting competitive access across maternity wards and neonatal intensive care units. Philips Healthcare leverages its installed base of obstetric monitoring platforms to sustain recurring service revenue. GE HealthCare anchors its position through backward integration into transducer manufacturing, while Mindray competes aggressively on portable monitor configurations for mid-tier hospitals.
Fetal and neonatal heart monitors comprise electronic systems that detect, amplify, and display cardiac signals from fetuses and newborns, typically operating at ultrasound frequencies between 1-3 MHz for Doppler-based devices or capturing ECG waveforms via adhesive electrodes with sampling rates exceeding 240 Hz. These systems serve the clinical purpose of detecting fetal distress, arrhythmias, and hypoxic events before irreversible organ damage occurs. Wireless monitors now capture the fastest-growing share of product type demand as hospitals prioritize mobility during active labor, while electrocardiography technology leads the technology dimension due to its diagnostic specificity in NICU settings where beat-to-beat variability analysis guides therapeutic decisions.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and market access costs for manufacturers targeting the United States and European Union. China's NMPA medical device registration requirements add a separate compliance layer for companies seeking volume in that jurisdiction. Stakeholders must monitor how reimbursement coding changes for remote fetal monitoring affect home care provider adoption of portable Doppler systems.
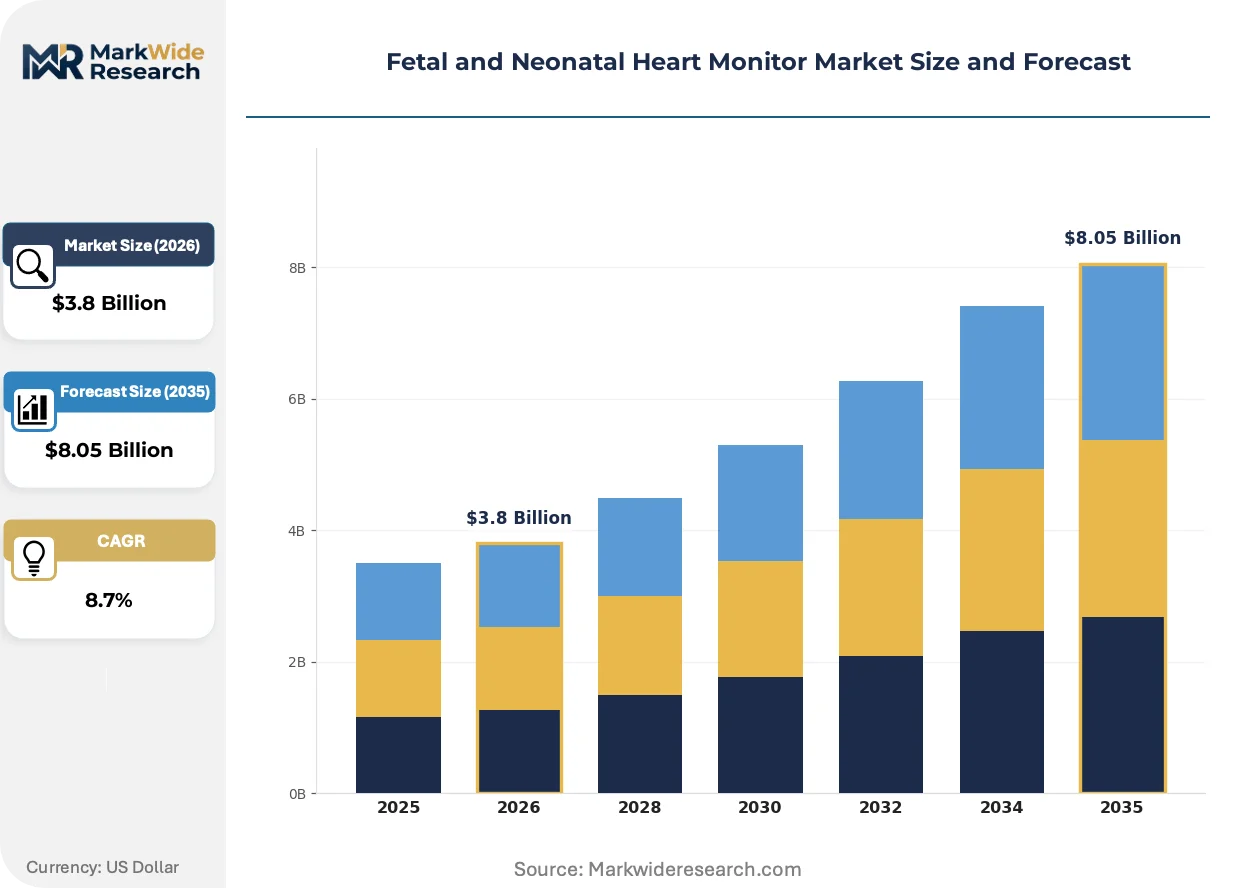
Market Dynamics
Hospital procurement departments are abandoning capital purchases for wireless fetal monitor fleets, forcing manufacturers to restructure revenue models around recurring service streams and subscription-based leasing contracts.
Growth Catalysts
- EU MDR Technical Documentation:Stringent conformity assessment requirements for Class IIa medical devices accelerate replacement cycles among European tertiary maternal centers seeking certified equipment upgrades.
- Wireless Mobility During Active Labor:Untethered Doppler and ECG systems enable continuous cardiotocography without restricting maternal movement, driving NICU and labor ward procurement decisions.
- China's Tertiary Hospital Expansion:Provincial maternal health infrastructure investments concentrate demand in tier-one cities where high-risk pregnancy volumes justify advanced monitoring platforms.
Market Restraints
- FDA 510(k) Premarket Notification:Substantial equivalence demonstrations for new ultrasound transducer frequencies extend product launch timelines by 12-18 months.
- Transducer Manufacturing Concentration:Backward integration into piezoelectric crystal supply chains limits viable supplier alternatives for mid-tier monitor assemblers.
- Disposable Electrode Cost Volatility: Silver-silver chloride electrode prices fluctuate with precious metal markets, compressing margins on ECG-based neonatal systems.
Strategic Opportunities
- Home-Based Remote Monitoring:Portable Doppler devices with cloud-connected waveform transmission open reimbursement-eligible channels for high-risk outpatient surveillance.
- AI-Assisted Arrhythmia Detection:Machine learning algorithms processing 240+ Hz ECG sampling rates reduce false-positive alerts in NICU settings.
- Subscription Fleet Management:Outcome-based leasing contracts align vendor incentives with hospital uptime requirements and preventive maintenance schedules.
Industry Challenges
- Biomedical Engineer Shortage:Specialized training for wireless telemetry troubleshooting and electrode placement protocol compliance outpaces workforce pipeline expansion.
- Legacy System Interoperability:HL7 FHIR integration with existing hospital information systems requires custom middleware development for multi-vendor monitor deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fetal and Neonatal Heart Monitor Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Monitors, Portable Monitors, Fetal Dopplers, Transducers Technology: Ultrasound, Electrocardiography, Magnetocardiography, Impedance Cardiography Application: Labor & Delivery, NICU, Obstetrics, Emergency Care End User: Hospitals, Private Clinics, Home Care Providers, Research Institutes |
| Companies Covered | GE HealthCare, Philips Healthcare, Siemens Healthineers, Medtronic PLC, Mindray, Drägerwerk AG & Co. KGaA, Spacelabs Healthcare, Edan Instruments, Fujifilm SonoSite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fetal and Neonatal Heart Monitor Market Emerging Trajectories
Digital signal processing architectures and cloud-native data pipelines are compressing hardware differentiation cycles, forcing established manufacturers to compete on analytics capabilities and service integration rather than sensor specifications alone.
Artificial intelligence inference engines embedded directly at the monitor edge are rendering obsolete centralized server-based arrhythmia classification workflows that introduced critical latency in emergency NICU responses. Tertiary maternal centers in Germany and the United States pilot these systems for real-time ST-segment analysis during high-risk deliveries. The shift compresses IT infrastructure requirements while elevating cybersecurity validation burdens for manufacturers.
EU MDR post-market surveillance mandates now require systematic collection of clinical performance data across the device lifecycle, compelling manufacturers to redesign quality management systems for continuous real-world evidence generation. This regulatory architecture elevates documentation costs disproportionately for single-product entrants lacking established vigilance infrastructures. European notified bodies report extended audit queues as legacy certificate holders rush MDR transition deadlines.
Hospital materials management departments unbundle after-sales service contracts from equipment leases, negotiating standalone preventive maintenance agreements with third-party clinical engineering firms. This purchasing behavior fragments vendor service revenue streams while creating openings for independent service organizations certified under ISO 13485 quality standards. The pattern concentrates in United States health systems pursuing operational expenditure optimization through competitive service bidding.
Fetal and Neonatal Heart Monitor Market Segmentation
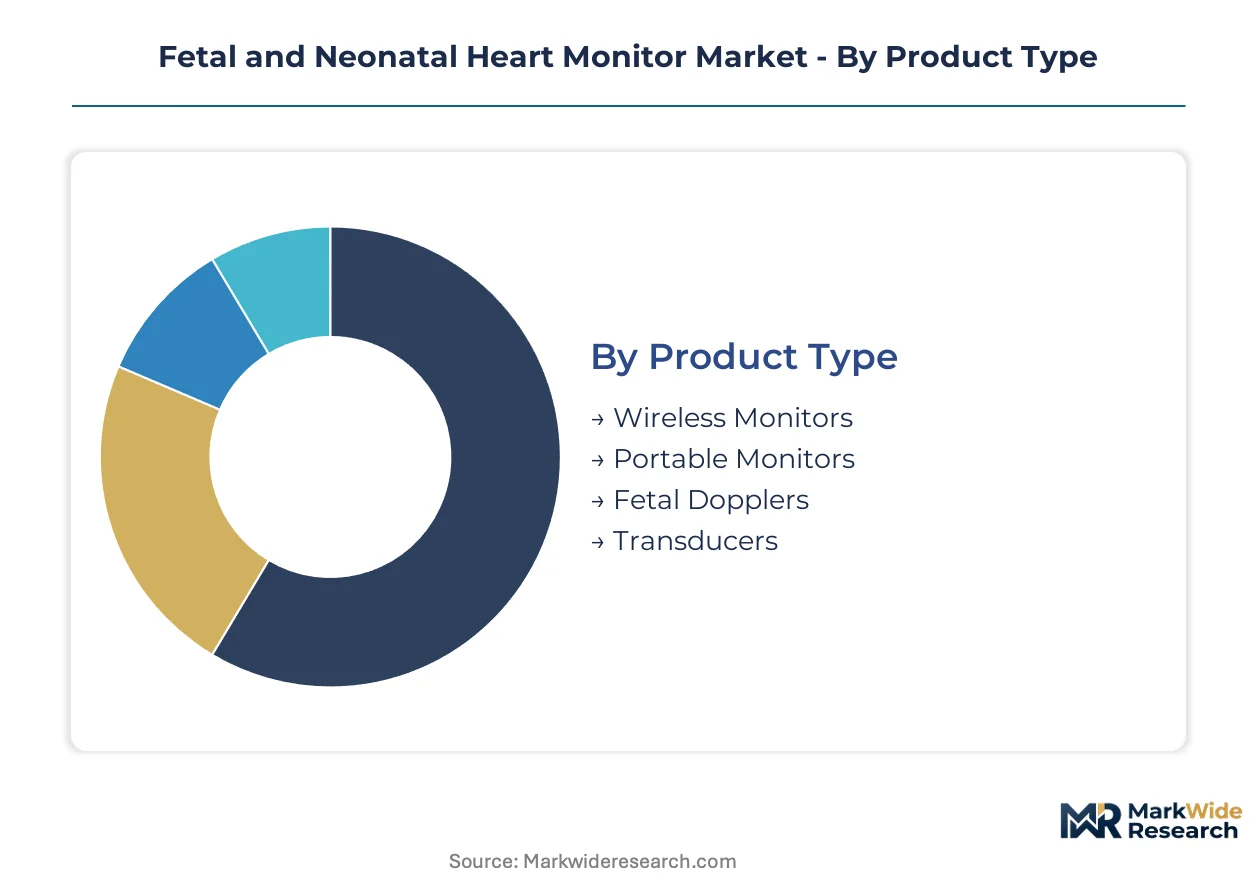
Segmentation in the Fetal and Neonatal Heart Monitor Market reveals distinct procurement patterns across clinical settings. Wireless telemetry systems command premium positioning in tertiary maternal centers, while portable Doppler units penetrate outpatient and home care channels where reimbursement flexibility varies.
Product Type:
Clinical use-case spectrum spans tethered bedside systems through ambulatory telemetry, with mobility requirements dictating hardware architecture and battery chemistry specifications.
- Wireless Monitors:Battery-powered telemetry units transmit ECG and Doppler signals via encrypted Wi-Fi or proprietary radio protocols to central nursing stations. United States tertiary hospitals prioritize these for active labor suites where maternal mobility reduces cesarean intervention rates. The steepest expansion trajectory sits here as subscription fleet models displace capital purchases.
- Portable Monitors:Compact cart-based or handheld configurations with integrated displays serve mid-tier hospital labor wards and transport scenarios. Germany's provincial maternal centers favor these for cost-containment during EU MDR transition periods. Demand concentrates where infrastructure budgets constrain full wireless deployment.
- Fetal Dopplers:Handheld ultrasound devices operating at 1-3 MHz for intermittent auscultation in outpatient settings.
- Transducers:Piezoelectric crystal assemblies for ultrasound and ECG signal acquisition, often backward-integrated by major manufacturers.
Established volume favors Transducers; emerging adoption favors Wireless Monitors.
Technology:
Signal processing methodology determines diagnostic specificity, with sampling rates and noise rejection thresholds shaping clinical utility across risk stratification protocols.
- Electrocardiography:Adhesive electrode systems capturing 240+ Hz sampling rates enable beat-to-beat variability analysis critical for NICU hypoxic event detection. United States neonatal intensive care units mandate this specificity for therapeutic decision support. Regulatory validation burdens under FDA 510(k) pathways elevate development costs.
- Ultrasound:Doppler-shift detection at 1-3 MHz frequencies supports non-invasive fetal heart rate monitoring without skin contact requirements. China's tertiary hospital expansion drives volume here for high-risk pregnancy surveillance. NMPA registration timelines extend market access for new entrants.
- Magnetocardiography:Superconducting quantum interference device arrays detect fetal cardiac magnetic fields with superior signal-to-noise ratios for arrhythmia diagnosis.
- Impedance Cardiography:Thoracic electrical bioimpedance measurement for non-invasive cardiac output estimation in hemodynamically unstable neonates.
Diagnostic precision favors Electrocardiography; penetration breadth favors Ultrasound.
Application:
Acuity level and care setting dictate monitor specification, with continuous versus intermittent monitoring requirements driving hardware selection and staffing protocols.
- Labor & Delivery:Continuous cardiotocography during active labor demands wireless or portable systems with maternal position tolerance. United States health systems deploy these across birthing center networks. Reimbursement coding for remote monitoring influences capital allocation.
- NICU:Critically ill neonates require multi-parameter integration with ventilator and infusion pump data streams. Germany's perinatal centers lead adoption of AI-embedded edge devices here. EU MDR post-market surveillance mandates elevate documentation requirements.
- Obstetrics:Antepartum surveillance in outpatient clinics relies on intermittent Doppler assessment and telemedicine integration.
- Emergency Care:Pre-hospital and emergency department triage applications prioritize rapid-deployment portable configurations.
Revenue concentration favors Labor & Delivery; technology upgrade intensity favors NICU.
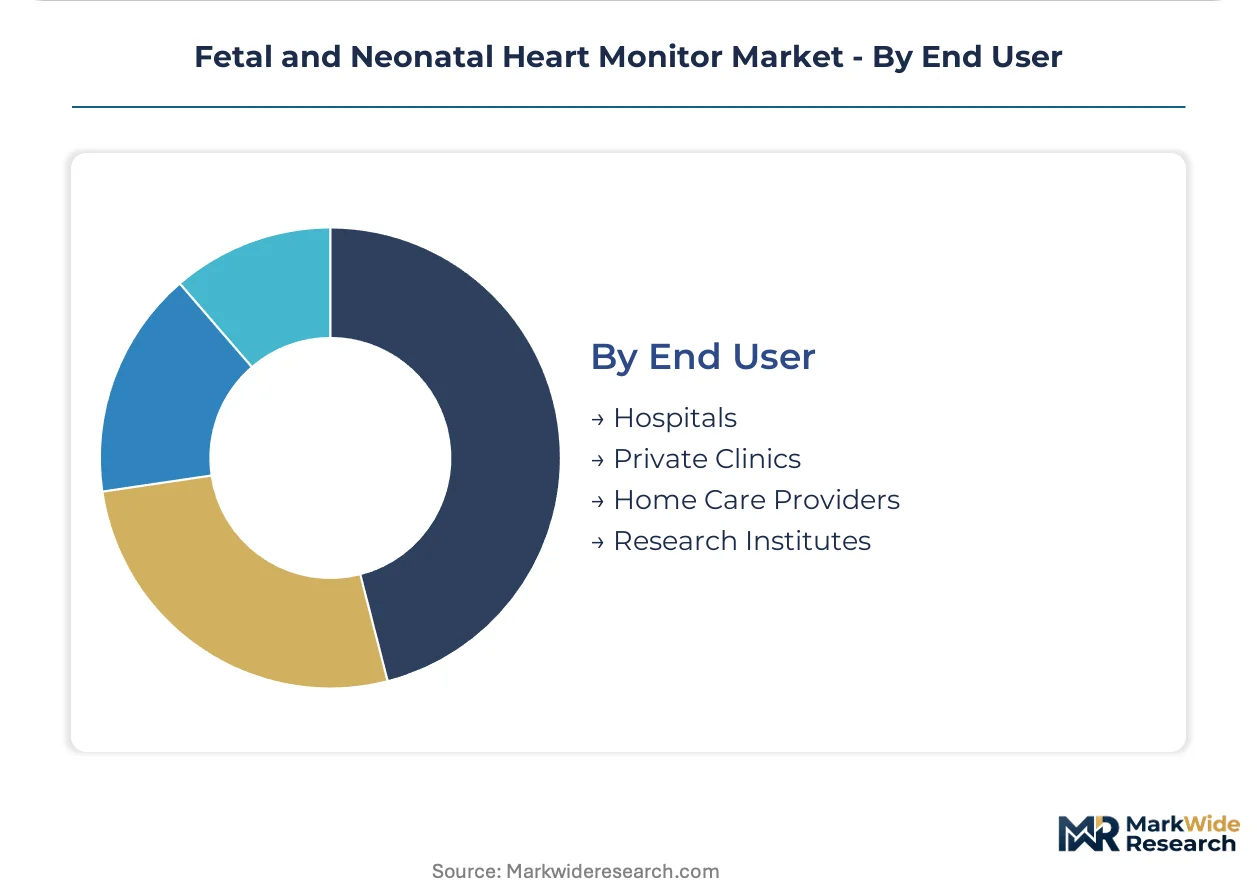
End User:
Procurement authority and reimbursement pathways fragment demand across institutional and distributed care models, with leasing versus ownership preferences diverging sharply.
- Hospitals:Centralized purchasing departments negotiate fleet-wide subscription contracts with uptime guarantees and preventive maintenance schedules. United States health systems unbundle service agreements to third-party clinical engineering firms. Capital expenditure constraints accelerate operational expenditure transitions.
- Home Care Providers:Portable Doppler and wireless patch systems enable high-risk outpatient surveillance with cloud-connected waveform transmission. Reimbursement eligibility under remote patient monitoring codes drives adoption in Germany and the United States. FDA clearance for home-use indications remains limited.
- Private Clinics:Independent obstetric practices prioritize cost-efficient portable monitors for routine prenatal surveillance.
- Research Institutes:Academic medical centers source specialized magnetocardiography and high-sampling-rate ECG systems for clinical trial endpoints.
Contract value favors Hospitals; expansion elasticity favors Home Care Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement incentives for remote maternal monitoring are reshaping procurement patterns across major healthcare economies. Tertiary maternal centers in developed markets accelerate wireless fleet deployment while emerging economies expand provincial hospital infrastructure. Regulatory harmonization pressures concentrate vendor compliance investments in the United States, Germany, and China.
United States
CMS remote patient monitoring reimbursement codes drive adoption of cloud-connected Doppler systems among high-risk obstetric populations. FDA 510(k) clearance pathways for wireless telemetry devices extend development timelines but validate premium positioning. Texas Medical Center and Boston's Longwood Medical Area anchor concentrated demand for AI-embedded edge monitoring systems.
Germany
EU MDR post-market surveillance mandates accelerate replacement cycles among university-affiliated perinatal centers seeking certified equipment upgrades. BfArM vigilance reporting requirements elevate documentation burdens for manufacturers without established quality management systems. Berlin-Brandenburg and Bavaria's medical technology clusters concentrate procurement authority for multi-hospital wireless fleet contracts.
China
National Health Commission tertiary hospital expansion targets concentrate demand in tier-one cities managing high-risk pregnancy volumes. NMPA Class II medical device registration requirements extend market access timelines for new entrants relative to domestic incumbents. Yangtze River Delta hospital procurement consortia negotiate volume-based pricing for portable monitor configurations.
Japan
PMDA priority review vouchers for maternal-fetal medicine devices incentivize local clinical trial investments by multinational manufacturers. METI medical device export promotion programs support domestic manufacturers seeking ASEAN market expansion. Kanto region perinatal centers pilot magnetocardiography systems for fetal arrhythmia diagnosis in academic settings.
United Kingdom
NHS England maternity transformation program funding prioritizes continuous cardiotocography capability across birthing center networks. MHRA post-Brexit regulatory autonomy maintains EU MDR alignment while streamlining domestic device registration pathways. London-Southeast integrated care systems unbundle service contracts from equipment leases to third-party clinical engineering providers.
Fetal and Neonatal Heart Monitor Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented maternity ward procurement environments. Equipment leasing models and subscription fleet management are consolidating vendor relationships around recurring revenue capabilities rather than hardware specifications. Three archetypes dominate: diversified medical technology conglomerates with backward integration into transducer manufacturing, mid-tier portable monitor specialists competing on configuration flexibility, and emerging AI-analytics platforms seeking edge-computing partnerships. Competitive moves concentrate on M&A for telemetry software capabilities and strategic partnerships with cloud infrastructure providers.
Among diversified medical technology conglomerates, GE HealthCare and Philips Healthcare occupy positions as archetypal channel controllers with installed base advantages and service integration capabilities. Siemens Healthineers exemplifies the European-centered competitor leveraging regulatory compliance infrastructure across EU MDR jurisdictions. These three anchors represent distinct geographic origins and corporate structures while competing on similar subscription-based leasing terms.
| Leading Market Players |
|---|
| GE HealthCare |
| Philips Healthcare |
| Siemens Healthineers |
| Medtronic PLC |
| Mindray |
| Drägerwerk AG & Co. KGaA |
| Spacelabs Healthcare |
| Edan Instruments |
| Fujifilm SonoSite |
| Others |
Supply Flow & Price Mechanics
Shanghai-Rotterdam container freight corridors transmit cost volatility from piezoelectric crystal suppliers through to hospital procurement departments, compressing margins on ECG electrode assemblies while amplifying price spreads between FDA-cleared wireless systems and uncertified portable alternatives. This logistics tension concentrates pricing power among manufacturers with captive transducer production, forcing mid-tier assemblers into unfavorable contract terms.
Pricing Analysis
Certification level creates the primary spread across the product spectrum, with FDA 510(k)-cleared and EU MDR-certified wireless monitors commanding premium positioning against uncertified portable alternatives. Subscription-based leasing models now dominate hospital procurement, replacing per-unit transactional sales with recurring service streams that bundle preventive maintenance and software updates. Cost compression in the portable monitor tier intensifies as provincial maternal centers in China and Germany prioritize EU MDR compliance budgets over feature expansion. Mid-tier hospital buyers exhibit acute price sensitivity, while tertiary maternal centers in the United States absorb premiums for AI-embedded edge systems.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized EMS providers in Malaysia, Mexico, and Poland that assemble wireless telemetry units and portable monitor chassis for major device brands. Piezoelectric crystal supply draws from Japanese and German specialty ceramics manufacturers, while silver-silver chloride electrode production sources from Chinese precious metal processors. Single-source vulnerability in ultrasound transducer frequency calibration equipment creates chokepoint exposure for new entrants seeking rapid product launches. Distribution runs through hospital GPO contracts and regional medical device distributors with ISO 13485-certified service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment and installed base switching costs protect incumbent positions. Network effects from cloud-connected telemetry platforms amplify these barriers for new entrants.
For Market Incumbents: Pre-empt subscription fleet consolidation by acquiring independent service organizations with ISO 13485 certification, neutralizing third-party clinical engineering firms that fragment service revenue. Extend backward integration into piezoelectric crystal supply chains to offset silver electrode cost volatility and secure transducer frequency calibration capacity before mid-tier competitors lock in supplier commitments.
For New Entrants and Emerging Players: Build out AI-assisted arrhythmia detection capabilities as a software companion to existing hardware platforms, bypassing FDA 510(k) hardware clearance timelines. Target home care provider channels in Germany and the United States where remote patient monitoring reimbursement codes create elasticity for cloud-connected portable Doppler systems with limited regulatory burden.
For Investors and Strategic Acquirers: Telemetry software specialists with FHIR integration capabilities and edge-computing partnerships represent the most attractive acquisition archetype for platform consolidation plays. Long-term viability hinges on recurring revenue ratios from subscription contracts rather than hardware shipment volumes. Watch FDA breakthrough device designations for AI-embedded NICU monitors as an inflection signal for regulatory pathway acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | FDA clearance validates premium positioning for wireless telemetry systems in United States tertiary centers. |
| EU MDR CE Marking Pathway | MDR certification unlocks replacement cycle demand among German university-affiliated perinatal centers. |
| Hospital System Partnership | Multi-hospital fleet contracts with uptime guarantees secure recurring service revenue streams. |
| Software Companion Development | AI inference engines embedded at the monitor edge reduce NICU alert latency and IT infrastructure requirements. |
| Reimbursement Strategy | Remote patient monitoring coding alignment enables cloud-connected Doppler adoption among United States home care providers. |
Methodological Framework
The analysis maps wireless telemetry systems, portable monitors, fetal Dopplers, and transducer components, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and clinical engineering directors. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS reimbursement code databases, and NMPA registration records. Bottom-up unit demand estimates triangulated against top-down market sizing from hospital procurement database analysis.
Assumptions held fixed include EU MDR transition timelines, FDA clearance pathway durations, and CMS remote monitoring reimbursement stability, while variables included China's tertiary hospital expansion pace and silver electrode commodity price trajectories. Segmentation modeling spanned product type, technology methodology, clinical application, and end-user procurement authority across the projection horizon. CAGRs derived from logistic diffusion curves fitted to replacement cycle data and fleet penetration rates, with AI adoption velocity and wireless telemetry battery chemistry improvements as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native telemetry startups or Chinese domestic manufacturers with NMPA fast-track access would shift outcomes. Regulatory delays at FDA or notified body capacity constraints represent revision risks. Quarterly review of FDA 510(k) clearance queues and EU MDR certificate expiration schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
Patient Monitoring Pods Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
Global Vital Sign Monitoring Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
Asthma Monitoring Devices Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market