
 Multi-Channel Remote ECG Monitors Market | 2026-2036
Multi-Channel Remote ECG Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Channel Remote ECG Monitors Market Foresight
China is rewriting capacity dynamics in connected medical device manufacturing as domestic producers scale output of Bluetooth-enabled cardiac wearables. Philips Healthcare leverages its installed base of hospital telemetry systems to extend into home-based monitoring workflows. GE Healthcare anchors its position through deep integration with enterprise imaging and electronic health record networks. BioTelemetry Inc. competes on service density, operating one of the largest independent cardiac monitoring networks in North America.
Multi-channel remote ECG monitors are ambulatory electrocardiography systems that capture simultaneous electrical signals from multiple cardiac leads, typically three to twelve channels, and transmit data via cellular, Wi-Fi, or Bluetooth protocols to centralized analysis platforms for real-time or near-real-time arrhythmia detection. These devices serve the primary commercial purpose of enabling continuous cardiac surveillance outside traditional clinical settings, reducing emergency department utilization while capturing transient events that intermittent monitoring misses. Mobile cardiac telemetry systems command premium positioning due to their ability to deliver real-time clinician alerts during symptomatic episodes, whereas Holter monitors retain volume leadership in routine diagnostic workups. Wearable device technology is gaining fastest traction among homecare patients, though cloud-based solutions concentrate margin pools through recurring software licensing and data analytics subscriptions.
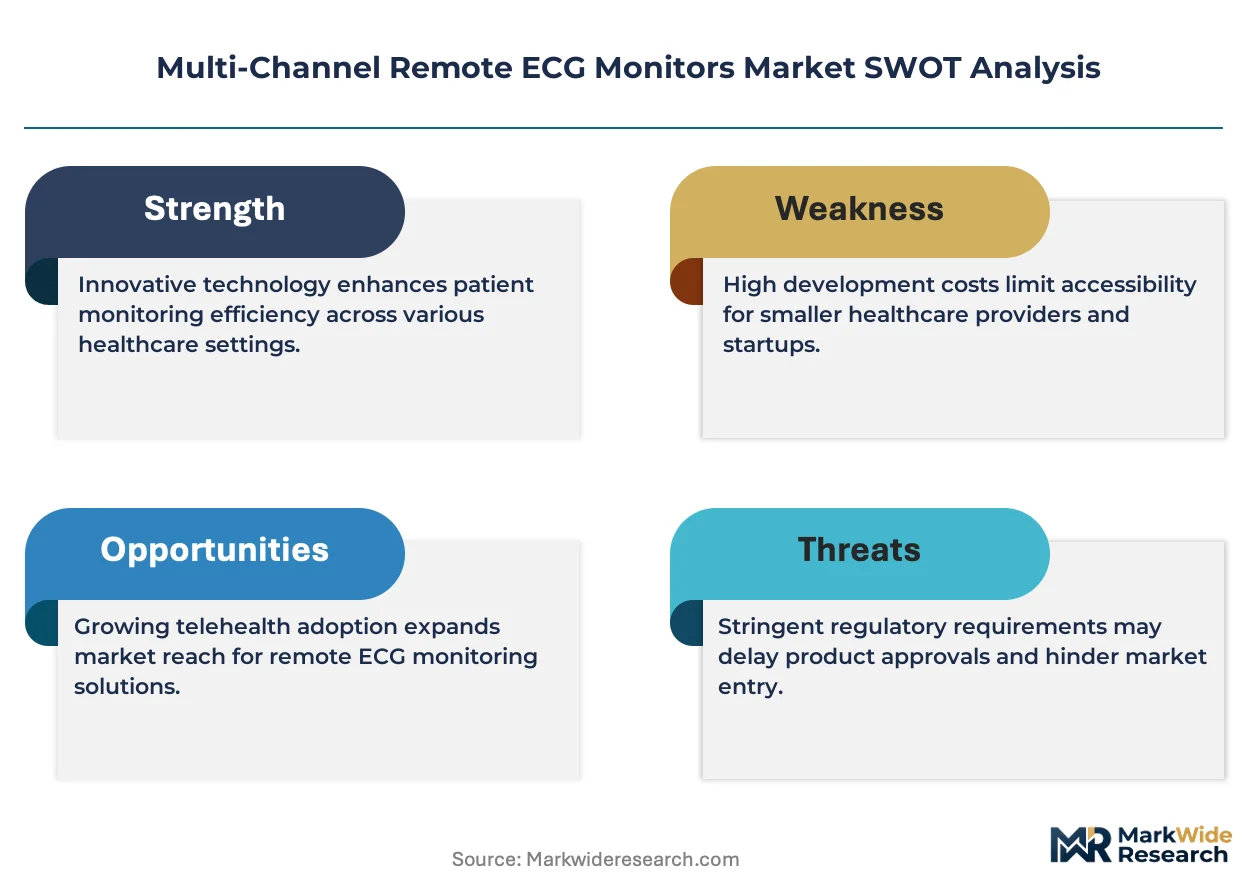
FDA premarket clearance pathways for software-as-a-medical-device and the EU MDR's tightened clinical evidence requirements for active implantable peripherals are reshaping product development timelines and market access conditions for multi-channel ECG systems. HIPAA security rule enforcement and GDPR data localization mandates further constrain how patient waveform data traverses international cloud infrastructure, favoring vendors with regional data center deployments. Stakeholders must weigh regulatory compliance investment against the pace of reimbursement expansion for remote physiological monitoring codes.
Market Dynamics
Cloud-based telemetry platforms are compressing the traditional hardware-software boundary, forcing vendors to restructure around recurring data analytics subscriptions rather than device margins.
Growth Catalysts
- Medicare RPM reimbursement:CMS remote patient monitoring codes now reimburse multi-channel ECG services monthly, creating sustainable revenue streams for ambulatory monitoring networks across United States hospital systems.
- Bluetooth-enabled cardiac wearables:Domestic Chinese manufacturers are scaling production of connected medical devices, flooding export markets with lower-cost hardware that accelerates patient access to continuous monitoring.
- Value-based care penalties:Hospital readmission reduction programs under CMS rules drive integrated delivery networks to expand remote cardiac surveillance programs beyond traditional telemetry wards.
Market Restraints
- GDPR data localization:EU mandates requiring patient waveform data to reside within regional cloud infrastructure inflate vendor operating costs and complicate cross-border service delivery.
- Semiconductor supply concentration:Bluetooth and cellular module production clusters in East Asia expose hardware manufacturers to geopolitical disruption and input cost volatility.
- EU MDR clinical evidence requirements:Tightened premarket pathways for active implantable peripherals extend product development timelines and raise regulatory compliance investment thresholds.
Strategic Opportunities
- Homecare patient segments:Wearable device technology penetration remains underdeveloped among post-acute cardiac patients discharged to residential settings, representing whitespace for subscription-based monitoring services.
- AI-ECG convergence:Machine learning algorithms trained on multi-lead waveform databases enable automated arrhythmia classification, reducing human analyst overhead while expanding service capacity.
- India PLI scheme:Production-linked incentives for medical device manufacturing attract contract assembly investment, creating regional supply hubs for Bluetooth-enabled cardiac hardware serving South Asian markets.
Industry Challenges
- FDA SaMD validation timelines:Software-as-a-medical-device premarket clearance pathways lack precedent for adaptive algorithms, creating uncertainty in regulatory submission strategies.
- Legacy EHR integration:Enterprise imaging and electronic health record networks operate on proprietary data standards, forcing costly custom interface development for telemetry platform vendors.
- Cardiac electrophysiologist scarcity:Interpretation of multi-channel ambulatory recordings requires specialized clinical expertise that concentrates in academic medical centers, constraining service scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Channel Remote ECG Monitors Market |
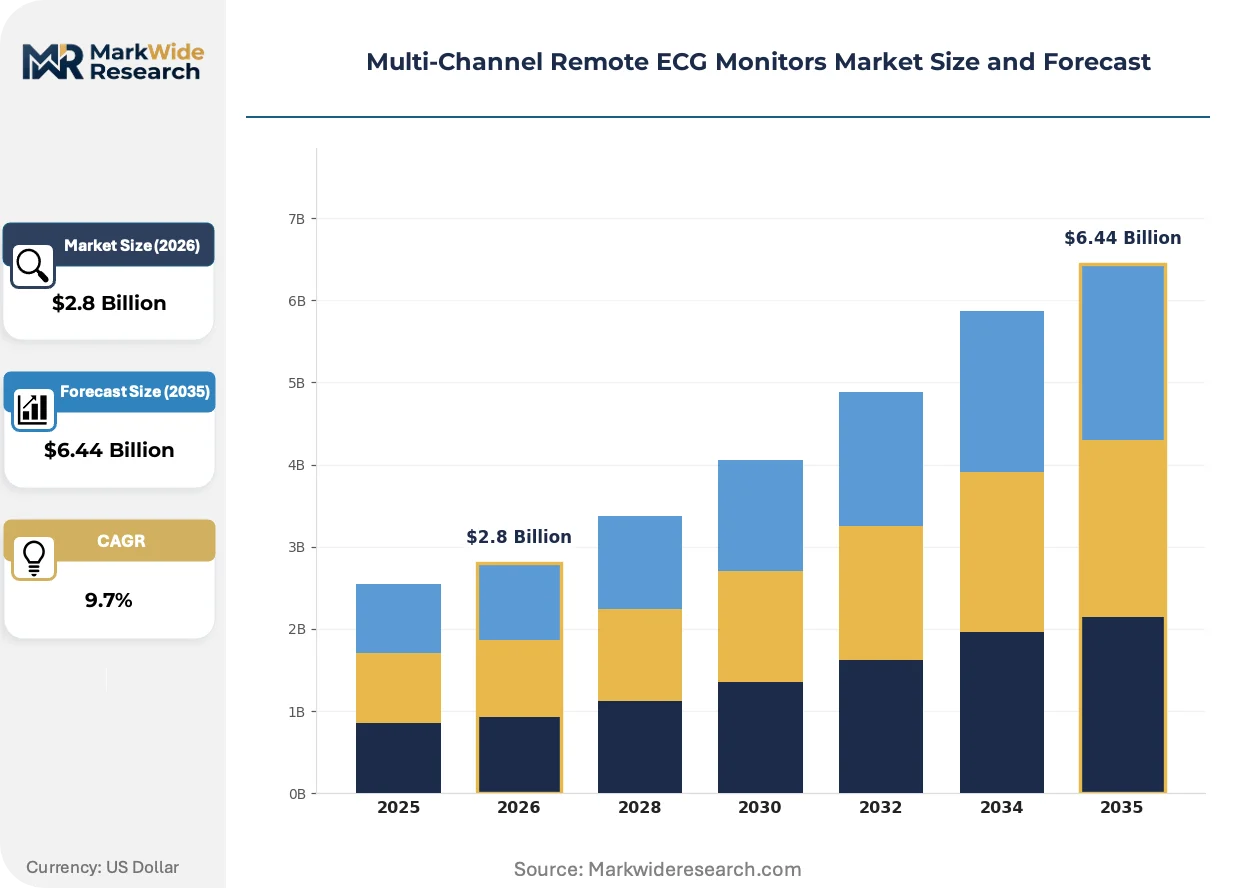
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holter Monitors, Event Monitors, Mobile Cardiac Telemetry, Wireless ECG Monitors End User: Hospitals, Telehealth Providers, Ambulatory Surgery Centers, Homecare Patients Technology: Cloud-Based Solutions, Bluetooth-Enabled Devices, Mobile Apps, Wearable Devices Delivery Mode: Subscription-Based Services, One-Time Purchase, Pay-Per-Use, Bundled Solutions |
| Companies Covered | Philips Healthcare, GE Healthcare, BioTelemetry Inc., Nihon Kohden Corporation, Medtronic plc, iRhythm Technologies Inc., Schiller AG, Shenzhen Mindray Bio-Medical Electronics Co. Ltd., VivaLNK Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Channel Remote ECG Monitors Market Shifts & Advancements
Artificial intelligence inference engines are migrating from centralized cloud servers to edge-deployed monitoring hardware, compressing alert latency while raising new validation requirements for distributed medical algorithms.
Deep learning models trained on twelve-lead ECG databases now classify atrial fibrillation, ventricular tachycardia, and conduction abnormalities with diagnostic performance approaching specialist cardiologist interpretation. Academic medical centers in Germany and the United States are piloting these algorithms for real-time triage of mobile cardiac telemetry alerts. This capability is virtualizing the traditional human analyst workflow, collapsing the labor cost structure that has historically constrained service margins.
The EU MDR's tightened clinical evidence requirements for active implantable peripherals now mandate prospective validation studies for algorithm-augmented diagnostic devices, extending market access timelines by eighteen to thirty-six months. Manufacturers must submit real-world performance data from European patient populations, not extrapolated from US or Asian cohorts. Cardiac wearable vendors with limited European installed bases face disproportionate compliance burdens compared to incumbents with established EU telemetry networks.
Integrated delivery networks are consolidating vendor relationships around single-source telemetry platforms that bundle hardware, software, and clinical interpretation services. Health systems in Texas, California, and Florida now issue multi-year sole-source contracts to capture volume discounts and simplify data governance. This procurement concentration disadvantages standalone device manufacturers lacking captive monitoring service operations, forcing partnerships or vertical capability acquisitions to remain competitive.
Multi-Channel Remote ECG Monitors Market Segmentation
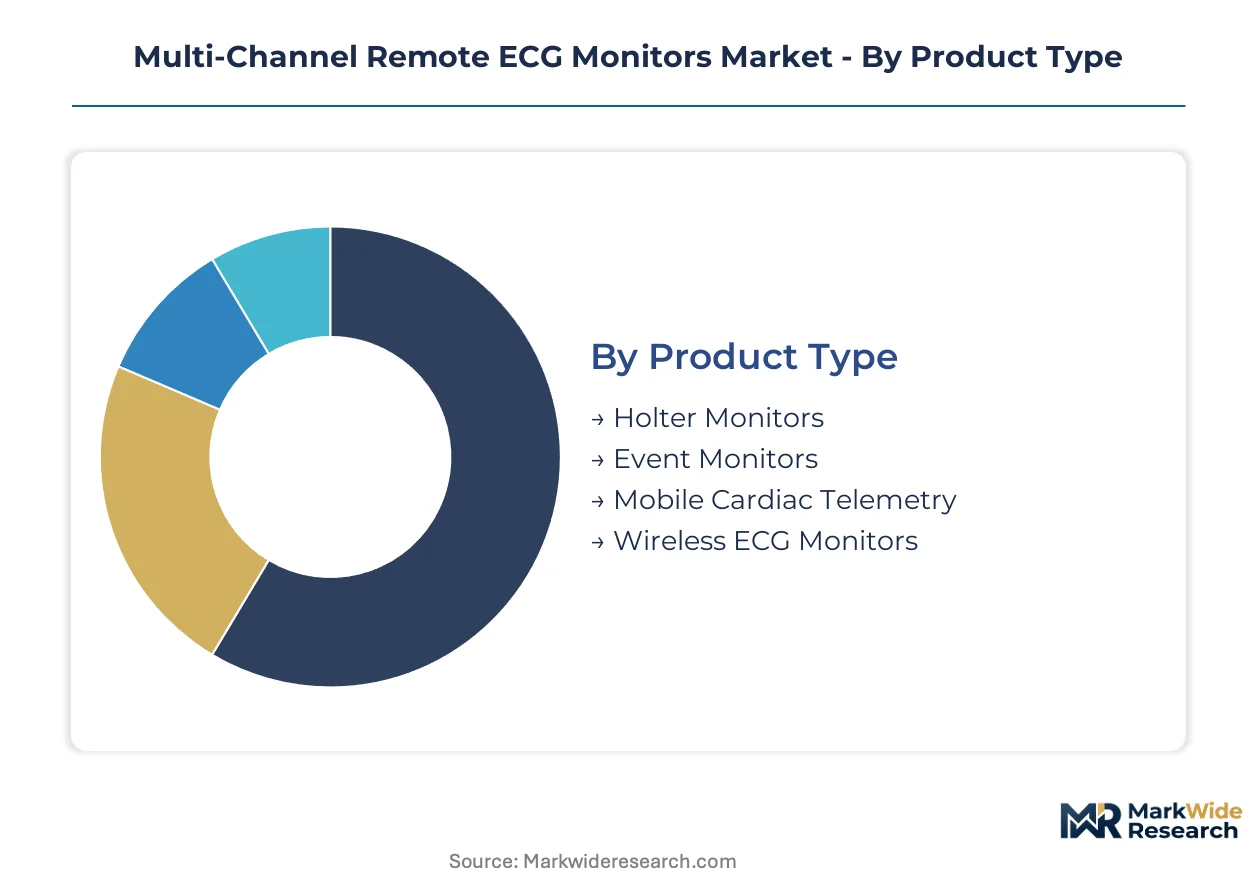
Segmentation in multi-channel remote ECG monitors reveals divergent margin structures across hardware, software, and service layers. Vendors configure after-sales-service intensity differently by product type and delivery mode, reshaping customer lifetime value calculations.
Product Type:
After-sales-service intensity varies sharply across product categories, with telemetry systems demanding continuous cloud infrastructure support while Holter monitors require minimal ongoing vendor engagement.
- Mobile Cardiac Telemetry:Real-time cellular transmission systems capture multi-lead waveforms with automated arrhythmia alerts routed to centralized monitoring centers. Demand concentrates in United States hospital systems seeking CMS reimbursement for remote patient monitoring services, though subscription renewal rates depend on clinical outcome documentation.
- Holter Monitors:Continuous 24-48 hour ambulatory recorders store ECG data for retrospective analysis without real-time transmission capabilities. Volume leadership persists in routine diagnostic workups at German cardiology practices where cost-conscious procurement favors established hardware paradigms over recurring service fees.
- Event Monitors:Patient-activated or auto-triggered devices capture symptomatic episodes through intermittent recording.
- Wireless ECG Monitors:Wi-Fi-enabled bedside systems bridge inpatient telemetry and home monitoring workflows.
Holter monitors hold the largest share; momentum sits with mobile cardiac telemetry.
End User:
Customer procurement sophistication determines pricing architecture, with integrated delivery networks negotiating enterprise licenses while homecare segments absorb per-device premiums.
- Hospitals:Acute care systems deploy multi-channel telemetry for post-operative cardiac surveillance and step-down unit monitoring. Procurement in Texas and California health systems favors sole-source contracts bundling hardware, software, and clinical interpretation to simplify data governance.
- Homecare Patients:Post-acute cardiac patients discharged to residential settings drive wearable device adoption for longitudinal rhythm monitoring. Reimbursement pathways through United States Medicare create sustainable payment mechanisms, though patient adherence to wearing protocols constrains effective monitoring duration.
- Telehealth Providers:Virtual care platforms integrate remote ECG feeds into asynchronous consultation workflows.
- Ambulatory Surgery Centers:Same-day procedure facilities deploy compact monitoring for pre-operative risk stratification.
Hospitals command the dominant revenue position; homecare patients represent the steepest expansion trajectory.
Technology:
Technology stack choices determine regulatory pathway complexity, with cloud-based platforms facing HIPAA security rule enforcement while wearable hardware navigates FDA premarket clearance timelines.
- Cloud-Based Solutions:Centralized telemetry platforms aggregate multi-lead data streams for algorithmic analysis and clinician dashboard visualization. Integrated delivery networks in Florida now mandate regional data center deployments to satisfy patient privacy requirements, inflating vendor infrastructure costs.
- Wearable Devices:Skin-adhesive or chest-strap form factors enable multi-day continuous monitoring with Bluetooth transmission to paired smartphones. Chinese domestic manufacturers are scaling production of connected cardiac wearables, flooding export markets with lower-cost hardware that accelerates patient access.
- Bluetooth-Enabled Devices:Short-range wireless protocols connect sensors to relay devices or mobile handsets.
- Mobile Apps:Software interfaces on iOS and Android platforms display ECG waveforms and patient symptom diaries.
Cloud-based solutions capture the recurring revenue concentration; wearable devices are climbing the fastest.
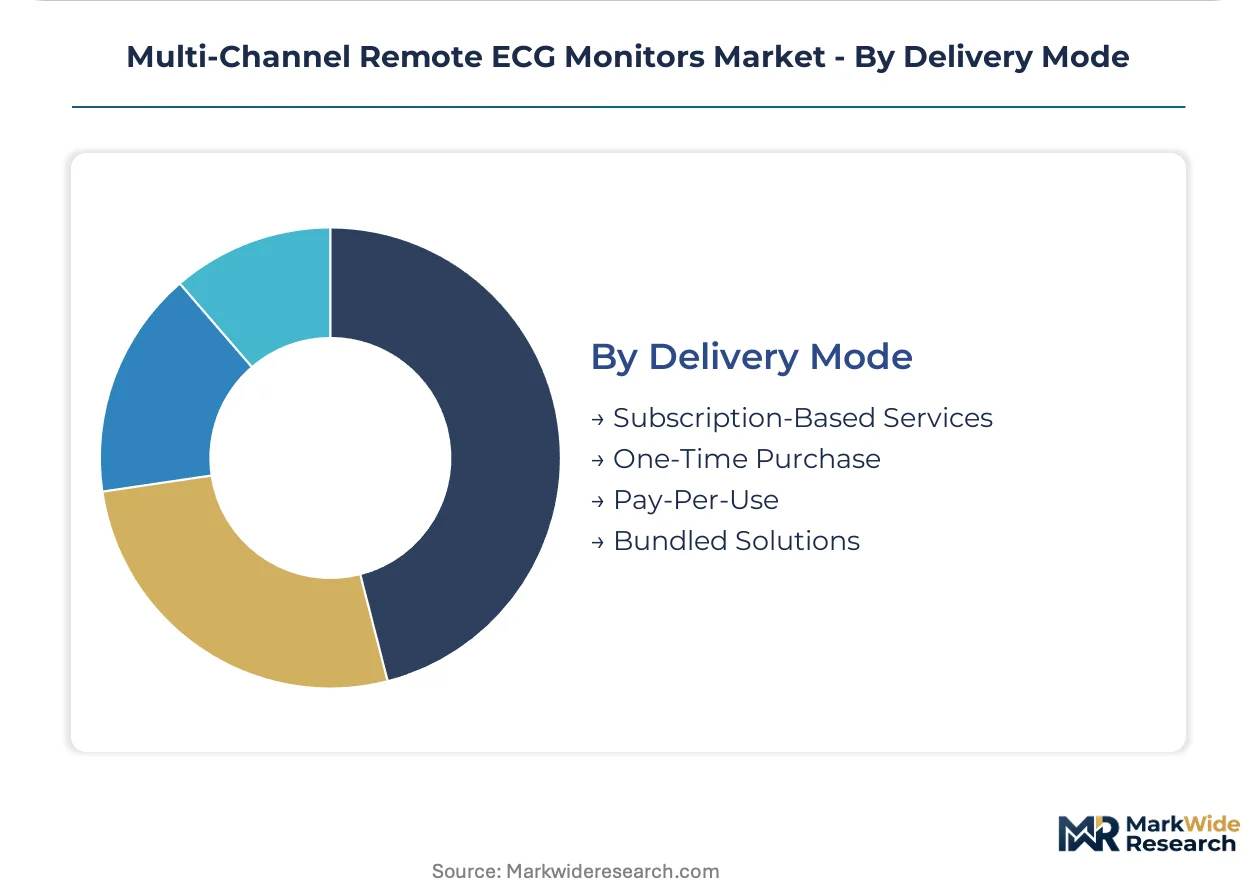
Delivery Mode:
Contract structure shapes vendor cash flow predictability, with subscription models smoothing revenue recognition against lumpy capital equipment sales.
- Subscription-Based Services:Monthly or annual fees bundle device provision, cellular connectivity, cloud analytics, and clinical interpretation into unified per-patient pricing. United States Medicare remote patient monitoring reimbursement codes validate this model for ambulatory monitoring networks.
- Bundled Solutions:Multi-year enterprise agreements combine hardware deployment with professional services and outcome guarantees. Procurement concentration among Texas and California health systems favors this structure for operational simplicity.
- One-Time Purchase:Capital equipment transactions transfer ownership risk to the acquiring facility.
- Pay-Per-Use:Per-study or per-day pricing aligns costs with actual monitoring duration.
Subscription-based services dominate new contract value; bundled solutions are gaining share fastest among consolidated health systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA reimbursement pathways anchor United States demand, while EU MDR compliance costs and Chinese manufacturing scale reshape competitive geography across national markets.
United States
Medicare remote patient monitoring codes now reimburse multi-channel ECG services monthly, sustaining ambulatory monitoring network revenue. CMS value-based care penalties for hospital readmissions drive integrated delivery networks in Texas and California toward sole-source telemetry contracts. The Boston-Cambridge corridor concentrates AI-ECG algorithm development, with academic medical centers piloting real-time arrhythmia classification systems.
Germany
Cost-conscious cardiology practices in Bavaria and North Rhine-Westphalia favor Holter monitor hardware over recurring subscription fees, preserving volume leadership for traditional diagnostic workflows. EU MDR tightened clinical evidence requirements extend product development timelines for algorithm-augmented devices entering European markets. The Baden-Württemberg medical technology cluster hosts validation studies for twelve-lead ECG deep learning models trained on European patient cohorts.
China
Domestic manufacturers scale Bluetooth-enabled cardiac wearable production for export market penetration, compressing hardware cost structures internationally. NMPA regulatory pathways for software-as-a-medical-device accelerate premarket clearance for cloud-based telemetry platforms. The Yangtze River Delta manufacturing corridor concentrates connected medical device assembly capacity, with Shenzhen-based producers flooding export channels.
India
Production-linked incentive schemes for medical device manufacturing attract contract assembly investment for regional supply hub development. CDSCO regulatory harmonization with international standards reduces market access friction for imported multi-channel ECG systems. The Karnataka-Telangana medical technology corridor near Bangalore hosts emerging cardiac wearable assembly operations serving South Asian demand.
Japan
PMDA premarket approval requirements emphasize local clinical evidence generation for algorithm-driven diagnostic devices, extending entry timelines for foreign vendors. METI industrial policy supports domestic production of precision medical sensors for cardiac monitoring applications. The Kansai region around Osaka maintains concentration in traditional electrocardiography equipment manufacturing.
Multi-Channel Remote ECG Monitors Market Competitive Landscape
Diversified health technology conglomerates and specialized cardiac monitoring service providers split the market between integrated platform bundling and independent network density strategies. Hospital procurement concentration around single-source contracts favors vendors with captive clinical interpretation services. Three archetypes dominate: diversified medical technology majors leveraging installed base extension, independent telemetry service operators competing on analyst network scale, and emerging wearable-focused hardware specialists. Competitive dynamics center on vertical capability acquisition and regional data center deployment for compliance localization.
Within the diversified technology tier, Philips Healthcare and GE Healthcare exemplify platform bundling strategies that combine enterprise imaging integration with telemetry service extension. BioTelemetry Inc. occupies a distinct position as an independent monitoring network operator without captive hardware manufacturing. Among Asia-based manufacturers, Shenzhen Mindray Bio-Medical Electronics Co. Ltd. represents the contract assembly scale archetype serving export market volume demand.
| Leading Market Players |
|---|
| Philips Healthcare |
| GE Healthcare |
| BioTelemetry Inc. |
| Nihon Kohden Corporation |
| Medtronic plc |
| iRhythm Technologies Inc. |
| Schiller AG |
| Shenzhen Mindray Bio-Medical Electronics Co. Ltd. |
| VivaLNK Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in Shenzhen-based Bluetooth module assembly is compressing hardware margins while elevating bargaining power for integrated delivery networks negotiating multi-year telemetry contracts. This utilization dynamic forces Chinese original equipment manufacturers toward extended payment terms and volume discounts, while cloud-platform vendors capture pricing power through recurring software subscriptions that hospital systems cannot easily displace.
Pricing Analysis
Price spreads between United States and Chinese procurement markets exceed threefold for comparable wearable hardware, though subscription-based service fees converge globally. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared mobile cardiac telemetry systems from CE-marked Holter monitors and unbranded Bluetooth wearables. Cost compression in economy-tier hardware is intensifying because Yangtze River Delta manufacturers are scaling output for export markets. Homecare patients exhibit highest price sensitivity, while hospital systems absorbing CMS reimbursement demonstrate lowest sensitivity to per-device premiums.
Supply Chain Analysis
Extended payment terms now stretch ninety to one hundred twenty days for semiconductor module procurement, reflecting supplier financing pressure from downstream original equipment manufacturers. Component sourcing draws from Taiwan for Bluetooth system-on-chip design, South Korea for cellular modem fabrication, and China for final device assembly. Raw material dependencies center on lithium-polymer batteries, medical-grade silicone adhesives, and FR-4 printed circuit board substrates. Single-source vulnerability concentrates in cellular baseband processor supply. Distribution runs through group purchasing organizations for hospital systems and direct-to-consumer channels for wearable devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-channel remote ECG monitoring sits in early-cycle expansion, with Medicare reimbursement tailwinds now validating sustainable payment models that will drive penetration through the decade.
For Market Incumbents: Entrench market position through captive clinical interpretation service density and regional data center deployment for HIPAA compliance localization. Deepen backward integration into cloud analytics infrastructure to defend against software-as-a-medical-device entrants. Prioritize sole-source contract renewal with Texas and California integrated delivery networks before competitive RFP cycles accelerate. For New Entrants and Emerging Players: Build out AI-augmented arrhythmia classification capabilities targeting post-acute homecare segments where patient adherence gaps create service whitespace. Penetration remains shallow among Medicare-eligible populations discharged to residential settings. Pursue white-label hardware partnerships with Shenzhen manufacturers to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based telemetry platforms as software margins expand relative to hardware provisioning costs. Long-term viability favors platform operators with recurring revenue concentration over device-centric hardware specialists. Monitor FDA premarket clearance velocity for software-as-a-medical-device algorithms as the critical inflection signal for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Sole-source contracts with Texas and California IDNs lock in multi-year revenue visibility. |
| FDA Submission | Software-as-a-medical-device clearance for AI-ECG algorithms accelerates time-to-reimbursement. |
| CE Marking Pathway | EU MDR compliance for algorithm-augmented devices opens German cardiology practice procurement. |
| Backward Integration | In-house cloud infrastructure reduces dependency on third-party hosting for HIPAA compliance. |
| Reimbursement Strategy | CMS remote patient monitoring code optimization secures sustainable Medicare payment pathways. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cardiac electrophysiologists, hospital biomedical engineering directors, GPO contracts managers, and cloud telemetry platform product executives. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare reimbursement code filings, EU MDR technical documentation requirements, and hospital procurement contract disclosures. Bottom-up unit demand estimates triangulated against top-down addressable market sizing across product type, end user, and technology segmentation dimensions.
Calibration against historical shipment data from connected medical device manufacturers anchored volume projections across the analysis window. Segmentation modeling captured mobile cardiac telemetry, Holter monitors, event monitors, and wireless ECG systems by hospital, homecare, telehealth, and ambulatory surgery center end users. Technology stack differentiation across cloud-based, wearable, Bluetooth-enabled, and mobile app platforms shaped adoption curve assumptions. CAGRs derived from regression analysis of reimbursement expansion rates and hardware cost decline trajectories.
Stress conditions across CMS reimbursement policy shifts, EU MDR enforcement stringency, and semiconductor supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway timelines and payment parity evolution. Macroeconomic contraction, regulatory acceleration, or algorithmic diagnostic breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
Asthma Monitoring Devices Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Remote Home Monitoring Systems Market
Patient Monitoring
Asia-Pacific Fetal and Neonatal Monitoring Market
Patient Monitoring
South America Respiratory Monitoring Market
Patient Monitoring
Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market