
 Global Home Blood Pressure Monitoring Devices Market | 2026-2036
Global Home Blood Pressure Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Blood Pressure Monitoring Devices Market Foresight
Multi-source component procurement is broadening among device manufacturers seeking supply resilience for pressure sensors and display modules. Omron Healthcare Inc. leverages vertically integrated manufacturing in Japan to sustain cost discipline across its upper-arm monitor portfolio. A&D Medical anchors its competitive stance through precision sensor calibration capabilities that differentiate output consistency. Withings SA positions its connected-device ecosystem to navigate the shift from standalone monitors to integrated telehealth platforms.
Home blood pressure monitoring devices are automated or manual instruments that measure arterial pressure through inflatable cuffs, pressure transducers, and digital processing algorithms with accuracy thresholds typically validated against ANSI/AAMI SP10 or equivalent protocols. These instruments serve primarily to enable chronic hypertension patients to track cardiovascular status outside clinical settings and trigger timely medical intervention. Upper arm monitors dominate unit volume due to established clinical trust and favorable reimbursement positioning, while ambulatory devices capture premium margins from cardiology practices seeking 24-hour circadian data. Digital electronic technology leads shipment value by displacing aneroid and mercury platforms under regulatory phase-out mandates.
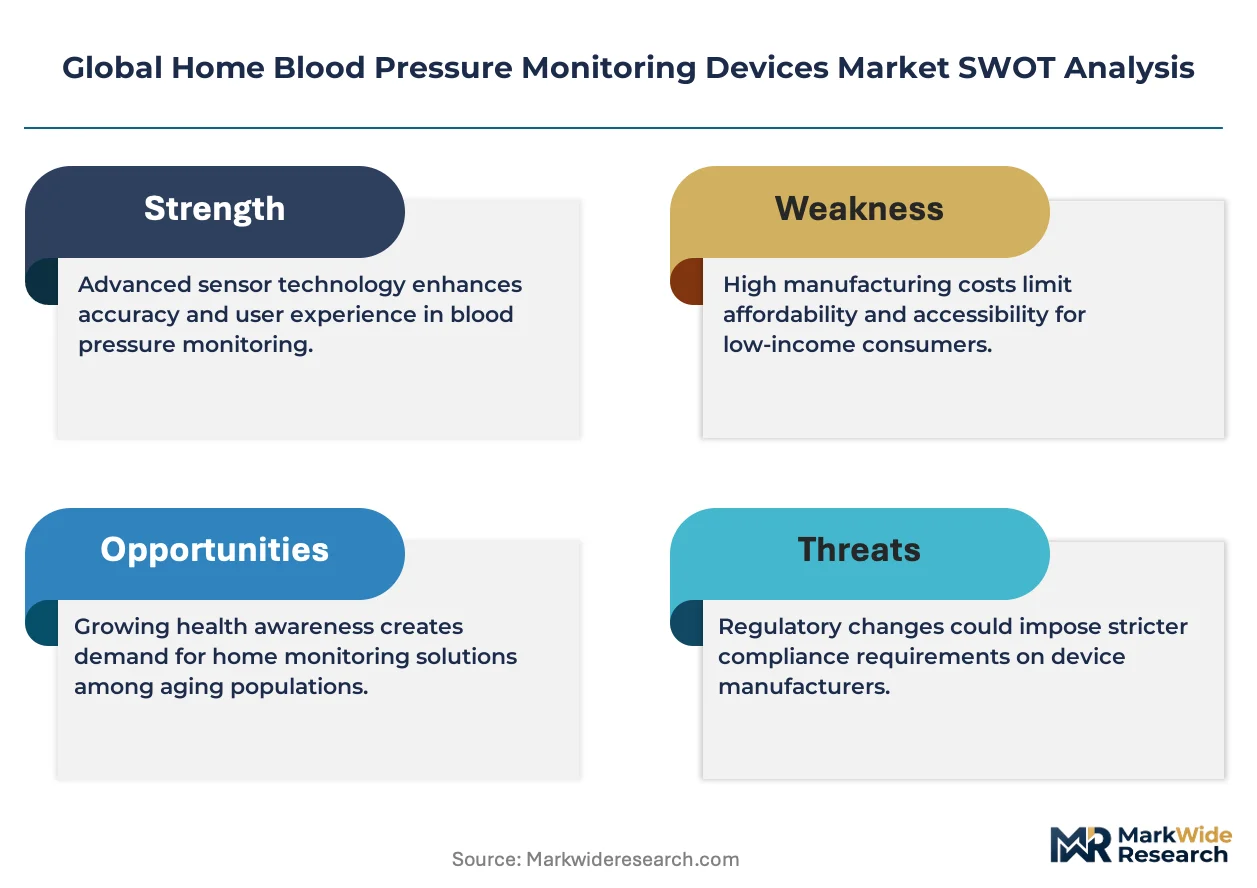
FDA clearance pathways under 510(k) requirements shape product entry timelines for manufacturers targeting the United States, while CE marking under the EU MDR governs European market access with intensified clinical evidence demands. Japan's PMDA enforces JIS T 1115 accuracy standards that filter out lower-precision imports and protect domestic incumbents. Stakeholders must monitor how reimbursement code expansions for remote patient monitoring interact with tightening accuracy validation requirements across jurisdictions.
Market Dynamics
Bluetooth-enabled connectivity and smartphone integration are compressing device replacement cycles across patient populations, creating a structural pull toward connected ecosystems that renders standalone monitors economically obsolete faster than historical depreciation patterns anticipated.
Growth Catalysts
- Remote Patient Monitoring Reimbursement Expansion:United States CMS code expansions for home-based cardiovascular diagnostics reduce patient out-of-pocket burdens and accelerate clinical adoption of ambulatory monitoring protocols.
- Aging Demographics in High-Income Markets:Japan's super-aged population and Germany's expanding hypertensive cohort sustain replacement demand for precision-validated upper-arm devices.
- ANSI/AAMI SP10 Accuracy Validation:Stringent protocol adherence requirements filter out low-precision competitors and elevate clinically trusted manufacturers to preferred supplier status.
Market Restraints
- Pressure Sensor Supply Concentration:Japanese and German sensor foundries control critical MEMS transducer output, exposing device assemblers to allocation risk during semiconductor demand surges.
- Mercury Device Phase-Out Mandates:WHO and national environmental regulations accelerate obsolescence of established aneroid calibration infrastructure without fully subsidized replacement pathways.
- Validation Cost Burden:EU MDR clinical evidence requirements impose documentation costs that disproportionately constrain mid-tier manufacturers seeking CE marking.
Strategic Opportunities
- India's Underpenetrated Home Diagnostics Segment:CDSCO streamlined medical device registration and expanding private insurance coverage create first-mover positioning for Bluetooth-integrated monitors.
- Telehealth Platform Convergence:API-enabled data streaming into electronic health record systems positions hardware vendors as subscription revenue participants rather than discrete device suppliers.
- Brazil's ANVISA Fast-Track Pathway:Priority review designations for cardiovascular remote monitoring devices compress market entry timelines relative to standard 510(k) or MDR routes.
Industry Challenges
- Firmware Cybersecurity Certification:FDA premarket guidance on connected device software assurance extends development timelines and requires specialized engineering talent scarce outside major metropolitan technology clusters.
- Multi-Jurisdiction Accuracy Harmonization:Divergent validation protocols across PMDA JIS T 1115, ANSI/AAMI SP10, and IEC 81060-2 standards force redundant testing expenditures that erode margin on global product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Blood Pressure Monitoring Devices Market |
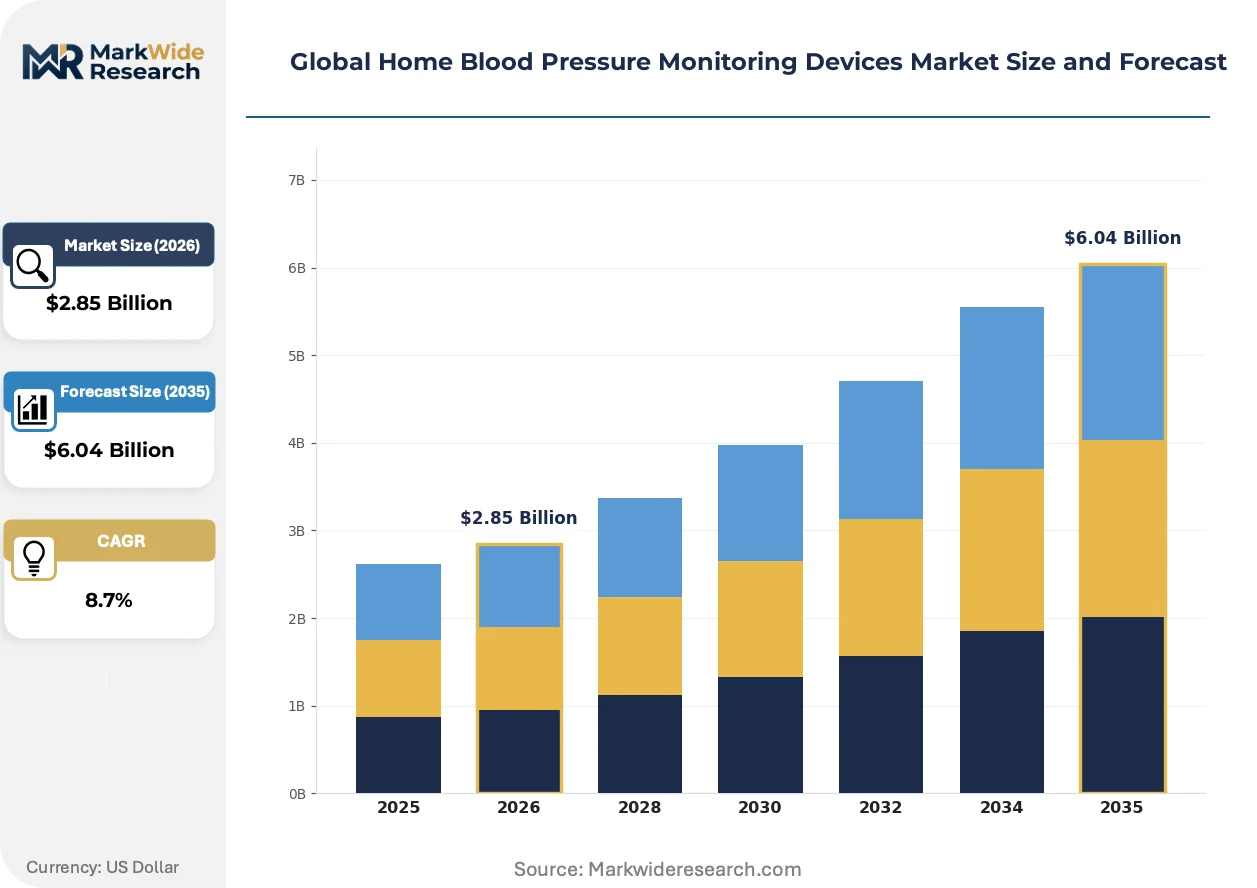
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $6.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upper Arm Monitors, Wrist Monitors, Finger Monitors, Ambulatory Devices Technology: Oscillometric, Aneroid, Mercury Sphygmomanometers, Digital Electronic Application: Hypertension Management, Cardiac Risk Assessment, Prenatal Monitoring, Geriatric Care End User: Home Care Patients, Telehealth Services, Pharmacies, Wellness Centers |
| Companies Covered | Omron Healthcare Inc., A&D Medical, Koninklijke Philips N.V., GE Healthcare, Beurer GmbH, Microlife AG, American Diagnostic Corporation, Withings SA, Rossmax International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Blood Pressure Monitoring Devices Market Shifts & Advancements
Photoplethysmography and cuffless optical sensors are disrupting the mechanical pressure-transducer paradigm, enabling form-factor miniaturization that expands wearable integration possibilities beyond traditional upper-arm positioning.
Optical sensing arrays embedded in wrist-worn and finger-clip configurations are absorbing market share from pneumatic cuff architectures among fitness-oriented and early-stage hypertensive cohorts seeking continuous monitoring without circulatory occlusion. Cardiology practices in the United States and Japan are piloting these platforms for nocturnal blood pressure pattern detection. The technology is absorbing validation investment that previously concentrated on incremental electronic sphygmomanometer precision improvements.
EU MDR Article 10 clinical evidence requirements intensified post-market surveillance obligations for Class IIa cardiovascular devices, compelling manufacturers to maintain active registry participation or risk certificate suspension. German notified bodies and Dutch regulatory consultants report extended review queues as legacy device portfolios undergo technical documentation remediation. Ambulatory blood pressure monitor suppliers with pre-2021 MDD certifications face compressed transition timelines that favor larger entities with dedicated regulatory affairs infrastructure.
Hospital procurement consortia in France and the United Kingdom are unbundling device supply from data platform subscriptions, forcing hardware vendors to compete on unit economics while software-integrated competitors capture recurring revenue streams. Cardiology department buying committees now evaluate total cost of ownership across five-year replacement cycles rather than upfront capital expenditure. This behavioral shift is most visible in National Health Service supply frameworks where integrated telehealth outcomes factor into vendor scorecard weightings.
Global Home Blood Pressure Monitoring Devices Market Segmentation
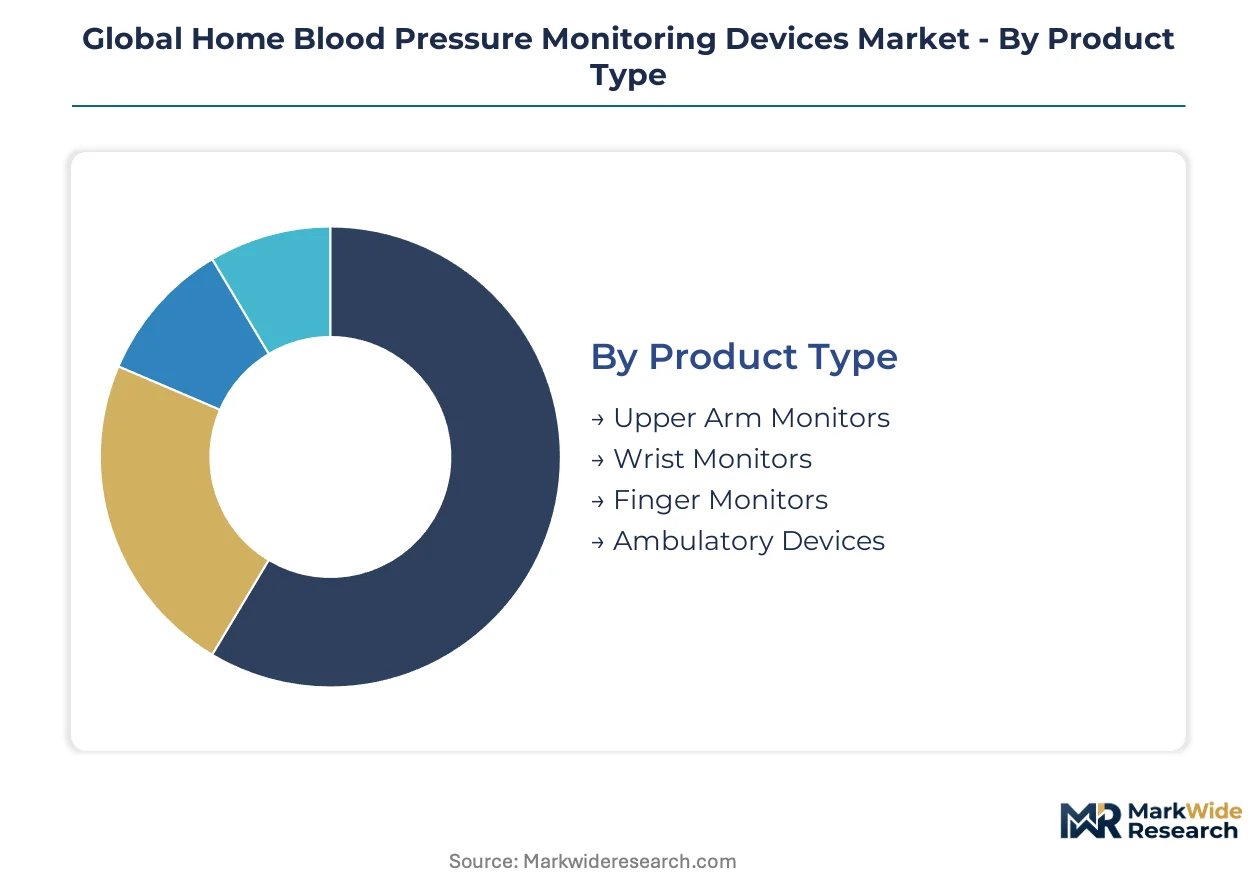
Device selection in home blood pressure monitoring pivots on clinical validation requirements, reimbursement eligibility, and patient dexterity constraints. Manufacturers calibrate portfolio depth across these axes to capture recurring replacement revenue versus one-time diagnostic purchases.
Product Type:
Patient trust in measurement accuracy and physician prescribing patterns determine category preference more than price sensitivity alone.
- Upper Arm Monitors:Inflatable cuffs positioned over the brachial artery with automatic inflation and deflation mechanisms deliver readings correlated to auscultatory reference standards. Demand concentrates in the United States and Germany where CMS and statutory health insurance reimbursement codes favor validated upper-arm protocols for hypertensive patients managing chronic conditions.
- Ambulatory Devices:Programmable cuffs with programmable inflation schedules capture circadian blood pressure variation across 24-hour monitoring windows. Cardiology practices in Japan and the United States deploy these for nocturnal hypertension detection and masked hypertension assessment, commanding premium positioning through clinical workflow integration.
- Wrist Monitors:Compact oscillometric sensors positioned at the radial artery appeal to traveling professionals and patients with limited upper-arm mobility.
- Finger Monitors:Photoplethysmography-based optical sensing at the digital artery serves fitness-oriented users seeking portability over clinical precision.
Volume sits with Upper Arm Monitors; growth tilts toward Ambulatory Devices.
Technology:
Regulatory phase-out mandates and connectivity requirements are compressing the viable technology set faster than patient preference shifts alone would dictate.
- Digital Electronic:Microprocessor-controlled oscillometric detection with automatic cuff inflation, multiple measurement averaging, and Bluetooth data transmission dominates new device registrations. FDA 510(k) clearances and EU MDR certifications concentrate in this category as manufacturers abandon mechanical platforms.
- Oscillometric:Pressure transducer arrays detecting arterial wall oscillations during cuff deflation form the measurement core shared across digital electronic and upper-arm configurations. German and Japanese sensor foundries supply MEMS transducers that determine accuracy thresholds for ANSI/AAMI SP10 validation.
- Aneroid:Mechanical gauge-based sphygmomanometers requiring manual inflation and auscultation with stethoscope persist in emerging market clinics and training institutions.
- Mercury Sphygmomanometers:Columnar mercury manometers serving as clinical reference standards face WHO-mandated phase-out schedules across European and Asian jurisdictions.
Deployment concentrates in Digital Electronic; steepest expansion trajectory belongs to Oscillometric as cuffless optical variants absorb development investment.
Application:
Clinical indication severity and monitoring frequency requirements segment hardware specifications and reimbursement pathways.
- Hypertension Management:Longitudinal blood pressure tracking for diagnosed hypertensive patients drives the core replacement cycle, with Bluetooth-enabled devices transmitting readings to telehealth platforms for medication adjustment protocols.
- Cardiac Risk Assessment:Post-myocardial infarction and atrial fibrillation patients require rhythm-aware monitoring with irregular heartbeat detection algorithms.
- Prenatal Monitoring:Preeclampsia screening protocols in obstetric practices deploy home monitoring for gestational hypertension surveillance.
- Geriatric Care:Large-display interfaces and automated inflation accommodate age-related vision and dexterity limitations in Japan's super-aged population cohorts.
Revenue clusters in Hypertension Management; Prenatal Monitoring gains share fastest through obstetric telehealth integration.
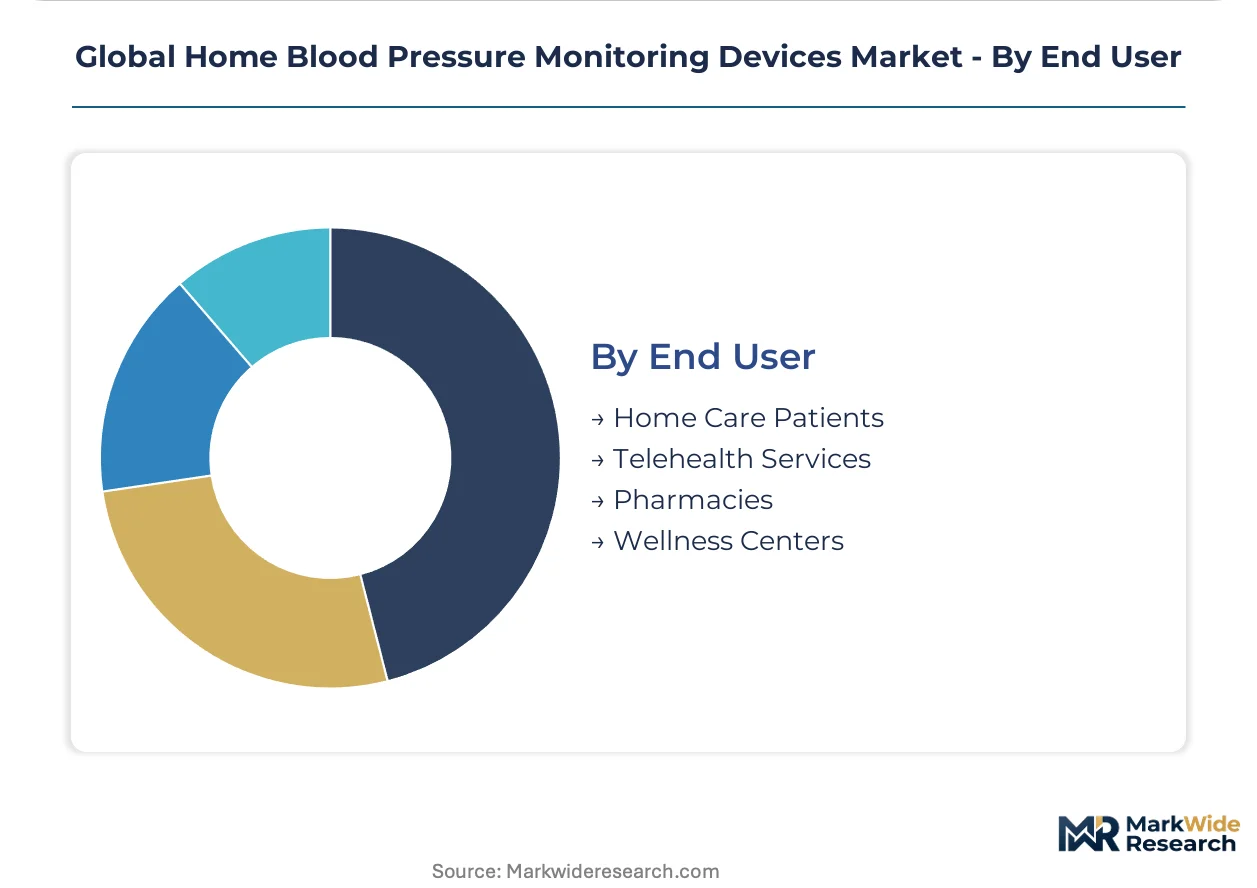
End User:
Procurement authority and payment responsibility fragment across patient self-pay, insurance reimbursement, and institutional purchasing channels.
- Home Care Patients:Individual purchasers selecting devices based on physician recommendation, insurance coverage status, and pharmacy retail availability represent the foundational demand pool.
- Telehealth Services:Remote patient monitoring platforms bundling device provision with subscription-based clinical oversight are displacing standalone retail purchases in United States Medicare Advantage networks.
- Pharmacies:Retail pharmacy chains in Germany and Japan position blood pressure monitors adjacent to prescription services, capturing walk-in diagnostic interest.
- Wellness Centers:Corporate and residential wellness programs deploy screening stations for preventive cardiovascular assessment.
Transaction volume flows through Home Care Patients; Telehealth Services capture margin expansion fastest through recurring revenue conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement expansion and Japan's super-aged demographics concentrate replacement demand for precision-validated devices. Germany's statutory health insurance frameworks and India's underpenetrated home diagnostics segment complete the demand distribution.
United States
CMS remote patient monitoring code expansions reduce out-of-pocket burdens for Medicare Advantage enrollees. FDA 510(k) clearance pathways under premarket notification requirements govern device entry timelines. Minneapolis and Boston medical device clusters host regulatory affairs infrastructure supporting Bluetooth-enabled monitor submissions.
Germany
Statutory health insurance reimbursement for validated upper-arm protocols sustains replacement cycles among hypertensive cohorts. EU MDR clinical evidence requirements intensify post-market surveillance obligations for Class IIa cardiovascular devices. Stuttgart and Hamburg host notified body technical documentation remediation queues for legacy device portfolios.
Japan
PMDA-enforced JIS T 1115 accuracy standards filter lower-precision imports and protect domestic incumbents. METI industrial policy supports MEMS transducer foundry capacity for pressure sensor supply. Tokyo-Osaka corridor manufacturing anchors vertically integrated production of upper-arm monitor portfolios.
India
CDSCO streamlined medical device registration and expanding private insurance coverage create first-mover positioning for connected monitors. Central Drugs Standard Control Organization priority review pathways compress entry timelines relative to standard routes. Mumbai and Bengaluru telehealth platform development clusters absorb hardware vendor API integration investments.
Brazil
ANVISA fast-track priority review designations for cardiovascular remote monitoring devices accelerate market access. National Health Agency regulatory frameworks align with Mercosur harmonization protocols for cross-border device circulation. São Paulo hospital procurement consortia evaluate total cost of ownership across five-year replacement cycles.
Global Home Blood Pressure Monitoring Devices Market Competitive Landscape
Strategic partnerships dominate the current landscape as hardware vendors seek telehealth platform integration. The vendor base clusters around three tiers: precision-validated incumbents with regulatory infrastructure, connected-device specialists capturing subscription revenue conversion, and regional assemblers competing on unit economics. Two archetypes define positioning: vertically integrated manufacturers controlling MEMS transducer supply, and ecosystem players bundling hardware with software platforms. M&A activity and API-enabled data streaming partnerships represent the dominant competitive vectors reshaping standalone monitor economics.
Among Japanese precision manufacturers, Omron Healthcare Inc. exemplifies vertically integrated production archetypes controlling sensor calibration capabilities. A&D Medical occupies a position within the accuracy-validation tier, while Withings SA represents ecosystem bundling strategies converting hardware shipments into recurring platform revenue. These three anchors illustrate the structural shift from discrete device supply toward integrated telehealth participation.
| Leading Market Players |
|---|
| Omron Healthcare Inc. |
| A&D Medical |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Beurer GmbH |
| Microlife AG |
| American Diagnostic Corporation |
| Withings SA |
| Rossmax International Ltd. |
| Others |
Supply & Pricing Matrix
MEMS transducer engineering talent concentration in Tokyo-Osaka and Stuttgart corridors widens pricing-tier spreads between precision-validated and commodity-grade monitors, as labor-cost differentials compound component-sourcing premiums across ANSI/AAMI SP10-certified and uncertified device tiers.
Pricing Analysis
Warranty and calibration service bundling separates premium-tier positioning from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 510(k) clearance status and Bluetooth connectivity inclusion. Price differentiation hinges on JIS T 1115 validation tier and after-sales sensor recalibration service. Cost compression in economy tiers intensifies because Chinese assemblers absorb margin pressure from German and Japanese sensor foundry allocation premiums. Telehealth platform bundling renders standalone retail purchasers most price-sensitive, while hospital procurement consortia exhibit lowest sensitivity due to total-cost-of-ownership evaluation frameworks.
Supply Chain Analysis
Pressure transducer supply rests on Japanese MEMS foundries in the Tokyo-Osaka corridor, German precision sensor manufacturers near Stuttgart, and Taiwanese contract assemblers serving cost-optimized tiers. Critical inputs span MEMS pressure sensors, medical-grade inflatable cuff polymers, and lithium-ion power cells. Single-source vulnerability concentrates in Japanese MEMS transducer output, where foundry allocation during semiconductor demand surges exposes device assemblers to component rationing. Distribution runs through hospital procurement consortia in France and the United Kingdom, retail pharmacy chains in Germany and Japan, and direct-to-patient telehealth platform subscriptions in United States Medicare Advantage networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS transducer foundry capacity constraints in Japan and Germany prop pricing power for precision-validated manufacturers, sustaining margin premiums through component allocation scarcity.
For Market Incumbents: Hedge against cuffless optical sensor substitution by accelerating photoplethysmography validation investments and securing exclusive MEMS transducer supply agreements with Tokyo-Osaka corridor foundries. Deepen backward integration into pressure sensor calibration capabilities to defend against emerging ecosystem players bundling hardware with telehealth subscriptions. For New Entrants and Emerging Players: Begin with India's underpenetrated home diagnostics segment, where CDSCO streamlined registration and expanding private insurance coverage create first-mover positioning for Bluetooth-integrated monitors at price points below Japanese and German incumbents. Target telehealth platform API integration as the primary go-to-market angle, converting hardware shipments into recurring data-subscription revenue rather than competing on standalone device unit economics. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated precision manufacturers controlling MEMS transducer supply given reimbursement code expansion for remote patient monitoring. Long-term viability favors entities with dedicated regulatory affairs infrastructure spanning FDA 510(k), EU MDR, and PMDA JIS T 1115 pathways. Watch ANVISA fast-track designation velocity in Brazil as the inflection indicator for emerging market regulatory pathway efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates United States market entry for Bluetooth-enabled monitors against ANSI/AAMI SP10 protocols. |
| CE Marking under EU MDR | Unlocks statutory health insurance reimbursement in Germany through Class IIa cardiovascular device certification. |
| Hospital System Partnership | Secures preferred supplier status within NHS and French procurement consortia evaluating total-cost-of-ownership frameworks. |
| Software Companion Development | Enables API-enabled data streaming into Epic and Cerner electronic health record systems for telehealth integration. |
| Reimbursement Strategy | Captures CMS remote patient monitoring code expansions reducing Medicare Advantage enrollee out-of-pocket burdens. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR technical documentation queues, and PMDA JIS T 1115 validation patterns anchored the trend analysis, supplemented by interviews with biomedical engineers at cardiology practices, hospital GPO contracts managers, regulatory affairs leads at precision manufacturers, and telehealth platform integration specialists. Secondary validation drew from FDA 510(k) premarket notification databases, EUDAMED CE marking records, CMS Medicare reimbursement code filings, and hospital procurement contract disclosures. Bottom-up device shipment estimates triangulated against top-down reimbursement expansion projections.
Segment-weighting across product type, technology platform, clinical application, and end-user procurement channel structured the analytical framework across the projection horizon. CAGRs derived from replacement cycle compression patterns linked to Bluetooth-enabled connectivity adoption and smartphone integration penetration. Modeled inputs incorporated aging demographic trajectories in Japan and Germany, remote patient monitoring reimbursement velocity in United States Medicare Advantage networks, and CDSCO registration pathway efficiency in India.
Sensor foundry allocation disruptions, EU MDR clinical evidence requirement enforcement variance, and telehealth platform consolidation patterns are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding reimbursement code stability and accuracy validation protocol harmonization. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
South Korea Patient Monitoring Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Remote Patient Monitoring Software Market
Patient Monitoring
Health Sensors Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Global Intrapartum Monitoring Devices Market
Patient Monitoring
United Kingdom Remote Patient Monitoring Market
Patient Monitoring
Pain Monitoring Devices Market
Patient Monitoring
Respiratory Monitoring Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Respiratory Monitoring Devices Market