
 Middle East and Africa Body Temperature Monitoring Market | 2026-2036
Middle East and Africa Body Temperature Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Body Temperature Monitoring Market Foresight
South Africa's medical device assembly corridor is fragmenting as local distributors compete with direct imports from Asia-Pacific manufacturers. Omron Corporation leverages its Osaka-based R&D network to sustain premium positioning across private hospital chains in the UAE. Cardinal Health anchors its regional footprint through cold-chain logistics partnerships that extend into East African markets. Philips dominates the high-end infrared segment through exclusive supply agreements with Saudi Arabia's Ministry of Health.
Body temperature monitoring encompasses devices that measure core or surface thermal status through contact or non-contact sensing modalities, typically resolving to 0.1°C precision for clinical decision-making. Infrared thermometers employ thermopile sensors detecting emitted radiation in the 8-14 μm spectral range, enabling hygienic screening without patient contact in infectious disease settings. Digital thermometers still occupy the largest volume share across Middle East and Africa home care channels due to unit economics and battery longevity. Wearable devices represent the fastest-expanding technology dimension, though margin pools concentrate in Bluetooth-enabled continuous monitoring platforms for post-operative wards. Epidemic control applications are driving bulk procurement of Wi-Fi connected thermal screening stations at ports of entry across the Red Sea corridor.
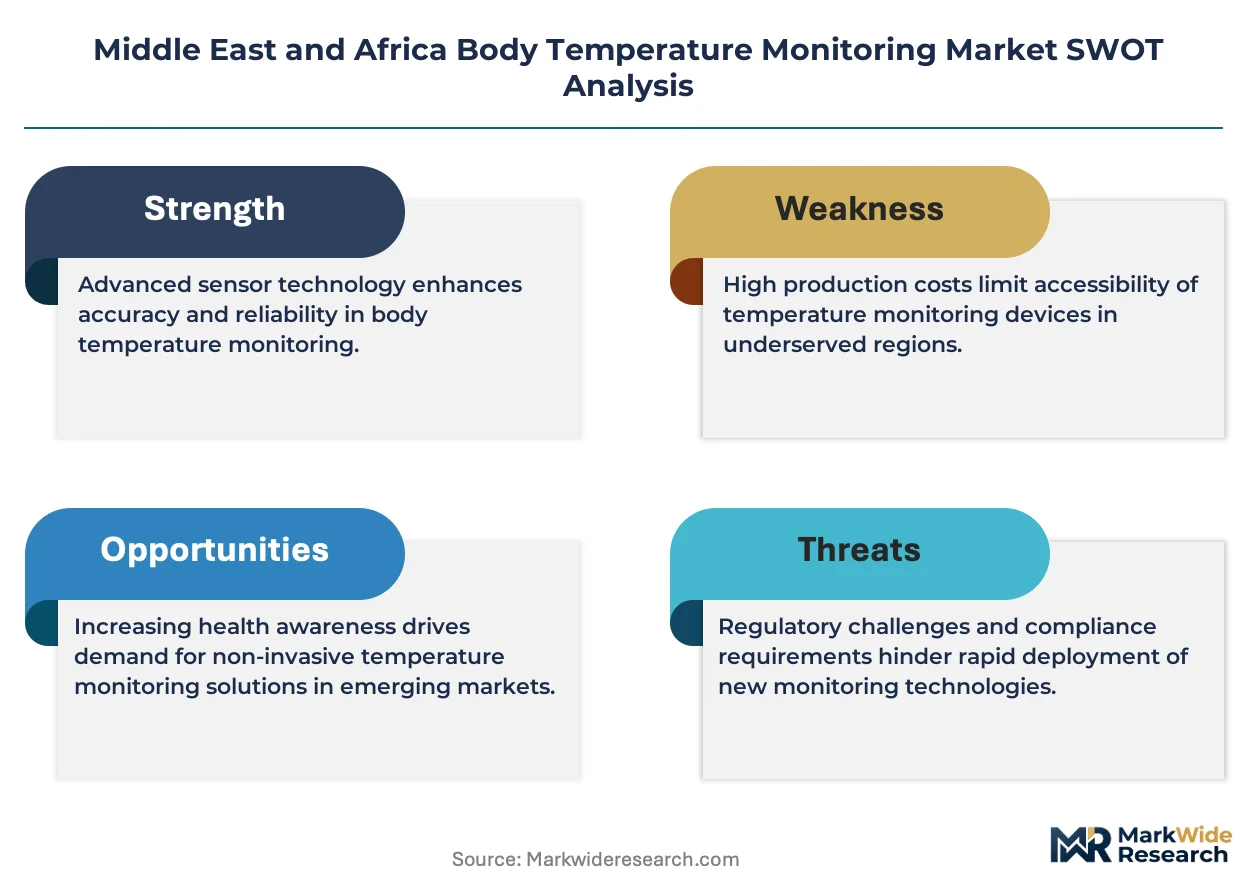
Saudi Arabia's SFDA enforces IEC 60601-2-56 compliance for clinical thermometers, effectively filtering low-cost unregistered imports from Gulf distribution networks. South Africa's Health Products Regulatory Authority applies SANS 60601 standards that delay market entry for manufacturers lacking local testing partnerships. The EU MDR's extraterritorial influence shapes procurement specifications at European-owned hospital groups operating in Morocco and Tunisia. Stakeholders must monitor evolving pre-market authorization timelines as national regulators build independent testing capacity rather than relying on mutual recognition agreements.
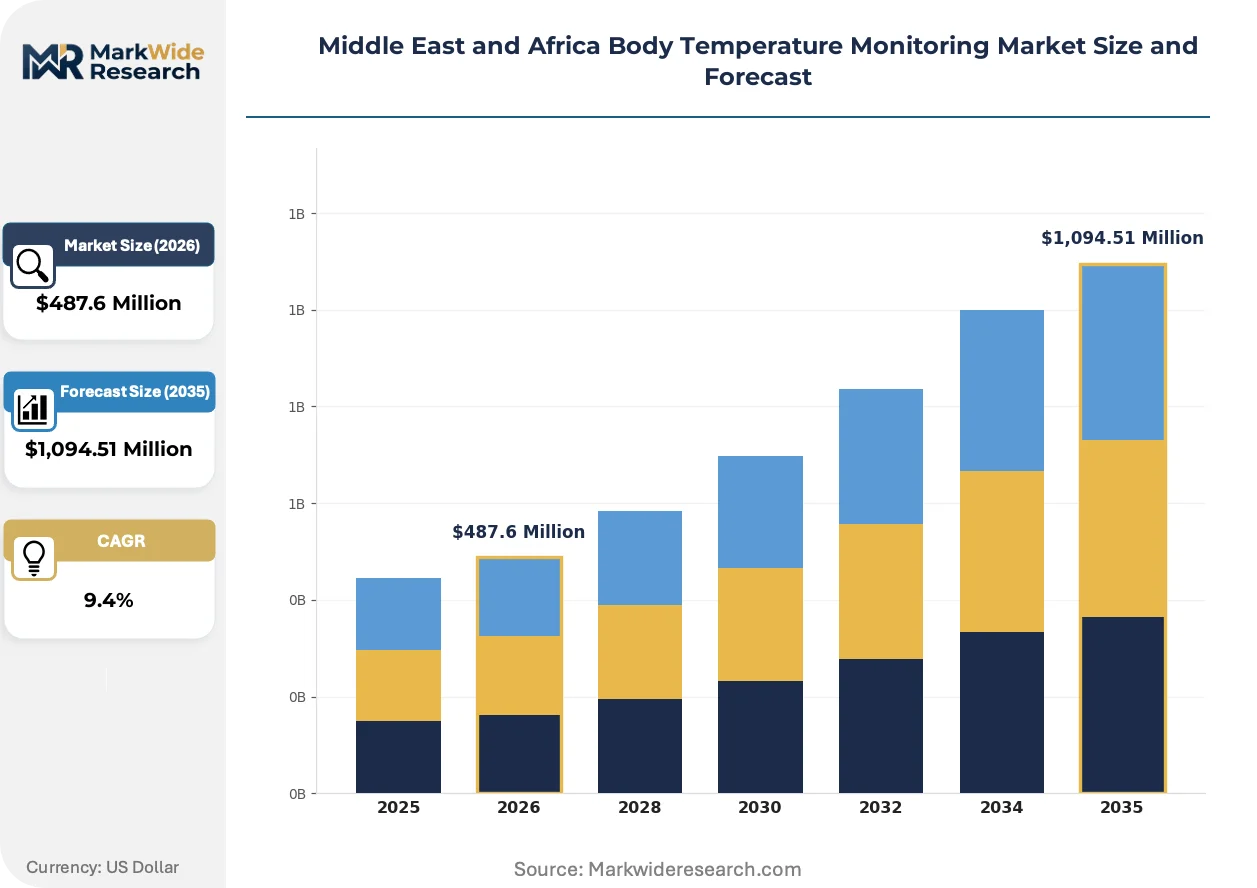
Market Dynamics
Hospital procurement across Gulf Cooperation Council states is accelerating non-contact infrared adoption while Saudi Arabia's SFDA tightens quality benchmarks, creating a bifurcation between certified clinical-grade supply and unregistered low-cost imports.
Growth Catalysts
- Infectious disease protocols:Post-pandemic screening mandates at ports of entry across the Red Sea corridor sustain bulk procurement of Wi-Fi connected thermal stations.
- Wearable patch platforms:Bluetooth-enabled continuous monitoring for post-operative wards in South African private hospitals is expanding addressable clinical applications.
- SFDA registration requirements:Saudi Arabia's enforcement of IEC 60601-2-56 compliance is filtering substandard imports and elevating average selling prices for compliant devices.
Market Restraints
- Sensor supply concentration:Thermopile sensor fabrication concentrates in East Asian foundries, exposing regional assemblers to input bottlenecks and currency volatility.
- Testing partnership requirements:South Africa's Health Products Regulatory Authority mandates local SANS 60601 verification, delaying market entry for manufacturers lacking established laboratory relationships.
- Battery chemistry limitations:Lithium cell degradation in wearable patches under tropical humidity conditions compresses product lifecycles and elevates replacement costs.
Strategic Opportunities
- Nigerian primary care networks:Federal hospital digitization programs create first-mover advantage for cloud-integrated temperature logging systems in West Africa's largest market.
- East African cold-chain extension:Logistics partnerships anchored in Dubai are opening distribution corridors into Kenya, Ethiopia, and Tanzania for temperature-sensitive pharmaceutical monitoring.
- EU MDR procurement alignment:European-owned hospital groups in Morocco and Tunisia are adopting EU-equivalent specifications, creating premium positioning for MDR-certified manufacturers.
Industry Challenges
- Biomedical calibration expertise:Shortage of trained technicians for infrared device validation across sub-Saharan Africa extends service turnaround times and elevates warranty costs.
- Legacy system integration:Hospital information system fragmentation in Egypt and Algeria complicates API connectivity for continuous monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Body Temperature Monitoring Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,094.51 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Thermometers, Digital Thermometers, Disposable Thermometers, Wearable Devices End User: Hospitals, Clinics, Home Care, Laboratories Technology: Bluetooth, Wi-Fi, Infrared, Thermocouple Application: Fever Detection, Health Monitoring, Clinical Research, Epidemic Control |
| Companies Covered | 3M Company, Omron Corporation, Welch Allyn, Cardinal Health, Helen of Troy Limited, Medtronic, Stryker Corporation, Koninklijke Philips, General Electric, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Body Temperature Monitoring Market Shifts & Advancements
Device architectures are converging around multi-modal sensing while regulatory frameworks fragment along national testing requirements, and procurement authority consolidates within centralized Gulf health ministries.
Thermopile arrays paired with machine learning edge processors are hybridizing traditional infrared thermometry with predictive fever detection algorithms. Private hospital chains in the UAE are deploying these systems in emergency triage workflows. The convergence is compressing differentiation between standalone screening devices and integrated patient monitoring platforms.
Saudi Arabia's SFDA is extending pre-market authorization timelines beyond mutual recognition agreements as the regulator builds independent electromagnetic compatibility testing capacity. Domestic manufacturers are responding by establishing local technical file compilation partnerships. This regulatory decoupling most affects mid-tier importers previously reliant on European Notified Body certificates.
Centralized ministry procurement in Gulf states is displacing distributor-led hospital sales with framework agreements covering multi-year device supply and calibration services. Medical device assemblers in South Africa are losing share to direct manufacturer relationships. The shift is most visible in Saudi Arabia's Ministry of Health exclusive supply arrangements for high-end infrared segments.
Middle East and Africa Body Temperature Monitoring Market Segmentation
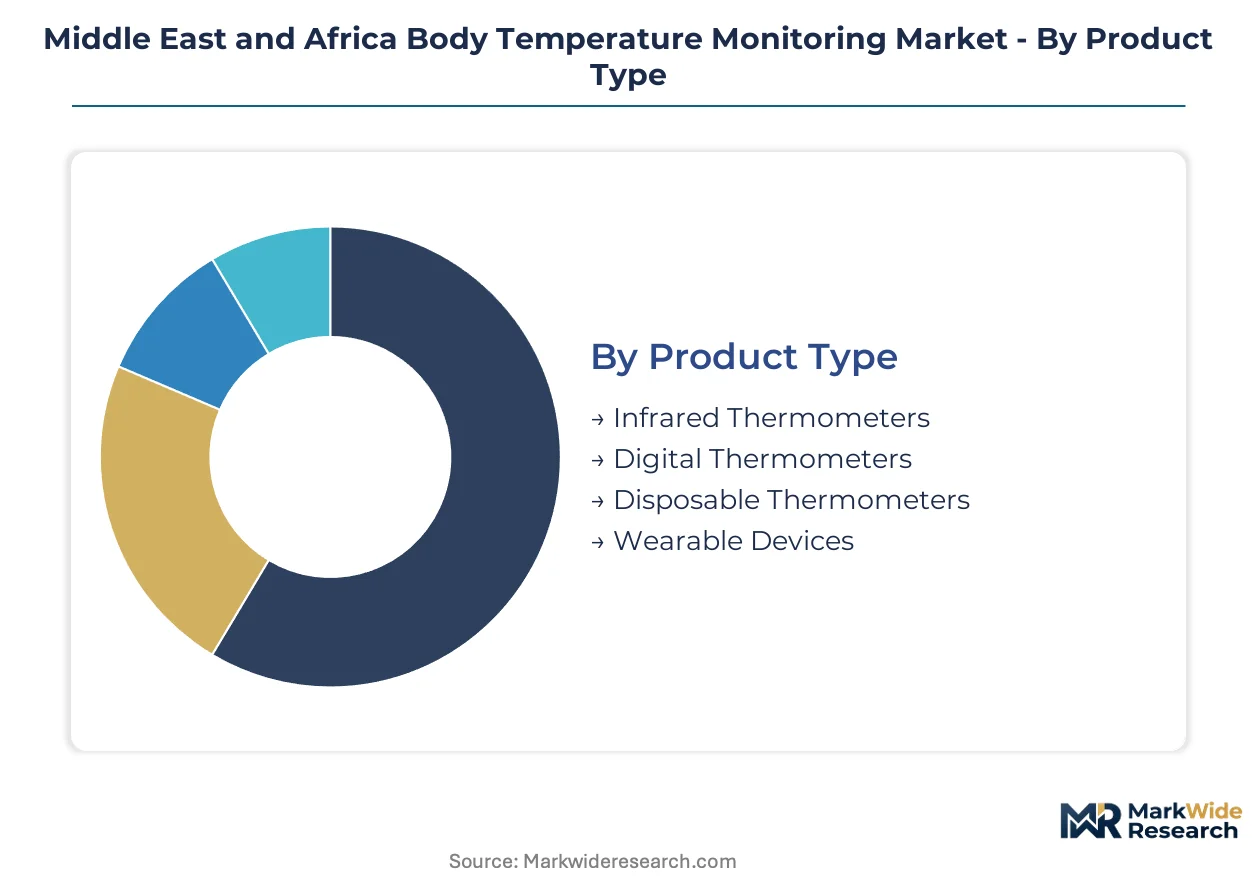
Body temperature monitoring equipment fragments across four analytical dimensions that shape procurement priorities and margin structures. Product type determines sensor technology and unit economics. End user concentration drives regulatory compliance requirements and channel strategies across the Middle East and Africa.
Product Type:
Mature contact-based technologies dominate unit volumes while non-contact platforms capture premium positioning in infectious disease settings.
- Infrared Thermometers:Thermopile sensors detect emitted radiation in the 8-14 μm spectral range, enabling hygienic screening without patient contact. Demand concentrates in Saudi Arabian Ministry of Health procurement and UAE private hospital chains where IEC 60601-2-56 compliance is mandatory.
- Wearable Devices:Bluetooth-enabled continuous monitoring platforms integrate adhesive temperature patches with cloud analytics for post-operative wards. South African private hospitals absorb the bulk of sub-Saharan demand as clinical workflow digitization accelerates.
- Digital Thermometers:Thermistor-based contact devices with 0.1°C precision remain the default for home care channels across Nigeria and Egypt due to battery longevity and price accessibility.
- Disposable Thermometers:Single-use chemical strip thermometers serve field screening and resource-constrained primary care networks in East African markets.
Digital thermometers retain volume leadership across home care channels; wearable devices hold the steepest expansion curve in private hospital procurement.
End User:
Institutional buyers command specification authority while home care volumes reflect population scale and retail distribution density.
- Hospitals:Acute care facilities require calibrated clinical-grade devices with HIS integration capability. Gulf Cooperation Council states centralize procurement through ministry framework agreements that bundle devices with multi-year calibration services.
- Home Care:Consumer-directed purchases favor unit economics and battery longevity over connectivity features. Nigerian retail pharmacy chains and Egyptian distributor networks shape competitive dynamics.
- Clinics:Outpatient facilities balance screening throughput with capital constraints. Kenyan and Ethiopian primary care digitization programs are expanding addressable demand for cloud-integrated logging systems.
- Laboratories:Research and reference laboratories demand traceable calibration chains and data integrity features for clinical trial applications.
Hospitals anchor premium revenue pools through centralized procurement; clinics are gaining share fastest as federal digitization programs deploy across West Africa.
Technology:
Connectivity modules differentiate margin tiers while core sensing modalities determine clinical validation requirements.
- Bluetooth:Low-energy wireless protocols enable continuous data streaming from wearable patches to bedside monitors and EMR systems. South African private hospital post-operative wards are standardizing on Bluetooth-enabled platforms.
- Infrared:Non-contact thermopile detection supports mass screening workflows at ports of entry across the Red Sea corridor where Wi-Fi connected thermal stations are being bulk-procured.
- Wi-Fi:Enterprise-grade connectivity supports centralized thermal screening stations with cloud analytics and multi-device fleet management for epidemic control applications.
- Thermocouple:Precision contact sensors serve laboratory calibration reference standards and specialized clinical research applications requiring NIST-traceable accuracy.
Infrared sensing underpins the largest installed base; Bluetooth connectivity is climbing the fastest as continuous monitoring platforms penetrate private hospital wards.
Application:
Use case specificity determines device specification, regulatory pathway, and procurement channel.
- Fever Detection:Screening-focused devices prioritize speed and throughput over precision margins. Saudi Arabian port authorities and UAE airport operators drive demand for multi-person thermal imaging systems.
- Health Monitoring:Longitudinal temperature tracking for chronic condition management and wellness applications. Wearable patch platforms are expanding from hospital discharge into home-based recovery protocols.
- Epidemic Control:Surveillance-grade systems with centralized data aggregation for public health authorities. Gulf ministry procurement of Wi-Fi connected thermal stations sustains this segment following pandemic-era mandate institutionalization.
- Clinical Research:Protocol-compliant devices with audit trails and data integrity features for pharmaceutical trials and academic studies.
Fever detection commands the broadest addressable demand; health monitoring applications are gaining share fastest as wearable platforms extend into post-operative and chronic care workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA enforcement of IEC 60601-2-56 compliance anchors Saudi Arabia's regulatory gravity, filtering substandard imports and elevating quality benchmarks across Gulf Cooperation Council procurement networks.
Saudi Arabia
Ministry of Health exclusive supply agreements for high-end infrared segments concentrate procurement authority within centralized frameworks. SFDA pre-market authorization timelines now extend beyond mutual recognition agreements as domestic electromagnetic compatibility testing capacity expands. Riyadh-based technical file compilation partnerships are displacing mid-tier importers previously reliant on European Notified Body certificates.
United Arab Emirates
Private hospital chains in Dubai and Abu Dhabi deploy multi-modal thermopile arrays with machine learning edge processors for emergency triage workflows. MOHAP registration requirements align with international quality benchmarks for clinical-grade device importation. The Dubai logistics corridor anchors cold-chain distribution partnerships extending temperature-sensitive pharmaceutical monitoring into East African markets.
South Africa
Private hospital post-operative wards absorb the bulk of sub-Saharan demand for Bluetooth-enabled continuous monitoring platforms. The Health Products Regulatory Authority mandates local SANS 60601 verification, delaying market entry for manufacturers lacking established laboratory relationships. Cape Town and Johannesburg medical device assembly corridors fragment as local distributors compete with direct Asia-Pacific manufacturer imports.
Nigeria
Federal hospital digitization programs create first-mover positioning for cloud-integrated temperature logging systems in West Africa's largest addressable market. Retail pharmacy chains in Lagos and Kano shape competitive dynamics for home care channel distribution. The national pharmaceutical regulator maintains import registration requirements that filter unregistered low-cost thermometer shipments.
Egypt
Hospital information system fragmentation complicates API connectivity for continuous monitoring platforms in Cairo and Alexandria acute care networks. Public health authorities sustain bulk procurement of screening-focused devices for port and airport epidemic control applications. Egyptian distributor networks retain influence over consumer-directed digital thermometer volumes despite ministry-level centralization elsewhere in the region.
Middle East and Africa Body Temperature Monitoring Market Competitive Landscape
Multinational conglomerates and specialized medical device manufacturers split the market between premium clinical-grade positioning and volume-accessible home care channels. Concentration remains moderate with tiered competitive dynamics separating IEC-certified suppliers from unregistered import competitors. Three strategic archetypes dominate: diversified health technology conglomerates with Gulf ministry framework agreements, specialized diagnostic device manufacturers with Osaka or Amsterdam R&D networks, and regional logistics-anchored distributors with cold-chain capabilities. Dominant competitive moves include exclusive multi-year supply and calibration service bundling, plus direct manufacturer relationships displacing South African assembler intermediation.
Within the diversified health technology tier, Koninklijke Philips exemplifies premium infrared positioning through Saudi Ministry of Health exclusive arrangements, while General Electric occupies a similar archetype with imaging-integrated monitoring portfolios. Among specialized diagnostic manufacturers, Omron Corporation represents Osaka-based R&D network leverage for private hospital chain penetration, and Welch Allyn anchors American diagnostic device specialization. Cardinal Health sits within the logistics-anchored distributor archetype, with Dubai-based cold-chain partnerships extending into Kenyan and Ethiopian corridors.
| Leading Market Players |
|---|
| 3M Company |
| Omron Corporation |
| Welch Allyn |
| Cardinal Health |
| Helen of Troy Limited |
| Medtronic |
| Stryker Corporation |
| Koninklijke Philips |
| General Electric |
| Others |
Supply & Pricing Matrix
Osaka-based thermopile sensor foundries anchor global capacity for infrared detection elements, and their output constraints transmit directly into Gulf procurement premiums for clinical-grade devices. Manufacturers holding captive supply relationships with these East Asian fabricators command pricing power across Saudi Arabia's IEC 60601-2-56 certified segments.
Pricing Analysis
Price spreads between Dubai and Lagos distribution points exceed threefold for identical infrared thermometer SKUs, reflecting certification tier and cold-chain logistics bundling. Three-tier pricing structure across IEC-certified clinical, MOHAP-registered standard, and unregistered economy levels separates procurement channels. Pricing pressure stems from direct Asia-Pacific manufacturer imports undercutting South African assembly corridors. Home care channels in Nigeria exhibit highest price sensitivity; Gulf ministry framework agreements show lowest.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn and Jabil Electronics for Bluetooth-enabled wearable assemblies, plus specialized thermopile foundries in Japan and Taiwan for infrared sensor fabrication. Component sourcing draws from Malaysian PCB substrate plants, Chinese lithium cell manufacturers, and German precision thermistor suppliers. Single-source vulnerability in thermopile arrays exposes regional assemblers to input bottlenecks. Distribution runs through Dubai logistics hubs extending cold-chain corridors into East African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat; SFDA and MOHAP certification requirements create switching costs that lock hospital procurement into validated supplier relationships.
For Market Incumbents: Harden exclusive calibration service bundling within Saudi Ministry of Health framework agreements to block mid-tier importers. Deepen backward integration into thermopile sensor sourcing through direct foundry partnerships in Taiwan and Japan, neutralizing supply concentration risk from emerging Asia-Pacific competitors. For New Entrants and Emerging Players: Nigerian federal hospital digitization programs represent the most penetrable entry point for cloud-integrated temperature logging systems without legacy HIS fragmentation. East African cold-chain extension corridors through Dubai offer logistics-anchored positioning for temperature-sensitive pharmaceutical monitoring applications. Pursue SANS 60601 testing partnerships in Johannesburg to unlock South African private hospital procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors Bluetooth-enabled continuous monitoring platforms over commoditized infrared screening devices as post-operative ward digitization accelerates. Long-term viability rests on software companion development and EMR integration capabilities rather than hardware margin capture. Watch SFDA electromagnetic compatibility testing capacity expansion as signal for regulatory decoupling from European Notified Body certificates.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Technical File Compilation Partnership | Local registration capability accelerates pre-market authorization timelines for Riyadh-based operations. |
| Bluetooth-Enabled Wearable Platform Launch | South African private hospital post-operative wards standardize on continuous monitoring integration. |
| Dubai Cold-Chain Logistics Partnership | Temperature-sensitive pharmaceutical monitoring extends distribution reach into Kenyan and Ethiopian corridors. |
| Cloud-Integrated Temperature Logging System | Nigerian federal hospital digitization programs create first-mover positioning in West Africa's largest market. |
| Multi-Modal Thermopile Array with Edge Processing | UAE emergency triage workflows deploy predictive fever detection algorithms for screening throughput. |
Research Methodology
A standing panel of hospital procurement managers, biomedical calibration technicians, GPO contracts specialists, and regulatory affairs leads provided ongoing calibration across the research program. Primary fieldwork combined structured interviews with secondary validation against SFDA registration databases, MOHAP device listings, South African Health Products Regulatory Authority filings, and customs import records. Bottom-up shipment data triangulated with top-down ministry procurement disclosures.
Scenario bracketing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, end user concentration, connectivity technology, and application specificity. CAGRs derived from weighted average of historical trend extrapolation and technology diffusion curves. Forecast inputs incorporated thermopile sensor supply constraints and regulatory authorization timeline shifts.
Macroeconomic conditions sit as an overlay; deviation in Gulf currency peg stability or lithium cell commodity pricing would shift the trajectory. Forecasts reflect documented assumptions on SFDA testing capacity expansion and Bluetooth protocol adoption curves in South African private healthcare. Quarterly review of ministry procurement award announcements and thermopile foundry capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Cardiac Patch Monitor Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
Continuous Cardiac Monitoring Devices Market
Patient Monitoring
Coronary Pressure Monitors Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
Neuro-Monitoring System Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Global Consumer Healthcare Sensor Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
North America Remote Patient Monitoring Systems Market
Patient Monitoring
Neurology Patient Monitoring Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
Multi-Channel Remote ECG Monitors Market
Patient Monitoring
North America Hemodynamic Monitoring Market