
 Wearable ECG Monitors Market | 2026-2036
Wearable ECG Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable ECG Monitors Market Insights
The capital-intensity divergence between full-stack medical device manufacturers and consumer-electronics entrants is bifurcating competitive strategy in wearable ECG monitors. Medtronic leverages decades of clinical trial infrastructure and regulatory relationships to sustain premium positioning in prescription-grade patch monitors. Apple competes through vertical integration of semiconductor design with consumer health platforms, dominating direct-to-consumer distribution at scale.
Wearable ECG monitors are portable biosensing devices that acquire, process, and transmit electrical activity of the heart through skin-contact electrodes, typically sampling at 128–512 Hz with noise-filtering algorithms to enable ambulatory arrhythmia detection outside clinical settings. Their primary purpose spans diagnostic-grade cardiac surveillance prescribed by physicians and consumer wellness tracking for fitness optimization. Patch monitors lead in clinical revenue contribution due to reimbursement codes and extended wear duration, while smartwatch ECG functionality grows fastest among fitness enthusiasts seeking seamless health-data integration. Bluetooth-enabled devices anchor current shipment volumes, though cloud-based architectures are capturing margin pools through subscription telemetry services for telemedicine users.
FDA 510(k) clearance requirements and HIPAA data-security mandates shape product development timelines and channel access for US-focused manufacturers, while ISO 13485 quality-management certification governs European market entry through CE marking under the EU MDR. The EU AI Act introduces additional conformity obligations for algorithm-driven arrhythmia classification, tightening documentation burdens for cloud-based analytics providers. Stakeholders must monitor evolving reimbursement parity between prescription and over-the-counter ECG form factors as payers reassess remote monitoring value frameworks.
Market Dynamics
Reimbursement infrastructure for remote cardiac monitoring is concentrating demand toward prescription-grade patch monitors while compressing margins for consumer-electronics entrants lacking clinical trial infrastructure. Medicare payment codes in the United States now cover extended ambulatory ECG monitoring, redirecting capital toward FDA-cleared devices with proven diagnostic accuracy.
Growth Catalysts
- Medicare Reimbursement Codes:Remote patient monitoring payment infrastructure in the United States sustains revenue predictability for patch monitor manufacturers serving cardiology clinics.
- AI-Enabled Arrhythmia Detection:Machine learning algorithms embedded in cloud telemetry platforms accelerate diagnostic throughput for telemedicine providers managing chronic heart failure populations.
- Bluetooth Low Energy:Wireless protocol standardization reduces hardware integration costs for original equipment manufacturers developing multi-sensor wearable form factors.
Market Restraints
- Clinical Trial Burden:FDA 510(k) clearance requires prospective validation studies against predicate devices, extending development timelines by 18-24 months for algorithm-driven classification features.
- Electrode Material Concentration:Silver-silver chloride sensor supply chains cluster in East Asian contract manufacturers, exposing patch producers to input cost volatility and logistics disruptions.
- Signal Artifact Limitations:Motion noise and skin impedance variation degrade ECG quality during high-intensity physical activity, constraining diagnostic utility in fitness-oriented smartwatch deployments.
Strategic Opportunities
- EU AI Act Compliance Services:Algorithm documentation and conformity assessment outsourcing creates margin pools for specialized regulatory consultancies serving cloud-based analytics providers.
- Home-Based Heart Failure Monitoring:Integration of ECG with pulmonary artery pressure sensors addresses readmission reduction mandates for Medicare accountable care organizations.
- Direct-to-Employer Contracts:Self-insured corporations in the United States bypass traditional payer channels to purchase population-scale cardiac screening for workforce risk stratification.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time biosignal processing expertise concentrates in semiconductor design hubs, forcing device manufacturers into bidding wars for signal-processing engineers.
- HIPAA Technical Safeguards:Encryption key management and audit logging requirements extend quality management system implementation timelines for telemetry service providers.
- Legacy EHR Integration:HL7 FHIR interface development consumes substantial professional services capacity as hospitals demand seamless data flow into Epic and Cerner workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable ECG Monitors Market |
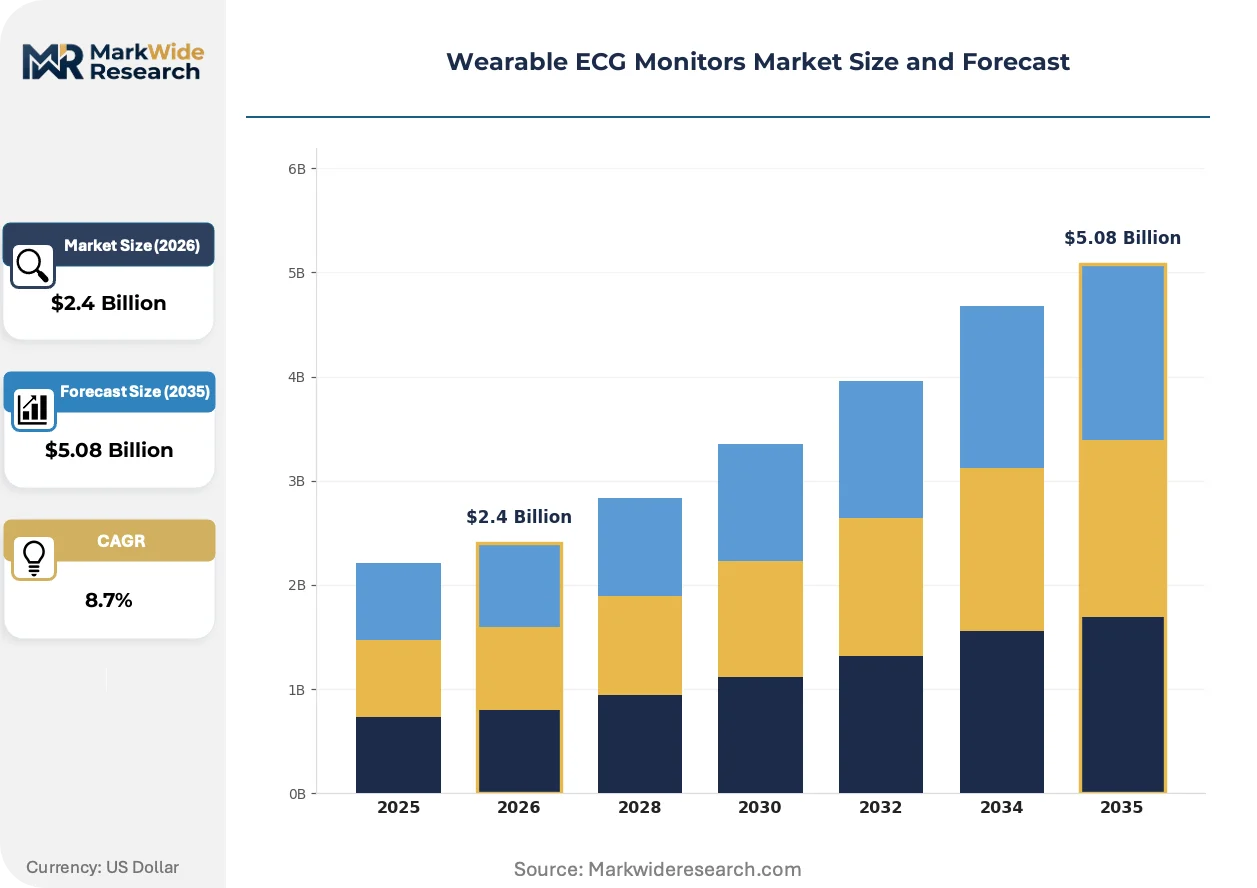
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatch, Patch Monitor, Handheld Device, Chest Strap End User: Patients, Healthcare Providers, Fitness Enthusiasts, Telemedicine Users Technology: Bluetooth, Cloud-Based, Wired, Optical Application: Cardiac Monitoring, Fitness Tracking, Remote Patient Monitoring, Health Management |
| Companies Covered | Medtronic, Koninklijke Philips N.V., OMRON Corporation, Abbott, Fitbit, Apple, Samsung Electronics, iRhythm Technologies, AliveCor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable ECG Monitors Market Trends and Innovations
Convergence of semiconductor miniaturization with machine learning inference at the edge is redefining what constitutes a clinically viable cardiac monitoring device. Three developments capture this transformation.
Silicon photonics and advanced packaging techniques are miniaturizing multi-lead ECG acquisition circuits into sub-square-centimeter footprints. Cardiology clinics in the United States are adopting these ultra-compact patch monitors for 14-day ambulatory studies, replacing legacy Holter systems. The technology is compressing device manufacturing costs while extending wear duration through reduced power consumption.
The EU AI Act's risk-based classification framework imposes documentation burdens on algorithm-driven arrhythmia detection systems marketed in Europe. Cloud-based telemetry providers must maintain technical files demonstrating conformity assessment for high-risk medical device software. This regulatory pressure is redirecting product development resources toward explainable AI architectures that satisfy notified body scrutiny under the EU MDR.
Employer-sponsored wellness programs are displacing traditional insurance-channel distribution for consumer-grade ECG functionality. Large self-insured corporations in the United States now contract directly with device manufacturers for workforce cardiac screening at scale. This channel shift is visible most prominently in technology and financial services sectors where executive health benefits budgets exceed traditional clinical procurement thresholds.
Wearable ECG Monitors Market Segmentation
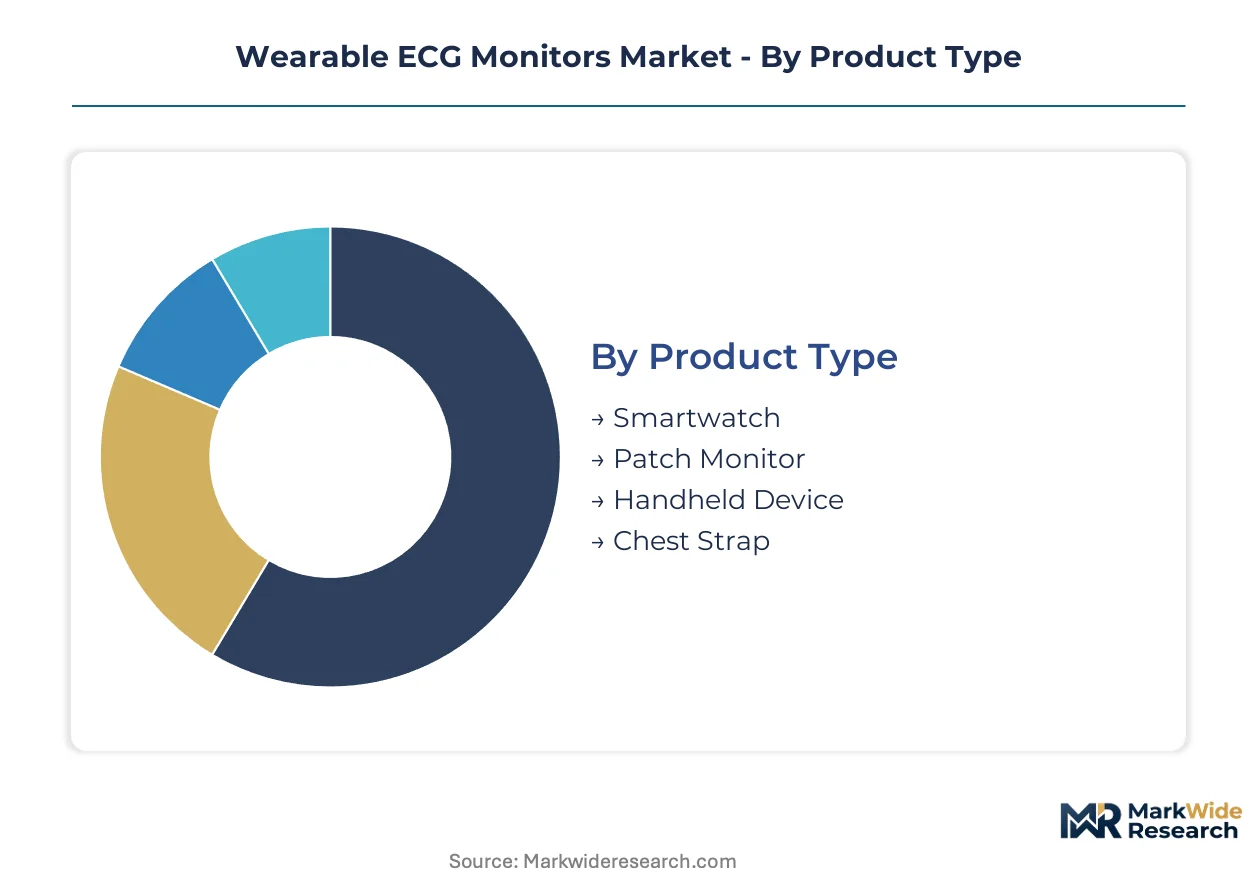
Segmentation in wearable ECG monitors reveals how reimbursement codes, consumer behavior, and technical specifications split demand across divergent use cases. Product form factors and connectivity architectures determine whether manufacturers target prescription revenue streams or direct-to-consumer wellness markets.
Product Type:
Patch monitors face substitution pressure from smartwatch ECG functionality as consumers prioritize seamless device integration over clinical-grade accuracy.
- Patch Monitor:Adhesive single-lead electrodes with extended 7-14 day wear duration and FDA 510(k) clearance for ambulatory arrhythmia detection. Demand concentrates in United States cardiology clinics where Medicare reimbursement codes for remote cardiac monitoring sustain prescription volume.
- Smartwatch:Photoplethysmography and electrical heart sensors embedded in wrist-worn consumer electronics, sampling at 128 Hz with algorithmic AFib detection. Fitness enthusiasts in employer-sponsored wellness programs drive fastest uptake through direct-to-consumer channels bypassing clinical procurement.
- Handheld Device:Portable two-lead acquisition systems with immediate smartphone transmission for episodic symptom capture.
- Chest Strap:Elastic band electrodes with high sampling rates optimized for athletic heart rate variability tracking during exertion.
Patch monitors retain volume leadership; smartwatches hold the steepest expansion curve.
End User:
Cost tier stratification separates institutional procurement with reimbursement backing from out-of-pocket consumer expenditure.
- Healthcare Providers:Hospital systems and cardiology clinics purchasing FDA-cleared devices for diagnostic-grade ambulatory monitoring under remote patient monitoring programs. United States Medicare accountable care organizations represent the concentration point as readmission reduction mandates align with extended ECG surveillance.
- Telemedicine Users:Chronic heart failure patients managed through cloud-connected patch monitors with automated algorithmic triage. Demand accelerates where telehealth platforms integrate ECG data into clinician workflow through HL7 FHIR interfaces with Epic and Cerner systems.
- Patients:Individuals with diagnosed arrhythmias seeking prescription-grade monitoring outside clinical settings.
- Fitness Enthusiasts:Wellness-focused consumers purchasing consumer-grade ECG functionality for performance optimization and occasional rhythm screening.
Healthcare providers dominate revenue contribution; telemedicine users are climbing the fastest.
Technology:
Supply concentration in semiconductor packaging and wireless protocol stacks shapes competitive positioning across connectivity architectures.
- Bluetooth:Low Energy 5.0 protocol enabling 10-meter range transmission to paired smartphones with sub-milliamp power draw. Original equipment manufacturers in Taiwan and South Korea anchor component supply, driving hardware integration cost reductions for multi-sensor wearable form factors.
- Cloud-Based:Continuous telemetry architectures with edge preprocessing and centralized algorithmic analysis on AWS or Azure infrastructure. United States telemedicine providers and Medicare Advantage plans concentrate demand where subscription telemetry services capture recurring revenue streams.
- Wired:USB-C or proprietary cable connections for high-fidelity data transfer in clinical validation settings.
- Optical:Photoplethysmography-based heart rate estimation without electrical skin contact, sacrificing diagnostic specificity for comfort.
Bluetooth-enabled devices retain shipment volume leadership; cloud-based architectures gain share fastest.
Application:
Maturity gradients separate established diagnostic categories from emerging wellness-oriented use cases with unproven reimbursement pathways.
- Cardiac Monitoring:Diagnostic-grade arrhythmia detection including AFib, flutter, and ventricular ectopy through physician-prescribed patch monitors. United States cardiology clinics and electrophysiology practices anchor demand where FDA clearance and Medicare payment codes create sustainable revenue predictability.
- Remote Patient Monitoring:Post-discharge surveillance for heart failure exacerbation through integrated ECG and pulmonary artery pressure monitoring. Medicare accountable care organizations in the United States drive fastest expansion as CMS readmission penalties intensify hospital investment in ambulatory telemetry.
- Fitness Tracking:Heart rate zone training and recovery metrics for athletic performance optimization.
- Health Management:General wellness screening and longitudinal heart rhythm documentation without clinical intervention triggers.
Cardiac monitoring retains revenue concentration; remote patient monitoring exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds European benchmarks by 40-60% due to Medicare reimbursement infrastructure, while Asian markets compress margins through hardware commoditization and direct-to-consumer distribution channels.
United States
Medicare accountable care organizations drive prescription-grade patch monitor procurement through readmission reduction mandates. FDA 510(k) clearance pathways compress time-to-market for AI-enabled arrhythmia detection algorithms. Minneapolis and Boston anchor clinical trial infrastructure for algorithm validation studies against predicate devices.
Germany
Cardiology clinics adopt extended ambulatory ECG monitoring under statutory health insurance reimbursement frameworks. EU MDR and EU AI Act conformity obligations tighten documentation burdens for cloud-based analytics providers. Munich and Berlin concentrate notified body relationships and regulatory consultancy capacity for CE marking support.
China
Domestic semiconductor packaging capabilities reduce hardware integration costs for multi-sensor wearable form factors. NMPA medical device registration requirements govern market entry for diagnostic-grade ECG functionality. Shenzhen and Shanghai anchor contract manufacturing clusters for Bluetooth-enabled device assembly.
Japan
Aging demographics accelerate demand for home-based heart failure monitoring integrated with telemedicine platforms. PMDA regulatory review timelines extend product development cycles for algorithm-driven classification features. Tokyo and Osaka concentrate electrophysiology practice networks and hospital system procurement decision-making.
South Korea
Employer-sponsored wellness programs in technology and financial services sectors drive direct-to-consumer smartwatch ECG adoption. MFDS medical device approval requirements align with international standards for electrical biosignal acquisition safety. Seoul anchors semiconductor design expertise for edge machine learning inference chips.
Wearable ECG Monitors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure. Prescription-grade patch monitor revenue concentrates among full-stack medical device manufacturers with decades of clinical trial infrastructure, while consumer-electronics entrants dominate direct-to-consumer distribution through vertical integration of semiconductor design with health platforms. Three archetypes define competitive positioning: legacy device manufacturers with regulatory relationships, consumer technology platforms with scale advantages, and specialized algorithm developers with telemetry service capabilities. Dominant competitive moves include strategic partnerships between hardware manufacturers and telemedicine platforms, plus portfolio diversification into subscription-based cloud analytics.
Among legacy medical device manufacturers, Medtronic and Abbott exemplify the prescription-grade archetype through sustained investment in FDA-cleared diagnostic platforms. Apple and Samsung Electronics occupy the consumer-electronics tier, leveraging semiconductor design capabilities and existing device ecosystems for wellness-oriented ECG functionality. iRhythm Technologies represents the specialized algorithm developer archetype, focusing on cloud-based telemetry services and automated arrhythmia classification for telemedicine integration.
| Leading Market Players |
|---|
| Medtronic |
| Koninklijke Philips N.V. |
| OMRON Corporation |
| Abbott |
| Fitbit |
| Apple |
| Samsung Electronics |
| iRhythm Technologies |
| AliveCor |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day electrode inventory cycles in silver-silver chloride sourcing compress margin buffers for patch monitor manufacturers while amplifying pricing power for East Asian contract manufacturers with captive material positions. This lead-time band tethers FDA-cleared device economics to semiconductor packaging hubs in Taiwan and South Korea, where foundry allocation decisions cascade through finished-goods pricing to United States cardiology clinics.
Pricing Analysis
The customization-premium spread between standard Bluetooth-enabled patch monitors and configured-to-order cloud-telemetry systems spans subscription SaaS-tiered models against per-unit transactional hardware sales. Price differentiation rests on FDA 510(k) certification tier and after-sales algorithm-update bundling, with Medicare-reimbursed prescription-grade devices commanding substantial premiums over direct-to-consumer smartwatch alternatives. Pricing pressure stems from consumer-electronics entrants leveraging semiconductor design scale to compress wellness-tier margins. Fitness enthusiasts through employer-sponsored wellness programs exhibit highest price sensitivity, while hospital purchasing committees under accountable care organization mandates demonstrate lowest sensitivity due to readmission penalty avoidance.
Supply Chain Analysis
Inventory concentration in silver-silver chloride electrode substrates and Bluetooth Low Energy 5.0 protocol chips exposes patch manufacturers to single-source vulnerability in East Asian contract manufacturing clusters. Geographic supply concentration centers on Taiwan for semiconductor packaging, South Korea for wireless component integration, and China for final device assembly. Raw material dependencies include medical-grade adhesive polymers, biocompatible conductive gels, and lithium-polymer cell substrates. Distribution runs through GPO contracts with United States hospital systems for prescription-grade devices, while consumer-tier products bypass clinical procurement through direct-to-employer channels and retail electronics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as photoplethysmography-based optical heart rate estimation in consumer smartwatches erodes diagnostic-grade patch monitor addressable markets among wellness-focused cohorts.
For Market Incumbents: Secure algorithm-exclusivity arrangements with telemedicine platforms to lock cloud-telemetry revenue streams against consumer-electronics platform expansion. Deepen backward integration into silver-silver chloride electrode substrate sourcing to buffer Taiwan foundry allocation volatility. Fortify FDA 510(k) predicate device portfolios against AI-enabled arrhythmia detection entrants compressing diagnostic-throughput timelines. For New Entrants and Emerging Players: Anchor in EU AI Act conformity assessment services for cloud-based analytics providers facing documentation burdens under MDR notified body scrutiny. Target employer-sponsored wellness programs in United States technology and financial services sectors where executive health benefits budgets exceed traditional clinical procurement thresholds. Pursue direct-to-employer contracting models bypassing GPO and payer channel complexity. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because FDA 510(k) clearance timelines and Medicare reimbursement code stability concentrate durable revenue predictability among established clinical trial infrastructure holders. Acquisition target archetype: specialized algorithm developers with HL7 FHIR-integrated telemetry platforms and existing hospital system deployments. Signal to watch: CMS readmission penalty rate adjustments that would intensify or relax hospital investment in ambulatory ECG surveillance.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses time-to-market for AI-enabled arrhythmia detection features against predicate device benchmarks. |
| CE Marking Pathway Investment | Secures EU MDR conformity for cloud-based telemetry under tightening AI Act documentation obligations. |
| Hospital System Partnership | Locks procurement volume through GPO contracts with Medicare accountable care organizations. |
| Software Companion Development | Enables Epic and Cerner HL7 FHIR integration for seamless clinician workflow embedding. |
| Reimbursement Strategy Execution | Captures sustainable revenue predictability through Medicare remote patient monitoring payment code alignment. |
Research Methodology
The analysis maps patch monitors, smartwatches, handheld devices, and chest straps, each validated through electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined secondary validation through FDA 510(k) clearance databases, CMS Medicare reimbursement code filings, hospital procurement contract registries, and EU MDR notified body technical file disclosures. Bottom-up shipment estimates by product form factor triangulated against top-down revenue aggregates across connectivity architectures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, end user archetype, connectivity technology, and application category alongside reimbursement pathway clustering. CAGRs derived from fitted growth curves incorporating Medicare accountable care organization expansion rates, FDA clearance pipeline velocity, and employer-sponsored wellness program penetration trajectories. Industry-specific forecast inputs included silver-silver chloride electrode supply elasticity and Bluetooth protocol standardization adoption curves.
Material uncertainties — reimbursement parity reassessments between prescription and over-the-counter ECG form factors, EU AI Act enforcement intensity variations, and semiconductor foundry allocation disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding Medicare payment code stability and cloud-telemetry subscription retention rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
Europe Biomedical Sensors Market
Patient Monitoring
Remote Patient Monitoring Software Market
Patient Monitoring
Fetal and Neonatal Heart Monitor Market
Patient Monitoring
Patient Scales Market
Patient Monitoring
Bedside Monitors Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Global Blood Pressure Monitoring Devices Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Global Fetal and Neonatal Monitoring Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market