
 Japan Patient Care Monitoring Equipment Market | 2026-2036
Japan Patient Care Monitoring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Patient Care Monitoring Equipment Market Foresight
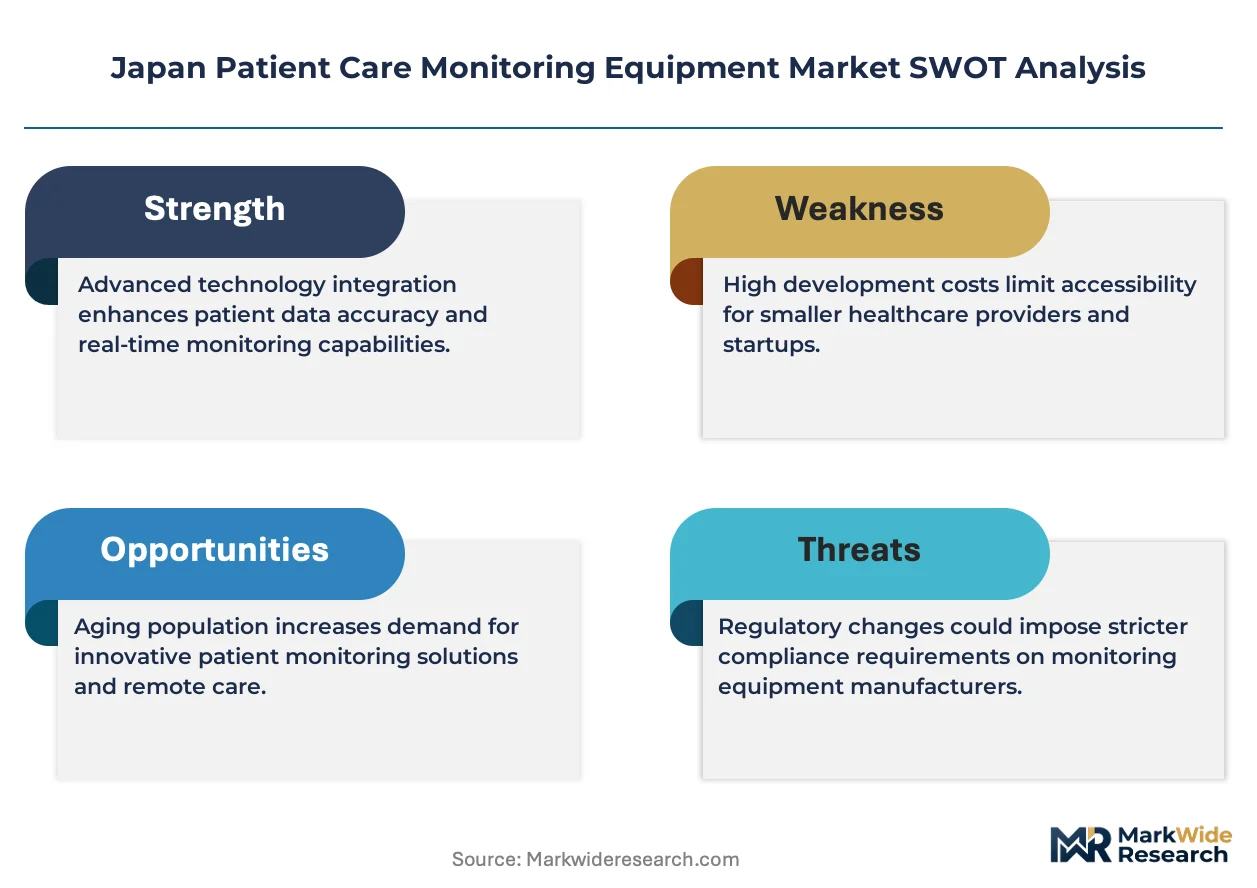
Modular sensor configurations paired with subscription-based software tiers is repositioning procurement decisions across Japanese healthcare networks. Nihon Kohden Corporation leverages its domestic manufacturing footprint to anchor hospital contracts in the Kansai region. Omron Corporation differentiates through specialized home blood pressure and ECG monitoring portfolios that sustain retail pharmacy channel dominance. GE Healthcare competes by extending its cloud analytics architecture into integrated delivery networks serving aging prefectural populations.
Patient care monitoring equipment encompasses electronic systems that acquire, process, display, and transmit physiological parameters including electrocardiographic waveforms, blood oxygen saturation, respiratory rate, and invasive pressure readings with sampling frequencies typically exceeding 250 Hz for diagnostic-grade cardiac channels. These systems serve continuous surveillance functions in clinical environments where early deterioration detection reduces adverse events and length-of-stay metrics. Cardiac monitors occupy the largest installed base in Japanese tertiary hospitals, while wearable devices represent the fastest-expanding margin pool as ambulatory electrocardiography reimbursement broadens under national health insurance revisions. Telehealth solutions command premium positioning in postoperative care pathways, though home care segments face margin compression from standardized remote monitoring fee schedules.
PMDA's QMS ordinance and JIS T 0601-1 electrical safety standards govern device approval and post-market surveillance obligations for all manufacturers distributing in Japan. METI's Medical and Nursing Care Device Industry Promotion Plan creates subsidy pathways for domestic producers developing AI-integrated diagnostic algorithms. Stakeholders must monitor evolving reimbursement classifications for remote therapeutic monitoring as the Ministry of Health, Labour and Welfare recalibrates fee-for-service schedules to align with decentralized care delivery models.
Market Dynamics
Japan's patient care monitoring equipment sector is undergoing a fundamental reconfiguration as METI's digital health subsidies and PMDA's streamlined AI-device approval pathways compress development timelines for domestic manufacturers. This regulatory-industrial alignment is accelerating the shift from hardware-centric procurement to integrated platform contracts that bundle sensors, cloud infrastructure, and predictive analytics.
Growth Catalysts
- Remote patient monitoring reimbursement:Japan's Ministry of Health, Labour and Welfare expanded fee-for-service codes for ambulatory electrocardiography and postoperative telemetry, creating direct revenue pathways for hospitals deploying wearable vital signs monitors in elderly care applications.
- AI-integrated diagnostic algorithms:METI's Medical and Nursing Care Device Industry Promotion Plan subsidizes domestic producers developing machine learning models for arrhythmia detection and sepsis prediction, lowering R&D barriers for specialized software modules.
- Kanto region aging demographics:Concentrated elderly populations in Tokyo and surrounding prefectures sustain institutional demand for continuous surveillance systems in long-term care facilities and home-based care networks.
Market Restraints
- PMDA QMS ordinance compliance costs:Post-market surveillance obligations and JIS T 0601-1 electrical safety certification requirements impose substantial documentation and testing burdens on smaller domestic manufacturers seeking hospital procurement contracts.
- Standardized remote monitoring fee schedules:National health insurance revisions have compressed margins for home care segments, limiting profitability of cloud-based telemetry services despite expanding volume.
- Semiconductor component import dependency:Japanese device assemblers rely on concentrated overseas suppliers for high-frequency analog front-ends and low-power wireless chipsets, exposing production schedules to supply volatility.
Strategic Opportunities
- Osaka acute care hospital expansion:Major tertiary facilities in the Kansai region are retrofitting intensive care units with modular sensor configurations, creating procurement windows for integrated monitoring platforms with subscription-based software tiers.
- Retail pharmacy channel penetration:Specialized home blood pressure and ECG monitoring portfolios can extend beyond hospital networks into consumer-facing distribution, capturing out-of-pocket spending from health-conscious demographics.
- Cloud analytics architecture convergence:Integration of edge computing with centralized data lakes enables predictive deterioration alerts that reduce length-of-stay metrics, aligning with prefectural hospital efficiency mandates.
Industry Challenges
- Legacy system interoperability:Hospital information systems in Japanese tertiary facilities operate on fragmented data standards, forcing monitoring platform vendors to maintain multiple integration protocols and delaying deployment timelines.
- Biomedical engineering talent scarcity:Specialized expertise in signal processing for diagnostic-grade cardiac channels and regulatory affairs navigation remains concentrated among established manufacturers, constraining startup scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Patient Care Monitoring Equipment Market |
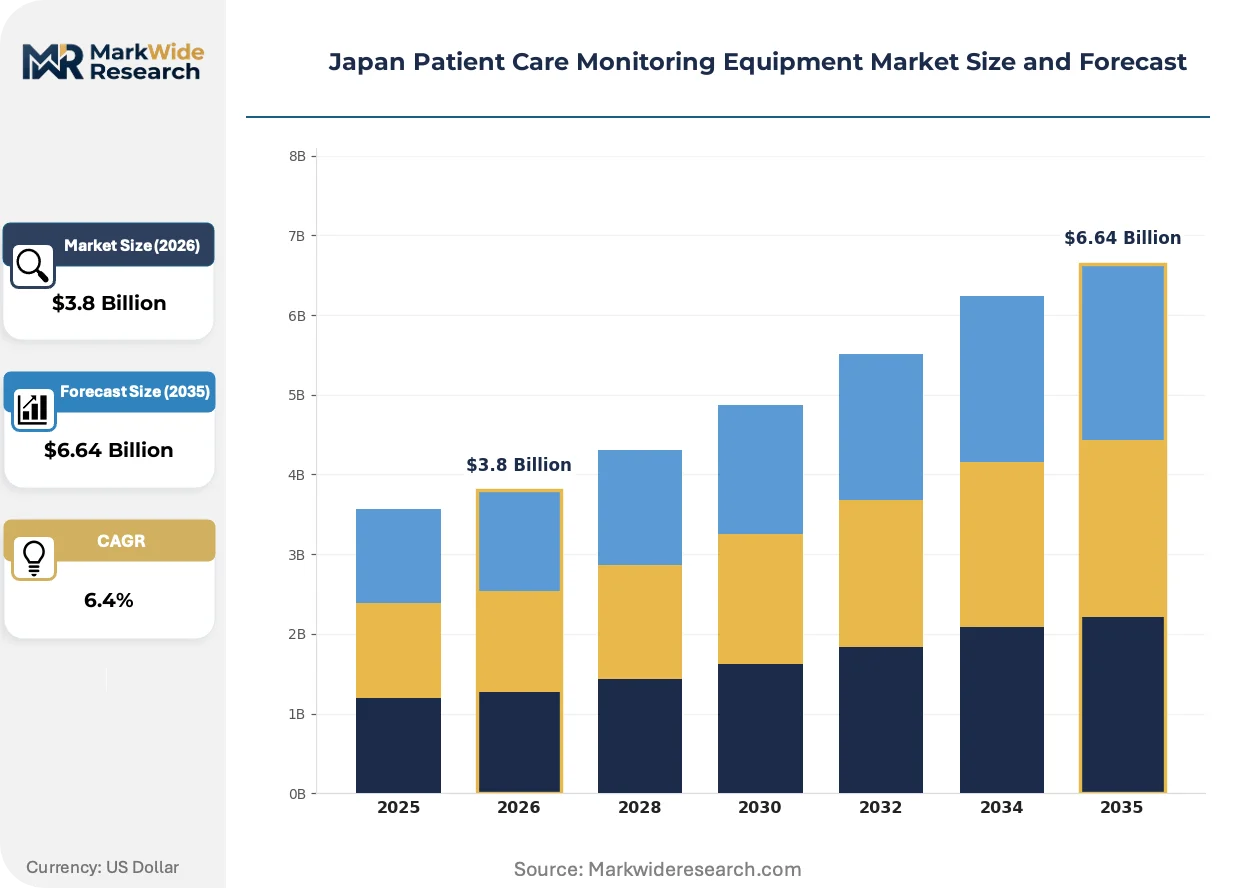
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Monitors, Vital Signs Monitors, Respiratory Monitors, Fetal Monitors End User: Hospitals, Home Care, Long-term Care Facilities, Specialty Clinics Technology: Wireless Monitoring, Telehealth Solutions, Wearable Devices, Cloud-based Systems Application: Chronic Disease Management, Postoperative Care, Elderly Care, Critical Care |
| Companies Covered | Nihon Kohden Corporation, Omron Corporation, GE Healthcare, Koninklijke Philips N.V., Abbott Laboratories, Boston Scientific Corporation, Siemens Healthcare GmbH, Baxter International Inc, Becton, Dickinson and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Patient Care Monitoring Equipment Market Shifts & Advancements
Wearable vital signs technology is compressing the boundary between acute and ambulatory care settings, forcing established equipment categories to reposition around continuous data streams rather than episodic measurement. This shift is redrawing competitive boundaries between hospital-grade manufacturers and consumer health device producers.
Photoplethysmography-enhanced wearables is expanding into diagnostic-grade cardiac monitoring applications previously dominated by bedside multi-parameter systems. Cardiology departments at Tokyo metropolitan hospitals are piloting ambulatory arrhythmia detection bracelets that sample at 250 Hz equivalent fidelity. This capability compression is enabling early discharge protocols that shift postoperative surveillance from intensive care units to home-based telemetry.
METI's 2024 revision to medical software classification guidelines has reclassified AI-powered deterioration prediction algorithms as Class II medical devices with abbreviated approval pathways. Domestic manufacturers now face reduced clinical evidence requirements for cloud-based sepsis alert systems. Osaka-based hospital networks are accelerating procurement of these platforms to meet prefectural readmission reduction targets.
Subscription-based software tiers are displacing perpetual license models in integrated delivery network contracts. Prefectural hospital consortia in the Kanto region now prioritize vendors offering predictive analytics modules priced per-monitored-bed rather than capital expenditure arrangements. This preference shift favors domestic manufacturers with captive cloud infrastructure over import-dependent competitors with hardware-centric business models.
Japan Patient Care Monitoring Equipment Market Segmentation
Equipment replacement cycles in Japanese healthcare networks accelerate where modular architectures permit sensor upgrades without full system overhauls. Procurement committees at Osaka and Tokyo tertiary facilities now weight interoperability specifications above brand loyalty when evaluating monitoring platform investments.
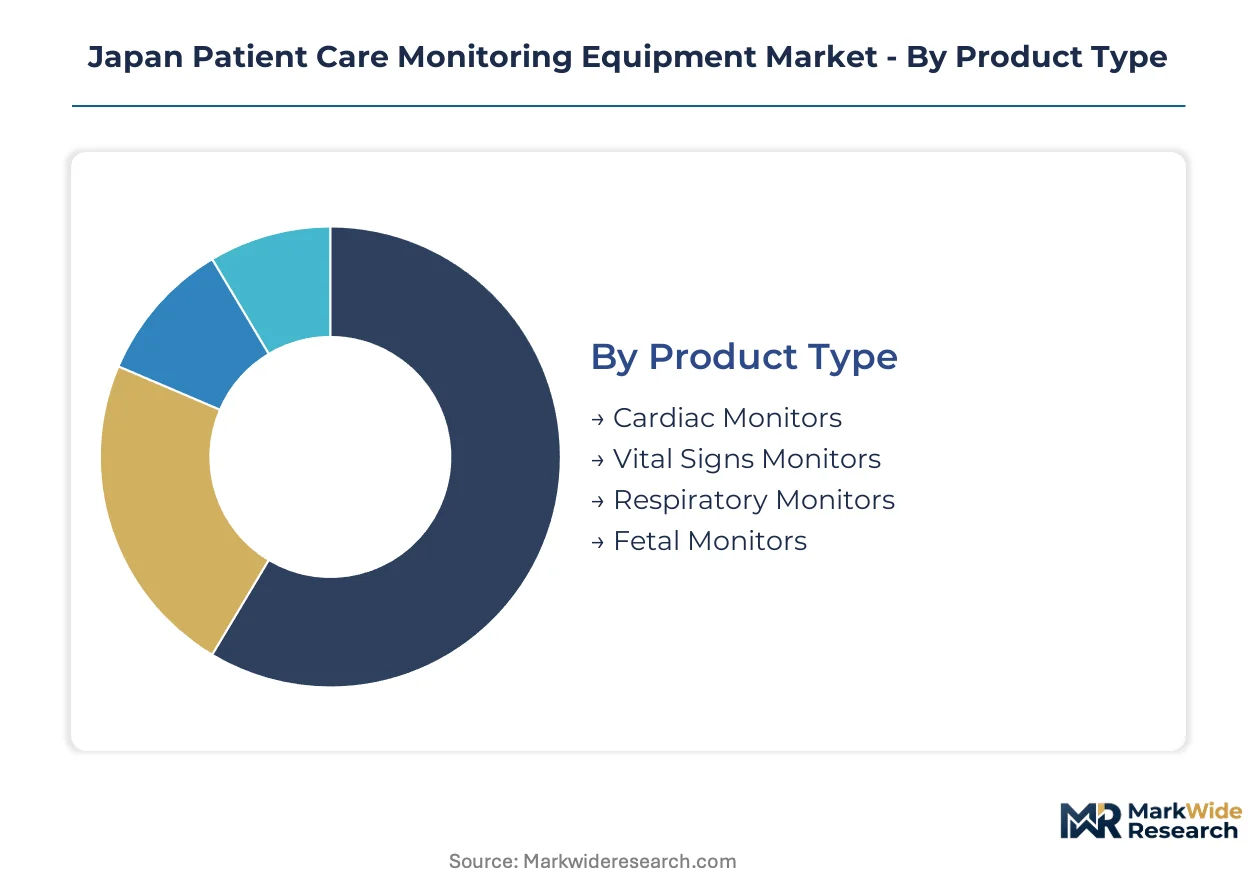
Product Type:
Upgrade pathways for diagnostic-grade systems in Japanese acute care hospitals favor platforms with field-replaceable acquisition modules and firmware-expandable processing units.
- Cardiac Monitors:Multi-parameter systems acquire electrocardiographic waveforms at sampling frequencies exceeding 250 Hz through diagnostic-grade channels. Tokyo metropolitan hospitals concentrate demand for these units as postoperative telemetry reimbursement expands under Ministry of Health, Labour and Welfare fee revisions.
- Vital Signs Monitors:Compact bedside units integrate non-invasive blood pressure, pulse oximetry, and temperature sensing through unified display architectures. Long-term care facilities in the Kanto region drive procurement volume as prefectural aging mandates intensify continuous surveillance requirements.
- Respiratory Monitors:Capnography and spirometry systems with integrated airway pressure sensing serve intensive care ventilation management.
- Fetal Monitors:Ultrasound-based cardiotocography systems with uterine contraction transducers support obstetric departments in perinatal care networks.
Cardiac monitors sit at the top of the volume ranking, with wearable devices climbing the fastest.
End User:
Customer procurement authority in Japan fragments across institutional purchasing consortia, retail pharmacy chains, and municipal care coordinators with diverging technical specifications.
- Hospitals:Tertiary acute care facilities in Osaka and Tokyo operate centralized biomedical engineering departments with capital expenditure authority over multi-parameter platform deployments. These institutions prioritize vendors offering subscription-based software tiers aligned with prefectural efficiency mandates.
- Home Care:Municipal care managers coordinate dispersed patient populations requiring cloud-connected telemetry for postoperative surveillance. Standardized remote monitoring fee schedules compress service margins despite expanding beneficiary enrollment.
- Long-term Care Facilities:Prefectural licensing requirements mandate continuous vital signs surveillance for high-dependency residents.
- Specialty Clinics:Cardiology and sleep disorder practices purchase ambulatory monitoring devices for diagnostic service revenue.
Hospitals command the dominant revenue share, while home care networks are gaining share fastest as discharge protocols accelerate.
Technology:
Technology selection in Japanese procurement cycles increasingly prioritizes cloud-native architectures over hardware-centric legacy systems with limited data portability.
- Wireless Monitoring:Low-power radio frequency and Bluetooth Low Energy protocols enable bedside-to-central-station data transmission without tethered cabling. Acute care hospitals in the Kansai region retrofit intensive care units with these configurations to support modular sensor placement.
- Telehealth Solutions:Integrated video consultation platforms with synchronous physiological data streaming connect tertiary specialists to remote care sites. METI digital health subsidies reduce deployment costs for prefectural hospital networks pursuing decentralized care models.
- Wearable Devices:Photoplethysmography-enhanced bracelets and patches sample cardiac signals at diagnostic-equivalent fidelity for ambulatory arrhythmia detection.
- Cloud-based Systems:Centralized data lakes with edge-computing preprocessing enable predictive deterioration alerts across distributed sensor networks.
Wireless monitoring retains the largest installed base, with telehealth solutions expanding most quickly following reimbursement pathway clarification.
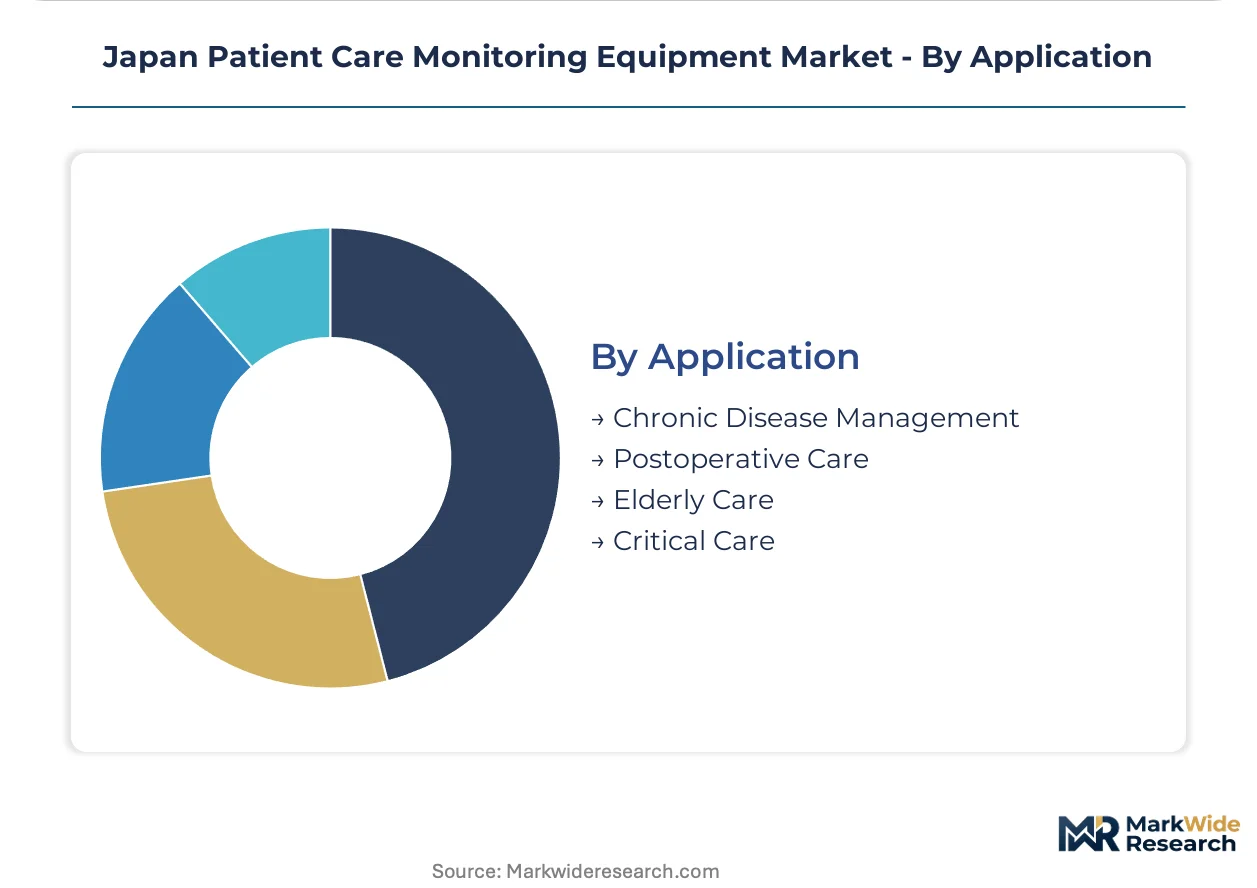
Application:
Application-specific demand in Japan correlates directly with national health insurance reimbursement classifications and prefectural readmission reduction targets.
- Chronic Disease Management:Continuous glucose monitoring integration with blood pressure telemetry supports diabetes and hypertension patient cohorts. Home-based deployments in Tokyo prefecture leverage expanded ambulatory electrocardiography fee codes for sustained monitoring revenue.
- Postoperative Care:Early discharge protocols shift surveillance from intensive care units to cloud-connected telemetry systems. Osaka hospital networks pilot AI-powered sepsis prediction algorithms to meet prefectural readmission reduction mandates.
- Elderly Care:Fall detection and nocturnal vital signs monitoring serve aging populations in Kanto region long-term care facilities.
- Critical Care:Multi-parameter invasive monitoring with arterial pressure and central venous oxygen saturation sensing supports surgical and trauma intensive care units.
Elderly care dominates current procurement volume, with postoperative care demonstrating the steepest expansion trajectory as early discharge protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's patient care monitoring equipment industry traces its modern foundations to post-war industrialization in the Kanto region, where domestic electronics manufacturers first integrated semiconductor sensing with clinical measurement protocols during the 1960s and 1970s.
Kanto/Tokyo
Tokyo metropolitan hospitals drive demand for multi-parameter cardiac monitoring systems as postoperative telemetry reimbursement expands under Ministry of Health, Labour and Welfare fee revisions. METI's Medical and Nursing Care Device Industry Promotion Plan subsidizes AI-integrated diagnostic algorithm development for domestic manufacturers headquartered in the capital region. Yokohama and surrounding prefectures concentrate R&D facilities for cloud-based telemetry platforms serving aging suburban populations.
Kansai/Osaka
Osaka's tertiary acute care facilities are retrofitting intensive care units with modular sensor configurations that permit field-replaceable acquisition modules. PMDA's streamlined QMS ordinance compliance pathways accelerate device approval timelines for Kansai-based manufacturers seeking hospital procurement contracts. Kyoto and Kobe medical device clusters specialize in photoplethysmography-enhanced wearables for ambulatory arrhythmia detection.
Chubu/Nagoya
Nagoya's industrial manufacturing heritage supports precision sensor component fabrication for diagnostic-grade cardiac channels sampling above 250 Hz. The region's automotive electronics suppliers pivot capabilities toward medical device analog front-ends as semiconductor import dependency creates domestic sourcing incentives. Toyota City's healthcare networks pilot integrated delivery network contracts bundling sensors with subscription-based predictive analytics.
Kyushu
Fukuoka's prefectural hospital networks pursue decentralized care delivery models leveraging METI digital health subsidies for telehealth infrastructure deployment. Long-term care facilities across the island face intensified continuous surveillance mandates for high-dependency elderly residents. Kumamoto medical device assemblers develop edge-computing preprocessing units for predictive deterioration alert systems.
Tohoku
Sendai's reconstruction-era healthcare infrastructure incorporates wireless monitoring protocols enabling bedside-to-central-station data transmission without tethered cabling. Municipal care managers in rural prefectures coordinate cloud-connected telemetry for dispersed postoperative patient populations despite standardized remote monitoring fee schedule compression. Aomori and Iwate long-term care facilities concentrate procurement volume for compact vital signs monitors integrating non-invasive blood pressure and pulse oximetry sensing.
Japan Patient Care Monitoring Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software-analytics capabilities, with integrated platform vendors commanding subscription-based recurring revenue while hardware-centric competitors face capital expenditure procurement resistance. The vendor base stratifies across three tiers: domestic manufacturers with captive cloud infrastructure, multinational medical technology conglomerates with hospital system relationships, and specialized component suppliers feeding modular sensor architectures. Two competitive moves dominate: backward integration into semiconductor analog front-end sourcing to mitigate import dependency, and strategic partnerships with prefectural hospital consortia to secure integrated delivery network contracts.
Among Japan-based manufacturers, Nihon Kohden Corporation and Omron Corporation exemplify contrasting strategic archetypes within the domestic tier. Nihon Kohden occupies a position anchored in hospital-grade multi-parameter systems with domestic manufacturing footprints securing Kansai region contracts. Omron represents the consumer-facing specialization vector, with retail pharmacy channel penetration sustaining out-of-pocket revenue streams. GE Healthcare sits within the multinational tier, extending cloud analytics architecture into prefectural networks serving aging populations. Koninklijke Philips N.V. and Siemens Healthcare GmbH round out the integrated platform competition, while Abbott Laboratories, Boston Scientific Corporation, Baxter International Inc, and Becton, Dickinson and Company populate the specialized device and consumables segments.
| Leading Market Players |
|---|
| Nihon Kohden Corporation |
| Omron Corporation |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Siemens Healthcare GmbH |
| Baxter International Inc |
| Becton, Dickinson and Company |
| Others |
Supply & Pricing Matrix
METI's Medical and Nursing Care Device Industry Promotion Plan gates qualified supply access for domestic manufacturers while anchoring premium-tier pricing for AI-integrated monitoring platforms that meet subsidy eligibility criteria.
Pricing Analysis
Subscription-based software tiers priced per-monitored-bed dominate integrated delivery network contracts, separating premium predictive analytics modules from standard telemetry and economy-grade hardware-only configurations. Price differentiation hinges on PMDA QMS ordinance certification tier and cloud-native architecture sophistication. Cost compression in home care segments intensifies as standardized remote monitoring fee schedules compress service margins. Municipal care managers exhibit highest price sensitivity, while Tokyo metropolitan tertiary hospitals prioritize interoperability specifications over unit cost.
Supply Chain Analysis
Biomedical engineering talent scarcity in Osaka and Nagoya manufacturing clusters constrains production scaling for diagnostic-grade cardiac channel components. Japanese device assemblers draw from concentrated overseas suppliers for high-frequency analog front-ends and low-power wireless chipsets, with Taiwan and South Korea anchoring semiconductor sourcing. Single-source vulnerability in wireless chipset supply exposes production schedules to logistics chokepoints. Distribution runs through prefectural hospital consortia and retail pharmacy chains serving distinct buyer archetypes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's patient care monitoring equipment market functions as a stable compounder, with Kanto region aging demographics sustaining institutional demand across multiple economic cycles.
For Market Incumbents: Anticipate margin compression from wearable device entrants by deepening cloud analytics capabilities and securing multi-year integrated delivery network contracts before reimbursement recalibration. METI's digital health subsidy expansion creates leverage for domestic manufacturers with captive infrastructure. Priority investment in JIS T 0601-1 electrical safety certification maintenance defends hospital procurement eligibility against emerging competitors. For New Entrants and Emerging Players: Retail pharmacy chains represent the most penetrable channel for specialized home blood pressure and ECG monitoring portfolios, capturing out-of-pocket spending from health-conscious demographics underserved by hospital-centric incumbents. Municipal care managers in Tohoku rural prefectures coordinate dispersed elderly populations with unmet telemetry needs. Go-to-market positioning should emphasize cloud-connected subscription pricing aligned with standardized remote monitoring fee schedules. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic manufacturers with modular sensor architectures and latent cloud infrastructure capacity. Long-term viability framing favors platform vendors with recurring revenue exposure over hardware-centric competitors facing capital expenditure procurement resistance. Watch PMDA's AI-device approval pathway expansion velocity as the primary inflection indicator for software-analytics premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA QMS Ordinance Compliance Investment | Secures hospital procurement eligibility and accelerates post-market surveillance obligations for domestic manufacturers. |
| Cloud Analytics Architecture Development | Enables predictive deterioration alerts that align with prefectural hospital efficiency mandates and readmission reduction targets. |
| Retail Pharmacy Channel Partnership | Extends specialized home monitoring portfolios into consumer-facing distribution beyond institutional networks. |
| AI-Integrated Diagnostic Algorithm Submission | Leverages METI subsidy pathways and streamlined Class II approval timelines for sepsis prediction modules. |
| Modular Sensor Configuration Platform | Permits field-replaceable acquisition modules that reduce full system replacement cycles in Osaka and Tokyo facilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and municipal care coordinators with secondary validation against PMDA device registration databases, METI subsidy disclosure filings, hospital procurement records, and Ministry of Health, Labour and Welfare reimbursement schedule revisions. Bottom-up installed base estimates and top-down expenditure flows were triangulated to anchor market sizing.
Segment-weighting approaches modeled product type, end user, technology, and application dimensions across the projection horizon. CAGRs derived from historical expenditure trajectories and forward-looking reimbursement pathway clarifications incorporated prefectural aging demographic projections and AI-device approval velocity assumptions.
Revisions become necessary when PMDA regulatory recalibration, METI subsidy program modification, or semiconductor supply disruption materialize. Forecasts reflect documented assumptions regarding reimbursement expansion continuity and domestic manufacturing incentive durability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
Europe Cardiac Holter Monitor Market
Patient Monitoring
AI in Remote Patient Monitoring Market
Patient Monitoring
Neuro-Monitoring System Market
Patient Monitoring
Europe Respiratory Monitoring Market
Patient Monitoring
Global Multi-Parameter Patient Monitoring Equipment Market
Patient Monitoring
North America Patient Monitoring Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Global Smart Pulse Oximeters Market