
 Urine Monitoring Systems Market | 2026-2036
Urine Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Urine Monitoring Systems Market Analytics
Aftermarket service revenue for connected urine monitoring hardware is tilting toward predictive maintenance contracts and remote calibration services. Baxter International Inc. leverages its dialysis infrastructure to bundle urinary output sensors with renal therapy platforms. Fresenius Medical Care anchors its position through captive distribution to nephrology clinics across Western Europe. Medtronic plc competes by extending its critical care monitoring ecosystem into automated urine analysis modules for ICU workflows.
Urine monitoring systems encompass wearable catheters, benchtop analyzers, dipstick readers, and cloud-connected fluid balance platforms that measure biomarkers such as creatinine, protein, and electrolyte concentrations through spectroscopic or electrochemical detection. These systems serve acute care, chronic disease management, and preventive screening by delivering real-time renal function data to clinicians. Wearable devices capture expanding margin pools as ambulatory surgery centers adopt continuous urine output tracking for enhanced recovery protocols. Electrochemical sensors lead technology adoption due to miniaturization advances that enable disposable, low-cost electrode arrays. Hospitals remain the dominant end user, though home care segments attract investment from manufacturers developing Bluetooth-enabled dipstick readers for diabetes self-management.
FDA 510(k) pathways govern clearance of automated urinalysis devices in the United States, while the EU Medical Device Regulation imposes clinical evidence requirements for software-as-a-medical-device urine analysis platforms. Japan's PMDA accelerates review timelines for AI-diagnostic urine monitoring systems through its Sakigake fast-track designation. Stakeholders must monitor evolving cybersecurity standards for connected incontinence and renal monitoring devices as health authority guidance hardens around data integrity in cloud-based diagnostic workflows.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships for connected urinary analysis platforms, compressing supplier margins while elevating technical service requirements as a competitive differentiator. This centralization is forcing device manufacturers to embed predictive analytics and remote calibration capabilities into base hardware contracts.
Growth Catalysts
- Japan's PMDA Sakigake fast-track:The designation accelerates review timelines for AI-diagnostic urine monitoring systems, compressing commercialization cycles for sensor-integrated devices targeting renal function tracking.
- Electrochemical sensor miniaturization:Disposable electrode arrays now enable low-cost, single-use detection of creatinine and electrolyte concentrations at point-of-care settings.
- Ambulatory surgery center expansion:Enhanced recovery after surgery protocols in United States outpatient facilities mandate continuous urine output tracking, driving wearable catheter adoption.
Market Restraints
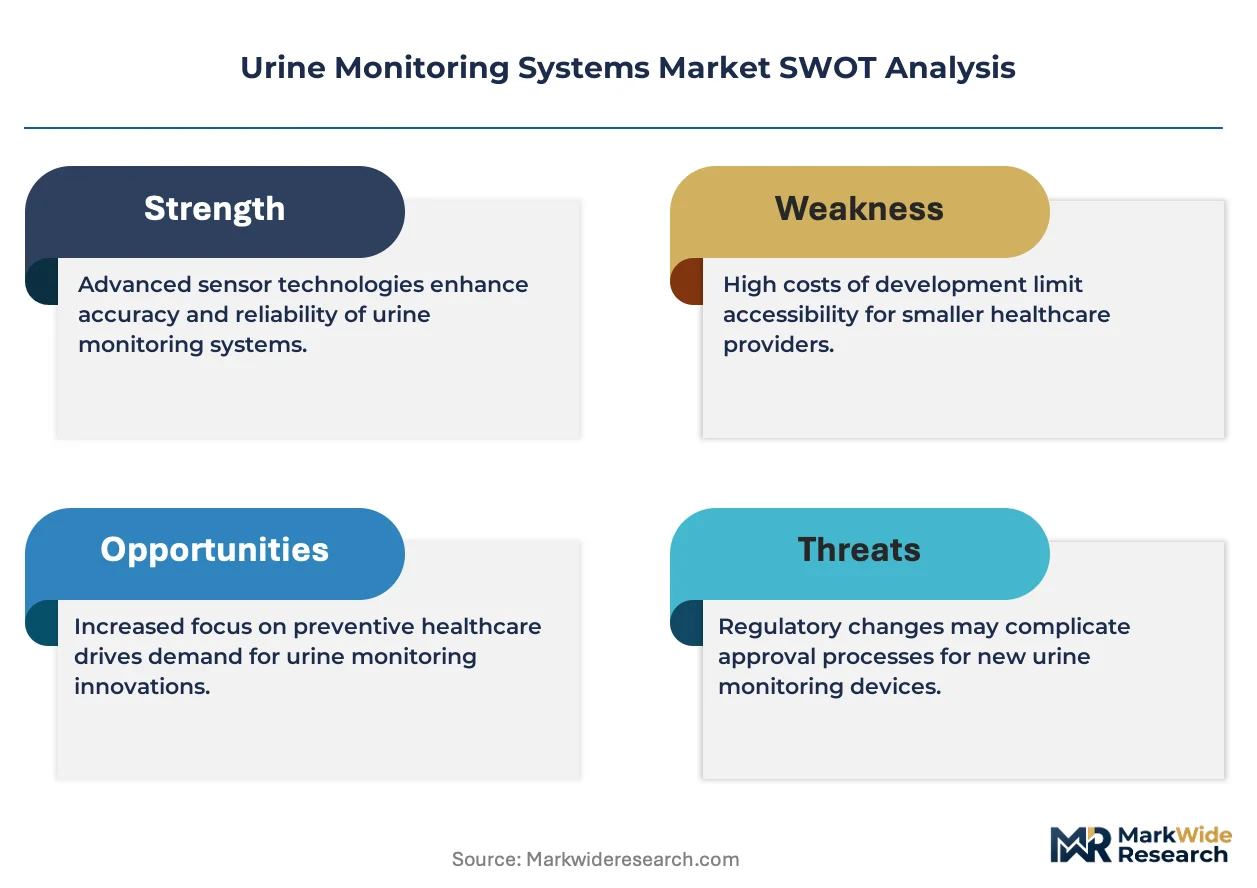
- Reimbursement fragmentation:United States CMS coding gaps for remote urine monitoring create payment uncertainty that delays hospital capital allocation decisions.
- Sensor supply concentration:Specialized electrochemical electrode manufacturing clusters in East Asia expose device makers to single-source risk during logistics disruptions.
- Substitute diagnostic modalities:Blood-based renal biomarker panels from centralized laboratories compete for the same clinical decision-making budgets in chronic kidney disease management.
Strategic Opportunities
- Home diabetes self-management:Bluetooth-enabled dipstick readers create direct-to-consumer revenue streams outside traditional hospital procurement channels.
- EU Medical Device Regulation clinical data requirements:Early movers investing in software-as-a-medical-device evidence packages capture preferential notified body attention for urine analysis platforms.
- Nephrology clinic captive distribution:Western European renal therapy networks seek integrated fluid balance platforms bundled with dialysis services.
Industry Challenges
- Cloud cybersecurity compliance:Health authority guidance hardening around data integrity in connected incontinence devices demands dedicated firmware engineering resources.
- Legacy EMR integration:Automated urine analysis modules face interoperability friction with proprietary intensive care unit data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urine Monitoring Systems Market |
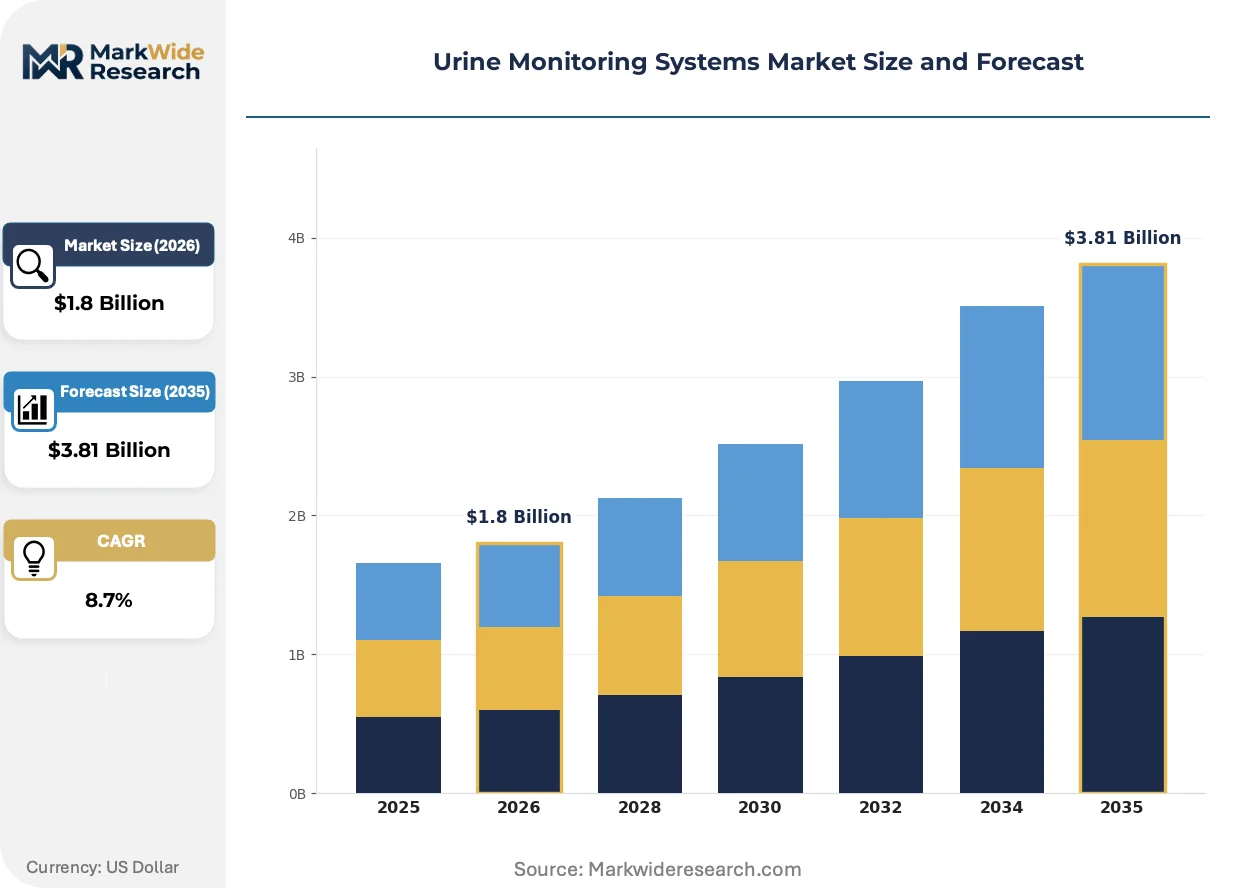
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
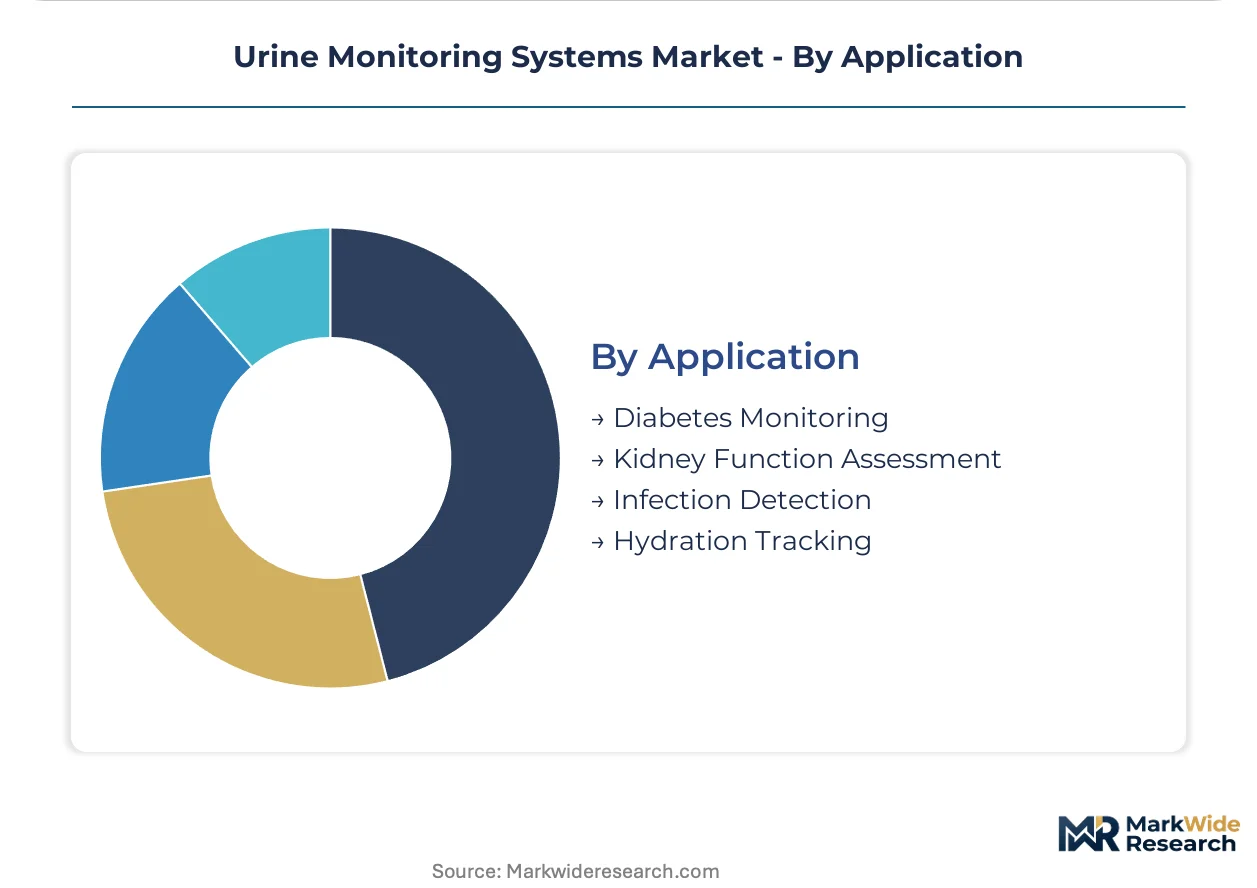
| Segmentation | Product Type: Wearable Devices, Analyzers, Test Strips, Online Monitoring Solutions End User: Hospitals, Home Care, Diagnostic Laboratories, Research Facilities Technology: Spectroscopy, Colorimetry, Electrochemical Sensors, Fluorescence Application: Diabetes Monitoring, Kidney Function Assessment, Infection Detection, Hydration Tracking |
| Companies Covered | Accuryn Medical, Becton Dickinson and Company, Cardinal Health, F. Hoffmann-La Roche Ltd, FIZE Medical, RenalSense, Baxter International Inc., Fresenius Medical Care, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urine Monitoring Systems Market Evolving Landscape
Spectroscopic detection methods are converging with disposable electrochemical architectures, reshaping how renal biomarker data flows from bedside sensors to cloud analytics platforms. This technical fusion is compressing the traditional separation between acute monitoring and chronic disease management workflows.
Multispectral imaging arrays embedded in benchtop analyzers are virtualizing the physical dipstick workflow, eliminating manual colorimetric interpretation errors while preserving the low-cost consumable model. United States hospital laboratories are adopting these systems at replacement-cycle pace, converting wet chemistry stations into automated renal diagnostic nodes that feed directly into electronic medical record streams.
The EU Medical Device Regulation's software-as-a-medical-device classification is forcing urine analysis platform developers to construct clinical evidence packages for algorithm-driven diagnostic outputs. Germany's notified bodies are processing these submissions with extended timelines, compelling manufacturers to front-load prospective validation studies. Japanese regulators are responding with streamlined Sakigake pathways for comparable AI-diagnostic systems.
United States hospital procurement departments are unbundling after-sales service from hardware acquisition, creating standalone markets for predictive maintenance contracts and remote calibration subscriptions. This purchasing behavior shift is most visible in integrated delivery networks managing multiple acute care facilities, where centralized biomedical engineering teams demand vendor-agnostic service level agreements for connected urinary output sensors.
Urine Monitoring Systems Market Segmentation
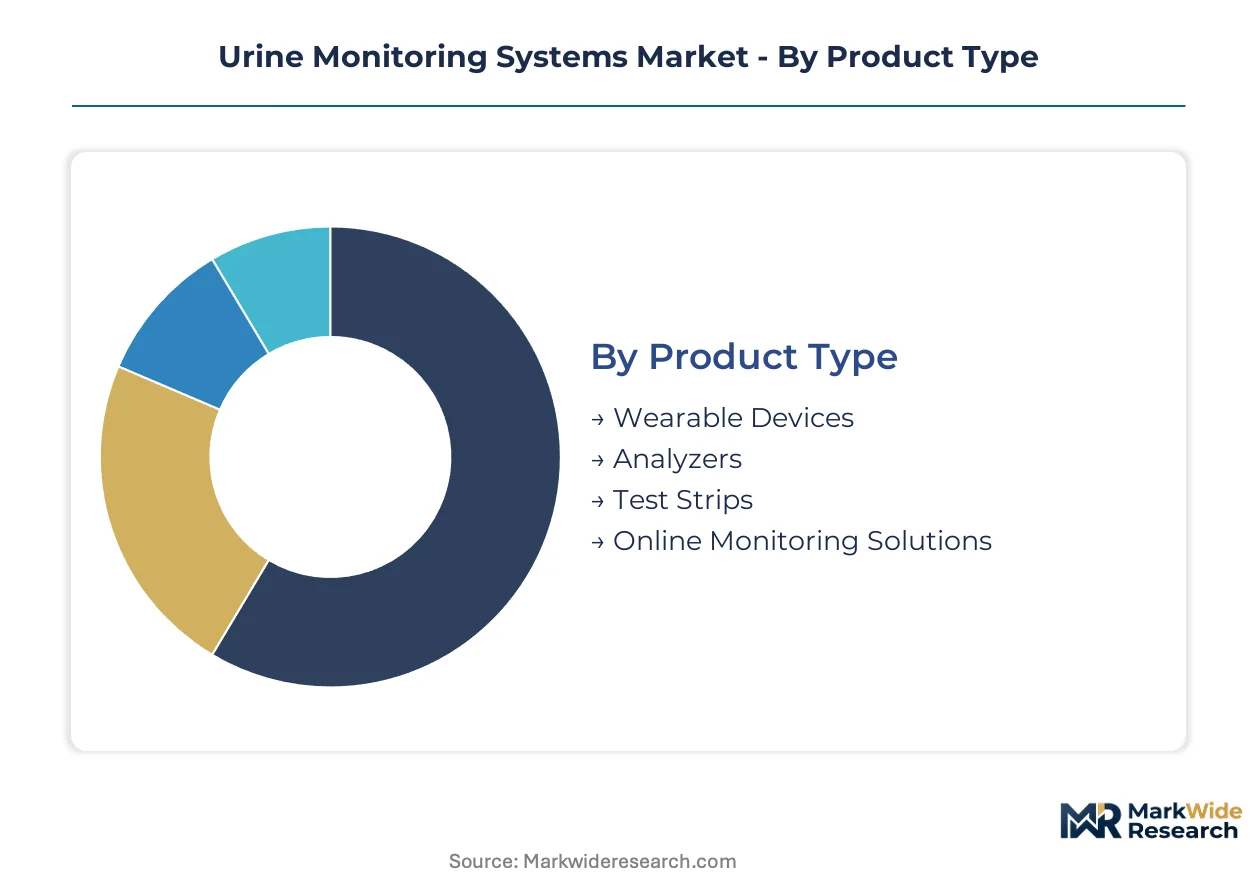
Segmentation in urine monitoring systems reveals distinct procurement cycles and margin architectures across hardware categories. Electrochemical miniaturization and cloud connectivity are fragmenting traditional boundaries between acute care and ambulatory deployment models.
Product Type:
Wearable catheters and benchtop analyzers operate on divergent replacement cycles, with disposable sensors turning over in days versus capital equipment measured in years.
- Wearable Devices:Continuous urine output sensors integrate Bluetooth telemetry for real-time fluid balance tracking. United States ambulatory surgery centers drive procurement for enhanced recovery protocols requiring post-discharge monitoring.
- Analyzers:Benchtop units deploy multispectral imaging arrays that automate colorimetric dipstick interpretation. Hospital laboratories in Germany prioritize these systems for high-throughput renal diagnostic workflows.
- Test Strips:Low-cost consumables with embedded reagent chemistry for creatinine and protein detection.
- Online Monitoring Solutions:Cloud-connected platforms aggregating sensor data across distributed care settings.
Analyzers dominate installed base. Wearable devices are where expansion concentrates.
End User:
Procurement authority varies sharply across settings, with integrated delivery networks consolidating vendor relationships while home care channels fragment purchasing decisions.
- Hospitals:Intensive care units and surgical wards deploy automated urine analysis modules for acute renal monitoring. Centralized biomedical engineering teams in United States health systems negotiate enterprise-wide service level agreements.
- Home Care:Bluetooth-enabled dipstick readers enable diabetes self-management outside clinical settings. Direct-to-consumer distribution in Japan bypasses traditional procurement channels.
- Diagnostic Laboratories:High-volume centralized testing facilities processing batch urinalysis samples.
- Research Facilities:Academic medical centers conducting biomarker validation studies for novel renal diagnostics.
Hospitals anchor revenue concentration. Home care is climbing the fastest.
Technology:
Detection modalities stratify by cost sensitivity and performance requirements, with electrochemical architectures displacing optical methods in point-of-care settings.
- Electrochemical Sensors:Disposable electrode arrays miniaturized for single-use creatinine and electrolyte measurement. Manufacturing clusters in East Asia supply electrode substrates to device makers worldwide.
- Spectroscopy:UV-visible absorbance detection for quantitative biomarker analysis in laboratory settings.
- Colorimetry:Visual or camera-based dipstick color matching for basic screening applications.
- Fluorescence:High-sensitivity detection of trace biomarkers in research and specialized clinical contexts.
Electrochemical sensors command volume leadership. Spectroscopy retains premium positioning in reference laboratories.
Application:
Clinical use cases differ in reimbursement clarity and monitoring intensity, with chronic disease management requiring longitudinal data streams versus acute episodes demanding immediate alerts.
- Kidney Function Assessment:Creatinine clearance monitoring and proteinuria detection for chronic kidney disease progression tracking. Nephrology clinics in Western Europe bundle fluid balance platforms with dialysis services.
- Diabetes Monitoring:Glucose and ketone detection via urine for glycemic control verification. United States CMS coding gaps create payment uncertainty for remote monitoring deployments.
- Infection Detection:Leukocyte esterase and nitrite screening for urinary tract infection diagnosis.
- Hydration Tracking:Specific gravity and osmolality measurement for athletic and military performance optimization.
Kidney function assessment holds the deepest clinical integration. Diabetes monitoring is gaining share fastest among ambulatory applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in Germany demonstrate the lowest price elasticity for connected urinary analysis platforms, while ambulatory surgery centers in the United States negotiate aggressively on per-procedure costs. Japanese nephrology clinics occupy a middle position, prioritizing regulatory clearance speed over absolute price minimization.
United States
Ambulatory surgery centers in Texas and Florida drive wearable catheter procurement for enhanced recovery protocols requiring post-discharge urine output tracking. FDA 510(k) pathways govern automated urinalysis device clearance, compressing time-to-market for sensor-integrated systems. Boston's medical device cluster hosts engineering teams developing Bluetooth-enabled dipstick readers for diabetes self-management channels.
Germany
Hospital laboratories in Bavaria and North Rhine-Westphalia prioritize benchtop analyzers with multispectral imaging arrays for high-throughput renal diagnostic workflows. EU Medical Device Regulation imposes clinical evidence requirements for software-as-a-medical-device urine analysis platforms, compelling manufacturers to front-load prospective validation studies. Baden-Württemberg's precision engineering base supplies electrode substrates to electrochemical sensor manufacturers.
Japan
Aging demographics and chronic kidney disease prevalence in Tokyo and Osaka metropolitan areas drive inpatient monitoring investments for automated renal diagnostics. PMDA's Sakigake fast-track designation accelerates review timelines for AI-diagnostic urine monitoring systems. Nagoya's medical device manufacturing corridor concentrates production of cloud-connected fluid balance platforms.
United Kingdom
Integrated care systems in London and the Southeast consolidate vendor relationships for connected urinary output sensors across multiple acute care facilities. MHRA alignment with EU MDR clinical data requirements extends validation timelines for algorithm-driven diagnostic outputs. Cambridge's life sciences cluster incubates startups developing spectroscopic detection methods for point-of-care settings.
China
Tier-3 hospital upgrades in the Yangtze River Delta and Pearl River Delta regions expand procurement of electrochemical sensor arrays for creatinine monitoring. NMPA regulatory pathways for AI-enhanced medical devices impose clinical trial requirements comparable to FDA standards. Shenzhen's electronics manufacturing ecosystem produces disposable electrode substrates at scale for global device makers.
Urine Monitoring Systems Market Competitive Landscape
Dialysis-integrated conglomerates and critical care monitoring specialists split the market between bundled renal therapy platforms and modular ICU workflow extensions. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates leveraging existing hospital relationships, renal therapy pure-plays with captive nephrology clinic distribution, and sensor-technology specialists miniaturizing electrochemical detection for point-of-care deployment. Dominant competitive moves include strategic bundling of hardware with predictive maintenance contracts and geographic expansion through notified body pre-certification in priority regulatory jurisdictions.
Among diversified medtech conglomerates, Baxter International Inc. and Medtronic plc exemplify contrasting ecosystem strategies, with the former anchoring its position through dialysis infrastructure integration and the latter extending critical care monitoring architectures into automated urine analysis modules. Fresenius Medical Care occupies a distinct tier as a renal therapy pure-play with captive distribution across Western European nephrology networks. These three entities represent the primary competitive anchors shaping procurement negotiations and service-level agreement structures in hospital procurement departments.
| Leading Market Players |
|---|
| Accuryn Medical |
| Becton Dickinson and Company |
| Cardinal Health |
| F. Hoffmann-La Roche Ltd |
| FIZE Medical |
| RenalSense |
| Baxter International Inc. |
| Fresenius Medical Care |
| Medtronic plc |
| Others |
Value Network & Pricing Analysis
Single-source dependency on East Asian electrode substrate manufacturers determines both pricing tier spreads and supply chain shape, compressing margins for device makers while elevating predictive maintenance contracts as margin recovery vehicles. FDA 510(k) clearance timelines and EU MDR clinical evidence requirements add regulatory chokepoint costs that stratify hardware pricing across certification tiers.
Pricing Analysis
Predictive maintenance and remote calibration subscriptions now drive lifetime value in connected urine monitoring hardware, with three-tier pricing structure across premium, standard, and economy levels separating enterprise service level agreements from per-procedure contracts and basic equipment sales. Price differentiation rests on certification tier—FDA-cleared AI-diagnostic modules command premiums over CE-marked equivalents—and vertical integration depth, with dialysis-conglomerate bundling offsetting hardware margin pressure. Cost compression in the standard tier is intensifying because United States integrated delivery networks unbundle after-sales service from capital acquisition. Home care direct-to-consumer channels exhibit highest price sensitivity, while German hospital laboratories demonstrate lowest elasticity for multispectral analyzer procurement.
Supply Chain Analysis
Electrode substrate feedstock draws from precision engineering clusters in Baden-Württemberg, semiconductor-grade manufacturing corridors in Nagoya, and electronics ecosystems in Shenzhen. Raw material dependencies center on noble metal coatings for electrochemical sensors, polymer substrates for disposable catheter arrays, and optical-grade glass for spectroscopic detection modules. Single-source vulnerability concentrates in East Asian electrode manufacturing during logistics disruptions. Distribution runs through captive nephrology clinic networks in Western Europe, hospital procurement consortiums in United States integrated delivery networks, and direct-to-consumer e-commerce channels for Bluetooth-enabled dipstick readers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Urine monitoring systems occupy an early-cycle expansion phase, with ambulatory surgery center adoption of continuous output tracking and home diabetes self-management penetration providing durable tailwinds through the projection horizon.
For Market Incumbents: Entrench market position by embedding predictive analytics into base hardware contracts and securing notified body pre-certification across priority regulatory jurisdictions. Blood-based renal biomarker panels from centralized laboratories threaten diagnostic budget allocation, necessitating backward integration into disposable electrode manufacturing to defend cost position. Capacity addition in Nagoya's medical device corridor and investment in Sakigake fast-track evidence packages constitute priority defensive levers. For New Entrants and Emerging Players: United States home care channels present underpenetrated white space where CMS coding gaps delay incumbent capital allocation and Bluetooth-enabled dipstick readers bypass traditional procurement gatekeepers. Western European nephrology clinic captive distribution networks offer second entry vector through fluid balance platform bundling with dialysis services. Direct-to-consumer go-to-market angles leveraging diabetes self-management apps and pharmacy retail partnerships accelerate initial traction. For Investors and Strategic Acquirers: FDA 510(k) clearance for AI-enhanced urinalysis devices reshapes the acquisition landscape by compressing commercialization timelines for sensor-integrated platforms and elevating software-as-a-medical-device capabilities as valuation drivers. Long-term viability across the analysis window favors targets with dual regulatory track records in United States and EU jurisdictions, demonstrated hospital procurement relationships, and electrochemical miniaturization IP. The signal to watch is PMDA Sakigake designation velocity for comparable AI-diagnostic systems as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI-Enhanced Device | Accelerates time-to-market for sensor-integrated systems targeting renal function tracking. |
| CE Marking Pathway Under EU MDR | Front-loads clinical evidence requirements for software-as-a-medical-device urine analysis platforms. |
| Hospital System Partnership | Secures enterprise-wide service level agreements with United States integrated delivery networks. |
| Software Companion Development | Enables Bluetooth telemetry integration for real-time fluid balance tracking in ambulatory settings. |
| Reimbursement Strategy | Addresses CMS coding gaps for remote urine monitoring to unlock hospital capital allocation. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hospital procurement managers, biomedical engineering directors, nephrology clinic administrators, and GPO contracts specialists; and secondary validation through FDA 510(k) filings, EU MDR notified body submission databases, hospital procurement records, and CMS reimbursement coding guidance. Bottom-up and top-down triangulation cross-checked manufacturer shipment data against end-user installation records across acute care and ambulatory settings.
Forecast inputs considered electrochemical sensor miniaturization curves, ambulatory surgery center expansion trajectories, and regulatory clearance velocity across FDA, EU MDR, and PMDA jurisdictions. Segmentation dimensions modeled include product type hierarchy, end-user procurement authority structures, detection modality technology tiers, and clinical application reimbursement clarity. CAGRs derived from installed base turnover rates and replacement cycle compression in analyzer categories, with wearable device adoption curves calibrated against enhanced recovery protocol penetration in United States outpatient facilities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by dialysis-integrated conglomerates into standalone sensor markets or sensor-technology specialists into full-platform offerings would shift outcomes beyond modeled ranges. Cross-checking against PMDA Sakigake approval velocity and United States CMS remote monitoring coding developments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
North America Patient Monitoring Market
Patient Monitoring
MRI Pulse Oximeters Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
North America Remote Patient Monitoring Systems Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
Asia-Pacific Patient Monitoring Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
Non-Invasive Respiratory Monitoring Market