
 North America Patient Monitoring Market | 2026-2036
North America Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Patient Monitoring Market Analytics
Modular sensor-to-platform architecture is decoupling hardware procurement from software subscription decisions across acute care settings. Medtronic leverages its vertically integrated sensor manufacturing to control component costs for implantable cardiac monitors. Koninklijke Philips N.V. anchors its North American position through bedside monitor deployments tied to enterprise-wide informatics contracts. Masimo Corporation differentiates via proprietary pulse oximetry algorithms that sustain premium positioning in anesthesia and critical care workflows.
Patient monitoring encompasses the continuous or intermittent acquisition, transmission, and display of physiological parameters including electrocardiographic waveforms, pulse oximetry values, respiratory rates, and invasive pressure measurements, typically sampled at 125-500 Hz for diagnostic-grade resolution and transmitted through wired or radio-frequency telemetry links to central nursing stations or cloud-hosted dashboards. The primary purpose is enabling early detection of clinical deterioration, reducing emergency response times, and supporting resource allocation decisions in settings ranging from operating rooms to home environments. Wearable devices and remote monitoring systems represent the fastest-expanding product categories as health systems seek to extend observation windows beyond traditional facility walls without proportional bed-day cost increases. Cloud-based solutions command growing attention from procurement committees because recurring subscription models shift capital expenditure profiles and enable faster cybersecurity patch cycles than on-premise architectures.
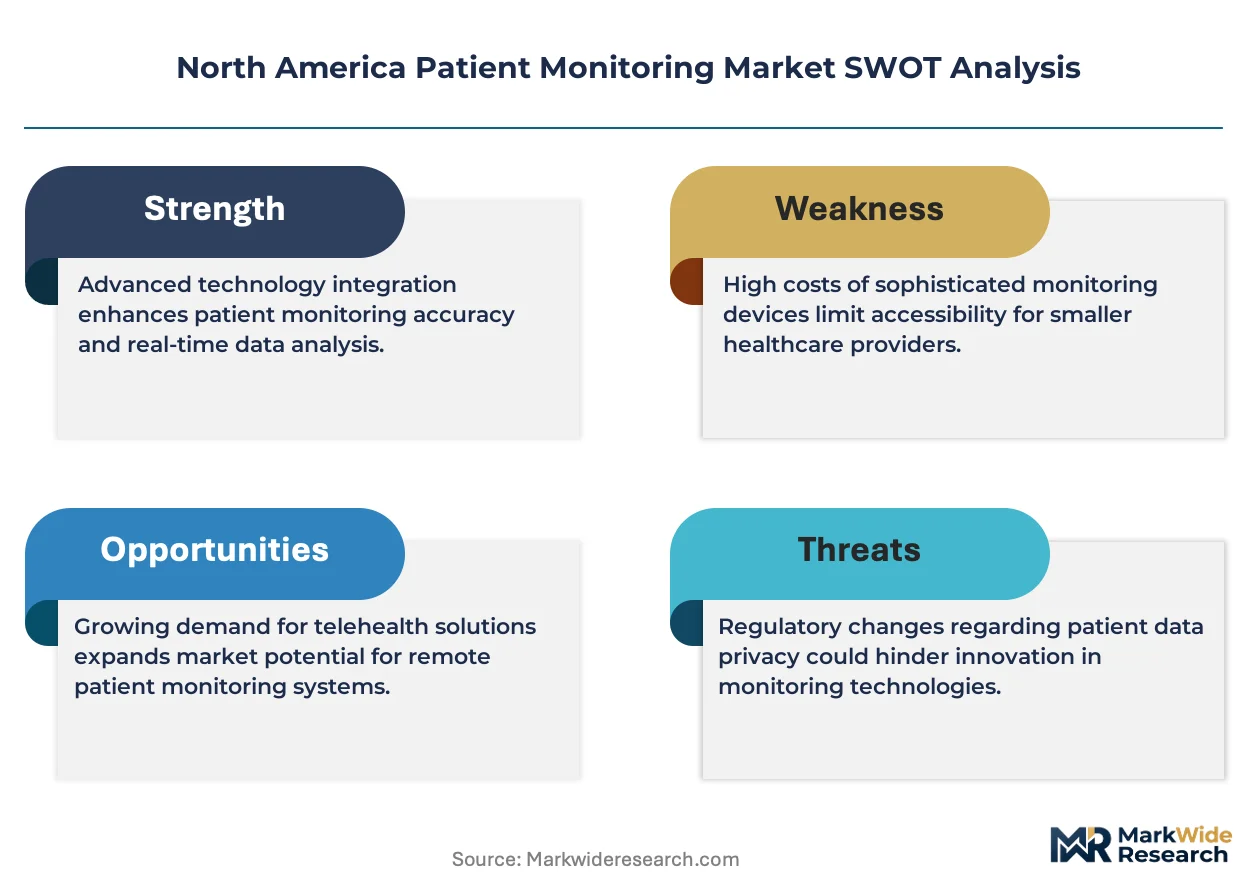
FDA premarket notification requirements under 21 CFR Part 870 for cardiovascular monitoring devices and evolving HIPAA Security Rule enforcement for cloud-hosted protected health information jointly elevate compliance spending for new entrants. The Federal Communications Commission governs wireless spectrum allocation for medical telemetry, constraining device transmission protocols in hospital-dense metropolitan zones. Stakeholders must weigh interoperability mandates against proprietary data architectures when selecting platforms that will operate across multi-state health system footprints.
Market Dynamics
The FDA's 21 CFR Part 870 premarket notification pathway for cardiovascular monitoring devices is compressing product launch timelines while elevating validation spending for cloud-connected platforms, forcing vendors to front-load compliance infrastructure before revenue generation begins.
Growth Catalysts
- Post-acute telemetry expansion:Hospital systems across Texas and California are extending continuous monitoring beyond ICU walls into step-down units and emergency departments, creating pull-through demand for wearable sensors and centralized dashboard platforms.
- HIPAA Security Rule enforcement:HHS Office for Civil Rights audits of cloud-hosted protected health information are accelerating procurement of cybersecurity-hardened architectures among integrated delivery networks.
- FCC spectrum allocation:Wireless medical telemetry service protections in hospital-dense metropolitan zones enable reliable radio-frequency transmission for ambulatory surgical centers and freestanding emergency facilities.
Market Restraints
- Semiconductor supply concentration:Custom ASICs for signal processing in implantable cardiac monitors face fabrication bottlenecks concentrated among Taiwan-based foundries, extending lead times for Medtronic and Abbott device divisions.
- Interoperability friction:Proprietary data architectures from bedside monitor incumbents resist HL7 FHIR integration, forcing health systems into costly middleware deployments or single-vendor lock-in.
- Substitution by consumer wearables:Apple Watch and Fitbit devices with irregular rhythm notifications capture low-acuity monitoring demand outside reimbursed clinical workflows, compressing addressable market for prescription-grade ambulatory ECG.
Strategic Opportunities
- Rural health network penetration:Critical access hospitals across Montana, North Dakota, and Alaska remain underpenetrated for enterprise telemetry platforms, presenting white-space expansion for vendors with simplified deployment models.
- AI-enabled predictive algorithms:FDA breakthrough device designation pathways for machine learning-based deterioration prediction are opening reimbursement discussions with CMS for algorithm-as-a-service billing codes.
- Ambulatory surgical center chains:Texas-based ASC operators are consolidating purchasing for disposable pulse oximetry sensors and capnography modules, creating channel entry points for mid-tier manufacturers.
Industry Challenges
- Biomedical engineering talent scarcity:Health systems struggle to recruit engineers capable of maintaining hybrid cloud-on-premise architectures, particularly in secondary markets outside Boston, San Francisco, and Minneapolis medical device clusters.
- Legacy device integration complexity:Decades-old RS-232 and proprietary serial protocols in existing bedside monitors resist API-layer abstraction, forcing expensive rip-and-replace cycles or brittle adapter hardware.
- Software validation timelines:FDA software-as-a-medical-device guidance requires 510(k) resubmission for each machine learning model retraining, compressing development velocity for adaptive algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Patient Monitoring Market |
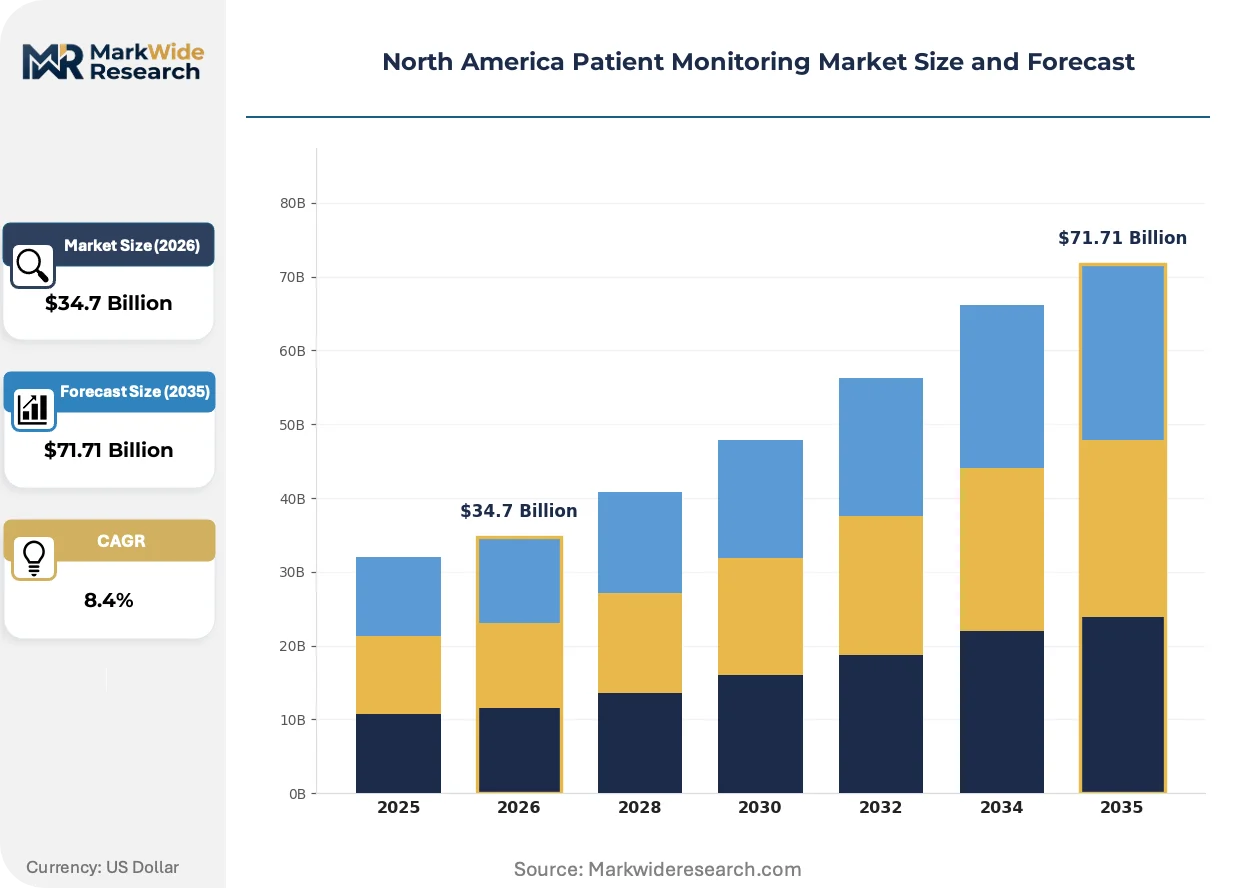
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $71.71 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Bedside Monitors, Implantable Monitors, Remote Monitoring Systems Technology: Digital Telemetry, Analog Telemetry, Wireless Technology, Cloud-Based Solutions End User: Hospitals, Home Care, Rehabilitation Centers, Long-Term Care Facilities Application: Cardiac Monitoring, Respiratory Monitoring, Fetal Monitoring, Neurological Monitoring |
| Companies Covered | Medtronic, Koninklijke Philips N.V., GE Healthcare, Siemens Healthineers, Abbott Laboratories, Masimo Corporation, Boston Scientific, Nihon Kohden Corporation, Hill-Rom Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Patient Monitoring Market Evolving Landscape
Sensor miniaturization and edge computing architectures are collapsing the physical footprint of diagnostic-grade monitoring while expanding viable deployment settings from operating rooms to patient homes.
Photoplethysmography arrays with multi-wavelength LED configurations are absorbing functions previously requiring separate pulse oximetry, capnography, and respiratory impedance modules into single wearable patches. Ambulatory surgical centers in Florida and Arizona are adopting these consolidated sensors for post-operative monitoring to reduce nursing labor intensity. The technology is absorbing capital expenditure from discrete device categories into subscription-managed platform contracts.
FDA draft guidance on predetermined change control plans for machine learning-enabled devices is creating regulatory infrastructure for continuous algorithm improvement without repeated 510(k) submissions. Manufacturers must pre-specify performance monitoring protocols and modification boundaries during initial authorization. Cardiac monitoring vendors with FDA-cleared deterioration prediction algorithms are responding by restructuring quality management systems around real-world performance surveillance.
Health system procurement committees are consolidating vendor relationships around enterprise informatics contracts that bundle bedside monitors, cloud telemetry, and predictive analytics under single-source agreements. This behavior is displacing point-solution purchasing for individual nursing units. The concentration is most visible among California's Kaiser Permanente and Sutter Health networks, where standardization across 30-plus hospitals creates volume leverage for multi-year platform commitments.
North America Patient Monitoring Market Segmentation
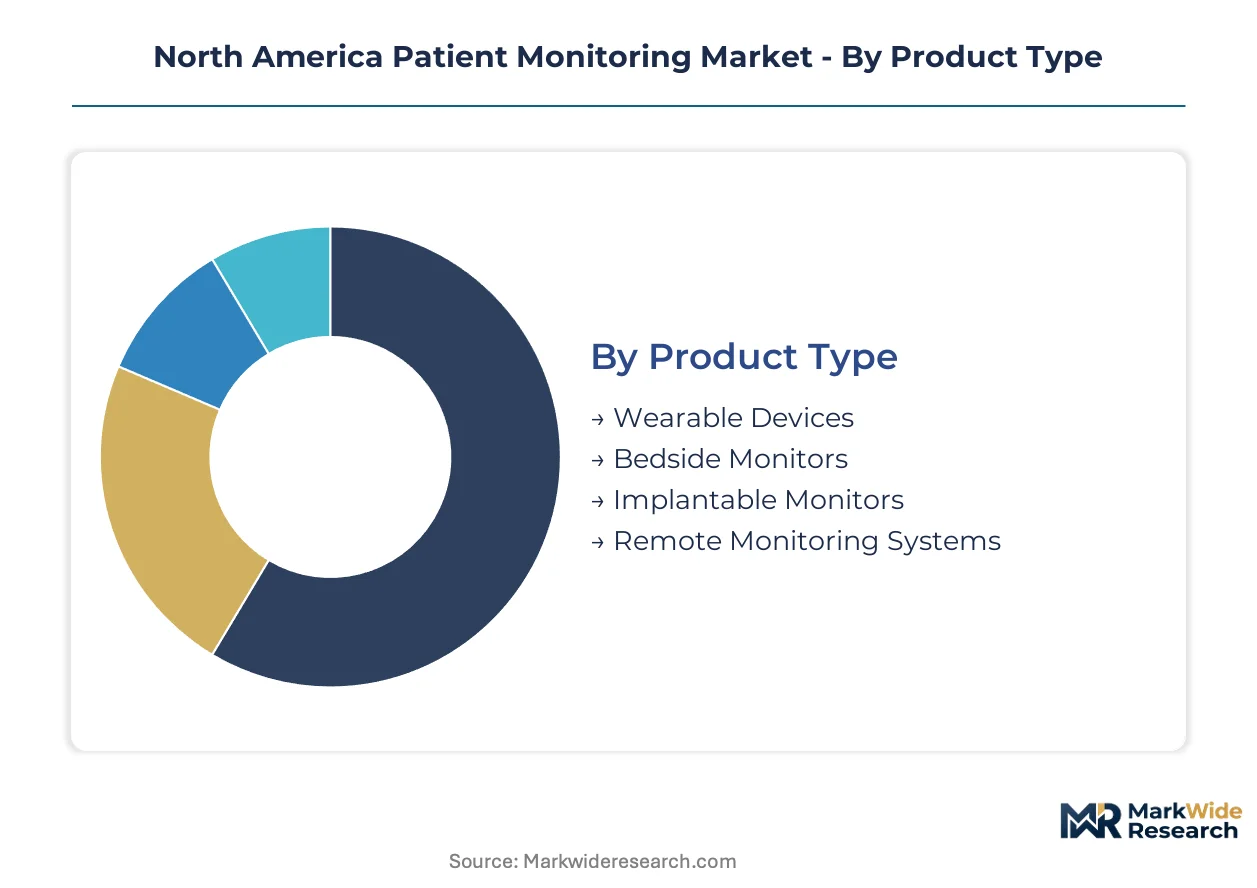
Patient monitoring segmentation reveals divergent margin profiles across hardware ownership models and software delivery architectures. Procurement committees weigh capital expenditure against recurring subscription commitments differently across acute care versus ambulatory settings.
Product Type:
Wearable Devices command premium pricing per monitored patient-day while Bedside Monitors anchor enterprise contract value through hardware refresh cycles.
- Wearable Devices:Photoplethysmography patches and multi-sensor wristbands enable ambulatory telemetry outside facility walls. Kaiser Permanente and Sutter Health networks in California are consolidating post-acute monitoring around disposable patch platforms to extend observation windows without proportional bed-day cost increases.
- Bedside Monitors:Multi-parameter units sampling ECG, SpO2, and invasive pressures at 125-500 Hz resolution remain the revenue anchor for enterprise informatics contracts. Texas ASC chains and Florida hospital systems prioritize these for OR and ICU standardization, though procurement is shifting toward subscription-managed platform models.
- Implantable Monitors:Loop recorders and insertable cardiac monitors face ASIC fabrication bottlenecks concentrated among Taiwan-based foundries.
- Remote Monitoring Systems:Cloud-hosted dashboards with centralized alarm management serve rural critical access hospitals across Montana and Alaska.
Today's leader: Bedside Monitors. Tomorrow's challenger: Wearable Devices.
Technology:
Cloud-Based Solutions are capturing procurement attention through cybersecurity-hardened architectures while Wireless Technology enables ambulatory deployment in FCC-protected spectrum zones.
- Cloud-Based Solutions:HIPAA-compliant hosting with automated patch cycles shifts capital expenditure profiles toward operational expenditure. HHS Office for Civil Rights audits are accelerating adoption among integrated delivery networks seeking to avoid penalty exposure.
- Wireless Technology:Radio-frequency medical telemetry service devices operate in protected spectrum allocations within hospital-dense metropolitan zones. Texas freestanding emergency facilities and Arizona ASCs leverage this for reliable ambulatory transmission without wired infrastructure.
- Digital Telemetry:Packet-switched data transmission with encryption protocols supports enterprise-scale central nursing station integration.
- Analog Telemetry:Legacy amplitude-modulated transmission persists in older hospital infrastructure requiring rip-and-replace avoidance.
Cloud-Based Solutions are climbing the fastest as procurement committees prioritize cybersecurity compliance and operational expenditure flexibility.
End User:
Hospitals dominate contract value through enterprise-wide standardization while Home Care represents the steepest expansion trajectory as reimbursement shifts toward remote patient monitoring codes.
- Hospitals:Acute care systems across California and Texas consolidate vendor relationships around multi-year platform commitments spanning bedside monitors, cloud telemetry, and predictive analytics. Standardization across 30-plus hospital networks creates volume leverage for procurement committees.
- Home Care:CMS reimbursement pathways for remote physiologic monitoring are enabling post-discharge observation for cardiac and respiratory patients. Medicare Advantage plans in Florida and Arizona are driving adoption to reduce readmission penalties.
- Rehabilitation Centers:Step-down facilities require intermediate-acuity monitoring with simplified nursing workflows.
- Long-Term Care Facilities:Skilled nursing facilities face staffing constraints that favor automated deterioration detection over continuous human observation.
Hospitals retain pricing power through volume concentration. Home Care is gaining share fastest as reimbursement infrastructure matures.
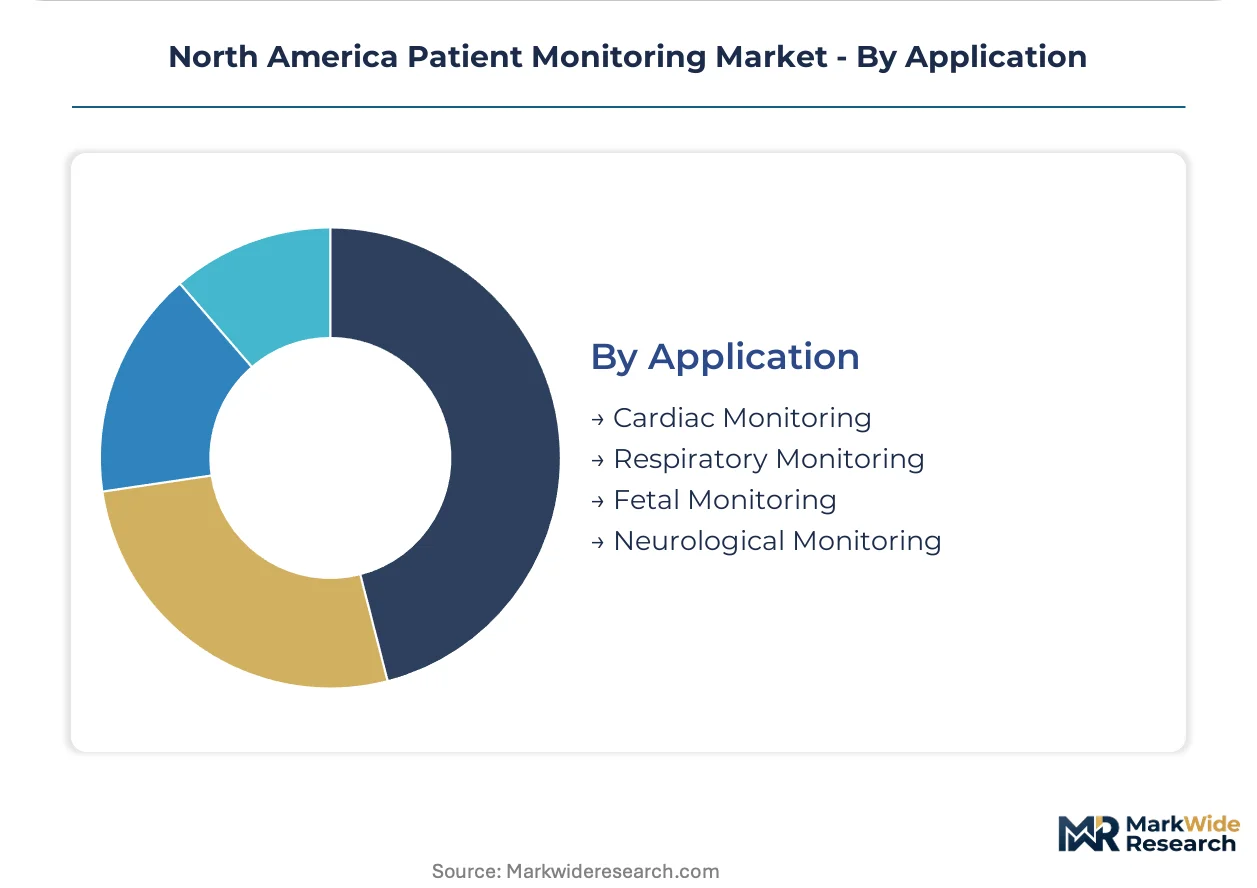
Application:
Cardiac Monitoring anchors installed base value through implantable and ambulatory ECG devices while Neurological Monitoring commands the highest per-procedure pricing in critical care workflows.
- Cardiac Monitoring:Continuous ECG telemetry with arrhythmia detection algorithms represents the largest installed base across acute care settings. FDA 510(k) pathways for machine learning-enabled deterioration prediction are opening algorithm-as-a-service billing discussions with CMS.
- Neurological Monitoring:Intracranial pressure and electroencephalography systems serve neurocritical care units with the highest per-patient monitoring costs. Boston and San Francisco medical device clusters concentrate engineering talent for these specialized applications.
- Respiratory Monitoring:Capnography and respiratory impedance modules consolidate into multi-wavelength photoplethysmography arrays for post-operative surveillance.
- Fetal Monitoring:Intrapartum cardiotocography systems face replacement pressure from wireless patch alternatives in labor and delivery units.
Cardiac Monitoring holds the deepest installed base. Neurological Monitoring offers the steepest margin expansion for vendors with specialized engineering capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient monitoring technology first achieved commercial scale in the United States during the 1960s with the development of intensive care telemetry systems at academic medical centers. This historical foundation established the US as the primary demand center for enterprise-grade monitoring platforms. The North American market now concentrates procurement authority within integrated health networks spanning major metropolitan corridors.
United States
Kaiser Permanente and Sutter Health networks in California are consolidating post-acute monitoring around disposable patch platforms to extend observation windows without proportional bed-day cost increases. FDA 21 CFR Part 870 premarket notification requirements compress product launch timelines while elevating validation spending for cloud-connected platforms. Texas-based ambulatory surgical center chains are driving demand for disposable pulse oximetry sensors and capnography modules.
California
Integrated health networks across the San Francisco Bay Area and Los Angeles Basin are standardizing enterprise informatics contracts that bundle bedside monitors, cloud telemetry, and predictive analytics under multi-year platform commitments. HHS Office for Civil Rights audits of cloud-hosted protected health information accelerate procurement of cybersecurity-hardened architectures. The state's medical device engineering talent concentrates in San Diego and Silicon Valley clusters.
Texas
Freestanding emergency facilities and ambulatory surgical center chains in Houston and Dallas-Fort Worth leverage FCC-protected wireless medical telemetry service spectrum for reliable ambulatory transmission without wired infrastructure. Post-acute telemetry expansion into step-down units and emergency departments creates pull-through demand for wearable sensors and centralized dashboard platforms. Rural critical access hospitals in West Texas remain underpenetrated for enterprise telemetry platforms.
Canada
Health Canada medical device licensing requirements for cardiovascular monitoring equipment align with FDA validation standards, enabling cross-border platform deployments from US vendors. Provincial health authorities in Ontario and Quebec are piloting remote patient monitoring reimbursement pathways for post-discharge cardiac observation. Toronto and Vancouver medical device clusters concentrate engineering talent for cloud-hosted telemetry integration.
North America Patient Monitoring Market Competitive Landscape
Premium-margin players sit above commodity-margin players across algorithm sophistication and enterprise contract scale. The vendor base organizes into three tiers: vertically integrated sensor manufacturers controlling component costs, enterprise informatics platforms anchoring multi-hospital standardization, and specialized algorithm developers commanding per-procedure pricing in anesthesia and critical care workflows. Dominant competitive moves include enterprise-wide platform consolidation contracts and FDA breakthrough device designation pursuit for machine learning-enabled deterioration prediction.
Within the vertically integrated tier, Medtronic anchors positions through captive manufacturing of implantable cardiac monitor components. Koninklijke Philips N.V. exemplifies the enterprise informatics archetype through bedside monitor deployments tied to multi-year health network agreements. Masimo Corporation occupies a specialist position via proprietary pulse oximetry algorithms that sustain premium positioning in high-acuity clinical workflows.
| Leading Market Players |
|---|
| Medtronic |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Siemens Healthineers |
| Abbott Laboratories |
| Masimo Corporation |
| Boston Scientific |
| Nihon Kohden Corporation |
| Hill-Rom Holdings |
| Others |
Value Network & Pricing Analysis
Silicon wafer spot prices and rare earth oxide indices cascade through North American patient monitoring supply chains, compressing margins for hardware manufacturers while elevating subscription premiums for cybersecurity-hardened cloud platforms. Procurement committees in California and Texas health systems now weight component cost transparency against recurring SaaS commitments when standardizing enterprise telemetry contracts.
Pricing Analysis
Subscription-managed platform contracts with three-tier pricing structure across premium, standard, and economy levels now dominate enterprise procurement, with differentiation anchored in FDA 510(k) clearance tier and algorithm sophistication rather than hardware specifications alone. Cost compression in standard-tier bedside monitors stems from Taiwan-based ASIC fabrication bottlenecks, while premium positioning for AI-enabled deterioration prediction algorithms remains insulated from price erosion. Critical access hospitals in Montana and Alaska exhibit highest price sensitivity due to constrained capital budgets, whereas integrated delivery networks in California demonstrate lowest sensitivity through multi-year volume commitments.
Supply Chain Analysis
FDA 21 CFR Part 870 qualification and ISO 13485 certification gating constrains supplier pools for cardiovascular monitoring components, with fabrication concentrated in Taiwan for custom signal-processing ASICs, Malaysia for sensor assembly, and Mexico for final device integration. Raw material dependencies center on silicon wafers, indium tin oxide for display panels, and lithium-ion cells for wearable power systems. Single-source vulnerability in Taiwan-based foundry capacity represents the dominant structural risk, with distribution running through health system GPO contracts and direct-to-hospital logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American patient monitoring functions as a regulatory compounder, with FDA software-as-a-medical-device guidance and evolving HIPAA Security Rule enforcement continuously elevating compliance spending that entrenches incumbent positions while raising barriers for new entrants.
For Market Incumbents: Deepen enterprise informatics platform consolidation by bundling bedside monitors, cloud telemetry, and predictive analytics under multi-year commitments that resist point-solution displacement. Expand backward integration into sensor manufacturing to mitigate Taiwan foundry concentration risk, while restructuring quality management systems around FDA predetermined change control plans for continuous algorithm improvement without repeated 510(k) submissions. For New Entrants and Emerging Players: Direct-to-ASC digital sales channels offer the most penetrable route for mid-tier manufacturers seeking entry without health system GPO exclusion. Rural critical access hospitals across Montana, North Dakota, and Alaska remain underpenetrated for simplified deployment models, while Texas-based ambulatory surgical center chains present consolidated purchasing entry points for disposable pulse oximetry and capnography modules through subscription-based sensor-as-a-service positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized algorithm developers commanding per-procedure pricing in anesthesia and critical care workflows, particularly those pursuing FDA breakthrough device designation for machine learning-enabled deterioration prediction. Long-term viability over the coming decade hinges on reimbursement infrastructure maturation for algorithm-as-a-service billing codes. The signal to watch is CMS coverage determination for predictive analytics in remote patient monitoring codes.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for ML-Enabled Deterioration Prediction | Breakthrough device designation opens CMS reimbursement discussions for algorithm-as-a-service billing codes. |
| Hospital System Partnership for Enterprise Telemetry | Multi-year platform commitments across 30-plus hospital networks create volume leverage and vendor lock-in. |
| Software Companion Development for Wearable Patches | Photoplethysmography arrays with edge computing architectures collapse physical footprint while expanding deployment settings. |
| Reimbursement Strategy for Remote Patient Monitoring | Medicare Advantage plans in Florida and Arizona drive adoption to reduce readmission penalties through CMS pathway navigation. |
| CE Marking Pathway for Cross-Border Expansion | Health Canada alignment with FDA validation standards enables platform deployments from US vendors into Ontario and Quebec. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and FDA regulatory affairs specialists with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and FCC spectrum allocation documentation. Bottom-up demand modeling from individual health system deployments triangulated against top-down market sizing from vendor revenue disclosures.
Segment-weighted forecasting applied differential growth assumptions across product type, technology architecture, end-user setting, and application area throughout the projection horizon. CAGRs derived from regression analysis of historical penetration rates against reimbursement infrastructure maturity and regulatory approval timelines, with specific inputs including HIPAA Security Rule enforcement intensity and FDA software-as-a-medical-device guidance implementation pace.
Semiconductor supply disruption, FDA guidance revision, and CMS reimbursement code expansion are the dominant revision risks that could materially alter trajectory assumptions. A model refresh is warranted upon material change in FDA predetermined change control plan finalization or Taiwan foundry capacity allocation policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Mobile Heart Monitoring Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
South America Fetal and Neonatal Monitoring Market
Patient Monitoring
Global Body Temperature Monitoring Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
Lung Monitoring Devices Market
Patient Monitoring
Global Consumer Healthcare Sensor Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
Fetal and Neonatal Heart Monitor Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
Home Care Monitoring and Diagnostics Market
Patient Monitoring
China ICU Patient Monitor Market