
 Oman Blood Glucose Monitoring Market | 2026-2036
Oman Blood Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Blood Glucose Monitoring Market Insights
Aftermarket consumable revenue is reshaping profitability structures across the Oman Blood Glucose Monitoring landscape. Abbott Diabetes Care leverages extensive testing strip supply agreements with public hospital networks. Roche Diabetes Care anchors its position through certified diabetes educator partnerships in Muscat and Salalah. LifeScan IP Holdings LLC competes via pharmacy-centric distribution that reaches secondary cities beyond the capital region.
Blood glucose monitoring encompasses electrochemical biosensor systems that measure interstitial or capillary glucose concentrations through enzyme-mediated reactions, typically employing glucose oxidase or glucose dehydrogenase chemistry on disposable test strips. Continuous glucose monitors dominate technology-led spending as flash glucose monitoring systems replace conventional fingerstick routines among insulin-dependent patients in Oman. Self-monitoring devices retain volume leadership in absolute unit terms but face margin compression from government tender pricing. The home care end user segment captures the fastest structural expansion as telemedicine protocols endorsed by the Ministry of Health shift routine diabetes management out of hospital settings.
The Ministry of Health and the country's national pharmaceutical regulator enforce device registration requirements that align with Gulf Cooperation Council harmonized standards for in vitro diagnostic medical devices. MOHAP standards for glucose meter accuracy and strip lot consistency shape procurement criteria for public sector tenders, effectively filtering market access for new entrants. Stakeholders must monitor how Oman's forthcoming mandatory health insurance expansion alters out-of-pocket spending thresholds for premium monitoring technologies versus basic self-testing kits.
Market Dynamics
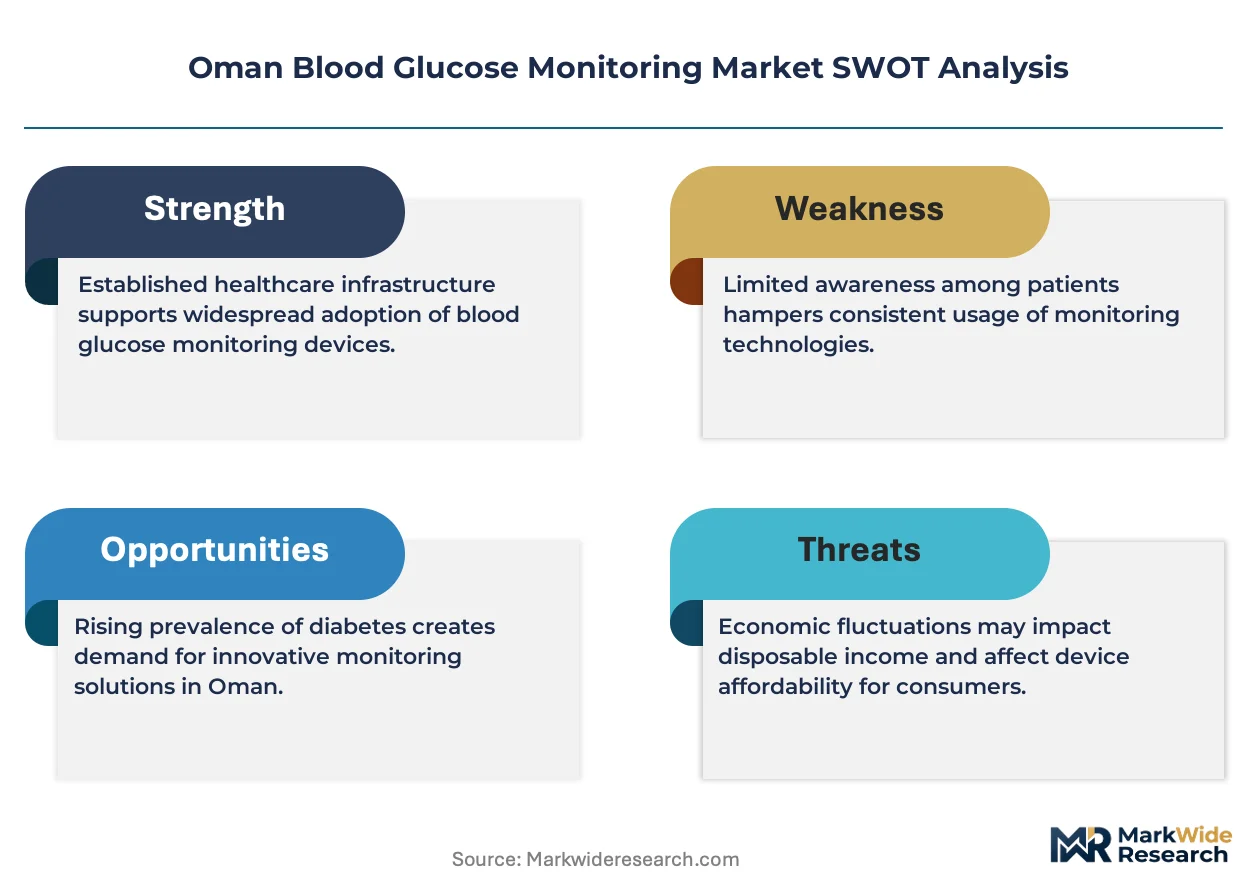
The Ministry of Health's mandatory health insurance expansion is compressing out-of-pocket spending thresholds and forcing tiered product positioning across Oman's blood glucose monitoring landscape. This structural force is accelerating vendor consolidation around certified diabetes educator networks and public hospital procurement channels.
Growth Catalysts
- MOH screening protocols:The Ministry of Health's national diabetes screening programs are expanding reimbursement coverage for continuous glucose monitors across public hospital networks. This policy shift pulls insulin-dependent patients toward flash glucose monitoring systems.
- Telemedicine protocols:Ministry-endorsed remote diabetes management frameworks are shifting routine monitoring out of hospital settings into home care environments. Specialist endocrinology services in Muscat are piloting integrated remote monitoring platforms.
- Coastal governorate clustering:Demand concentrates in Muscat and surrounding coastal regions where specialist endocrinology infrastructure and pharmacy distribution density enable rapid continuous monitor adoption.
Market Restraints
- Test strip cost volatility:Electrochemical biosensor chemistry inputs face pricing pressure from enzyme supply concentration. Disposable test strip margins compress under government tender pricing regimes.
- GCC harmonized standards:Gulf Cooperation Council device registration requirements create regulatory friction for new entrants seeking public sector procurement access. MOHAP accuracy and lot consistency standards filter market participation.
- Capillary testing substitution:Flash glucose monitoring systems are displacing conventional fingerstick routines among insulin-dependent patient segments. Self-monitoring blood glucose devices face volume erosion in premium patient cohorts.
Strategic Opportunities
- Secondary city pharmacy networks:Distribution beyond Muscat and Salalah into interior governorates remains underpenetrated. Pharmacy-centric models can capture Type 2 diabetes management in regions lacking specialist endocrinology access.
- Insurance mandate tailwinds:Oman's forthcoming mandatory health insurance expansion creates reimbursement pathways for premium continuous monitoring technologies. Policy frameworks will elevate device categories previously restricted to out-of-pocket purchase.
- Certified educator partnerships:Diabetes educator certification programs anchor patient training and device onboarding. Vendor alliances with Ministry-recognized educator networks secure preferred positioning in public hospital discharge protocols.
Industry Challenges
- Integrated platform complexity:Telemedicine-enabled monitoring requires seamless data flow between patient devices, clinician dashboards, and electronic health record systems. Legacy hospital IT infrastructure in regional facilities creates integration friction.
- Certified diabetes educator scarcity:Patient onboarding for continuous monitor systems depends on trained educator availability. Ministry-recognized certification programs face capacity constraints relative to expanding device deployment targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Blood Glucose Monitoring Market |
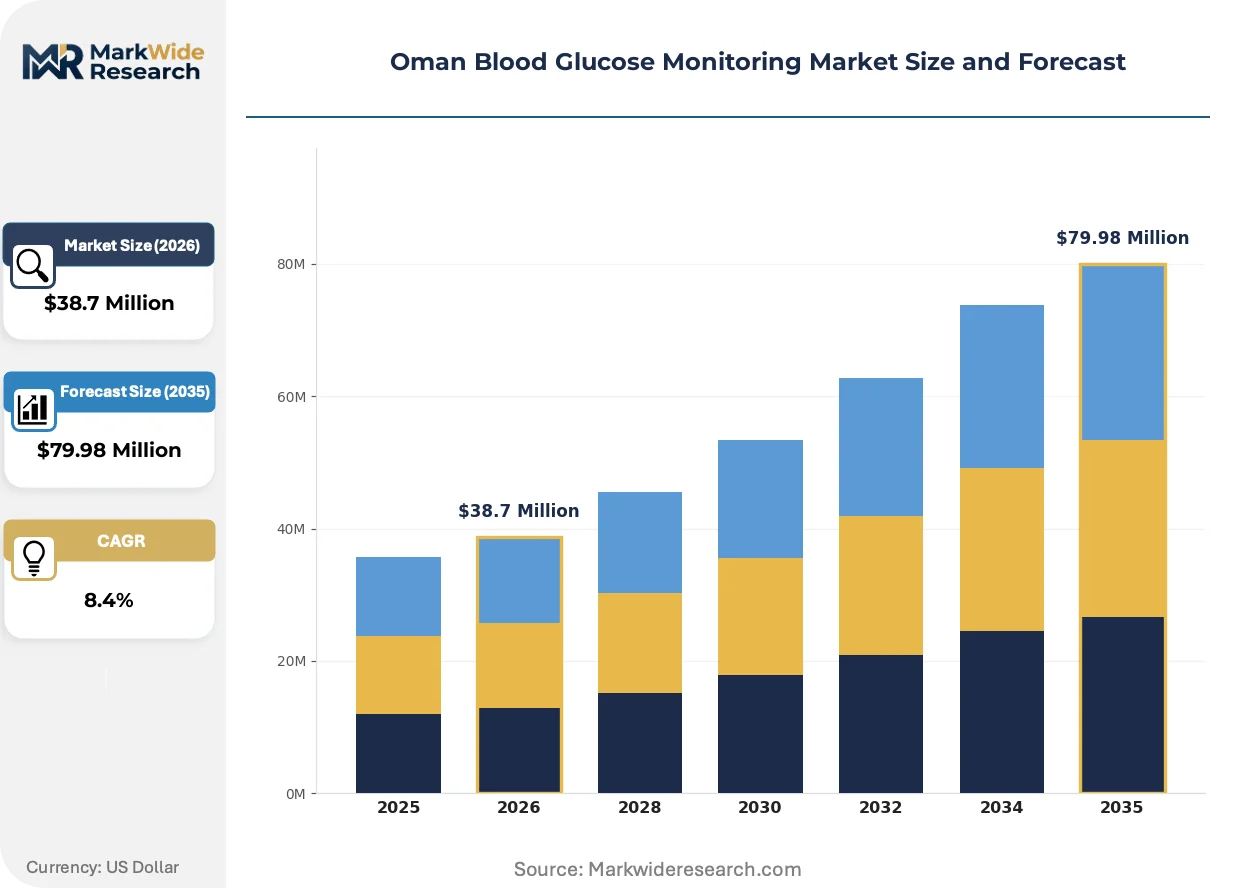
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $79.98 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Monitoring Devices, Continuous Glucose Monitors, Testing Strips, Lancets End User: Home Care, Hospitals, Clinics, Pharmacies Technology: Wireless, Bluetooth, Flash Glucose Monitoring, Non-Invasive Distribution Channel: Online, Offline, Direct Sales, Medical Supply Stores |
| Companies Covered | Abbott Diabetes Care, Roche Diabetes Care, Medtronic PLC, Dexcom Inc., LifeScan IP Holdings LLC, Ascensia Diabetes Care, Senseonics Inc., ARKRAY Inc., Bionime Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Blood Glucose Monitoring Market Trends and Innovations
Flash glucose monitoring technology is digitizing patient data workflows and compressing the role of conventional fingerstick testing in Omani diabetes management. This transformation is reshaping vendor competitive positioning around integrated software platforms rather than hardware alone.
Continuous glucose monitoring systems employing factory-calibrated interstitial sensors are digitizing how insulin-dependent patients track glycemic patterns. Endocrinology specialists in Muscat's public hospital networks are adopting these platforms for Type 1 and intensive insulin-requiring Type 2 patients. The technology is digitizing patient-clinician communication channels and enabling remote titration decisions that previously required in-person consultation.
MOHAP standards for glucose meter accuracy and strip lot consistency are tightening procurement criteria across Oman's public health system. These regulations are filtering tender participation toward vendors with established Gulf Cooperation Council registration and local quality assurance infrastructure. Continuous monitor manufacturers with integrated software validation are responding by aligning product submissions with harmonized GCC in vitro diagnostic medical device requirements.
Home care end users are consolidating device selection authority previously dispersed across hospital discharge planners and retail pharmacy staff. Ministry of Health telemedicine protocols are empowering patients to initiate monitoring technology discussions with specialists directly. This behavioral shift is most visible in Muscat governorate households with established internet connectivity and smartphone penetration.
Oman Blood Glucose Monitoring Market Segmentation
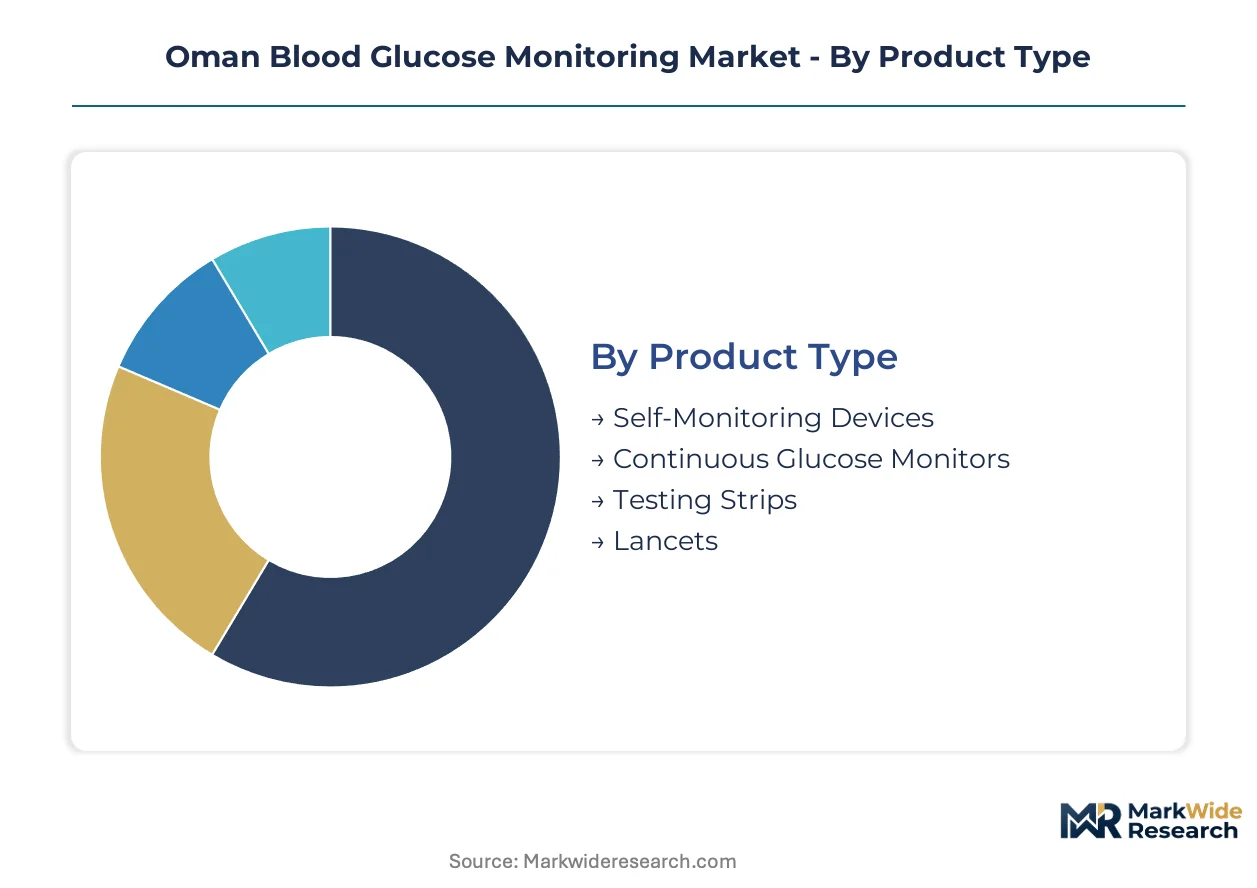
Segmentation in Oman's blood glucose monitoring landscape reveals how technology adoption, patient location, and procurement channel shape vendor strategy. Understanding these divisions exposes where flash glucose systems displace legacy fingerstick methods and how telemedicine protocols redirect spending toward home-based solutions.
Product Type:
Product categories span the full spectrum from disposable consumables to capital-intensive sensor platforms, with reimbursement status determining access tier for Omani patients.
- Self-Monitoring Devices:Electrochemical biosensor meters employing glucose oxidase chemistry on capillary blood samples dominate unit volume across Oman's public hospital tenders. Government procurement compresses margins while maintaining broad patient access in secondary cities lacking continuous monitor infrastructure.
- Continuous Glucose Monitors:Factory-calibrated interstitial sensors with factory-set algorithms eliminate routine fingerstick calibration for insulin-dependent patients. Demand concentrates in Muscat governorate households where Ministry of Health telemedicine protocols enable remote specialist oversight of glycemic patterns.
- Testing Strips:Disposable enzyme-mediated biosensor strips generate recurring revenue through public hospital supply agreements and pharmacy retail channels.
- Lancets:Single-use skin penetration devices accompany self-monitoring systems in bundled procurement packages.
The dominant share belongs to Self-Monitoring Devices, while Continuous Glucose Monitors is closing the gap fastest.
End User:
Patient location and care setting determine device sophistication, with Ministry of Health protocols accelerating the shift from institutional to domiciliary monitoring.
- Home Care:Patients managing Type 2 diabetes in residential settings drive structural expansion as telemedicine frameworks endorsed by the Ministry of Health relocate routine glycemic surveillance from outpatient clinics. Smartphone-connected devices enable direct data transmission to Muscat-based endocrinology specialists.
- Hospitals:Public hospital networks in Muscat, Sohar, and Salalah anchor procurement volume for inpatient glycemic management and discharge planning.
- Clinics:Primary health care centers across coastal governorates provide initial diabetes screening and basic monitoring device distribution.
- Pharmacies:Retail pharmacy networks extend device access into interior regions lacking specialist endocrinology infrastructure.
Home Care captures the steepest expansion trajectory, though Hospitals retain the largest installed base of monitoring equipment.
Technology:
Connectivity and measurement methodology differentiate patient experience, with wireless data transmission becoming standard for insulin-intensive cohorts.
- Wireless:Radiofrequency-enabled monitors transmit glucose readings to clinician dashboards without patient-initiated data entry. Integration with Ministry of Health electronic health record systems accelerates adoption in Muscat's public hospital discharge protocols.
- Bluetooth:Short-range wireless protocols pair patient smartphones with monitoring hardware for automated logging and caregiver alerts.
- Flash Glucose Monitoring:Factory-calibrated interstitial sensors enable on-demand glucose scanning without fingerstick confirmation, displacing conventional self-monitoring among insulin-dependent patients in Oman's coastal urban centers.
- Non-Invasive:Optical and transdermal measurement technologies remain pre-commercial in Omani regulatory pathways, with MOHAP accuracy standards filtering market entry.
Flash Glucose Monitoring commands premium positioning, while Wireless connectivity is gaining share fastest among new device installations.
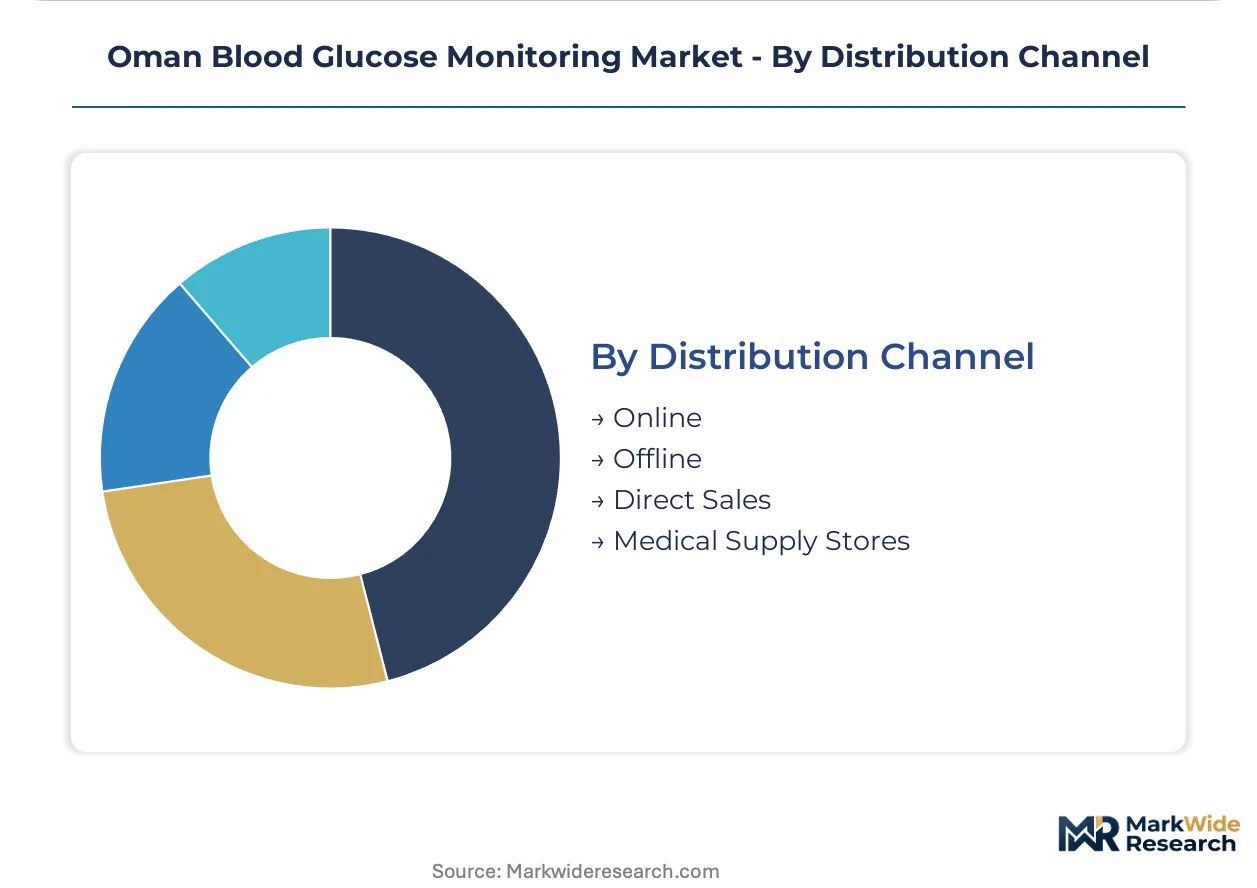
Distribution Channel:
Channel structure reflects patient digital literacy, insurance coverage status, and geographic proximity to medical infrastructure.
- Online:E-commerce platforms and direct-to-patient portals serve smartphone-enabled households in Muscat with subscription-based continuous monitor resupply. Digital channels bypass pharmacy density constraints in interior governorates.
- Offline:Brick-and-mortar pharmacy and medical supply retail maintains volume leadership through government tender fulfillment and cash-patient segments.
- Direct Sales:Vendor field forces engage public hospital procurement committees and certified diabetes educator networks for institutional contracts.
- Medical Supply Stores:Specialized durable medical equipment distributors serve home care patients with insurance-mandated documentation requirements.
Offline channels retain the dominant transaction volume, though Online is expanding most quickly among urban insulin-dependent patient cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Oman's governorates. Muscat households show willingness to absorb premium continuous monitor costs, while interior regions remain highly price-sensitive to basic self-testing kits.
Muscat Governorate
Specialist endocrinology density and smartphone penetration drive flash glucose monitor adoption. Ministry of Health telemedicine protocols enable remote clinician oversight of insulin-dependent patients. Royal Hospital and Sultan Qaboos University Hospital anchor procurement volume for integrated monitoring platforms.
Dhofar Governorate
Salalah's growing diabetes prevalence creates demand for pharmacy-distributed self-monitoring devices. MOHAP standards filter tender participation toward vendors with established quality assurance infrastructure. Certified diabetes educator partnerships at Sultan Qaboos Hospital support patient onboarding for continuous systems.
Al Batinah Governorate
Sohar's industrial workforce generates employer-sponsored screening programs expanding basic meter access. Ministry of Health screening protocols extend reimbursement coverage to public health centers. Distribution through retail pharmacy networks compensates for limited specialist endocrinology presence.
Ad Dakhiliyah Governorate
Nizwa's agricultural communities exhibit high Type 2 diabetes prevalence with constrained specialist access. Government tender pricing compresses margins on self-monitoring strips while maintaining broad patient access. Telemedicine links to Muscat-based specialists enable remote management of complex cases.
Ash Sharqiyah Governorate
Sur and Ibra households rely on pharmacy-centric distribution for routine diabetes management. Insurance mandate expansion will elevate device categories previously restricted to out-of-pocket purchase. Coastal location enables faster supply chain resupply from Muscat distribution hubs.
Oman Blood Glucose Monitoring Market Competitive Landscape
Capability concentration sits with multinational diagnostic specialists; scale advantage sits with diversified medical technology conglomerates. The vendor base organizes around three strategic archetypes: integrated diabetes care platforms, consumables-focused suppliers, and sensor technology innovators. Dominant competitive moves include certified educator network partnerships and public hospital procurement channel consolidation.
Within the integrated platform tier, Abbott Diabetes Care and Roche Diabetes Care exemplify multinational specialists leveraging Gulf Cooperation Council registration and local quality infrastructure. Dexcom Inc. occupies a position among sensor-focused innovators. These three entities represent distinct competitive vectors—consumables supply agreements, educator certification alliances, and factory-calibrated interstitial technology—without any single approach commanding definitive market control.
| Leading Market Players |
|---|
| Abbott Diabetes Care |
| Roche Diabetes Care |
| Medtronic PLC |
| Dexcom Inc. |
| LifeScan IP Holdings LLC |
| Ascensia Diabetes Care |
| Senseonics Inc. |
| ARKRAY Inc. |
| Bionime Corporation |
| Others |
Pricing and Supply Chain Analysis
Muscat's concentrated medical device import and distribution infrastructure channels pricing power toward established vendors with Gulf Cooperation Council registration and Ministry of Health tender access. The coastal governorate's role as Oman's primary entry point for electrochemical biosensor consumables and continuous glucose monitoring hardware concentrates procurement leverage among multinational diagnostic specialists serving public hospital networks.
Pricing Analysis
Aftermarket consumable revenue from disposable testing strips and sensor resupply drives lifetime customer value across Oman's blood glucose monitoring landscape. Three-tier pricing structure across premium continuous monitors, standard self-monitoring systems, and economy fingerstick meters reflects insurance coverage tiers and patient out-of-pocket capacity. Cost compression in the self-monitoring segment intensifies because government tender pricing caps strip margins, while premium continuous monitor pricing holds firmer among insulin-dependent cohorts with reimbursement access. Cash-paying patients in interior governorates exhibit highest price sensitivity, whereas smartphone-enabled households in Muscat absorb premium device costs.
Supply Chain Analysis
Export control restrictions on advanced sensor manufacturing equipment limit domestic production capacity for continuous glucose monitoring systems in Oman. Device assembly and consumable manufacturing concentrate in the United States, Germany, and Malaysia, with final distribution resting on cold-chain logistics for enzyme-stabilized testing strips. Raw material dependencies span glucose oxidase biochemistry substrates, medical-grade polymers for sensor housings, and precision electronics for wireless transmission modules. Single-source vulnerability in factory-calibrated sensor supply creates resupply risk for flash glucose monitoring patients. Distribution runs through Ministry of Health central procurement for public hospitals, pharmacy wholesale networks for retail channels, and direct-to-patient subscription platforms for urban continuous monitor users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around Ministry of Health procurement committees and expanding mandatory health insurance frameworks, compressing vendor margins while elevating reimbursement-dependent purchasing authority.
For Market Incumbents: Build certified diabetes educator network moats to secure preferred positioning in public hospital discharge protocols and patient onboarding pathways. Deepen backward integration into enzyme-stabilized strip manufacturing to defend margin position against government tender compression. Anchor procurement channel control through multi-year supply agreements with Royal Hospital and Sultan Qaboos University Hospital networks. Flash glucose monitoring substitution threatens self-monitoring device volumes; counter through integrated software platform investments that lock clinicians into data dashboard ecosystems. For New Entrants and Emerging Players: Secondary city pharmacy networks in Nizwa, Sur, and Ibra represent the most penetrable entry point for basic self-monitoring devices where specialist endocrinology access remains constrained. Telemedicine-enabled home care segments in Muscat households with established smartphone penetration offer white-space opportunity for subscription-based continuous monitor resupply models. Pursue go-to-market alignment with Ministry of Health screening protocol expansion to capture newly diagnosed Type 2 diabetes patients entering reimbursement-covered device pathways. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with consumable resupply infrastructure and certified educator training capacity. Long-term viability over the five-to-ten year horizon hinges on software platform integration with Ministry of Health electronic health record systems rather than hardware differentiation alone. Acquisition targets should demonstrate established GCC registration, local quality assurance infrastructure, and existing public hospital tender participation. Monitor flash glucose monitoring reimbursement expansion signals as inflection indicator for continuous monitor market acceleration versus self-monitoring device erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures preferred vendor status in Ministry of Health discharge protocols and procurement tenders. |
| Software Companion Development | Enables seamless glucose data integration with Muscat-based specialist telemedicine platforms. |
| Reimbursement Strategy | Aligns device submissions with mandatory health insurance expansion and MOH screening protocols. |
| CE Marking Pathway | Accelerates Gulf Cooperation Council harmonized registration for public sector market access. |
| Certified Educator Network Investment | Anchors patient onboarding capacity for continuous monitor adoption in insulin-dependent cohorts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted to construct a grounded view of Oman's blood glucose monitoring landscape. Primary interviews engaged hospital procurement managers at Royal Hospital and Sultan Qaboos University Hospital, certified diabetes educators operating in Muscat and Salalah, pharmacy distribution channel heads, and biomedical engineers managing device integration with Ministry of Health electronic health record systems. Secondary validation drew from MOHAP device registration databases, Gulf Cooperation Council harmonized standards documentation, public hospital tender records, and Ministry of Health telemedicine protocol publications. Bottom-up patient population estimates triangulated against top-down healthcare expenditure flows.
Calibration against historical adoption curves for flash glucose monitoring technology and self-monitoring device procurement volumes anchored the analytical framework across the projection horizon. Segmentation modeling incorporated product type tiers, end user settings, connectivity technology, and distribution channel structure. CAGRs were derived from fitted growth curves adjusted for insurance mandate expansion timing and telemedicine protocol rollout phases. Forecast inputs included diabetes prevalence projections, specialist endocrinology capacity expansion plans, and smartphone penetration thresholds for remote monitoring platform adoption.
Practitioners should monitor Ministry of Health reimbursement policy revisions and mandatory health insurance implementation pace for early signals of market trajectory shifts. Forecasts reflect assumptions about regulatory continuity, enzyme supply chain stability, and telemedicine infrastructure investment levels. Material shifts in GCC harmonized standards, flash glucose monitoring substitution rates, or public hospital procurement centralization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Multi-Item Patient Monitor Market
Patient Monitoring
Patient Temperature Management Systems Market
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Heart Monitoring Devices Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Asthma Monitoring Devices Market
Patient Monitoring
Remote Home Monitoring Systems Market
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
Remote Patient Monitoring System Market
Patient Monitoring
Europe Biomedical Sensors Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
Global Smart Pulse Oximeters Market