
 North America Paints and Coatings Market | 2026-2036
North America Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
North America Paints and Coatings Market Outlook
Low-VOC and zero-VOC specification tiers is reorganizing competitive dynamics across the North America Paints and Coatings Market. The Sherwin-Williams Company leverages its captive retail network to control distribution density in professional contractor channels. PPG Industries, Inc. anchors its position through backward integration into titanium dioxide and specialty resin production. Benjamin Moore & Co. differentiates via premium-grade architectural formulations targeted at high-end residential repaint cycles.
North America paints and coatings comprise liquid, powder, and UV-curable film-forming systems applied to substrates for protection, decoration, or functional performance, typically specified by solids content, VOC g/L limits, and dry-film thickness measured in mils. Acrylic water-based formulations lead residential decorative volumes due to ease of application and cleanup compliance, while epoxy and polyurethane chemistries concentrate in industrial maintenance where chemical resistance and abrasion tolerance command margin premiums. Powder coating adoption accelerates in automotive OEM lines as EPA VOC thresholds tighten and line-efficiency targets rise.
EPA regulations under the National Volatile Organic Compound Emission Standards for Architectural Coatings directly constrain solvent-based formulation viability, while OSHA worker exposure limits and state-level CARB rules in California compound compliance complexity for multi-jurisdictional manufacturers. NHTSA corrosion-performance standards and FAA exterior coating specifications further segment demand by end-use certification tier. Stakeholders must monitor regulatory divergence between federal thresholds and state-level California Air Resources Board mandates when allocating R&D and manufacturing footprint across the region.
Market Dynamics
EPA National Volatile Organic Compound Emission Standards are compressing solvent-based formulation viability while redirecting R&D spending toward water-borne and powder systems across the North America Paints and Coatings Market.
Growth Catalysts
- Infrastructure stimulus:Federal highway and bridge appropriations are expanding procurement of epoxy-based traffic marking and protective steel coatings across state transportation departments.
- REACH-aligned state mandates:California Air Resources Board rules are accelerating specification of zero-VOC architectural products in commercial repaint contracts.
- UV-curable chemistry:Furniture and flooring manufacturers are adopting instant-cure radiation systems to eliminate thermal drying bottlenecks in high-throughput finishing lines.
Market Restraints
- Titanium dioxide concentration:Pigment supply concentrates among three global producers, exposing North American formulators to input cost volatility and allocation risk.
- Epoxy resin technical limitation:Chalking and UV degradation constrain exterior architectural use, restricting epoxy penetration to interior industrial and marine segments.
- OSHA worker exposure friction:Isocyanate handling protocols in polyurethane spray applications are extending contractor certification timelines and raising compliance costs.
Strategic Opportunities
- Canadian Prairie provinces:Agricultural equipment and grain storage infrastructure remain underpenetrated by high-performance maintenance coatings relative to US Midwest density.
- Biobased resin convergence:Alkyd and polyurethane platforms incorporating soy- and linseed-derived polyols are capturing sustainability-specified commercial repaint contracts.
- Direct contractor platforms:Digital procurement portals are disintermediating traditional distributor layers in professional painter channels.
Industry Challenges
- Formulation chemist scarcity:Retiring expertise in solvent-to-water conversion and UV oligomer design is outpacing university pipeline output.
- Multi-jurisdictional certification lag:Navigating divergent EPA, CARB, and Health Canada PMRA approval timelines extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Paints and Coatings Market |
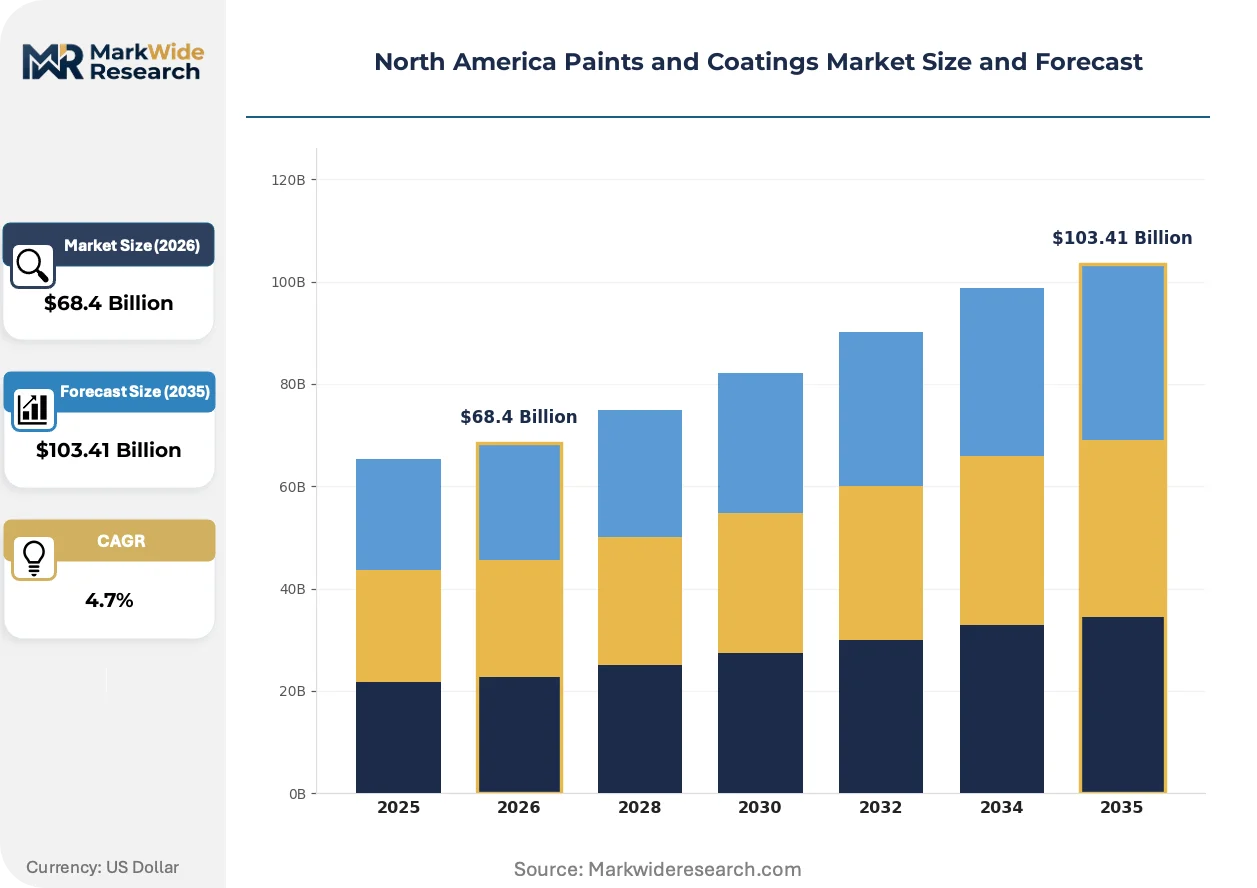
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Alkyd, Epoxy, Polyurethane End User: Construction, Automotive, Aerospace, Marine Application: Residential, Commercial, Industrial, Decorative Formulation: Water-Based, Solvent-Based, Powder Coating, UV-Cured |
| Companies Covered | Axalta Coating Systems, Behr Paint Co., The Sherwin-Williams Company, Innovative Chemical Products Group, Benjamin Moore & Co., PPG Industries, Inc., Akzo Nobel N.V., Cloverdale Paint Inc., RPM International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Paints and Coatings Market Strategic Shifts
Formulation chemistry is pivoting toward instant-cure and biobased platforms while distribution digitization restructures how professional contractors source specification-grade products across the region.
UV-LED curable coatings are miniaturizing curing equipment footprints and enabling inline finishing for heat-sensitive substrates like medium-density fiberboard and engineered flooring. Residential furniture manufacturers in the Carolina Piedmont are retrofitting spray lines with LED arrays to eliminate infrared oven capital and energy draw. This technology is miniaturizing the spatial and thermal infrastructure required for industrial-grade film formation, compressing facility upgrade costs for mid-cap wood finishers.
EPA's strengthened National Volatile Organic Compound Emission Standards for Architectural Coatings are eliminating solvent-borne alkyd viability in retail decorative channels. Formulators are accelerating water-borne urethane-alkyd hybrid development to match solvent-based block resistance and flow characteristics. Professional contractor segments in the Northeast and Mid-Atlantic are experiencing the most acute specification pressure, with municipal and institutional repaint contracts now mandating sub-50 g/L VOC ceilings.
Professional painters are consolidating purchasing through manufacturer-direct mobile applications that bypass traditional distributor markups on specification-grade architectural products. Independent painting contractors in Texas and Florida metropolitan corridors are adopting subscription replenishment models for high-rotation base and trim SKUs. This channel shift is most visible in high-volume residential repaint markets where contractor loyalty programs and volume-tier pricing are displacing counter-based distributor relationships.
North America Paints and Coatings Market Segmentation
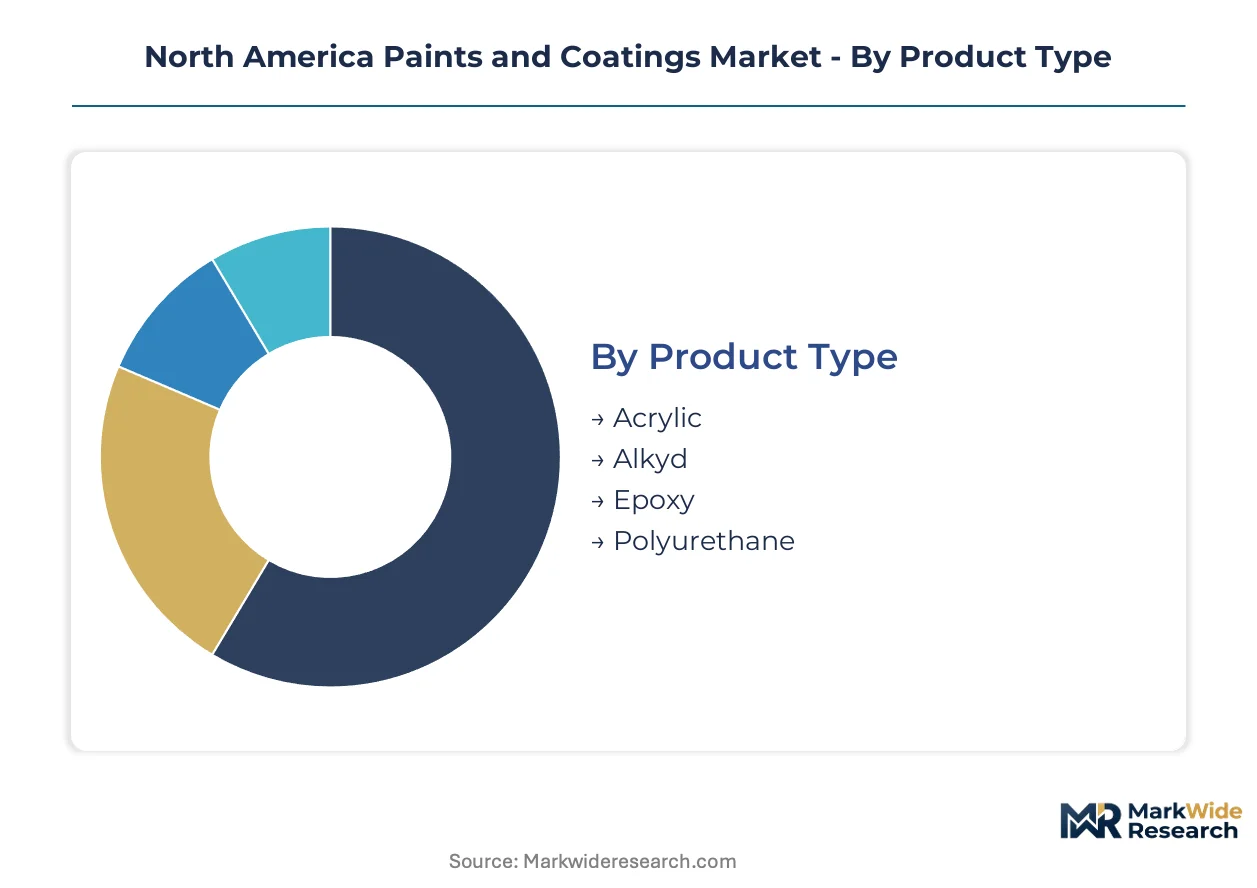
Formulation chemistry, end-use certification tiers, and application environments create distinct margin architectures across the North America Paints and Coatings Market. Specification requirements diverge sharply between architectural decorative channels and industrial protective segments, forcing portfolio segmentation that balances volume scale against technical premium capture.
Product Type:
Margin pools concentrate in polyurethane and epoxy chemistries where performance specifications command formulation premiums, while acrylic and alkyd segments compete on scale efficiency and regulatory compliance.
- Acrylic:Water-borne emulsion polymers dominate residential decorative volumes through ease of application and EPA VOC compliance. Demand clusters in Sun Belt metro corridors where new construction and repaint cycles run highest, with low-odor specifications driving contractor preference in occupied-space applications.
- Polyurethane:Two-component aliphatic systems capture premium margins in industrial maintenance and transportation OEM lines where abrasion resistance and UV stability are specified. Consumption concentrates in US Gulf Coast petrochemical facilities and Great Lakes automotive assembly plants where corrosion protection standards are most stringent.
- Alkyd:Oil-modified polyester resins retain niche demand in trim and cabinet applications where block resistance and flow characteristics exceed water-borne alternatives. CARB compliance pressure is accelerating hybrid urethane-alkyd development to preserve solvent-borne performance under sub-50 g/L ceilings.
- Epoxy:Bisphenol-A and novolac systems anchor protective coatings for marine, industrial flooring, and infrastructure steel where chemical resistance and adhesion are critical. Chalking limitations restrict exterior architectural use to interior industrial segments.
The dominant share belongs to acrylic, while polyurethane is closing the gap fastest through specification upgrades in transportation and industrial maintenance channels.
End User:
Application environments range from weather-exposed infrastructure to precision aerospace finishing, with certification complexity and performance liability creating tiered margin structures.
- Construction:Architectural coatings for new build and repaint cycles generate the highest absolute volumes, with professional contractor channels specifying low-VOC products under EPA and CARB mandates. Demand splits between residential repaint in Northeast and Mid-Atlantic metropolitan corridors and commercial new construction in Texas and Florida growth markets.
- Automotive:OEM clearcoat and basecoat systems require OEM qualification cycles lasting 24-36 months, with powder coating adoption accelerating as assembly lines target zero-VOC emissions and energy efficiency. Refinish demand concentrates in collision repair networks serving high-density urban vehicle populations.
- Marine:Antifouling and protective systems for commercial shipping and offshore platforms specify copper-biocide and silicone foul-release chemistries under EPA Vessel General Permit discharge limits. Application concentrates in Gulf Coast shipyards and Pacific Northwest fishing vessel fleets.
- Aerospace:FAA-qualified exterior coatings for commercial aviation and military platforms demand extreme UV stability, rain erosion resistance, and weight minimization. Qualification barriers limit qualified supplier pools to a handful of specification-grade formulators.
Construction holds the volume base, though automotive specification upgrades are expanding value per gallon fastest through OEM qualification requirements.
Application:
Customer procurement patterns separate specification-driven professional channels from price-sensitive retail decorative segments, with service intensity and technical support requirements shaping go-to-market economics.
- Residential:DIY and professional repaint cycles drive the highest SKU velocity, with color-matching services and contractor loyalty programs differentiating manufacturer-direct platforms from traditional distributor channels. Demand concentrates in owner-occupied housing stock across suburban expansion corridors.
- Industrial:Protective coatings for manufacturing facilities, warehouses, and processing plants require application-specific formulation support and corrosion engineering consultation. Procurement runs through specification engineers rather than purchasing departments, extending sales cycles but preserving margin premiums.
- Commercial:Institutional and office repaint contracts increasingly mandate zero-VOC products under LEED and WELL building certification frameworks, with California specifications spreading to other jurisdictions through national account standardization.
- Decorative:Specialty finishes including faux effects, metallics, and textured coatings serve high-end residential and hospitality segments where aesthetic differentiation commands price premiums independent of functional performance.
Residential captures the broadest volume footprint, while industrial applications are expanding value density fastest through protective coating specification upgrades.
Formulation:
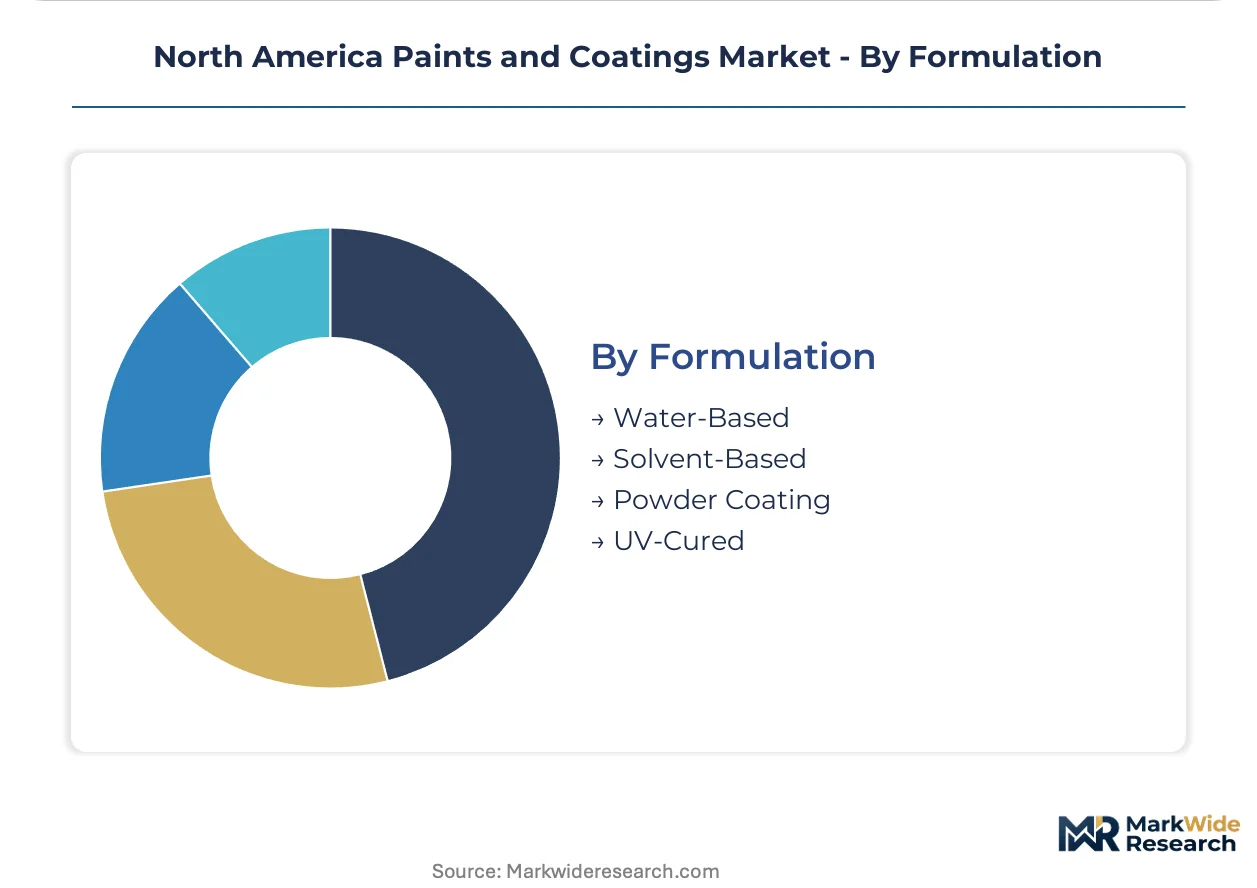
Regulatory pressure on volatile organic compound emissions is restructuring viable technology platforms, with water-borne and powder systems displacing solvent-borne volumes while UV-cured systems capture specialty high-throughput niches.
- Water-Based:Acrylic and polyurethane dispersions lead architectural decorative volumes, with formulation advances closing the performance gap to solvent-borne systems in block resistance, gloss retention, and early moisture resistance. EPA National VOC Emission Standards are accelerating specification in professional contractor channels.
- Powder Coating:Thermoset epoxy and polyester systems eliminate VOC emissions entirely while enabling single-coat coverage and near-zero waste through reclaim systems. Automotive OEM lines and appliance manufacturing are retrofitting spray booths to capture energy and regulatory compliance advantages.
- Solvent-Based:Alkyd and urethane systems retain demand in industrial maintenance and specialty applications where water-borne alternatives fail on chemical resistance or application latitude. Regulatory compression is restricting viable use cases to exempt industrial categories and geographic jurisdictions with less stringent enforcement.
- UV-Cured:Acrylate oligomer systems enable instant film formation through LED or mercury vapor radiation, eliminating thermal drying infrastructure for heat-sensitive substrates. Furniture and flooring manufacturers in the Carolina Piedmont are retrofitting lines to compress finishing cycle times and facility footprints.
Water-based formulations command the dominant position, while powder coating is gaining specification momentum fastest through automotive OEM line conversions and regulatory compliance advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional contractors in Texas and Florida growth corridors exhibit the lowest price elasticity, accepting premium formulations for speed and compliance, while Canadian Prairie agricultural equipment buyers remain highly price-sensitive, prioritizing volume procurement over performance specifications.
United States
Industrial maintenance coatings consumption clusters along the US Gulf Coast petrochemical corridor where facility corrosion protection standards are most stringent. EPA National Volatile Organic Compound Emission Standards are compressing solvent-based formulation viability while redirecting procurement toward water-borne and powder systems. The Carolina Piedmont furniture manufacturing belt is retrofitting spray lines with UV-LED curing arrays to eliminate thermal drying infrastructure.
Canada
Agricultural equipment and grain storage infrastructure in the Prairie provinces remain underpenetrated by high-performance maintenance coatings relative to US Midwest density. Health Canada PMRA approval timelines for new biocide registrations extend product launch cycles, creating regulatory friction for antifouling and protective system introductions. Ontario's manufacturing corridor around Toronto anchors automotive OEM powder coating demand as assembly lines target zero-VOC emissions.
Mexico
Automotive assembly plant expansion in Nuevo León and the Bajío Region is accelerating specification of OEM-qualified clearcoat and basecoat systems with 24-36 month qualification cycles. Mexican environmental regulations under SEMARNAT are tightening VOC thresholds in alignment with US EPA standards, forcing formulation convergence across cross-border supply chains. Querétaro's aerospace manufacturing cluster is generating qualified demand for FAA-specified exterior coatings with extreme UV stability requirements.
North America Paints and Coatings Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the North America Paints and Coatings Market. The vendor base separates into three tiers: integrated resin-to-retail conglomerates controlling captive distribution networks, specialty formulators serving specification-driven industrial channels, and regional distributors competing on logistics proximity and contractor credit terms. Dominant competitive moves include backward integration into titanium dioxide and specialty resin production, plus digital platform investments to disintermediate traditional distributor layers in professional painter channels.
Among integrated North American manufacturers, The Sherwin-Williams Company, PPG Industries, Inc., and Benjamin Moore & Co. occupy positions that exemplify divergent strategic archetypes. Sherwin-Williams represents the captive retail network model controlling distribution density in professional contractor channels. PPG anchors the backward integration archetype through in-house production of titanium dioxide and specialty resins. Benjamin Moore sits within the premium-grade formulation tier targeting high-end residential repaint cycles with specification-grade architectural products.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| Behr Paint Co. |
| The Sherwin-Williams Company |
| Innovative Chemical Products Group |
| Benjamin Moore & Co. |
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| Cloverdale Paint Inc. |
| RPM International Inc. |
| Others |
Value Chain & Pricing Dynamics
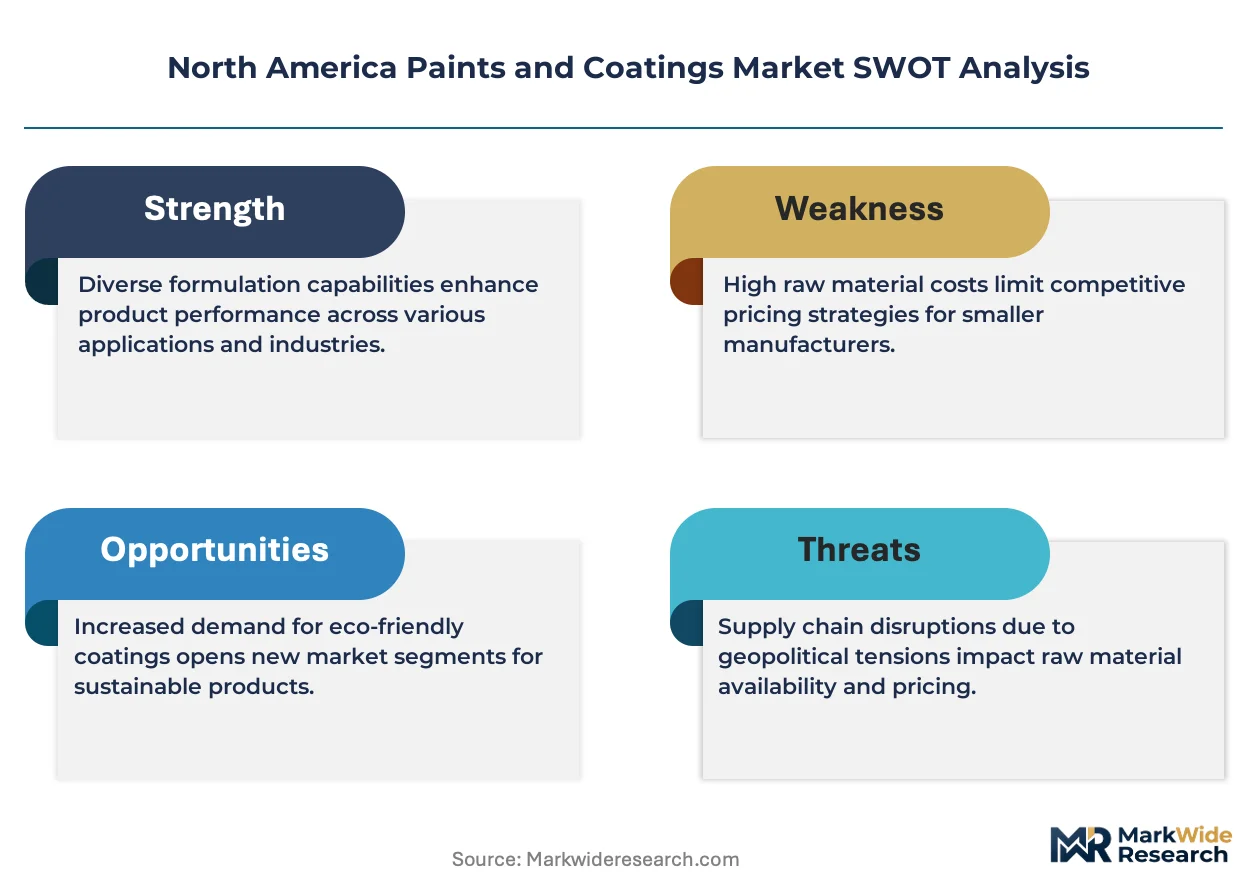
Water-borne resin substitution for solvent-borne alkyd systems is compressing formulation costs while redrawing procurement geography toward US Gulf Coast petrochemical hubs and Canadian specialty chemical corridors. This input shift simultaneously weakens titanium dioxide pricing power and elevates logistics premiums for just-in-time resin delivery to contractor channels.
Pricing Analysis
After-sales color-matching and contractor loyalty programs drive lifetime value capture across specification-grade architectural tiers. Three-tier pricing structure across premium, standard, and economy levels segments by VOC compliance grade and certification burden, with EPA sub-50 g/L mandates forcing compression in mid-tier solvent-borne offerings. Pricing pressure stems from pigment cost volatility as three global producers control titanium dioxide allocation. DIY retail segments exhibit highest price sensitivity, while professional contractors in Texas and Florida accept premium formulations for speed-to-completion.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underscores feedstock risk for epoxy resin precursors sourced from Middle Eastern petrochemical complexes. China, Germany, and the United States anchor titanium dioxide and specialty resin supply, with North American formulators drawing from German epoxy chemistry and Chinese pigment processing. Tariff exposure on imported biocides and resin intermediates elevates working capital requirements. Distribution runs through manufacturer-direct mobile platforms and traditional distributor networks serving contractor credit needs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America paints and coatings sits at an early-cycle expansion story as zero-VOC mandates penetrate commercial repaint contracts beyond California into national account specifications.
For Market Incumbents: Secure captive resin supply through backward integration into titanium dioxide and specialty polyurethane production to offset pigment allocation risk. Deepen contractor platform investments to disintermediate distributor markups before digital procurement becomes table stakes. EPA timeline compression on VOC thresholds threatens solvent-borne portfolio margins without rapid water-borne hybrid conversion. For New Entrants and Emerging Players: CARB-equivalent certification fast-tracks open penetration paths in institutional repaint segments where national accounts standardize sustainability specifications. Target Canadian Prairie agricultural equipment maintenance as an underpenetrated geography with limited incumbent technical service presence. Lead with biobased alkyd platforms incorporating soy-derived polyols to differentiate on sustainability credentials without legacy solvent-borne infrastructure. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty formulators with captive certification expertise over commodity architectural players. Long-term viability centers on regulatory navigation capabilities across EPA, CARB, and Health Canada PMRA jurisdictions. Watch for inflection in powder coating adoption rates across automotive OEM lines as zero-emission mandates tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide | Captive pigment supply insulates formulators from global allocation shocks and spot price volatility. |
| UV-LED Curing Line Retrofit | Carolina Piedmont furniture manufacturers compress thermal infrastructure capital and energy draw. |
| Direct Contractor Platform Launch | Manufacturer-direct mobile applications displace distributor markups in high-volume residential repaint. |
| Biobased Resin Platform Development | Soy- and linseed-derived polyols capture sustainability-specified commercial contracts. |
| Multi-Jurisdictional Certification Investment | Parallel EPA, CARB, and PMRA approval tracks compress 18-24 month launch cycle friction. |
Study Parameters
Initial hypotheses were tested against primary input from formulation chemists, professional painting contractors, distributor procurement managers, and automotive OEM coating engineers and refined through secondary validation. Primary fieldwork encompassed plant visits across US Gulf Coast petrochemical corridors and Carolina Piedmont furniture manufacturing clusters. Secondary sources included EPA National VOC Emission Standards filings, ACC industry shipment data, SEC 10-K disclosures from integrated manufacturers, and customs records on titanium dioxide import flows. Bottom-up volume estimates triangulated against top-down market value reconstructions.
Variance decomposition across product type, end-use certification tier, formulation technology, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory timeline assumptions. Forecast inputs incorporated EPA rulemaking schedules, automotive OEM powder coating conversion announcements, and contractor channel digital adoption curves.
Underlying assumptions cover steady-state regulatory enforcement, stable feedstock availability, and continuous UV-LED equipment cost decline, with deviation risk concentrated in titanium dioxide supply disruptions and multi-jurisdictional approval delays. Practitioners should keep alternative scenarios live as EPA VOC threshold stringency and Canadian PMRA biocide registration timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
Fire Resistant Paints Market
Paints & Coatings
Automotive OEM Coatings Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Bahrain Paints and Coatings Market
Paints & Coatings
Paint Thinner Market
Paints & Coatings
India Automotive OEM Coatings Market
Paints & Coatings
Germany Industrial Wood Coatings Market
Paints & Coatings
Saudi Arabia Architectural Paints Market
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market