
 Insulating Paints and Coatings Market | 2026-2036
Insulating Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Insulating Paints and Coatings Market Foresight
Industrial facility retrofits is recalibrating demand toward high-performance thermal barrier systems. PPG Industries leverages its industrial coating heritage to dominate specification-driven projects in energy-intensive sectors. Akzo Nobel N.V. anchors European demand through water-based innovations that meet tightening environmental standards. Jotun Group specializes in marine and protective applications where corrosion resistance and insulation converge.
Insulating paints and coatings are formulated with ceramic microspheres, aerogel dispersions, or hollow glass beads to achieve thermal conductivity values below 0.1 W/m·K, primarily serving to reduce heat transfer across building envelopes, industrial equipment, and transportation surfaces. Acrylic formulations lead residential and light commercial retrofit activity due to ease of application and compatibility with existing substrates. Epoxy systems capture industrial margin pools where chemical resistance and thermal protection must coexist in harsh operating environments. Polyurethane growth concentrates in automotive underbody and commercial roofing applications where flexibility and elongation properties prove critical.
EPA regulations in the United States restrict VOC content in architectural coatings, directly steering product development toward low-VOC and water-based technologies. REACH and the EU Green Deal in Europe mandate disclosure of hazardous substances and carbon footprint reduction, creating compliance costs that favor larger formulators with dedicated regulatory affairs capacity. Facility managers and procurement officers must monitor evolving national building codes and energy efficiency certification schemes to anticipate specification shifts that will determine competitive viability.
Market Dynamics
Industrial facility retrofits are recalibrating demand toward high-performance thermal barrier systems as energy cost pressures mount across manufacturing sectors. The convergence of tightening VOC regulations and state-backed building efficiency mandates is forcing rapid reformulation cycles among formulators.
Growth Catalysts
- REACH and EU Green Deal compliance:Tightening VOC limits across Europe push water-based system adoption, creating specification advantages for compliant formulators in industrial and architectural segments.
- China's dual carbon goals:State-backed retrofit programs accelerate building envelope upgrades, concentrating demand for ceramic microsphere and aerogel-dispersion coatings in commercial and residential construction.
- Ceramic microsphere technology:Advanced hollow ceramic formulations achieve thermal conductivity below 0.1 W/m·K, enabling specification in energy-intensive sectors previously unreachable with conventional insulation.
Market Restraints
- Titanium dioxide feedstock volatility:Price swings in TiO2, a critical pigment for reflective coatings, compress margin pools and force inventory risk onto smaller formulators without long-term supply agreements.
- Epoxy resin supply concentration:Production of high-purity epoxy precursors clusters in East Asian petrochemical corridors, exposing industrial coating manufacturers to shipping cost spikes and geopolitical friction.
- Aerogel dispersion stability:Technical limitations in shelf-life extension and application consistency restrict aerogel-based systems to premium niche applications rather than mass-market penetration.
Strategic Opportunities
- India's building code enforcement gap:Underpenetrated enforcement of Energy Conservation Building Code standards creates first-mover positioning for thermal coating specification as state-level adoption accelerates.
- Data center thermal management:Emerging application in hyperscale facility envelope insulation combines fire resistance with thermal performance, opening specification channels outside traditional construction.
- Automotive lightweighting convergence:Technology convergence of phase-change materials with spray-applied coatings enables underbody thermal management that replaces heavier insulation mats in electric vehicle platforms.
Industry Challenges
- Applicator certification bottlenecks:Compressed timelines for training spray technicians on advanced aerogel and ceramic systems delay project deployment and inflate labor costs for specification-grade work.
- Multi-substrate compatibility testing:Integration complexity with legacy building materials—concrete, aged masonry, galvanized steel—extends R&D cycles and fragments product lines across regional substrate preferences.
- Cross-border formulation registration:Divergent national chemical registries force redundant toxicology dossiers, stretching regulatory affairs capacity at mid-tier formulators attempting geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulating Paints and Coatings Market |
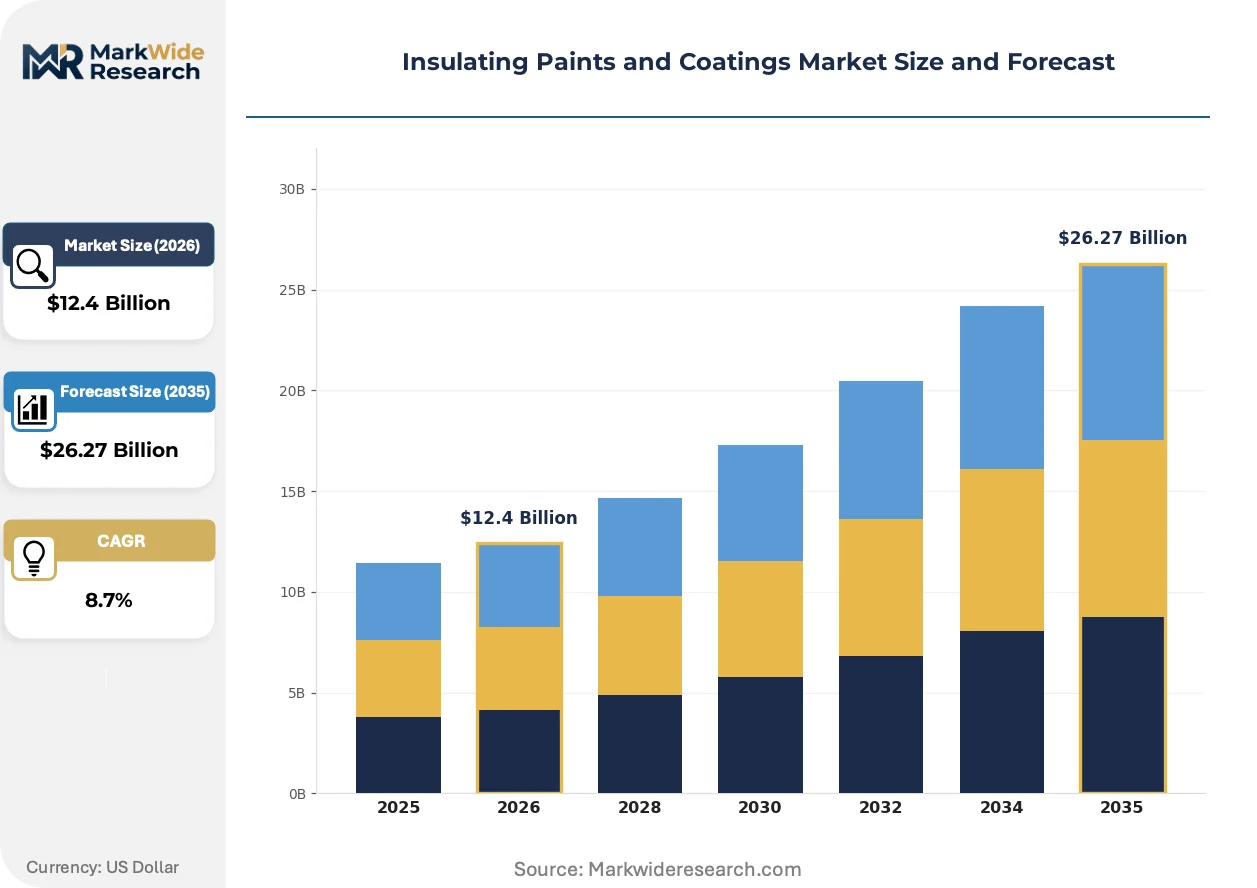
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Silicone Application: Residential, Commercial, Industrial, Automotive End User: Contractors, Manufacturers, Homeowners, Facility Managers Technology: Water-Based, Solvent-Based, High-Temperature, Low-VOC |
| Companies Covered | PPG Industries, Inc., The Sherwin-Williams Company, Akzo Nobel N.V., Nippon Paint Holdings Co., Ltd., Kansai Paint Co., Ltd., Jotun Group, Axalta Coating System, Carboline Company, Hempel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulating Paints and Coatings Market Shifts & Advancements
Spray-application robotics and AI-guided thickness monitoring are compressing installation timelines while tightening specification compliance. Formulators now compete on application technology as much as coating chemistry.
Aerogel-loaded spray systems is automating quality control in commercial roofing and industrial tank applications. Facility managers at petrochemical complexes adopt these platforms to eliminate thickness variation penalties in warranty coverage. The technology is automating specification compliance documentation that previously required manual inspection protocols.
EPA architectural coating VOC rules are tightening permissible limits on solvent-borne systems in maintenance and repair categories. Industrial users face reformulation deadlines that favor water-based epoxy and polyurethane alternatives with comparable chemical resistance. Marine and protective segments in US Gulf Coast facilities accelerate pilot programs with low-VOC thermal barrier systems to preempt enforcement actions.
Certification-driven specification now dominates procurement in European commercial construction, where Energy Performance Certificate ratings directly influence asset valuation. General contractors bundle thermal coating packages with blower-door testing guarantees, displacing commodity paint bids. Germany and Nordic markets exhibit the tightest coupling between coating specification and whole-building energy modeling.
Insulating Paints and Coatings Market Segmentation
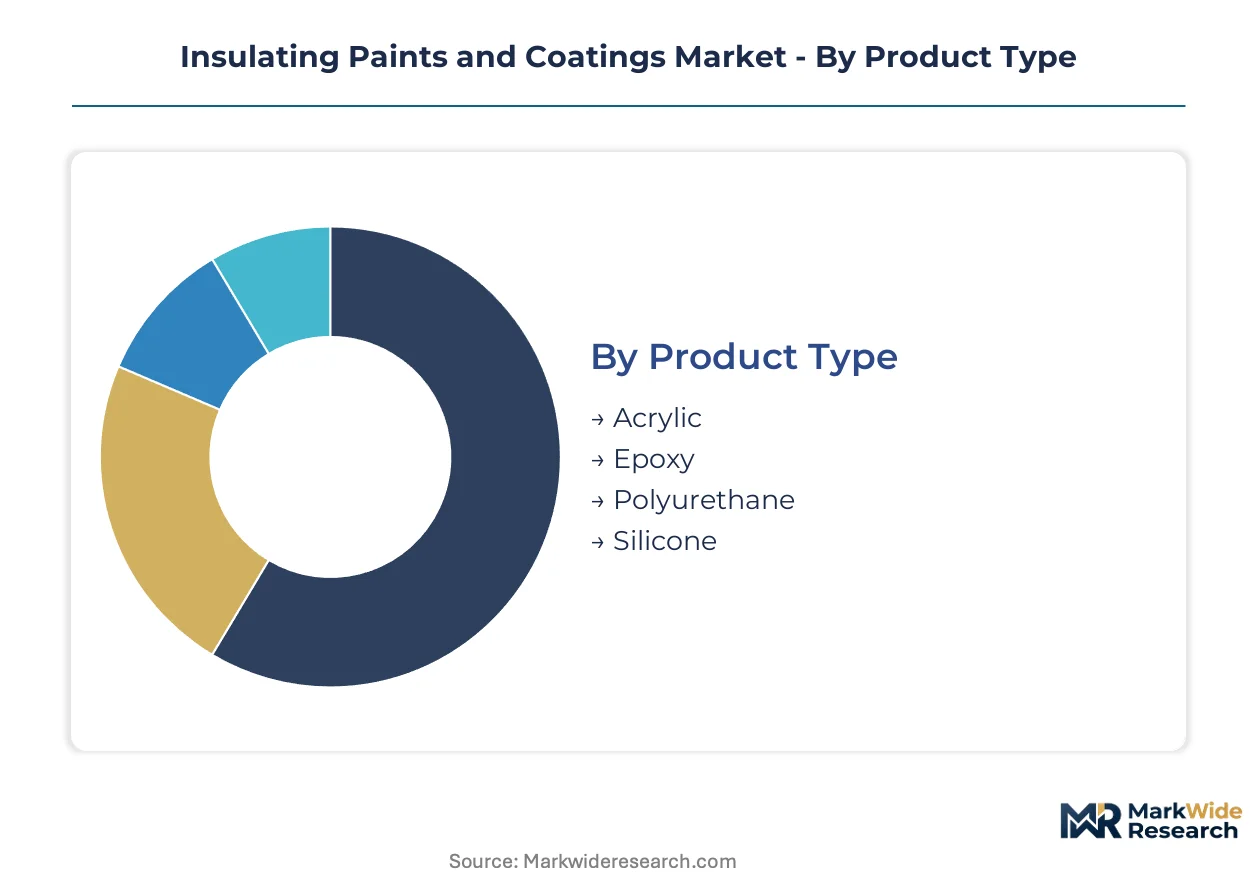
Segmentation in insulating paints and coatings reveals how formulation chemistry, application environment, and regulatory pressure intersect to determine commercial viability. Understanding these divisions exposes where specification power concentrates and where margin pools shift.
Product Type:
Ceramic microsphere loadings and resin backbone chemistry define thermal performance thresholds and substrate compatibility across architectural and industrial deployments.
- Acrylic:Water-dispersible resins loaded with hollow glass beads serve residential retrofits and light commercial envelopes where ease of roller or spray application drives contractor preference. Demand clusters in China's state-backed building efficiency programs and North American DIY renovation channels, constrained by temperature limits that exclude high-heat industrial surfaces.
- Epoxy:Two-part systems combining bisphenol-A resins with ceramic fillers achieve chemical resistance alongside thermal barriers in petrochemical tanks, processing equipment, and marine structures. Industrial facility managers in Germany's chemical corridor and US Gulf Coast refineries specify these for warranty-backed protection in corrosive environments above 120°C operating temperatures.
- Polyurethane:Aliphatic and aromatic isocyanate systems deliver elongation and flexibility for automotive underbody applications and commercial roofing membranes exposed to thermal cycling. Formulators target electric vehicle platforms where lightweighting requirements displace heavier insulation mats.
- Silicone:Inorganic polysiloxane binders withstand continuous exposure to 250°C+ surfaces in exhaust systems, industrial ovens, and aerospace components. Niche specification in high-temperature industrial zones limits volume but sustains premium pricing tiers.
Mature deployment sits with Acrylic in residential maintenance cycles. Newer deployment is concentrated in Epoxy as industrial energy audits accelerate capital retrofit schedules.
Application:
Building envelope geometry and operational duty cycles determine whether thermal coatings compete against conventional insulation or complement it in hybrid assemblies.
- Residential:Exterior wall and attic applications in single-family and multi-family structures where thin-film insulation avoids spatial penalties of batt or board systems. German Energy Performance Certificate requirements and China's dual carbon retrofit mandates are expanding specification beyond premium new construction into mass-market renovation.
- Commercial:Office facades, retail envelopes, and institutional roofing where whole-building energy modeling drives procurement decisions. General contractors in Nordic markets bundle coating packages with blower-door testing guarantees that displace commodity paint bids.
- Industrial:Processing equipment, storage tanks, and pipeline exteriors where thermal barrier coatings reduce heat loss and personnel protection hazards. Petrochemical complexes in the US Gulf Coast and Rotterdam-Antwerp corridor pilot low-VOC thermal systems to preempt EPA and REACH enforcement timelines.
- Automotive:Underbody, firewall, and battery enclosure applications where phase-change material integration enables thermal management without weight penalties. Electric vehicle platforms at scale manufacturers are validating spray-applied ceramic systems as mat replacements.
Volume leadership belongs to Commercial specification in European certificate-driven construction. Steepest expansion trajectory is emerging in Automotive as lightweighting converges with thermal performance requirements.
End User:
Procurement authority and technical specification capability separate price-sensitive commodity buyers from performance-driven premium segments.
- Contractors:Application specialists bidding on renovation and new construction projects where coating selection balances material cost against labor efficiency and callback risk. Training certification on aerogel and ceramic spray systems creates specification bottlenecks that favor established regional players.
- Manufacturers:Industrial equipment OEMs and automotive assemblers integrating thermal coatings into original design specifications. Quality documentation and lot traceability requirements filter supplier pools toward formulators with dedicated regulatory affairs capacity.
- Homeowners:DIY purchasers at retail hardware channels driven by visible energy bill reduction claims and ease of application marketing. Product liability exposure from overstated R-value claims has tightened labeling requirements under FTC guidance.
- Facility Managers:Industrial and commercial building operators with capital budget authority for energy efficiency retrofits and maintenance cycles. Energy audit findings and utility rebate programs increasingly mandate thermal coating inclusion in envelope upgrade scopes.
Price pressure concentrates on Homeowner retail channels. Margin protection is strongest with Facility Managers where energy cost documentation justifies premium formulation selection.
Technology:
Regulatory compliance timelines and application infrastructure requirements are forcing rapid platform transitions that fragment competitive positioning across geographies.
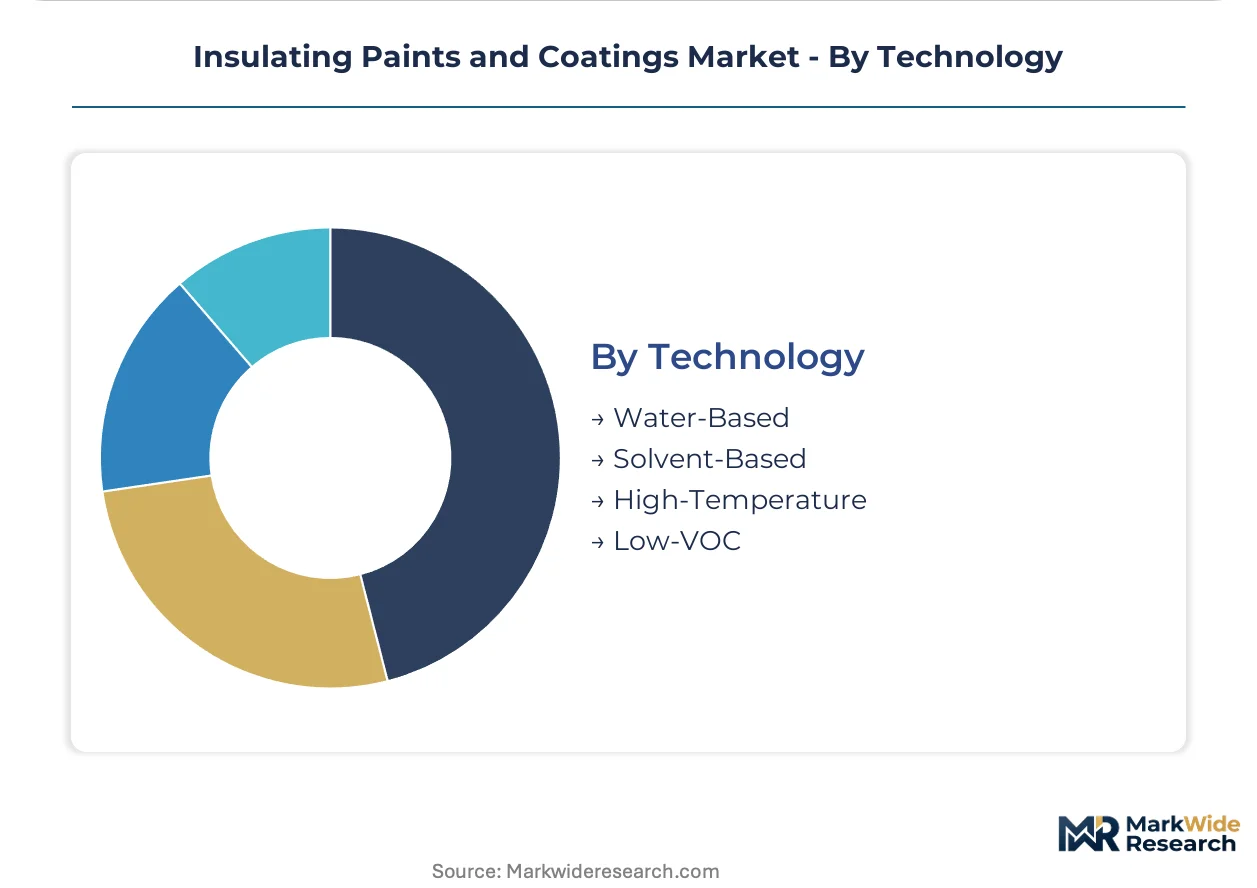
- Water-Based:Acrylic and polyurethane dispersions with VOC content below regulatory thresholds mandated by EPA architectural coating rules and REACH restrictions. European formulators anchor market position here, with German and Nordic markets exhibiting tightest coupling between water-based specification and whole-building certification.
- Solvent-Based:High-solids epoxy and alkyd systems retaining share in industrial maintenance categories where chemical resistance and substrate adhesion requirements exceed current water-based performance. Compressed reformulation deadlines in US maintenance categories are accelerating substitution.
- High-Temperature:Silicone and modified epoxy formulations rated for continuous service above 200°C in exhaust systems, industrial ovens, and processing equipment. Application requires specialized surface preparation and cure protocols that limit contractor pool.
- Low-VOC:Emerging category spanning water-based, high-solids, and exempt-solvent technologies that meet tightening limits in California SCAQMD, Ozone Transport Commission states, and EU member implementations. Formulators compete on certification documentation speed as much as chemistry.
Regulatory compliance investment is heaviest in Low-VOC platform development. Immediate volume concentration remains in Water-Based systems where application infrastructure and contractor training are already scaled.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-backed retrofit zones concentrate demand acceleration for thermal barrier systems. The Yangtze River Delta special economic corridors anchor manufacturing scale for ceramic microsphere formulations. Germany's Ruhr industrial belt drives specification-grade epoxy adoption under REACH enforcement timelines.
United States
Industrial facility retrofits across Texas and Louisiana petrochemical corridors expand thermal coating procurement. EPA architectural coating VOC rules compress reformulation deadlines toward water-based epoxy alternatives. Houston-Galveston refineries pilot low-VOC thermal barrier systems to preempt Gulf Coast enforcement actions.
Germany
Energy Performance Certificate ratings in commercial construction bundle coating packages with blower-door guarantees. REACH disclosure mandates and EU Green Deal carbon footprint reduction targets favor formulators with dedicated regulatory affairs capacity. The Rhine-Ruhr chemical corridor specifies warranty-backed epoxy systems for tanks operating above 120°C.
China
State-backed building envelope retrofit programs under dual carbon goals accelerate ceramic microsphere and aerogel-dispersion coating demand. MEE environmental standards tighten VOC limits in manufacturing provinces. Yangtze River Delta construction clusters concentrate specification activity for commercial and residential envelope upgrades.
India
Underpenetrated Energy Conservation Building Code enforcement creates first-mover positioning as state-level adoption accelerates. BIS standards development for thermal coating performance lags behind demand growth. Maharashtra and Gujarat industrial zones drive early specification in pharmaceutical and food processing facility retrofits.
Japan
METI building efficiency standards and JIS certification requirements filter supplier pools toward documented quality systems. Automotive lightweighting convergence drives underbody thermal coating validation for electric vehicle platforms. Kansai manufacturing clusters test spray-applied ceramic systems as insulation mat replacements.
Insulating Paints and Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The industrial coating segment concentrates around formulators with legacy protective coating heritage and regulatory compliance infrastructure. Three archetypes dominate: diversified multinational chemical conglomerates with dedicated coating divisions, mid-cap regional specialists with substrate-specific expertise, and application-technology integrators bundling robotics with formulation supply. Competitive moves center on water-based platform expansion and spray-application technology licensing to capture specification-grade project flows.
Among diversified coating conglomerates, PPG Industries Inc. and Akzo Nobel N.V. occupy positions anchored in industrial heritage and European regulatory compliance capacity respectively. Jotun Group exemplifies the mid-cap specialist archetype with concentrated expertise in marine and protective applications. These three represent the tier where specification power concentrates around documented warranty backing and lot traceability systems that filter procurement pools at industrial and automotive OEMs.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Akzo Nobel N.V. |
| Nippon Paint Holdings Co., Ltd. |
| Kansai Paint Co., Ltd. |
| Jotun Group |
| Axalta Coating System |
| Carboline Company |
| Hempel |
| Others |
Supply & Pricing Matrix
Industrial facility managers with capital budget authority for energy retrofit programs command specification-driven pricing premiums. Their procurement power concentrates around documented thermal performance guarantees and warranty-backed installation protocols.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to ceramic microsphere formulations ordered on compressed delivery schedules. Project-based pricing dominates specification-grade industrial work, with differentiation anchored in ISO 9001 certification tiers and lot-traceability documentation. Price erosion runs through commodity acrylic residential channels where DIY retail competition intensifies. Homeowner segments exhibit highest price sensitivity; facility managers at petrochemical complexes show lowest, justified by energy audit payback calculations.
Supply Chain Analysis
Freight cost spikes from East Asian petrochemical corridors have compressed margins on epoxy resin shipments to European and North American formulators. Production of high-purity bisphenol-A precursors concentrates in China, South Korea, and Japan; titanium dioxide pigment supply clusters in China, Ukraine, and Australia. Formulators face tariff exposure on ceramic microsphere imports under evolving trade frameworks. Distribution runs through regional coating distributors with applicator certification programs, bypassing direct OEM supply for all but the largest industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerogel dispersion manufacturing capacity constraints prop pricing premiums for specification-grade thermal barrier systems. This supply bottleneck concentrates margin capture among incumbents with captive precursor supply.
For Market Incumbents: Deepen backward integration into ceramic microsphere production to offset TiO2 feedstock volatility. Expand water-based formulation capacity in Germany and China ahead of REACH and MEE enforcement timelines. Certify spray-application technician networks to lock out unqualified regional competitors from warranty-backed industrial projects. For New Entrants and Emerging Players: Specialty applicators with robotics integration capabilities offer the fastest channel to specification-grade revenue. Target India's underpenetrated Energy Conservation Building Code enforcement zones before state-level adoption accelerates. Lead with blower-door testing guarantees bundled with coating packages to displace commodity bids in Nordic commercial construction. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap formulators with REACH-compliant water-based platforms and stranded regulatory affairs capacity in European industrial corridors. Five-to-ten-year viability hinges on positioning ahead of automotive lightweighting convergence for electric vehicle thermal management. Monitor EPA enforcement actions in US Gulf Coast petrochemical zones as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Microspheres | Captive supply of hollow ceramic precursors insulates margin pools from TiO2 volatility. |
| Water-Based Platform Expansion | REACH and EPA compliance deadlines favor reformulated epoxy and polyurethane alternatives. |
| Spray-Application Robotics Licensing | AI-guided thickness monitoring compresses installation timelines and tightens warranty compliance. |
| Applicator Certification Program Scale-Up | Training bottlenecks on aerogel systems filter procurement pools toward established regional players. |
| Automotive OEM Thermal Management Partnership | Phase-change material integration positions coatings as insulation mat replacements in electric vehicle platforms. |
Research Methodology
Trade databases, customs records, and SEC filings from coating manufacturers formed the secondary backbone for supply-side calibration. Primary interviews with industrial facility managers, commercial general contractors, coating applicators, and regulatory affairs directors at formulators supplied demand-side validation. Bottom-up and top-down triangulation cross-checked volume estimates against production capacity disclosures and end-use consumption patterns.
Bottom-up modeling anchored forecasts in substrate-specific application rates and regional building code enforcement trajectories. Segmentation dimensions included resin chemistry, end-use vertical, technology platform, and geographic regulatory cluster. CAGRs derived from slope analysis of historical retrofit spending and projected energy efficiency mandate expansion. Key inputs spanned ceramic microsphere loading rates and aerogel dispersion stability improvements.
Several conditions sit outside the modeled scope, including geopolitical disruptions to East Asian petrochemical supply corridors and breakthroughs in competing insulation technologies. Forecasts reflect assumptions about regulatory enforcement timelines and raw material price trajectories. Stakeholders should weight assumptions against their own operating context and supply contract structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Middle-East Paints and Coatings Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Mosquito-Repellent Paints Market
Paints & Coatings
Faux Paints and Coatings Market
Paints & Coatings
Fire Resistant Paints Market
Paints & Coatings
Paint Buckets Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
Furniture Wood Coatings Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
ASEAN Paints and Coatings Market
Paints & Coatings
Global Primer Market
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
Global Thinners and Paint Strippers Market
Paints & Coatings
Hybrid Paint Cans Market