
 Polyurethane Resins Paints and Coatings Market | 2026-2036
Polyurethane Resins Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane Resins Paints and Coatings Market Analytics
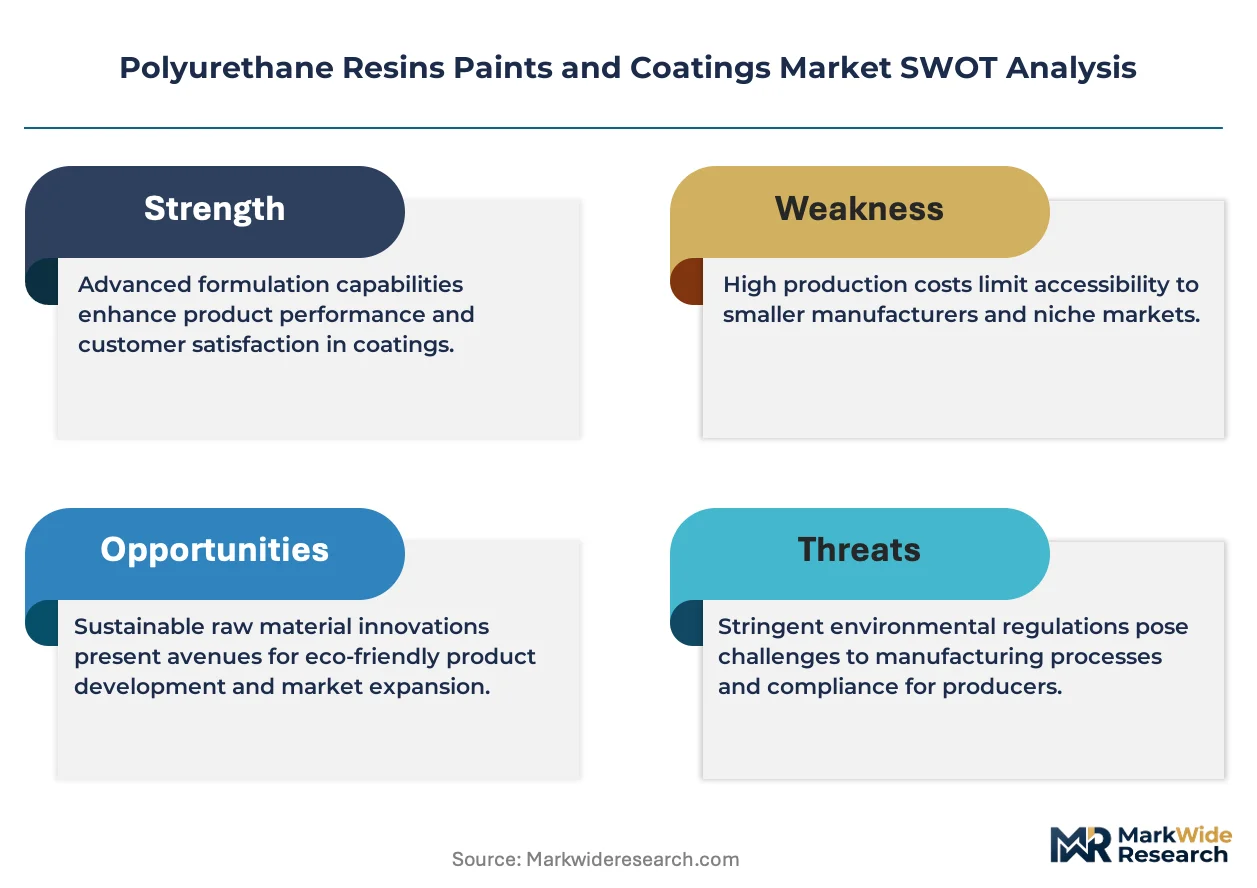
Epoxy is shifting from marine and industrial topcoats toward primer applications as polyurethane resins capture share in high-durability, UV-stable finishes. BASF SE leverages backward integration into isocyanate feedstocks to control raw material costs across European manufacturing. PPG Industries Inc. anchors its position through automotive OEM relationships and electrostatic spray technology leadership. Akzo Nobel N.V. differentiates via water-based architectural formulations that comply with tightening VOC limits.
Polyurethane resins paints and coatings comprise isocyanate-cured polymer systems typically formulated with aliphatic or aromatic diisocyanates and polyol components, delivering film thicknesses of 50-200 microns with exceptional abrasion resistance and gloss retention for protective and decorative substrates. Water-based formulations lead volume in architectural applications where VOC thresholds have tightened, while UV-cured systems represent the fastest-expanding technology segment due to instant cure cycles that eliminate solvent emissions and reduce energy consumption in furniture and industrial finishing lines. Solvent-based polyurethane maintains margin concentration in automotive and heavy equipment sectors where performance specifications exceed current water-borne capabilities.
EPA regulates VOC emissions from architectural and industrial maintenance coatings under 40 CFR Part 59, while REACH restricts isocyanate monomer concentrations in EU consumer products and mandates skin-sensitization labeling. China's MEE enforces GB standards on solvent content that favor water-based polyurethane adoption in manufacturing clusters. Stakeholders must monitor regulatory divergence between low-VOC mandates in Europe and performance-driven solvent tolerance in emerging industrial markets to align formulation portfolios with compliance trajectories.
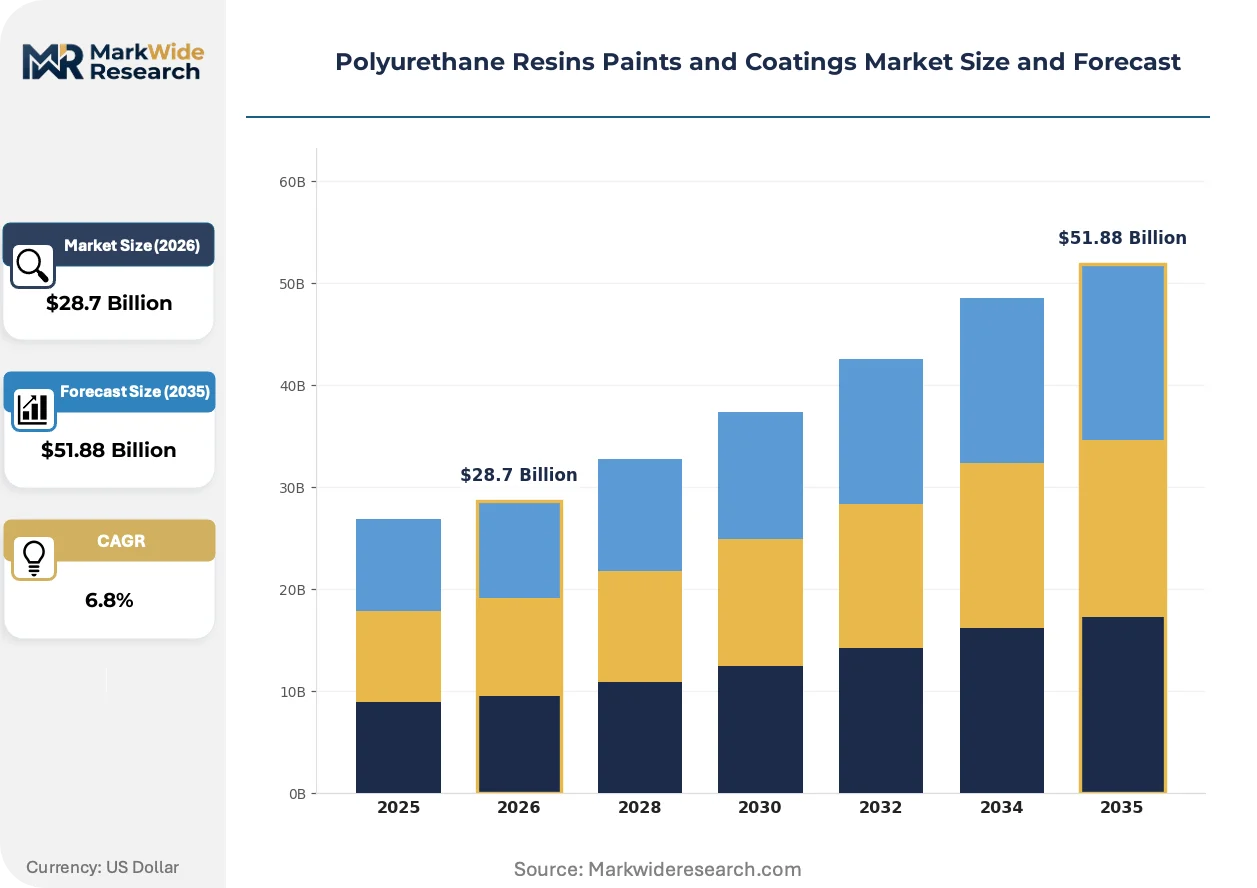
Market Dynamics
Water-based polyurethane formulation technology is compressing solvent-system margins while automotive OEMs accelerate specification shifts toward UV-stable, lightweight protective coatings. This dual pressure is restructuring competitive positioning across formulation tiers and application equipment supply chains.
Growth Catalysts
- REACH isocyanate restrictions:ECHA-mandated skin-sensitization labeling and monomer concentration limits are accelerating water-borne system R&D investment across European manufacturing clusters.
- Automotive lightweighting mandates:OEM coating specifications for aluminum and composite substrates favor polyurethane chemistries that deliver 50-200 micron films with abrasion resistance.
- China construction volume:MEE enforcement of GB solvent-content standards in manufacturing clusters is concentrating demand for compliant architectural formulations in Shanghai and Guangdong provinces.
Market Restraints
- MDI/TDI feedstock volatility:Aromatic diisocyanate pricing swings tied to benzene derivative markets compress margin predictability for European and North American formulators.
- Performance ceiling in water-borne systems:Current water-based polyurethane chemistry cannot match solvent-borne gloss retention and chemical resistance for heavy equipment and marine topcoat specifications.
- Isocyanate supply concentration:Backward-integrated producers in Germany and China control captive isocyanate supply, limiting independent formulator cost flexibility.
Strategic Opportunities
- UV-cured furniture finishing:Instant cure cycles eliminating solvent emissions are creating white space in Italian and German woodworking clusters where energy costs dominate operational decisions.
- India infrastructure build-out:BIS adoption of VOC-aligned coating standards for commercial construction is opening specification windows for water-based polyurethane in Mumbai and Delhi NCR projects.
- Electrostatic spray convergence:Integration of robotic application systems with low-VOC polyurethane formulations is enabling automotive tier-one suppliers to consolidate coating operations.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in isocyanate-polyol reaction kinetics and water-borne dispersion stability is concentrating at integrated producers, constraining independent R&D capacity.
- Multi-jurisdiction certification lag:Separate EPA 40 CFR Part 59, REACH Annex XVII, and China MEE compliance timelines extend product launch cycles by 18-24 months for global formulation portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane Resins Paints and Coatings Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Oil-Based, UV-Cured Application: Automotive, Furniture, Industrial, Architectural End User: Construction, Automotive OEMs, Woodworking, General Manufacturing Technology: Electrostatic Spray, Airless Spray, Roller Application, Brush Application |
| Companies Covered | BASF SE, The Sherwin-Williams Company, PPG Industries Inc., Akzo Nobel N.V., Axalta Coating Systems, Covestro AG, Jotun, Arkema, RPM International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane Resins Paints and Coatings Market Evolving Landscape
Formulation chemistry is bifurcating between high-performance solvent systems for industrial specifications and water-borne platforms for regulatory compliance, with curing technology emerging as the primary differentiation axis. Equipment integration and application method innovation are compressing the traditional separation between coating supply and finishing operations.
UV-curable polyurethane oligomer systems are decentralizing capital-intensive thermal oven infrastructure from furniture and industrial finishing lines. European woodworking manufacturers in Italy and Germany are adopting mercury-vapor and LED-cure units that eliminate solvent-based flash-off zones. This technology is decentralizing production geography by enabling smaller-batch, distributed finishing operations near end-use assembly points rather than centralized coating facilities.
EPA 40 CFR Part 59 Subpart D architectural coating VOC limits are forcing reformulation of interior clear wood finishes and floor coatings toward water-borne polyurethane platforms. The rule's 275 g/L effective limit for floor coatings is compressing solvent-borne product lines from major supplier portfolios. California Air Resources Board Suggested Control Measure provisions are extending these thresholds to industrial maintenance categories, accelerating water-borne adoption in US manufacturing facility refurbishment cycles.
Automotive OEMs are unbundling coating specification decisions from historical supplier relationships, with procurement teams now directly engaging specialty resin producers for performance-guaranteed systems. Tier-one suppliers in Germany and Japan are bypassing traditional distributor channels to secure locked-in polyol supply for just-in-sequence coating operations. This pattern is most visible in electric vehicle battery tray and motor housing coating programs where thermal management specifications demand application-specific formulation collaboration.
Polyurethane Resins Paints and Coatings Market Segmentation
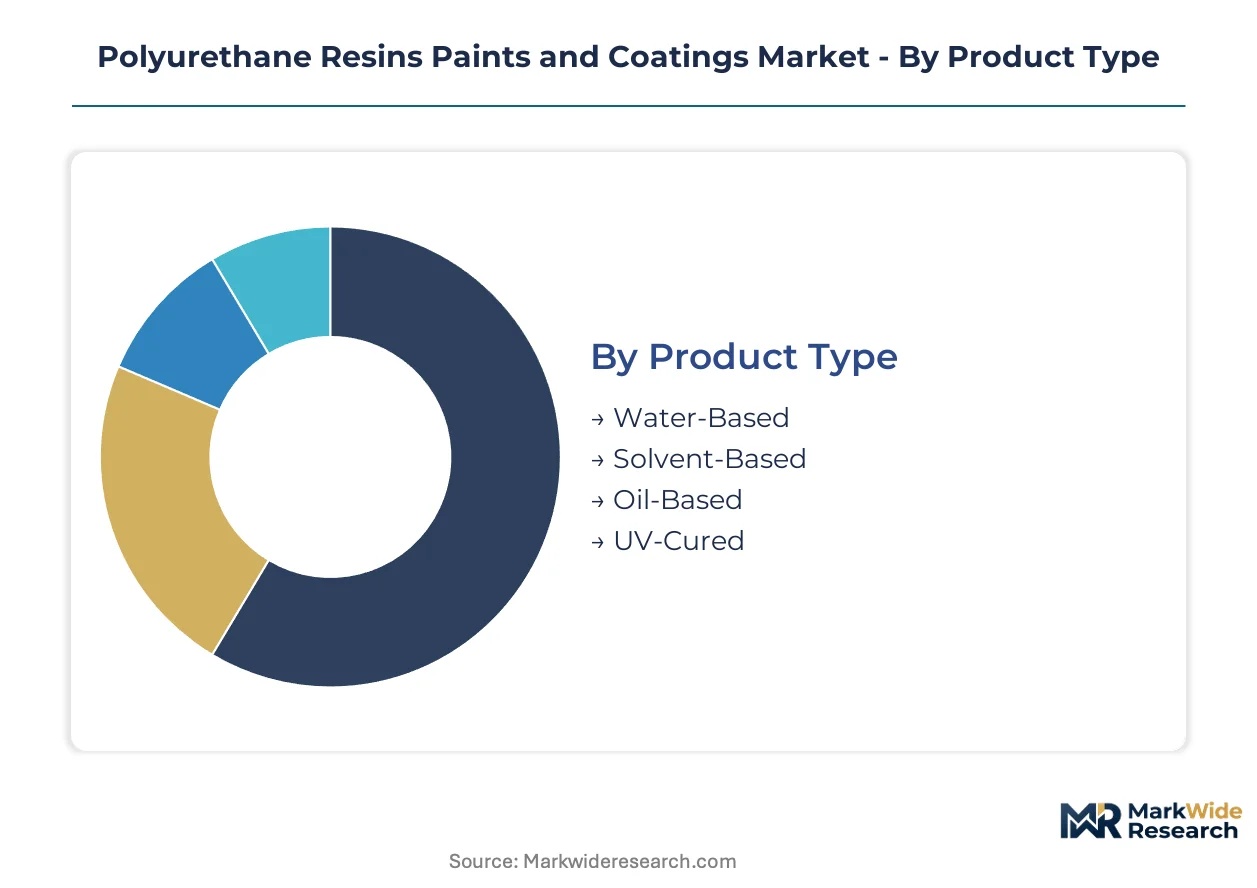
Polyurethane coating formulations diverge sharply across chemistry platforms and curing technologies, with each segment carrying distinct regulatory exposure and performance ceilings. Understanding these technical boundaries determines supplier positioning and R&D resource allocation.
Product Type:
Technology specifications define the primary axis of differentiation, separating compliant water-borne platforms from legacy solvent systems.
- Water-Based:Polyurethane dispersions employ ionic or non-ionic stabilization of isocyanate-terminated prepolymers in aqueous media, delivering VOC levels below regulatory thresholds. Demand concentrates in architectural applications across Germany and France where REACH skin-sensitization labeling has accelerated specification shifts away from solvent alternatives.
- Solvent-Based:Aromatic and aliphatic diisocyanate systems dissolved in oxygenated or hydrocarbon carriers achieve superior gloss retention and chemical resistance. Heavy equipment manufacturers in the US and marine yards in South Korea maintain procurement concentration here where performance specifications exceed current water-borne capabilities.
- Oil-Based:Modified alkyd-urethane hybrids provide penetration and flexibility for wood substrates in furniture and flooring applications.
- UV-Cured:Acrylate-functional oligomers with photoinitiator packages enable instant polymerization under mercury-vapor or LED sources.
Mature deployment sits with solvent-based formulations. Newer deployment is concentrated in water-based and UV-cured systems.
Application:
End-use performance requirements create tiered demand patterns across durability and aesthetic specifications.
- Automotive:Clearcoat and basecoat systems for OEM assembly lines demand 50-200 micron film builds with UV stability and chip resistance. Procurement from German and Japanese tier-one suppliers is accelerating for electric vehicle battery tray coatings where thermal management properties are critical.
- Furniture:Decorative and protective finishes for residential and commercial wood products span matte through high-gloss specifications. Italian and German woodworking clusters are driving UV-cured adoption where energy costs dominate operational decisions and solvent emissions face tightening local limits.
- Industrial:Protective coatings for machinery, metal fabrication, and infrastructure assets prioritize abrasion resistance and chemical exposure tolerance.
- Architectural:Interior and exterior building coatings balance aesthetic requirements with application efficiency for large surface areas.
Volume concentration rests with architectural applications. Margin expansion is sharpest in automotive specification programs.
End User:
Customer scale and procurement sophistication fragment demand across integrated manufacturers and distributed applicators.
- Construction:Commercial and residential building projects specify coatings for structural steel, concrete, and interior finishes. Developers in Shanghai and Guangdong provinces are consolidating procurement around GB-compliant water-based formulations as MEE enforcement intensifies in manufacturing clusters.
- Automotive OEMs:Original equipment manufacturers directly engage resin suppliers for performance-guaranteed coating systems. Battery and motor housing programs are unbundling historical distributor relationships in favor of locked-in polyol supply for just-in-sequence operations.
- Woodworking:Furniture manufacturers and millwork operations apply finishes on-site or through contracted finishing services.
- General Manufacturing:Diverse industrial facilities maintain coatings for equipment protection, facility maintenance, and product finishing.
Procurement scale is largest with construction volume. Technical collaboration intensity is highest with automotive OEMs.
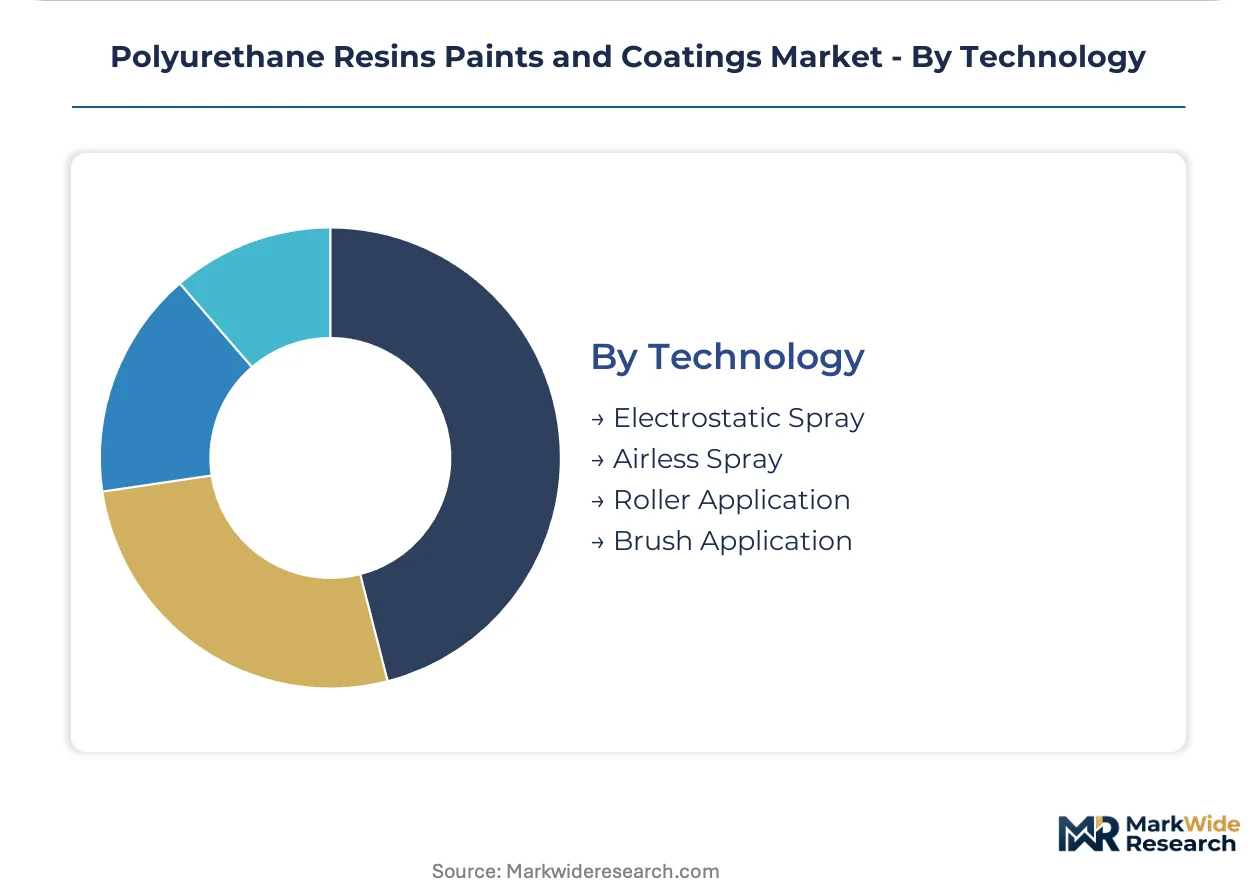
Technology:
Application method determines transfer efficiency, labor requirements, and capital investment profiles across the coating operation.
- Electrostatic Spray:Charged particle deposition onto grounded substrates achieves 60-80% transfer efficiency with robotic integration. Automotive tier-one suppliers in Germany and Japan are converging this equipment with low-VOC formulations to consolidate coating operations and reduce material waste.
- Airless Spray:High-pressure fluid atomization without compressed air enables rapid coverage of large surface areas with high-solids materials. Shipyards in South Korea and industrial maintenance contractors in the US deploy this method for protective coatings where speed outweighs precision requirements.
- Roller Application:Manual or powered roller systems suit large flat surfaces in architectural and flooring applications.
- Brush Application:Hand-applied finishing for touch-up, repair, and small-batch custom work.
Capital intensity peaks with electrostatic spray integration. Labor dependency remains highest with brush application methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates demand volume for polyurethane coatings through construction and automotive expansion, while regulatory pressure in Europe and North America accelerates water-borne formulation shifts. Procurement patterns diverge between performance-driven solvent tolerance in emerging industrial markets and compliance-first specification in mature economies.
China
Construction megaprojects and electric vehicle battery tray coating programs drive specification volume. MEE enforces GB solvent-content standards that favor water-based polyurethane adoption in manufacturing clusters. Shanghai and Guangdong provinces concentrate procurement as developers consolidate around compliant architectural formulations.
Germany
Automotive OEMs and tier-one suppliers demand UV-stable finishes for aluminum and composite lightweighting. REACH skin-sensitization labeling and isocyanate monomer limits accelerate water-borne R&D investment. Bavarian and Baden-Württemberg industrial clusters host electrostatic spray integration with low-VOC formulations.
United States
Heavy equipment manufacturers and marine yards maintain solvent-borne procurement where performance specifications exceed water-based capabilities. EPA 40 CFR Part 59 Subpart D compresses solvent product lines for floor coatings toward 275 g/L limits. California Air Resources Board provisions extend VOC thresholds to industrial maintenance categories.
Italy
Furniture manufacturers in woodworking clusters drive UV-cured polyurethane adoption where energy costs dominate operational decisions. ECHA-mandated labeling aligns with local solvent emission tightening. Northern Italian finishing operations deploy mercury-vapor and LED-cure units to eliminate flash-off zones.
India
Commercial construction in Mumbai and Delhi NCR opens specification windows as BIS adopts VOC-aligned coating standards. Infrastructure build-out creates demand for protective coatings on structural steel and concrete. Domestic formulators face raw material cost pressure from concentrated isocyanate supply.
Polyurethane Resins Paints and Coatings Market Competitive Landscape
Backward integration into isocyanate feedstocks dominates the current landscape as producers seek cost control against MDI/TDI volatility. The vendor base concentrates around integrated chemical conglomerates with captive raw material supply, mid-scale regional formulators serving specific application niches, and equipment-integrated coating specialists. Strategic archetypes split between feedstock-integrated giants controlling polymer supply chains and application-technology leaders bundling formulation with spray systems. M&A activity targets water-borne formulation capabilities, while capacity expansion concentrates in Asian manufacturing clusters.
Among feedstock-integrated conglomerates, BASF SE and Covestro AG exemplify the archetype of producers controlling captive isocyanate supply from European manufacturing bases. PPG Industries Inc. occupies a position representing equipment-convergent specialists, anchoring the tier where automotive OEM relationships and electrostatic spray technology leadership define competitive differentiation. These three entities represent the dominant strategic vectors: backward-integrated chemical production, application-technology bundling, and performance-guaranteed specification partnerships with automotive tier-one suppliers.
| Leading Market Players |
|---|
| BASF SE |
| The Sherwin-Williams Company |
| PPG Industries Inc. |
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| Covestro AG |
| Jotun |
| Arkema |
| RPM International Inc. |
| Others |
Value Network & Pricing Analysis
Backward-integrated chemical conglomerates in Germany and China anchor pricing discipline through captive isocyanate production, compressing margin flexibility for independent formulators while concentrating procurement leverage with automotive OEMs and tier-one suppliers. This ownership pattern feeds directly into supply allocation decisions that favor long-term contract structures over spot-market exposure.
Pricing Analysis
Volume concentrates in architectural water-borne formulations where REACH and EPA compliance thresholds enforce commodity-like pricing, while margins expand in automotive OEM specification programs where UV-stable performance guarantees command premium positioning. Price differentiation rests on certification grade against VOC limits and volume scale in raw material offtake agreements. Cost compression in solvent-borne tiers is intensifying because water-borne chemistry is capturing specification share in furniture and industrial maintenance categories. Construction developers in Chinese manufacturing clusters exhibit highest price sensitivity, whereas German automotive tier-one suppliers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with aromatic diisocyanate feedstocks concentrated in German and Chinese manufacturing bases, where benzene derivative pricing volatility transmits directly into formulation cost structures. Raw material dependencies center on MDI, TDI, and specialty polyol streams drawn from backward-integrated producers. Tariff exposure on isocyanate imports into North American markets compounds margin pressure for non-integrated formulators. Distribution runs through regional chemical distributors serving construction and industrial maintenance applicators, with direct supply relationships dominating automotive OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyurethane coatings sector is executing a technology-transition phase as UV-cured oligomer systems displace thermal oven infrastructure in furniture and industrial finishing lines. Water-borne formulation platforms are simultaneously replacing solvent systems under tightening VOC regulatory mandates across European and North American markets.
For Market Incumbents: Acquire water-borne formulation capabilities and UV-curable oligomer technology portfolios to defend specification share against emerging specialty resin producers. Deepen backward integration into aliphatic diisocyanate feedstocks to buffer MDI/TDI volatility exposure. Prioritize certification investment against REACH skin-sensitization labeling requirements to maintain European market access. For New Entrants and Emerging Players: Equipment-integrated service providers represent the most penetrable channel partner type for bypassing established distributor relationships. Target Indian commercial construction markets in Mumbai and Delhi NCR where BIS VOC-aligned standards are opening specification windows before incumbent consolidation solidifies. Pursue white-label formulation partnerships with domestic Indian formulators facing raw material cost pressure. For Investors and Strategic Acquirers: Tier-one supplier bypass of traditional distributor channels is the leading indicator that direct resin procurement relationships will concentrate value capture with specialty formulation specialists. Frame five-to-ten-year viability around acquisition of mid-scale European water-borne formulators with REACH-compliant portfolios and locked-in automotive testing relationships. Watch for electrostatic spray equipment convergence with low-VOC formulations as the inflection signal for coating operation consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Feedstocks | Captive MDI/TDI supply insulates BASF and Covestro from benzene derivative volatility in European manufacturing. |
| UV-Curable Oligomer Capacity Expansion | Mercury-vapor and LED-cure units eliminate solvent flash-off zones in Italian and German woodworking clusters. |
| Water-Borne Formulation Certification Investment | REACH Annex XVII compliance accelerates specification shifts away from solvent alternatives in German architectural markets. |
| Direct OEM Supply Relationship Development | Locked-in polyol supply for just-in-sequence coating operations captures electric vehicle battery tray programs. |
| Electrostatic Spray Equipment Convergence | Robotic integration with low-VOC formulations consolidates coating operations for German and Japanese tier-one suppliers. |
Research Methodology
SEC 10-K filings, Cefic industry reports, and customs trade data formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with polyurethane plant managers, automotive OEM procurement leads, distribution channel partners, and technical R&D directors at formulation houses provided forward-looking specification trend validation. Bottom-up and top-down triangulation across these sources established volume and value estimates for each chemistry platform and application segment.
Bottom-up modeling of isocyanate consumption patterns and top-down cross-checks against end-use industry coating demand generated consistent outputs across the projection horizon. Segmentation dimensions included chemistry platform, curing technology, application method, and regional regulatory cluster. CAGRs were derived from trend extrapolation of specification shifts and capacity expansion announcements, with automotive lightweighting mandates and VOC regulatory timelines as primary forecast inputs.
Caveats apply where MDI/TDI feedstock volatility, REACH enforcement intensity, or automotive platform electrification pace could materially shift the outlook. Forecasts reflect assumptions about water-borne chemistry performance advancement and UV-cure equipment adoption rates that remain subject to technical validation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Bahrain Paints and Coatings Market
Paints & Coatings
Paints and Coatings Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
Canvas Primer Market
Paints & Coatings
Furniture Wood Coatings Market
Paints & Coatings
India Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
Floor Paints Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
Automotive Paints Market