
 Europe Architectural Coatings Market | 2026-2036
Europe Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Architectural Coatings Market Foresight
Aftermarket color-matching and tinting services is rewriting margin economics across the value chain. AkzoNobel N.V. leverages its Interpon powder coatings network to dominate specification channels for commercial facades. PPG Industries, Inc. sustains R&D intensity in low-VOC acrylic platforms through its Amsterdam innovation hub. DAW SE anchors regional supply in German-speaking markets with captive distribution through Caparol-branded retail outlets.
Architectural coatings encompass decorative and protective film-forming systems applied to building substrates, typically comprising binders, pigments, extenders, solvents or water carriers, and functional additives, with film thickness ranging from 30 to 150 microns depending on substrate and exposure class. Their primary purpose is to protect structural materials from moisture, UV degradation, and atmospheric pollutants while delivering specified aesthetic and hygiene performance across interior and exterior environments. Water-based emulsion systems now lead volume across residential applications due to tightening VOC ceilings, while nano-engineered coatings represent the fastest-expanding technology segment as self-cleaning and anti-microbial functionalities penetrate premium commercial specifications. Solvent-based alkyd and polyurethane segments retain margin concentration in industrial and heritage restoration niches where durability requirements exceed water-borne performance thresholds.
REACH registration requirements and the EU Green Deal carbon-border adjustments are forcing reformulation roadmaps toward bio-epoxy and silicate-based systems. The F-Gas Regulation and ECHA restrictions on titanium dioxide classification are reshaping raw material sourcing and pigment substitution strategies for manufacturers serving European construction markets. Stakeholders must monitor the interplay between national building renovation passports and product environmental footprint declarations as these frameworks progressively link public procurement eligibility to verified lifecycle performance data.
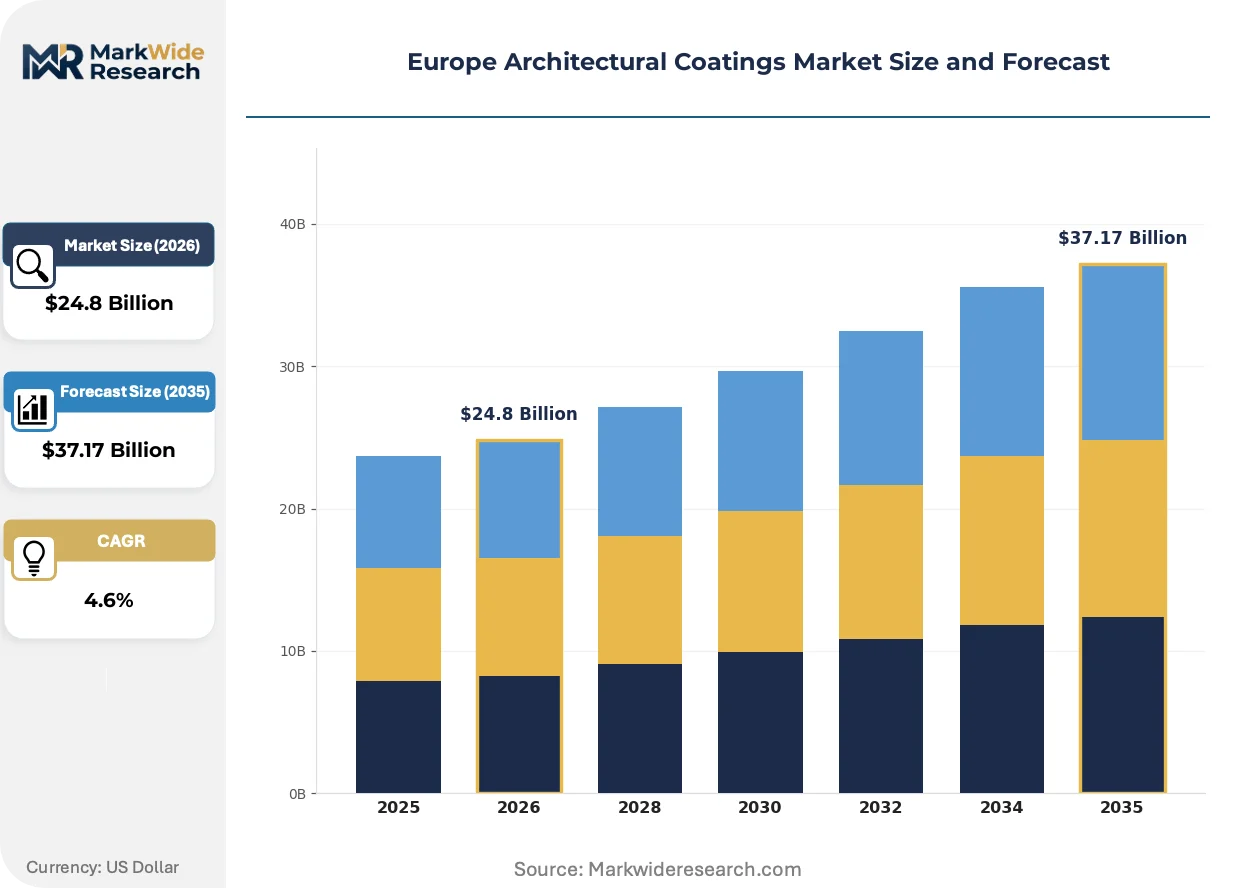
Market Dynamics
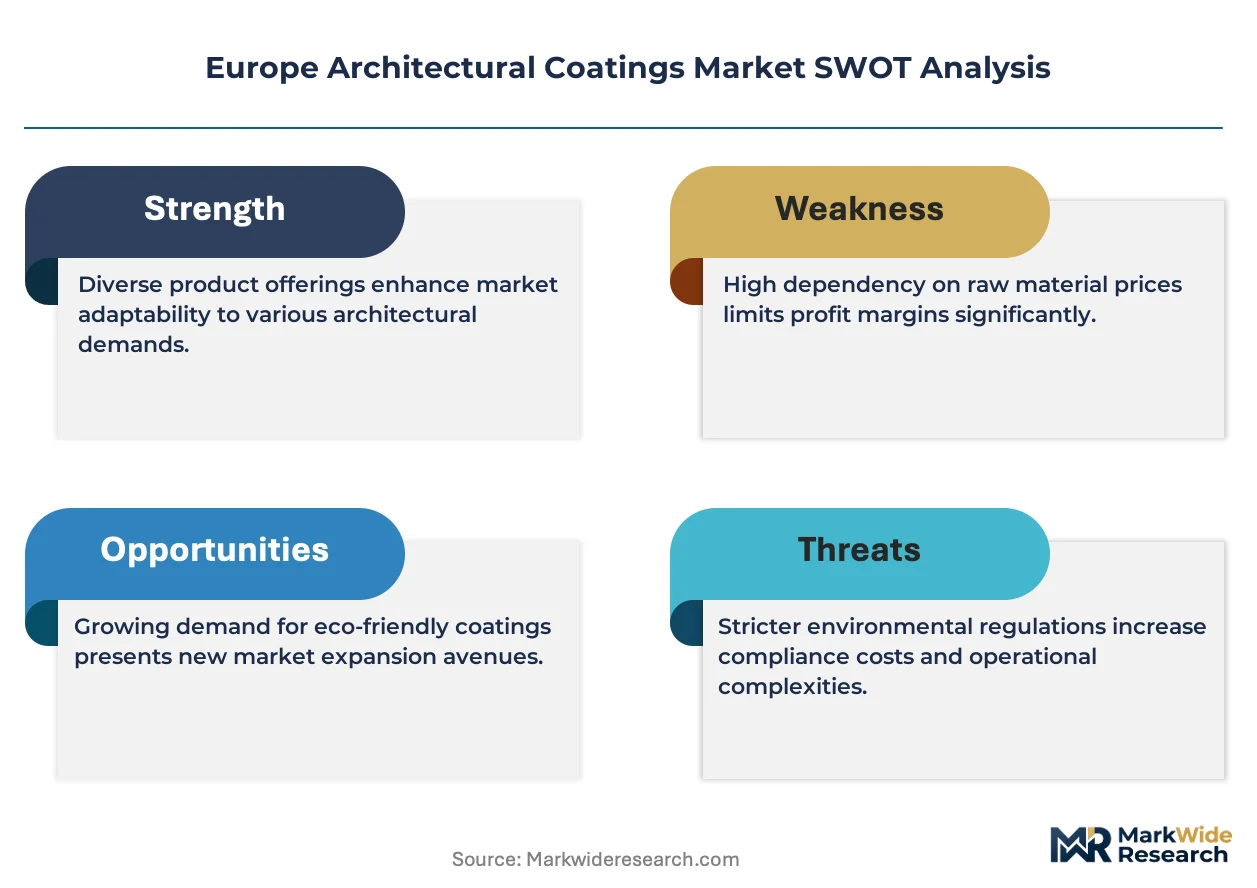
REACH registration deadlines and the EU Green Deal are compressing formulation cycles across European coating manufacturers, forcing simultaneous transitions in binder chemistry, pigment sourcing, and carbon accounting systems.
Growth Catalysts
- German residential renovation:Aging housing stock in North Rhine-Westphalia and Bavaria drives accelerated refresh cycles for exterior emulsion systems.
- F-Gas Regulation phase-down:Banned hydrofluorocarbon propellants in aerosol applications redirect investment toward compressed air and pump technologies.
- Climate-adaptive exterior coatings:Reflective and thermochromic formulations gain specification in Spanish and Italian commercial construction exposed to intensifying heat island effects.
Market Restraints
- Titanium dioxide reclassification:ECHA carcinogenicity labeling tightens occupational exposure limits and raises liability premiums for pigment handling.
- Bio-based binder cost premiums:Epoxidized soybean oil and lignin-derived resins trade at 15-40% above petrochemical equivalents, compressing mid-tier margins.
- Heritage restoration solvent dependence:Alkyd and polyurethane systems retain specification for monument conservation where water-borne durability falls short.
Strategic Opportunities
- Building renovation passports:France and Belgium mandate product environmental footprint declarations for public procurement eligibility.
- Nano-engineered functional coatings:Self-cleaning photocatalytic titanium dioxide and anti-microbial silver-ion systems penetrate premium healthcare and hospitality specifications.
- Specialist contractor direct channels:Bypassing traditional retail through specification-selling to applicator networks captures margin otherwise lost to distribution.
Industry Challenges
- Formulation chemist scarcity:Retiring expertise in silicate and alkyd chemistry outpaces university pipeline output across German and Dutch technical institutes.
- Dual certification timelines:Simultaneous CE marking and national eco-label approvals (Blue Angel, Nordic Swan) extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Architectural Coatings Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Solvent-based, Water-based, Powder Coatings Application: Residential, Commercial, Institutional, Industrial End User: Contractors, Property Developers, DIY, Architects Technology: Low-VOC, High-Performance, Eco-Friendly, Nano Coatings |
| Companies Covered | AkzoNobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Jotun, DAW SE, Flügger group A/S, Nippon Paint Holdings Co., Ltd., BASF SE, Hempel A/S, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Architectural Coatings Market Shifts & Advancements
European architectural coatings are pivoting from commodity volume toward certified performance tiers, with digital color services and lifecycle transparency becoming primary competitive differentiators rather than price.
Silicate-based mineral coatings are rendering obsolete conventional acrylic exterior systems in heritage and high-durability segments. Municipal conservation authorities in Italy and Portugal specify these breathable, alkali-resistant finishes for stone and render substrates. The shift compresses demand for synthetic resin dispersions in premium facade applications where 50-year service life guarantees dominate procurement criteria.
The EU Green Deal carbon-border adjustment mechanism tightens embedded emissions reporting for imported titanium dioxide and epoxy resins. Manufacturers must document Scope 3 upstream data to avoid tariff exposure on non-EU raw material sources. German and Dutch coating producers are accelerating captive bio-epoxy pilot plants to secure compliant supply chains before full 2026 implementation.
Aftermarket tinting unbundling disrupts traditional retail economics. Property maintenance contractors in Spain and Poland procure base whites through direct channels while subscribing to cloud-based spectrophotometer networks for on-site color matching. This bifurcation concentrates volume purchasing power among specialist applicators and erodes foot traffic at conventional trade outlets dependent on tinting service margins.
Europe Architectural Coatings Market Segmentation
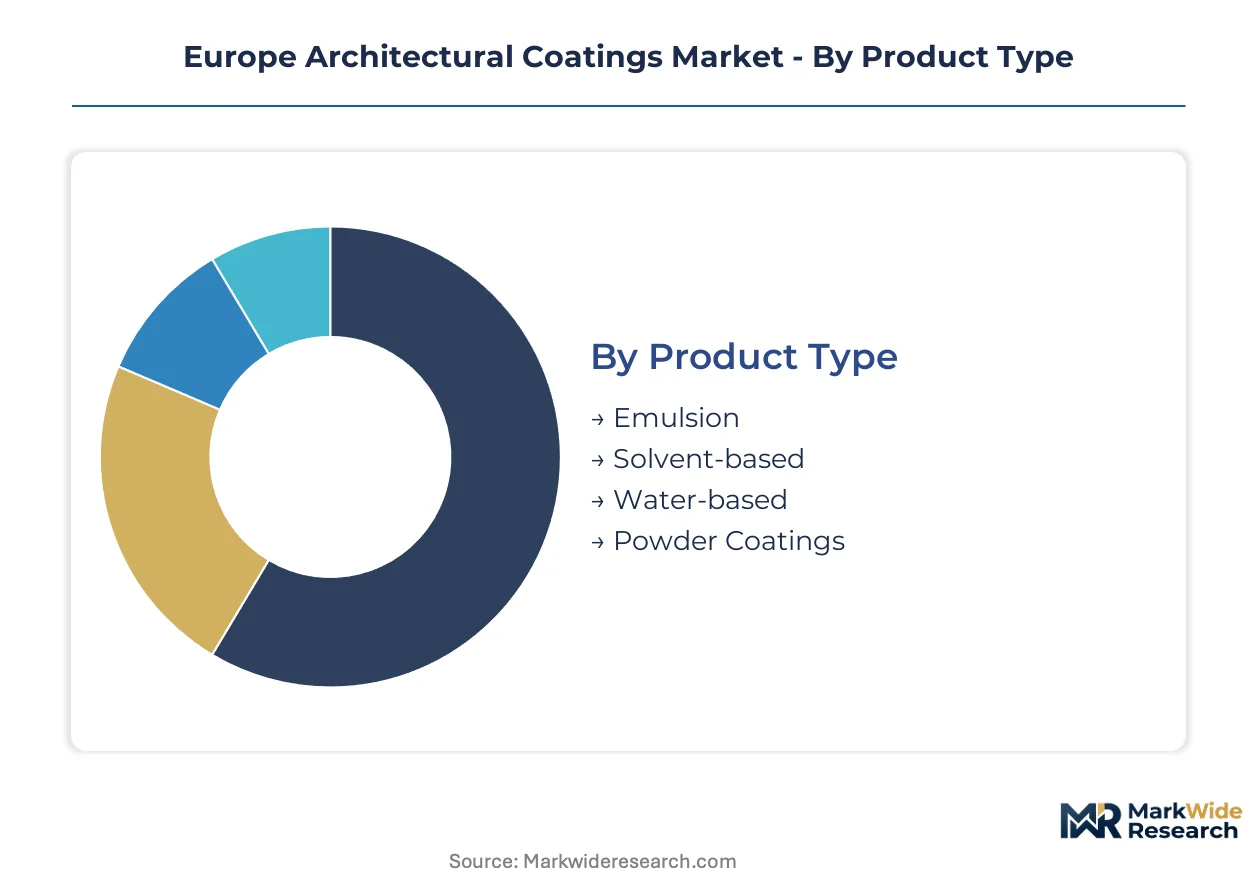
Architectural coatings in Europe fragment across formulation chemistry, application environment, and procurement channel, with each axis carrying distinct margin profiles and compliance burdens. Understanding these divisions reveals where REACH-driven reformulation costs concentrate and where specification-selling unlocks premium capture.
Product Type:
Mature emulsion systems dominate residential volume, while emerging powder and water-based technologies reshape commercial specification channels.
- Emulsion:Acrylic and vinyl acetate copolymer dispersions form the workhorse category for interior walls and ceilings across European housing stock. German and Polish contractors specify these for renovation cycles in aging multifamily blocks where cost efficiency outweighs durability premiums.
- Solvent-based:Alkyd and polyurethane systems retain irreplaceable positions in heritage restoration and industrial maintenance where water-borne films fail on substrate adhesion or chemical resistance. Italian conservation authorities mandate these for monument protection despite tightening VOC ceilings.
- Water-based:Advanced acrylic-urethane hybrids displace solvent systems in premium exterior applications across Nordic markets. Danish and Swedish building codes accelerate this shift through mandatory environmental product declarations.
- Powder Coatings:Thermoset epoxy-polyester systems command aluminum facade and rebar specifications where factory-applied durability exceeds field-applied alternatives. AkzoNobel's Interpon network dominates this channel through architect-direct specification relationships.
Emulsion handles the majority of throughput; powder coatings are expanding most quickly on specification-driven commercial projects.
Application:
Cost tier differentiation separates commoditized residential refresh from premium institutional durability guarantees.
- Residential:Interior emulsion and exterior masonry paints drive volume through retail and trade merchant channels. Spanish and Portuguese housing renovation, fueled by tourism rental upgrades, accelerates product refresh cycles beyond traditional maintenance intervals.
- Commercial:Office, retail, and hospitality specifications demand certified low-VOC systems with documented lifecycle performance. French building renovation passports now mandate environmental footprint declarations for public procurement eligibility in this segment.
- Institutional:Healthcare and education facilities prioritize anti-microbial and scrub-resistant formulations with extended service life guarantees. German KfW funding programs tie renovation subsidies to verified indoor air quality standards.
- Industrial:Warehousing and logistics infrastructure require chemical-resistant floor and cladding systems with rapid return-to-service properties. Distribution concentrates among specialist contractors bypassing conventional retail.
Residential absorbs the greatest absolute volume; commercial specifications are gaining share fastest on regulatory compliance requirements.
End User:
Customer type determines channel economics, with direct contractor relationships eroding traditional retail tinting margins.
- Contractors:Specialist applicators in Spain and Poland procure base whites through direct channels while subscribing to cloud-based spectrophotometer networks for on-site color matching. This bifurcation concentrates purchasing power and compresses distributor margins.
- Property Developers:Large-scale residential and commercial projects negotiate specification-based contracts with manufacturers for multi-year supply agreements. DAW SE's Caparol-branded retail outlets anchor this channel in German-speaking markets.
- DIY:Home improvement retailers serve occasional painters with pre-tinted convenience products. Foot traffic erosion accelerates as digital color services unbundle tinting from physical store visits.
- Architects:Specification authority over commercial facades and institutional interiors directs premium product selection. PPG Industries sustains R&D relationships with this group through its Amsterdam innovation hub.
Contractors control the greatest share of product flow; architect influence is climbing fastest on sustainability certification requirements.
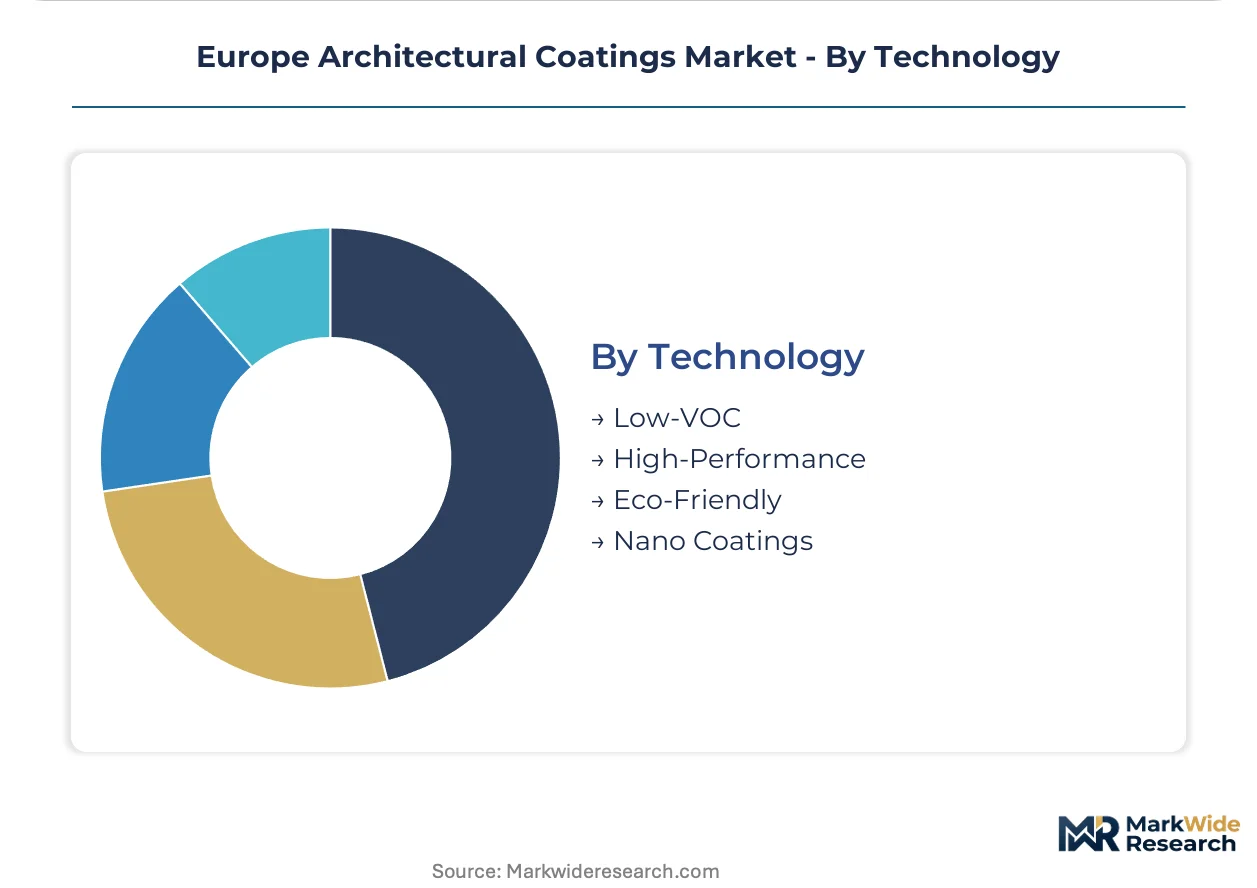
Technology:
Margin concentration aligns with performance tier, separating compliance-driven low-VOC commoditization from nano-engineered functional premiums.
- Low-VOC:Water-based emulsion and acrylic systems meeting EU Directive 2004/42/EC limits dominate residential compliance. REACH registration deadlines compress formulation cycles as manufacturers transition binder chemistry simultaneously.
- High-Performance:Polyurethane and fluoropolymer systems deliver abrasion and UV resistance for demanding exterior exposures. Heritage restoration in Italy and Portugal specifies these where synthetic resin durability exceeds mineral alternatives.
- Eco-Friendly:Bio-based epoxies from epoxidized soybean oil and lignin-derived resins trade at cost premiums but secure procurement eligibility under EU Green Deal carbon-border adjustments. German producers accelerate captive pilot plants to ensure compliant supply chains.
- Nano Coatings:Photocatalytic titanium dioxide and silver-ion anti-microbial systems penetrate premium healthcare and hospitality specifications. Self-cleaning functionality commands substantial price premiums in Mediterranean commercial construction exposed to intensifying heat island effects.
Low-VOC technology handles baseline regulatory compliance volume; nano-engineered functional systems are gaining share fastest on premium specification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contractors favor high-durability mineral systems for heritage facades, while Spanish developers prioritize reflective thermochromic coatings for new commercial construction exposed to Mediterranean heat island intensification.
Germany
North Rhine-Westphalia and Bavaria drive accelerated refresh cycles for exterior emulsion systems across aging multifamily housing stock. KfW funding programs tie renovation subsidies to verified indoor air quality standards enforced by the national building regulator. The Rhine-Ruhr industrial corridor concentrates captive bio-epoxy pilot plants as manufacturers secure compliant supply chains ahead of EU Green Deal carbon-border adjustments.
Spain
Tourism-driven hospitality refurbishment in Barcelona and Madrid accelerates product refresh cycles beyond traditional maintenance intervals. The national building code mandates environmental product declarations for public procurement eligibility in commercial construction. Andalusian commercial developers specify climate-adaptive reflective coatings as heat island effects intensify across Mediterranean coastal zones.
Italy
Municipal conservation authorities in Rome and Florence mandate breathable silicate finishes for stone and render substrates in monument protection. REACH registration deadlines compress formulation cycles as manufacturers transition binder chemistry simultaneously. The Lombardy manufacturing triangle anchors specialist contractor networks that bypass conventional retail through direct specification-selling channels.
France
Building renovation passports now mandate product environmental footprint declarations for public procurement eligibility in commercial and institutional segments. The national eco-label authority enforces Blue Angel-equivalent certification timelines that extend product launch windows. The Paris-Saclay innovation cluster concentrates architect-direct specification relationships for premium facade systems.
Poland
Property maintenance contractors procure base whites through direct channels while subscribing to cloud-based spectrophotometer networks for on-site color matching. The national construction regulator aligns vocational training programs with EU Green Deal competency requirements. The Silesian industrial basin concentrates distribution infrastructure serving German-speaking markets through cross-border supply arrangements.
Europe Architectural Coatings Market Competitive Landscape
Capability concentration sits with specialist manufacturers commanding specification authority; scale advantage sits with diversified chemical conglomerates optimizing formulation throughput. The vendor base spans three tiers: global coatings majors with architect-direct relationships, regional champions with captive distribution networks, and niche specialists in heritage restoration and nano-engineered functional systems. Dominant competitive moves include backward integration into bio-based resin supply and strategic partnerships with cloud-based color-matching platform operators.
Within the diversified coatings tier, AkzoNobel N.V. and PPG Industries, Inc. exemplify global majors leveraging innovation hub proximity to specification channels. DAW SE anchors regional supply concentration in German-speaking markets through vertically integrated retail operations. These three entities occupy distinct competitive positions: specification dominance through powder coating networks, R&D intensity in low-VOC platforms, and captive distribution control respectively.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Jotun |
| DAW SE |
| Flügger group A/S |
| Nippon Paint Holdings Co., Ltd. |
| BASF SE |
| Hempel A/S |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon-border adjustment exposure on imported titanium dioxide and epoxy resins determines both the premium spread between bio-based and conventional formulations and the geographic reconfiguration of supplier relationships toward captive European production.
Pricing Analysis
Long-term offtake contracts dominate procurement between German manufacturers and bio-epoxy pilot plants, while spot purchasing persists for standard petrochemical binders. Three-tier pricing structure across premium nano-functional, certified low-VOC, and economy emulsion levels reflects certification grade and volume scale differentiation. Cost compression in mid-tier bio-based segments is intensifying because epoxidized soybean oil and lignin-derived resins trade at sustained premiums to petrochemical equivalents. DIY retailers exhibit highest price sensitivity, while institutional buyers prioritize lifecycle performance over unit cost.
Supply Chain Analysis
Extended payment terms from German and Dutch manufacturers to Italian and Portuguese specialist contractors stabilize working capital across specification-driven project cycles. Raw material sourcing draws from Germany for captive bio-epoxy production, China for titanium dioxide, and the Netherlands for acrylic dispersions. Single-source vulnerability concentrates in non-EU titanium dioxide feedstock subject to carbon-border tariff exposure. Distribution runs through direct contractor channels in Southern Europe and vertically integrated retail networks in German-speaking markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from mineral silicate systems in heritage specification channels and from powder coatings in commercial facade applications.
For Market Incumbents: Harden specification authority through architect-direct relationships and captive bio-epoxy supply chains. Backward integration into epoxidized soybean oil production secures margin against petrochemical volatility. Certification investment in Blue Angel and Nordic Swan eco-labels extends product launch timelines but locks out mid-tier competitors.
For New Entrants and Emerging Players: Pursue cloud-based color-matching platform partnerships to bypass established tinting service infrastructure. Polish and Spanish contractor networks present the most penetrable channel white space. Specialist applicator direct-selling captures margin otherwise lost to conventional distribution.
For Investors and Strategic Acquirers: The market sits at a reformulation transition phase that favors manufacturers with captive bio-based resin supply and specification channel control. Long-term viability favors entities securing compliant supply chains ahead of full carbon-border implementation. Watch REACH registration deadline compliance rates as inflection indicator for competitive consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Epoxy Production | German manufacturers secure compliant supply chains ahead of EU carbon-border adjustments. |
| Architect-Direct Specification Relationships | Powder coating networks lock in commercial facade procurement decisions early in design cycles. |
| Cloud-Based Color-Matching Platform Partnership | Specialist contractors unbundle tinting from retail and concentrate purchasing power. |
| Dual Eco-Label Certification Investment | Blue Angel and Nordic Swan approvals extend launch timelines but create procurement barriers. |
| Specialist Contractor Channel Expansion | Direct specification-selling in Italy and Spain bypasses conventional retail margin erosion. |
Research Methodology
Cross-validation between primary interviews with formulation chemists, procurement leads at German housing associations, specialist contractor networks, and distribution channel partners anchors the qualitative findings. Secondary validation draws from ECHA registration databases, EU customs trade data on titanium dioxide imports, national building renovation passport frameworks, and SEC filings of listed coatings manufacturers. Bottom-up volume estimates from application segments reconcile with top-down market sizing through iterative calibration.
Calibration against historical REACH compliance timelines and carbon-border adjustment phase-in schedules shapes the projection framework across the analysis window. Segmentation dimensions include formulation chemistry, application environment, procurement channel, and technology tier. CAGRs derive from regression analysis of renovation cycle acceleration, regulatory compliance cost pass-through, and specification premium capture rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by bio-based resin startups or consolidated pigment suppliers would shift outcomes. Macroeconomic deviation in construction activity, regulatory acceleration of VOC ceilings, or breakthroughs in water-borne polyurethane durability would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Asia-Pacific Paint Thinner Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Automotive Coatings Market
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
Paints and Coatings Market
Paints & Coatings
Water Color Market
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
Europe Automotive Paints and Coatings Market
Paints & Coatings
Iran Paints and Coatings Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
Egypt Paints and Coatings Market