
 Acrylic Resins Market | 2026-2036
Acrylic Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Resins Market Intelligence
Revenue from specialized, application-specific formulations is tilting the profit pool away from commoditized, high-volume solvent-based resin sales. BASF SE leverages its extensive R&D capabilities to develop advanced waterborne systems for the automotive coatings industry. Dow competes on manufacturing scale and a broad portfolio that serves both construction and consumer goods applications. The Arkema Group differentiates through its focus on high-performance polymers and adhesives, targeting niche industrial segments.
Acrylic resins are thermoplastic or thermosetting polymers derived from acrylic acid, methacrylic acid, or their esters like methyl methacrylate. Their primary industrial purpose is to provide superior weatherability, clarity, and gloss in applications such as coatings, adhesives, and composites. Waterborne product types are gaining share over solvent-based alternatives due to environmental regulations and performance improvements. Within applications, the coatings segment remains the largest, while demand for adhesives and sealants in the construction end-use industry shows significant expansion.
The European Union's REACH regulation and US EPA rules on volatile organic compounds (VOCs) directly influence material composition and production processes. Concurrently, China's GB standards for paints and coatings set stringent performance and safety benchmarks, impacting formulations for market access. Success for manufacturers now depends on their ability to develop globally compliant yet regionally optimized resin platforms.
Market Dynamics
The transition from solvent-based to waterborne formulations, driven by stringent volatile organic compound regulations, is the central force shaping the acrylic resins market. Frameworks from the European Union's ECHA under REACH and the US EPA are compelling reformulation across the coatings and adhesives industries, accelerating innovation in polymer chemistry.
Growth Catalysts
- Regulatory Mandates:Stricter VOC limits under the EU's REACH and US EPA rules accelerate the shift to compliant waterborne acrylics in architectural coatings.
- Automotive Sector Demand:The automotive industry’s requirement for durable, weather-resistant exterior coatings provides a consistent demand stream for specialized acrylic formulations.
- Asian Infrastructure Projects:Construction growth in China and India creates concentrated demand for acrylic-based adhesives, sealants, and coatings in the building sector.
Market Restraints
- Raw Material Volatility:Price fluctuations of petrochemical-derived monomers like acrylic acid and methyl methacrylate impact production costs and margin stability for manufacturers.
- Performance Trade-offs:Some waterborne acrylics exhibit longer curing times than solvent-based systems, limiting adoption in high-speed industrial coating lines.
- Alternative Polymer Competition:Polyurethanes and epoxies present substitution threats in high-performance applications requiring superior abrasion or chemical resistance not met by acrylics.
Strategic Opportunities
- Bio-based Monomers:Developing acrylic resins from renewable feedstocks meets corporate sustainability goals and addresses demand for bio-circular materials in consumer goods.
- Hybrid Polymer Systems:Creating hybrid resins, like acrylic-polyurethane dispersions, allows for customized performance, targeting niche industrial applications with specific durability requirements.
- Green Building Materials:Formulating low-VOC adhesives and sealants that qualify for certifications like LEED opens access to the premium sustainable construction market.
Industry Challenges
- Regulatory Fragmentation:Manufacturers face complexity in developing globally compliant yet regionally optimized platforms that meet divergent standards like the EU's REACH and China's GB standards.
- Production Line Conversion:The capital expenditure required to retrofit or build new facilities for waterborne resin production presents a financial hurdle for some producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Resins Market |
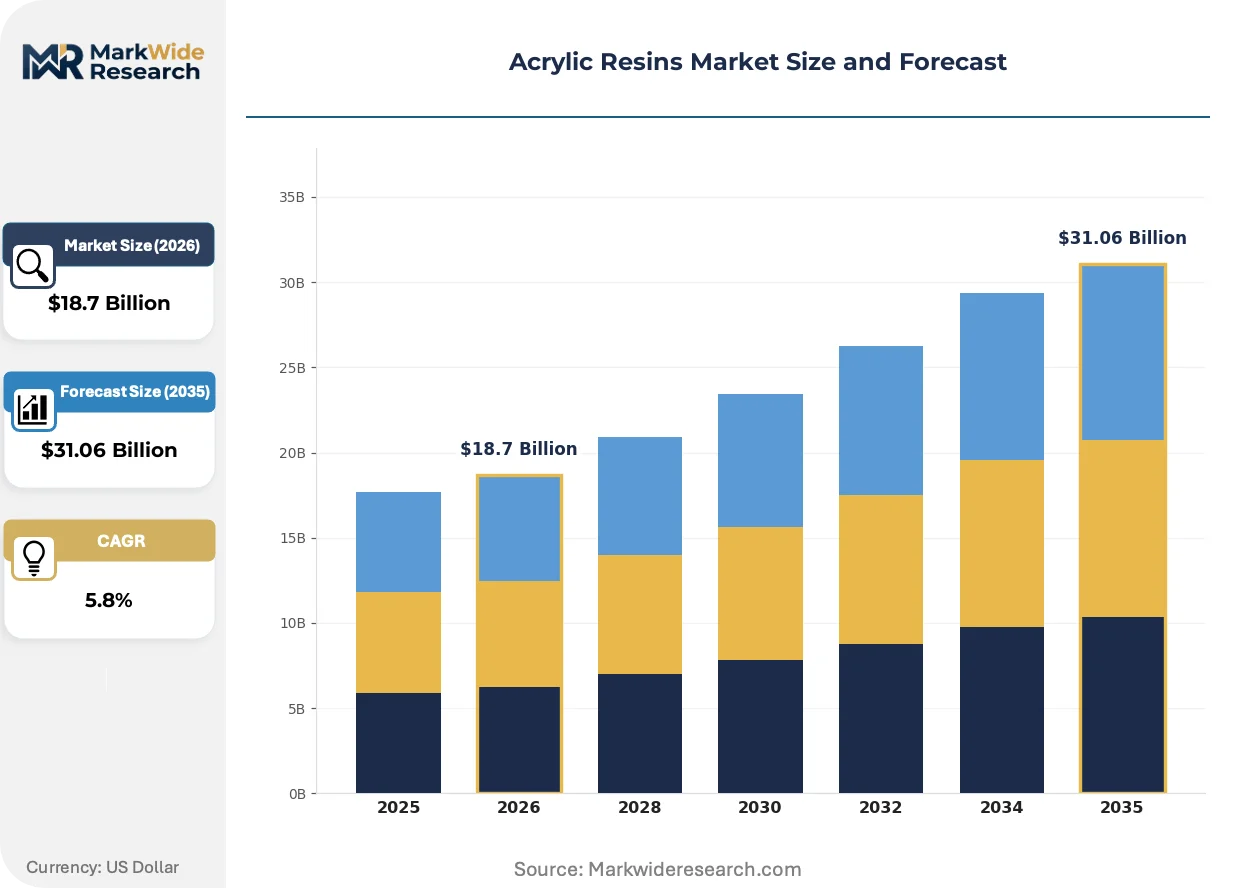
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne, Solvent-based, Emulsion, Powder End Use Industry: Automotive, Construction, Consumer Goods, Electronics Application: Coatings, Adhesives, Sealants, Composites Form: Liquid, Solid, Granular, Paste |
| Companies Covered | BASF SE, Dow, Arkema Group, Mitsubishi Chemical Group Corporation, Sumitomo Chemical Co., Ltd., DIC Corporation, Evonik Industries AG, Nippon Shokubai Co., Ltd., Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Resins Market Strategic Shifts & Innovations
Innovation in the acrylic resins market is driven by the need to balance regulatory compliance with end-user performance demands. This dynamic is pushing development toward more specialized, functional polymers that can replace traditional systems without compromising quality or durability in application.
Advanced waterborne acrylic systems are engineered to deliver high-performance characteristics with minimal volatile organic compound emissions. The automotive and architectural coatings industries are steadily adopting these new formulations to meet environmental mandates. Consequently, the market is migrating from a reliance on traditional solvent-based resins toward these more sophisticated, compliant waterborne platforms, compressing the value of older technologies.
China's national GB standards for paints and coatings establish stringent performance and safety benchmarks for market access. These regulations go beyond VOCs, setting specific limits on heavy metals and other hazardous substances, directly influencing resin composition. As a result, the coatings segment is most affected, forcing global manufacturers to develop specific formulations to comply with these rules for the vast Chinese market.
End-users are increasingly specifying application-specific formulations backed by performance data rather than purchasing bulk commodity resins. This behavioral change moves the basis of competition from pure price-per-kilogram to total applied cost and certified performance, disrupting traditional sales channels. The shift is most visible within the electronics and medical device sectors, where material qualification is a critical procurement requirement.
Acrylic Resins Market Segmentation
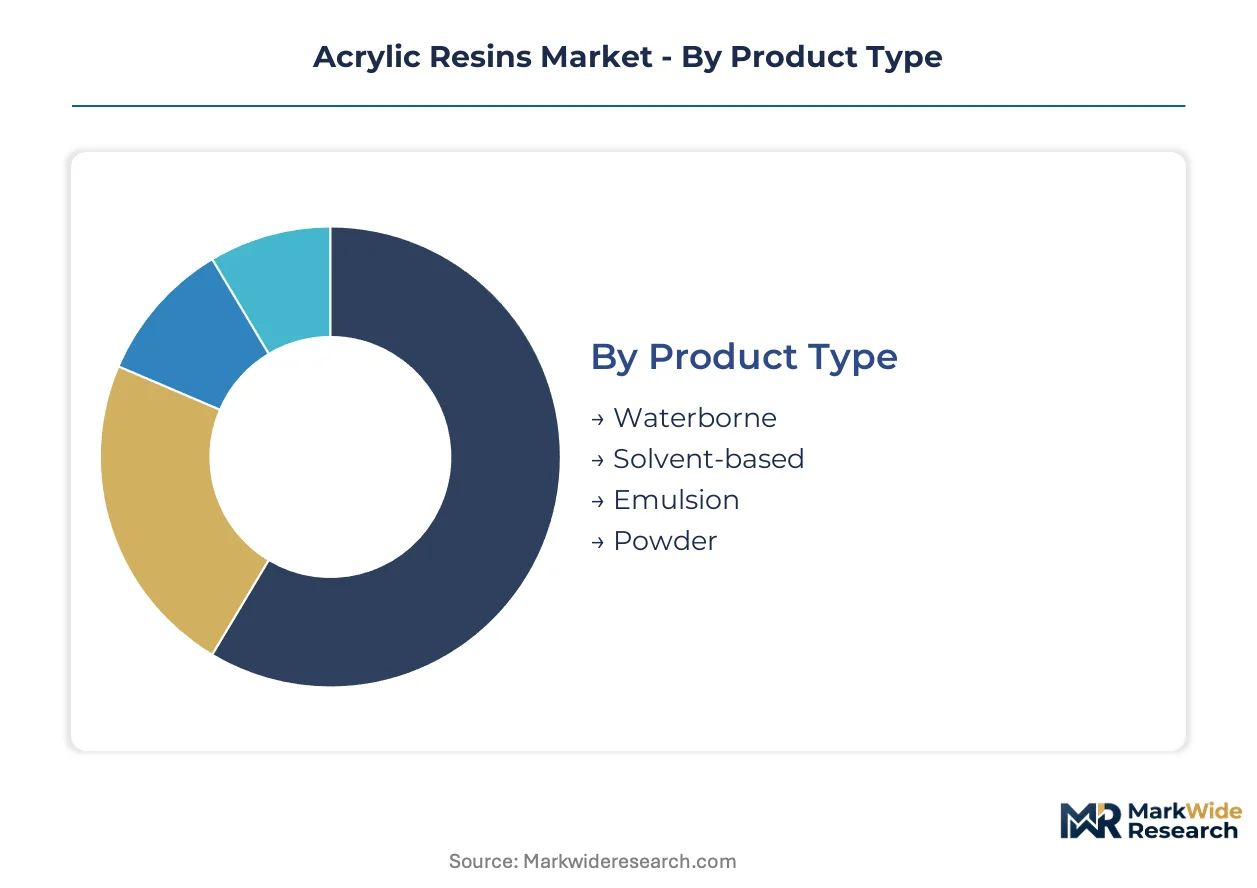
Understanding the acrylic resins market through its segmentation reveals the diverse applications and technological shifts influencing demand. This granular breakdown aids in identifying specific growth pockets and areas of innovation, particularly as regulatory pressures reshape product formulations and end-use preferences across various industries.
Product Type:
The spectrum of product types addresses varied performance needs, from traditional solvent-based systems to environmentally compliant waterborne solutions.
- Waterborne:These resins are dispersed in water, offering low volatile organic compound (VOC) emissions, making them compliant with stringent environmental regulations like the EU's REACH and US EPA rules. Demand is concentrating in architectural and automotive coatings due to performance improvements and regulatory mandates.
- Solvent-based:These acrylics are dissolved in organic solvents, historically valued for their fast drying times and superior film formation in industrial applications. While facing reformulation pressures, they retain significant use in specific high-performance industrial coatings where curing speed is critical.
- Emulsion:Formed through emulsion polymerization, these resins are stable dispersions of polymer particles in water, widely used in paints, coatings, and adhesives for their versatility and cost-effectiveness.
- Powder:Applied as dry powders and cured with heat, these resins offer excellent durability, chemical resistance, and zero VOCs, primarily utilized in protective coatings for metal substrates and appliances.
Established volume favors Solvent-based systems; emerging adoption favors Waterborne formulations.
End Use Industry:
Acrylic resins serve a broad range of end-use industries, each with distinct material specifications and performance requirements for durability and aesthetics.
- Automotive:This sector demands high-performance acrylic coatings for exterior finishes, offering superior weatherability, gloss retention, and scratch resistance to protect vehicle surfaces. The requirement for durable, weather-resistant exterior coatings provides a consistent demand stream for specialized acrylic formulations.
- Construction:Acrylics are integral to this industry for adhesives, sealants, and coatings, providing weather protection, bonding strength, and aesthetic finishes for buildings and infrastructure projects. Construction growth in China and India creates concentrated demand for these materials.
- Consumer Goods:Acrylic resins find use in various consumer products, including appliance coatings, packaging, and personal care items, valued for their clarity, gloss, and protective properties.
- Electronics:In electronics, acrylics are used for potting compounds, conformal coatings, and display components, offering electrical insulation, moisture resistance, and optical clarity for sensitive devices.
The automotive sector drives innovation in specialized formulations; construction projects create substantial volume demand.
Application:
Acrylic resins are applied across multiple functions, each leveraging the polymer's inherent characteristics for specific performance outcomes.
- Coatings:This application segment utilizes acrylics for their excellent weatherability, colorfastness, and gloss, forming protective and decorative layers on various substrates. The coatings segment remains the largest end-use for acrylic resins globally.
- Adhesives:Acrylic adhesives offer strong bonding, good cohesion, and resistance to environmental factors, making them suitable for diverse joining tasks in construction and consumer goods. Demand for adhesives and sealants in the construction end-use industry shows significant expansion.
- Sealants:Acrylic sealants provide flexibility, adhesion, and weather resistance, effectively filling gaps and preventing moisture ingress in building envelopes and automotive assemblies.
- Composites:In composites, acrylic resins act as matrices, binding reinforcement fibers to create lightweight yet strong materials for aerospace, marine, and automotive components.
Performance superiority defines the coatings application; bonding strength characterizes the adhesives segment.
Form:
The physical form of acrylic resins dictates their processing and application methods, ranging from ready-to-use liquids to solid granules requiring further processing.
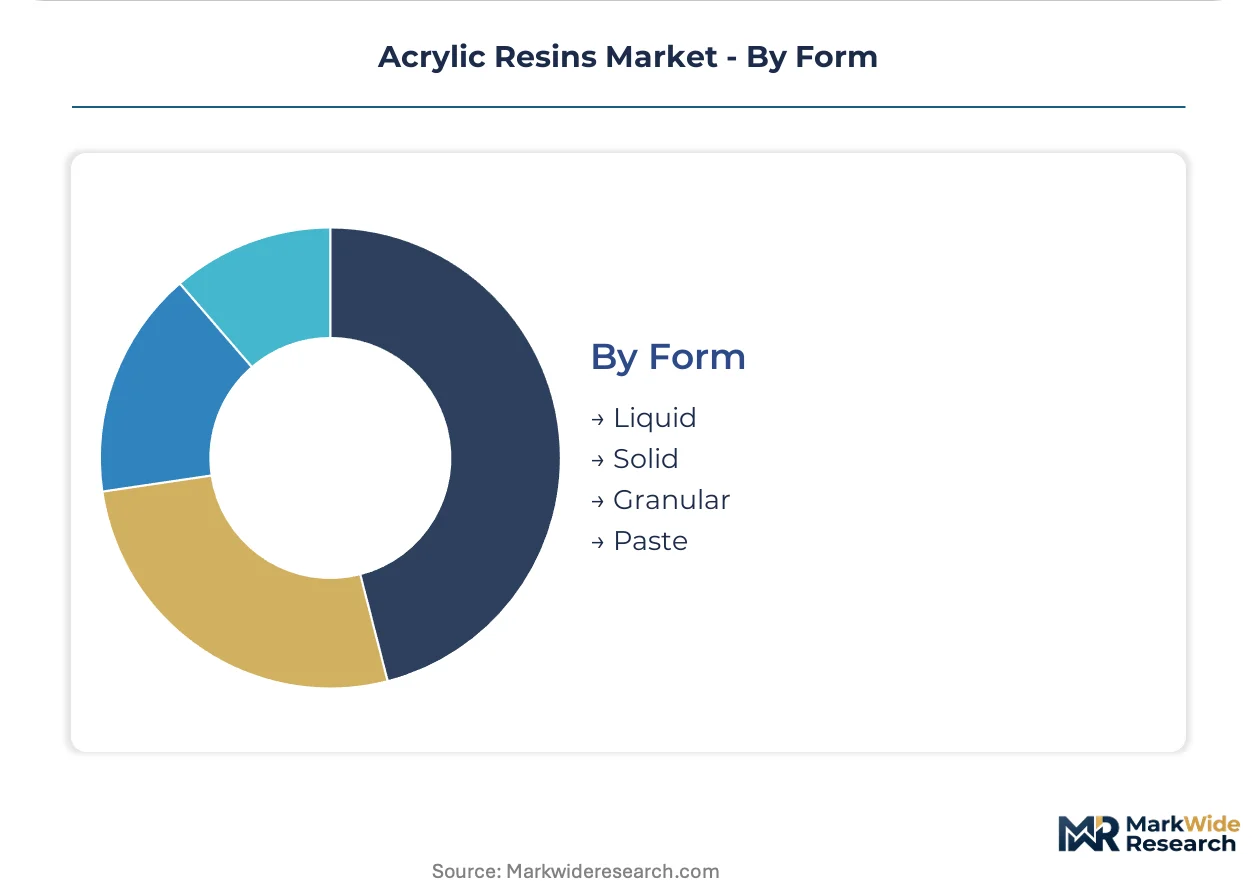
- Liquid:Liquid acrylic resins are typically supplied as emulsions, solutions, or dispersions, offering ease of handling and direct application in coatings, adhesives, and sealants. This form allows for convenient mixing and application in industrial and architectural settings.
- Solid:Solid acrylic resins, often in bead or pellet form, are used in powder coatings, molding compounds, and as raw materials for solvent-based systems, requiring melting or dissolution before application. Powder coatings represent a key use case for solid acrylics due to their zero-VOC nature.
- Granular:Granular acrylics are similar to solid forms but often refer to fine particles used in specific molding or extrusion processes, providing consistent flow properties for manufacturing.
- Paste:Paste-form acrylics are thicker formulations, frequently employed in high-build coatings, sealants, and putties where specific rheology and gap-filling capabilities are required.
Ease of application defines Liquid forms; specialized manufacturing processes utilize Solid and Granular acrylics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for acrylic resins varies significantly by geography, reflecting diverse industrial priorities and regulatory landscapes. While some regions prioritize high-performance automotive coatings, others drive demand through extensive construction projects. Environmental compliance also dictates product formulation preferences across global markets.
United States
Demand for waterborne acrylics in the United States stems from architectural coatings and automotive refinish applications. US EPA rules on volatile organic compounds compel manufacturers to innovate low-VOC formulations. The automotive manufacturing hubs in Michigan and the Southeast drive demand for durable exterior finishes.
Germany
The automotive sector in Germany consistently demands advanced acrylic formulations for exterior finishes and interior components. European Union's REACH regulation dictates strict material composition and production processes. Chemical production clusters along the Rhine-Main region develop specialized resin platforms.
China
Construction growth in China generates substantial demand for acrylic-based adhesives, sealants, and coatings. China's GB standards for paints and coatings set stringent performance and safety benchmarks for market access. Industrial parks in the Yangtze River Delta concentrate significant consumption for construction and electronics.
India
Infrastructure projects and a growing automotive industry fuel the need for acrylic resins in India. The country's environmental policies increasingly promote greener building materials. Major industrial corridors like the Delhi-Mumbai Industrial Corridor see concentrated application in building and automotive sectors.
Japan
The electronics and automotive industries in Japan require high-performance acrylics for optical clarity and protective coatings. Japan's METI promotes material innovations for sustainable manufacturing. Industrial zones around Tokyo and Nagoya leverage specialized acrylics for advanced electronics and vehicle production.
Acrylic Resins Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure for acrylic resins. The market segments into global chemical conglomerates, specialized high-performance polymer producers, and regional volume manufacturers. These archetypes engage in portfolio diversification and strategic partnerships to navigate evolving regulatory demands and expand market reach.
Global chemical conglomerates like BASF SE represent the tier focused on extensive research and development capabilities, particularly for advanced waterborne systems that meet stringent environmental mandates. Dow, a significant player, exemplifies the scale-driven approach, leveraging its broad portfolio across construction and consumer goods applications to maintain wide market penetration. The Arkema Group sits within the specialized high-performance polymer producer segment, targeting niche industrial applications with differentiated adhesives and advanced material solutions that offer superior performance characteristics.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Arkema Group |
| Mitsubishi Chemical Group Corporation |
| Sumitomo Chemical Co., Ltd. |
| DIC Corporation |
| Evonik Industries AG |
| Nippon Shokubai Co., Ltd. |
| Covestro AG |
Cost & Logistics Intelligence
China's industrial parks, particularly those in the Yangtze River Delta, concentrate significant acrylic resin production capacity, influencing global supply and downstream pricing. This concentration allows for economies of scale, impacting cost structures for manufacturers worldwide.
Pricing Analysis
Long-term offtake agreements define pricing for high-volume acrylic resin applications, while spot market transactions govern smaller, more immediate needs. Price differentiation stems from specialized formulation quality, compliance with certifications like LEED, and the volume scale of procurement. Pricing pressure intensifies due to volatile petrochemical-derived monomer costs, impacting margin stability for manufacturers. Construction end-users demonstrate higher price sensitivity compared to the electronics and medical device sectors, which prioritize performance and material qualification.
Supply Chain Analysis
Commodity price volatility in petrochemical-derived monomers like acrylic acid and methyl methacrylate represents a significant supply chain risk for acrylic resin manufacturers. Geographic supply concentrates in China, Germany, and the United States, influencing global availability. These regions rely on complex logistics networks to transport raw materials and finished products. Distribution runs through direct channels for large industrial clients and specialized distributors serving niche application segments, ensuring tailored product delivery and technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acrylic resins market presents a fragmentation opportunity, driven by end-users increasingly specifying application-specific formulations backed by performance data. This shift creates distinct niches for specialized product development and market penetration.
For Market Incumbents:Build regulatory compliance moats by heavily investing in advanced waterborne systems research and development. Incumbents must optimize production processes to meet stringent VOC regulations like the EU's REACH and US EPA rules, mitigating the threat of non-compliant formulations. Consolidate market share through strategic partnerships that expand waterborne manufacturing capacity in key regions. Develop globally compliant yet regionally optimized resin platforms to navigate diverse regulatory landscapes effectively.
For New Entrants and Emerging Players:Establish a beachhead in the bio-based monomer segment, addressing demand for sustainable materials in consumer goods. Target the green building materials market with low-VOC adhesives and sealants, a highly penetrable segment due to increasing certification requirements like LEED. Differentiate through innovative hybrid polymer systems, offering customized performance for niche industrial applications. A go-to-market strategy centered on environmental certifications will attract discerning buyers.
For Investors and Strategic Acquirers:Long-term, this sits as a regulatory-driven transition play because environmental mandates continue to reshape product formulations toward waterborne systems. Seek acquisition targets among specialized high-performance polymer producers with proven waterborne acrylic technology. These companies offer differentiated solutions for niche industrial applications. The signal to watch is the accelerating adoption rate of advanced waterborne systems in high-speed industrial coating lines, indicating broader market acceptance and performance parity.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Waterborne Acrylics | Manufacturers increase production of compliant waterborne formulations to meet regulatory-driven demand in architectural coatings. |
| Bio-based Monomer R&D | Chemical companies develop renewable feedstocks for acrylic resins, aligning with corporate sustainability goals. |
| Hybrid Polymer System Development | Producers create acrylic-polyurethane dispersions, customizing performance for niche industrial applications. |
| LEED Certification for Adhesives | Formulators target the green building market, gaining access to premium sustainable construction projects. |
| Global Regulatory Compliance Platform | Companies develop resin platforms that meet diverse standards like EU REACH and China's GB standards. |
Research Approach
Operator-level perspectives from plant managers, procurement leads at automotive OEMs, and technical R&D directors anchored the qualitative base of this study. Primary interviews offered granular insights, cross-referenced with extensive secondary research including customs data, chemical industry reports, and regulatory body publications. This approach ensured bottom-up and top-down triangulation for robust data validation.
Scenario-bracketing informed quantitative modeling, establishing a plausible range for market evolution across the analysis window. The analytical framework integrated segmentation dimensions including product type, end-use industry, application, and form. Compound annual growth rates were derived from historical trends and projected impacts of evolving VOC limits and raw material price forecasts. This ensured dynamic market projection over the projection horizon.
Sensitivities concentrate around unforeseen regulatory shifts, sustained raw material price volatility, and disruptive technological advancements. Forecasts reflect assumptions documented at the time of publication, acknowledging these inherent uncertainties. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
Resin Glue Market
Polymers & Resins
Vinyl Acetate Monomer (VAM) Market
Polymers & Resins
Highly Reactive Polyisobutylene (HR-PIB) Market
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Bio-Based PU Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Acrylic Monomers Market
Polymers & Resins
Asia-Pacific Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Circular Polymers Market