
 GCC Paints and Coatings Market | 2026-2036
GCC Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Paints and Coatings Market Foresight
ISO 12944 corrosion-protection certification is bifurcating the competitive landscape into qualified and non-qualified suppliers across marine and industrial segments. Jotun A/S leverages its marine coatings pedigree to dominate port and offshore maintenance cycles in the Arabian Gulf. National Paints Factory anchors regional distribution through manufacturing scale in the UAE and Saudi Arabia. Akzo Nobel NV differentiates via waterborne technology leadership for architectural specifications in green-certified towers.
GCC paints and coatings comprise resin-binder systems, pigments, solvents, and additives formulated to protect substrates from corrosion, weathering, and chemical exposure, with film thickness typically ranging from 25 to 500 microns depending on end-use severity. Architectural coatings constitute the volume base across residential and commercial construction, while protective coatings command premium pricing for infrastructure and energy assets exposed to extreme heat and saline atmospheres. Powder coatings are gaining share in metal fabrication and machinery applications as Saudi Arabia and the UAE tighten VOC emission controls on solventborne alternatives.
Saudi Standards, Metrology and Quality Organization (SASO) and the Emirates Authority for Standardization and Metrology (ESMA) enforce VOC limits and product labeling that reshape formulation requirements for suppliers seeking market access. The UAE's Green Building Regulations and Dubai Municipality's Al Safat rating system mandate low-emitting interior coatings, redirecting procurement toward certified waterborne systems. Stakeholders must monitor how Saudi Arabia's Saudi Green Initiative and evolving building codes will tighten environmental compliance timelines for imported and locally manufactured coating portfolios.
Market Dynamics
ISO 12944 certification requirements are restructuring competitive access across marine and industrial protective coatings, forcing formulation upgrades and supplier qualification investments that favor technically credentialed manufacturers over commodity distributors.
Growth Catalysts
- Saudi megaproject pipelines:Residential and infrastructure construction across Riyadh and Neom is expanding procurement volumes for decorative and protective coating systems.
- Dubai's Al Safat green building mandates:Low-VOC architectural coatings are now compulsory for commercial developments, redirecting specification toward certified waterborne technologies.
- Powder coating substitution:Metal fabrication and machinery sectors are adopting solvent-free alternatives as VOC emission controls tighten in Saudi Arabia and the UAE.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost fluctuations compress margin stability for decorative coating formulations.
- Specialty resin import dependence:Epoxy and polyurethane binder supply concentrates in Asian manufacturing hubs, exposing GCC blenders to freight and currency risks.
- Extreme climate performance thresholds:Thermal cycling and saline atmospheric exposure demand formulation complexity that extends R&D timelines beyond standard architectural coating development cycles.
Strategic Opportunities
- Oman and Bahrain infrastructure gaps:Underpenetrated protective coating demand in industrial zones and port facilities offers first-mover positioning for qualified suppliers.
- Saudi Green Initiative alignment:Carbon-neutral construction incentives will expand specification windows for bio-based and recycled-content coating systems.
- Digital specification platforms:Architect and contractor procurement is migrating to centralized e-procurement portals that reduce distributor intermediation.
Industry Challenges
- ISO 12944 auditor scarcity:Qualified corrosion-protection certification assessors are concentrated in European headquarters, delaying Middle East project approvals.
- Legacy solventborne inventory stranding:Distributors face write-downs as ESMA and SASO enforcement windows compress transition timelines for non-compliant stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Paints and Coatings Market |
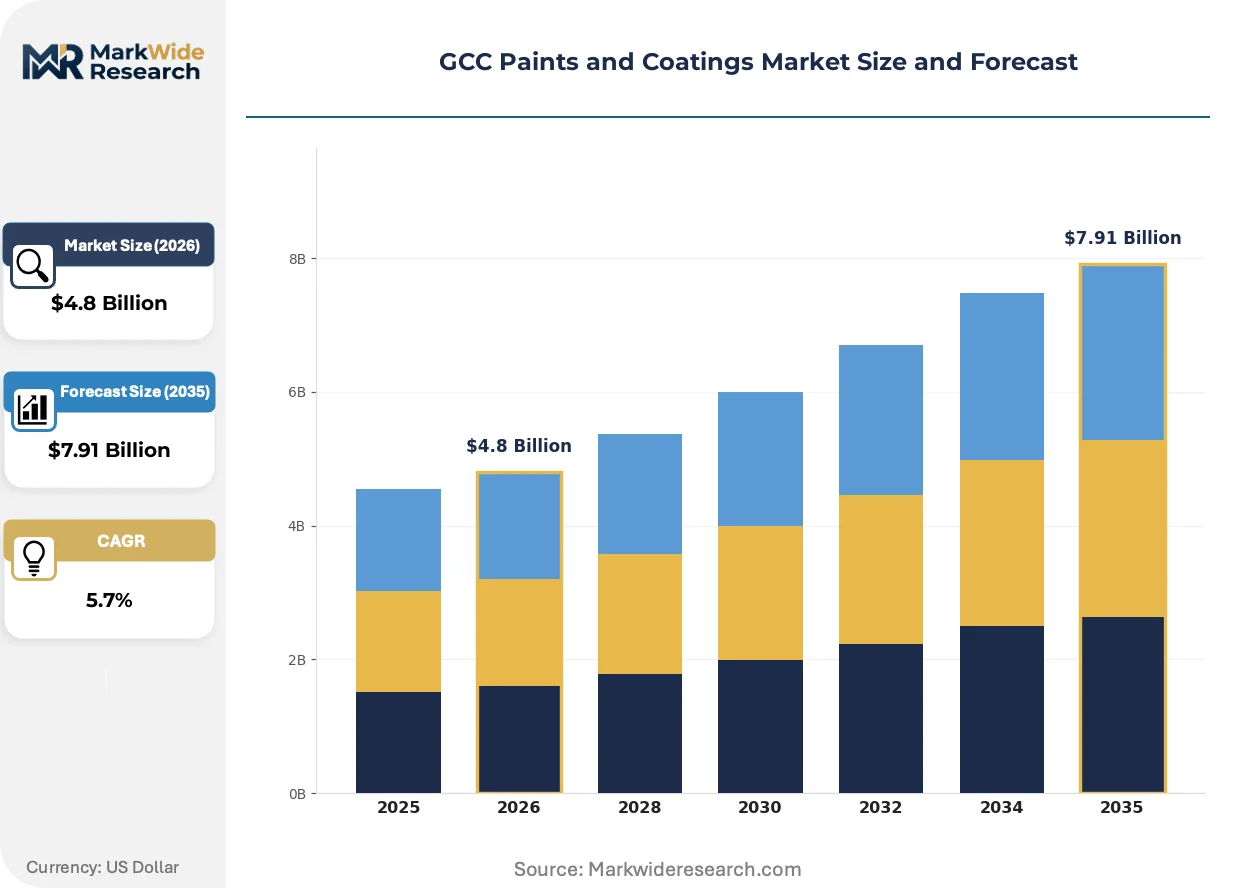
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural Coatings, Protective Coatings, Automotive Coatings, Powder Coatings, Industrial Coatings Technology: Waterborne, Solventborne, UV Curable, High Solid, Epoxy Application: Infrastructure, Marine Vessels, Aviation, Machinery, Transportation Equipment End User: Construction Firms, Shipbuilders, Aerospace Manufacturers, Heavy Equipment Producers, Metal Fabricators |
| Companies Covered | RPM International Inc., Berger Paints Emirates Ltd, Jotun A/S, Ritver Paints and Coating, National Paints Factory, PPG Industries Inc., Jazeera Paints, Beckers Group, Akzo Nobel NV, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Paints and Coatings Market Shifts & Advancements
Formulation chemistry is pivoting toward waterborne and high-solids systems while digital tools reshape how specifications reach contractors. Three developments are actively restructuring competitive positioning.
Self-healing microcapsule technology is decomposing traditional maintenance-cycle economics in offshore and marine applications. Platform operators in the Arabian Gulf are piloting autonomous repair coatings that extend protection intervals from five to fifteen years. This capability is compressing the addressable market for conventional touch-up and recoating services.
ESMA's 2024 VOC limit enforcement is eliminating solventborne architectural coatings from UAE commercial specifications. Manufacturers are accelerating waterborne acrylic and alkyd platform investments to maintain Dubai Municipality project access. Interior coating categories face the steepest compliance cost increases as certification testing expands.
Contractor purchasing consortia are consolidating specification influence across Saudi Arabia's residential construction sector. Volume aggregation platforms are displacing traditional distributor relationships for mid-scale developers in Riyadh and Jeddah. This behavioral shift is most pronounced in standard-grade decorative coatings where product differentiation is minimal.
GCC Paints and Coatings Market Segmentation
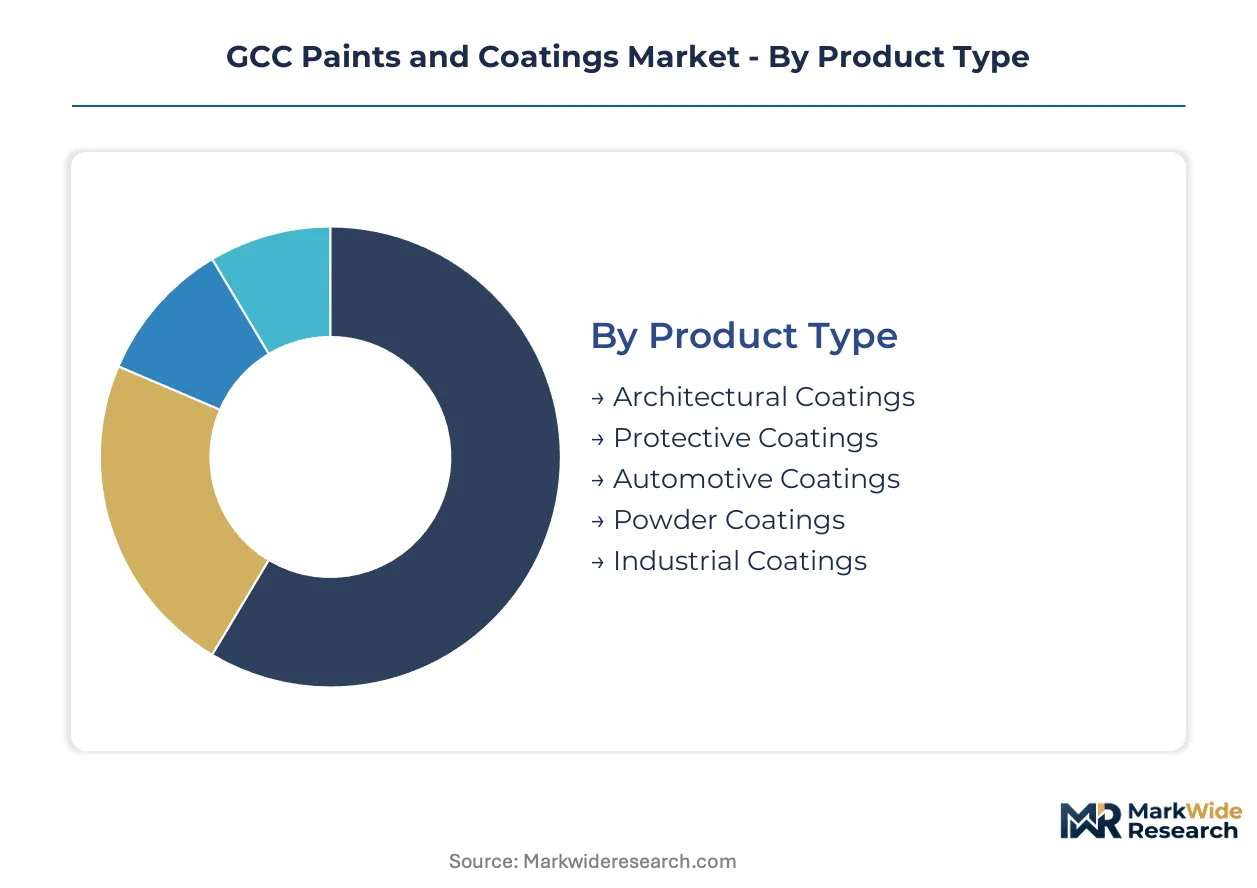
Segmentation in the GCC paints and coatings market reveals how regulatory pressure and end-use severity reshape procurement priorities. Product type and technology splits expose which formulations face obsolescence versus expansion under tightening VOC regimes.
Product Type:
Waterborne substitution pressure is most acute in decorative segments where consumer exposure risk drives regulatory speed, while industrial protective grades resist displacement due to performance irreplaceability.
- Architectural Coatings:Acrylic and alkyd resin systems formulated for interior and exterior building surfaces. Demand concentrates in Saudi Arabia's residential construction pipeline, where Riyadh and Jeddah developers specify certified low-VOC systems for SASO compliance. ESMA's enforcement windows are accelerating waterborne platform adoption.
- Protective Coatings:Epoxy and polyurethane binder systems engineered for corrosion protection in extreme saline and thermal cycling environments. Procurement concentrates across Saudi Arabia's energy infrastructure and UAE port facilities, where ISO 12944 certification mandates filter supplier pools.
- Automotive Coatings:Basecoat-clearcoat systems for OEM and refinish applications.
- Powder Coatings:Solvent-free thermoset formulations for metal substrate finishing.
- Industrial Coatings:High-performance systems for manufacturing equipment and process vessels.
Architectural coatings anchor the volume base while powder coatings gain share at the steepest rate.
Technology:
Cost tier stratification separates premium certified systems from commodity formulations facing margin compression.
- Waterborne:Acrylic and polyurethane dispersions with VOC content below regulatory thresholds. Dubai Municipality's Al Safat rating system mandates these systems for commercial interior specifications, redirecting procurement toward certified suppliers.
- Solventborne:Traditional alkyd and nitrocellulose systems with higher solids and VOC levels. ESMA's enforcement is eliminating these from UAE commercial specifications, stranding distributor inventory.
- UV Curable:Photoinitiator-activated systems for rapid-cure industrial finishing.
- High Solid:Reduced-solvent formulations bridging performance and compliance requirements.
- Epoxy:Two-component thermoset systems for chemical and abrasion resistance.
Waterborne technology commands the largest specification share while UV curable systems expand most quickly in industrial automation lines.
Application:
Geographic concentration of end-use severity drives formulation complexity requirements.
- Infrastructure:Bridge, tunnel, and utility coating systems exposed to thermal cycling and saline atmospheres. Saudi Arabia's megaproject pipeline dominates procurement volumes, where Neom and Riyadh developments specify extended durability warranties.
- Marine Vessels:Hull and superstructure coatings for corrosion and biofouling protection. Arabian Gulf port operators and offshore platform maintenance cycles concentrate demand for self-healing and extended-interval systems.
- Aviation:Aerodynamic and protective finishes for commercial and military aircraft.
- Machinery:Industrial equipment coatings for chemical and abrasion resistance.
- Transportation Equipment:Rail and commercial vehicle finishing systems.
Infrastructure applications generate the largest revenue pool while marine vessel coatings demonstrate the steepest technology premium expansion.
End User:
Customer scale and specification authority determine procurement channel access.
- Construction Firms:Residential and commercial developers procuring decorative and protective systems. Saudi Arabia's contractor purchasing consortia are consolidating volume aggregation platforms, displacing traditional distributor relationships.
- Shipbuilders:Newbuild and repair yards specifying marine coating systems. Arabian Gulf port expansion projects concentrate procurement for qualified ISO 12944 suppliers.
- Aerospace Manufacturers:OEM and MRO operations for commercial aviation.
- Heavy Equipment Producers:Mining and construction machinery manufacturers.
- Metal Fabricators:Custom and batch production finishing operations.
Construction firms represent the largest customer base while shipbuilders demonstrate the fastest procurement centralization through fleet-scale maintenance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ras Al-Khair industrial port complex underwrites Saudi Arabia's dominance in GCC protective coatings demand. Neom's linear city construction and Red Sea Project developments are redirecting specification volumes toward extended-durability marine and infrastructure systems.
Saudi Arabia
Neom and Riyadh residential megaprojects are expanding procurement for decorative and protective coating systems. SASO enforces VOC limits and product labeling requirements that reshape formulation standards for local and imported portfolios. Eastern Province energy infrastructure and Jubail Industrial City concentrate demand for ISO 12944-certified corrosion protection.
United Arab Emirates
Dubai commercial tower construction and Abu Dhabi cultural district developments specify low-VOC architectural systems. ESMA's 2024 VOC limit enforcement eliminates solventborne coatings from UAE commercial specifications. Dubai Municipality's Al Safat rating system mandates certified waterborne technologies for interior applications.
Qatar
Lusail City development and FIFA legacy infrastructure maintenance are sustaining protective coating procurement volumes. The country's national standardization body enforces construction material compliance that filters supplier access. Ras Laffan Industrial City petrochemical facilities concentrate demand for high-performance epoxy and polyurethane systems.
Oman
Duqm Special Economic Zone port and refinery construction are opening protective coating specification opportunities. The Sultanate's environmental regulations are tightening industrial emission controls that affect coating formulation requirements. Sohar Industrial Port and Salalah free zone infrastructure gaps offer first-mover positioning for qualified suppliers.
Kuwait
Silk City and Boubyan Island development projects are expanding architectural coating demand for residential and commercial construction. The Public Authority for Industry administers standards that affect import and local manufacturing compliance. Al-Zour refinery and South Al-Mutlaa residential city concentrate procurement for specialized protective and decorative systems.
GCC Paints and Coatings Market Competitive Landscape
Listed leaders compete with private specialists across certification credentialing and distribution scale. The market structures around three tiers: multinational coating conglomerates with marine and industrial pedigrees, regional manufacturing specialists with SASO and ESMA compliance depth, and commodity distributors facing margin compression from consolidated contractor purchasing. Strategic moves concentrate on ISO 12944 qualification investments and waterborne platform expansion to capture green building specification windows.
Among marine and industrial coating specialists, Jotun A/S and Akzo Nobel NV exemplify the certification-driven tier where technical pedigree determines project access. National Paints Factory anchors regional manufacturing scale across UAE and Saudi distribution networks. These three occupy positions that reflect the market's bifurcation between qualified suppliers commanding premium pricing and non-qualified competitors facing regulatory exclusion.
| Leading Market Players |
|---|
| RPM International Inc. |
| Berger Paints Emirates Ltd |
| Jotun A/S |
| Ritver Paints and Coating |
| National Paints Factory |
| PPG Industries Inc. |
| Jazeera Paints |
| Beckers Group |
| Akzo Nobel NV |
| Others |
Supply & Pricing Matrix
Waterborne resin substitution for solventborne alkyd systems simultaneously relocates supply geography toward Asian manufacturing hubs and compresses margin structures for GCC blenders dependent on imported specialty binders. This input transition amplifies price volatility exposure while rewarding vertically integrated suppliers with captive formulation capabilities.
Pricing Analysis
Volume-discount tiering structures separate ISO 12944-certified protective coating suppliers from commodity architectural distributors. Price differentiation centers on certification grade and after-sales technical service bundling. Pricing pressure stems from titanium dioxide feedstock volatility compressing decorative coating margins. Contractor purchasing consortia in Saudi Arabia demonstrate highest price sensitivity, while offshore platform operators accept premium positioning for extended-interval marine systems.
Supply Chain Analysis
Strait of Hormuz transit underwrites epoxy and polyurethane resin flows from South Korea, China, and Japan to GCC formulation plants. Raw material portfolios draw from titanium dioxide feedstock, acrylic monomer streams, and corrosion-inhibiting pigment concentrates. Single-source vulnerability concentrates in specialty resin supply where qualified alternatives face extended qualification timelines. Distribution runs through manufacturer-direct specifications for megaprojects and regional distributor networks for maintenance-cycle procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Saudi contractor purchasing consortia and digital procurement platforms, fragmenting traditional distributor intermediation and compressing margin capture for non-integrated suppliers.
For Market Incumbents: Fortify ISO 12944 certification depth to defend against emerging technical specialists from European marine coating pedigrees. Prioritize backward integration into waterborne resin supply through joint ventures with Asian manufacturing partners. Channel control investments in specification databases and architect-direct digital platforms reduce distributor dependency. For New Entrants and Emerging Players: Technical service gaps in offshore platform maintenance cycles offer white-space positioning where incumbent marine specialists concentrate on newbuild specifications. Oman and Bahrain industrial zone protective coating demand remains underpenetrated by qualified suppliers. Pursue fleet-scale maintenance contracts with Arabian Gulf port operators as anchor revenue before expanding to specification-driven newbuild procurement. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap regional manufacturers with SASO and ESMA compliance infrastructure already operational. Long-term viability favors suppliers with waterborne platform scale and marine certification pedigree. Watch for Saudi Green Initiative procurement rulemaking as inflection signal for bio-based coating specification windows.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 12944 Certification Investment | Qualification barriers filter supplier pools for Neom and Eastern Province energy infrastructure. |
| Waterborne Platform Expansion | Dubai Municipality Al Safat mandates eliminate solventborne alternatives from commercial specifications. |
| Backward Integration into Resin Supply | Captive binder production insulates GCC blenders from Asian freight and currency volatility. |
| Digital Specification Platform Development | Architect-direct procurement reduces distributor intermediation in Saudi residential construction. |
| Marine Maintenance Contract Consolidation | Fleet-scale agreements with Arabian Gulf port operators compress competitor access to platform operators. |
Research Methodology
Cross-validation between primary interviews with coating formulators, procurement leads at Saudi construction consortia, marine maintenance superintendents, and ESMA regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from SASO technical regulations, Dubai Municipality building code disclosures, customs trade data on resin imports, and SEC filings of listed coating manufacturers. Bottom-up demand modeling triangulates against top-down market sizing across the analysis window.
Sensitivity analysis tests volume and value outputs against segmentation dimensions including technology type, end-use severity grade, and regional regulatory cluster. CAGRs derive from regression analysis of historical procurement patterns and projected megaproject pipeline commitments. Forecast inputs incorporate VOC compliance timeline assumptions and marine coating maintenance cycle interval extensions from self-healing technology pilots.
Forecasts assume regulatory continuity in SASO and ESMA enforcement regimes; material policy shifts in Saudi Green Initiative implementation timelines would require re-modeling. Practitioners should keep alternative scenarios live as titanium dioxide supply disruptions and ISO 12944 auditor availability constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Middle-East Paints and Coatings Additives Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
Refinish Paint Market
Paints & Coatings
Asia-Pacific Paint Spray Guns Market
Paints & Coatings
Bahrain Paints and Coatings Market
Paints & Coatings
Low VOC Paints and Coatings Market
Paints & Coatings
India Automotive OEM Coatings Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
Automotive Paints Market
Paints & Coatings
Water-Borne Latex Paints Market
Paints & Coatings
Paints and Coatings Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Paint Thinner Market
Paints & Coatings
Middle East and Africa Paints and Coatings Market
Paints & Coatings
US Paints and Coatings Market