
 Low VOC Paint Market | 2026-2036
Low VOC Paint Market Size, Share, and Industry Trends Forecast 2026-2036
Low VOC Paint Market Outlook
Buyer concentration in the institutional segment is consolidating as hospital networks and school districts centralize procurement through national cooperative contracts. AkzoNobel NV leverages its European manufacturing footprint to serve these consolidated buyers with certified product lines. Sherwin-Williams Company anchors North American distribution through dedicated contractor channels. Asian Paints Ltd. competes on formulation adaptability for tropical humidity conditions.
Low VOC paint contains volatile organic compound concentrations below regulatory thresholds, typically achieved through water-based resin systems and solvent-free curing mechanisms that reduce atmospheric reactivity and indoor air contamination. Water-based formulations dominate volume while emulsion systems capture premium positioning in residential interior walls where emission standards are most stringent. Decorative coatings applications extend fastest as consumer awareness of indoor air quality intersects with aesthetic performance requirements.
EPA regulations under the National Volatile Organic Compound Emission Standards for Architectural Coatings mandate maximum VOC content by product category, while LEED v4.1 credits reward projects using paints certified by third-party emission programs. The EU Green Deal's renovation wave targets and REACH chemical restrictions compound compliance complexity for suppliers operating across jurisdictions. Stakeholders must monitor evolving state-level amendments that frequently precede federal threshold reductions.
Market Dynamics
EPA threshold reductions for architectural coatings are compressing formulation windows while LEED v4.1 credits accelerate specification migration toward third-party certified products. This regulatory tightening is forcing raw material substitution cycles faster than resin system development timelines.
Growth Catalysts
- LEED v4.1 Low-Emitting Materials Credit:Commercial builders in the United States now prioritize paints certified under CDPH v1.2 or SCS Global Services protocols to secure certification points. Hospital networks and K-12 districts have embedded these requirements into master specifications.
- German Building Energy Act (GEG) Renovation Mandates:Building renovation targets prioritize emission-controlled interior materials. Property owners in Berlin and Munich face compliance deadlines that favor low-VOC coating procurement.
- Water-based acrylic-urethane hybrid systems:These formulations deliver scrub resistance and gloss retention previously requiring solvent-borne chemistry. Residential interior wall applications in suburban North America now specify these systems as standard.
Market Restraints
- Titanium dioxide supply concentration:Pigment production clusters in China create input cost volatility for water-based formulations. Formulators face margin compression when ore processing disruptions occur.
- Cold-weather application limitations:Water-based systems require minimum substrate temperatures above 10°C for proper film formation. Northern climate construction schedules face seasonal constraints that solvent-borne alternatives avoid.
- REACH authorization timelines:ECHA scrutiny of biocidal preservatives extends registration periods for in-can protection systems. Suppliers encounter formulation lock-in while awaiting active substance approvals.
Strategic Opportunities
- India's Smart Cities Mission infrastructure:Municipal building specifications in Bangalore and Hyderabad increasingly reference low-emission materials. Local formulation adaptability for tropical humidity conditions creates first-mover positioning.
- Antimicrobial additive convergence:Silver-ion and quaternary ammonium compound integration addresses healthcare-acquired infection concerns. Hospital procurement teams now specify dual-function coating systems.
- Direct-to-contractor digital platforms:National painting contractor networks in the United States are consolidating purchasing through cooperative procurement platforms. Manufacturers bypass traditional distributor markups through these channels.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in water-based resin rheology and freeze-thaw stability commands premium compensation. Smaller manufacturers struggle to recruit against diversified chemical conglomerates.
- Multi-jurisdiction certification complexity:Products serving both EPA-regulated US markets and EU REACH jurisdictions require parallel testing protocols. Third-party laboratory capacity constraints extend time-to-market.
- Legacy substrate compatibility:Oil-based painted surfaces require specialized priming before water-based topcoat application. Contractor training gaps generate callback liability and specification reversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low VOC Paint Market |
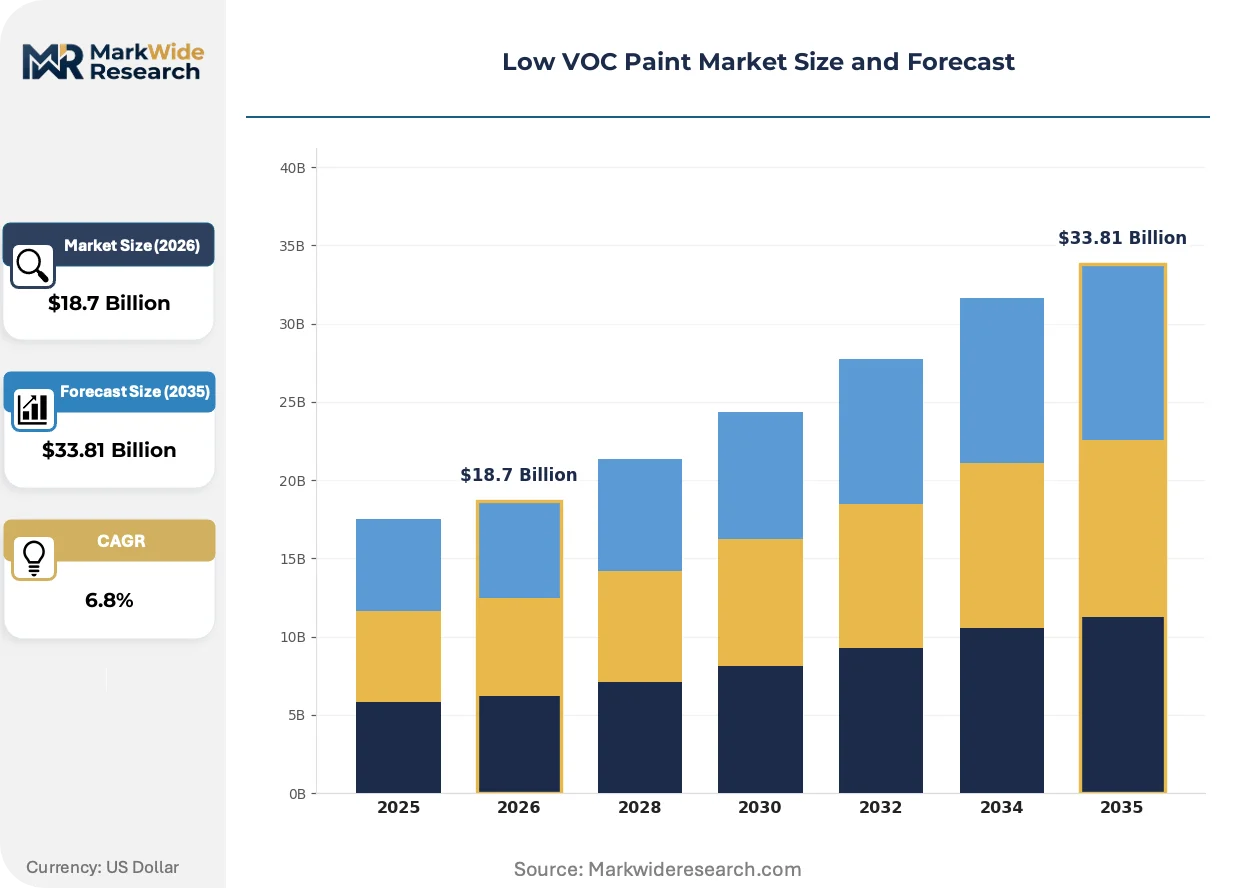
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Lacquer, Oil-based, Water-based End User: Residential, Commercial, Industrial, Institutional Application: Interior Walls, Exterior Walls, Furniture, Decorative Coatings Packaging Type: Canisters, Drums, Pails, Bottles |
| Companies Covered | AkzoNobel NV, Nippon Paint Holdings Co Ltd, BASF SE, Axalta Coating Systems Ltd., Benjamin Moore & Co., Sherwin-Williams Company, Asian Paints Ltd., Wacker Chemie AG, PPG Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low VOC Paint Market Strategic Shifts
Formulation chemistry is pivoting toward bio-based resin feedstocks while application technologies enable precision deposition that reduces material waste. These parallel developments are compressing the performance gap between sustainable and conventional coating systems.
Plant-derived alkyd resin technology is overtaking petroleum-based alternatives in trim and door applications where gloss retention and block resistance matter. Scandinavian manufacturers have scaled production of tall oil fatty acid derivatives that match solvent-borne drying characteristics. This bio-based substitution is overtaking synthetic alkyd volume in residential renovation segments where environmental claims drive purchase decisions.
EPA's proposed amendments to 40 CFR Part 59 subpart D would lower VOC ceilings for flat and non-flat coatings by 25-50 grams per liter. Architectural coating manufacturers face reformulation investments across entire product portfolios. The preemption clause in the proposal limits state-level stringency, creating regulatory clarity that favors national distribution strategies over state-by-state SKU proliferation.
Hospital facility managers now specify coating systems based on CDPH Section 01350 emission testing rather than VOC content alone. This performance-based selection criteria elevates products with superior 14-day chamber results regardless of regulatory compliance thresholds. The specification shift is most visible in California healthcare construction where OSHPD compliance intersects with institutional sustainability targets.
Low VOC Paint Market Segmentation
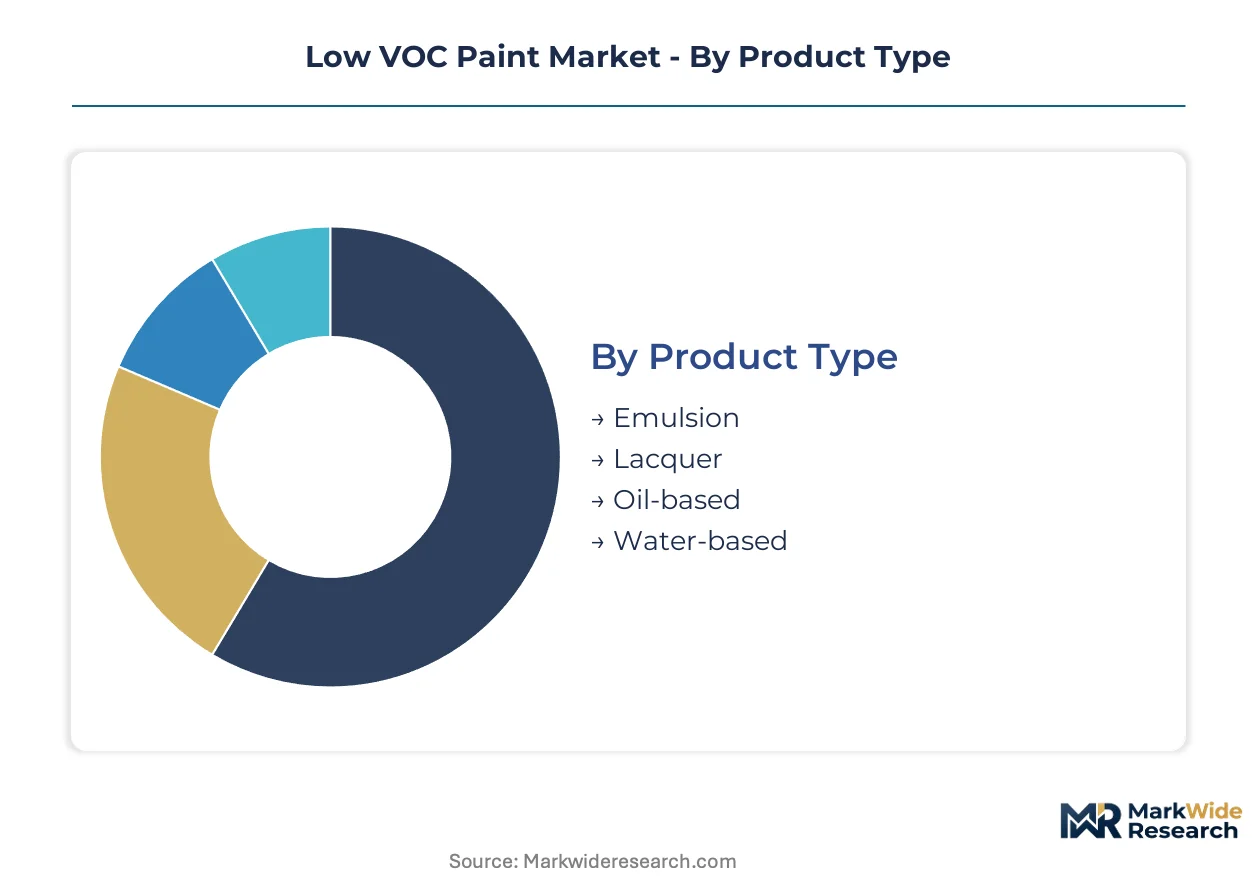
Formulation chemistry and application requirements fragment the Low VOC Paint Market into distinct procurement categories. Specification standards vary sharply between residential renovation and institutional new-build contexts. Each segmentation axis reveals divergent margin structures and compliance burdens.
Product Type:
Water-based resin systems dominate formulation development as EPA and EU thresholds tighten permissible solvent content. Hybrid chemistries now match solvent-borne performance in durability metrics previously unattainable.
- Water-based:Acrylic-urethane hybrids deliver scrub resistance above 10,000 cycles while maintaining VOC content below 50 g/L. Suburban North American residential interiors specify these systems as baseline standard. German renovation mandates under GEG accelerate specification migration from solvent alternatives.
- Emulsion:Polymer-stabilized aqueous dispersions capture premium positioning in healthcare and education construction where CDPH v1.2 certification is mandatory. Hospital networks in California and school districts in Texas centralize procurement around emulsion systems with documented 14-day chamber performance.
- Lacquer:Nitrocellulose and acrylic lacquer formulations serve furniture and trim applications requiring rapid drying and high-gloss finish. REACH authorization timelines for residual solvents complicate EU distribution.
- Oil-based:Alkyd resin systems retain niche demand in exterior applications and substrate-priming scenarios. Cold-weather workability sustures contractor preference in northern climate construction schedules.
Water-based leads on scale; emulsion leads on momentum.
End User:
Procurement concentration varies by buyer sophistication and specification authority. National cooperative contracts reshape competitive access across segments.
- Residential:Homeowner decision-making prioritizes odor minimization and same-day reoccupancy. Retail channel dominance creates price transparency that compresses premium positioning.
- Institutional:Hospital networks and K-12 districts embed LEED v4.1 and CDPH requirements into master specifications. Centralized purchasing through cooperative contracts consolidates vendor relationships around certified product lines.
- Commercial:Office and retail fit-out specifications balance emission compliance with accelerated construction schedules. Tenant improvement cycles drive recurring demand volume.
- Industrial:Manufacturing facility coatings face performance requirements for chemical resistance and abrasion tolerance that strain low-VOC formulation boundaries.
Residential commands volume concentration; institutional commands specification premium.
Application:
Surface exposure conditions dictate resin selection and certification requirements. Interior applications face stricter emission scrutiny than exterior equivalents.
- Interior Walls:Bedroom and living space coatings require 14-day chamber testing under CDPH Section 01350 protocols. LEED v4.1 Low-Emitting Materials credit eligibility drives specification toward third-party certified products.
- Decorative Coatings:Specialty finishes and texture systems capture value-added positioning in residential renovation. Consumer awareness of indoor air quality intersects with aesthetic performance requirements.
- Exterior Walls:UV resistance and hydrophobicity requirements favor silicone-modified and fluoropolymer-enhanced formulations. Climate exposure severity varies by regional construction codes.
- Furniture:Cabinet, trim, and millwork applications demand block resistance and gloss retention that bio-based alkyd technology increasingly addresses. Scandinavian tall oil derivatives match synthetic alkyd drying characteristics.
Interior walls lead on regulatory stringency; decorative coatings lead on consumer-driven expansion.
Packaging Type:
Container format aligns with application scale and distribution channel economics. Bulk formats concentrate in professional contractor segments.
- Pails:Five-gallon containers dominate professional painting contractor procurement through distributor and direct-platform channels. Volume discounts structure competitive positioning.
- Canisters:One-gallon and quart formats serve retail DIY and touch-up applications. Shelf-space competition drives packaging differentiation.
- Drums:Fifty-five-gallon bulk supply serves industrial and large commercial projects with continuous coating requirements. Logistics optimization favors regional blending facilities.
- Bottles:Aerosol and squeeze formats address spot repair and specialty craft applications. Limited volume contribution but high margin percentage.
Pails lead on revenue concentration; drums lead on volume expansion in commercial construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's renovation mandates under the Building Energy Act are compressing formulation timelines faster than Canada's emerging federal procurement standards, creating divergent compliance windows for multinational suppliers.
United States
Hospital networks in California and Texas are consolidating procurement through cooperative contracts that mandate CDPH v1.2 certification. EPA's proposed amendments to 40 CFR Part 59 would lower VOC ceilings for architectural coatings by 25-50 grams per liter. The Los Angeles-Long Beach corridor anchors specification authority for West Coast healthcare construction.
Germany
Property owners in Berlin and Munich face GEG compliance deadlines that prioritize emission-controlled interior materials. The EU Green Deal's renovation wave compounds REACH chemical restrictions for coating suppliers. The Rhine-Ruhr industrial cluster concentrates formulation R&D for water-based acrylic-urethane hybrid systems.
India
Municipal building specifications in Bangalore and Hyderabad increasingly reference low-emission materials under the Smart Cities Mission. BIS standards for architectural coatings are tightening alignment with international emission protocols. The Mumbai-Pune industrial corridor hosts manufacturing capacity serving tropical humidity formulation requirements.
China
GB standards for indoor air quality are elevating third-party certification requirements in Beijing and Shanghai commercial construction. The dual carbon policy framework is accelerating water-based resin substitution in state-funded infrastructure projects. The Yangtze River Delta concentrates pigment processing capacity that feeds regional formulation demand.
Canada
Health Canada is harmonizing VOC thresholds with EPA architectural coating standards ahead of federal green procurement expansion. Toronto and Vancouver healthcare authorities are embedding LEED v4.1 requirements into hospital construction specifications. The Ontario-Quebec corridor anchors distribution infrastructure serving institutional buyers.
Low VOC Paint Market Competitive Environment
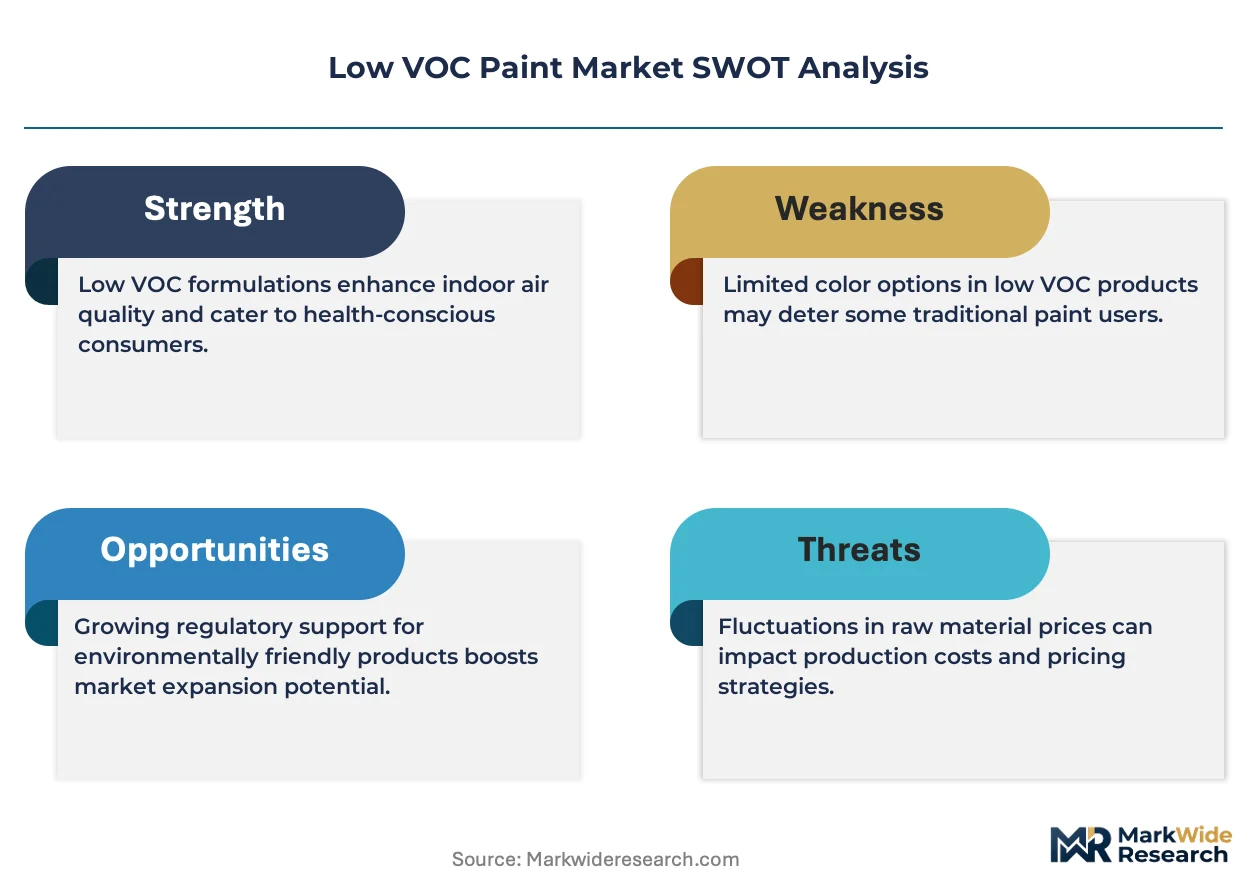
European producers anchor the premium certification tier; North American specialists hold volume positioning through contractor channel density. The vendor base stratifies across three tiers: diversified chemical conglomerates with resin backward integration, regional formulation specialists with certification depth, and private-label distributors with logistics scale. Strategic moves center on M&A for regulatory compliance capabilities and capacity expansion for water-based resin systems.
Within the diversified chemical conglomerate tier, AkzoNobel NV and BASF SE exemplify European manufacturing footprint strategies that serve consolidated institutional buyers with certified product lines. Sherwin-Williams Company occupies a position among North American specialists with dedicated contractor channel anchoring. Asian Paints Ltd. represents formulation adaptability archetypes competing on tropical climate performance requirements.
| Leading Market Players |
|---|
| AkzoNobel NV |
| Nippon Paint Holdings Co Ltd |
| BASF SE |
| Axalta Coating Systems Ltd. |
| Benjamin Moore & Co. |
| Sherwin-Williams Company |
| Asian Paints Ltd. |
| Wacker Chemie AG |
| PPG Industries Inc. |
| Others |
Value Chain & Pricing Dynamics
Backward integration into titanium dioxide feedstock anchors supply position and pricing power for water-based formulation leaders. Captive pigment sourcing insulates margin structures against ore processing disruptions concentrated in China's Yangtze River Delta.
Pricing Analysis
Capacity additions in Germany's Rhine-Ruhr cluster are reshaping price floors for acrylic-urethane hybrid systems. Three-tier pricing structure across premium CDPH-certified, standard LEED-compliant, and economy-grade residential tiers separates institutional buyers from retail DIY segments. Cost compression in economy tiers is intensifying because titanium dioxide supply volatility feeds through to water-based formulations. Hospital networks exhibit least price sensitivity while suburban renovation contractors face acute margin pressure.
Supply Chain Analysis
Direct-to-contractor digital platforms handle hyperscale professional demand while distributor networks retain retail channel control. Raw material sourcing draws from China's pigment processing cluster, Germany's specialty chemical base, and India's resin manufacturing corridor. Titanium dioxide, acrylic monomers, and bio-based alkyd precursors constitute critical input dependencies. Single-source vulnerability in Chinese ore processing creates exposure to export restriction scenarios. Distribution runs through cooperative procurement platforms for institutional buyers and traditional two-step distribution for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA's proposed 25-50 gram per liter VOC ceiling reduction functions as a regulatory compounder, forcing portfolio-wide reformulation investments that favor suppliers with captive resin capabilities.
For Market Incumbents: Anchor certification depth against emerging regional specialists by accelerating CDPH v1.2 and SCS Global Services protocol coverage across product lines. Defensive consolidation of formulation chemist talent pools in Germany and North America addresses scarcity-driven compensation inflation. Backward integration into bio-based alkyd feedstocks protects margin position as petroleum-derived alternatives face carbon accounting pressure.
For New Entrants and Emerging Players: Municipal infrastructure procurement teams in India's Smart Cities Mission represent an underserved buyer archetype with specification authority but limited vendor penetration. Tropical humidity formulation adaptability creates first-mover positioning in Bangalore and Hyderabad construction markets. Direct digital platform engagement with national painting contractor networks bypasses traditional distributor markups and accelerates volume scale.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction certification complexity exceeds internal laboratory capacity of mid-tier regional formulators. Five-to-ten year viability favors suppliers with parallel EPA and REACH compliance infrastructure. Acquisition target archetypes include emulsion system specialists with documented 14-day chamber performance and established hospital network relationships. Signal to watch: state-level VOC threshold amendments preceding federal reductions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Water-based resin production scaling in Germany addresses GEG renovation mandate demand concentration. |
| Backward Integration | Titanium dioxide captive supply insulates margin structures against Yangtze River Delta processing disruptions. |
| Green Manufacturing Transition | Bio-based tall oil alkyd scaling matches synthetic resin performance for Scandinavian renovation segments. |
| Long-term Supply Agreement | Cooperative procurement platform contracts with hospital networks lock in CDPH-certified volume commitments. |
| Joint Venture | Regional blending facilities in India's Mumbai-Pune corridor serve tropical humidity formulation requirements. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement with formulation chemists, procurement leads at hospital networks, distributor channel partners, and contractor cooperative managers combined with secondary validation against EPA regulatory filings, EU ECHA registration databases, customs trade data, and architectural coating industry association reports. Bottom-up demand modeling and top-down supply capacity assessment triangulated volume estimates.
Segment-weighting across formulation chemistry, end-user procurement concentration, application exposure conditions, and packaging format economics structured the analytical framework. CAGRs derived from regression analysis of historical regulatory threshold tightening patterns and substitution elasticity estimates. Modeled inputs included LEED v4.1 credit adoption curves, GEG renovation mandate compliance deadlines, and water-based system performance improvement trajectories.
Underlying measurement precision varies by segment; institutional and healthcare applications carry tighter precision than residential renovation due to specification documentation density. Forecasts reflect assumptions regarding regulatory implementation timelines and raw material supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Furniture Wood Coatings Market
Paints & Coatings
Global Primer Market
Paints & Coatings
Road Marking Paint Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Mosquito-Repellent Paints Market
Paints & Coatings
Saudi Arabia Paints and Coatings Market
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
Alkyd Coatings Market
Paints & Coatings
Global Decorative Paints and Coatings Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
Water-Soluble Paints Market
Paints & Coatings
Wall Putty Powder Market
Paints & Coatings
Low VOC Paints and Coatings Market
Paints & Coatings
Paint Buckets Market