
 India Architectural Coatings Market | 2026-2036
India Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
India Architectural Coatings Market Foresight
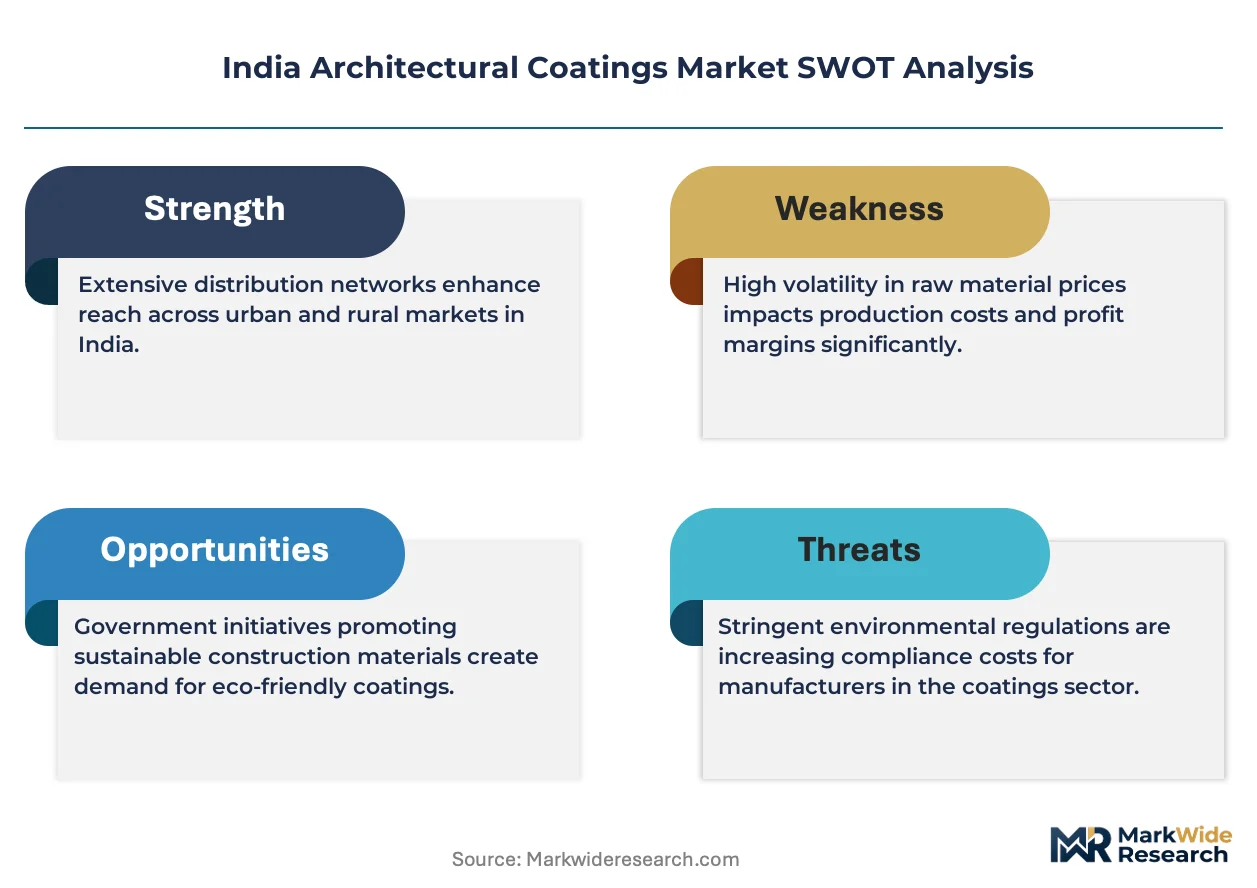
Multi-source procurement for titanium dioxide and acrylic resin is broadening as paint manufacturers diversify beyond domestic petrochemical suppliers. Asian Paints Ltd leverages backward integration into binder production to shield margin structures from raw material volatility. Berger Paints India Ltd sustains extensive dealer networks across tier-two and tier-three cities, while Indigo Paints Ltd differentiates through specialty wood coating lines that command premium positioning in southern markets.
Architectural coatings encompass decorative and protective liquid or paste formulations applied to interior and exterior building substrates, typically comprising pigments, binders, solvents or water carriers, and functional additives that cure to form adherent films with specified gloss, durability, and permeability characteristics. Emulsion water-based systems dominate volume due to regulatory pressure on solvent-borne volatile organic compound emissions, while acrylic formulations lead value generation because of superior ultraviolet resistance and color retention on concrete and plaster surfaces. The residential application segment anchors demand as government affordable housing programs and private urban redevelopment projects multiply substrate-ready square footage across Indian metropolitan corridors.
BIS mandates on lead and chromium content limits, coupled with Green Building Council India certification criteria for low-emitting interior materials, compel reformulation investments and filter non-compliant imports from regional traders. State-level real estate regulators in Maharashtra, Karnataka, and Telangana enforce project completion timelines that synchronize coating procurement cycles with construction milestones, compressing supplier lead time requirements. Stakeholders must monitor evolving state urban development authority specifications and BIS amendment drafts to anticipate mandatory VOC threshold reductions before compliance deadlines crystallize.
Market Dynamics
BIS certification mandates for lead-free formulations and low-VOC emulsion standards are redirecting manufacturer R&D spending toward water-based acrylic systems, compressing reformulation cycles and elevating compliance costs across the value chain.
Growth Catalysts
- Urban housing expansion:Residential property developers in Maharashtra and Gujarat are scaling decorative coating procurement as urban housing stock expands across metropolitan corridors.
- BIS low-VOC mandates:Regulatory pressure on solvent-borne volatile organic compound emissions accelerates emulsion water-based system adoption in interior applications.
- Acrylic resin performance:Superior ultraviolet resistance and color retention on concrete and plaster surfaces drives value generation in premium exterior segments.
Market Restraints
- Titanium dioxide cost volatility:Multi-source procurement broadens as paint manufacturers diversify beyond domestic petrochemical suppliers to shield input cost exposure.
- Western and southern demand concentration:Geographic clustering in Bangalore and Hyderabad creates regional supply-demand imbalances and logistics friction.
- Reformulation capex intensity:Green Building Council India certification criteria for low-emitting interior materials compel capital-intensive facility upgrades.
Strategic Opportunities
- Tier-two and tier-three dealer networks:Extensive distribution infrastructure in secondary cities captures underserved residential renovation demand.
- Specialty wood coating premium positioning:Differentiated product lines command margin expansion in southern markets with established furniture manufacturing clusters.
- Backward integration into binder production:In-house production of acrylic resins shields margin structures from raw material price swings and supply interruptions.
Industry Challenges
- Compressed supplier lead times:State-level real estate regulators in Maharashtra, Karnataka, and Telangana enforce project completion timelines that synchronize coating procurement cycles with construction milestones.
- Evolving BIS amendment tracking:Stakeholders must monitor amendment drafts to anticipate mandatory VOC threshold reductions before compliance deadlines crystallize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Architectural Coatings Market |
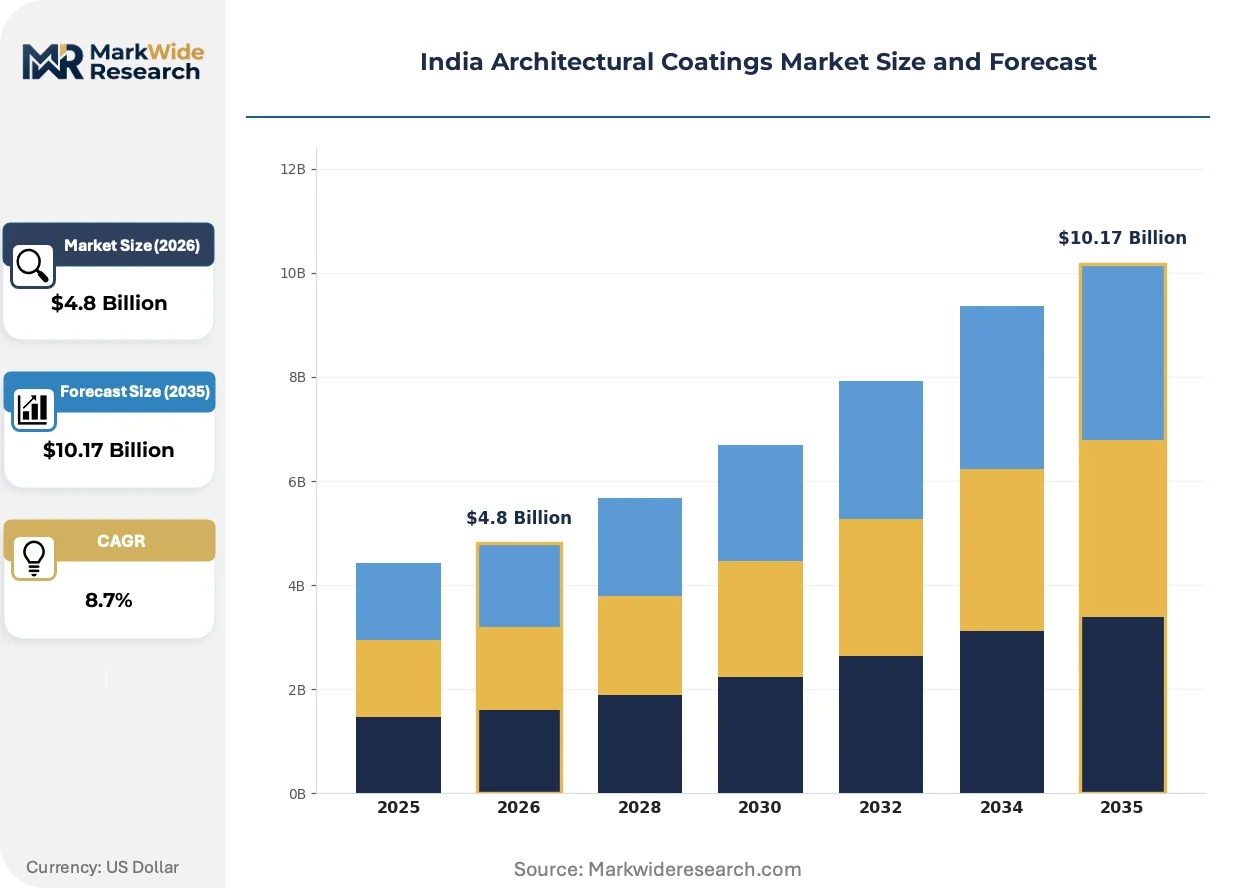
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Enamel, Primer, Solvent-based Application: Residential, Commercial, Industrial, Institutional Formulation: Acrylic, Alkyd, Polyurethane, Epoxy End User: Architects, Contractors, DIY Users, Property Developers |
| Companies Covered | JSW Paints, Indigo Paints Ltd, Asian Paints Ltd, Sheenlac Paints Ltd, Shalimar Paints Ltd, Berger Paints India Ltd, Nippon Paint India, Jenson & Nicholson India, Kansai Nerolac Paints Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Architectural Coatings Market Shifts & Advancements
Formulation chemistry and application methods are evolving rapidly as regulatory pressure intersects with performance demands from commercial construction and affordable housing programs.
Water-based acrylic emulsion technology is overtaking solvent-borne alkyd systems in exterior architectural applications. Commercial construction contractors in Bangalore and Hyderabad specify these formulations for premium enamel and polyurethane uptake on high-rise facades. The shift is compressing demand for traditional oil-based primers and enabling faster project turnaround with reduced curing times.
BIS mandates on lead and chromium content limits are filtering non-compliant imports from regional traders and compelling domestic manufacturers to establish certified testing protocols. Industrial consequence includes elevated quality assurance staffing and laboratory infrastructure investment. Decorative coating producers serving residential developers in Gujarat and Maharashtra are responding with accelerated reformulation timelines to maintain project certification eligibility.
Buyer specification of certified low-emitting materials is displacing price-primary procurement in premium residential and commercial segments. Green Building Council India certification-driven preference shifts are restructuring supplier evaluation criteria toward documented VOC testing and lifecycle emission data. This behavior change is most visible in western India, where LEED-registered commercial projects in Mumbai and Pune require material disclosure documentation from coating vendors.
India Architectural Coatings Market Segmentation
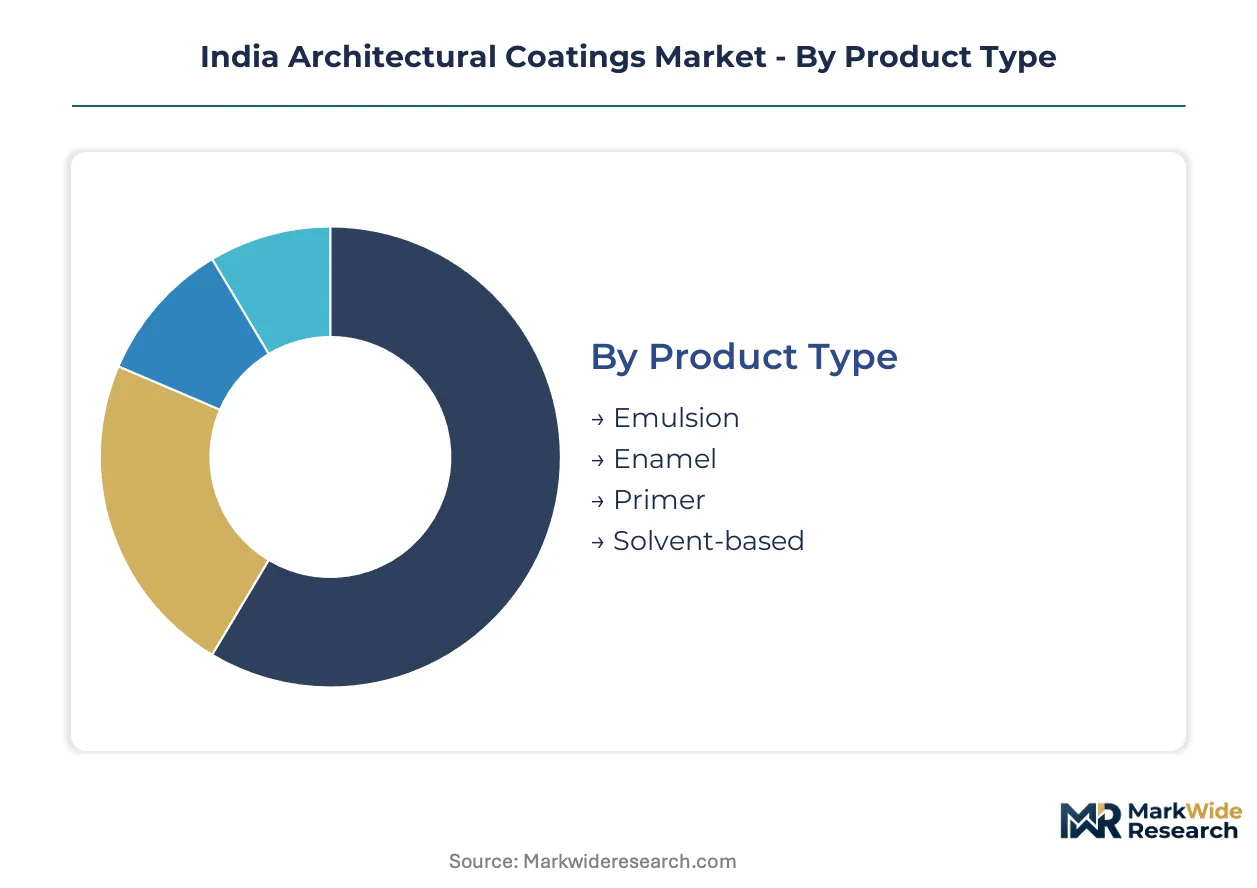
Architectural coatings in India fragment across formulation chemistry, application substrate, and procurement channel. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning across Maharashtra, Gujarat, and southern states.
Product Type:
Emulsion systems operate as standalone water-based solutions, while solvent-based products embed within industrial maintenance workflows requiring specialized application equipment.
- Emulsion:Water-based acrylic and vinyl acetate copolymer dispersions dominate interior wall applications across affordable housing projects in Mumbai and Pune. BIS low-VOC mandates compress reformulation cycles for residential developers seeking Green Building Council India certification eligibility.
- Enamel:High-gloss alkyd and polyurethane formulations cure to hard, washable films on metal and wood substrates. Commercial contractors in Bangalore specify premium enamel for high-traffic hotel lobbies and retail facades where abrasion resistance commands specification priority.
- Primer:Sealer formulations penetrate porous concrete and plaster to improve topcoat adhesion and coverage efficiency. Penetration is climbing fastest in tier-two city renovation markets where substrate quality varies.
- Solvent-based:Alkyd and nitrocellulose systems retain share in exterior metal protection and furniture finishing. Regulatory pressure from BIS VOC thresholds constrains volume expansion in residential interiors.
Emulsion leads volumes today; enamel is gaining share fastest in premium commercial specifications.
Application:
Cost tier stratification separates high-specification commercial projects from price-sensitive mass housing, with institutional procurement occupying a hybrid position.
- Residential:Decorative interior and exterior coatings applied to individual homes, apartments, and gated communities. Pradhan Mantri Awas Yojana implementation in Gujarat and Telangana multiplies substrate-ready square footage for emulsion and textured finish suppliers.
- Commercial:Office complexes, retail centers, and hospitality properties demand durable, aesthetic finishes with documented lifecycle performance. LEED-registered projects in Hyderabad and Chennai require material disclosure documentation that filters non-compliant vendors.
- Industrial:Protective coatings for manufacturing facilities, warehouses, and logistics infrastructure. Epoxy and polyurethane systems protect concrete floors and steel structures in automotive and pharmaceutical plants around Pune and Chennai.
- Institutional:Schools, hospitals, and government buildings balance budget constraints with durability requirements. Public works departments in Maharashtra specify certified low-lead formulations for educational infrastructure.
Residential anchors absolute volume; commercial is expanding most quickly on certification-driven specification upgrades.
Formulation:
Technology maturity curves separate established acrylic systems from emerging polyurethane hybrids, with alkyd formulations in managed decline.
- Acrylic:Thermoplastic resin systems provide ultraviolet resistance and color retention on exterior concrete and plaster. Water-based acrylic emulsions displace solvent-borne alternatives as BIS mandates harden on interior VOC emissions.
- Alkyd:Oil-modified polyester resins cure through oxidation to form glossy, durable films. Regulatory pressure on solvent content redirects R&D investment toward water-reducible and high-solids variants.
- Polyurethane:Two-component isocyanate-cured systems deliver chemical resistance and abrasion protection. Premium uptake concentrates in Bangalore commercial towers and Hyderabad IT parks where facade durability justifies material cost premiums.
- Epoxy:Amine-cured resin systems bond aggressively to concrete and steel for industrial floor and structural protection. Application complexity limits penetration to contractor-specified projects with skilled labor availability.
Acrylic dominates current volume; polyurethane is climbing the fastest on commercial facade specifications.
End User:
Procurement authority fragmentation separates specification influencers from purchasing decision-makers, with DIY channels disrupting traditional distribution.
- Architects:Design professionals specify coating systems during schematic and design development phases. Mumbai and Pune architectural firms increasingly require VOC testing documentation and lifecycle emission data from shortlisted vendors.
- Contractors:Construction execution teams procure coatings to meet project milestone schedules. Compressed lead time requirements in Karnataka and Telangana real estate regulations synchronize procurement with slab casting and finishing stages.
- DIY Users:Individual homeowners and small renovators purchase through retail hardware and paint stores. Dealer network expansion into tier-three cities captures renovation demand outside metropolitan contractor channels.
- Property Developers:Large residential and commercial project sponsors negotiate volume procurement agreements. Maharashtra and Gujarat developers scale decorative coating procurement as urban housing stock expands across metropolitan corridors.
Property developers lead current volume; DIY channels are gaining share fastest on retail network penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's Mumbai-Pune corridor anchors coating demand through commercial high-rise construction and affordable housing density. Western and southern states concentrate procurement volumes, while regulatory fragmentation across state urban development authorities shapes supplier compliance requirements.
Maharashtra
Residential property developers in Mumbai and Pune scale decorative coating procurement as urban housing stock expands across metropolitan corridors. State-level real estate regulators enforce project completion timelines that synchronize coating procurement cycles with construction milestones. Mumbai architectural firms increasingly require VOC testing documentation and lifecycle emission data from shortlisted vendors.
Gujarat
Pradhan Mantri Awas Yojana implementation multiplies substrate-ready square footage for emulsion and textured finish suppliers across Ahmedabad and Surat. BIS certification mandates for lead-free formulations redirect manufacturer R&D spending toward water-based acrylic systems. Dealer network expansion into tier-three cities captures renovation demand outside metropolitan contractor channels.
Karnataka
Commercial construction in Bangalore sustains premium enamel and polyurethane uptake on high-rise facades and IT park infrastructure. Compressed lead time requirements in state real estate regulations synchronize procurement with slab casting and finishing stages. LEED-registered commercial projects require material disclosure documentation from coating vendors.
Telangana
Hyderabad's IT corridor and pharmaceutical manufacturing clusters drive protective coating specifications for industrial and commercial substrates. State urban development authority specifications evolve rapidly, compelling stakeholders to monitor amendment drafts for anticipated VOC threshold reductions. Property developers negotiate volume procurement agreements as urban housing stock expands.
Tamil Nadu
Chennai's automotive and electronics manufacturing ecosystems generate industrial protective coating demand alongside commercial construction activity. Public works departments specify certified low-lead formulations for educational infrastructure across the state. Epoxy and polyurethane systems protect concrete floors and steel structures in manufacturing facilities.
India Architectural Coatings Market Competitive Landscape
Global majors compete with regional champions across formulation technology and distribution reach, creating a tiered structure where scale advantages intersect with local market intimacy. The vendor base clusters around three strategic archetypes: integrated resin producers with captive raw material security, extensive dealer network operators penetrating secondary cities, and specialty coating specialists commanding premium positioning in niche substrates. Dominant competitive moves include backward integration into binder production and accelerated tier-two and tier-three distribution infrastructure deployment.
Among domestic integrated manufacturers, Asian Paints Ltd exemplifies the archetype of resin-producing scale players, while Berger Paints India Ltd occupies a position within the network-intensive tier, and Indigo Paints Ltd represents specialty differentiation focused on premium substrate segments. These three anchors illustrate how competitive positioning stratifies across supply chain control, distribution depth, and product specialization vectors in the Indian market.
| Leading Market Players |
|---|
| JSW Paints |
| Indigo Paints Ltd |
| Asian Paints Ltd |
| Sheenlac Paints Ltd |
| Shalimar Paints Ltd |
| Berger Paints India Ltd |
| Nippon Paint India |
| Jenson & Nicholson India |
| Kansai Nerolac Paints Ltd |
| Others |
Supply & Pricing Matrix
BIS low-VOC certification mandates gate qualified supply access and premium-tier pricing eligibility as manufacturers reformulate water-based acrylic systems to meet compliance thresholds. Green Building Council India certification requirements filter non-compliant imports and elevate domestic producers with certified testing infrastructure into higher-margin specification tiers.
Pricing Analysis
Input-cost pass-through from titanium dioxide and acrylic resin volatility compresses margin structures for non-integrated manufacturers while shielding resin-producing scale players. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with LEED-registered commercial projects in Mumbai and Pune commanding material disclosure premiums. Pricing pressure stems from multi-source procurement broadening as manufacturers diversify beyond domestic petrochemical suppliers. DIY users in tier-three cities exhibit highest price sensitivity, while commercial contractors specifying polyurethane systems for Bangalore IT parks demonstrate lowest sensitivity due to performance-tier requirements.
Supply Chain Analysis
Titanium dioxide supply rests on Chinese sulfate-process producers and South Korean chloride-route specialists, with acrylic resin production concentrating among Indian petrochemical complexes and Southeast Asian polymer hubs. Key inputs span rutile-grade TiO2, vinyl acetate monomer, and specialty additives for UV stabilization. Single-source vulnerability concentrates in high-performance pigment grades where qualified alternative suppliers remain limited. Distribution runs through extensive dealer networks penetrating tier-two and tier-three cities, supplemented by direct volume procurement agreements between property developers and integrated manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in water-based acrylic premium tiers as BIS mandates displace solvent-borne alternatives and reformulation capex filters fragmented competitors. Backward integration into binder production and certified testing infrastructure investment separate margin-protected scale players from input-cost-exposed assemblers.
For Market Incumbents: Cement dealer network control in Karnataka and Telangana secondary cities against emerging regional challengers by accelerating tier-three distribution infrastructure deployment. Defend specification influence with Mumbai and Pune architectural firms through VOC testing documentation and lifecycle emission data capabilities. Prioritize captive acrylic resin production to shield margin structures from petrochemical price swings.
For New Entrants and Emerging Players: The price-point gap between premium polyurethane commercial specifications and economy emulsion residential tiers offers entry latitude for mid-market water-based acrylic specialists. Target Gujarat affordable housing contractors underserved by established brand presence in Ahmedabad and Surat satellite markets. Penetrate through specialty wood coating lines commanding premium positioning in southern furniture manufacturing clusters.
For Investors and Strategic Acquirers: Roll-up economics work for regional coating specialists with certified BIS testing infrastructure because regulatory compliance capex creates acquisition currency for integrated platforms. Long-term viability favors targets with backward integration into binder production and established architectural firm specification relationships. Watch BIS amendment drafts for anticipated VOC threshold reductions as inflection indicator for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Binder Production | In-house acrylic resin manufacturing shields Asian Paints from petrochemical volatility and supply interruption. |
| Tier-Two and Tier-Three Dealer Network Expansion | Berger Paints captures renovation demand outside metropolitan contractor channels across secondary cities. |
| Specialty Wood Coating Line Development | Indigo Paints commands premium positioning in southern furniture manufacturing clusters. |
| Green Building Council India Certification Investment | Documented VOC testing enables specification entry for LEED-registered commercial projects in Hyderabad. |
| Multi-Source Titanium Dioxide Procurement | Diversification beyond domestic suppliers reduces input cost exposure for emulsion volume producers. |
Research Methodology
Bottom-up residential and commercial construction modeling reconciled against top-down petrochemical feedstock and coating production tracking forms the analytical core. Primary interviews with plant managers at integrated manufacturers, procurement leads at Maharashtra property developers, distribution channel partners across Gujarat tier-two cities, and technical R&D directors at specialty coating producers combine with secondary validation from BIS certification databases, customs trade data on titanium dioxide imports, SEC filings of listed paint manufacturers, and state urban development authority project registrations. Triangulation across these sources calibrates volume and value estimates.
Historical trendline analysis of emulsion, enamel, primer, and solvent-based formulation volumes establishes baseline growth patterns extrapolated across the projection horizon. Segmentation dimensions span product chemistry, application substrate, procurement channel, and regional regulatory cluster. CAGRs derive from construction pipeline data, affordable housing program implementation rates, and BIS compliance timeline assumptions. Industry-specific forecast inputs include Pradhan Mantri Awas Yojana substrate-ready square footage projections and LEED-registered commercial project counts in Bangalore and Hyderabad.
Caveats apply where BIS amendment drafts crystallizing mandatory VOC thresholds, state real estate regulator enforcement intensity shifts, or petrochemical feedstock price dislocations could materially shift the outlook. A small set of named triggers—regulatory compliance deadlines, raw material sourcing disruptions, and certification-driven specification preference shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Global Primer Market
Paints & Coatings
Global Antifouling Paints and Coatings Market
Paints & Coatings
India Industrial Coatings Market
Paints & Coatings
Middle East & Africa Corrosion Protection Coating Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Paint Cans Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
Bahrain Paints and Coatings Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Fluorescent Paint Market