
 Automotive Paints Market | 2026-2036
Automotive Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Paints Market Intelligence
A transition from single-source supplier contracts to multi-source procurement for specialized coatings is shifting competitive dynamics among automotive OEMs. PPG Industries leverages its global manufacturing footprint to serve multinational vehicle assemblers across key markets in North America and Europe. BASF SE differentiates through its R&D in sustainable waterborne and powder coating technologies. Axalta Coating Systems specializes in the high-margin refinish and aftermarket segments.
Automotive paints are multi-layered liquid or powdered coatings engineered for both protection and aesthetic appeal on vehicle bodies. These systems, typically applied in distinct layers like primers and clear coats, must provide resistance to corrosion, UV radiation, and abrasion. Waterborne paints continue to displace traditional solventborne paints due to stricter environmental standards. While the OEM finish application for new vehicles commands the largest volume, the refinish segment for repair workshops offers superior margin potential.
Regulatory frameworks are a primary force shaping product development. The EU’s REACH legislation and directives from the US EPA impose stringent limits on volatile organic compound (VOC) emissions, driving innovation. Similarly, China's GB standards for coatings influence specifications for vehicles produced and sold in that market. Suppliers must therefore navigate a complex matrix of performance, cost, and compliance requirements for each regional platform.
Market Dynamics
The dual pressures of stringent Volatile Organic Compound (VOC) emission regulations and the automotive industry's pivot to electric vehicles are the central forces reshaping paint chemistry. This dynamic compels a rapid transition to waterborne systems and creates new performance requirements.
Growth Catalysts
- Stricter Environmental Mandates:Regulations like the EU's REACH framework and directives from the US EPA accelerate the market-wide phase-out of high-VOC solventborne paints in favor of compliant waterborne or powder technologies.
- Waterborne Technology Maturation:Advances in resin and additive chemistry have improved the durability, adhesion, and color-matching capabilities of waterborne basecoats, making them a viable, high-quality alternative for OEM finish applications.
- Automotive Production in China:The concentration of vehicle assembly in China's major industrial hubs creates sustained, high-volume demand for coatings that comply with local GB standards for performance and environmental safety.
Market Restraints
- Input Cost Volatility:Price fluctuations in key raw materials, including titanium dioxide, pigments, and acrylic resins, directly impact production costs and compress profit margins for paint manufacturers.
- Application Complexity:Waterborne paints require more sophisticated and climate-controlled application booths compared to solventborne systems, increasing capital and operational costs for automotive assembly plants.
- Technical Limitations of Alternatives:Powder coatings, while offering zero-VOC benefits, face challenges in achieving certain metallic finishes and are difficult to apply to heat-sensitive plastic components used in modern vehicles.
Strategic Opportunities
- Electric Vehicle Coatings:The shift to EVs creates demand for new coating functionalities, including dielectric paints for battery safety, thermal management coatings, and specialized primers for lightweight composite materials.
- Sensor-Compatible Finishes:Developing clear coats and topcoats with compositions that do not interfere with LiDAR, radar, and other sensors is critical for advancing autonomous driving systems (ADAS).
- Bio-Based Formulations:Incorporating renewable raw materials such as plant-based resins and bio-solvents into paint formulations allows suppliers to meet OEM demand for products with a lower carbon footprint and improved sustainability profiles.
Industry Challenges
- Global Compliance Management:Harmonizing a single paint formulation to meet the disparate VOC limits and chemical registration requirements of the US EPA, Europe's ECHA, and China's MEE is a significant technical and administrative burden.
- Capital-Intensive Line Conversion:The high capital expenditure required for automotive OEMs to retrofit or replace existing solventborne paint application lines with equipment suitable for waterborne or powder coatings can delay adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Paints Market |
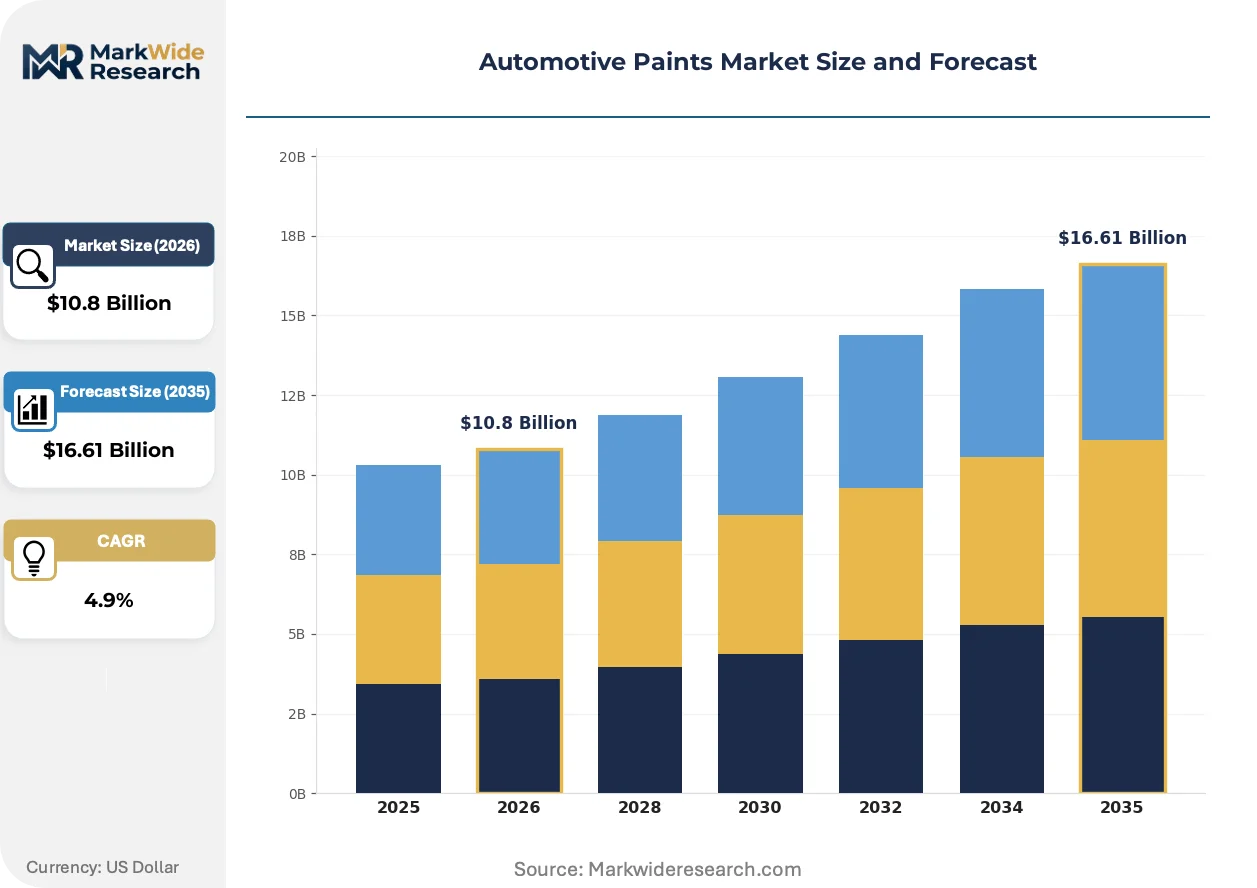
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $16.61 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne Paints, Solventborne Paints, Powder Coatings, UV Curable Paints, Polyester Paints Technology: Electrostatic Spray, Airless Spray, Thermal Spray, Dip Coating, Roll Coating, Brush Coating Application: OEM Finish, Refinish, Touch-Up, Undercoat, Primers, Clear Coat End User: Vehicle Assemblers, Tier-1 Suppliers, Aftermarket Providers, Dealerships, Repair Workshops |
| Companies Covered | PPG Industries, BASF SE, Akzo Nobel N.V., Axalta Coating Systems, The Sherwin-Williams Company, Nippon Paint Holdings Co., Ltd., Kansai Paint Co., Ltd., RPM International Inc., KCC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Paints Market Strategic Shifts & Innovations
Product innovation is now inseparable from sustainability compliance, pushing development beyond mere aesthetics. This forces suppliers to engineer coatings that simultaneously reduce environmental impact, enable new vehicle technologies, and meet traditional durability standards for corrosion and UV protection.
Specialized coatings for electric vehicle components provide critical thermal management and dielectric insulation. Automotive OEMs are rapidly adopting these materials for battery casings and electric motor housings. This focus on functional properties beyond color and gloss is electrifying the material science of automotive finishes, creating new value streams tied to vehicle performance and safety.
The EU's Corporate Sustainability Reporting Directive (CSRD) is expanding disclosure requirements beyond direct factory emissions. This compels paint suppliers to provide verifiable data on the lifecycle carbon footprint and chemical composition of their products. OEM procurement teams in Europe are now using this data as a key selection criterion, affecting supplier contracts for new vehicle platforms.
Automotive OEMs are moving away from monolithic, single-supplier contracts for their entire paint portfolio. The new procurement model involves sourcing specialized coatings, such as anti-corrosion primers or advanced clear coats, from multiple niche vendors to access innovation and mitigate supply risk. This multi-sourcing strategy is most apparent in North America and Europe for high-performance and luxury vehicle lines.
Automotive Paints Market Segmentation
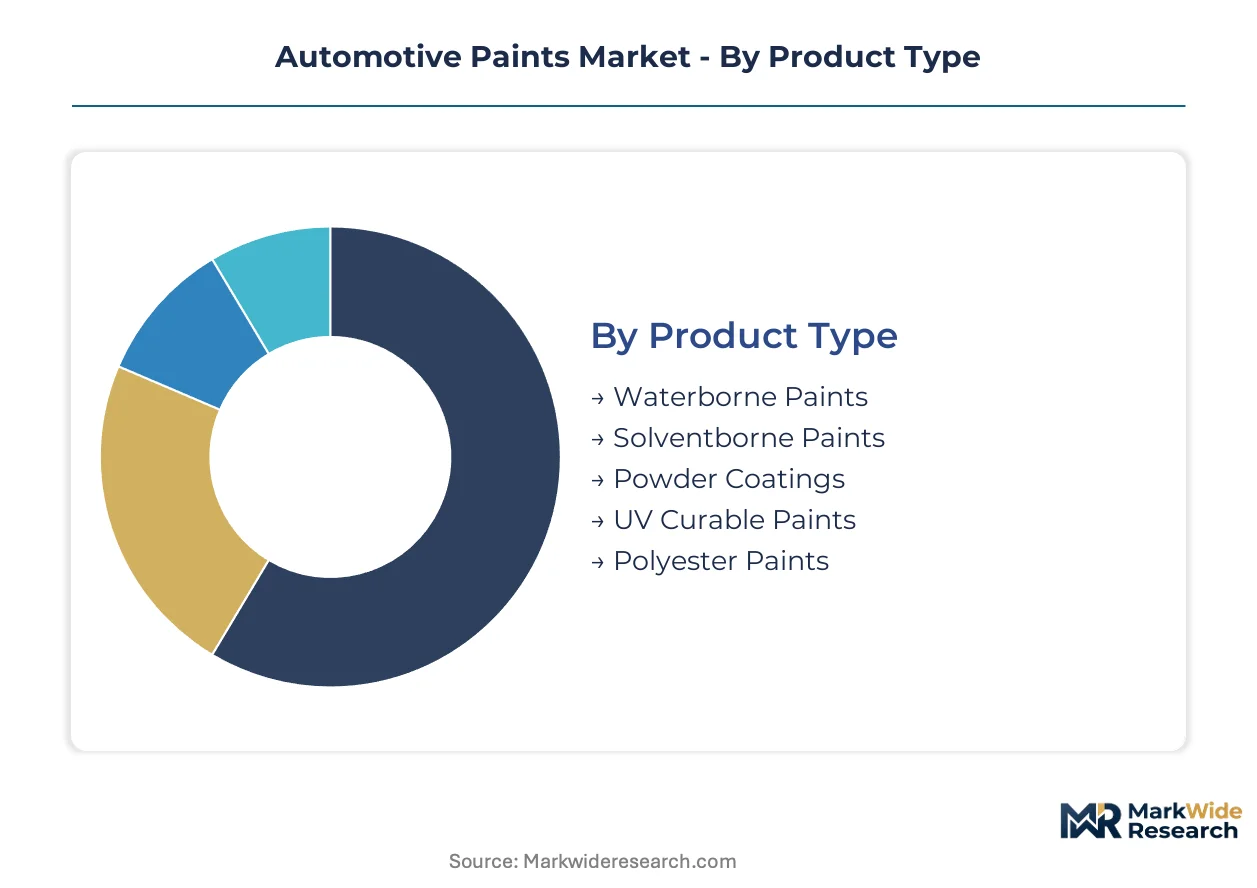
The Automotive Paints Market segmentation provides a granular view of product types, application technologies, and end-user demands that drive material innovation and procurement strategies. Understanding these distinct segments is critical for suppliers to align their R&D investments with evolving regulatory landscapes and shifting OEM requirements.
Product Type:
Product type segmentation is heavily influenced by the certification burden, with waterborne and powder coatings requiring extensive validation under environmental frameworks like the EU's REACH and China's GB standards.
- Waterborne Paints:These formulations utilize water as the primary solvent, significantly reducing volatile organic compound (VOC) emissions during application. Demand concentrates in vehicle assembly plants across Europe and North America, driven by stringent environmental regulations from the US EPA and ECHA.
- Solventborne Paints:Traditional paint systems rely on organic solvents for pigment dispersion and resin delivery, offering robust performance and ease of application. While facing displacement in regulated markets, these systems maintain a presence in certain industrial applications and regions with less stringent VOC controls.
- Powder Coatings:Applied as a dry powder, these coatings are cured with heat, producing zero VOC emissions and offering high durability. They are gaining traction for underbody components and interior parts in China's automotive production hubs due to their environmental benefits.
- UV Curable Paints:These coatings polymerize rapidly under ultraviolet light, enabling faster processing times and lower energy consumption. UV curable paints are primarily used for specialized applications like headlamp lenses and interior trim components.
- Polyester Paints:Known for their excellent hardness and chemical resistance, polyester-based formulations are often used in primers and topcoats for specific automotive parts. They offer a balance of performance and cost-effectiveness for various vehicle applications.
Waterborne Paints sits at the top of the volume ranking, with Powder Coatings climbing the fastest.
Technology:
The choice of application technology directly impacts capital expenditure and operational efficiency within automotive manufacturing facilities, with advanced systems offering greater precision and material utilization.
- Electrostatic Spray:This technology uses an electrostatic charge to attract paint particles to the vehicle body, maximizing transfer efficiency and reducing overspray. It is a dominant application method in OEM facilities for its material savings and uniform coverage.
- Airless Spray:Airless spray systems atomize paint by forcing it through a small orifice at high pressure, delivering a thick, even coat without the use of compressed air. This method is common in refinish shops and for applying undercoats due to its speed and versatility.
- Thermal Spray:Thermal spray techniques involve heating and propelling coating materials onto a surface, creating a durable protective layer. This specialized technology finds application in high-performance or functional coatings, particularly for engine components or wear-resistant surfaces.
- Dip Coating:Vehicle bodies are fully immersed in a paint bath, ensuring complete coverage of complex geometries and internal surfaces. Dip coating, especially electrocoating, is a foundational step in OEM primer application for corrosion protection.
- Roll Coating:This method applies paint using rollers, providing a uniform film thickness over flat or gently curved surfaces. Roll coating is typically employed for pre-coated metal sheets used in automotive sub-assemblies.
- Brush Coating:The most basic application method, brush coating involves manually applying paint with a brush. It is primarily used for small touch-ups, repair work, or specialized detailing in aftermarket settings.
Electrostatic Spray technology offers the highest efficiency, while Dip Coating ensures comprehensive coverage for complex parts.
Application:
Application segments reflect the distinct stages of a vehicle's lifecycle, from initial manufacturing to subsequent repair and maintenance, each with unique performance requirements and margin profiles.
- OEM Finish:This segment encompasses all paint layers applied during the initial vehicle assembly process by original equipment manufacturers. It represents the largest volume demand for automotive paints, particularly in China's expanding automotive production sector.
- Refinish:Coatings used for vehicle repair and repainting after market sale, typically performed by independent body shops or dealership service centers. The refinish segment offers superior margin potential due to the specialized nature of color matching and repair processes.
- Touch-Up:Small-scale paint applications to correct minor defects or stone chips on a vehicle's surface. Touch-up products are sold through dealerships and aftermarket channels for consumer or professional use.
- Undercoat:Protective layers applied to the underside of a vehicle to prevent corrosion, abrasion, and damage from road debris. Undercoats are critical for vehicle longevity, especially in regions with harsh weather conditions.
- Primers:The foundational layer of an automotive paint system, primers provide adhesion for subsequent coats and enhance corrosion resistance. They are essential for preparing the vehicle surface for topcoat application.
- Clear Coat:The outermost transparent layer of the paint system, providing gloss, UV protection, and resistance to scratches and environmental damage. Clear coats are vital for maintaining the aesthetic appeal and durability of the vehicle's finish.
OEM Finish commands the largest market share, with the Refinish segment showing the steepest expansion trajectory.
End User:
End-user segmentation highlights the diverse customer base for automotive paints, ranging from large-scale industrial consumers to smaller service providers, each with distinct procurement patterns.
- Vehicle Assemblers:Major automotive manufacturers that integrate paint systems into their production lines for new vehicles. These entities typically engage in long-term contracts with paint suppliers, demanding high-volume, consistent product quality.
- Tier-1 Suppliers:Companies that provide major components or sub-assemblies directly to vehicle assemblers, often requiring specialized coatings for their parts. These suppliers adhere to stringent OEM specifications for paint performance and compliance.
- Aftermarket Providers:Businesses that supply paint products and related materials to repair workshops, dealerships, and individual consumers for post-sale maintenance. This segment emphasizes product availability and color matching capabilities.
- Dealerships:Automotive dealerships often operate their own service centers for minor repairs, touch-ups, and detailing. They procure smaller volumes of specialized paints for their in-house operations.
- Repair Workshops:Independent body shops and collision repair centers that utilize refinish paints for vehicle restoration. These workshops prioritize ease of application, durability, and accurate color reproduction.
Vehicle Assemblers represent the primary procurement channel, while Repair Workshops are a significant contributor to aftermarket demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's automotive production hubs are a primary engine for automotive paint demand, driven by high-volume vehicle assembly. Stricter environmental regulations globally are reshaping regional market dynamics. Manufacturers are adapting formulations to meet diverse compliance requirements across continents.
China
China's expanding vehicle assembly operations generate substantial demand for automotive paints. Compliance with China's GB standards for coatings is critical for market access. Major industrial zones like the Yangtze River Delta are seeing significant investment in advanced waterborne and powder coating facilities.
Germany
German automotive manufacturers require high-performance paints for their premium vehicle lines and sustainable production goals. The EU's REACH legislation mandates the phase-out of high-VOC solventborne systems. Production clusters in Bavaria and Baden-Württemberg drive innovation in waterborne and bio-based formulations.
United States
United States vehicle assemblers demand advanced coatings for new vehicle platforms and electric vehicle components. US EPA directives impose stringent limits on volatile organic compound emissions, accelerating the shift to waterborne paints. Automotive manufacturing centers in Michigan and Ohio are actively converting existing paint lines.
Japan
Japanese automotive production prioritizes durability, aesthetic quality, and environmental performance for its global exports. METI environmental guidelines encourage the adoption of low-VOC and energy-efficient paint systems. The Chubu region, centered around Nagoya, leads in implementing advanced UV curable and waterborne paint technologies.
India
India's expanding automotive sector drives demand for cost-effective and environmentally compliant paint solutions for local production. BIS standards for industrial coatings influence product specifications for both OEM and aftermarket segments. Manufacturing hubs in Chennai and Pune are witnessing rising adoption of waterborne paints.
Automotive Paints Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized niches in electric vehicle coatings and sustainable formulations. The automotive paints market exhibits a tiered structure, with global chemical conglomerates alongside specialized coating providers. These companies compete across OEM and refinish segments, leveraging distinct technological advantages and extensive distribution networks. Strategic partnerships with vehicle assemblers and continuous R&D investment in compliant solutions are dominant competitive moves. Geographic expansion into high-growth markets like China also remains a key strategy for market share capture.
Within the established tier, companies like PPG Industries and BASF SE exemplify diversified global operations, serving multinational vehicle assemblers across key markets. PPG Industries, a US-based corporation, leverages its extensive manufacturing footprint and broad product portfolio. BASF SE, a German chemical giant, anchors its competitive positioning through robust R&D in sustainable waterborne and powder coating technologies. Axalta Coating Systems, another US-based entity, represents a specialist archetype, focusing on high-margin refinish and aftermarket segments. These players consistently adapt their offerings to meet evolving regulatory landscapes and OEM demands for performance and sustainability.
| Leading Market Players |
|---|
| PPG Industries |
| BASF SE |
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| The Sherwin-Williams Company |
| Nippon Paint Holdings Co., Ltd. |
| Kansai Paint Co., Ltd. |
| RPM International Inc. |
| KCC Corporation |
| Others |
Cost & Logistics Intelligence
Stricter environmental mandates from the US EPA and EU REACH compel paint suppliers to invest heavily in waterborne technologies. This shift impacts production costs and ultimately influences pricing power across the automotive paints supply chain.
Pricing Analysis
Input cost volatility for titanium dioxide and acrylic resins directly influences paint manufacturers' pricing strategies. The dominant pricing model involves long-term contract-based offtake agreements with vehicle assemblers, often with price adjustments tied to raw material indices. Price differentiation stems from formulation complexity for specialized coatings and the certification level required for specific vehicle platforms. Pricing pressure stems from OEMs' multi-sourcing strategies, making repair workshops the most price-sensitive segment, while vehicle assemblers prioritize performance and compliance.
Supply Chain Analysis
Workforce availability in key manufacturing geographies like China, Germany, and the United States affects production capacity and lead times for automotive paints. The supply chain draws from critical raw materials including titanium dioxide, pigments, and acrylic resins, sourced globally. A structural risk involves single-source vulnerability for specialized additives, impacting formulation flexibility. Distribution runs through direct channels to vehicle assemblers and a network of aftermarket providers for refinish products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities exist in the automotive paints market due to varying environmental compliance costs between highly regulated regions like Europe and emerging markets. This allows for strategic production and sourcing decisions.
For Market Incumbents:Acquire specialized R&D capabilities in bio-based formulations to counter the threat of stringent EU CSRD disclosure requirements. Consolidate global manufacturing footprints to optimize production for waterborne systems, leveraging existing infrastructure in North America and Europe. This provides a lever against margin pressure from input cost volatility and enhances compliance with diverse regional regulations.
For New Entrants and Emerging Players:Specialized component suppliers represent a key channel for new entrants to target the electric vehicle coatings segment. Focus on developing dielectric paints for battery safety and thermal management coatings for EV motors, areas with underpenetration. A go-to-market angle involves collaborating directly with EV platform developers to integrate new coating functionalities early in the design cycle for specific vehicle classes.
For Investors and Strategic Acquirers:Asymmetric upside sits with mid-cap specialists possessing patented waterborne and powder coating technologies. Long-term viability depends on their ability to scale production while maintaining R&D intensity for sustainable formulations. Acquisition targets should be companies with established OEM relationships in China or Germany for high-performance applications. The signal to watch is an increase in OEM procurement teams' explicit demand for lifecycle carbon footprint data.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding waterborne and powder coating production in China's industrial hubs meets local GB standards and OEM demand. |
| Green Manufacturing Transition | Implementing renewable energy sources and waste reduction in European plants aligns with EU CSRD requirements and sustainable production goals. |
| Long-term Supply Agreement | Securing critical raw material supplies, such as titanium dioxide, mitigates input cost volatility for paint manufacturers. |
| Joint Venture | Partnering with local chemical companies in India helps navigate BIS standards and penetrate the expanding automotive sector. |
| Technology Licensing | Offering advanced UV curable paint formulations to specialized component manufacturers creates new value streams for headlamp lenses. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to build a comprehensive market view. This included interviews with OEM procurement teams, R&D directors at paint manufacturers, and aftermarket distributors. Secondary validation drew from customs data, company financial reports, and regulatory filings by the US EPA and ECHA. Bottom-up and top-down triangulation ensured data accuracy.
Historical market performance was cross-referenced with expert panel input to project future growth trajectories across the analysis window. The analytical framework modeled segmentation dimensions including product type, application technology, end-user, and vehicle class. Compound annual growth rates were derived from a multi-variant regression analysis, incorporating automotive production forecasts and regional regulatory compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to raw material availability and environmental regulations. Forecasts reflect assumptions regarding technological advancements and OEM adoption rates. Practitioners should monitor global economic stability and regional automotive production.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Solar Paint Market
Paints & Coatings
Paint Curing Lamp Market
Paints & Coatings
Saudi Arabia Paints and Coatings Market
Paints & Coatings
Asia-Pacific Architectural Coatings Market
Paints & Coatings
Asia-Pacific Paint Thinner Market
Paints & Coatings
Faux Finish Coatings Market
Paints & Coatings
Radar Absorbing Paint Market
Paints & Coatings
Middle East & Africa Corrosion Protection Coating Market
Paints & Coatings
Middle East and Africa Floor Coatings Market
Paints & Coatings
Paint Sprayer Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
India Floor Coatings Market
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Europe Automotive Paints and Coatings Market