
 Residential Solar Energy Market | 2026-2036
Residential Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Solar Energy Market Outlook
Utility-averse homeowners are redrawing procurement patterns across the residential solar value chain. Sunrun leverages its vertically integrated installation and financing platform to capture recurring revenue streams. Tesla Energy sustains brand pull through its Solar Roof Tiles and Powerwall ecosystem integration. Enphase Energy dominates microinverter architecture, anchoring module-level power electronics as a default specification.
Residential solar energy encompasses photovoltaic and thermal systems engineered for on-site electricity generation at single-family homes, multi-unit dwellings, and planned communities, typically rated between 3 kW and 20 kW DC capacity and designed for 25-year operational lifespans. Photovoltaic Systems command the largest installed base while Solar Batteries capture expanding margin pools as homeowners prioritize backup resilience. Rooftop installations outpace ground-mount alternatives in urban density corridors, though Hybrid configurations integrating on-grid connectivity with battery islanding are accelerating fastest among new permits.
The US Inflation Reduction Act's 30% residential clean energy credit, administered through the IRS, is reshaping payback calculus for American households while the EU Green Deal's building renovation targets pressure member states to streamline rooftop permitting. Germany's KBA-adjacent building codes and Australia's CEC accreditation standards further define product eligibility and installer qualification thresholds. Stakeholders must monitor how interconnection queue reforms and net metering restructuring alter project economics in key state-level markets.
Market Dynamics
Utility-averse homeowners are redrawing procurement patterns across the residential solar value chain, forcing installers and financiers to restructure customer acquisition and service bundling around energy independence rather than simple bill savings.
Growth Catalysts
- The US Inflation Reduction Act:The 30% residential clean energy credit administered through the IRS compresses payback periods for American households, accelerating rooftop deployment in suburban single-family housing.
- CEC accreditation standards:Australia's installer qualification thresholds elevate consumer confidence and reduce soft costs, streamlining permitting processes across state-level markets.
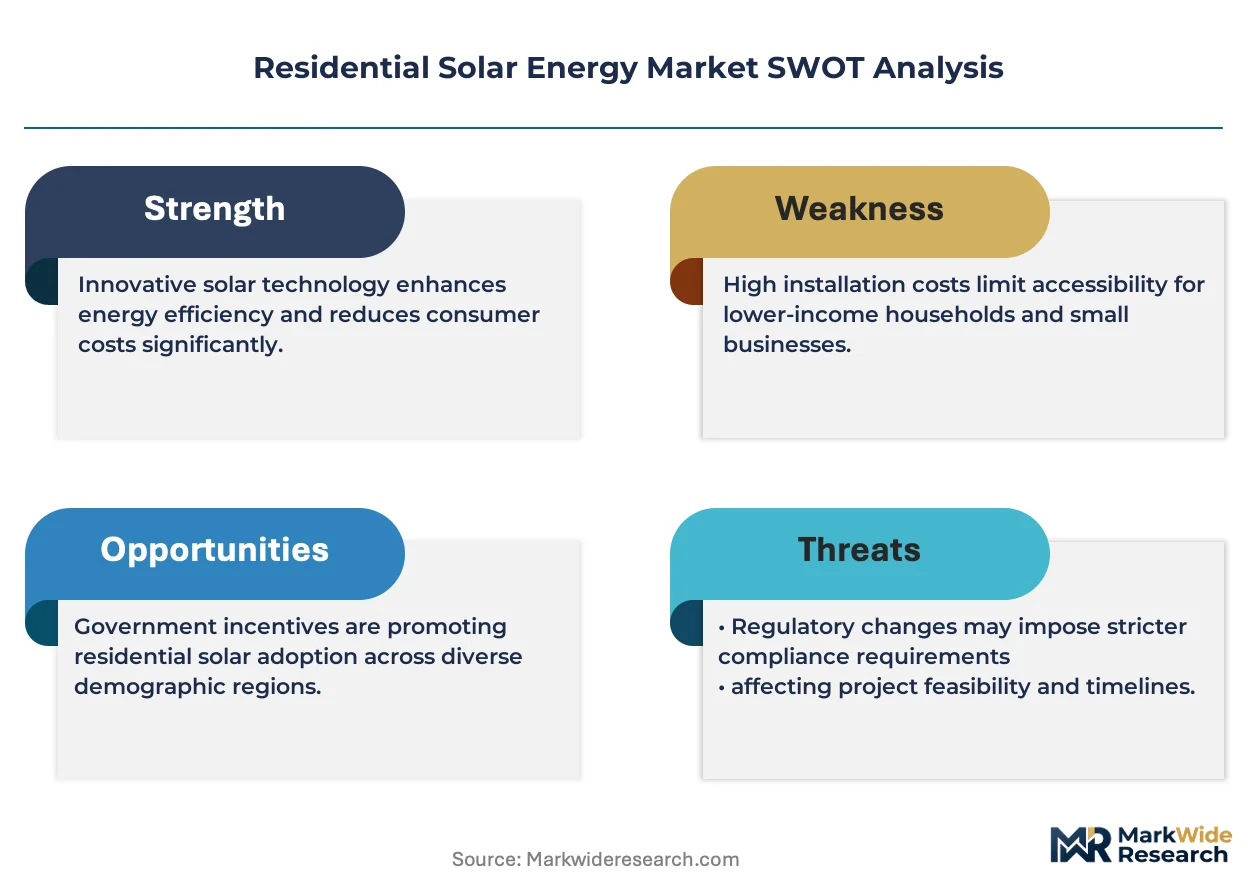
- Battery islanding capabilities:Hybrid configurations integrating on-grid connectivity with backup resilience are capturing expanding margin pools as homeowners prioritize energy security over pure economics.
Market Restraints
- Polysilicon supply concentration:Input cost volatility from concentrated upstream refining capacity in specific geographies compresses module margins and destabilizes installer pricing.
- Interconnection queue reforms:Regulatory friction from restructuring net metering policies in key state-level markets alters project economics and extends commissioning timelines.
- Natural gas peaker plants:Grid-scale substitution threats from dispatchable fossil assets delay utility investment in distributed solar infrastructure in certain markets.
Strategic Opportunities
- EU Green Deal building renovation targets:Regulatory tailwinds pressure member states to streamline rooftop permitting, creating white space for turnkey installation platforms.
- Multi-unit dwelling penetration:Underpenetrated housing stock in Germany's apartment sector offers volume expansion as split-incentive barriers erode through virtual net metering innovations.
- Powerwall-to-Solar Roof integration:Technology convergence between energy storage and building-integrated photovoltaics enables premium positioning in new construction segments.
Industry Challenges
- NABCEP certification timelines:Talent gaps in credentialed installer labor constrain deployment velocity and elevate soft costs across fragmented contractor networks.
- Legacy electrical panel upgrades:Integration complexity with aging residential infrastructure requires unexpected capex outlays that disrupt standardized sales workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Solar Energy Market |
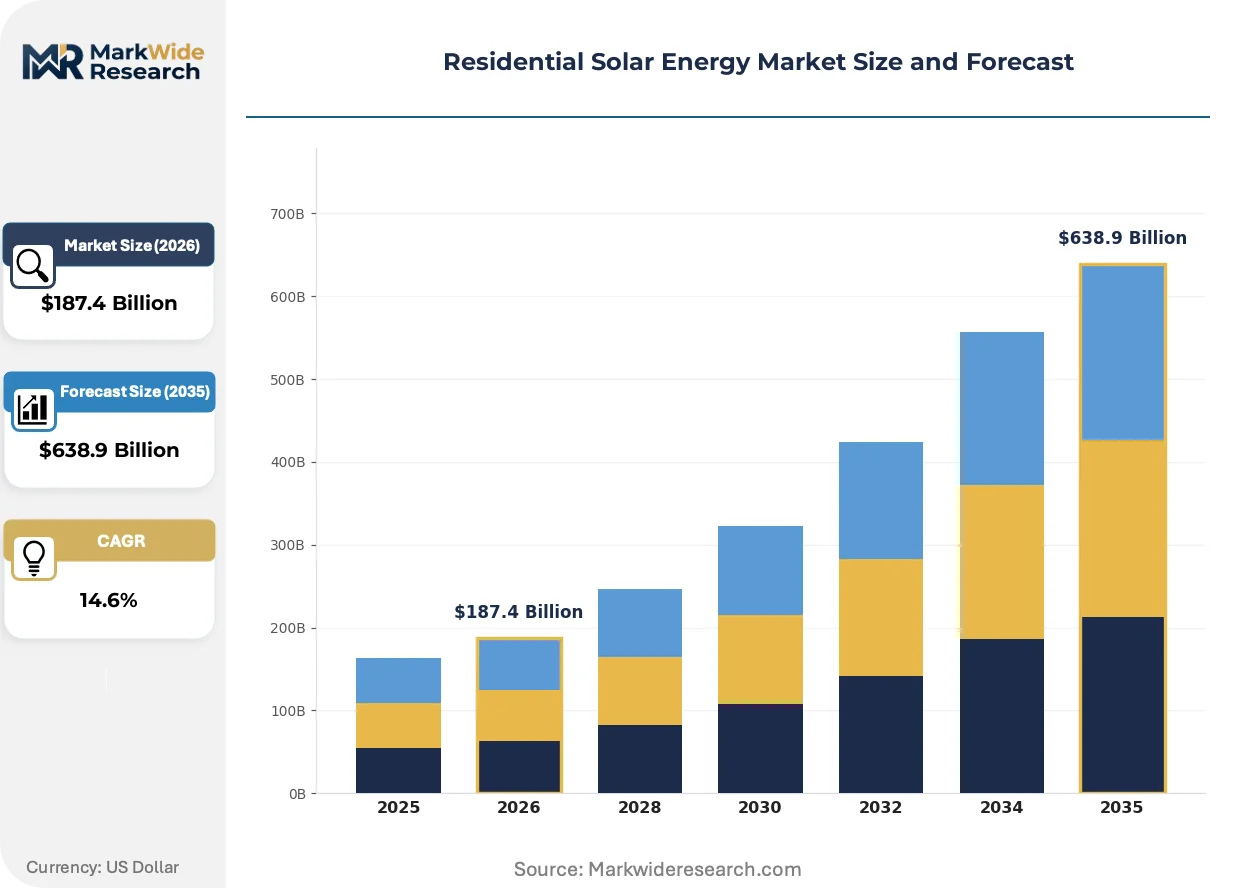
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Systems, Solar Roof Tiles, Solar Batteries, Inverters End User: Homeowners, Property Developers, Residential Communities, Landlords Technology: C-Si, Thin-Film, Bifacial, Concentrated Solar Power Installation Type: On-Grid, Off-Grid, Hybrid, Rooftop |
| Companies Covered | Sunrun, Tesla Energy, Enphase Energy, SunPower Corporation, REC, Hanwha Q Cells, SolarEdge Technologies, Canadian Solar, JinkoSolar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Solar Energy Market Strategic Shifts
Module-level power electronics are compressing system architecture and enabling granular performance monitoring, while financing innovation and regulatory pressure reshape how residential solar reaches end customers.
Microinverter architecture is decomposing the traditional string inverter topology in residential applications. Suburban homeowners with battery storage intent are specifying module-level electronics as default equipment. This technology shift is decomposing centralized inverter margins and redistributing value capture toward semiconductor packaging specialists.
Germany's KBA-adjacent building codes are mandating solar-ready roofing standards for new construction permits. The industrial consequence elevates building-integrated photovoltaics from premium niche to compliance-driven specification. Single-family developers in Bavaria and Baden-Württemberg are responding by pre-wiring electrical infrastructure and standardizing tile-compatible mounting systems.
Direct-to-consumer financing platforms are displacing traditional third-party ownership structures. The leasing and PPA channel faces disintermediation as cash purchase and loan products capture preference among creditworthy homeowners. This behavioral shift is most visible in Australia's CEC-accredited installer networks, where digital origination tools now dominate customer acquisition economics.
Residential Solar Energy Market Segmentation
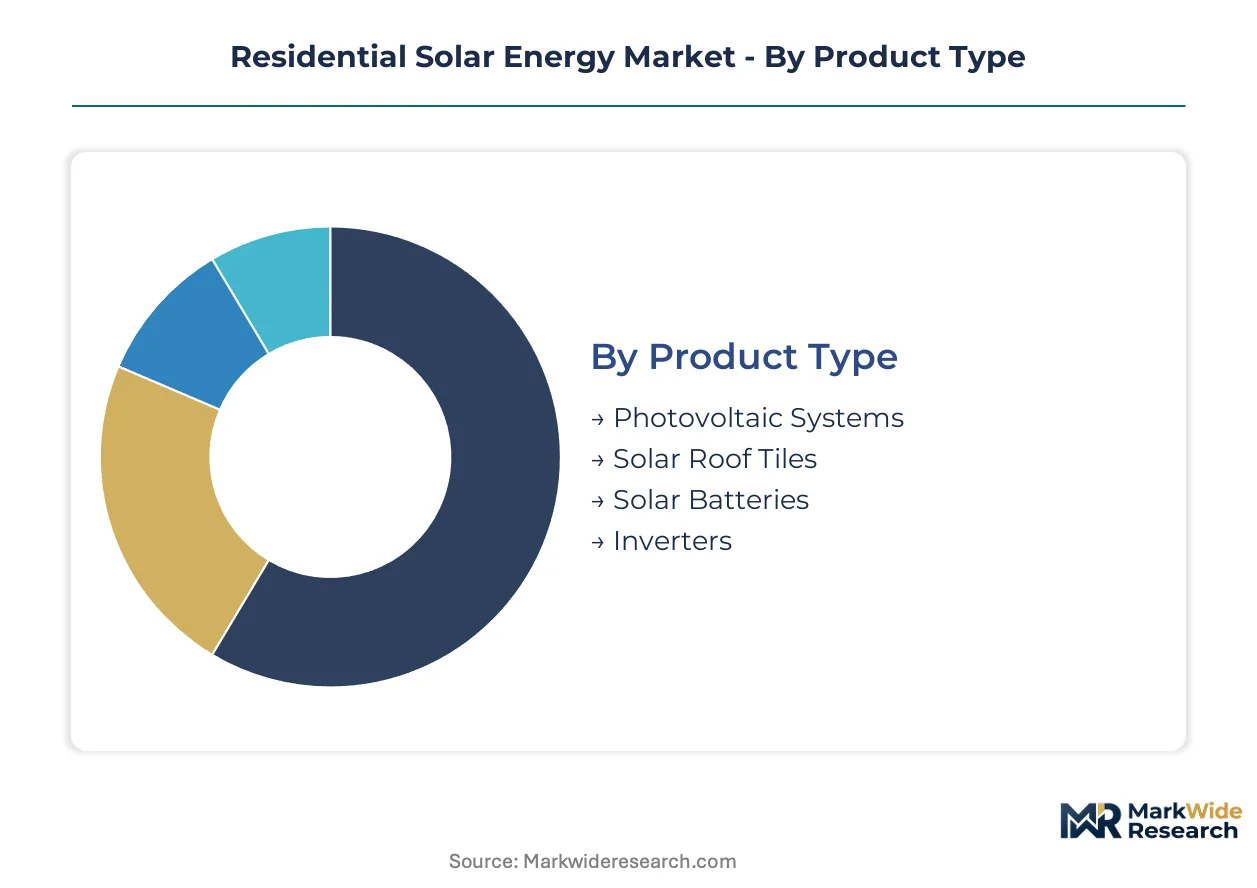
Residential solar markets fragment across product architectures, customer archetypes, and grid-interconnection strategies. Each segmentation axis reveals distinct margin pools, regulatory exposure, and installer capability requirements that shape competitive positioning.
Product Type:
Photovoltaic Systems and Solar Batteries concentrate demand in suburban single-family housing across Germany, Australia, and the United States. Solar Roof Tiles and Inverters serve narrower addressable markets with higher specification sensitivity.
- Photovoltaic Systems:Silicon-based module assemblies rated between 3 kW and 20 kW DC capacity dominate installed capacity. Demand concentrates in suburban single-family housing across Germany, Australia, and the United States where rooftop geometry accommodates standard panel dimensions and permitting pathways are established.
- Solar Batteries:Lithium-ion storage systems with islanding capabilities capture expanding margin pools as homeowners prioritize backup resilience over pure bill savings. The fastest expansion runs through this segment as utility-averse buyers reconfigure procurement around energy independence.
- Solar Roof Tiles:Building-integrated photovoltaic roofing replaces conventional materials with electricity-generating surfaces. Germany's KBA-adjacent building codes are elevating these from premium niche to compliance-driven specification in new construction.
- Inverters:Power electronics convert DC module output to grid-synchronized AC power. Microinverter architecture is displacing string topology as module-level monitoring becomes default specification among battery-intent buyers.
Photovoltaic Systems command the established base. The steepest expansion runs through Solar Batteries.
End User:
Customer archetypes diverge sharply in financing preference, decision velocity, and service bundling requirements. Cost tiers separate cash purchasers from third-party ownership seekers.
- Homeowners:Owner-occupiers with single-family detached properties represent the core addressable market. Australia's CEC-accredited installer networks report digital origination tools now dominate acquisition economics for this creditworthy segment.
- Property Developers:New construction specifiers integrate solar-ready infrastructure during build phase. Germany's building codes mandate pre-wiring and tile-compatible mounting systems in Bavaria and Baden-Württemberg.
- Residential Communities:Planned developments and homeowner associations deploy shared solar infrastructure serving multiple dwellings. Virtual net metering innovations are eroding split-incentive barriers that previously constrained apartment sector penetration.
- Landlords:Rental property owners face tenant pass-through complexity and capital recovery uncertainty. Direct-to-consumer financing platforms are displacing traditional third-party ownership structures for this risk-averse segment.
Homeowners anchor current volume. Residential Communities are gaining share fastest as virtual net metering matures.
Technology:
Cell architecture determines efficiency curves, temperature coefficients, and manufacturing cost structures. Supply concentration in upstream polysilicon refining creates margin volatility across technology tiers.
- C-Si:Crystalline silicon cells command the largest installed base through proven reliability and established supply chains. Input cost volatility from concentrated upstream refining capacity compresses module margins.
- Thin-Film:Cadmium telluride and copper indium gallium selenide alternatives suit specific rooftop constraints. Niche applications persist where weight loading or shading tolerance outweigh efficiency premiums.
- Bifacial:Dual-sided cells capture albedo reflection from underlying surfaces. Ground-mount and elevated rooftop configurations in high-reflectivity climates show strongest uptake.
- Concentrated Solar Power:Mirror-based thermal systems scale poorly to residential capacity ranges. Effectively absent from addressable market except in specialized off-grid configurations.
C-Si maintains the established base. Bifacial modules are climbing the fastest as balance-of-system costs decline.
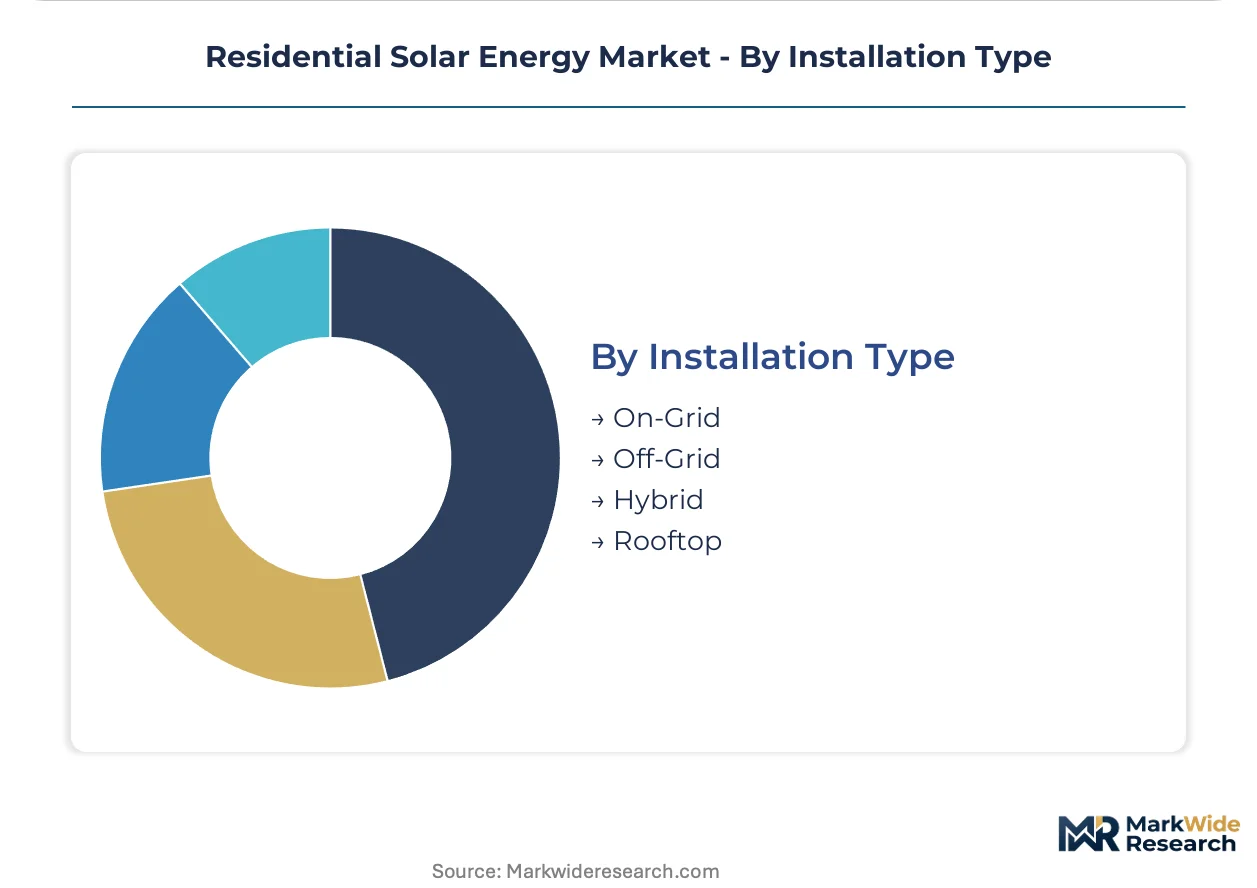
Installation Type:
Grid-interconnection strategy determines hardware specification, permitting pathway, and revenue model. Application context separates urban density corridors from rural off-grid deployments.
- On-Grid:Net-metered systems export surplus generation to utility infrastructure. Interconnection queue reforms in key state-level markets are altering project economics and extending commissioning timelines.
- Off-Grid:Battery-dependent standalone systems serve locations beyond distribution network reach. Remote properties in Australia and rural United States sustain this segment despite higher capital intensity.
- Hybrid:Configurations integrating on-grid connectivity with battery islanding capabilities are accelerating fastest among new permits. The US Inflation Reduction Act's residential clean energy credit compresses payback periods for these systems.
- Rooftop:Building-surface mounting outpaces ground-mount alternatives in urban density corridors. Suburban single-family housing across Germany, Australia, and the United States concentrates deployment.
On-Grid systems command the established base. Hybrid configurations are gaining share fastest as resilience premiums outweigh pure economic optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision-engineered inverters and mounting systems flow into Australian and American installer networks, establishing a transatlantic supply corridor that shapes procurement standards across three continents.
United States
Suburban single-family housing in California, Texas, and Florida drives deployment velocity. The IRS administers the 30% residential clean energy credit under the Inflation Reduction Act, compressing payback periods for hybrid battery systems. Installer networks in the Southwest cluster around Phoenix and Las Vegas, where solar irradiance and net metering policies align.
Germany
Bavaria and Baden-Württemberg anchor European demand through new construction mandates. The KBA-adjacent building codes enforce solar-ready roofing standards, elevating building-integrated photovoltaics from premium niche to compliance specification. Munich-based project developers pre-wire electrical infrastructure and standardize tile-compatible mounting systems for single-family subdivisions.
Australia
Queensland and South Australia sustain the highest per-capita penetration rates globally. The Clean Energy Council's accreditation standards elevate consumer confidence and reduce soft costs across state-level markets. Sydney and Melbourne installer networks report digital origination tools now dominate customer acquisition economics for creditworthy homeowners.
China
Polysilicon refining capacity concentrates in Xinjiang and Inner Mongolia, feeding module assembly plants in Jiangsu and Zhejiang provinces. The MIIT's dual carbon goals accelerate domestic distributed solar deployment while export volumes to Germany and Australia expand. Yangtze River Delta manufacturers supply microinverter components to American and European integrators.
Residential Solar Energy Market Competitive Environment
Listed leaders compete with private specialists across financing and installation platforms, creating a tiered structure where scale advantages in customer acquisition clash with regional installer relationships. The vendor base organizes around three strategic archetypes: vertically integrated installation-and-financing platforms, semiconductor packaging specialists dominating module-level power electronics, and module manufacturers with captive cell capacity. Competitive intensity manifests through installer network acquisitions and direct-to-consumer digital origination tools.
Within the integrated platform tier, Sunrun and Tesla Energy exemplify divergent approaches to customer ownership and technology bundling. Sunrun's vertically integrated model captures recurring revenue through installation and financing integration. Tesla Energy sustains brand pull through ecosystem integration spanning energy generation and storage. Enphase Energy anchors the power electronics specialist archetype, with its microinverter architecture redistributing value capture from traditional string inverter suppliers.
| Leading Market Players |
|---|
| Sunrun |
| Tesla Energy |
| Enphase Energy |
| SunPower Corporation |
| REC |
| Hanwha Q Cells |
| SolarEdge Technologies |
| Canadian Solar |
| JinkoSolar |
| Others |
Value Chain & Pricing Dynamics
Australia's CEC accreditation standards gate both installer qualification and price differentiation simultaneously. Certified contractors command premium positioning while uncredentialed competitors compete on stripped-down economics. The regime compresses soft costs for qualified players and widens spreads between compliant and non-compliant service tiers.
Pricing Analysis
Prior-generation string inverter systems trade at steep discounts to current-generation microinverter architectures, while next-generation building-integrated photovoltaic roofing commands substantial premiums. Three-tier pricing structure across premium, standard, and economy levels separates Powerwall-integrated hybrid systems from standalone rooftop arrays from basic grid-tied configurations. Price differentiation hinges on battery islanding capability and module-level monitoring granularity. Cost compression in economy-tier commoditized panels is intensifying because polysilicon input volatility feeds through to module assembly. Property developers exhibit lowest price sensitivity due to compliance-driven procurement, while landlord segments remain most cost-conscious.
Supply Chain Analysis
Inventory cycles for lithium-ion cells now stretch twelve to sixteen weeks, compressing installer working capital and forcing pre-positioning of battery systems ahead of seasonal demand surges. Polysilicon refining concentrates in Xinjiang and Inner Mongolia, with module assembly clustering in Jiangsu and Zhejiang provinces. Crystalline silicon wafers, aluminum framing, and power electronics components constitute critical input dependencies. Single-source vulnerability in semiconductor packaging for microinverters creates chokepoint exposure. Distribution runs through vertically integrated installation platforms and CEC-accredited contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residential solar sits in early-cycle expansion as battery storage intent reconfigures buyer archetypes toward energy independence. The US Inflation Reduction Act's residential clean energy credit accelerates this shift by compressing payback periods for hybrid system configurations.
For Market Incumbents: Consolidate installer network relationships in suburban single-family corridors before virtual net metering erodes split-incentive barriers. Acquire CEC-accredited or NABCEP-credentialed contractor capacity to constrain talent gaps that elevate soft costs. Deepen backward integration into battery system assembly to capture margin pools shifting from modules to storage.
For New Entrants and Emerging Players: Digital origination tool underinvestment by legacy financiers creates white-space for loan-origination platforms targeting creditworthy homeowner segments. Germany's apartment sector offers penetrable volume as KBA-adjacent building codes force new construction compliance. Pursue direct-to-consumer acquisition models displacing third-party ownership structures.
For Investors and Strategic Acquirers: The EU Green Deal's building renovation targets reshape the acquisition landscape toward turnkey installation platforms with regulatory compliance capabilities. Long-term viability centers on recurring revenue models rather than one-time hardware margins. Target microinverter semiconductor packaging specialists with captive grid-forming technology. Watch interconnection queue reform progress as inflection indicator for utility-scale substitution threats.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Assembly | Captures expanding margin pools as homeowners prioritize Powerwall-integrated resilience over pure economics. |
| CEC/NABCEP Certification Investment | Elevates consumer confidence and reduces soft costs across fragmented contractor networks in key markets. |
| Virtual Net Metering Platform Launch | Erodes split-incentive barriers constraining apartment sector penetration in Germany and Australia. |
| Digital Origination Tool Deployment | Displaces traditional third-party ownership acquisition economics for creditworthy homeowner segments. |
| Building-Integrated Photovoltaic Partnership | Positions for compliance-driven specification under KBA-adjacent solar-ready roofing mandates. |
Study Parameters
The analysis maps photovoltaic systems, solar batteries, solar roof tiles, and inverter architectures, each validated through utility planning officers, EPC contractors, CEC-accredited installers, and IPP project developers. Primary interviews with these stakeholders combined secondary validation through EIA data, IEA distributed solar outlooks, FERC interconnection filings, and Clean Energy Council accreditation records. Bottom-up project pipeline aggregation triangulates against top-down regulatory incentive modeling.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product architecture, end-user archetype, technology tier, and grid-interconnection strategy. CAGRs derive from installed capacity build rates, policy incentive trajectories, and battery cost curve assumptions. Forecast inputs incorporate IRS credit administration timelines and EU Green Deal implementation pacing.
Forecasts assume regulatory continuity in US IRA credit regimes and EU Green Deal building renovation targets; material policy shifts would require re-modeling of payback period calculus and deployment velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Indonesia Renewable Energy Market
Solar Power Systems
Rooftop Solar PV Market
Solar Power Systems
Europe Concentrated Solar Power Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market
Solar Power Systems
PV Array Combiner Box Sales Market
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
Global Solar Panel Tracking Mount Market
Solar Power Systems
Solar Skin Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
AR Photovoltaic Glass Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Solar PV Module Market