
 US Solar PV Market | 2026-2036
US Solar PV Market Size, Share, and Industry Trends Forecast 2026-2036
US Solar PV Market Insights
The thin-film versus crystalline silicon capability gap is reorganizing competitive tiers among US solar PV manufacturers. First Solar leverages its vertically integrated cadmium telluride production to control costs at utility scale. Qcells anchors its position through Georgia-based manufacturing sustained by domestic content incentives. NextEra Energy dominates project development and long-term power purchase agreement execution across the Southeast and Texas.
Solar photovoltaic systems convert sunlight into direct current electricity through semiconductor junctions, with monocrystalline silicon cells achieving laboratory efficiencies above 26 percent and commercial modules typically ranging from 19 to 22 percent. Utility-scale installations lead absolute capacity additions, while bifacial modules capture expanding share by harvesting reflected light from ground surfaces. Residential deployments sustain premium pricing through net metering structures, though policy fragmentation across state public utility commissions creates margin volatility. Thin-film technology occupies specialized roles in utility applications where temperature coefficients and spectral response advantages offset efficiency gaps.
The Federal Energy Regulatory Commission shapes interstate transmission access, while the Internal Revenue Service administers investment and production tax credit qualification under the Inflation Reduction Act. State renewable portfolio standards in California, New York, and Illinois mandate procurement timelines that pull forward project development cycles. OSHA and state-level electrical codes govern installation workforce safety and system commissioning standards. Stakeholders must monitor interconnection reform proceedings and domestic content rule finalization as these determine project finance viability and supply chain sourcing strategies.
Market Dynamics
The Inflation Reduction Act's domestic content bonus credits are restructuring supply chain economics, forcing developers to requalify module sourcing against Treasury Department guidance while interconnection queue bottlenecks in ERCOT and CAISO delay project energization timelines.
Growth Catalysts
- Data center clean power procurement:Hyperscale operators in Northern Virginia and Phoenix are contracting gigawatt-scale solar capacity to meet carbon-neutral commitments, pulling forward utility-scale development cycles.
- Investment Tax Credit safe harbor:The IRS continuity safe harbor provisions allow projects to preserve credit eligibility despite construction delays, de-risking capital deployment across multi-year build schedules.
- Texas interconnection reform:ERCOT's competitive renewable energy zones and transmission buildout are reducing curtailment risk, concentrating developer activity in West Texas solar belts.
Market Restraints
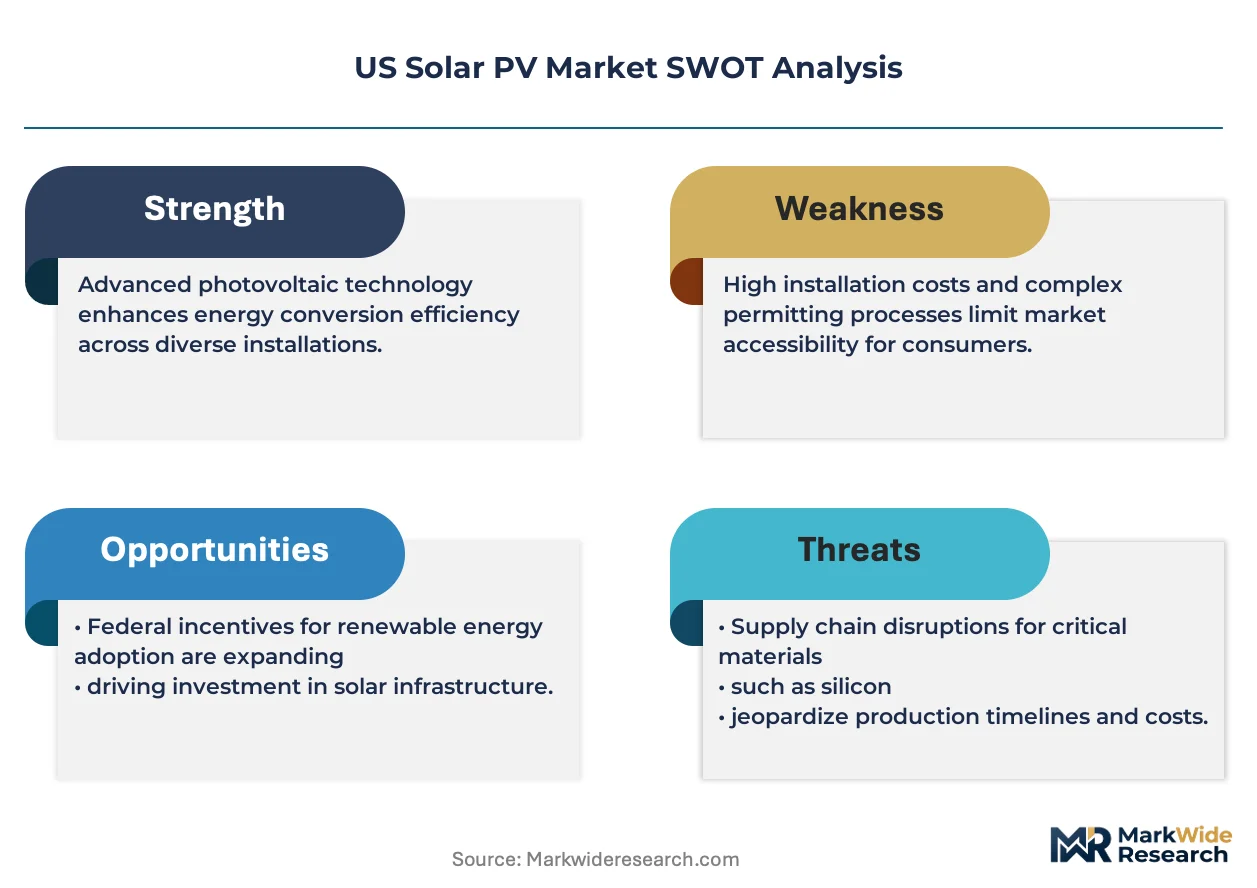
- Polysilicon supply concentration:Xinjiang-sourced polysilicon triggers forced labor rebuttable presumption under UFLPA, complicating import clearance at U.S. ports and forcing supply chain audits.
- Land use permitting friction:County-level zoning restrictions and agricultural land preservation statutes in California's Central Valley limit available acreage for utility-scale arrays.
- Interconnection study backlogs:FERC Order 2023 implementation lags at regional transmission organizations, with cluster study queues extending beyond 36 months in SPP and MISO.
Strategic Opportunities
- Agrivoltaics deployment:Dual-use solar installations on grazing lands and pollinator habitats in Colorado and Minnesota qualify for USDA conservation incentives while generating lease revenue for agricultural operators.
- Bifacial module technology:Albedo harvesting from desert surfaces and snow-covered ground in the Mountain West is expanding capacity factors beyond monofacial baselines.
- Section 45X manufacturing credits:Domestic wafer, cell, and module production incentives are attracting capital to polysilicon-to-module vertical integration projects in the Southeast.
Industry Challenges
- Electrician workforce scarcity:NECA and IBEW training pipeline capacity constraints limit installation crew availability, particularly in markets experiencing simultaneous data center and solar construction booms.
- Domestic content rule ambiguity:Treasury's proposed 40 percent domestic content threshold for full bonus credit eligibility remains in comment period, freezing procurement decisions pending final guidance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Solar PV Market |
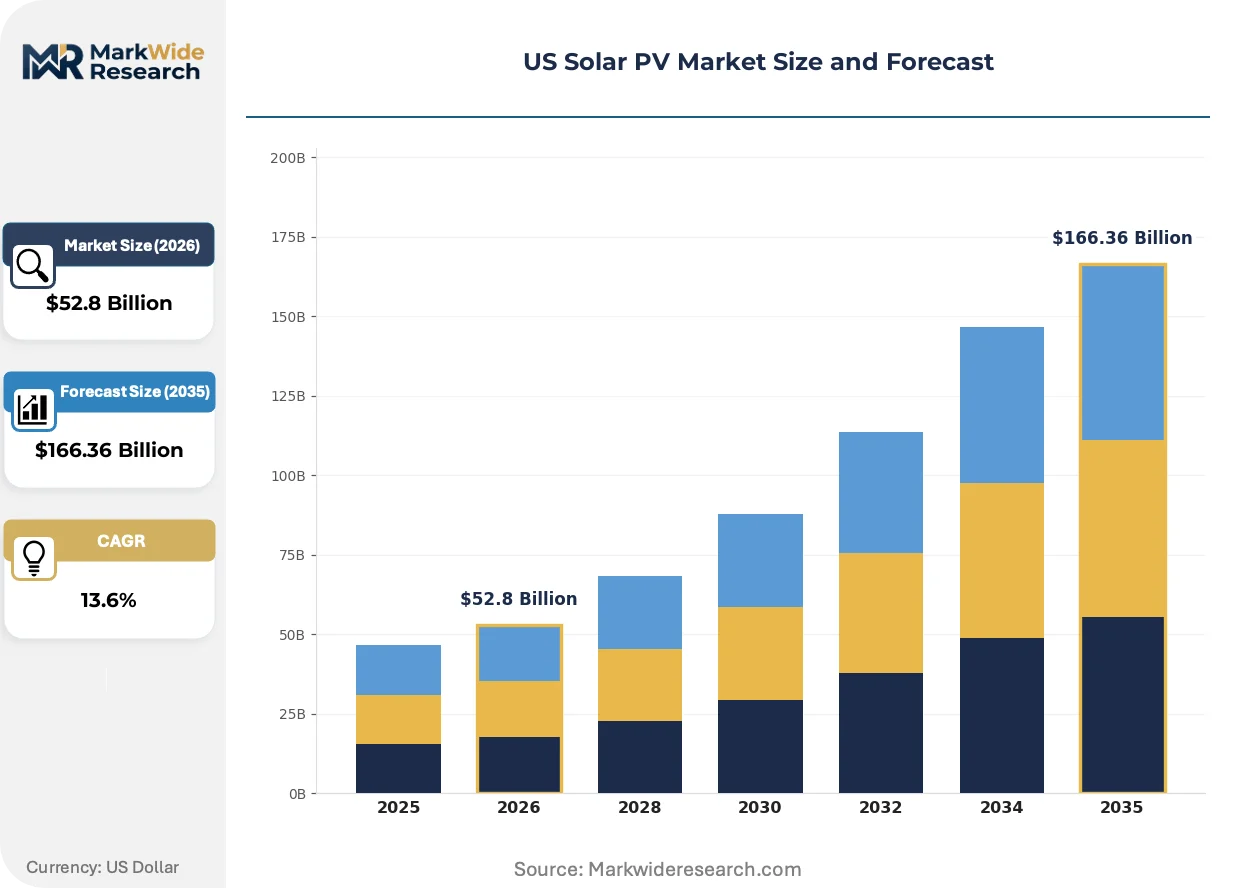
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $166.36 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Installation Type: Residential, Commercial, Utility-scale, Off-grid Material Type: Monocrystalline, Polycrystalline, Thin-film, Bifacial Technology: Grid-tied, Standalone, Hybrid, Tracking systems End User: Homeowners, Businesses, Government, Non-profits |
| Companies Covered | First Solar, Qcells, Canadian Solar, NextEra Energy, SunPower Corporation, Enphase Energy, Illuminate USA, T1 Energy, Sunrun, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Solar PV Market Trends and Innovations
Module efficiency gains and balance-of-system cost compression are converging with software-defined plant controls, reshaping how solar assets participate in wholesale electricity markets and grid services procurement.
Perovskite tandem cell architectures are miniaturizing efficiency gaps between laboratory demonstrations and commercial viability. First Solar and Oxford PV pilot lines are scaling deposition processes for cadmium telluride-perovskite stacks. Utility procurement teams are embedding tandem performance warranties into RFP evaluation criteria, anticipating module efficiencies exceeding 30 percent within the decade.
The IRS domestic content bonus credit regulations are forcing supply chain requalification across module procurement. Developers must trace polysilicon origin through wafer, cell, and module assembly to satisfy 40 percent domestic content thresholds. Southeast manufacturing clusters in Georgia and Alabama are capturing procurement preference as Treasury guidance hardens sourcing requirements.
Corporate offtakers are consolidating clean energy procurement through virtual power purchase agreements rather than direct asset ownership. Data center and semiconductor manufacturers in Arizona and Texas are aggregating demand into multi-buyer VPPA structures. These synthetic hedges transfer operational risk to project sponsors while preserving renewable energy credit claims for Scope 2 emissions accounting.
US Solar PV Market Segmentation
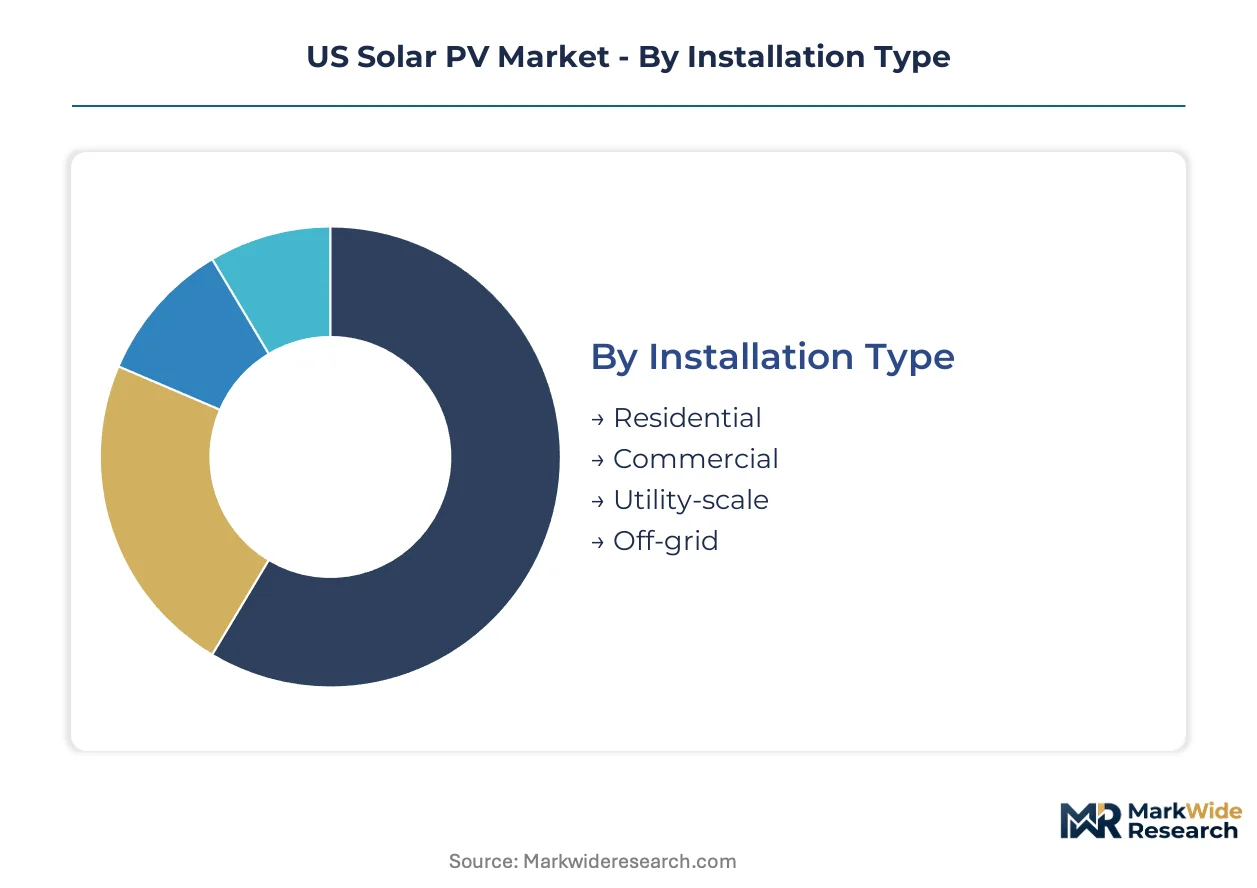
Segmentation in the US Solar PV Market determines how federal incentives, state renewable portfolio standards, and interconnection rules apply differently across deployment scales and technologies. Tax credit eligibility, domestic content requirements, and permitting pathways vary substantially by installation type and end-user classification.
Installation Type:
FERC and state public utility commissions regulate each scale through distinct interconnection standards and net metering frameworks.
- Residential:Rooftop systems under 20 kW AC capacity connect through simplified interconnection procedures in most jurisdictions. California's NEM 3.0 tariff restructuring and Arizona's export rate reductions are compressing payback periods and shifting customer acquisition economics toward battery pairing.
- Utility-scale:Ground-mounted arrays exceeding 5 MW AC capacity dominate absolute capacity additions and qualify for full Investment Tax Credit or Production Tax Credit benefits. ERCOT's West Texas solar belts and California's Central Valley concentrate development activity where land availability and transmission access align.
- Commercial:Behind-the-meter installations serving retail, manufacturing, and logistics facilities typically range from 100 kW to 2 MW. C&I offtakers leverage accelerated depreciation schedules and green bond financing to improve project returns.
- Off-grid:Standalone systems power remote agricultural operations, telecommunications infrastructure, and rural residences beyond distribution grid reach. USDA REAP grants support deployment in persistently poor counties across Appalachia and the Great Plains.
Utility-scale handles the majority of throughput; residential is expanding most quickly on share as battery costs decline and NEM reforms stabilize.
Material Type:
Module chemistry determines efficiency profiles, temperature coefficients, and eligibility for domestic content bonus credits under Treasury guidance.
- Monocrystalline:Single-crystal silicon cells achieve the highest commercial efficiencies, typically 19-22 percent for standard modules and up to 24 percent for premium lines. Residential and commercial rooftops in space-constrained markets favor these modules despite higher per-watt costs.
- Thin-film:Cadmium telluride and copper indium gallium selenide technologies offer superior spectral response and lower temperature coefficients. First Solar's Ohio and Alabama manufacturing facilities supply utility-scale projects seeking to satisfy domestic content thresholds.
- Polycrystalline:Multi-crystal silicon modules trade efficiency for cost advantages in price-sensitive developing markets. US procurement has shifted away from this technology as monocrystalline manufacturing scales drove cost convergence.
- Bifacial:Dual-glass constructions harvest reflected light from albedo surfaces, expanding capacity factors 5-15 percent above monofacial baselines. Desert installations in Arizona and snow-covered ground in Colorado maximize this technology's yield advantages.
Monocrystalline commands the largest installed base; bifacial is gaining share fastest as albedo modeling improves and tracking system compatibility spreads.
Technology:
System architecture choices determine grid services participation, resilience value, and inverter loading ratios that shape project economics.
- Grid-tied:Systems without storage export all generation to the distribution network under net energy metering or wholesale market arrangements. IEEE 1547-2018 interconnection standards govern voltage ride-through and reactive power capabilities.
- Hybrid:Solar-plus-storage configurations pair photovoltaic arrays with lithium-ion batteries to shift generation and provide capacity services. ERCOT's ancillary services market and California's Resource Adequacy requirements pull forward hybrid deployment.
- Standalone:Off-grid systems incorporate battery storage and backup generation for complete energy independence. Remote mining operations and military microgrids in the Southwest prioritize this architecture.
- Tracking systems:Single-axis and dual-axis trackers follow solar azimuth to boost energy yield 15-25 percent over fixed-tilt baselines. Large-format modules and improved drive reliability are reducing tracker cost premiums for utility-scale projects.
Grid-tied configurations account for the dominant share of capacity; hybrid systems are climbing the fastest as battery costs fall and capacity markets mature.
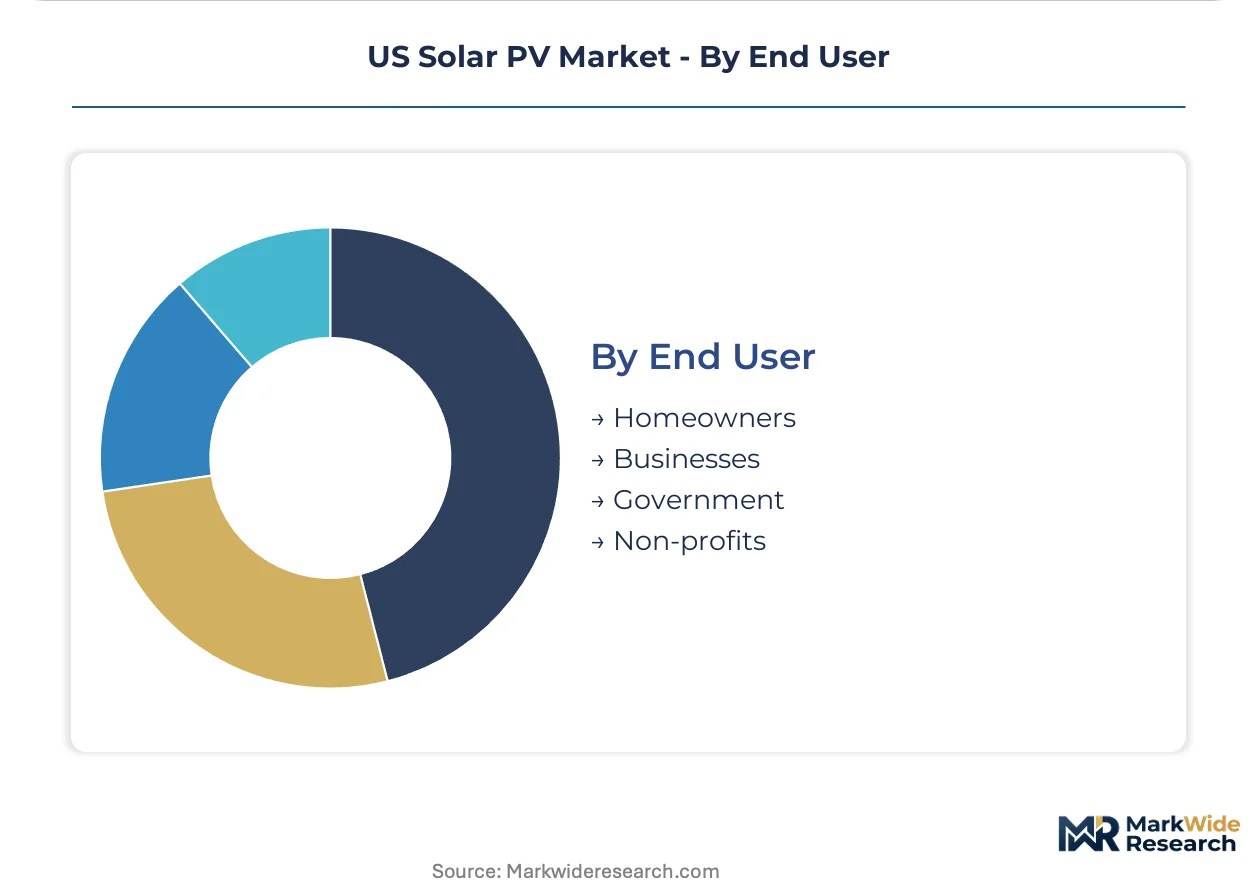
End User:
Customer tax status, offtake contract structures, and sustainability disclosure requirements segment procurement behavior and financing approaches.
- Businesses:Corporate offtakers execute virtual power purchase agreements and on-site leases to meet Scope 2 emissions targets. Data center operators in Northern Virginia and semiconductor manufacturers in Arizona aggregate demand into multi-buyer VPPA structures.
- Government:Federal agencies, state entities, and municipal utilities procure through power purchase agreements subject to Buy American Act compliance. Defense Department installations prioritize cyber-secure inverters and domestic supply chains under EO 14017.
- Homeowners:Individual residential customers finance through loans, leases, or property-assessed clean energy assessments. State-level solar property tax exemptions and sales tax holidays influence adoption timing.
- Non-profits:Tax-exempt entities cannot directly monetize Investment Tax Credits and rely on third-party ownership or direct pay elective under IRA Section 6417. Churches, schools, and community development organizations in low-income communities qualify for additional bonus credits.
Business offtakers drive the majority of contracted capacity; government procurement is steepest expansion trajectory as federal clean electricity mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas developers exhibit the highest price elasticity to interconnection timelines, while California buyers prioritize domestic content compliance over per-watt premiums. This demand-elasticity contrast shapes regional procurement strategies across the US solar PV landscape.
Texas
West Texas solar belts attract gigawatt-scale deployment through ERCOT's competitive renewable energy zones and transmission buildout. FERC Order 2023 implementation lags complicate cluster study timelines, though the state leads absolute capacity additions. The Permian Basin and Rio Grande Valley concentrate developer activity where land availability and grid access align.
California
Central Valley agricultural land preservation statutes limit utility-scale acreage, pushing development toward desert regions. The California Public Utilities Commission's NEM 3.0 tariff restructuring compresses residential payback periods. Imperial County and Riverside County host the state's largest operating solar farms under IOU procurement mandates.
Arizona
Phoenix-area hyperscale data centers contract clean power to meet carbon-neutral commitments, pulling forward utility-scale development. The Arizona Corporation Commission's export rate reductions shift customer acquisition economics toward battery pairing. Maricopa County and Pima County dominate installation throughput.
Georgia
Southeast manufacturing clusters capture procurement preference as Treasury domestic content guidance hardens. The state's renewable portfolio standard mandates pull forward project development cycles. Metro Atlanta anchors Qcells' vertically integrated production serving utility-scale offtakers.
Colorado
Mountain West bifacial deployments maximize albedo harvesting from snow-covered ground. USDA conservation incentives support agrivoltaics installations on grazing lands and pollinator habitats. Weld County and Pueblo County lead county-level permitting approvals for dual-use solar arrays.
US Solar PV Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the US solar PV market. The vendor base organizes into three tiers: vertically integrated thin-film specialists, domestic-content-compliant crystalline silicon manufacturers, and project development platforms with long-term PPA execution capabilities. Consolidation pressures intensify as Treasury domestic content rules freeze procurement decisions. Dominant competitive moves include manufacturing capacity expansion in the Southeast and strategic partnerships securing interconnection queue positions.
Among thin-film specialists, First Solar exemplifies vertically integrated cadmium telluride production. Qcells occupies a position within the domestic-content-compliant tier through Georgia-based manufacturing. NextEra Energy anchors the project development platform archetype across the Southeast and Texas, representing scale-driven execution capabilities in long-term power purchase agreement markets.
| Leading Market Players |
|---|
| First Solar |
| Qcells |
| Canadian Solar |
| NextEra Energy |
| SunPower Corporation |
| Enphase Energy |
| Illuminate USA |
| T1 Energy |
| Sunrun |
| Others |
Pricing and Supply Chain Analysis
IRA domestic content bonus credit regulations simultaneously gate supply qualification and price differentiation across module procurement tiers. Treasury's 40 percent domestic content threshold forces developers to trace polysilicon origin through wafer, cell, and module assembly, compressing margins on non-compliant imports while Southeast manufacturing captures procurement premiums.
Pricing Analysis
After-sales service contracts and performance warranties drive lifetime value capture across utility-scale deployments. Three-tier pricing structure across premium domestic-content modules, standard compliant imports, and economy non-compliant tiers reflects certification grade and domestic assembly location. Cost compression in standard tiers intensifies because Southeast manufacturing scale is narrowing efficiency gaps with premium lines. Utility offtakers exhibit lowest price sensitivity as IRA credits offset module premiums, while residential installers face acute margin pressure from NEM 3.0 tariff restructuring.
Supply Chain Analysis
Inventory lead times for polysilicon and aluminum frames have extended as customs enforcement under UFLPA complicates port clearance. Module assembly draws from Southeast manufacturing clusters in Georgia and Alabama, polysilicon purification in Tennessee, and wafer slicing capacity developing in the Carolinas. Single-source vulnerability concentrates in metallurgical-grade silicon feedstock and silver paste for cell metallization. Distribution runs through EPC contractors and utility procurement desks rather than wholesale channel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic content rule finalization fragments procurement into compliance-tiered niches. Data center clean power mandates create specialized offtake segments rewarding rapid IRA qualification.
For Market Incumbents: Fortify Southeast manufacturing footprints through captive wafer and cell capacity additions in Georgia and Alabama. Secure interconnection queue positions in ERCOT and CAISO before cluster study backlogs extend further. Prioritize Treasury guidance compliance certification to defend against thin-film specialists capturing domestic content premiums.
For New Entrants and Emerging Players: Lead with agrivoltaics development in Colorado and Minnesota where USDA conservation incentives reduce land cost barriers. Target commercial and industrial behind-the-meter segments in Arizona where export rate reductions are accelerating battery pairing demand. Pursue strategic partnerships with agricultural landholders for dual-use site control.
For Investors and Strategic Acquirers: IRA Section 45X manufacturing credit finalization reshapes the acquisition landscape toward polysilicon-to-module vertical integration targets. Five-to-ten year viability hinges on Treasury domestic content threshold durability and interconnection reform implementation pace. Monitor FERC Order 2023 cluster study timeline compression as the signal indicating developer margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Southeast Manufacturing Capacity Buildout | Captures IRA Section 45X credits while satisfying Treasury domestic content thresholds for bonus eligibility. |
| Utility-Scale Power Purchase Agreement Execution | Locks in long-term revenue streams with data center operators in Northern Virginia and Phoenix markets. |
| Thin-Film Technology Licensing | Transfers cadmium telluride deposition expertise to new entrants seeking temperature coefficient advantages. |
| Vertical Integration into Polysilicon Purification | Secures UFLPA-compliant feedstock supply while qualifying for upstream manufacturing incentives. |
| Green Certification Program Development | Aligns module production with corporate offtaker Scope 2 emissions accounting requirements. |
Research Methodology
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base. Primary interviews with ERCOT and CAISO interconnection queue managers supplemented secondary validation through EIA capacity data, FERC filing records, IEA renewable market reports, and Treasury guidance comment filings. Bottom-up project development pipeline aggregation triangulated against top-down state renewable portfolio standard procurement mandates.
Sensitivity analysis tested module cost trajectories, interconnection timeline scenarios, and domestic content threshold variations across the projection horizon. Segmentation dimensions modeled include installation scale, material chemistry, system architecture, and end-user tax status. CAGRs derived from capacity addition forecasts incorporating IRA credit phase-down schedules and regional transmission buildout timelines. Forecast inputs encompassed hyperscaler data center power demand disclosures and county-level zoning restriction databases.
The analysis sits within stated boundaries; outcomes outside sustained IRA credit extension and interconnection reform implementation would require recalibration. Forecasts reflect assumptions regarding Treasury domestic content guidance finalization and UFLPA enforcement intensity. Revision becomes warranted when FERC Order 2023 cluster study timelines exceed 48 months or Section 45X credit values adjust downward.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Rooftop Solar PV Market
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
Egypt Solar Photovoltaic (PV) Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
US Solar Market
Solar Power Systems
Solar Panel Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Photovoltaic Solar Kits Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Organic Solar Cells Market