
 Indonesia Renewable Energy Market | 2026-2036
Indonesia Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Renewable Energy Market Foresight
Independent power producer procurement is narrowing as state utility offtake agreements consolidate around fewer, larger developers. Pertamina Geothermal Energy leverages its subsurface expertise and existing concession holdings to dominate geothermal baseload development. PT Barito Renewables Energy anchors its position through captive coal-to-renewables transitions and utility-scale solar pipelines. Canadian Solar Inc. competes on module cost and regional supply chain proximity, while Star Energy Geothermal sustains operational excellence across mature Darajat and Wayang Windu fields.
Indonesia renewable energy encompasses electricity generation from solar irradiance, geothermal reservoirs, hydropower cascades, and wind streams converted through turbines, inverters, and binary cycle plants into grid-synchronous alternating current with typical geothermal brine temperatures exceeding 150°C serving base-load dispatch. Photovoltaic deployment leads capacity additions due to modular installation and declining module costs, while geothermal commands premium tariffs reflecting its baseload reliability and high capital intensity. Industrial applications represent the fastest-growing demand segment as smelters, data centers, and textile manufacturers seek direct power purchase agreements to offset fossil fuel exposure and meet buyer sustainability requirements.
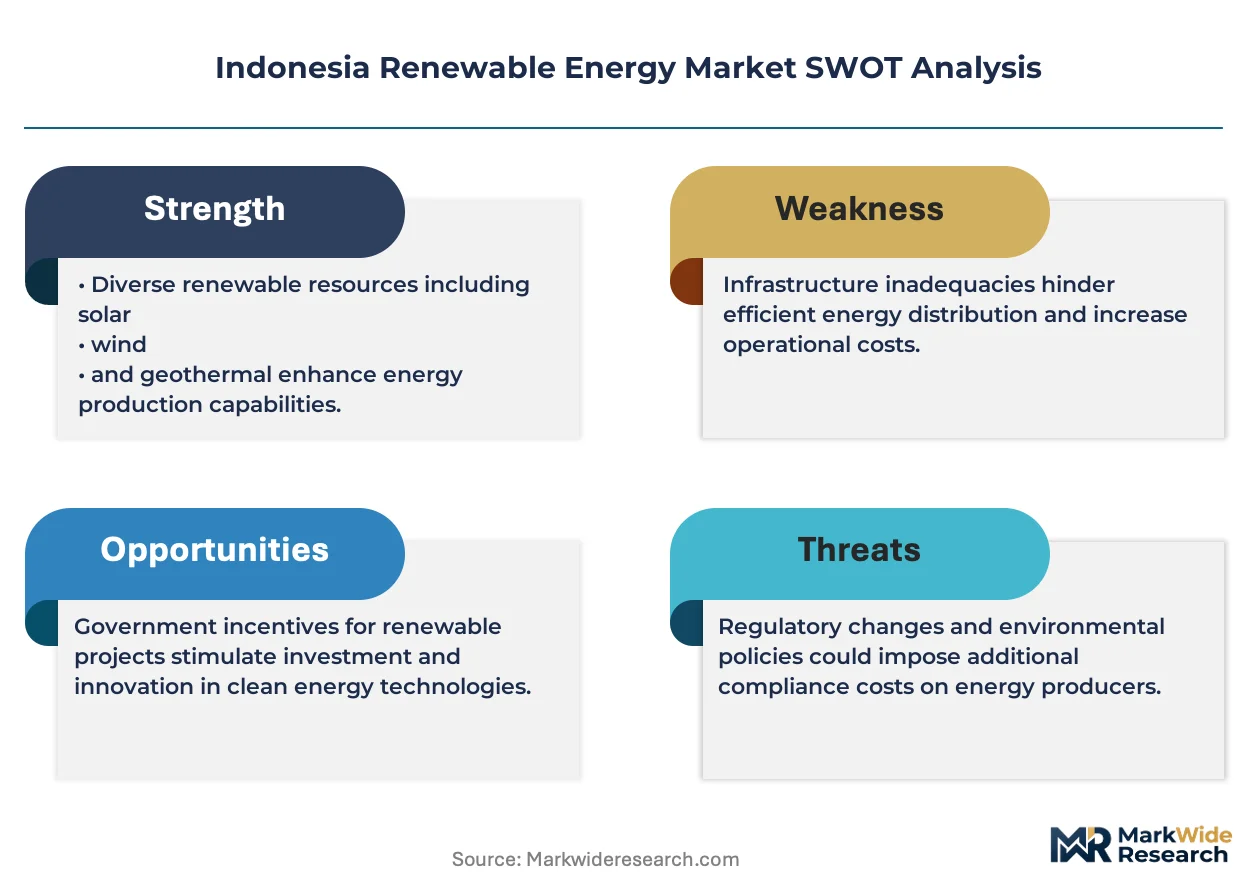
MEMR tariff regulations and PLN's renewable energy purchase framework shape project bankability, while BIS-equivalent certification and CEA grid codes govern equipment standards and interconnection compliance. Provincial governments in East Nusa Tenggara and North Sulawesi are issuing local permits that accelerate or obstruct site access, creating fragmented approval timelines. Stakeholders must monitor PLN's RUPTL revision cycles and provincial spatial planning conflicts to anticipate offtake window openings and land-use constraints.
Market Dynamics
PLN's renewable energy purchase obligations under MEMR regulations are consolidating offtake around fewer developers with proven execution capacity, compressing procurement timelines while raising capital barriers for new entrants.
Growth Catalysts
- MEMR Tariff Framework:The Ministry of Energy and Mineral Resources has established feed-in tariff structures that improve geothermal and solar project bankability, attracting infrastructure capital toward utility-scale developments.
- Industrial Direct PPA Demand:Smelters, data centers, and textile manufacturers in Java-Bali are executing bilateral power purchase agreements to secure renewable supply and meet buyer sustainability mandates.
- Geothermal Concession Consolidation:Existing license holders with subsurface data and drilling capabilities are accelerating field development, leveraging prior exploration investments to reduce development risk.
Market Restraints
- Grid Interconnection Bottlenecks:Java-Bali transmission capacity constraints delay project energization, forcing developers to absorb extended commissioning timelines and carrying costs.
- Local Content Requirements:BIS-equivalent certification mandates for solar modules and inverters limit supplier pools, creating procurement friction and equipment cost premiums.
- Land-Use Spatial Conflicts:Provincial spatial planning in East Nusa Tenggara and North Sulawesi creates permitting fragmentation, with overlapping forest conservation and agricultural designations blocking site access.
Strategic Opportunities
- Captive Coal-to-Renewables Transition:Industrial estates with embedded coal generation are retrofitting for solar-plus-storage hybrid systems, opening retrofit engineering and EPC contracts.
- Remote Island Electrification:Mini-grid and distributed solar-wind hybrid architectures in Maluku and Papua address PLN's universal access mandates outside the main interconnection backbone.
- Green Hydrogen Feedstock Supply:Excess renewable generation in South Sulawesi and Sumatra is attracting electrolyzer investments for ammonia and industrial hydrogen export production.
Industry Challenges
- Geothermal Reservoir Engineering Talent:Specialist geoscientists and drilling engineers with high-temperature brine experience command premium compensation, constraining project staffing velocity.
- CEA Grid Code Compliance:Central Electricity Authority interconnection standards require extensive modeling and testing protocols, extending project approval cycles by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Renewable Energy Market |
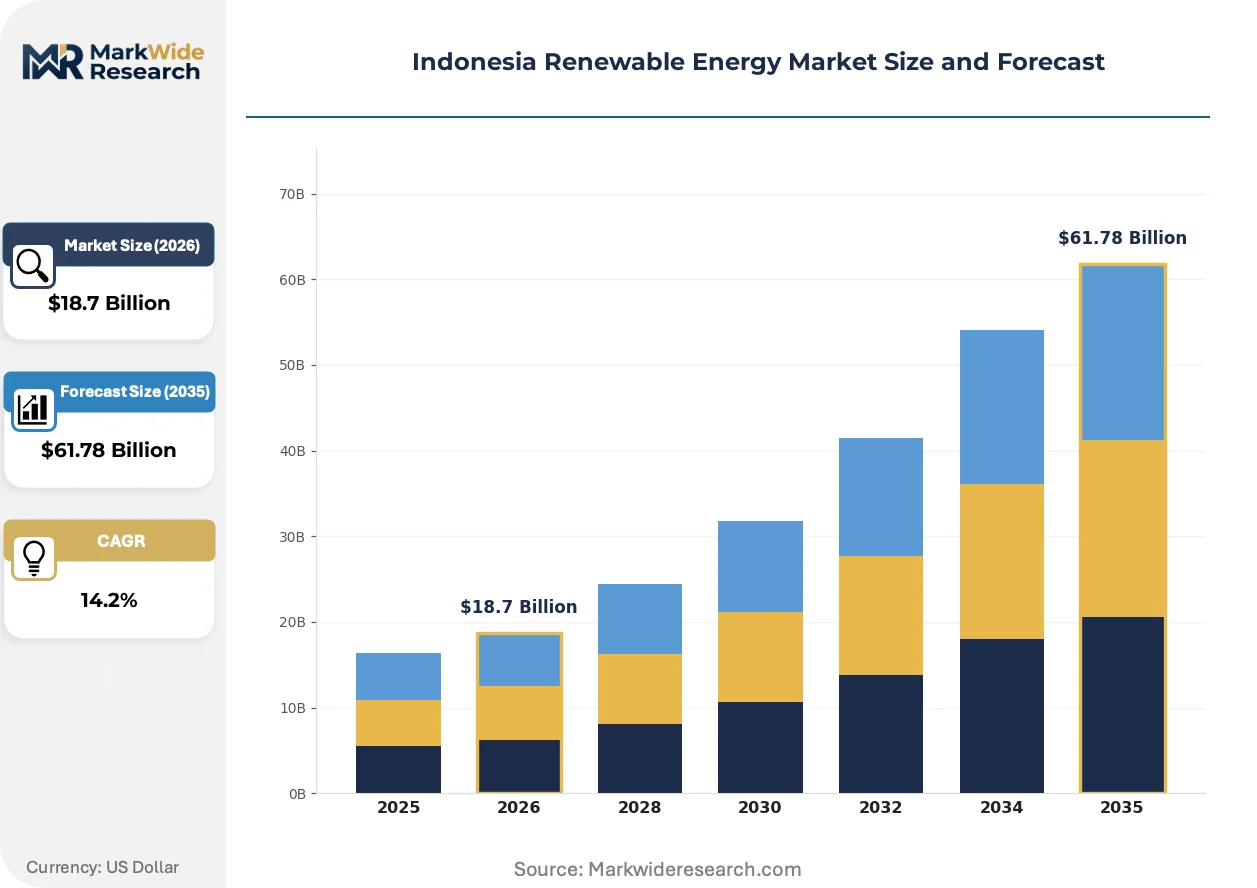
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Hydro, Geothermal Technology Type: Photovoltaic, Wind Turbines, Biomass, Ocean Energy Application: Power Generation, Off-Grid Solutions, Residential Systems, Industrial Applications End User: Utilities, Commercial, Residential, Government |
| Companies Covered | Pertamina Geothermal Energy, PT Sumber Energi Sukses Makmur, BCPG Public Company Limited, Star Energy Geothermal, TotalEnergies ENEOS, Canadian Solar Inc., Trina Solar Ltd, Sindicatum Renewable Energy Company, PT Barito Renewables Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Renewable Energy Market Shifts & Advancements
Technology convergence between solar photovoltaic and battery energy storage is restructuring project economics, while regulatory instruments and buyer procurement patterns accelerate deployment models away from traditional utility-centric frameworks.
Bifacial solar modules with tracking systems is migrating from premium demonstration projects to standard configuration for utility-scale developers. IPP engineering teams specify these architectures to capture elevated irradiance on Java's northern coastal plains. The technology is migrating from niche applications to baseline procurement specifications, compressing LCOE benchmarks and forcing module suppliers to reconfigure regional product portfolios.
MEMR's renewable energy tariff regulations have introduced ceiling and floor pricing mechanisms that index geothermal and solar tariffs to regional production costs. Developers must now model fuel price linkage formulas into long-term offtake agreements. Geothermal baseload projects face the most pronounced adjustment, as their capital-intensive structures require tariff stability across multi-decade contract horizons.
Direct corporate power purchase agreements are displacing traditional PLN-mediated procurement for industrial offtakers. Smelters and data center operators in Batang and Bekasi are negotiating sleeved contracts with renewable developers, bypassing utility intermediation. This pattern concentrates in Java-Bali load centers where grid access and creditworthy counterparties coincide.
Indonesia Renewable Energy Market Segmentation
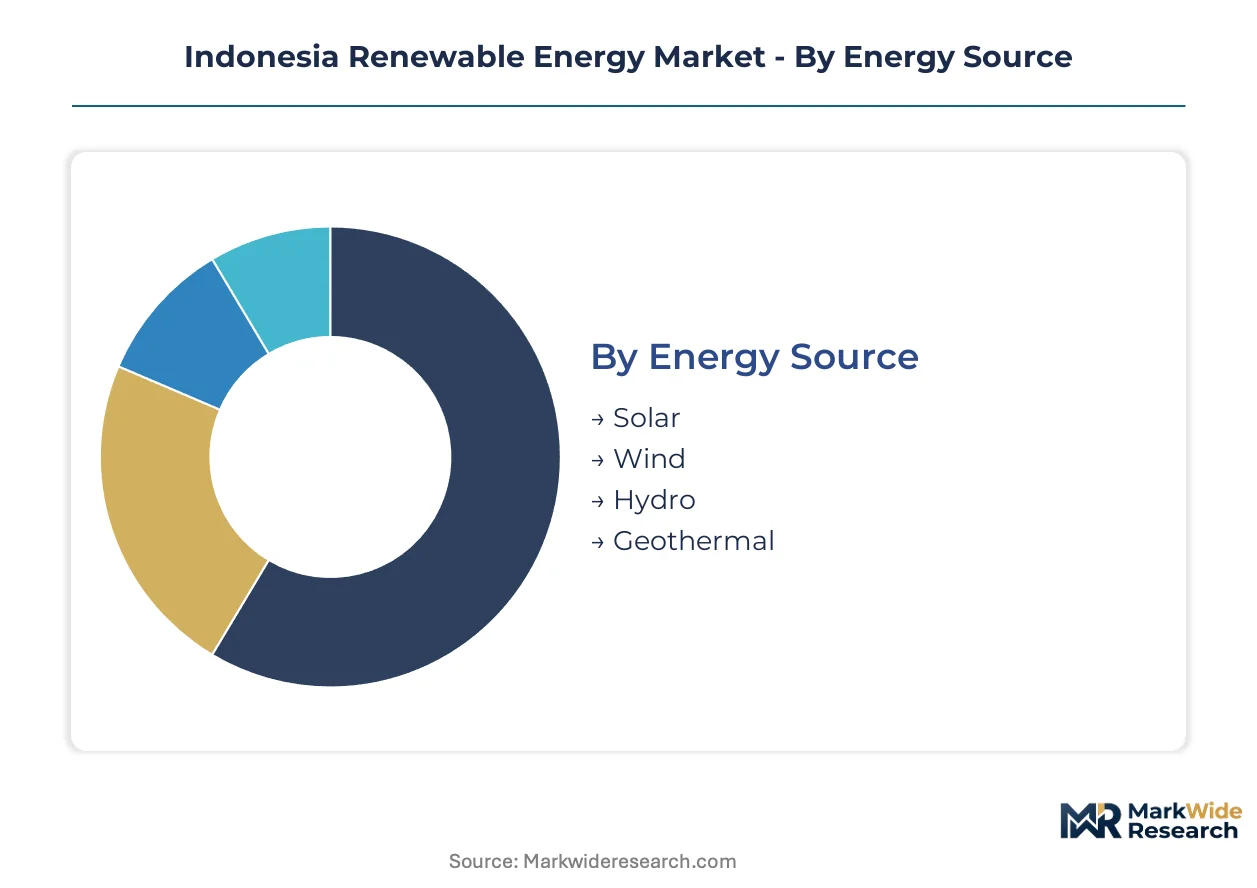
Segmentation clarity determines capital allocation precision across Indonesia's renewable buildout. PLN's procurement consolidation and MEMR tariff indexing reward developers who align technology choices with specific offtake windows and grid access points.
Energy Source:
After-sales service intensity varies sharply across thermal versus intermittent sources, with baseload technologies demanding reservoir engineering contracts and O&M specialization that intermittent sources rarely require.
- Geothermal:Binary and flash-cycle plants extract heat from volcanic reservoirs with brine temperatures exceeding 150°C, requiring continuous subsurface monitoring and scale management. Java's smelter corridor and Bali's tourism load centers anchor demand, though reservoir engineering talent scarcity constrains project velocity.
- Solar:Photovoltaic arrays convert irradiance through monocrystalline and bifacial modules with minimal moving parts, lowering O&M intensity but demanding rapid inverter replacement capabilities. Deployment concentrates on Java's northern coastal plains where PLN's transmission backbone meets industrial estates.
- Wind:Horizontal-axis turbines capture seasonal monsoon patterns across South Sulawesi and Nusa Tenggara with capacity factors below geothermal baseload. Site access challenges in remote archipelagos limit service network density.
- Hydro:Run-of-river and small-scale cascade installations leverage Indonesia's steep topography and high rainfall, though sediment management and seasonal flow variation drive maintenance scheduling complexity.
By volume, Solar leads. By growth pace, Geothermal is ahead.
Technology Type:
Cost tier stratification separates mature mass-manufactured equipment from emerging technology platforms requiring demonstration-scale deployment.
- Photovoltaic:Crystalline silicon modules dominate utility-scale procurement with declining unit costs and established BIS-equivalent certification pathways. Java-Bali industrial offtakers specify these systems for direct PPA execution.
- Wind Turbines:Onshore horizontal-axis machines adapt to Indonesia's lower wind speeds through larger rotor diameters and taller hub heights. Nusa Tenggara's narrow islands present logistical constraints for component transport.
- Biomass:Agricultural residue and palm oil waste combustion plants serve captive industrial demand in Sumatra and Kalimantan, though feedstock supply chain reliability varies with plantation harvest cycles.
- Ocean Energy:Tidal and wave conversion prototypes remain pre-commercial, with MEMR demonstration tariffs insufficient to attract project finance for pilot installations in the Maluku archipelago.
By installed base, Photovoltaic leads. By margin structure, Geothermal commands premium returns.
Application:
Customer type fragmentation distinguishes centralized utility procurement from distributed behind-the-meter deployment with divergent interconnection standards.
- Power Generation:Utility-scale projects feed PLN's transmission network under MEMR tariff frameworks, requiring CEA grid code compliance and extended approval timelines. These developments anchor Indonesia's RUPTL capacity targets.
- Industrial Applications:Captive generation at smelters, data centers, and textile facilities bypasses PLN intermediation through sleeved bilateral contracts. Batang and Bekasi industrial zones concentrate this demand.
- Off-Grid Solutions:Mini-grid and standalone systems address universal electrification mandates in Maluku and Papua outside the Java-Bali interconnection backbone. Diesel displacement drives procurement economics.
- Residential Systems:Rooftop solar with net metering serves urban households in Jakarta and Surabaya, though financing penetration remains limited by mortgage-style product availability.
By capital deployment, Power Generation leads. By contract velocity, Industrial Applications is accelerating.
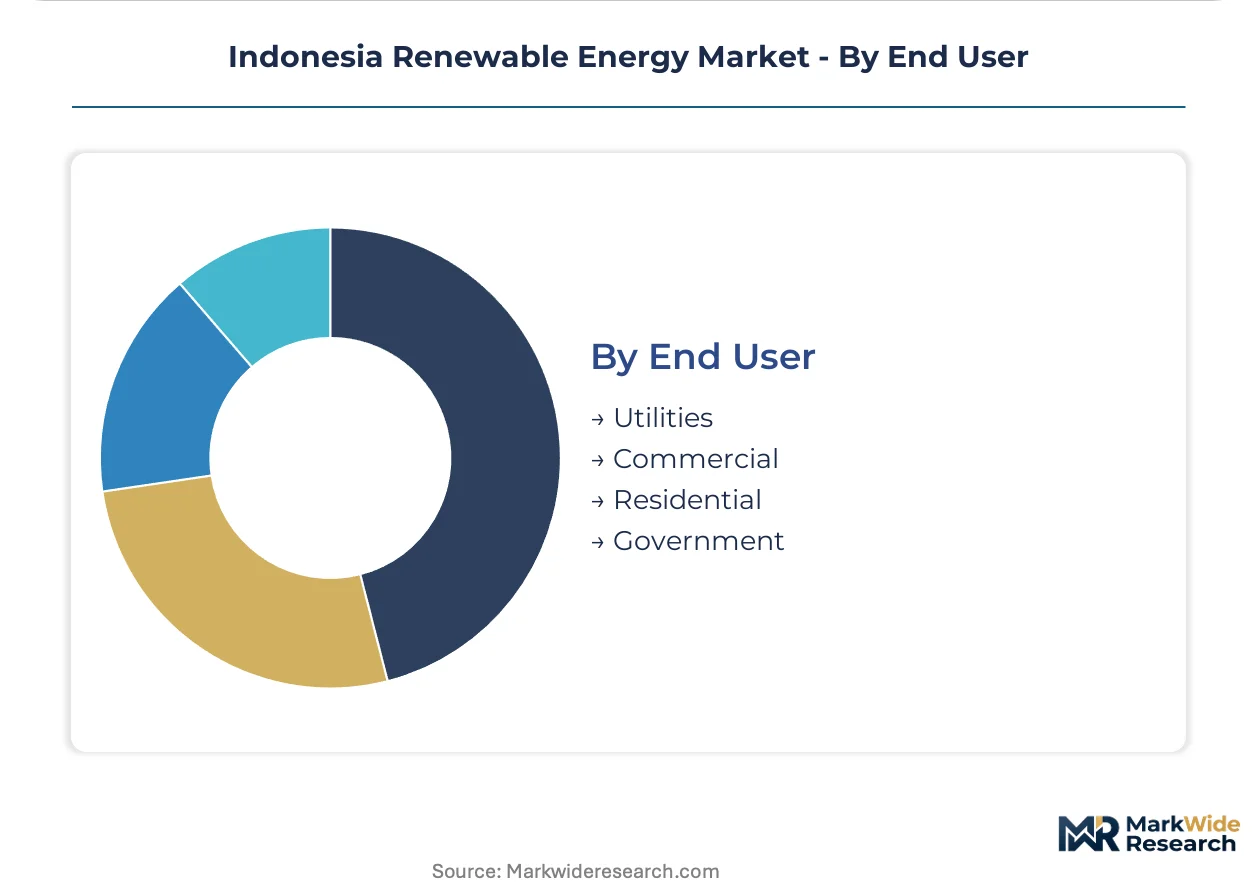
End User:
Volume concentration tracks creditworthiness hierarchies, with state-backed offtakers absorbing development risk that commercial counterparties transfer to developers.
- Utilities:PLN and regional distribution entities procure under renewable purchase obligations with sovereign-backed payment security. MEMR regulations shape tariff ceilings and floor pricing mechanisms.
- Commercial:Corporate offtakers in manufacturing, mining, and digital infrastructure execute direct PPAs to meet buyer sustainability mandates and offset fossil fuel exposure.
- Government:Public buildings and municipal infrastructure deploy rooftop solar under national green building directives, with procurement fragmented across provincial tender processes.
- Residential:Individual households purchase systems through dealer networks with limited financing integration, constraining market penetration outside affluent urban districts.
By project scale, Utilities lead. By growth momentum, Commercial is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEMR regulations anchor development across Indonesia's archipelago, with Java-Bali absorbing the majority of utility-scale procurement while outer islands pursue distributed solutions under PLN's electrification mandates.
Java-Bali
Industrial estates in Batang and Bekasi drive demand for direct corporate PPAs as smelters and data centers seek renewable supply. MEMR's tariff ceiling and floor mechanisms shape project bankability for developers interconnecting to PLN's transmission backbone. Grid congestion in West Java delays energization timelines, forcing developers to absorb extended commissioning costs.
Sumatra
Palm oil processing clusters in North Sumatra and Riau generate captive biomass demand alongside emerging utility-scale solar pipelines. Provincial spatial planning conflicts with forest conservation designations obstruct site access in upland areas. PLN's RUPTL revision cycles determine offtake window availability for independent power producers.
Sulawesi
Nickel smelter corridors in South Sulawesi anchor industrial direct PPA execution as operators seek to meet buyer sustainability mandates. MEMR demonstration tariffs for ocean energy remain insufficient to attract project finance for tidal prototypes in the Makassar Strait. Remote mini-grid architectures address universal access mandates outside the main interconnection backbone.
East Nusa Tenggara
Seasonal monsoon patterns support wind deployment across narrow island geographies with capacity factors below geothermal baseload. Provincial governments issue local permits that accelerate or obstruct site access, creating fragmented approval timelines. Diesel displacement economics drive distributed solar-wind hybrid procurement in off-grid settlements.
Maluku and Papua
Universal electrification mandates outside the Java-Bali interconnection backbone concentrate mini-grid deployment in archipelagic settlements. PLN's remote island electrification program absorbs distributed generation solutions despite higher per-kWh delivery costs. Land-use spatial conflicts with indigenous territorial claims complicate site development in Papua's highland regions.
Indonesia Renewable Energy Market Competitive Landscape
State-affiliated energy conglomerates and independent power producers split the market between geothermal baseload dominance and solar capacity expansion. Consolidation pressures favor developers with proven execution records and existing concession holdings. Three archetypes prevail: integrated state energy groups with subsurface expertise, regional IPPs executing coal-to-renewables transitions, and international module suppliers competing on cost proximity. Competitive moves center on concession consolidation and direct corporate PPA origination.
Within the state-affiliated tier, Pertamina Geothermal Energy exemplifies subsurface capability leverage through existing volcanic reservoir holdings. PT Barito Renewables Energy occupies a position bridging captive industrial transition and utility-scale solar development. Canadian Solar Inc. represents the international equipment supplier archetype competing on module cost and regional supply chain proximity.
| Leading Market Players |
|---|
| Pertamina Geothermal Energy |
| PT Sumber Energi Sukses Makmur |
| BCPG Public Company Limited |
| Star Energy Geothermal |
| TotalEnergies ENEOS |
| Canadian Solar Inc. |
| Trina Solar Ltd |
| Sindicatum Renewable Energy Company |
| PT Barito Renewables Energy |
| Others |
Supply & Pricing Matrix
Chinese crystalline silicon module manufacturing concentration feeds directly into margin compression for Indonesian utility-scale solar developers, while MEMR tariff ceilings cap downstream price recovery and force EPC contractors to absorb equipment volatility through fixed-price contracts.
Pricing Analysis
Java-Bali solar projects command modest premiums over Sumatra developments due to grid proximity and industrial offtaker density, though price differentiation stems primarily from BIS-equivalent certification tiers and after-sales service bundling rather than module quality alone. Pricing pressure intensifies as bifacial module commoditization erodes technology premiums and PLN consolidates procurement around fewer developers with execution track records. Industrial direct PPA buyers in Batang and Bekasi exhibit lowest price sensitivity due to sustainability mandate compliance requirements, while remote mini-grid procurement in Maluku faces acute cost constraints from diesel displacement economics.
Supply Chain Analysis
Chinese module suppliers and Taiwanese inverter manufacturers hold dominant contract-manufacturing capacity serving Indonesian project pipelines, with South Korean and Japanese component specialists anchoring premium tier equipment for geothermal balance-of-plant systems. Polysilicon feedstock and lithium-ion storage cells draw from concentrated East Asian supply bases, creating tariff exposure from regional trade policy shifts. Distribution runs through Singapore-based trading houses for bulk equipment import, with local EPC firms managing final-mile logistics and customs clearance for Java-Bali project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's renewable energy market fragments across technology archetypes and geographic access tiers, with PLN procurement consolidation and industrial direct PPA emergence creating distinct competitive arenas for specialized players.
For Market Incumbents: Build subsurface data moats through geothermal reservoir monitoring networks and drilling capability retention. Consolidate concession holdings in Java's volcanic corridors before MEMR licensing windows narrow. Defensive moves center on locking in long-term O&M contracts for mature fields like Darajat and Wayang Windu, while expanding solar EPC capacity to capture coal-to-renewables retrofit demand from captive industrial generators facing buyer sustainability audits. For New Entrants and Emerging Players: East Nusa Tenggara wind development presents accessible entry points with lower incumbent saturation and provincial permit frameworks that reward local partnership structures. Mini-grid solar-wind hybrid architectures in Maluku and Papua offer white-space deployment under PLN's universal access mandates, with diesel displacement economics supporting viable tariffs outside MEMR ceiling constraints. Go-to-market positioning should emphasize remote logistics execution and community land-use negotiation capabilities rather than utility-scale capital scale. For Investors and Strategic Acquirers: Capital is best deployed toward geothermal developers with proven reservoir engineering teams and existing exploration license holdings, given the decade-long development cycles and specialized talent scarcity that protect incumbent positions. Acquisition screening should prioritize firms with operational assets in Java's smelter corridor and bilateral PPA origination capabilities. The inflection signal to monitor is PLN's RUPTL revision cadence and provincial spatial planning conflicts that accelerate or obstruct site access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Geothermal Concession Consolidation | Existing license holders with subsurface data reduce development risk and accelerate field commissioning timelines. |
| Industrial Direct PPA Origination | Bilateral contracts with Batang smelters and Bekasi data centers bypass PLN intermediation and capture premium tariffs. |
| Captive Coal-to-Renewables Transition | Retrofit engineering for solar-plus-storage hybrid systems opens EPC contracts at industrial estates with embedded generation. |
| Remote Mini-Grid Deployment | Distributed architectures in Maluku and Papua address universal access mandates with higher per-kWh delivery economics. |
| Green Hydrogen Feedstock Supply | Excess renewable generation in South Sulawesi attracts electrolyzer investments for ammonia export production. |
Research Methodology
Cross-validation between PLN procurement databases and MEMR regulatory filings anchors the qualitative findings on tariff framework evolution and offtake window timing. Primary interviews with IPP project developers, utility planning officers, EPC contractors, and grid operators combined with secondary validation from IEA country reports, IRENA technology roadmaps, and Indonesian customs trade data support bottom-up and top-down triangulation across technology segments.
Calibration against historical capacity additions and announced project pipelines shapes the projection framework across the analysis window. Segmentation dimensions modeled include energy source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derive from equipment cost trajectory assumptions, interconnection queue velocities, and industrial electricity demand elasticity. Key inputs incorporate bifacial module price curves, geothermal drilling cost inflation, and PLN RUPTL revision cycles.
The forecast holds incumbent behavior within observed patterns; aggressive concession acquisition moves by state-affiliated energy groups or sudden MEMR tariff ceiling adjustments would shift outcomes materially. Regulatory uncertainty around provincial spatial planning and CEA grid code compliance timelines present specific revision risks. Quarterly review of PLN procurement announcements, provincial permit issuance rates, and module import customs data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
Ground Mount PV Utility Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
Solar Cullet Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
Solar Power Tracker Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
Global Solar Power Windows Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Solar PV Inverter Market
Solar Power Systems
Global Solar PV Balance of System Market