
 Rooftop Solar PV Market | 2026-2036
Rooftop Solar PV Market Size, Share, and Industry Trends Forecast 2026-2036
Rooftop Solar PV Market Intelligence
Energy-as-a-Service subscription models, bundling installation with ongoing maintenance and monitoring, is realigning the value proposition beyond simple hardware sales. Sunrun Inc. specializes in these residential service agreements, offering solar power with no upfront cost. SolarEdge Technologies, Inc. differentiates through its integrated smart energy solutions, providing advanced system monitoring. JinkoSolar Holding Co., Ltd. sustains its market position through massive panel production scale.
Rooftop solar PV refers to photovoltaic systems installed on the roofs of residential or commercial buildings. These systems utilize solar panels, typically made of monocrystalline or polycrystalline silicon cells, to convert sunlight directly into DC electricity, which is then converted to usable AC power by an inverter. Monocrystalline panels command a premium due to higher efficiency, dominating new installations. The residential installation segment represents the largest volume, driven by homeowner demand for energy independence.
Government policies are critical, with frameworks like the US Inflation Reduction Act (IRA) and the EU Green Deal offering substantial subsidies and tax credits. In parallel, China's dual carbon goals mandate increased renewable capacity, directly boosting rooftop installations through provincial targets. Successfully navigating grid interconnection standards and integrating battery storage will determine long-term profitability for system installers and component manufacturers.
Market Dynamics
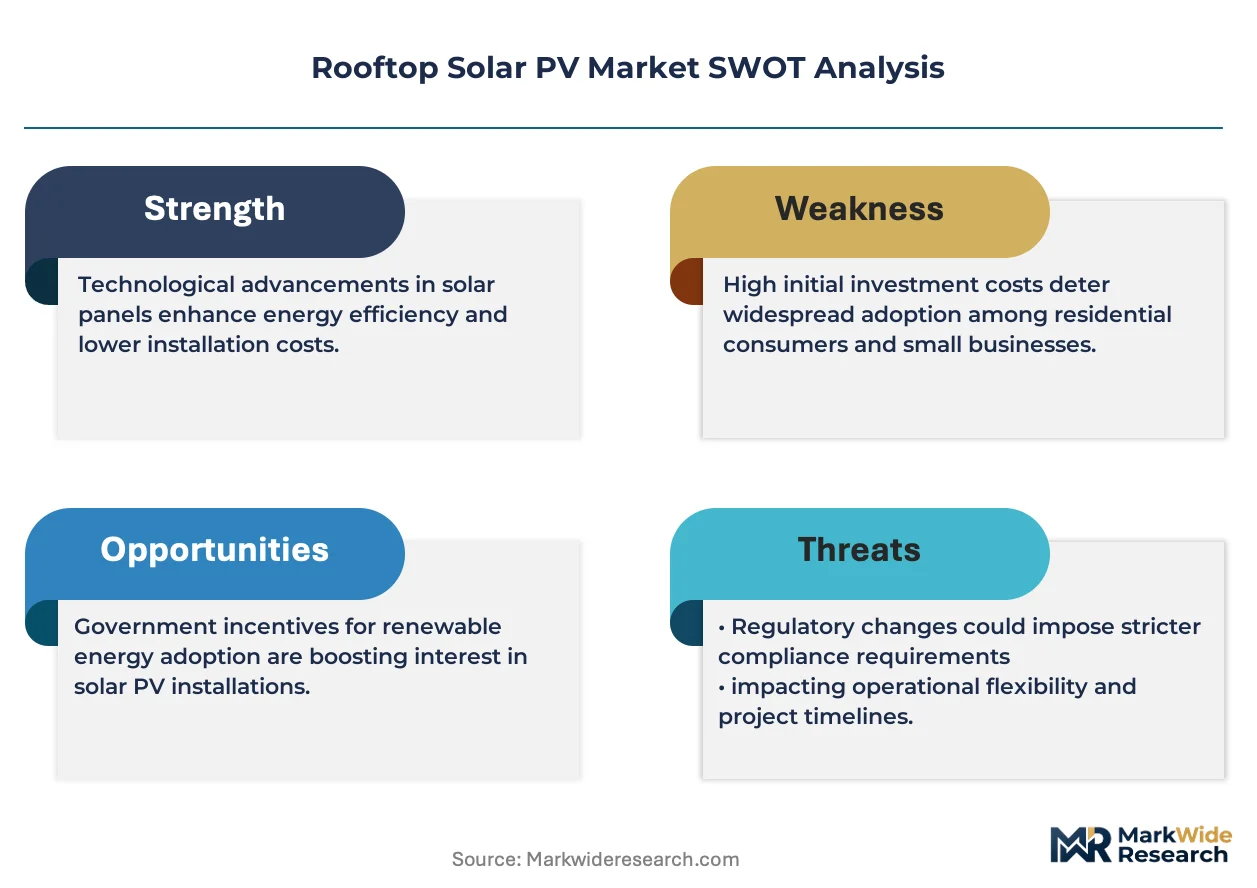
The market's central dynamic is the transition from one-time hardware sales to recurring revenue models. This shift is propelled by government incentives like the US Inflation Reduction Act and commercial sector demand for predictable operational energy costs, fundamentally altering value capture.
Growth Catalysts
- Policy Incentives:The US Inflation Reduction Act's tax credits and China's dual carbon goals provide direct subsidies and mandates that accelerate system installations.
- Commercial Opex Reduction:Retail and logistics chains are installing rooftop systems to lower long-term electricity costs and meet corporate sustainability targets.
- Energy Independence:Homeowner demand for resilience against grid outages and greater control over energy bills is a primary driver for the residential segment.
Market Restraints
- Grid Interconnection Delays:Inconsistent utility standards, particularly in the US, create approval backlogs and add significant project costs and uncertainty for system installers.
- High Initial Capital Outlay:The total upfront cost for a complete PV system remains a primary adoption barrier for residential customers lacking access to financing.
- Supply Chain Bottlenecks:Dependence on polysilicon and panel manufacturing concentrated in China creates exposure to geopolitical trade friction and potential tariff actions.
Strategic Opportunities
- Energy-as-a-Service Expansion:Subscription models bundling installation and maintenance unlock residential markets by removing the high upfront cost barrier for homeowners.
- Integrated Battery Storage:Coupling PV systems with battery storage creates a higher-value offering by enabling energy self-sufficiency and providing grid backup.
- Emerging Market SMEs:Targeting small-to-medium enterprises in countries like India and Vietnam offers a substantial growth avenue as they seek stable energy costs.
Industry Challenges
- Skilled Labor Scarcity:A deficit of certified electricians and installation technicians constrains deployment speed in high-growth regions, impacting project timelines and quality control.
- Navigating Permit Complexity:Installers face significant administrative overhead from a patchwork of inconsistent municipal building and electrical codes, which slows project velocity and increases soft costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rooftop Solar PV Market |
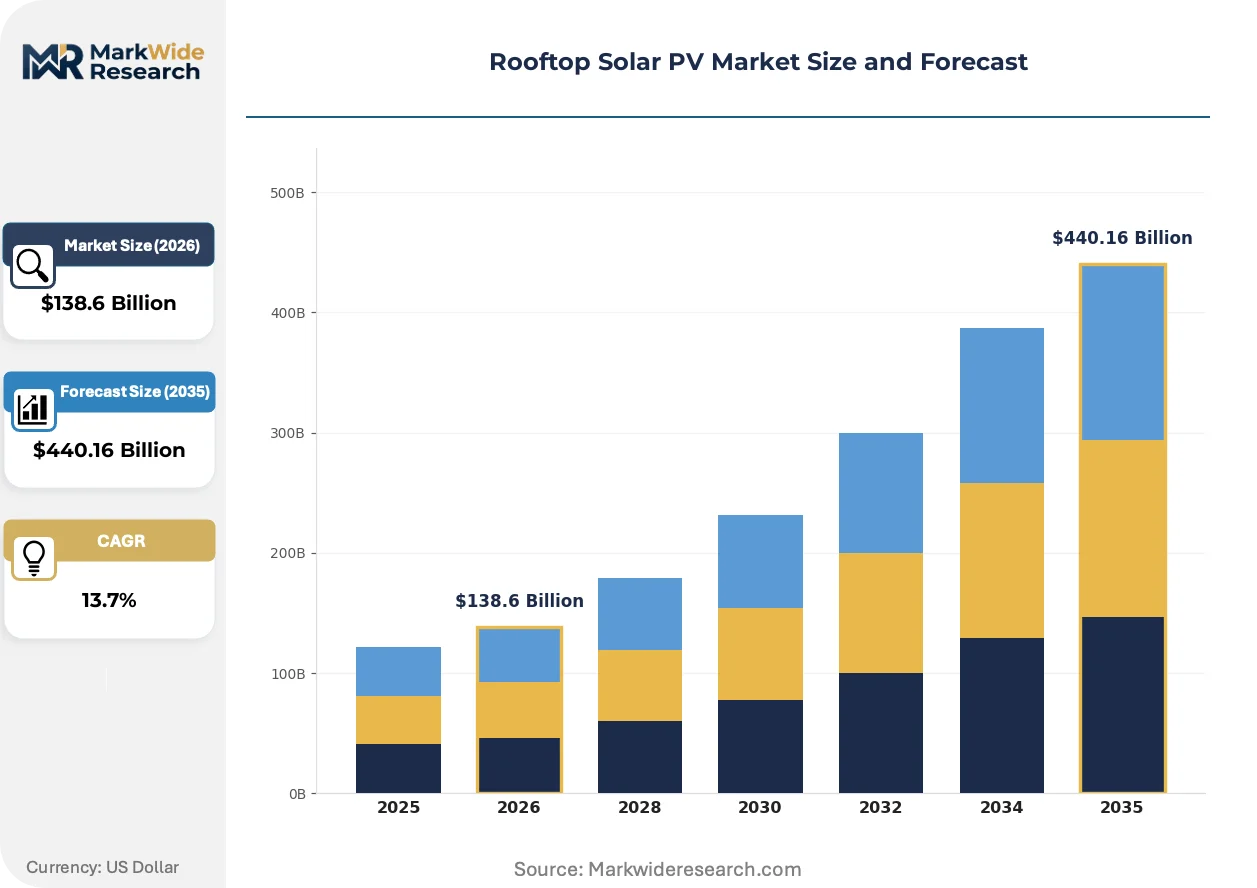
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $440.16 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial, Building-Integrated Photovoltaics Installation Type: Residential, Commercial, Institutional, Agricultural, Community Solar Mounting Structure: Fixed Tilt, Adjustable Tilt, Tracking Systems, Floating, Ground Mounted End User Segment: Homeowners, Retail Chains, Educational Facilities, Farms, Cooperative Societies |
| Companies Covered | SolarEdge Technologies, Inc., Trina Solar Co. Ltd, Sunrun Inc., SunPower Corporation, JinkoSolar Holding Co., Ltd., First Solar, Inc., Canadian Solar Inc., SMA Solar Technology AG, Enphase Energy, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rooftop Solar PV Market Strategic Shifts & Innovations
The competitive landscape is shifting from a focus on panel manufacturing scale to system-level intelligence and service integration. This evolution prioritizes software, grid services, and long-term customer relationships over simple hardware transactions.
Integrated smart energy solutions combine PV generation with home energy management systems and EV chargers. Commercial and high-end residential buyers are adopting these systems to maximize self-consumption and participate in grid services. This convergence of hardware and software is rewriting the value proposition from standalone power generation to holistic home energy ecosystem management.
New grid interconnection standards, such as IEEE 1547-2018 in the United States, mandate advanced inverter capabilities for grid support. This forces inverter manufacturers to incorporate functions like voltage regulation and frequency response into their products. The residential and commercial segments are most affected, as installers must ensure compliance for new systems to receive permission to operate.
Subscription-based service models, popularized in the residential sector, are gaining traction. These Energy-as-a-Service agreements replace large upfront capital outlays with predictable monthly payments, bundling installation, monitoring, and maintenance. This shift is most prominent in North American markets, where it broadens the addressable market to include more credit-sensitive homeowners.
Rooftop Solar PV Market Segmentation
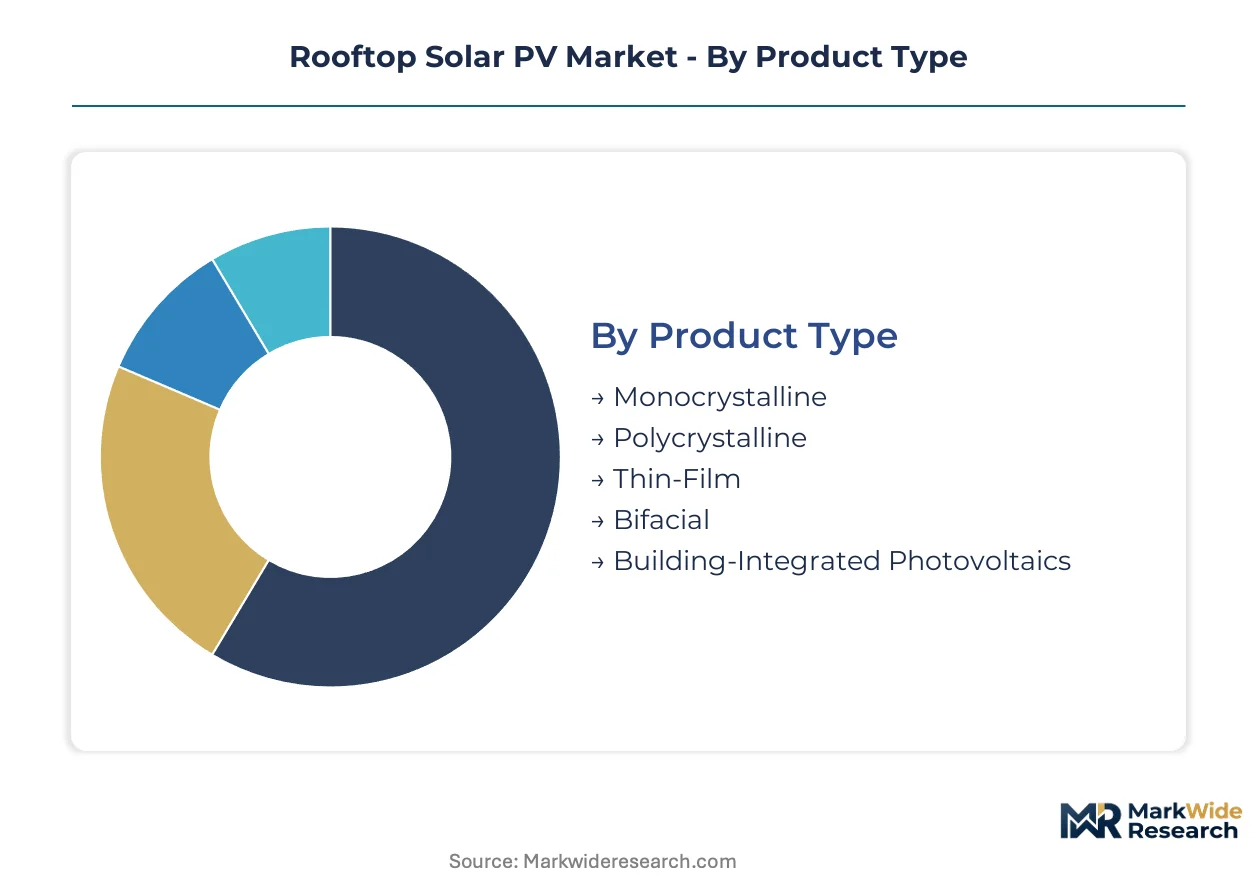
Understanding the market's segmentation reveals the diverse technological and application-specific demands driving rooftop solar PV adoption. This granular view helps identify where value accrues across different product types, installation methods, and end-user requirements. Each segment reflects unique operational needs and investment priorities.
Product Type:
The product type segmentation highlights the trade-offs between efficiency, cost, and specialized applications across different solar panel technologies. High-efficiency options command premium pricing, while volume production drives down costs for standard panels.
- Monocrystalline:Monocrystalline panels feature single-crystal silicon, offering higher efficiency and a sleek, uniform appearance. Demand concentrates in the residential sector, where homeowners prioritize maximum power generation from limited roof space.
- Polycrystalline:Polycrystalline panels use multiple silicon crystals, making them more cost-effective but slightly less efficient. Commercial installations in countries like China often utilize this technology, balancing initial investment with substantial energy output.
- Thin-Film:Thin-Film panels utilize extremely thin layers of semiconductor material, offering flexibility and lighter weight for specialized architectural applications.
- Bifacial:Bifacial panels capture sunlight from both sides, increasing overall energy yield, particularly in installations with reflective surfaces or elevated mounting.
- Building-Integrated Photovoltaics:Building-Integrated Photovoltaics (BIPV) seamlessly integrate solar technology into building materials, serving both power generation and aesthetic functions.
Today's leader: Monocrystalline. Tomorrow's challenger: Bifacial.
Installation Type:
The installation type delineates distinct application environments, each with unique scale, regulatory requirements, and financing structures.
- Residential:Residential installations involve smaller-scale PV systems on individual homes, designed to offset household electricity consumption. Homeowner demand for energy independence in the United States drives this segment, supported by incentives like the IRA.
- Commercial:Commercial installations encompass larger systems on business premises like retail chains, aimed at reducing operational expenses. Retail chains in Europe adopt these systems to lower long-term electricity costs and meet sustainability targets.
- Institutional:Institutional installations serve public or private organizations like schools and hospitals, focusing on long-term energy savings and environmental commitments.
- Agricultural:Agricultural installations provide power for farm operations, irrigation, and rural electrification, often benefiting from specific government subsidies for rural development.
- Community Solar:Community Solar projects allow multiple subscribers to benefit from a shared solar array, expanding access to solar power for those without suitable rooftops.
The commercial segment is expanding most quickly, while community solar represents a significant opportunity for market penetration.
Mounting Structure:
Mounting structure selection significantly influences system performance, installation cost, and overall energy yield.
- Fixed Tilt:Fixed tilt systems install panels at a predetermined angle and orientation, offering the simplest and most cost-effective mounting solution. These systems are widely used in residential and commercial applications across China.
- Tracking Systems:Tracking systems actively adjust panel orientation to follow the sun's path, maximizing energy capture. Demand for tracking systems emerges in high-end commercial installations in the United States, optimizing energy yield.
- Adjustable Tilt:Adjustable tilt systems allow manual or seasonal angle changes, providing a compromise between fixed tilt simplicity and tracking system performance.
- Floating:Floating PV systems are installed on water bodies like reservoirs, conserving land and often benefiting from cooler operating temperatures.
- Ground Mounted:Ground mounted systems install solar panels directly on land, suitable for larger-scale projects where roof space is insufficient or unavailable.
Fixed tilt structures provide fundamental functionality, while tracking systems offer an advanced value proposition through enhanced output.
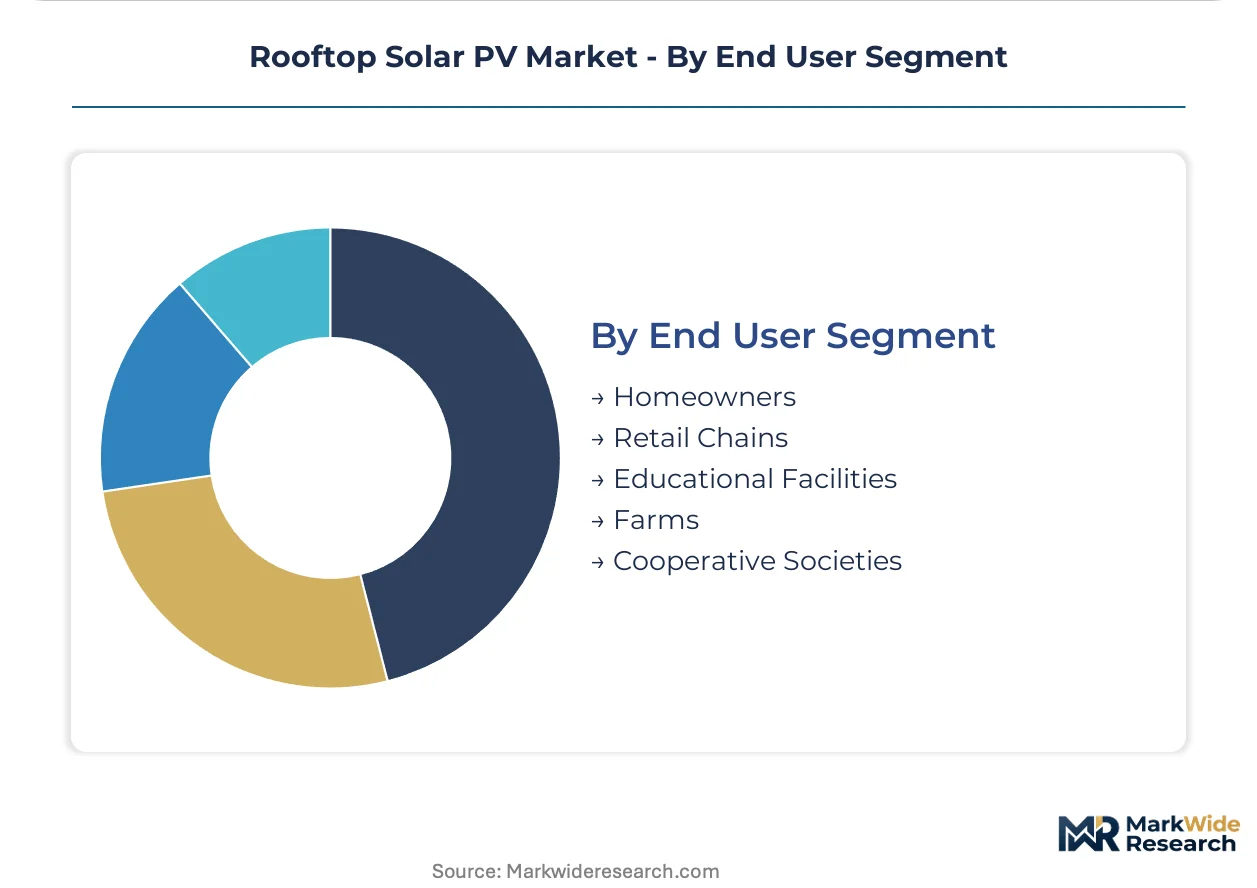
End User Segment:
The end-user segment highlights the diverse customer profiles driving demand for rooftop solar PV, each with specific motivations and procurement patterns.
- Homeowners:Homeowners represent individual residential customers installing solar PV to reduce electricity bills and achieve energy independence. This segment's demand is concentrated in the United States, propelled by IRA tax incentives.
- Retail Chains:Retail chains are commercial entities deploying rooftop solar across multiple store locations to manage operational costs and meet sustainability targets. Large retail chains in Europe are increasingly adopting these systems.
- Educational Facilities:Educational Facilities, such as schools and universities, adopt solar PV to lower utility expenses, provide hands-on learning opportunities, and demonstrate environmental stewardship.
- Farms:Farms utilize rooftop solar for powering agricultural operations, reducing dependence on grid electricity, and potentially benefiting from specific rural energy programs.
- Cooperative Societies:Cooperative Societies implement shared solar installations for their members, often in residential communities, to provide affordable, locally sourced renewable energy.
Homeowners represent the largest segment for market penetration, while retail chains demonstrate significant commercial scaling potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States drives rooftop solar PV demand through homeowner energy independence, China's market expansion focuses on national policy mandates. Both countries accelerate installations through distinct but equally powerful governmental initiatives, creating diverse regional growth patterns.
United States
Homeowner demand for energy independence against grid outages fuels significant residential installations. The US Inflation Reduction Act provides substantial tax incentives, directly accelerating system deployments across the country. Commercial businesses also seek operational cost reductions, increasing their adoption rates. California and Texas exhibit strong growth, with numerous installers navigating state-specific grid interconnection standards.
China
China's dual carbon goals mandate increased renewable capacity, significantly boosting commercial rooftop installations. National policies promote distributed energy resources, supporting large-scale deployments across various industrial zones. These initiatives also address energy security concerns for local businesses. The Yangtze River Delta region sees rapid adoption, driven by manufacturing facilities seeking stable energy costs.
Germany
Sustainability targets and high electricity prices motivate businesses and homeowners to adopt rooftop PV systems. The EU Green Deal and national feed-in tariffs offer financial support, making solar investments highly attractive. Grid modernization efforts also support greater integration of distributed generation. Bavaria and North Rhine-Westphalia lead in installations, integrating advanced energy management solutions.
India
Emerging market SMEs seek stable energy costs, driving demand for commercial rooftop solar solutions. Specific government subsidies for rural development support agricultural installations and community projects, expanding access to clean energy. Policies like the PLI scheme encourage domestic manufacturing of solar components. Gujarat and Maharashtra are key states, where new industrial parks are increasingly incorporating PV.
Rooftop Solar PV Market Key Industry Players
Top-tier vendors anchor the global market through massive production scale, while specialized providers differentiate with advanced technology. The competitive landscape features a mix of large-scale panel manufacturers, integrated system providers, and service-oriented companies. Strategic archetypes include high-volume panel producers, smart energy solution integrators, and Energy-as-a-Service specialists. Companies are increasingly pursuing strategic partnerships and portfolio diversification to capture new market segments.
Within the smart energy solution integrators, SolarEdge Technologies, Inc. exemplifies advanced system monitoring capabilities for integrated energy systems. Sunrun Inc., an Inc. company, occupies a position as a leading residential Energy-as-a-Service provider, offering solar power with no upfront cost through subscription models. JinkoSolar Holding Co., Ltd., a Chinese-based Co. Ltd., anchors the high-volume panel production segment through its massive manufacturing scale. These entities reflect the diverse strategies employed across the market, from hardware optimization to recurring revenue models and service integration.
| Leading Market Players |
|---|
| SolarEdge Technologies, Inc. |
| Trina Solar Co. Ltd |
| Sunrun Inc. |
| SunPower Corporation |
| JinkoSolar Holding Co., Ltd. |
| First Solar, Inc. |
| Canadian Solar Inc. |
| SMA Solar Technology AG |
| Enphase Energy, Inc. |
| Others |
Cost & Logistics Intelligence
Monocrystalline panel efficiency and premium pricing create a distinct tier divergence from cost-effective polycrystalline panels, influencing manufacturing strategies. This bifurcation reflects varying end-user priorities and regional supply chain concentrations.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard PV panels. The dominant pricing structure is project-based for commercial installations, while residential customers often utilize subscription models. Price differentiation stems from panel efficiency and integration with smart energy solutions. Pricing softness runs through the commodity panel segment due to oversupply, making homeowners without financing access most price-sensitive.
Supply Chain Analysis
Polysilicon supply rests heavily on Chinese manufacturing facilities. China and Southeast Asia concentrate panel manufacturing, drawing from silicon wafers, inverters, and mounting structures sourced globally. Geopolitical trade friction creates a structural risk for panel imports, impacting availability and cost. Distribution runs through a fragmented network of regional installers and specialized integrators, connecting manufacturers to diverse end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rooftop solar PV market functions as a regulatory compounder, with the US Inflation Reduction Act significantly driving demand. This legislation accelerates installations by providing substantial tax incentives, reshaping investment flows.
For Market Incumbents: Lock in long-term power purchase agreements with commercial and institutional clients. Consolidate regional installer networks to gain economies of scale. Integrate battery storage solutions for higher-value offerings, countering emerging entrants focused solely on hardware. Investment in advanced inverter technology and grid services provides a critical lever for differentiation.
For New Entrants and Emerging Players: Launch via Energy-as-a-Service subscription models in residential markets. Target underserved small-to-medium enterprises in emerging markets like India and Vietnam for stable energy costs. The residential segment in North America, leveraging financing solutions, is most penetrable. Offer bundled installation, monitoring, and maintenance services to remove upfront cost barriers and gain market share.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized integrators offering smart energy solutions and battery storage. Long-term viability over the next decade hinges on companies navigating grid interconnection complexities and skilled labor scarcity. Target mid-sized firms with strong regional installation footprints and proprietary software for energy management. The signal to watch is a sustained reduction in grid interconnection approval times.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Energy-as-a-Service Offerings | Unlocks residential markets by removing high upfront costs for homeowners. |
| Develop Integrated Battery Storage Solutions | Creates higher-value offerings by enabling energy self-sufficiency for commercial users. |
| Invest in Advanced Inverter Technology | Ensures compliance with new grid interconnection standards like IEEE 1547-2018. |
| Strategic Partnerships for Skilled Labor | Addresses the deficit of certified electricians and installation technicians in high-growth regions. |
| Target Emerging Market SMEs | Captures substantial growth avenues in countries like India and Vietnam seeking stable energy costs. |
Research Approach
Bottom-up residential and commercial modeling reconciled against top-down panel supply tracking forms the analytical core. Primary interviews with installation executives, utility planning officers, and component manufacturers provided crucial insights. This was validated by secondary research from IEA reports, national energy agency statistics, and corporate sustainability disclosures. EPC contractors, government policy advisors, and energy management software developers contributed to the fieldwork.
An input-output matrix integrated supply-side capacity with demand-side adoption rates across the analysis window. Segmentation dimensions modeled included product type, installation method, end-user segment, and regional policy frameworks. Compound annual growth rates derived from historical data trends incorporated projected policy impacts. Key forecast inputs included polysilicon pricing and national renewable energy targets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under evolving geopolitical trade policies. Forecasts reflect assumptions regarding grid interconnection efficiency and skilled labor availability. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Solar Power Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
Biohybrid Solar Cell Market
Solar Power Systems
Photovoltaic (PV) Materials Market
Solar Power Systems
Solar Panel Cleaning Equipment Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Portable Solar Charger Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
Dual Axis Solar Tracker Market