
 PV Array Combiner Box Sales Market | 2026-2036
PV Array Combiner Box Sales Market Size, Share, and Industry Trends Forecast 2026-2036
PV Array Combiner Box Sales Market Insights
UL 1741 certification is bifurcating the competitive landscape into qualified suppliers and excluded entrants. Schneider Electric leverages its North American manufacturing footprint to sustain utility-scale relationships. Eaton Corporation anchors its position through integrated power distribution portfolios spanning switchgear to string combiners. Weidmuller differentiates with European-engineered terminal technology adapted for high-voltage PV string aggregation.
A PV array combiner box consolidates multiple DC input circuits from solar strings into a single output, typically housing fuses, surge protection, and monitoring interfaces within an IP65-rated enclosure rated for 600V to 1500V DC operation. String combiner configurations dominate current volumes, though micro combiner architectures are gaining traction in rooftop applications where module-level power electronics reduce balance-of-system labor. Utility-scale end users command the largest absolute spend, while commercial installations represent the fastest-growing segment as C&I offtakers pursue behind-the-meter solar with storage integration.
FERC Order 2023 interconnection reforms and IEEE 1547-2018 grid support requirements are tightening compliance burdens for combiner box manufacturers seeking US market access. The EPA's renewable energy procurement mandates for federal facilities create a parallel demand channel with distinct Buy America content thresholds. Stakeholders must monitor evolving state-level interconnection standards and inverter-combiner communication protocols as distributed energy resource architectures reshape hardware specifications.
Market Dynamics
Utility-scale solar developers are consolidating procurement around smart combiner systems with integrated monitoring as interconnection queue delays force earlier-stage grid compliance investment. This structural pull is compressing supplier qualification timelines and reshaping vendor relationships.
Growth Catalysts
- IRA Domestic Content Bonus:The Inflation Reduction Act's adder credit is forcing project developers to source combiner boxes from North American-qualified manufacturers, redirecting procurement flows toward domestic fabricators.
- FERC Order 2023 Interconnection Reform:Streamlined grid connection procedures are accelerating project development timelines, pulling forward combiner box demand from developers previously stalled in regional transmission organization queues.
- Module-level power electronics:Rapid adoption of power optimizers and microinverters in commercial rooftop installations is creating parallel demand for compact string aggregation hardware with enhanced arc-fault detection.
Market Restraints
- Copper and aluminum price volatility:Raw material input swings for busbar and conductor assemblies are compressing fabrication margins and complicating long-term contract pricing for utility-scale EPCs.
- UL 1741-SA certification backlog:Extended testing timelines at certified laboratories are creating supply-side bottlenecks for manufacturers seeking smart inverter function integration in combiner enclosures.
- Silicon carbide MOSFET substitution:Emerging string inverter architectures with higher voltage tolerance are reducing per-string combiner count in some utility-scale designs.
Strategic Opportunities
- Behind-the-meter storage coupling:Commercial and industrial solar-plus-storage installations require DC-coupled combiner configurations with bi-directional current monitoring, opening hardware specification windows.
- Texas ERCOT congestion pricing:Locational marginal price volatility is accelerating merchant solar development in the Texas Interconnection, concentrating demand for high-reliability outdoor-rated combiner systems.
- IEEE 1547-2018 ride-through mandates:Grid support functionality requirements are creating upgrade cycles for legacy combiner installations lacking voltage and frequency disturbance tolerance.
Industry Challenges
- Embedded firmware cybersecurity:Smart combiner systems with remote monitoring interfaces face escalating threat surface management requirements under NERC CIP guidelines.
- Skilled field technician scarcity:High-voltage DC commissioning and arc-flash qualified labor shortages are extending installation timelines and elevating contractor costs for complex string aggregation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PV Array Combiner Box Sales Market |
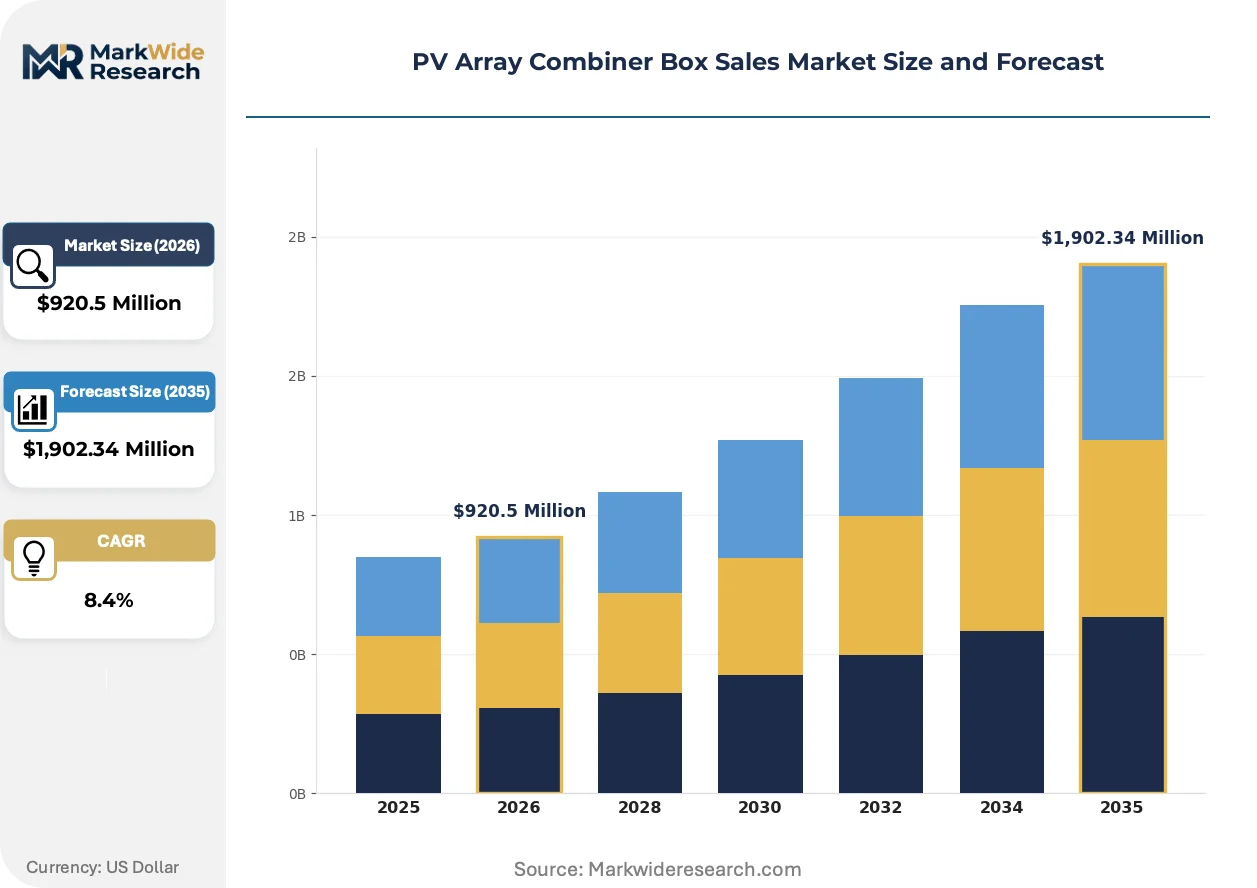
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,902.34 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Combiner, Micro Combiner, Fuse Combiner, DC Disconnect Installation Type: On-grid, Off-grid, Rooftop, Ground-mounted End User: Residential, Commercial, Industrial, Utility Scale Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage |
| Companies Covered | Schneider Electric, Eaton Corporation, CFAT, XJ Group, Wuxi Longmax, Noark, Kingshore, Weidmuller, Sungrow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PV Array Combiner Box Sales Market Trends and Innovations
Digitalization of DC-side power electronics is collapsing the traditional separation between passive aggregation hardware and active grid interface equipment. This convergence is redrawing product category boundaries and forcing incumbents to acquire embedded systems capabilities.
Intelligent combiner architectures with integrated string-level monitoring and remote disconnect are bifurcating the product landscape. Utility-scale developers in California and Texas are specifying these systems for all new procurement. Passive combiner boxes without communication capability are retreating to cost-sensitive distributed generation segments.
FERC Order 2023 interconnection reforms are compressing study phase timelines for generator interconnection agreements. Developers must submit production modeling with certified equipment earlier in project development. Combiner manufacturers are pre-certifying configurations with multiple inverter OEMs to maintain eligibility.
Buyers are unbundling hardware procurement from EPC installation contracts. Large independent power developers are sourcing combiner boxes directly through framework agreements with manufacturers, bypassing traditional electrical distributor channels. This disintermediation is most pronounced in the Southwest where vertically integrated solar developers maintain direct supplier relationships.
PV Array Combiner Box Sales Market Segmentation
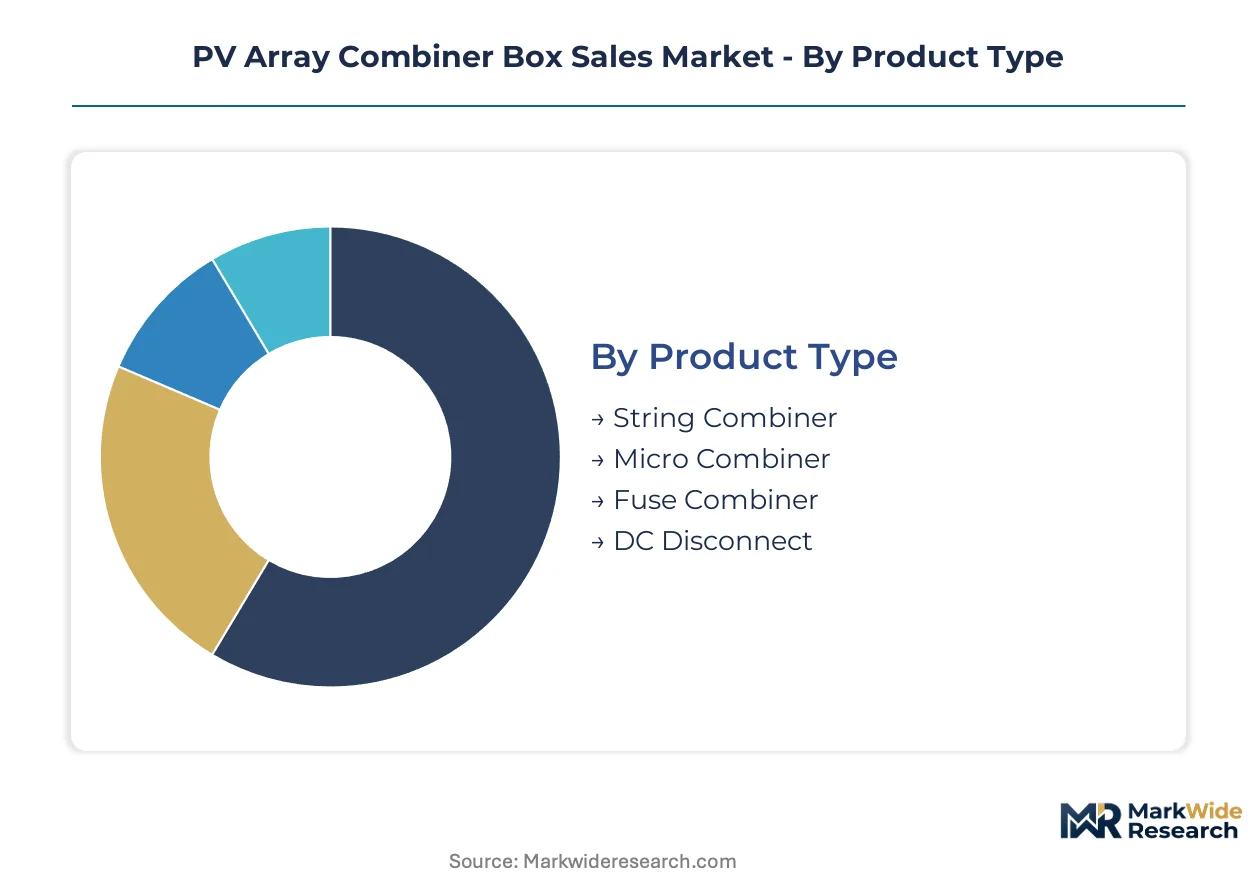
Combiner box procurement patterns diverge sharply across application contexts, with voltage tolerance and grid-connection architecture dictating specification requirements. Each segmentation dimension captures distinct competitive dynamics, from raw material exposure in high-current designs to firmware complexity in monitored systems.
Product Type:
Micro combiner architectures face the most acute substitution pressure as module-level power electronics collapse string aggregation into inverter housings.
- String Combiner:These units consolidate 8 to 24 DC input circuits through fused busbar assemblies housed in NEMA 3R or 4X enclosures. Utility-scale developers in Texas and California specify these for gigawatt-scale projects where centralized inverter architectures dominate procurement.
- Micro Combiner:Compact enclosures aggregating 2 to 4 strings serve commercial rooftop installations with restricted mechanical space. Demand concentrates in behind-the-meter solar-plus-storage configurations where DC-coupled battery integration requires granular current monitoring.
- Fuse Combiner:Passive protection-focused designs with replaceable fuse elements target cost-sensitive distributed generation markets lacking remote monitoring requirements.
- DC Disconnect:Switching devices with visible blade contacts provide isolation capability for maintenance operations, typically specified as integrated components within larger combiner assemblies rather than standalone units.
String combiner configurations anchor the volume base while micro combiner formats gain share at the steepest rate.
Installation Type:
Cost tier stratification separates premium outdoor-rated systems from economy indoor configurations, with enclosure material selection driving price differentiation.
- Ground-mounted:Large-format combiner boxes with pad-mount foundations serve utility-scale solar farms across the Southwest, where ambient temperature extremes demand active thermal management in enclosure design.
- Rooftop:Compact combiner units with integrated arc-fault detection address commercial building codes in jurisdictions with stringent fire safety requirements for elevated installations.
- On-grid:Grid-tied configurations incorporate IEEE 1547-2018 ride-through functionality, with voltage and frequency disturbance tolerance mandatory for interconnection approval.
- Off-grid:Standalone systems with battery charge controller integration serve remote industrial loads and rural electrification projects lacking transmission infrastructure access.
Ground-mounted systems generate the highest absolute revenue per unit while rooftop configurations expand most quickly in metropolitan markets with constrained land availability.
End User:
Customer type determines procurement channel structure, with direct manufacturer relationships displacing electrical distribution for the largest independent power developers.
- Utility Scale:Independent power producers and vertically integrated developers source combiner boxes through framework agreements with North American-qualified manufacturers to satisfy IRA domestic content thresholds.
- Commercial:Corporate offtakers pursuing behind-the-meter solar with storage integration drive demand for DC-coupled combiner configurations with bi-directional current monitoring capabilities.
- Industrial:Manufacturing facilities with high load factors specify combiner systems compatible with captive solar generation and demand response programs.
- Residential:Single-family installations represent the smallest absolute segment, with module-level electronics reducing per-project combiner count in many rooftop designs.
Utility-scale procurement anchors manufacturer revenue while commercial installations climb the fastest as C&I solar-plus-storage adoption accelerates.
Voltage Rating:
Technology maturity separates established 1000V and 1500V DC platforms from emerging higher-voltage architectures enabled by silicon carbide power semiconductors.
- High Voltage:1500V DC-rated combiner boxes dominate current utility-scale procurement, with insulation coordination and creepage distance specifications standardized across major inverter OEMs.
- Medium Voltage:1000V DC configurations retain share in retrofit applications and distributed generation markets where legacy module strings constrain system voltage elevation.
- Ultra High Voltage:Experimental 2000V+ DC platforms target next-generation string inverter architectures with reduced conductor sizing requirements for long DC homeruns.
- Low Voltage:Sub-600V designs serve residential and small commercial applications where electrical code requirements limit accessible voltage levels for non-qualified personnel.
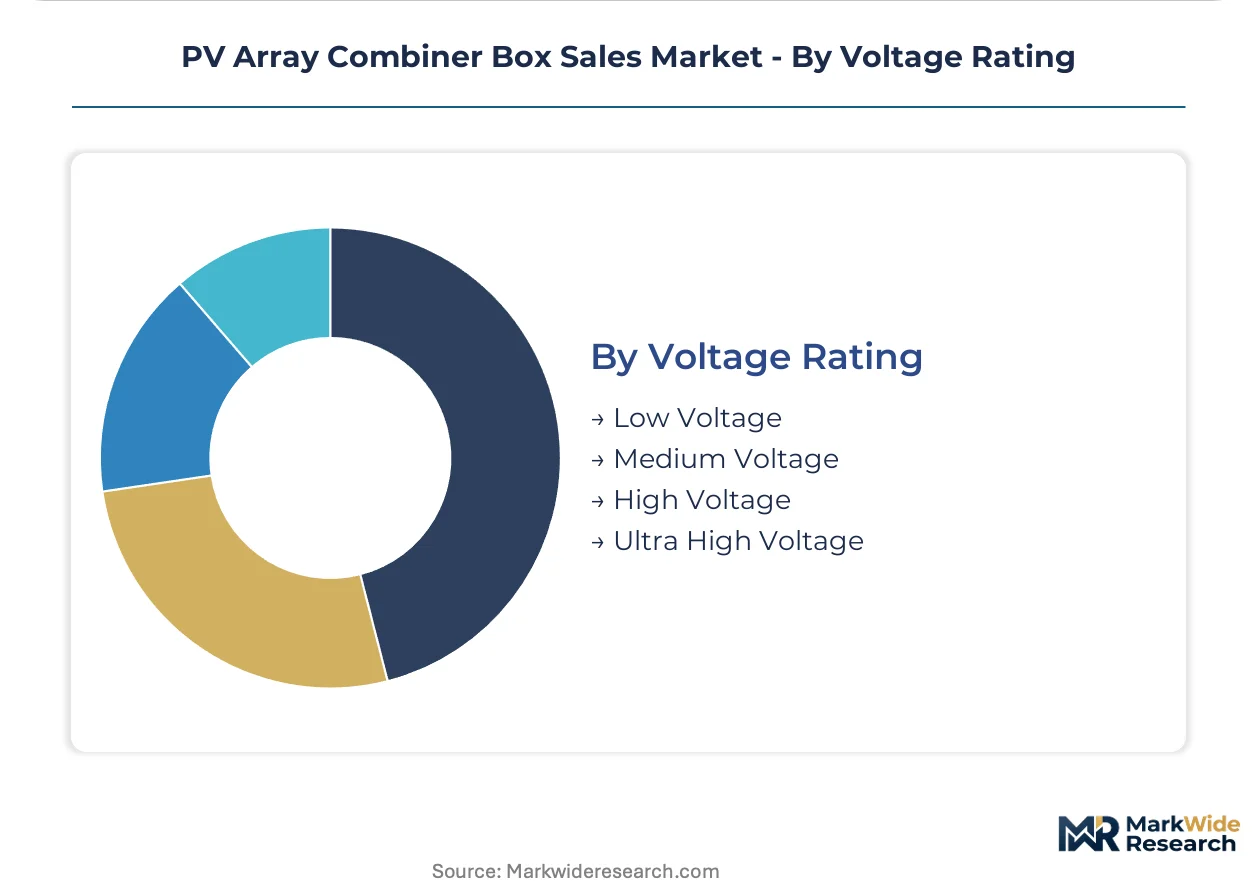
High voltage ratings dominate current installation volumes while ultra high voltage platforms attract development investment for future project pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale developers in the United States drive the largest absolute procurement volumes, while commercial installations in Germany and utility pipelines in India expand fastest. Project finance availability and interconnection queue management determine regional demand pacing.
United States
Texas and California host gigawatt-scale project pipelines straining electrical infrastructure capacity. FERC Order 2023 interconnection reforms compress study timelines, forcing earlier-stage equipment procurement. ERCOT congestion pricing accelerates merchant solar development in West Texas, concentrating demand for outdoor-rated combiner systems.
China
Domestic module production overcapacity drives downstream integration into combiner box manufacturing. MIIT industrial policy prioritizes solar supply chain self-sufficiency across provinces. Yangtze River Delta fabricators supply string combiner configurations for Belt and Road export projects across Southeast Asia.
Germany
Commercial rooftop solar-plus-storage adoption accelerates behind-the-meter deployment in industrial zones. EU Green Deal taxonomy alignment pressures EPCs to document embodied carbon in electrical balance-of-system components. Bavarian engineering clusters develop compact micro combiner architectures for distributed generation markets.
India
PLI scheme incentives attract domestic manufacturing investment for 1500V DC-rated combiner enclosures. CEA grid code revisions mandate smart monitoring interfaces for all utility-scale interconnections. Gujarat and Rajasthan host concentrated solar park development requiring high-reliability string aggregation hardware.
Australia
Queensland and New South Wales utility-scale pipelines face protracted transmission access timelines. CER small-scale renewable energy scheme drives commercial rooftop deployment with storage coupling requirements. Stringent AS/NZS electrical safety standards elevate certification burdens for imported combiner equipment.
PV Array Combiner Box Sales Market Competitive Landscape
Player mix skews toward diversified electrical equipment conglomerates with integrated power distribution portfolios. Market structure concentrates around three to five vertically integrated suppliers capable of satisfying IRA domestic content thresholds. Strategic archetypes separate North American-qualified fabricators, European terminal technology specialists, and Chinese scale-driven producers. Competitive moves center on pre-certification partnerships with inverter OEMs and direct framework agreements with independent power developers bypassing distribution channels.
Within the diversified conglomerate tier, Schneider Electric and Eaton Corporation anchor positions through integrated offerings spanning switchgear to string combiners. Weidmuller represents the European engineering-specialist archetype with terminal technology adapted for high-voltage PV string aggregation. Chinese scale-driven producers including Sungrow and XJ Group occupy cost-competitive positions in markets without domestic content requirements.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton Corporation |
| CFAT |
| XJ Group |
| Wuxi Longmax |
| Noark |
| Kingshore |
| Weidmuller |
| Sungrow |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at North American metal fabrication facilities shapes both supply concentration and price floors for PV array combiner box procurement. IRA domestic content bonus thresholds force developers toward qualified suppliers with captive aluminum busbar production, compressing vendor pools and hardening entry-level pricing for non-compliant imports.
Pricing Analysis
Cost-plus contracts with London Metal Exchange aluminum indexation dominate utility-scale procurement, insulating EPCs from raw material volatility while preserving fabricator margins. Price differentiation separates UL 1741-SA certified smart combiner systems from passive fuse boxes lacking monitoring capability. Pricing pressure intensifies in the standard tier as Chinese scale producers enter markets without domestic content mandates. Commercial installers exhibit highest price sensitivity, while independent power producers prioritize qualification compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of copper busbar and surge protection components characterizes procurement behavior ahead of tariff announcement windows. Manufacturing concentrates in China, the United States, and Germany, with Yangtze River Delta fabricators serving Belt and Road export markets and Texas-based producers capturing IRA-compliant domestic demand. Raw material sourcing draws from Chilean copper cathode and domestic aluminum smelter output. Single-source vulnerability in silicon carbide surge arresters creates supply chain risk. Distribution runs through direct framework agreements with developers, bypassing traditional electrical distribution channels in the Southwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PV array combiner box demand is accelerating under FERC Order 2023 interconnection reforms that compress equipment procurement timelines. Smart combiner architectures with integrated monitoring represent the dominant technological inflection reshaping vendor qualification requirements.
For Market Incumbents: Consolidate backward integration into aluminum busbar and enclosure fabrication to defend margin position against raw material volatility. Acquire embedded firmware capabilities to meet NERC CIP cybersecurity guidelines for smart combiner systems. Pre-certify configurations with Sungrow and SMA inverter OEMs to maintain eligibility under compressed interconnection study timelines. For New Entrants and Emerging Players: Anchor in commercial solar-plus-storage installations where DC-coupled combiner configurations with bi-directional monitoring face qualified supplier shortages. Target Texas ERCOT merchant solar developers seeking outdoor-rated systems for congestion-exposed projects. Pursue white-label partnerships with electrical distributors lacking in-house combiner assembly capability. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among combiner OEMs with long-term service agreements for firmware updates and monitoring platform subscriptions. Acquisition targets with captive North American manufacturing footprints and UL 1741-SA certification pipelines offer superior long-term viability. Watch for inflection when FERC Order 2023 implementation accelerates beyond initial compliance deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Combiner Pre-Certification | Early inverter OEM partnerships secure eligibility under compressed FERC timelines. |
| Domestic Manufacturing Footprint Expansion | IRA bonus credit qualification redirects procurement toward North American fabricators. |
| Embedded Firmware Cybersecurity Investment | NERC CIP compliance becomes mandatory for utility-scale interconnection approval. |
| Direct Developer Framework Agreements | Disintermediation of electrical distribution channels captures margin in utility-scale procurement. |
| DC-Coupled Storage Integration Development | Bi-directional current monitoring opens specification windows in commercial solar-plus-storage. |
Research Methodology
Desk research of EIA project databases, FERC interconnection filings, and inverter OEM technical specifications preceded structured interviews with utility-scale IPP development executives, EPC procurement leads, and combiner box manufacturing operations managers. Primary fieldwork captured procurement timeline compression effects under FERC Order 2023 reforms. Secondary validation drew from IRA domestic content guidance documents, IEEE 1547-2018 implementation records, and aluminum futures market data. Bottom-up project pipeline aggregation and top-down equipment intensity modeling were triangulated against manufacturer shipment disclosures.
Variance decomposition across voltage rating, installation type, and end-user segments structured the analytical framework throughout the projection horizon. Modeled dimensions included product architecture, grid-connection compliance tier, and regional regulatory cluster. CAGRs were derived from equipment intensity ratios applied to solar capacity deployment trajectories. Forecast inputs incorporated silicon carbide MOSFET adoption curves and Buy America content threshold evolution.
Decision-makers should treat outputs as directional under base assumptions of sustained IRA incentive continuity and FERC Order 2023 implementation pace; material deviation would warrant model refresh. Forecasts reflect assumptions regarding interconnection queue management effectiveness and raw material price stabilization. Specific risk factors include UL 1741-SA certification backlog extension and copper price volatility beyond historical bands. Revision becomes warranted when domestic content bonus qualification thresholds cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar System in Kuwait Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
Solar Interconnect Ribbon Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
Saudi Arabia Solar Energy Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Greece Renewable Energy Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
Solar Panel Laminator Market
Solar Power Systems
Solar PV Tracker Market