
 Solar Skin Market | 2026-2036
Solar Skin Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Skin Market Analytics
The EU Green Deal is broadening addressable demand for building-integrated solar across member states. Canadian Solar Inc. leverages its module manufacturing scale to supply aesthetic solar overlays for European retrofit projects. First Solar, Inc. anchors thin-film supply chains with cadmium telluride expertise suited to flexible substrate applications. LONGi Green Energy Technology Co., Ltd. dominates monocrystalline wafer output and extends into building-applied photovoltaic formats for premium residential segments.
Solar skin denotes photovoltaic laminates engineered to mimic conventional roofing, facade, or cladding materials while converting incident radiation to electrical output, typically achieving 10-18% conversion efficiency through silicon or thin-film deposition on flexible polymer substrates. The technology serves architects and developers seeking to preserve aesthetic continuity without sacrificing energy generation capacity. BIPV and aesthetic solutions command margin pools where certification complexity and custom color matching deter commoditization, while flexible panels compete on installation speed for retrofit residential applications. Rooftop installations lead volume but building-integrated formats grow fastest as municipal planners tighten envelope performance codes.
EMA guides clinical-grade material safety assessments for polymer substrates in occupied structures, while REACH governs chemical disclosure across European supply chains and CE marking mandates performance testing for electrical building components. The EU AI Act introduces algorithmic transparency requirements for smart-grid-integrated solar skin systems with predictive maintenance functions. Stakeholders must monitor how evolving fire-resistance classifications and recyclability mandates reshape product qualification timelines and supplier qualification costs.
Market Dynamics
The Solar Skin Market is reconfiguring around building-integrated photovoltaic mandates that embed energy generation into envelope performance codes. Municipal planners in Germany, California, and New South Wales now treat aesthetic solar laminates as compliance instruments rather than optional upgrades.
Growth Catalysts
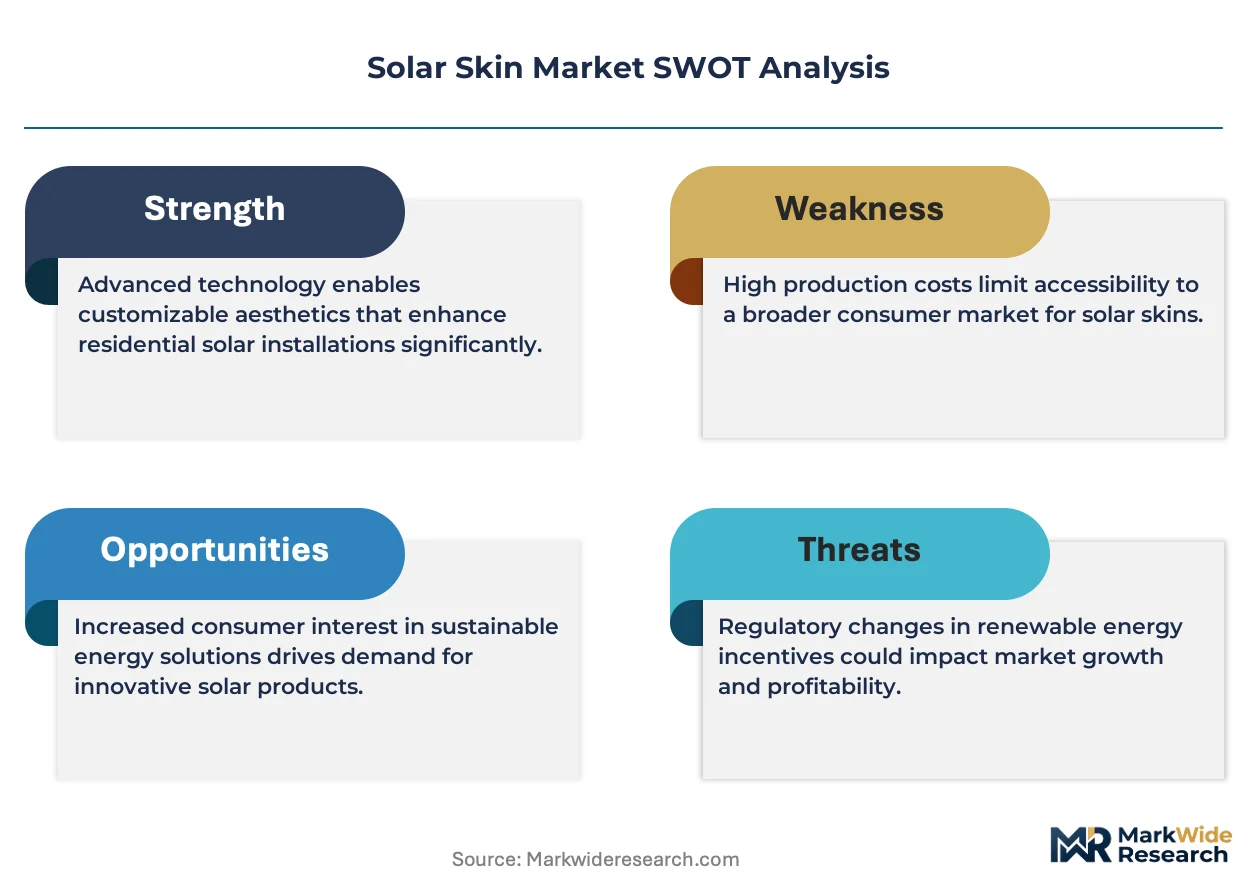
- EU Green Deal envelope standards:Member states must achieve net-zero building stock by mid-century. Solar skin satisfies operational and embodied carbon targets simultaneously.
- Retrofit residential demand:Homeowners in heritage districts face restrictions on visible conventional panels. Mimetic photovoltaic surfaces circumvent aesthetic review boards.
- Thin-film deposition advances:Cadmium telluride and copper indium gallium selenide chemistries now achieve flexible substrate compatibility at commercial scale.
Market Restraints
- Polymer substrate cost volatility:Ethylene-vinyl acetate and fluoropolymer films fluctuate with petrochemical feedstock indices, compressing module margins.
- Wafer supply concentration:Monocrystalline silicon ingot production clusters in specific East Asian manufacturing zones, exposing downstream laminators to single-source risk.
- Conversion efficiency ceiling:Mimetic surface treatments reduce photon transmission, capping output below conventional panel benchmarks.
Strategic Opportunities
- Commercial facade underpenetration:Office towers in Frankfurt and Melbourne present untapped vertical surface area where planning codes now mandate renewable contribution.
- Smart-grid convergence:Predictive maintenance algorithms embedded in solar skin systems create recurring software revenue streams alongside hardware sales.
- Direct-to-developer channels:Architectural specification bypasses traditional installer networks, capturing margin pools previously allocated to distribution intermediaries.
Industry Challenges
- Fire-resistance certification timelines:IEC and UL testing protocols for polymer-backed photovoltaic assemblies extend product qualification cycles by quarters.
- BIPV-specific installation labor scarcity:Conventional roofing crews lack training in electrical isolation and weatherproofing integration, constraining deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Skin Market |
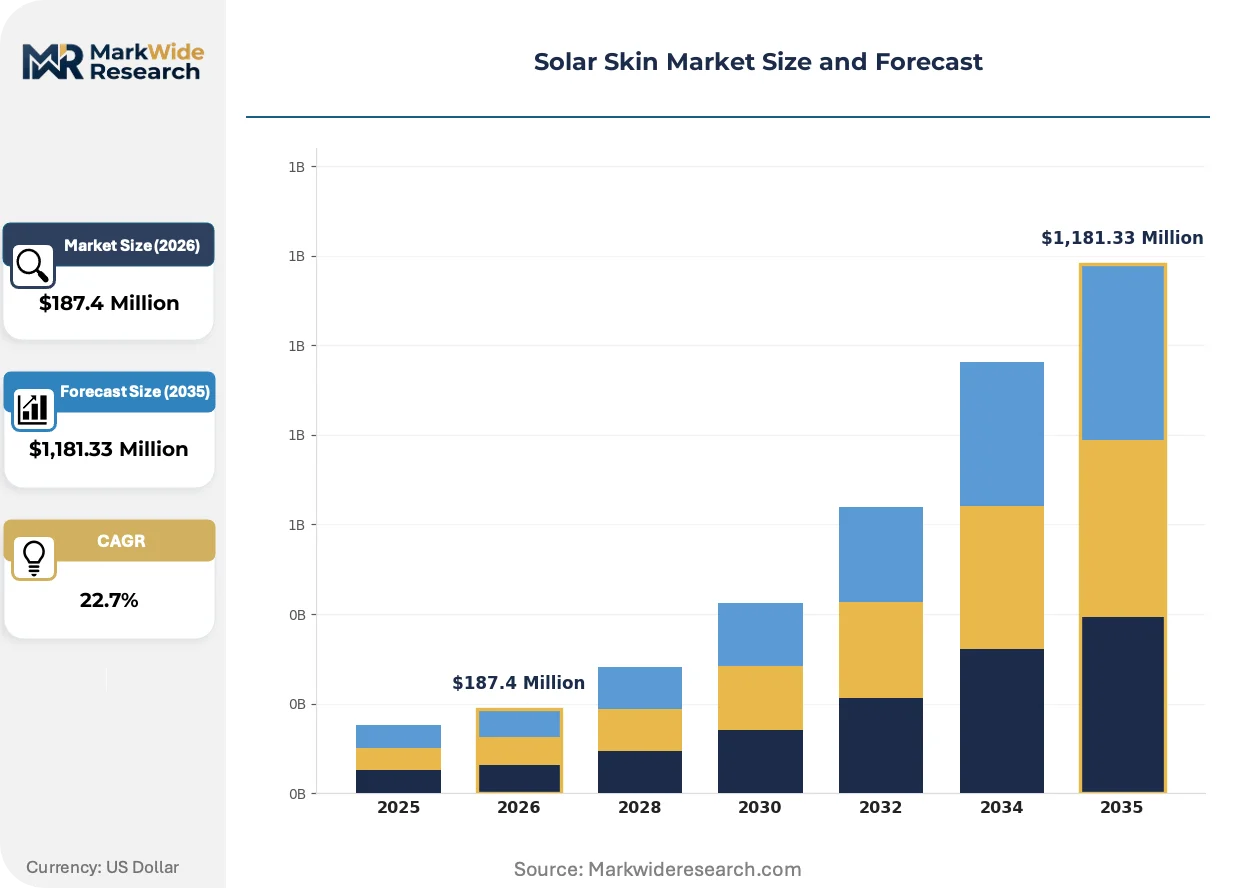
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Panels, BIPV, Aesthetic Solutions, Integrated Systems Application: Residential, Commercial, Industrial, Portable Solutions Installation Type: Rooftop, Ground-Mounted, Building-Integrated, Off-Grid Systems Technological Trend: Smart Grids, IoT Integration, Energy Storage, Advanced Materials |
| Companies Covered | Canadian Solar Inc., Enphase Energy, Inc., First Solar, Inc., LONGi Green Energy Technology Co., Ltd., SolarEdge Technologies, Inc., Trina Solar Co. Ltd, Sunrun Inc., JA Solar Technology Co., Ltd., JinkoSolar Holding Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Skin Market Evolving Landscape
Photovoltaic surface engineering is diverging from commodity panel manufacturing toward architectural material science. Three distinct trajectories now govern competitive investment priorities.
Perovskite-silicon tandem deposition is modularizing across European pilot lines. Research consortia in Germany and the Netherlands demonstrate 20%+ conversion efficiency on flexible substrates while preserving color-matching latitude. Architectural firms specify these laminates for cultural institutions where conventional arrays face visual impact restrictions.
REACH chemical disclosure mandates are tightening substrate formulation transparency across European supply chains. Manufacturers must now document full material composition for polymer back-sheets and encapsulants, extending reformulation cycles. German and Austrian building authorities reference these disclosures in fire-safety assessments, privileging suppliers with pre-validated chemical registries.
Developer procurement teams now require outcome-guaranteed performance contracts rather than equipment-only transactions. Australian and Californian commercial projects specify kilowatt-hour delivery commitments with penalty clauses, transferring operational risk to solar skin vendors. This compression of the traditional design-build-operate sequence favors vertically integrated manufacturers with captive installation and monitoring capabilities.
Solar Skin Market Segmentation
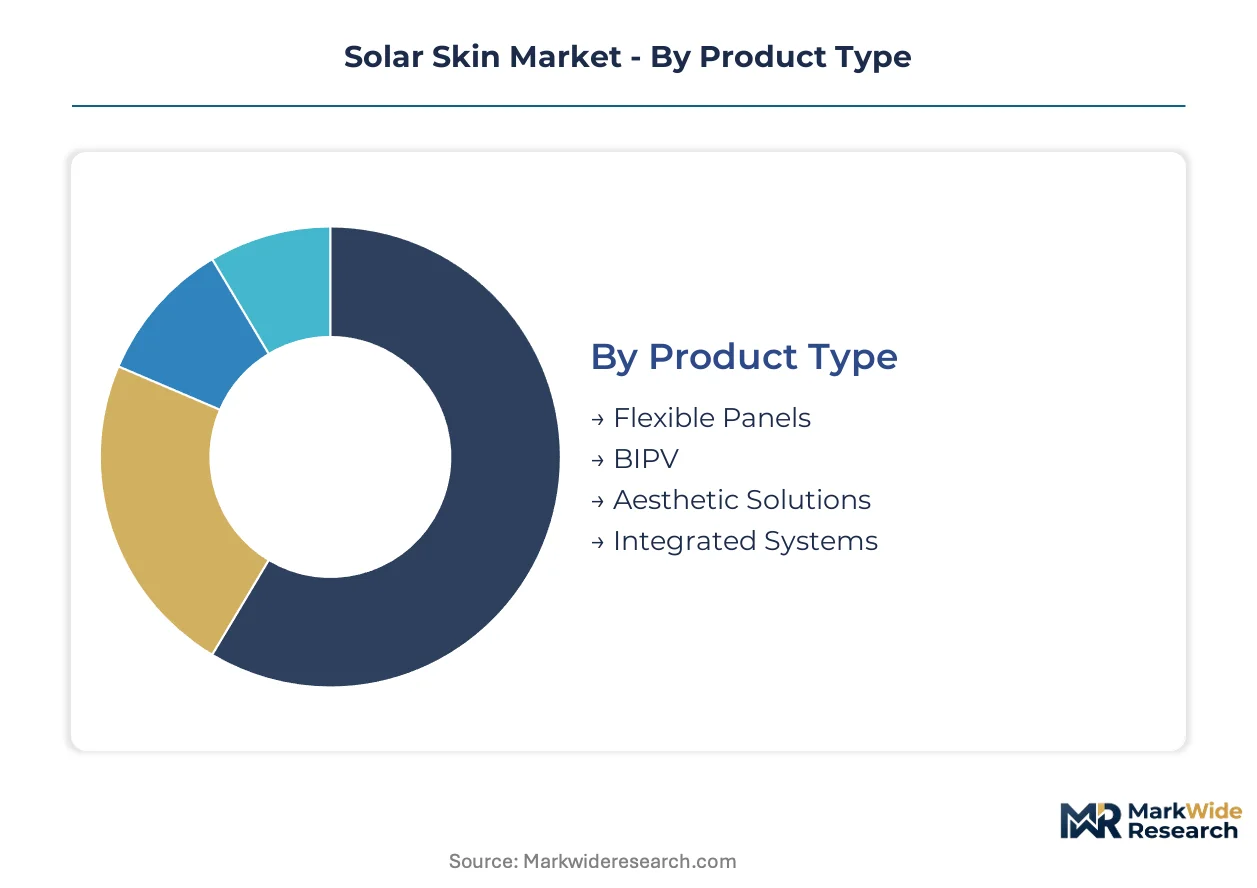
Solar skin manufacturers face divergent certification pathways across product architectures. Segmentation reveals where polymer substrate approvals, electrical safety testing, and fire-resistance ratings concentrate compliance investment.
Product Type:
CE marking applies universally, yet IEC 61215 testing cycles stretch longest for flexible substrates while BIPV formats trigger additional EN 13501-1 fire classification requirements.
- Flexible Panels:Polymer-backed laminates using ethylene-vinyl acetate encapsulation achieve substrate conformity through EMA polymer safety assessments. Australian heritage retrofit projects in Sydney and Melbourne drive specification, where aesthetic review boards restrict conventional panel visibility.
- BIPV:Structural glazing integration demands dual certification—photovoltaic performance under IEC 61215 plus building material approval under national construction codes. German envelope performance mandates in Bavaria and North Rhine-Westphalia treat BIPV as compliance instruments for net-zero building stock targets.
- Aesthetic Solutions:Color-matched laminates require REACH chemical disclosure for pigment formulations.
- Integrated Systems:Pre-wired facade modules bundle inverters and monitoring hardware.
Flexible panels sit at the top of the volume ranking, with BIPV climbing the fastest.
Application:
Cost tier stratification separates premium architectural specification from commodity retrofit demand.
- Residential:Homeowners in California's heritage districts and German Denkmalschutz zones purchase mimetic laminates to circumvent visible panel restrictions. IRA tax credits reduce installed cost barriers for US single-family retrofits.
- Commercial:Frankfurt and Melbourne office towers present untapped vertical surface area where municipal planners now mandate renewable contribution through envelope performance codes.
- Industrial:Warehouse roofscapes prioritize installation speed over aesthetic matching.
- Portable Solutions:Lightweight folding arrays target disaster relief and remote construction.
Residential captures the largest installed base, with commercial facade applications expanding most quickly.
Installation Type:
Geography determines labor scarcity severity and installation velocity constraints.
- Rooftop:Conventional roofing crews in Germany and the United States lack cross-training in electrical isolation and weatherproofing integration, constraining deployment timelines for residential retrofit volume.
- Building-Integrated:Glazier-electrician coordination requirements extend project schedules. New South Wales planning codes now mandate BIPV contribution for commercial envelope compliance, accelerating specification in Sydney and Newcastle developments.
- Ground-Mounted:Agricultural dual-use installations face soil-permeability regulations.
- Off-Grid Systems:Remote Australian cattle stations and German Alpine huts drive demand for battery-coupled laminates.
Rooftop leads current deployment, with building-integrated formats gaining share fastest.
Technological Trend:
Margin pool distribution separates hardware commoditization from software-enabled recurring revenue.
- Smart Grids:Predictive maintenance algorithms embedded in solar skin systems create recurring software revenue streams alongside module sales. EU AI Act transparency requirements now govern algorithmic disclosure for grid-integrated installations.
- IoT Integration:Real-time performance monitoring via cellular or mesh networks enables outcome-guaranteed contracting. Australian commercial projects specify kilowatt-hour delivery commitments with penalty clauses.
- Energy Storage:DC-coupled battery integration requires inverter compatibility certification.
- Advanced Materials:Perovskite-silicon tandem deposition on flexible substrates reaches pilot scale in German and Dutch research consortia.
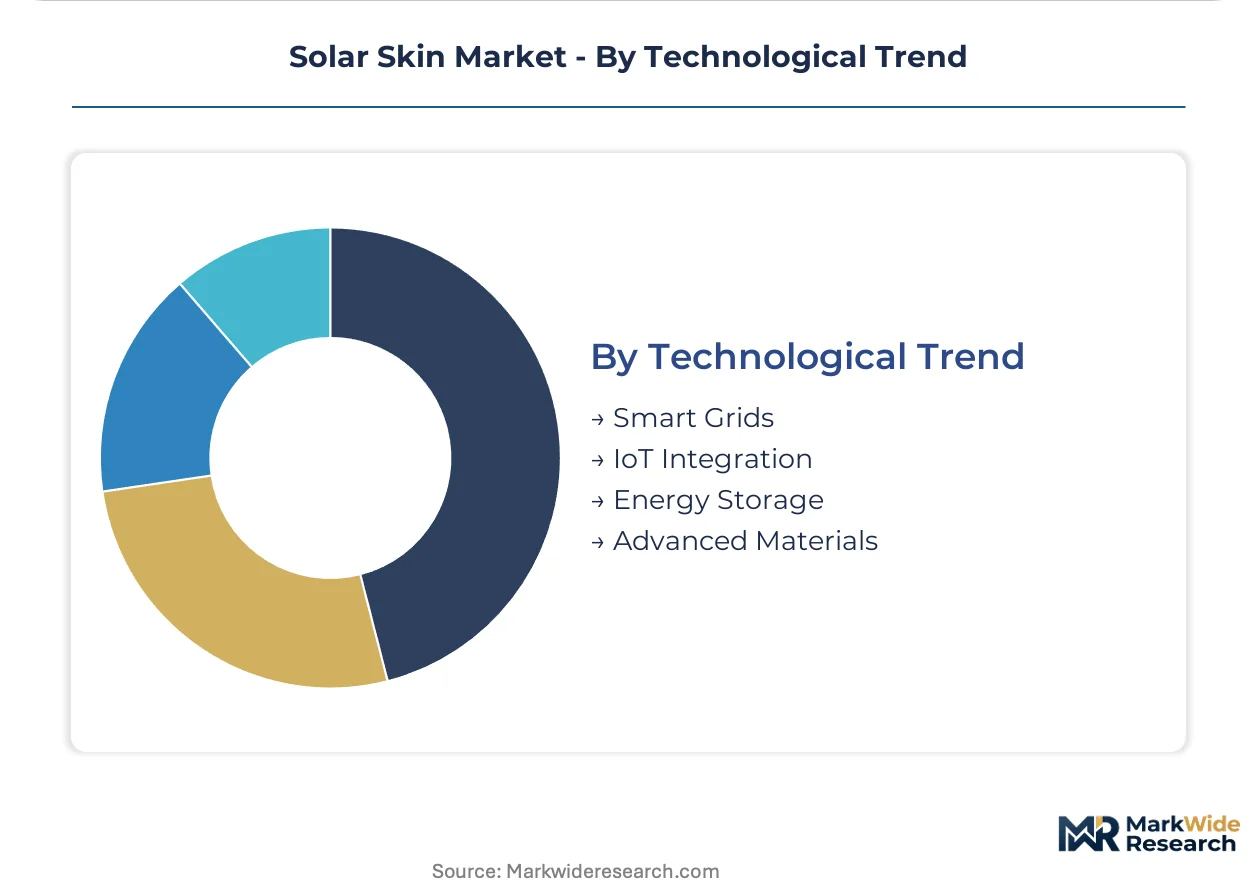
Smart grids command premium pricing, with IoT integration showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered building-integrated photovoltaic standards through its EnEV and subsequent GEG regulations, establishing the technical and regulatory template that California, Australia, and the Netherlands later adapted for their own net-zero building codes.
Germany
Bavarian and North Rhine-Westphalian envelope performance mandates treat BIPV as mandatory compliance instruments for mid-century building stock targets. The GEG (Gebäudeenergiegesetz) mandates renewable energy contribution shares for new construction and major renovations. Research consortia in Freiburg and Dresden pilot perovskite-silicon tandem deposition on flexible substrates for cultural institutions facing Denkmalschutz visual impact restrictions.
United States
California Title 24 and the federal Inflation Reduction Act tax credits accelerate residential retrofit adoption in heritage districts with visible panel restrictions. The California Energy Commission updates envelope standards triennially, embedding solar contribution requirements into compliance calculations. Installer networks in Los Angeles and San Diego counties expand cross-training programs for roofing-electrical integration to address labor scarcity constraining deployment velocity.
Australia
New South Wales planning codes now mandate BIPV contribution for commercial envelope compliance, accelerating specification in Sydney and Newcastle high-rise developments. The Clean Energy Council accredits solar skin products for grid connection eligibility. Melbourne and Brisbane architectural practices specify mimetic laminates for heritage overlay precincts where conventional arrays face aesthetic review board rejection.
Netherlands
The Dutch Building Decree and municipal Amsterdam climate mandates require near-zero energy performance for new construction, positioning solar skin as envelope compliance technology. Eindhoven research institutes advance thin-film deposition compatibility with curved architectural surfaces. Rotterdam port-area redevelopment projects specify BIPV facade integration for warehouse-to-office conversions under circular construction procurement rules.
Japan
METI's ZEH (Net Zero Energy House) roadmap and updated building energy efficiency standards expand addressable demand for aesthetic solar overlays in dense urban districts. Tokyo and Osaka metropolitan governments tighten envelope performance codes for commercial high-rises. Kyushu-based manufacturing clusters develop polymer substrate formulations meeting JIS fire-resistance classifications for multi-occupancy structures.
Solar Skin Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin pools in the solar skin market. Integrated module manufacturers with captive wafer supply chains occupy positions adjacent to specialized architectural laminators and inverter-integrated system bundlers. Three archetypes now govern competitive positioning: scale-driven commodity suppliers, premium-tier aesthetic specialists, and vertically integrated project developers. Capacity expansion and strategic technology licensing constitute the dominant competitive moves as firms seek to secure polymer substrate supply and fire-resistance certification capabilities.
Among North American-anchored energy technology developers, Enphase Energy, Inc. and SolarEdge Technologies, Inc. exemplify the inverter-integrated system archetype, while First Solar, Inc. represents thin-film deposition expertise applied to flexible substrate compatibility. Chinese-originating module manufacturers including LONGi Green Energy Technology Co., Ltd. and Trina Solar Co. Ltd occupy scale-driven positions extending into building-applied photovoltaic formats.
| Leading Market Players |
|---|
| Canadian Solar Inc. |
| Enphase Energy, Inc. |
| First Solar, Inc. |
| LONGi Green Energy Technology Co., Ltd. |
| SolarEdge Technologies, Inc. |
| Trina Solar Co. Ltd |
| Sunrun Inc. |
| JA Solar Technology Co., Ltd. |
| JinkoSolar Holding Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between fire-rated BIPV laminates and commodity flexible panels splits both pricing power and sourcing strategies across German, Australian, and Californian procurement channels. Premium architectural formats command design-fee capture through REACH-validated chemical registries and IEC 61215 dual certification, while retrofit-grade products compete on ethylene-vinyl acetate input costs and installer network density.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes the solar skin market around certification complexity and after-sales bundling. Premium BIPV formats with EN 13501-1 fire ratings and smart-grid integration capture margin pools above commodity flexible panels, while price erosion runs through standard-tier products as Chinese wafer supply expands and polymer substrate costs fluctuate with petrochemical indices. Residential heritage retrofit buyers in Sydney and Los Angeles exhibit highest price sensitivity, whereas Frankfurt commercial developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke fulfillment patterns for solar skin manufacturers serving European, Asia-Pacific, and North American demand clusters. Monocrystalline silicon ingot production draws from China, Malaysia, and Vietnam, while cadmium telluride thin-film deposition rests on captive supply from Ohio and Malaysia. Single-source vulnerability concentrates in East Asian wafer supply, with distribution running through certified installer networks rather than traditional electrical wholesale channels. Ethylene-vinyl acetate, fluoropolymer back-sheets, and copper indium gallium selenide precursors represent critical input dependencies subject to REACH disclosure mandates and tariff exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar skin market compounds steadily as municipal envelope performance codes hardwire renewable contribution requirements into building stock compliance across Germany, California, and New South Wales. Regulatory embedding creates durable demand visibility independent of pure electricity price arbitrage.
For Market Incumbents: To counter thin-film deposition commoditization from Chinese scale players, First Solar and LONGi should deepen captive installation capabilities in Sydney and Frankfurt while accelerating perovskite-silicon tandem pilot lines. Certification investment in pre-validated REACH chemical registries preserves specification access to Bavarian Denkmalschutz projects where fire-resistance ratings gate market entry. For New Entrants and Emerging Players: Direct-to-developer digital specification platforms bypass traditional installer margin extraction in Melbourne and Rotterdam commercial facade segments. White-space concentration sits in outcome-guaranteed performance contracting for Australian high-rise envelope compliance, where kilowatt-hour delivery commitments with penalty clauses transfer operational risk to vendors. Architectural software integration partnerships with BIM platform providers accelerate specification velocity. For Investors and Strategic Acquirers: Consolidation pressure builds where fire-resistance certification timelines stretch product qualification cycles beyond 18 months and polymer substrate supply concentrates among three European chemical conglomerates. Long-term viability favors vertically integrated manufacturers with captive wafer supply and in-house installation monitoring capabilities. The signal to watch is municipal adoption of predictive maintenance algorithm mandates under EU AI Act transparency requirements, which would advantage software-embedded hardware providers.| Strategic Initiative | Industry Significance |
|---|---|
| Fire-Resistance Certification Pre-Validation | REACH-validated chemical registries accelerate German BIPV approval timelines by quarters. |
| Perovskite-Silicon Tandem Pilot Scale-Up | Freiburg and Dresden research consortia demonstrate 20%+ efficiency on flexible polymer substrates. |
| Direct-to-Developer Specification Platform | BIM-integrated channels capture margin pools previously allocated to distribution intermediaries. |
| Outcome-Guaranteed Performance Contracting | Australian commercial projects specify kilowatt-hour delivery commitments with vendor penalty clauses. |
| Smart-Grid Algorithm Transparency Compliance | EU AI Act disclosure requirements govern predictive maintenance functions in grid-integrated installations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with photovoltaic module procurement directors, BIPV specification architects, polymer substrate chemical engineers, and municipal building code enforcement officers with secondary validation. EIA generation data, IEA renewable technology roadmaps, FERC interconnection filings, and project development databases anchored demand-side modeling. Bottom-up installation forecasts triangulated against top-down envelope performance code adoption curves across German Länder, California counties, and Australian states.
Segment-weighting approaches distributed value and volume across product type, application, installation format, and technological trend dimensions. The analytical framework applied penetration curves for BIPV mandate adoption, perovskite-silicon tandem commercialization timelines, and smart-grid integration rates across the projection horizon. CAGRs derived from fitted adoption S-curves moderated by polymer substrate cost elasticity and installer labor supply constraints.
The model assumes a particular technology adoption path; alternative pathways for perovskite-silicon tandem deposition reaching scale ahead of IEC stability certification would alter the outlook. Forecasts reflect documented assumptions regarding municipal code enforcement velocity and REACH chemical disclosure implementation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Chile Solar Energy Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Malaysia Solar Energy Market
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
Off-Grid Solar Lighting Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
Third Generation Solar Cell Sales Market
Solar Power Systems
Boat Solar Panel Market
Solar Power Systems
Bifacial Solar Panels Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
Canada Solar Energy Market
Solar Power Systems
Building Applied Photovoltaics (BAPV) Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
Philippines Solar Energy Market