
 Finland Renewable Energy Market | 2026-2036
Finland Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Finland Renewable Energy Market Foresight
A capital-intensity divergence between integrated utilities and project developers is bifurcating competitive dynamics in Finland's renewable sector. Fortum Oyj leverages its nuclear-to-renewables transition platform to sustain large-scale hybrid project pipelines. OX2 Group AB specializes in offshore wind development across the Bothnian Sea, while Ilmatar anchors distributed generation through its growing portfolio of wind and solar assets.
Finland renewable energy encompasses electricity, heat, and transport fuel derived from wind, solar, biomass, and hydropower resources, with installed systems typically operating at 25-45% capacity factors for onshore wind and 15-22% for utility-scale photovoltaic arrays. The primary purpose is displacing fossil fuel consumption across Finland's energy-intensive pulp and paper, metals processing, and district heating sectors. Biomass dominates electricity generation applications due to extensive forest industry residues and established combined heat and power infrastructure. Wind power represents the fastest-expanding energy source as seabed leasing accelerates in Bothnian coastal zones, while photovoltaic systems gain traction in commercial and industrial end-user segments seeking behind-the-meter supply.
Finland's Ministry of Economic Affairs and Employment implements national energy and climate strategies, while the Energy Authority regulates grid connection and market access for renewable producers. The Climate Change Act establishes binding carbon neutrality obligations that reshape utility procurement and industrial offtake agreements. Stakeholders must monitor auction design evolution and hydrogen corridor development to capture value from sector coupling and power-to-X integration.
Market Dynamics
Finland's renewable energy sector is being reshaped by the Climate Change Act's binding carbon neutrality mandate, which forces utilities to accelerate fossil fuel displacement across district heating networks and industrial offtake agreements.
Growth Catalysts
- Biomass Residue Abundance:Forest industry byproducts from pulp and paper operations provide feedstock security for combined heat and power plants serving Helsinki, Tampere, and Turku district heating networks.
- Offshore Wind Leasing:The Energy Authority's seabed allocation framework in the Bothnian Sea unlocks investment flows from domestic pension funds and Nordic energy majors into utility-scale developments.
- Industrial Electrification:Metals processing and forest products sectors face procurement pressure under carbon neutrality obligations, driving power purchase agreement volumes with renewable developers.
Market Restraints
- Grid Connection Queues:The Energy Authority's interconnection approval timelines create bottlenecks for wind and solar projects seeking market access, extending development cycles.
- Seasonal Generation Mismatch:Photovoltaic output peaks during summer months when district heating demand collapses, limiting capacity value for combined heat and power displacement.
- Skilled Technician Scarcity:Offshore wind turbine installation and high-voltage cable laying require specialized maritime and electrical expertise concentrated in limited Nordic labor pools.
Strategic Opportunities
- Power-to-X Integration:Hydrogen corridor development linking coastal wind zones to industrial inland clusters enables sector coupling and synthetic fuel production for transport applications.
- Behind-the-Meter Solar:Commercial and industrial end-users in southern Finland deploy rooftop photovoltaic systems to hedge against volatile wholesale electricity pricing.
- Hybrid Project Structuring:Co-location of wind, solar, and battery storage assets optimizes grid connection utilization and captures price arbitrage across generation profiles.
Industry Challenges
- Permitting Complexity:Environmental impact assessments for Bothnian Sea offshore wind sites involve multiple authorities and seasonal restrictions protecting marine ecosystems.
- Legacy Asset Stranding:District heating utilities face write-down risks on natural gas and coal boilers before technical end-of-life, complicating capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finland Renewable Energy Market |
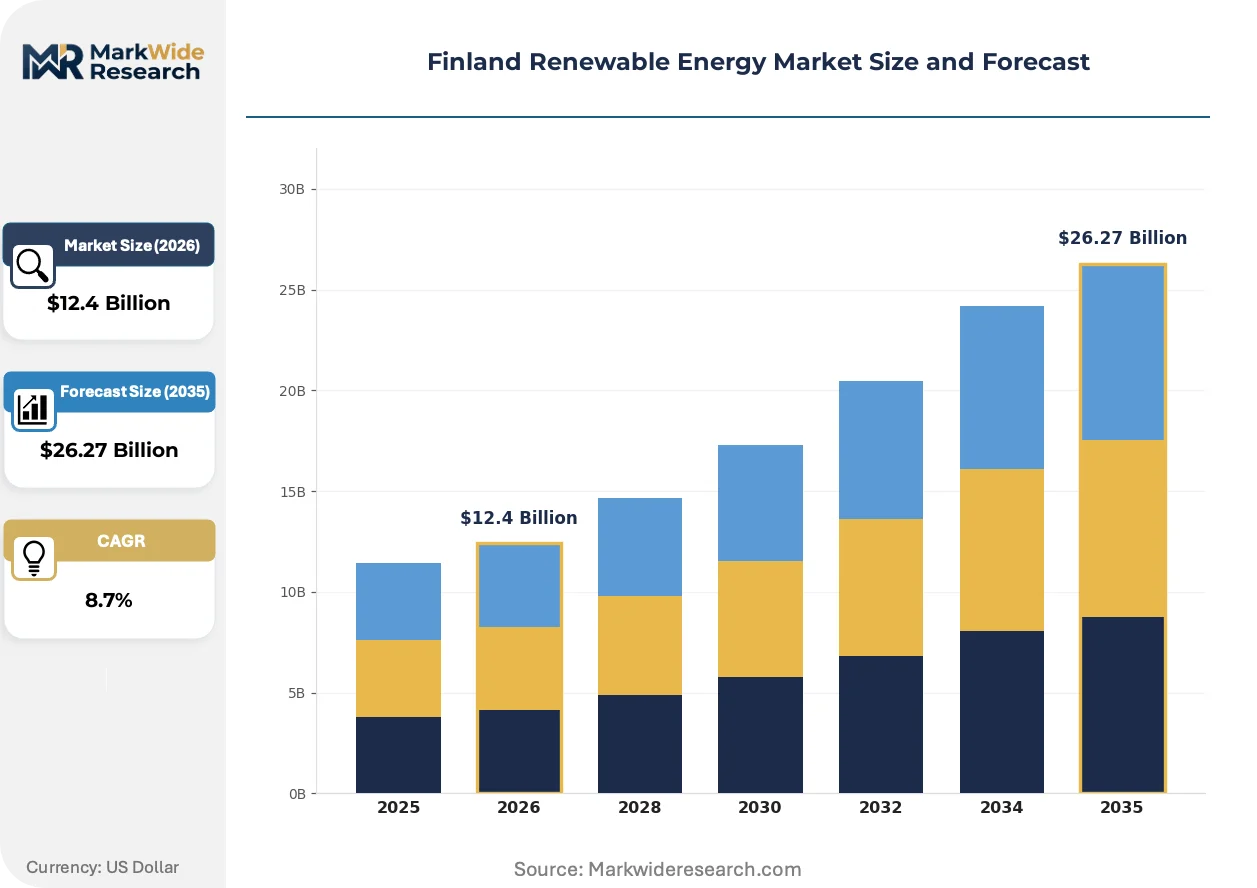
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Wind Power, Solar Energy, Biomass, Hydropower Application: Electricity Generation, Heating, Transportation, Industrial Use Technology: Photovoltaic Systems, Offshore Turbines, Biofuels, Thermal Systems End User: Residential, Commercial, Industrial, Government |
| Companies Covered | Fortum Oyj, Pohjolan Voima Oyj, Vattenfall AB, OX2 Group AB, Ilmatar, UPM Kymmene Oyj, Statkraft, ABO Wind AG, Taaleri, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finland Renewable Energy Market Shifts & Advancements
Technology convergence and procurement model evolution are restructuring competitive positioning across Finland's renewable value chain, with implications for developer margins and utility offtake strategies.
Hybrid renewable systems combining wind, solar, and battery storage are bifurcating project economics between integrated utilities with balance sheet capacity and pure-play developers dependent on merchant revenue exposure. Fortum Oyj and municipal energy groups deploy these configurations to maximize grid connection utilization rates. The technology is compressing development timelines for projects securing long-term power purchase agreements.
The Climate Change Act's carbon neutrality mandate is forcing industrial offtakers into renewable procurement commitments ahead of auction mechanism refinements. Metals processors and pulp manufacturers face compliance pressure without finalized subsidy frameworks. This regulatory uncertainty is accelerating direct bilateral contracting between generators and large consumers.
Corporate buyers in the forest products sector are consolidating renewable energy procurement through portfolio approaches rather than single-asset power purchase agreements. This aggregation model displaces traditional utility intermediation for industrial clusters in eastern and central Finland. The behavior is most visible among integrated paper producers seeking Scope 2 emissions reductions for EU supply chain compliance.
Finland Renewable Energy Market Segmentation
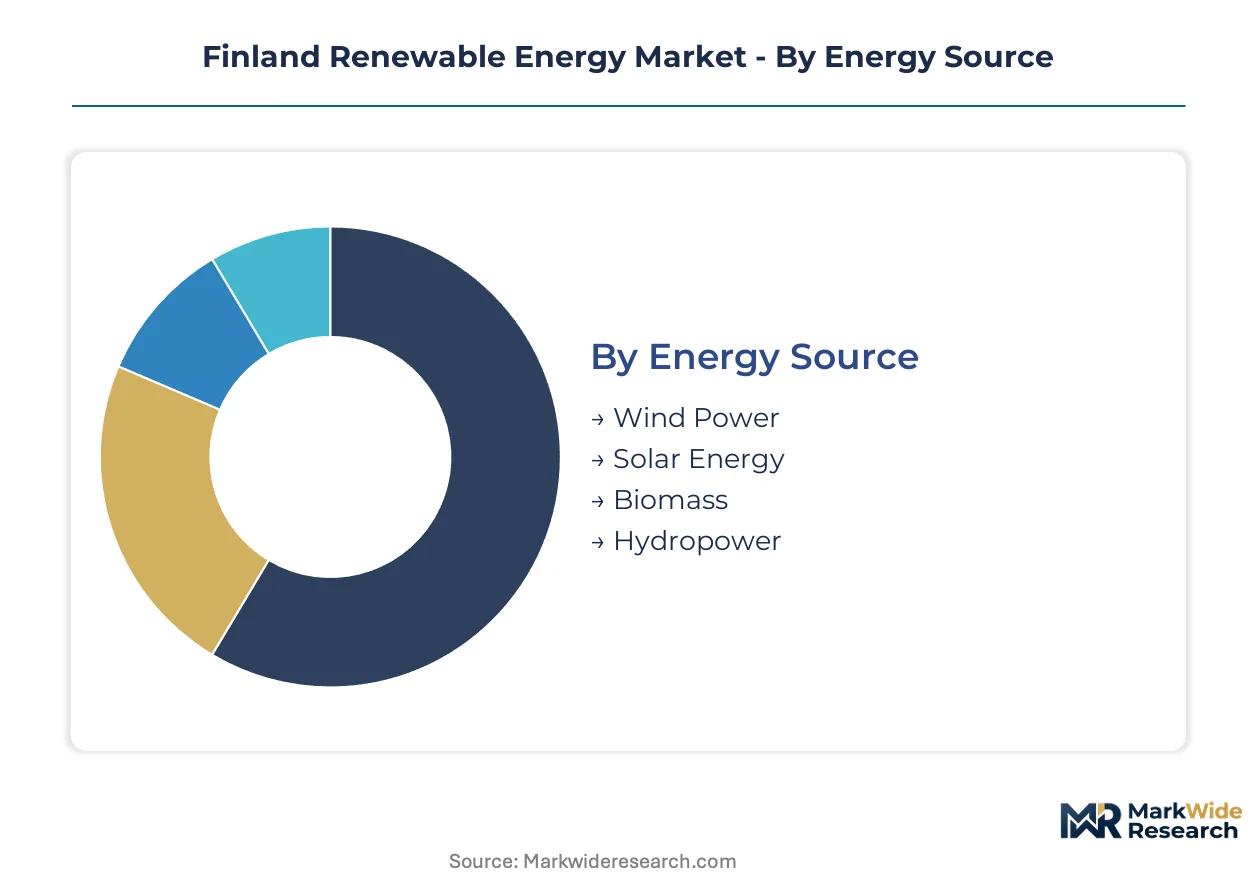
Finland's renewable energy market segments reflect distinct infrastructure legacies and emerging investment corridors. Each category reveals divergent growth trajectories between established biomass networks and nascent offshore wind zones.
Energy Source:
Domestic resource endowments dominate three segments, while one draws heavily on seabed leasing frameworks for export-cable development.
- Wind Power:Onshore turbines operate at 25-45% capacity factors across coastal plains, while offshore developments in the Bothnian Sea concentrate pension fund capital. Grid connection queues at the Energy Authority currently bottleneck project commissioning timelines.
- Solar Energy:Utility-scale photovoltaic arrays achieve 15-22% capacity factors, with commercial rooftop deployment accelerating in southern Finland behind-the-meter segments. Summer generation peaks misalign with district heating demand cycles.
- Biomass:Forest industry residues from pulp and paper operations feed combined heat and power infrastructure anchoring Helsinki, Tampere, and Turku thermal networks.
- Hydropower:Existing run-of-river installations provide baseload flexibility; limited greenfield potential constrains expansion to modernization investments.
Biomass holds the largest share; momentum sits with offshore wind.
Application:
Cost-tier differentiation separates capital-intensive industrial electrification from distributed residential heating retrofits.
- Electricity Generation:Utility-scale procurement dominates capacity additions, with Fortum Oyj and municipal groups deploying hybrid wind-solar-battery configurations. Power purchase agreement volumes are climbing fastest among metals processors seeking Scope 2 compliance.
- Heating:District heating networks across Finnish cities anchor biomass demand as utilities retire natural gas and coal boilers ahead of Climate Change Act deadlines. Seasonal storage limitations constrain solar thermal penetration.
- Transportation:Biofuel blending mandates drive demand for forest residue-derived ethanol and biodiesel; hydrogen corridor development targets synthetic fuel production for heavy freight.
- Industrial Use:Direct renewable thermal supply and process electrification face procurement pressure from carbon neutrality obligations without finalized subsidy auction mechanisms.
Electricity generation commands the deepest capital deployment; industrial use is expanding most quickly.
Technology:
Volume concentration favors mature thermal and turbine systems over emerging photovoltaic manufacturing.
- Photovoltaic Systems:Crystalline silicon modules dominate commercial and industrial rooftop installations; limited domestic panel production creates import dependency on Asian supply chains.
- Offshore Turbines:Fixed-bottom foundations prevail in Bothnian Sea leasing zones; installation vessel scarcity and specialized maritime technician shortages extend development timelines.
- Biofuels:Forest industry residue processing leverages existing pulp and paper infrastructure for ethanol and biodiesel output.
- Thermal Systems:Biomass boilers and combined heat and power plants serve established district heating networks with proven operational track records.
Thermal systems retain the largest installed base; offshore turbines are gaining share fastest.
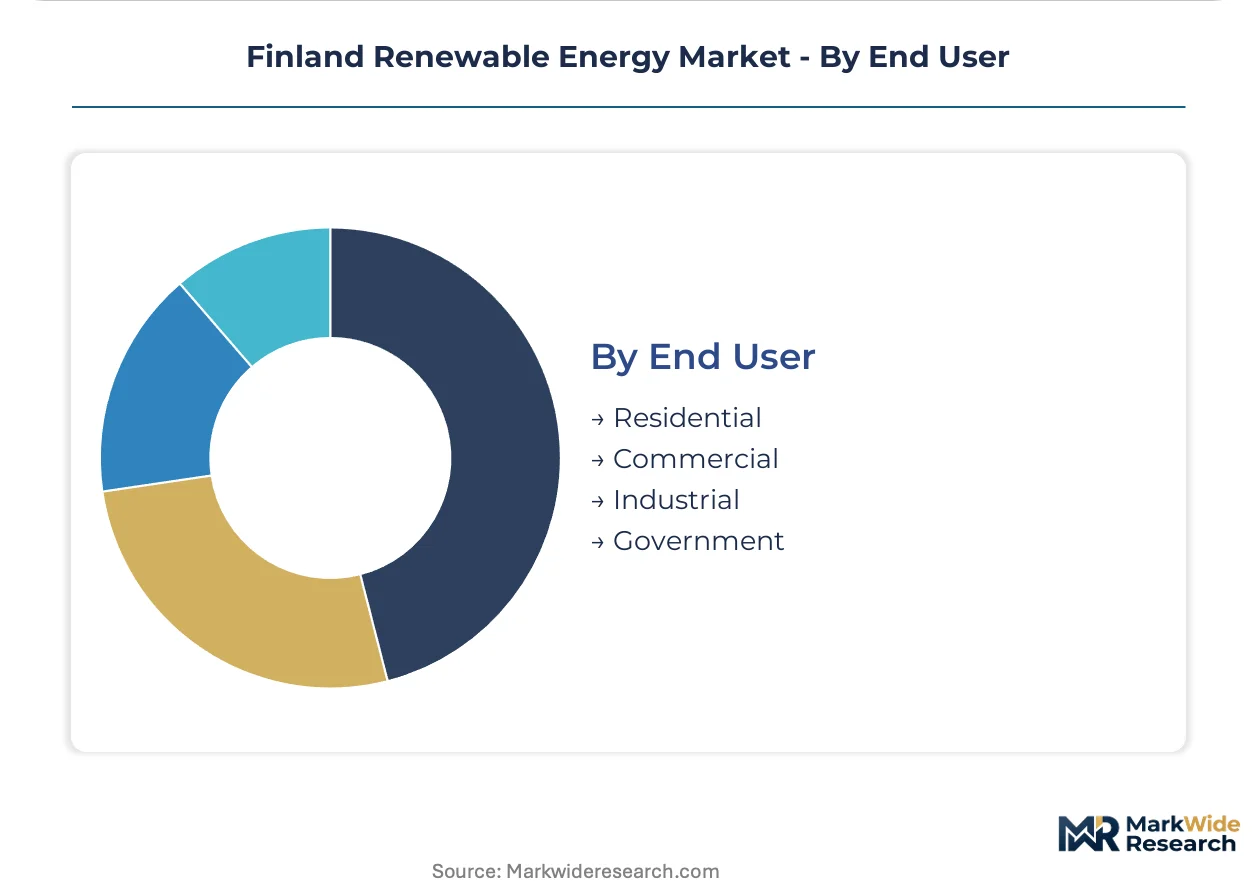
End User:
Customer-type segmentation reveals procurement pattern divergence between price-sensitive residential consumers and compliance-driven industrial offtakers.
- Industrial:Metals processing and forest products sectors face binding carbon neutrality obligations under the Climate Change Act, accelerating direct bilateral contracting with generators ahead of auction mechanism refinements.
- Commercial:Retail and service sector entities deploy behind-the-meter solar to hedge wholesale electricity price volatility; portfolio aggregation models consolidate procurement across property portfolios.
- Residential:Individual households participate through district heating tariffs and distributed solar installations; capital constraints limit penetration relative to commercial segments.
- Government:Municipal energy companies and state procurement frameworks set technology-neutral auction designs while hydrogen corridor planning reshapes public infrastructure investment priorities.
Industrial end users hold the largest procurement volume; commercial deployment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finland's offshore wind zones command premium development costs against inland biomass corridors where residue feedstock anchors thermal economics. This pricing-power asymmetry concentrates pension fund capital in coastal leasing blocks while municipal utilities dominate district heating procurement.
Capital Region
Helsinki's district heating network drives biomass boiler replacements as Helen Oy retires natural gas capacity under Climate Change Act deadlines. The Energy Authority's grid connection queue prioritizes hybrid projects serving metropolitan load centers. Espoo's Aalto University campus anchors research partnerships for power-to-X pilot installations.
Pirkanmaa
Tampere's thermal infrastructure demands forest residue supply security from surrounding Satakunta timberlands. Municipal energy company Tampereen Sähkölaitos procures combined heat and power capacity through long-term biomass contracts. Nokia's industrial park attracts behind-the-meter solar deployment from commercial tenants hedging wholesale price exposure.
Southwest Finland
Turku's archipelago geography constrains onshore wind while favoring offshore development in adjacent Bothnian Sea zones. Turku Energia's coal phase-out accelerates biomass and heat pump investments. Port of Turku infrastructure supports installation vessel logistics for seabed leasing rounds.
Bothnian Coast
Vaasa and Kokkola industrial clusters process metals and forest products under binding carbon neutrality procurement pressure. OX2 Group AB concentrates development rights in Pohjanmaa offshore zones. The region's shallow seabed geology favors fixed-bottom turbine foundations over floating alternatives.
Eastern Finland
North Karelia's pulp and paper residues supply combined heat and power plants serving Joensuu and Kuopio district heating networks. UPM Kymmene Oyj integrates biomass generation with lumber mill operations. Limited grid transmission capacity constrains utility-scale wind export to southern load centers.
Finland Renewable Energy Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Finland's renewable value chain. Integrated utilities with nuclear-to-renewables transition platforms command balance sheet capacity for hybrid project structuring. Pure-play developers specialize in offshore wind or distributed generation segments. Competitive dynamics center on seabed leasing acquisition and long-term power purchase agreement origination.
Among Nordic integrated energy groups, Fortum Oyj and Vattenfall AB occupy positions spanning generation, grid, and retail operations. Specialized developers including OX2 Group AB exemplify the offshore wind archetype concentrated in Bothnian Sea zones. Ilmatar represents distributed generation specialists building wind and solar portfolios outside utility-scale procurement channels.
| Leading Market Players |
|---|
| Fortum Oyj |
| Pohjolan Voima Oyj |
| Vattenfall AB |
| OX2 Group AB |
| Ilmatar |
| UPM Kymmene Oyj |
| Statkraft |
| ABO Wind AG |
| Taaleri |
| Others |
Supply & Pricing Matrix
Turbine installation vessel scarcity across the Bothnian Sea concentrates capital deployment among pension funds and integrated utilities with multi-project pipelines, compressing developer margins while elevating price floors for seabed leasing rounds. This scale asymmetry rewards balance-sheet-heavy players like Fortum Oyj and municipal energy groups that amortize grid connection costs across hybrid wind-solar-battery configurations.
Pricing Analysis
Configured-to-order premiums for offshore wind projects with bespoke foundation engineering and export cable routing command spreads over standardized onshore turbine supply. Long-term power purchase agreements with industrial offtakers anchor project finance, while merchant-exposed developers face price differentiation driven by certification tier and geographic delivery cost. Pricing pressure stems from grid connection queue delays extending development timelines. Metals processors demonstrate lowest price sensitivity due to carbon neutrality compliance mandates, whereas commercial rooftop solar buyers exhibit highest sensitivity to capital expenditure thresholds.
Supply Chain Analysis
Inventory lead times for offshore turbine components stretch 18-24 months due to nacelle assembly concentration in Denmark, Germany, and Spain. Rare earth magnet supply for direct-drive generators draws from China, with blade manufacturing anchored in Poland and Turkey. Single-source vulnerability in installation vessel availability constitutes the dominant supply chain risk. Distribution runs through EPC contractors with Nordic maritime expertise, linking European component hubs to Bothnian Sea construction zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
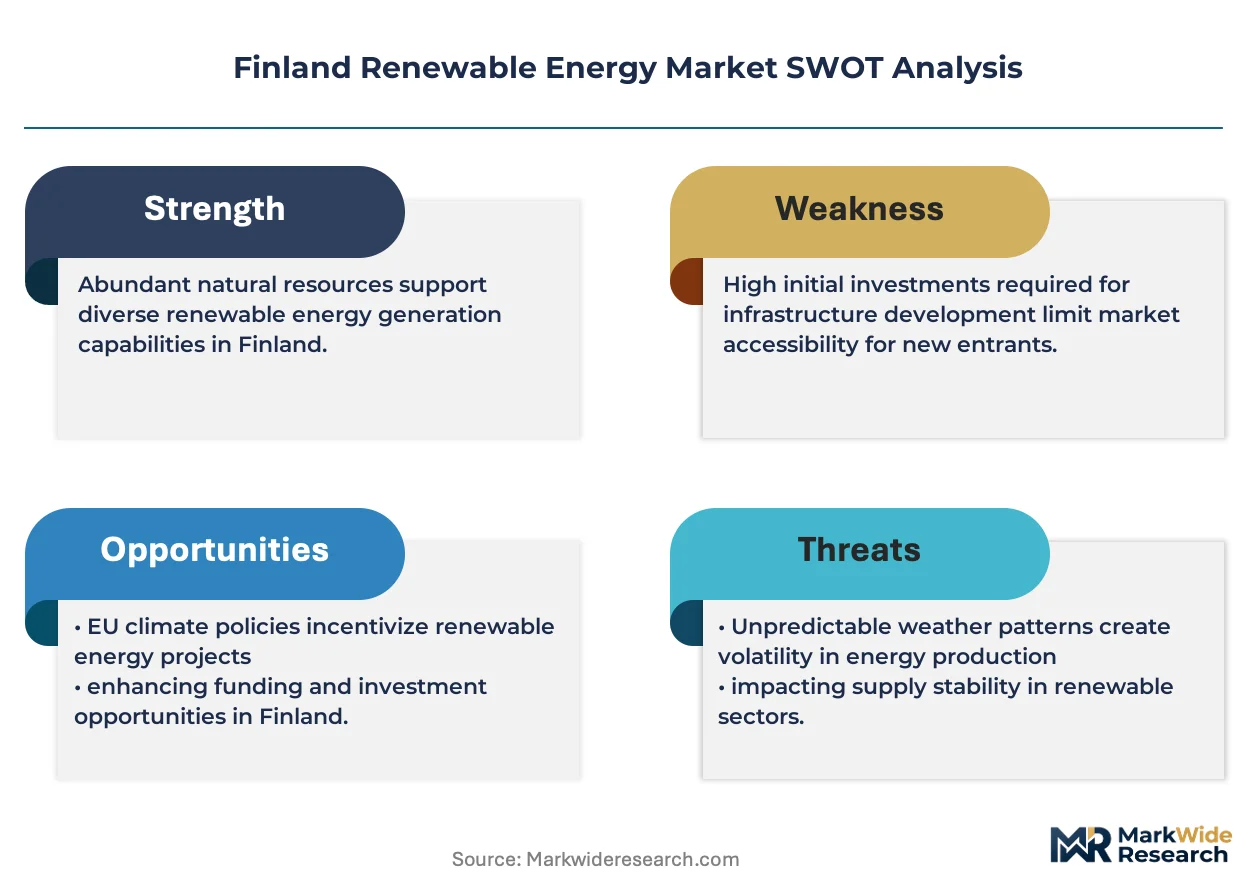
Finland's renewable energy sector constitutes a defensive-moat market where regulatory entrenchment via the Climate Change Act's binding carbon neutrality mandate creates durable incumbent advantages through long-term offtake relationships and seabed leasing rights.
For Market Incumbents: Compound hybrid project portfolios by co-locating wind, solar, and battery storage to maximize grid connection utilization rates against emerging pure-play developers lacking balance sheet capacity. Secure additional seabed leasing blocks in Pohjanmaa zones before auction mechanism refinements dilute first-mover advantages. Prioritize vertical integration into power-to-X infrastructure along hydrogen corridors to capture synthetic fuel premiums from transport sector procurement. For New Entrants and Emerging Players: Behind-the-meter commercial solar deployment in southern Finland represents the most penetrable white-space where incumbent utilities under-serve price-sensitive retail and service sector tenants. Target portfolio aggregation models for forest products sector corporate buyers seeking Scope 2 emissions reductions without utility intermediation. Pursue direct bilateral contracting with pulp manufacturers in eastern Finland as the primary go-to-market angle, bypassing auction-dependent procurement channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated utilities with district heating network concessions and long-term power purchase agreement books. Five-to-ten year viability favors developers with secured seabed leasing and permitted hybrid projects over merchant-exposed pure-plays. Target acquisition archetypes include distributed generation specialists with operational wind and solar assets outside utility-scale channels. Monitor hydrogen corridor infrastructure commitments as the signal to watch for sector coupling inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Seabed Leasing Acquisition | Energy Authority allocation rounds in Bothnian Sea zones concentrate pension fund capital deployment. |
| Hybrid Project Development | Co-located wind-solar-battery configurations optimize grid connection utilization for municipal utilities. |
| Power Purchase Agreement Origination | Direct bilateral contracting with metals processors accelerates under Climate Change Act procurement pressure. |
| Power-to-X Infrastructure Buildout | Hydrogen corridor development enables synthetic fuel production for transport sector compliance. |
| Behind-the-Meter Solar Deployment | Commercial rooftop installations hedge wholesale price volatility for retail and service sector tenants. |
Research Methodology
Desk research of Energy Authority seabed leasing records, Fingrid transmission system data, and municipal utility procurement disclosures preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork across Helsinki, Tampere, and Vaasa clusters validated secondary intelligence on biomass supply security and offshore wind development timelines. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic assumptions from national energy and climate strategy documents.
Variance decomposition across fuel source, generation capacity tier, and regional grid type segmentation dimensions anchored the analytical framework over the projection horizon. CAGRs derived from installed capacity buildout trajectories and levelized cost of energy movements incorporated industrial electrification demand curves and district heating network decarbonization schedules as sector-specific forecast inputs.
Underlying assumptions cover seabed leasing round continuity, biomass residue feedstock availability, and grid connection queue resolution timelines, with deviation risk concentrated in permitting delays for Bothnian Sea environmental impact assessments and hydrogen corridor infrastructure commitment pacing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
South Africa Renewable Energy Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Ocean Power Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
PV Water Heater Market
Renewable Energy
Iran Renewable Energy Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
Renewable Energy Sources Market
Renewable Energy
Solar Cooker Market
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market
Renewable Energy
Green Renewable Energy Market