
 Global Artificial Photosynthesis Market | 2026-2036
Global Artificial Photosynthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Photosynthesis Market Foresight
ISO 19880 certification for hydrogen fuel quality is collapsing the field of qualified system integrators, raising barriers for new entrants. Panasonic Corporation leverages its semiconductor fabrication heritage to anchor photoelectrochemical cell production. Siemens Energy competes through electrolyzer scale-up capabilities tied to offshore wind hydrogen projects. Toshiba Corporation specializes in catalytic material architectures derived from its fuel cell research legacy.
Artificial photosynthesis encompasses engineered systems that replicate natural photosynthesis to convert solar energy, water, and carbon dioxide into storable fuels or chemicals, typically operating at 10-20% solar-to-fuel efficiency in laboratory demonstrations. The primary commercial purpose centers on producing green hydrogen, synthetic methane, or liquid hydrocarbons without fossil feedstocks. Photoelectrochemical technology dominates current patent filings but biomimetic approaches attract venture funding for their potential efficiency breakthroughs. Fuel production applications command the deepest strategic investment pools, while carbon capture applications remain technically immature with limited revenue visibility.
The EU Green Deal and REACH chemical safety standards shape equipment material specifications and carbon intensity accounting across European deployments. Japan's METI coordinates national hydrogen roadmap targets with JIS standards for electrolyzer performance verification. The US Department of Energy and EPA jointly influence federal funding priorities and lifecycle emissions thresholds for synthetic fuel qualification. Stakeholders must track which regulatory frameworks achieve cross-border recognition first, as this determines where capital flows for multi-hundred-megawatt installations.
Market Dynamics
Carbon pricing mechanisms under the EU Green Deal are compressing project economics for fossil-derived hydrogen, forcing energy companies to accelerate photoelectrochemical pilot installations. This regulatory pressure is redistributing capital toward demonstration-scale artificial photosynthesis systems before 2030 compliance deadlines.
Growth Catalysts
- EU carbon border adjustment:Imports of carbon-intensive hydrogen face escalating tariffs, creating immediate pull for domestically produced synthetic fuels.
- Photoelectrochemical efficiency gains:Laboratory demonstrations now achieve 18-20% solar-to-hydrogen conversion, narrowing the gap with electrolyzer benchmarks.
- Japan's hydrogen valley funding:METI subsidies for integrated production-consumption clusters are de-risking first-of-a-kind commercial deployments.
Market Restraints
- Platinum-group metal scarcity:Catalytic electrodes depend on iridium and ruthenium supplies concentrated in South Africa and Russia.
- ISO 19880 certification barriers:Hydrogen fuel quality standards restrict qualified system integrators to a narrow pool of incumbent industrial gas specialists.
- Alkaline electrolyzer substitution:Mature electrolysis technology captures near-term green hydrogen procurement at 60-70% lower capital intensity.
Strategic Opportunities
- Offshore wind-hydrogen coupling:North Sea lease rounds in Germany and Denmark enable dedicated renewable feedstock supply without grid interconnection costs.
- Carbon capture integration:Direct air capture pairing with artificial photosynthesis offers synthetic methane production for maritime fuel applications.
- US Inflation Reduction Act credits:Section 45V hydrogen production tax credits subsidize first-mover projects through 2032.
Industry Challenges
- Photoelectrochemical engineering talent:The field requires rare combinations of semiconductor fabrication, electrochemistry, and process scale-up expertise.
- Multiphysics simulation complexity:Integrated light-harvesting, charge transport, and catalytic reaction modeling demands computational infrastructure beyond typical chemical engineering scopes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Photosynthesis Market |
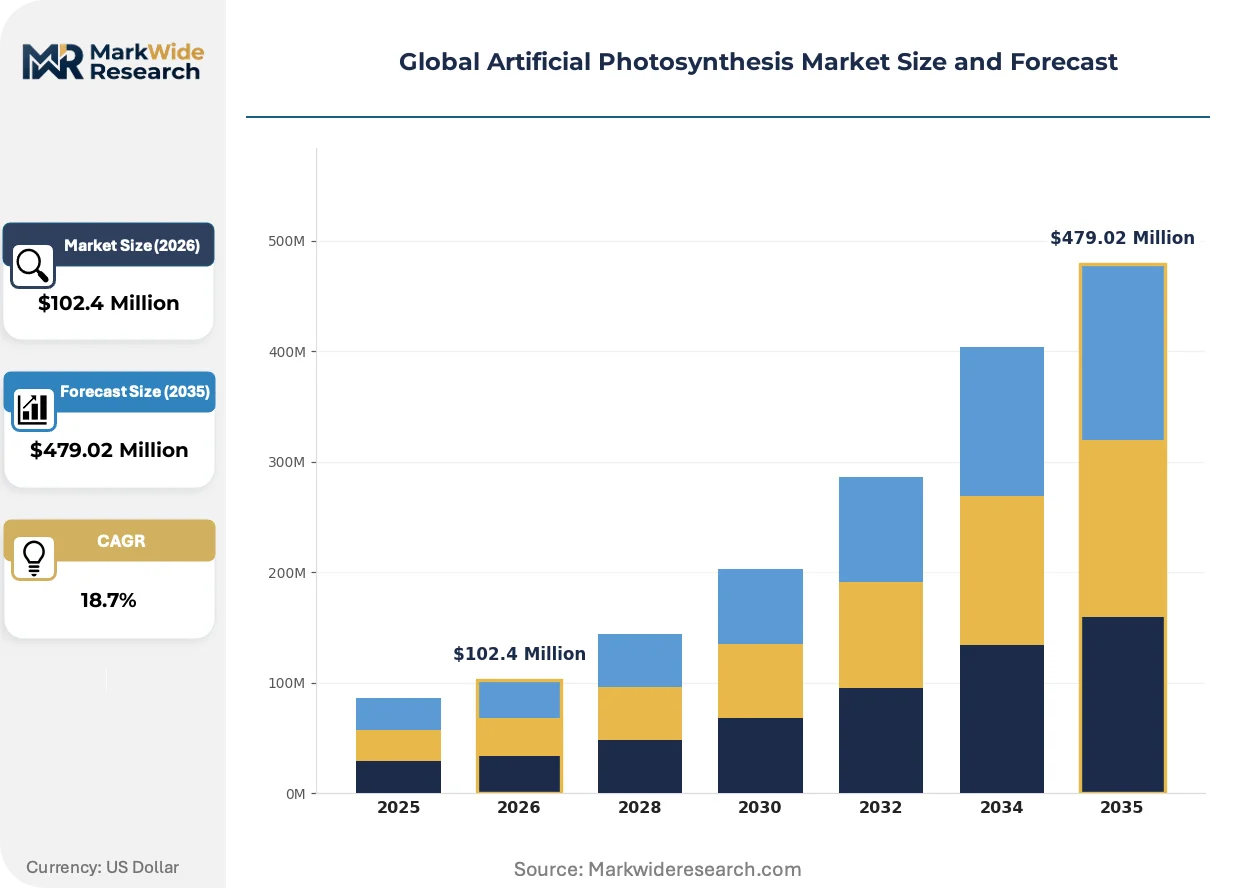
| Market Size in 2026 | $102.4 Million |
| Market Size in 2035 | $479.02 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Catalytic, Photoelectrochemical, Biomimetic, Hybrid Application: Fuel Production, Carbon Capture, Water Treatment, Biomass Generation End User: Energy Companies, Research Institutions, Agricultural Industry, Chemical Manufacturers Product Type: Solar Cells, Bioreactors, Electrolyzers, Others |
| Companies Covered | Panasonic Corporation, Siemens Energy, ENGIE, Toshiba Corporation, Fujitsu, Evonik Industries AG, Fujifilm Corporation, Mitsubishi Chemical Corporation, Twelve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Photosynthesis Market Shifts & Advancements
Artificial photosynthesis is transitioning from materials science breakthroughs to systems engineering optimization, with competitive advantage shifting toward integrated device architecture rather than isolated efficiency metrics.
Tandem photoelectrochemical cells are decomposing the traditional separation between light absorption and catalytic conversion. Research consortia in the Netherlands and California are deploying these architectures for direct seawater splitting. The technology is decomposing cost structures by eliminating separate electrolyzer hardware and membrane stacks.
REACH chemical safety standards are tightening material specifications for photoelectrode coatings and electrolyte formulations. Manufacturers must now submit full toxicity dossiers for novel catalytic materials before European deployment. German equipment suppliers are responding by qualifying earth-abundant catalyst alternatives to preempt authorization delays.
Long-term offtake contracting is displacing spot market exposure for synthetic fuel output. Aviation and maritime fuel buyers in Japan and Singapore are locking 10-15 year purchase agreements to secure supply for Scope 3 emissions targets. This pattern concentrates procurement power with integrated energy majors possessing balance sheet capacity to underwrite construction risk.
Global Artificial Photosynthesis Market Segmentation
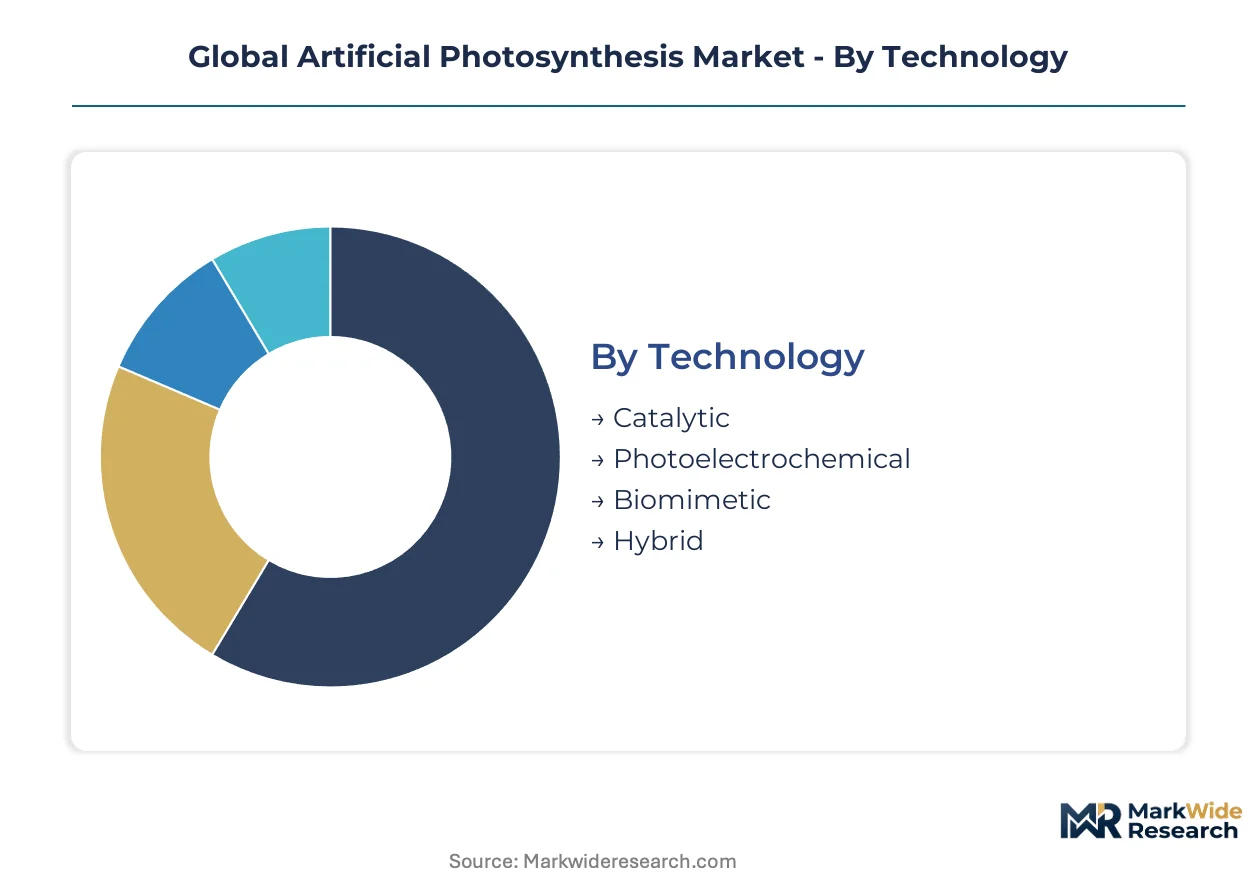
Technology choice determines capital intensity and operational efficiency for artificial photosynthesis deployments. Segment boundaries shift as laboratory breakthroughs migrate toward commercial engineering requirements.
Technology:
Photoelectrochemical systems face acute substitution pressure from mature alkaline electrolyzers in near-term hydrogen procurement.
- Photoelectrochemical:Integrated light-harvesting semiconductor electrodes convert solar energy directly to chemical bonds without separate electrolyzer hardware. Japanese METI-funded hydrogen valleys in Yokohama and Fukuoka anchor first commercial demonstrations.
- Catalytic:Heterogeneous catalyst systems drive thermochemical water splitting and CO2 reduction at elevated temperatures. German energy majors deploy pilot arrays in North Sea offshore wind zones to exploit waste heat integration.
- Biomimetic:Synthetic molecular assemblies replicate natural photosynthetic reaction centers. Venture funding concentrates in California and Netherlands consortia pursuing efficiency breakthroughs beyond semiconductor limits.
- Hybrid:Combined biological and inorganic components leverage enzyme selectivity with engineered electrode stability. Early-stage pilots target carbon capture integration for synthetic methane production.
Photoelectrochemical retains volume leadership; biomimetic holds the steepest expansion curve.
Application:
Cost tier stratification separates fuel production maturity from carbon capture pre-commercial status.
- Fuel Production:Green hydrogen, synthetic methane, and liquid hydrocarbon synthesis command strategic investment pools. EU carbon border adjustment mechanisms compress fossil-derived fuel economics in German and Dutch port zones.
- Carbon Capture:Direct air capture pairing with artificial photosynthesis remains technically immature with limited revenue visibility. Research consortia target maritime fuel applications to justify capital deployment.
- Water Treatment:Photoelectrochemical pollutant degradation and desalination byproduct recovery address industrial wastewater compliance. Japanese chemical manufacturers pilot integrated systems for semiconductor fabrication effluent.
- Biomass Generation:Engineered photosynthetic microorganisms produce protein feedstocks and biochemical precursors. Agricultural industry trials in Denmark explore algae-derived alternatives to soy imports.
Fuel production dominates current procurement; carbon capture climbs the fastest toward commercial threshold.
End User:
Customer type concentration reflects balance sheet capacity to underwrite first-of-a-kind construction risk.
- Energy Companies:Integrated majors possess project finance infrastructure for multi-hundred-megawatt installations. German utilities leverage EU Green Deal compliance deadlines to justify photoelectrochemical pilot scale-up.
- Research Institutions:National laboratories and university consortia advance materials science foundations. US Department of Energy funding priorities shape fundamental research trajectories.
- Chemical Manufacturers:Industrial gas specialists seek ISO 19880 certification scope expansion into synthetic fuel qualification. BASF and Linde consortia test catalytic reactor integration with existing steam methane reforming assets.
- Agricultural Industry:Protein and biochemical feedstock procurement drives bioreactor deployment interest. Singapore food security initiatives subsidize algae biomass demonstration contracts.
Energy companies anchor demand volume; chemical manufacturers gain share fastest through certification leverage.
Product Type:
Supply concentration in semiconductor fabrication heritage shapes competitive positioning across device categories.
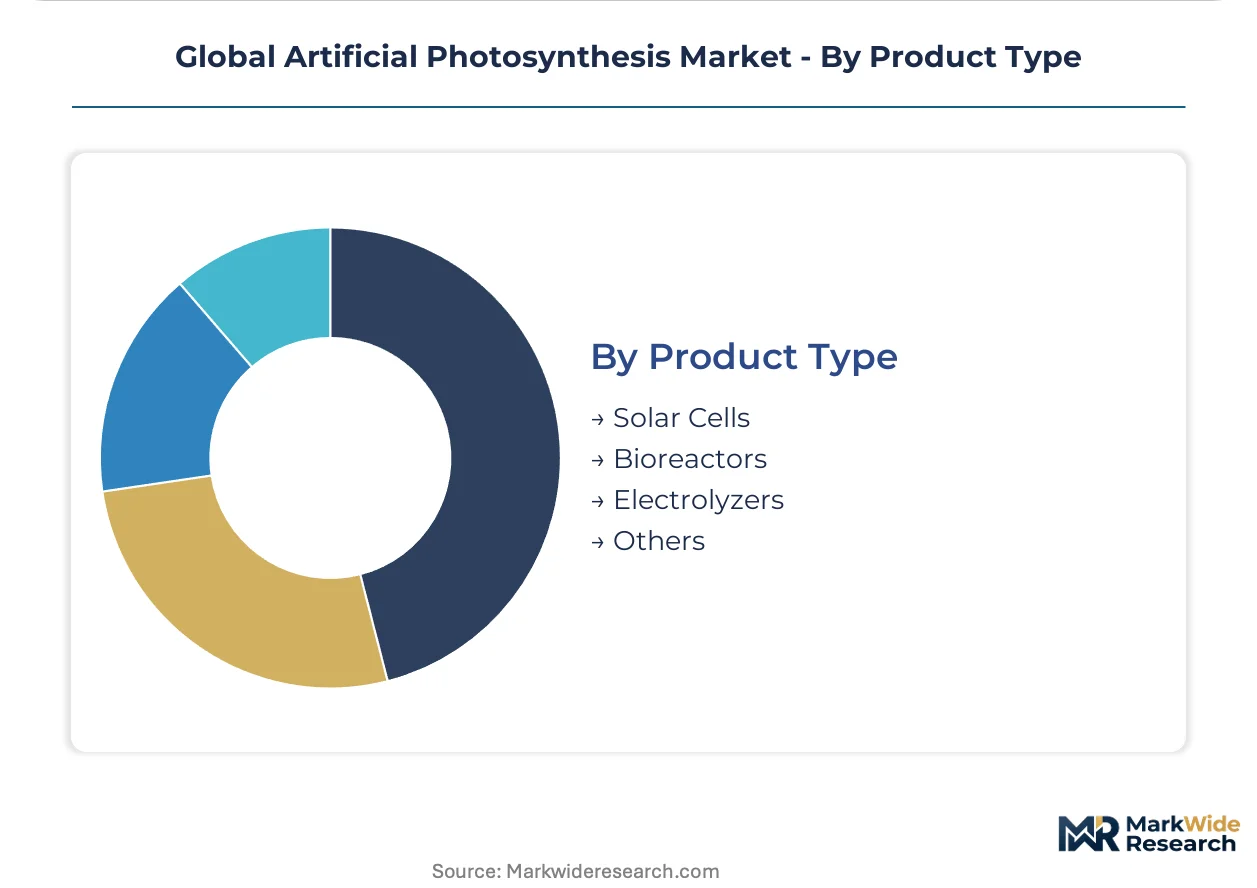
- Solar Cells:Tandem photoelectrochemical architectures decompose traditional separation between light absorption and catalytic conversion. Panasonic semiconductor fabrication lines in Osaka requalify for photoelectrode wafer production.
- Electrolyzers:Solid oxide and proton exchange membrane systems hybridize with photoelectrochemical inputs. Siemens Energy scales alkaline and PEM platforms for North Sea offshore wind hydrogen coupling.
- Bioreactors:Closed photobioreactor systems cultivate engineered cyanobacteria and microalgae. Netherlands consortia deploy tubular and flat-panel geometries for direct seawater splitting trials.
- Others:Membrane stacks, gas separation units, and thermal management subsystems complete integrated system architectures. German equipment suppliers qualify earth-abundant catalyst alternatives under REACH authorization protocols.
Electrolyzers retain installed base dominance; solar cells expand most quickly through tandem cell commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea offshore wind grid interconnects Germany and Denmark, creating dedicated renewable corridors for photoelectrochemical hydrogen production without transmission bottlenecks. Japan's hydrogen import pipeline infrastructure from Australia and Brunei underwrites its synthetic fuel demand. METI-funded hydrogen valleys in Yokohama and Fukuoka anchor first commercial demonstrations.
Germany
North Sea offshore wind lease rounds enable direct renewable feedstock supply for photoelectrochemical pilots. The EU Green Deal carbon border adjustment mechanism compresses fossil-derived hydrogen economics, accelerating compliance-driven investment. Energy majors deploy demonstration arrays in Lower Saxony and Schleswig-Holstein to exploit 2030 deadlines.
Japan
METI coordinates national hydrogen roadmap targets with JIS standards for electrolyzer performance verification. Hydrogen valley subsidies de-risk first-of-a-kind commercial deployments in port zones. Yokohama and Fukuoka clusters integrate photoelectrochemical production with steel and chemical offtake contracts.
United States
The Department of Energy and EPA jointly influence federal funding priorities and lifecycle emissions thresholds for synthetic fuel qualification. Section 45V hydrogen production tax credits subsidize first-mover projects through 2032. California research consortia advance tandem cell architectures for direct seawater splitting trials.
Netherlands
Port of Rotterdam hydrogen backbone infrastructure enables synthetic fuel export to German industrial corridors. REACH chemical safety standards tighten material specifications for photoelectrode coatings before European deployment. Eindhoven-region research consortia pursue biomimetic efficiency breakthroughs with venture capital backing.
Denmark
Ørsted-dominated offshore wind zones supply dedicated renewable capacity for electrolyzer coupling without grid interconnection costs. National carbon neutrality targets by 2045 compress project timelines for fossil fuel substitution. Copenhagen-region pilot installations test photoelectrochemical integration with district heating networks.
Global Artificial Photosynthesis Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology risk profiles. The vendor base clusters around three tiers: integrated energy majors with project finance infrastructure, industrial conglomerates with semiconductor or chemical heritage, and venture-funded specialists pursuing efficiency breakthroughs. Dominant competitive moves include strategic partnerships for offtake contracting and technology licensing to accelerate scale-up timelines.
Within the industrial conglomerate tier, Panasonic Corporation and Toshiba Corporation occupy positions anchored by semiconductor fabrication and fuel cell research heritage respectively. Siemens Energy exemplifies the energy-major archetype through electrolyzer scale-up capabilities. Venture-funded specialists like Twelve represent the breakthrough-technology vector, though commercial deployment timelines remain uncertain. These named entities illustrate how competitive advantage shifts toward integrated device architecture rather than isolated laboratory metrics.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Siemens Energy |
| ENGIE |
| Toshiba Corporation |
| Fujitsu |
| Evonik Industries AG |
| Fujifilm Corporation |
| Mitsubishi Chemical Corporation |
| Twelve |
| Others |
Supply & Pricing Matrix
ISO 19880 certification gates both supplier qualification and price tiering simultaneously, restricting system integrators to industrial gas incumbents while concentrating procurement power with balance-sheet-heavy energy majors. This regulatory chokepoint compresses margins for uncertified entrants and amplifies price premiums for qualified deployment partners.
Pricing Analysis
Volume-discount tiering structures separate project-scale offtake agreements from spot procurement for pilot installations. Pricing stratifies across certified system integrators, qualified EPC contractors, and unverified technology vendors based on ISO 19880 compliance status and proven installation track records. Cost compression in the unverified tier is intensifying because alkaline electrolyzer substitution offers 60-70% lower capital intensity for near-term hydrogen buyers. Research institutions exhibit highest price sensitivity due to grant-dependent budgets, while integrated energy companies absorb premium pricing to secure de-risked deployment timelines.
Supply Chain Analysis
Platinum-group metal supply from South Africa and Russia underwrites catalytic electrode production, creating single-source vulnerability for iridium and ruthenium feedstocks. Photoelectrochemical system manufacturing draws from Japanese semiconductor fabrication lines, German precision engineering clusters, and South Korean electrolyzer component suppliers. Distribution runs through industrial gas majors with existing hydrogen infrastructure, bypassing independent channel development for synthetic fuel offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial photosynthesis market is recovering from pilot-phase capital rationing as EU carbon border adjustments and Japan's hydrogen valley subsidies restore project economics. This cyclical upturn favors first-movers with certified deployment capabilities and locked offtake contracts.
For Market Incumbents: Compound certification leverage by expanding ISO 19880 qualification scope into synthetic methane and liquid hydrocarbon categories before 2030 compliance deadlines. Secure exclusive EPC partnerships with North Sea offshore wind developers to preempt alkaline electrolyzer substitution in German and Danish lease zones. Lock 10-15 year offtake agreements with aviation and maritime fuel buyers to defend margin position against venture-funded biomimetic challengers. For New Entrants and Emerging Players: JIS standards fast-track for electrolyzer performance verification opens procurement access to METI-funded hydrogen valleys in Yokohama and Fukuoka. Target carbon capture integration pilots for maritime fuel applications, where technical immaturity has left incumbent positions unsettled. Pursue technology licensing to German equipment suppliers seeking earth-abundant catalyst alternatives under REACH authorization protocols. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-funded biomimetic specialists in California and Netherlands consortia pursuing efficiency breakthroughs beyond semiconductor limits. Long-term viability hinges on commercial demonstration timelines for tandem photoelectrochemical cells and direct seawater splitting architectures. Monitor US Department of Energy funding priorities and Section 45V credit utilization rates as inflection indicators for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 19880 Certification Expansion | Industrial gas majors like Linde extend qualification scope into synthetic fuel categories before compliance deadlines. |
| North Sea Offshore Wind Coupling | German utilities exploit lease rounds to secure dedicated renewable feedstock without grid interconnection costs. |
| Earth-Abundant Catalyst Qualification | German equipment suppliers preempt REACH authorization delays by substituting platinum-group metals in photoelectrode coatings. |
| Long-Term Offtake Contracting | Aviation and maritime buyers in Japan and Singapore lock supply agreements to secure Scope 3 emissions targets. |
| Tandem Cell Commercialization | Panasonic leverages semiconductor fabrication heritage to requalify Osaka production lines for photoelectrode wafer output. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across energy company project developers, photoelectrochemical research directors, industrial gas procurement leads, and electrolyzer EPC contractors. Secondary validation drew from METI hydrogen roadmap disclosures, EU Green Deal implementation tracking, US Department of Energy funding announcements, and IEA technology roadmaps. Bottom-up installation capacity modeling triangulated against top-down addressable market sizing from national hydrogen strategies.
Across the analysis window, projections incorporate technology segmentation by photoelectrochemical, catalytic, biomimetic, and hybrid architectures alongside application splits across fuel production, carbon capture, water treatment, and biomass generation. CAGRs derive from patent filing trajectories, pilot installation announcements, and offtake contract velocity rather than linear extrapolation. Forecast inputs include platinum-group metal price volatility, REACH authorization timelines, and JIS standards revision cycles.
Decision-makers should treat outputs as directional under base assumptions of sustained EU carbon pricing and METI subsidy continuity; material deviation in either regime would warrant model refresh. Practitioners should keep alternative scenarios live as US Inflation Reduction Act credit phase-out schedules and South African mining export restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
South Africa Renewable Energy Market
Renewable Energy
Iran Renewable Energy Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Green Power Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Solar Home Lights Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
South Korea Renewable Energy Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
Asia-Pacific Renewable Energy Market
Renewable Energy
Renewable Energy in South America Market
Renewable Energy
Thailand Renewable Energy Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
North Africa Renewable Energy Market