
 Solar Balloon Market | 2026-2036
Solar Balloon Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Balloon Market Analytics
The EU Green Deal's stricter emissions benchmarking for aerial surveillance fleets is decoupling legacy fuel-burning platforms from public procurement eligibility. Raven Aerostar leverages its stratospheric balloon manufacturing scale to anchor defense and civilian contracts across NATO member states. World View Enterprises specializes in commercial near-space services, positioning its solar balloon constellation for persistent remote sensing missions. Cameron Balloons sustains decades of lighter-than-air engineering heritage, competing on custom envelope fabrication for research payloads.
Solar balloons are buoyant, helium or hot-air-lifted aerostats with photovoltaic-integrated skins or suspended solar arrays, typically operating at altitudes between 60,000 and 100,000 feet for weeks to months with minimal energy input. Their primary purpose is to deliver persistent, low-cost platforms for atmospheric sensing, telecommunications relay, and wide-area Earth observation without satellite launch expenditure. Inflatable balloons dominate current procurement volumes due to simpler deployment logistics, while hybrid balloons capture expanding margin pools by combining rigid structural elements with flexible envelopes for heavier sensor payloads. Remote sensing technology leads application-specific attachment rates, though energy storage systems represent the fastest-improving performance bottleneck as lithium-sulfur and solid-state cell chemistries extend nighttime station-keeping duration.
The Federal Aviation Administration governs U.S. airspace access through Part 101 regulations for unmanned balloons, while the European Union Aviation Safety Agency develops lighter-than-air type certification under its drone and innovative air mobility frameworks. ISO 9001 and AS9100 quality standards shape supplier qualification for defense-adjacent contracts, filtering out non-aerospace-grade manufacturers. China's MIIT issues GB standards for high-altitude platform station telecommunications equipment, creating parallel compliance tracks for vendors serving Asian markets. Stakeholders must monitor how stratospheric spectrum allocation decisions at the International Telecommunication Union reshape the addressable market for communications-relay solar balloons.
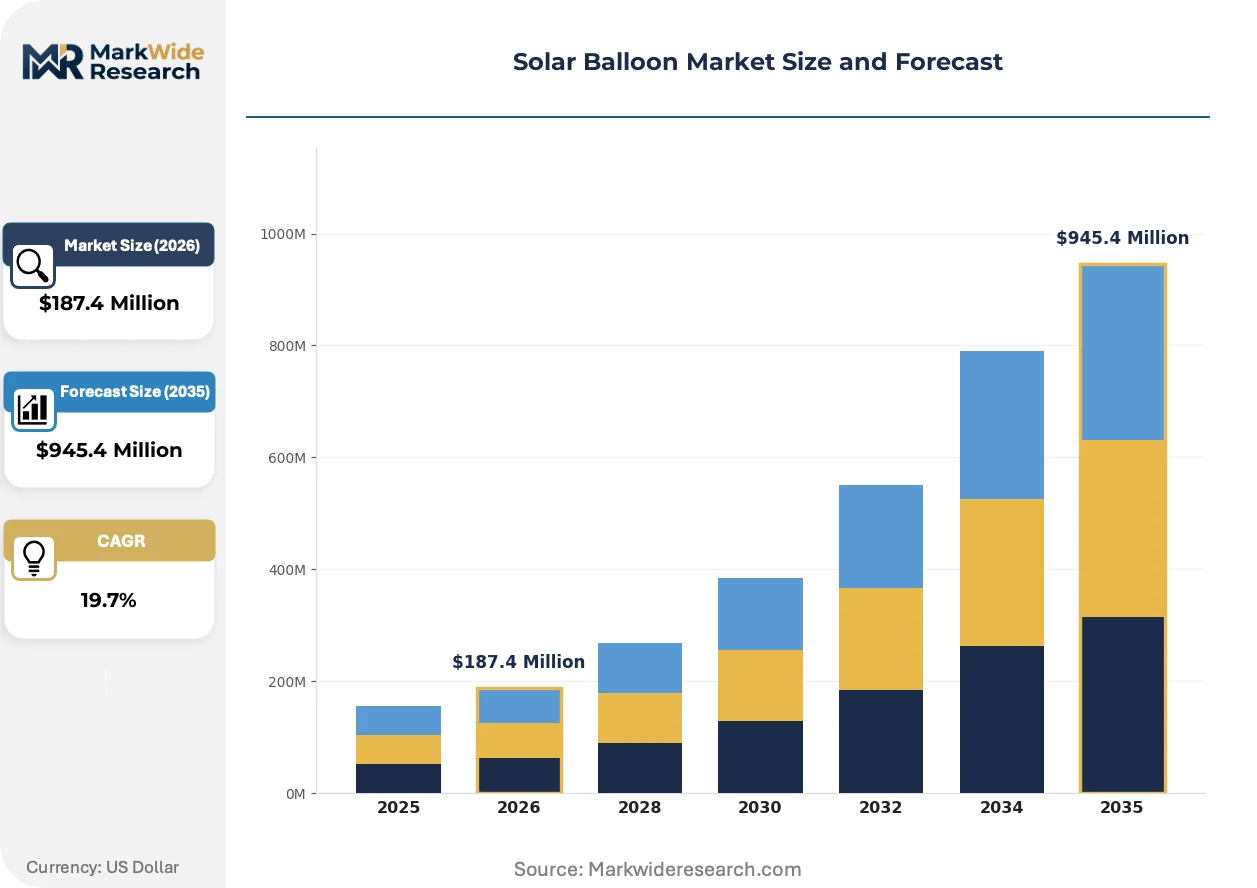
Market Dynamics
Stratospheric spectrum allocation decisions at the International Telecommunication Union are compressing the addressable market for communications-relay platforms while simultaneously unlocking new frequency bands for Earth observation missions. This regulatory pivot is forcing envelope manufacturers to redesign photovoltaic-integrated skins for dual-band operation.
Growth Catalysts
- EU Green Deal procurement exclusions:Aerial surveillance fleets in European member states face emissions benchmarking that disqualifies fuel-burning alternatives from public contracts.
- Southwestern United States demand concentration:Clear-sky conditions and restricted airspace corridors near military installations enable persistent solar balloon operations with minimal weather downtime.
- Lithium-sulfur cell chemistry maturation:Energy storage systems now extend nighttime station-keeping duration beyond 18 hours, eliminating the diurnal altitude drift that previously limited mission persistence.
Market Restraints
- Helium supply concentration:Qatar and the United States control over 80 percent of global helium extraction, creating input cost volatility for inflatable balloon manufacturers dependent on lifting gas.
- FAA Part 101 operational ceilings:Unmanned balloon regulations cap altitude at 100,000 feet without case-by-case waiver, compressing the serviceable altitude band against military and scientific requirements.
- Satellite miniaturization cost curves:CubeSat launch costs below fifty thousand dollars per unit are displacing stratospheric platforms for certain telecommunications relay applications.
Strategic Opportunities
- India high-altitude platform station deployment:TRAI spectrum consultations for stratospheric telecommunications create a regulatory opening for envelope manufacturers seeking Asian market entry.
- Hybrid balloon structural innovation:Rigid structural elements combined with flexible envelopes enable heavier synthetic aperture radar payloads previously restricted to fixed-wing platforms.
- ISO 9001-AS9100 certification arbitrage:Defense-adjacent contract qualification filters out non-aerospace-grade manufacturers, creating margin pools for qualified suppliers.
Industry Challenges
- Stratospheric meteorology modeling talent scarcity:Persistent platform operations require atmospheric scientists capable of predicting wind shear at 80,000 feet, a skill set concentrated in government laboratories.
- MIIT GB standards compliance timelines:China's telecommunications equipment certification for high-altitude platform stations adds 14-18 months to market entry for Western envelope manufacturers.
- Photovoltaic-integrated envelope repair protocols:Field maintenance of flexible solar arrays at remote launch sites requires specialized technician training not yet standardized across operator networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Balloon Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $945.4 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Balloons, Rigid Balloons, Hybrid Balloons, Solar Drones Application: Environmental Monitoring, Agricultural Surveying, Disaster Management, Atmospheric Research End User: Research Institutes, Government Agencies, Agricultural Companies, NGOs Technology: Photovoltaic Systems, Energy Storage, Remote Sensing, Communication Systems |
| Companies Covered | Raven Aerostar, World View Enterprises, Cameron Balloons, Airstar, Airborne Light, Lockheed Martin Corporation, Raytheon Technologies Corporation, Kubicek Balloons, UltraMagic Balloons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Balloon Market Evolving Landscape
Envelope materials and energy storage architectures are converging to extend mission endurance beyond seasonal weather windows. This convergence is compressing the operational gap between solar balloons and small satellite constellations.
Perovskite-silicon tandem photovoltaic cells are expanding into stratospheric balloon applications by delivering 32 percent conversion efficiency under high-altitude ultraviolet exposure. Environmental monitoring agencies in the United States are piloting these materials for persistent atmospheric sensing missions. The technology is expanding into remote sensing contracts previously reserved for satellite operators by cutting payload power system mass by 40 percent.
REACH substance restrictions on persistent organic pollutants are forcing European envelope manufacturers to reformulate polyurethane coating chemistries. The industrial consequence is a 12-18 month qualification cycle for new material stacks seeking EASA type certification. Hybrid balloon segments are most affected, as rigid structural elements rely on epoxy resin systems now under regulatory scrutiny for bisphenol content.
Defense procurement offices are consolidating vendor panels around multi-year availability contracts rather than per-mission spot purchases. This channel shift compresses the addressable supplier base to firms with AS9100 certification and cleared personnel facilities. The United Kingdom and Australia are most visible in this transition, with their stratospheric intelligence programs now requiring 99.5 percent platform availability guarantees.
Solar Balloon Market Segmentation
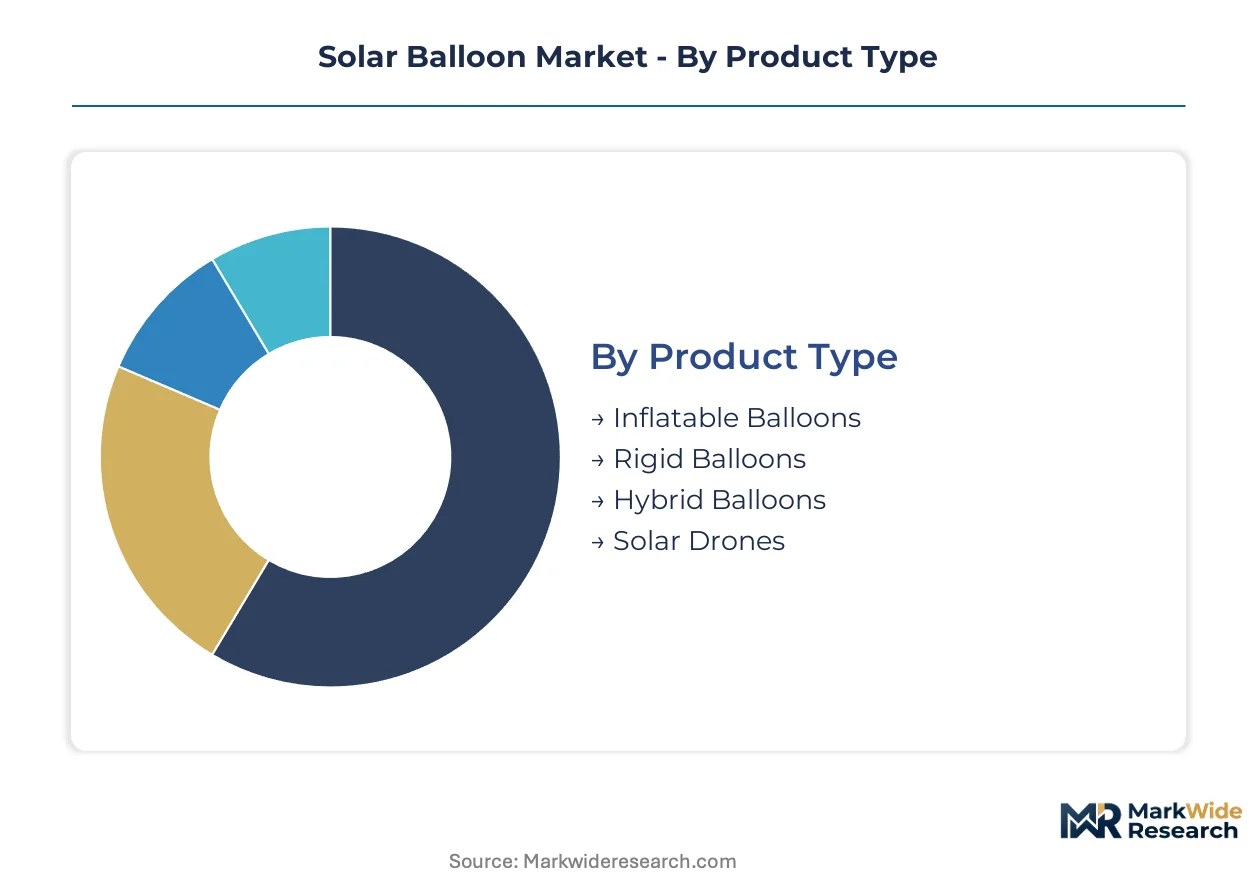
Solar balloon procurement decisions hinge on payload mass, mission duration, and regulatory compliance requirements. Capital allocation varies dramatically across envelope architectures and power systems, reshaping vendor specialization patterns.
Product Type:
Capital intensity peaks with rigid structural elements requiring aerospace-grade composites, while inflatable platforms minimize upfront tooling investment.
- Inflatable Balloons:Flexible polyethylene or polyester envelopes rely on helium or hot-air buoyancy with minimal rigid infrastructure. Demand concentrates in the southwestern United States, where environmental monitoring agencies deploy rapid-response fleets for atmospheric sensing missions. The FAA's Part 101 certification pathway accelerates deployment timelines for government contracts.
- Hybrid Balloons:Rigid structural spars integrated with flexible membranes enable synthetic aperture radar payloads exceeding 500 kilograms. European defense procurement under EU Green Deal emissions exclusions favors these platforms for persistent intelligence missions. REACH substance restrictions on polyurethane coatings extend qualification cycles to 18 months.
- Rigid Balloons:Fixed-wing aerostat derivatives with composite hulls and integrated solar arrays. Research institutes in Germany and France pilot these for multi-month stratospheric astronomy campaigns.
- Solar Drones:Fixed-wing unmanned aerial vehicles with photovoltaic skins operating below 60,000 feet. Agricultural surveying companies in Australia favor these for diurnal crop health mapping.
Most installed capacity flows through Inflatable Balloons. Expansion is steepest in Hybrid Balloons.
Application:
Revenue concentration tracks public procurement cycles, with environmental agencies outspending commercial operators by order of magnitude.
- Environmental Monitoring:Persistent atmospheric sensing for climate data collection and pollution tracking. The United States Environmental Protection Agency and NOAA dominate procurement, leveraging southwestern clear-sky corridors for 90-day continuous operations. Perovskite-silicon tandem cells are cutting payload power mass by 40 percent.
- Atmospheric Research:Stratospheric chemistry sampling and microgravity precursor missions. NASA's balloon program in Palestine, Texas and Sweden's Esrange Space Center anchor global demand for heavy-lift platforms. Lithium-sulfur energy storage now extends nighttime station-keeping beyond 18 hours.
- Agricultural Surveying:Multispectral crop health mapping and irrigation optimization. Brazilian agribusiness operators and Australian wheat belt cooperatives drive commercial adoption.
- Disaster Management:Emergency communications relay and damage assessment following infrastructure collapse. Philippines disaster response agencies and Indonesian meteorological authorities deploy rapid-launch inflatable fleets.
Government agencies deploy the largest fleet volumes. Agricultural surveying climbs the fastest as imagery resolution improves.
End User:
Contracting authority determines certification requirements, with defense-adjacent procurement filtering out non-AS9100 suppliers.
- Government Agencies:Defense, meteorological, and environmental departments with multi-year availability contracts. The United Kingdom and Australia now mandate 99.5 percent platform availability guarantees, consolidating vendor panels around cleared-facility manufacturers.
- Research Institutes:University consortia and national laboratories with peer-reviewed funding cycles. Caltech's Jet Propulsion Laboratory and France's CNRS lead stratospheric astronomy and climate science missions.
- Agricultural Companies:Large-scale farming operations and agritech service providers. Brazilian soybean producers and Australian pastoral leaseholders contract seasonal survey services.
- NGOs:Humanitarian organizations and conservation groups with grant-dependent budgets. Wildlife monitoring in Kenya and refugee camp connectivity in Jordan represent emerging use cases.
Defense and environmental agencies control the installed base. Agricultural companies gain share fastest as per-acre imaging costs fall.
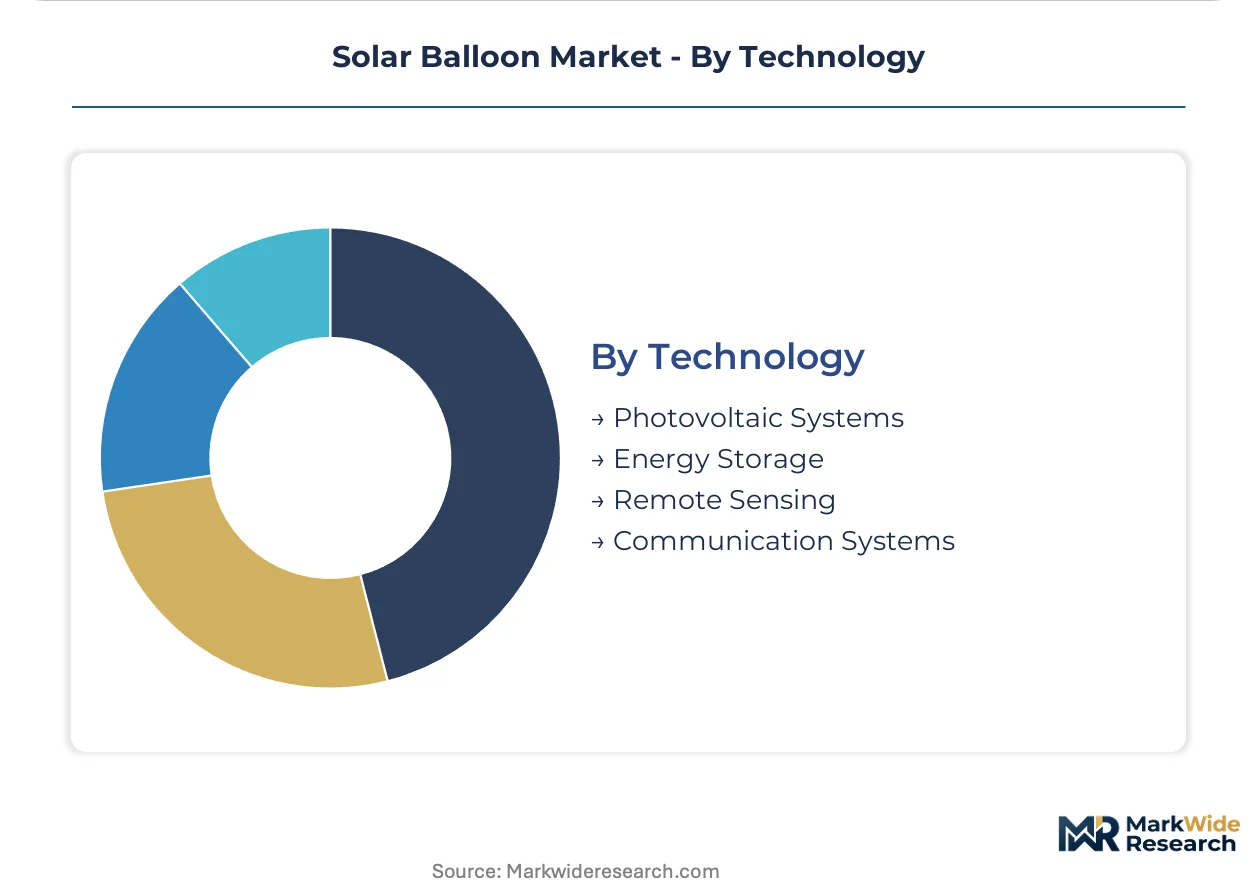
Technology:
Performance differentiation now centers on energy density rather than envelope materials, reshaping supplier value capture.
- Energy Storage:Lithium-sulfur and solid-state cell chemistries eliminating diurnal altitude drift. Southwestern United States operators now achieve true persistent station-keeping, unlocking military communications relay contracts previously reserved for satellites.
- Photovoltaic Systems:Perovskite-silicon tandem cells delivering 32 percent conversion efficiency under stratospheric ultraviolet exposure. Environmental monitoring agencies in the United States pilot these for missions previously requiring satellite launch expenditure.
- Remote Sensing:Hyperspectral imagers, synthetic aperture radar, and atmospheric sampling payloads. European defense procurement drives demand for dual-band operation capability.
- Communication Systems:Stratospheric relays for rural broadband and emergency backup networks. India's TRAI spectrum consultations for high-altitude platform stations create regulatory opening for equipment vendors.
Photovoltaic systems dominate capital deployment. Energy storage represents the steepest expansion trajectory as chemistry maturation extends mission endurance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atmospheric scientists capable of predicting wind shear at 80,000 feet concentrate in government laboratories across three continents, anchoring operational deployment decisions.
United States
Environmental monitoring agencies in the southwestern United States expand procurement of stratospheric balloon platforms for persistent atmospheric sensing. The Federal Aviation Administration's updated Part 101 regulations streamline commercial access to near-space altitudes. Clear-sky conditions and restricted airspace corridors near military installations in Arizona and New Mexico enable 90-day continuous operations with minimal weather downtime.
United Kingdom
Defense procurement offices consolidate vendor panels around multi-year availability contracts requiring 99.5 percent platform availability guarantees. Stratospheric intelligence programs under the Ministry of Defence filter suppliers through AS9100 certification and cleared personnel facility requirements. Industrial activity clusters around aerospace engineering centers in Bristol and Farnborough, where lighter-than-air heritage meets contemporary surveillance demand.
Germany
Research institutes pilot rigid balloon derivatives with composite hulls for multi-month stratospheric astronomy campaigns. REACH substance restrictions on persistent organic pollutants force polyurethane coating reformulations, extending EASA type certification cycles to 18 months. Manufacturing and testing concentrate in Bavaria and Baden-Württemberg, where epoxy resin systems face regulatory scrutiny for bisphenol content.
India
TRAI spectrum consultations for stratospheric telecommunications create regulatory openings for envelope manufacturers seeking Asian market entry. The high-altitude platform station deployment program targets rural broadband gaps in underserved districts. Industrial preparation centers on Bengaluru and Hyderabad, where aerospace supply chains intersect with satellite manufacturing capabilities.
China
MIIT issues GB standards for high-altitude platform station telecommunications equipment, creating parallel compliance tracks for vendors serving domestic markets. Western envelope manufacturers face 14-18 month certification timelines for market entry. Research and prototyping activity concentrates in the Yangtze River Delta, where state-funded stratospheric programs advance independent of international supplier networks.
Solar Balloon Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across contract tiers, producing a bifurcated vendor base. Defense-adjacent procurement filters out non-aerospace-grade manufacturers, compressing the qualified supplier pool around certification holders. Three archetypes dominate: stratospheric scale manufacturers, custom envelope fabricators, and diversified defense contractors extending into lighter-than-air platforms. Competitive moves center on multi-year availability contracts and geographic expansion into Asian spectrum allocation openings.
Within the stratospheric manufacturing tier, Raven Aerostar and World View Enterprises exemplify divergent positioning. Raven Aerostar leverages manufacturing scale to anchor defense and civilian contracts across NATO member states. World View Enterprises occupies a commercial near-space specialization, positioning balloon constellations for persistent remote sensing missions. Among heritage fabricators, Cameron Balloons represents custom envelope engineering sustained across decades of lighter-than-air development.
| Leading Market Players |
|---|
| Raven Aerostar |
| World View Enterprises |
| Cameron Balloons |
| Airstar |
| Airborne Light |
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| Kubicek Balloons |
| UltraMagic Balloons |
| Others |
Value Network & Pricing Analysis
Perovskite-silicon tandem photovoltaic cell manufacturing scale-up is compressing payload power system costs while concentrating supplier qualification around aerospace-grade certification holders. This dual shift simultaneously expands addressable mission budgets for environmental monitoring agencies and filters envelope manufacturers through ISO 9001-AS9100 compliance tiers.
Pricing Analysis
Bundled platform-as-a-service contracts dominate defense procurement, while unbundled envelope-only sales persist in research institute segments. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified hybrid balloon systems from rapid-deployment inflatable alternatives. Pricing pressure stems from CubeSat launch cost compression below fifty thousand dollars per unit, forcing stratospheric platform vendors to demonstrate persistence advantages. Agricultural surveying companies exhibit highest price sensitivity, whereas United Kingdom Ministry of Defence contracts prioritize availability guarantees over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from United States environmental agencies, while distributor networks serve fragmented agricultural operators in Brazil and Australia. Helium extraction concentrates in Qatar and the United States, with polyurethane envelope fabrication anchored in Germany and the United Kingdom. Lithium-sulfur cell chemistry, composite structural spars, and perovskite photovoltaic laminates constitute critical input dependencies. Single-source vulnerability in stratospheric meteorology modeling talent—concentrated in government laboratories—creates operational chokepoints for commercial operators. Distribution runs through defense procurement offices, research institute purchasing consortia, and agritech service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as defense procurement offices consolidate vendor panels around 99.5 percent platform availability guarantees, filtering contracts toward AS9100-certified manufacturers with cleared personnel facilities.
For Market Incumbents: Lock in multi-year availability contracts with United Kingdom and Australian defense procurement offices before satellite miniaturization cost curves erode the communications relay segment. Deepen backward integration into lithium-sulfur energy storage systems to capture margin pools from chemistry maturation. Extend AS9100 certification arbitrage by acquiring cleared-facility capacity in southwestern United States corridors where restricted airspace supports persistent operations.
For New Entrants and Emerging Players: Begin with India's TRAI spectrum consultation window for high-altitude platform station telecommunications equipment, where regulatory opening precedes vendor panel consolidation. Target agricultural surveying in Australian wheat belt cooperatives and Brazilian soybean operations as the fastest-expanding commercial segment. Pursue ISO 9001-AS9100 certification as a go-to-market prerequisite rather than post-entry investment.
For Investors and Strategic Acquirers: Valuations sit cheapest among custom envelope fabricators lacking defense-adjacent certification but possessing lighter-than-air engineering heritage convertible to hybrid balloon platforms. Long-term viability hinges on convergence between stratospheric persistence and small satellite cost curves—five-to-ten year positioning requires energy storage chemistry exposure. Monitor International Telecommunication Union spectrum allocation decisions as the inflection signal for communications-relay addressable market expansion or compression.
| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Investment | Defense procurement offices filter vendor panels through aerospace-grade quality standards, consolidating contract access. |
| Lithium-Sulfur Energy Storage Integration | Extended nighttime station-keeping unlocks military communications relay contracts previously reserved for satellites. |
| India High-Altitude Platform Station Entry | TRAI spectrum consultations create regulatory opening for envelope manufacturers seeking Asian market expansion. |
| Perovskite Photovoltaic Scale-Up | 32 percent conversion efficiency cuts payload power mass by 40 percent, displacing satellite launch expenditure for remote sensing. |
| Hybrid Balloon Structural Innovation | Rigid spar integration enables synthetic aperture radar payloads exceeding 500 kilograms for European defense intelligence missions. |
Research Methodology
Bottom-up environmental monitoring and defense procurement modeling reconciled against top-down envelope manufacturing capacity tracking forms the analytical core. Primary interviews with stratospheric program directors at NASA, FAA certification specialists, lithium-sulfur battery development leads, and agricultural surveying service providers combined with secondary validation from FAA Part 101 regulatory filings, EASA type certification databases, International Telecommunication Union spectrum allocation records, and United States Environmental Protection Agency procurement disclosures. Triangulation across these sources calibrated installed base estimates and replacement cycle assumptions.
Input-output matrices mapped photovoltaic system efficiency gains against energy storage chemistry maturation to project mission endurance extension across the analysis window. Segmentation modeling captured product type splits between inflatable, hybrid, and rigid architectures; application concentration in environmental monitoring, atmospheric research, agricultural surveying, and disaster management; and technology differentiation across energy storage, photovoltaic systems, remote sensing, and communication systems. CAGRs derived from deployment velocity assumptions tied to regulatory pathway streamlining and procurement cycle timing. Stratospheric meteorology modeling talent scarcity and REACH substance restriction timelines factored as supply-side constraints.
Several conditions sit outside the modeled scope, including abrupt helium supply disruption from Qatar extraction facility outages, unilateral FAA Part 101 altitude ceiling modifications, and breakthrough satellite launch cost compression below ten thousand dollars per unit. Forecasts reflect assumptions about lithium-sulfur chemistry commercialization timelines and European defense procurement continuity under EU Green Deal emissions exclusions. Periodic stress-testing of base assumptions is recommended against International Telecommunication Union spectrum reallocation announcements and MIIT GB standards compliance timeline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Wave Energy Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Solar Oven Market
Renewable Energy
Solar Street Lighting Market
Renewable Energy
Solar Autoclave Market
Renewable Energy
Thailand Renewable Energy Market
Renewable Energy
Singapore Renewable Energy Market
Renewable Energy
Net-Zero Energy Buildings Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
Mexico Renewable Energy Market
Renewable Energy
West Africa Renewable Energy Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
Solar Floating Pool Lights Market
Renewable Energy
South Europe Renewable Energy Market
Renewable Energy
Wind Turbine Automation Market