
 Solar Navigation Light Market | 2026-2036
Solar Navigation Light Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Navigation Light Market Insights
Marine equipment distribution through specialized lighthouse and buoy system integrators is reconfiguring as direct procurement from national port authorities expands. Carmanah Technologies Corporation leverages its vertically integrated manufacturing to sustain pricing control across North American coastal installations. Sealite Pty Ltd anchors Australasian supply through dedicated distributor networks serving harbor masters and maritime safety agencies.
Solar navigation lights are photovoltaic-powered self-contained luminous signaling devices, typically incorporating monocrystalline silicon panels, nickel-metal hydride or lithium battery storage, and LED emitters rated for visibility ranges from two to fifteen nautical miles, engineered to operate autonomously without grid connection or routine fuel replacement. The marine application segment dominates procurement volumes given mandatory carriage requirements for commercial vessels under SOLAS conventions, while offshore platforms represent the fastest-growing installation category as oil and gas operators retrofit remote structures with zero-maintenance lighting. LED lights command the largest product type share due to luminous efficacy advantages and declining semiconductor costs, though multi-functional lights integrating AIS transponders and remote monitoring capabilities capture expanding margin pools.
IMO SOLAS regulations, IALA recommendation guidelines, and national maritime administration standards collectively shape product certification requirements and procurement specifications across coastal jurisdictions. The US Coast Guard maintains separate approval processes for private aids to navigation, while EMA and national lighthouse authorities across Europe enforce harmonized visibility and reliability benchmarks. Stakeholders must monitor evolving battery chemistry safety standards and emerging cyber-resilience requirements for networked navigation aids as remote monitoring capabilities proliferate.
Market Dynamics
Port authorities across Singapore, South Korea, and Vietnam are mandating compliance with updated IALA maritime safety codes, forcing a wholesale replacement cycle of conventional beacon systems with photovoltaic-powered alternatives.
Growth Catalysts
- SOLAS Convention Mandates:The International Maritime Organization's Safety of Life at Sea regulations require commercial vessels to carry self-contained luminous signaling devices, creating baseline demand across all flagged fleets.
- East Asian Port Modernization:Singapore's Maritime and Port Authority has issued technical specifications prioritizing solar-powered aids to navigation for new offshore terminal developments.
- Lithium Battery Chemistry Advances:Improved energy density in nickel-metal hydride and lithium-ion storage systems extends autonomous operation windows from seasonal to multi-year maintenance cycles.
Market Restraints
- Monocrystalline Silicon Panel Concentration:Chinese photovoltaic module manufacturers control approximately 80% of upstream cell supply, exposing procurement costs to trade policy volatility.
- IALA Certification Timelines:Harmonized visibility and reliability benchmarking across European lighthouse authorities creates 18-24 month approval bottlenecks for new product entrants.
- Conventional Grid-Powered Legacy Infrastructure:Existing hardwired beacon networks in North American Great Lakes installations represent sunk capital that delays replacement decisions.
Strategic Opportunities
- Indonesian Archipelago Expansion:The Directorate General of Sea Transportation is tendering for 2,000+ unlit aids to navigation across remote island chains lacking grid connectivity.
- AIS Transponder Convergence:Multi-functional lights integrating automatic identification system transmitters with LED emitters capture premium positioning in vessel traffic service zones.
- Remote Monitoring Platforms:Cellular and satellite telemetry integration enables predictive maintenance contracts that transform one-time equipment sales into recurring revenue streams.
Industry Challenges
- Cyber-Resilience Certification:Networked navigation aids with remote access capabilities now face emerging penetration testing requirements from the US Coast Guard's Cyber Command.
- Marine Electrical Engineering Talent:The specialized skill set combining photovoltaic system design with IALA photometric standards remains concentrated among aging lighthouse authority technical staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Navigation Light Market |
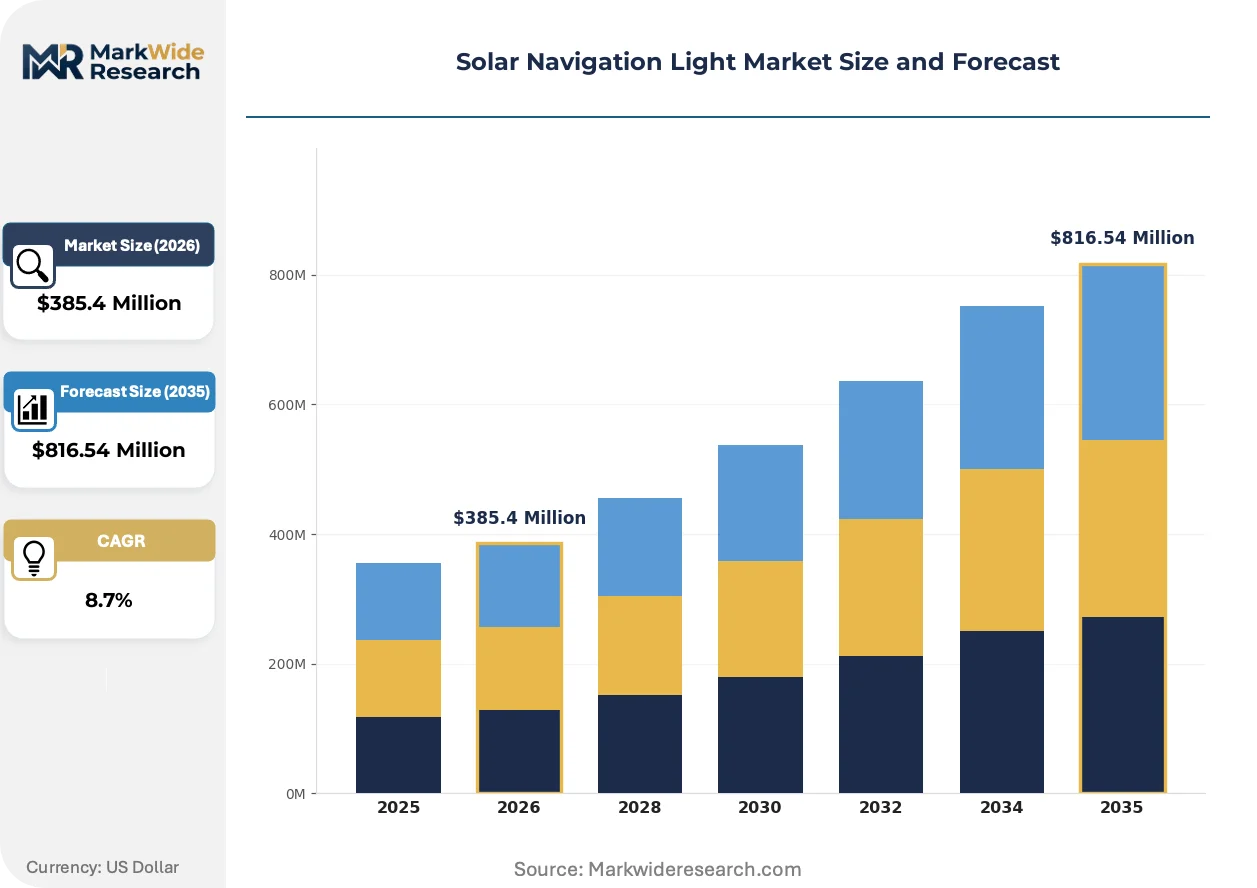
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lights, Beacon Lights, Multi-functional Lights, Signal Lights Application: Marine, Aviation, Offshore Platforms, Emergency Services Installation Type: Fixed Mount, Portable, Floating, Rail-mounted End User: Government Agencies, Private Vessels, Shipping Companies, Recreational Boating |
| Companies Covered | Carmanah Technologies Corporation, Sealite Pty Ltd, Pharos Marine Automatic Power Inc., Tideland Signal Corporation, Sabik Marine, Orga BV, Zeni Lite Buoy Co., Ltd., Ryokuseisha Corporation, JFC Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Navigation Light Market Trends and Innovations
Photovoltaic beacon technology is compressing installation timelines and eliminating cable trenching requirements, while remote telemetry integration is redefining service delivery models across coastal jurisdictions.
Software-defined light control is virtualizing the traditional hardware-based flasher mechanism. Solid-state programming now generates IALA-compliant character sequences through microcontroller firmware rather than mechanical chopper disks. Offshore platform operators in the North Sea and Gulf of Mexico are specifying these programmable units to reduce spare parts inventory. This virtualization is compressing the traditional supplier base by enabling semiconductor manufacturers to displace legacy electromechanical component vendors.
REACH substance restrictions on nickel-cadmium battery chemistries are accelerating lithium iron phosphate adoption in European lighthouse authority specifications. The European Chemicals Agency's 2024 candidate list update restricts cadmium content in marine equipment sold within EU member states. Scandinavian and Baltic Sea installations are responding fastest, with Sweden's Maritime Administration completing fleet-wide chemistry transitions ahead of compliance deadlines.
Direct procurement from national port authorities is disintermediating traditional marine equipment distributors in East Asian markets. Harbor masters in Busan, Kaohsiung, and Ho Chi Minh City now issue technical specifications requiring vendor pre-qualification through centralized government procurement portals. This channel compression is most visible in Vietnam, where the Vietnam Maritime Administration's national tendering platform has consolidated previously fragmented lighthouse district purchasing decisions.
Solar Navigation Light Market Segmentation
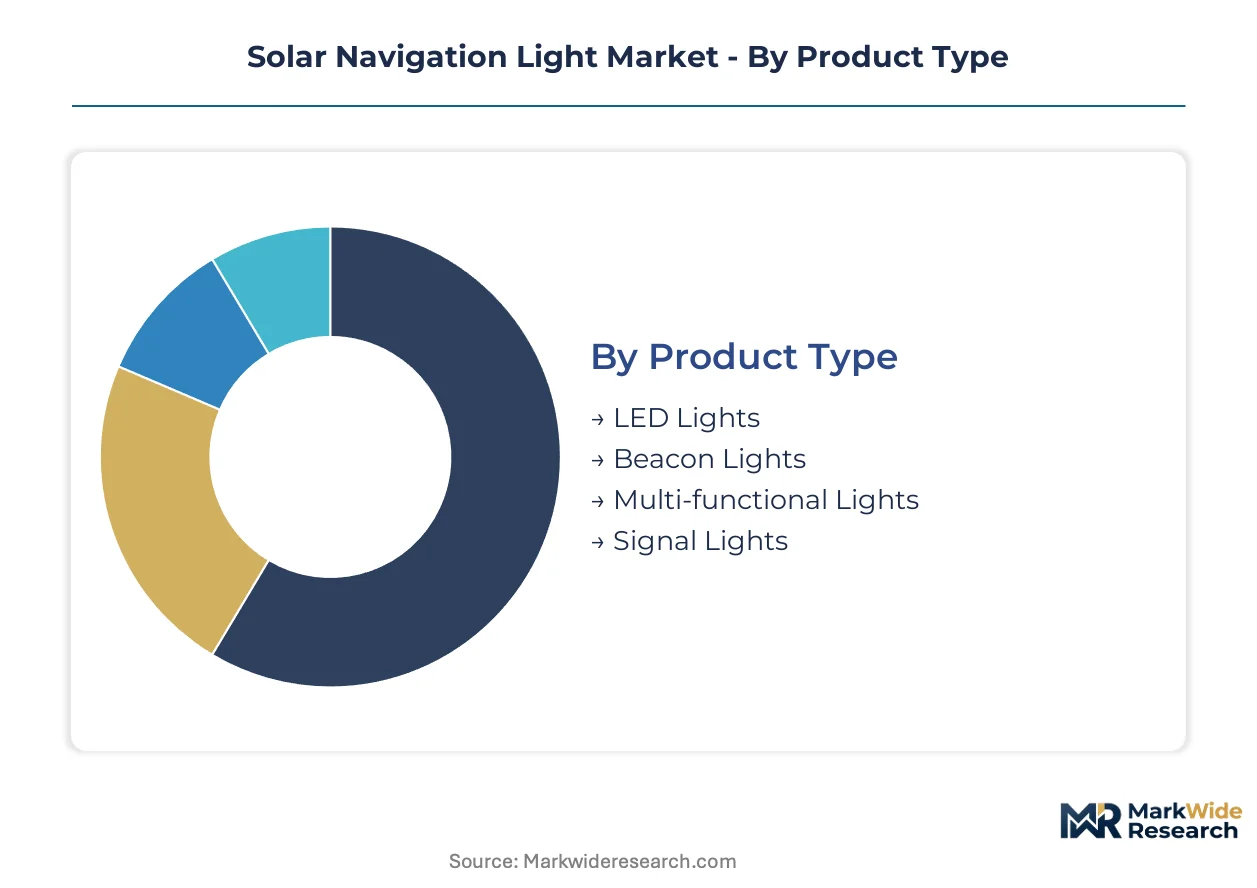
Segmentation in solar navigation lights reveals divergent replacement cycles across product architectures and end-use environments. Procurement patterns vary sharply between regulatory-mandated marine installations and discretionary recreational applications, while installation physics dictate entirely different supply chain configurations.
Product Type:
Replacement cycles compress from multi-year beacon overhauls to rapid LED emitter swaps, with functional integration driving the steepest upgrade tempo.
- LED Lights:Solid-state emitters rated for 50,000+ hour lifespans dominate new procurement, with luminous efficacy above 120 lumens per watt reducing photovoltaic panel sizing requirements. Singapore's Maritime and Port Authority specifies these for all new offshore terminal aids to navigation, citing maintenance elimination.
- Multi-functional Lights:Integrated units combining LED emitters with AIS transponders and cellular telemetry command premium positioning in vessel traffic service zones. North Sea offshore platform operators specify these programmable units to collapse spare parts inventory and enable remote status monitoring.
- Beacon Lights:Traditional rotating or flashing units with mechanical chopper mechanisms persist in legacy installations.
- Signal Lights:Specialized color-coded luminous devices for channel marking and hazard identification.
LED lights dominate installed base. Multi-functional lights are where expansion concentrates.
Application:
Cost tiers separate capital-intensive offshore retrofits from volume-driven marine compliance mandates, with aviation representing a certification-heavy premium tier.
- Marine:SOLAS-mandated carriage requirements for commercial vessels create baseline demand across all flagged fleets, with harbor masters specifying autonomous solar units for unlit channel markers. East Asian shipping corridors concentrate procurement volumes as port modernization accelerates.
- Offshore Platforms:Oil and gas operators retrofit remote structures with zero-maintenance lighting, eliminating helicopter-borne technician visits for battery replacement. Gulf of Mexico and North Sea installations specify lithium iron phosphate chemistry for multi-year autonomous operation.
- Aviation:FAA-compliant solar-powered airport edge lighting for remote airstrips.
- Emergency Services:Rapid-deployment luminous marking for disaster response and temporary hazard identification.
Marine applications anchor procurement volume. Offshore platforms are climbing the fastest.
Installation Type:
Volume concentrates in fixed infrastructure, while portability commands margin premiums through rental and contingency service models.
- Fixed Mount:Permanent installations on buoys, lighthouses, and offshore structures represent the core revenue base, with IALA photometric standards governing visibility range and flash character specifications.
- Portable:Rapid-deployment units with integrated photovoltaic panels and telescopic masts serve temporary channel marking and construction zone safety.
- Floating:Self-contained units for mooring buoys and dynamic positioning reference points.
- Rail-mounted:Specialized fixtures for marine vessel deck mounting and temporary platform lighting.
Fixed mount installations dominate installed base. Portable units are gaining share fastest.
End User:
Customer type dictates procurement channel structure, with government tenders favoring pre-qualified vendor pools and private fleets prioritizing total cost of ownership.
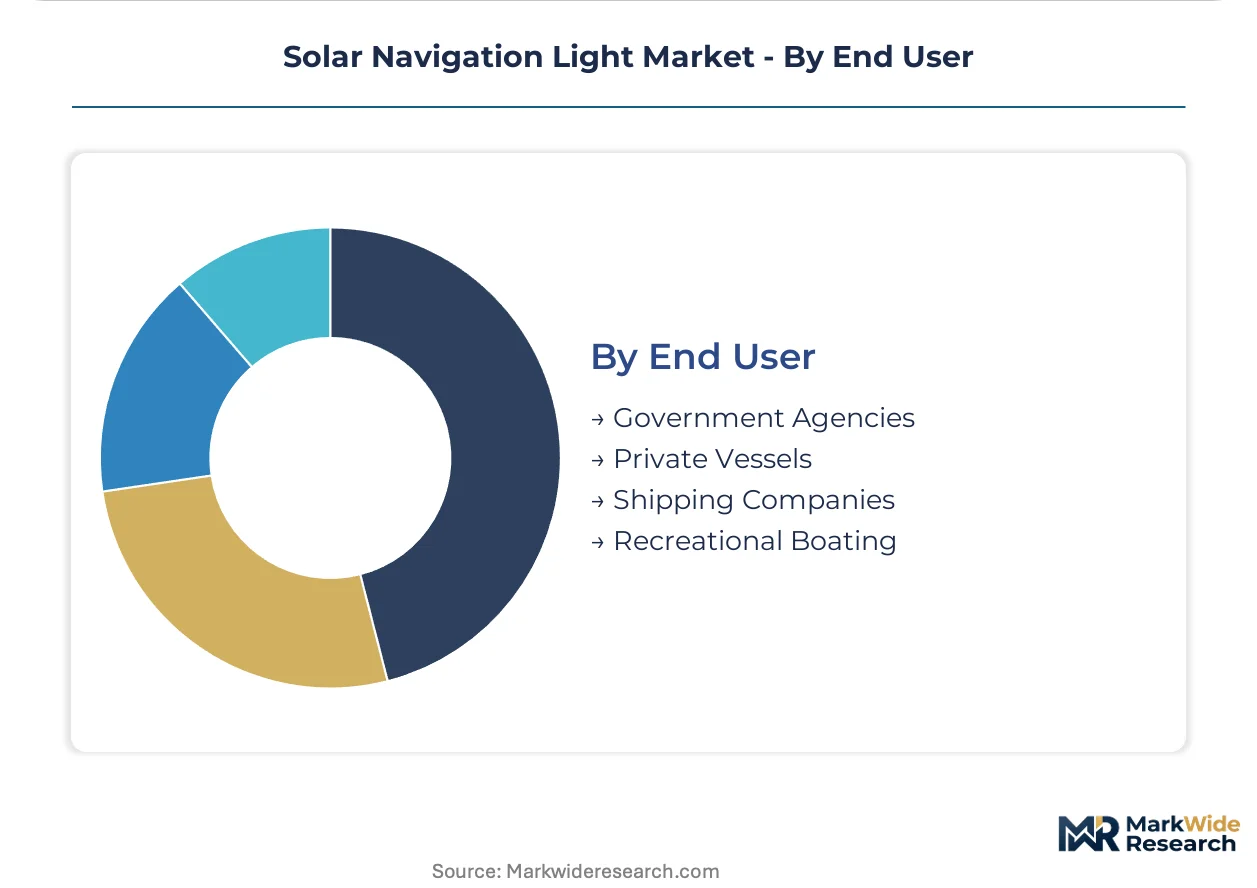
- Government Agencies:National lighthouse authorities and port authorities issue harmonized technical specifications with 18-24 month certification timelines, consolidating previously fragmented district purchasing through centralized procurement portals.
- Shipping Companies:Container lines and bulk carriers prioritize SOLAS compliance with minimal crew maintenance burden, specifying sealed lithium battery systems for multi-voyage autonomous operation.
- Private Vessels:Yacht and commercial fishing vessel owners balance regulatory minimums against discretionary feature upgrades.
- Recreational Boating:Weekend sailors and marina operators represent price-sensitive demand with seasonal replacement patterns.
Government agencies dominate installed base. Shipping companies are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Singapore's Tuas mega-terminal anchors Asia-Pacific procurement volumes for solar navigation lights, with East Asian shipping corridors generating concentrated replacement demand as port authorities modernize aids to navigation infrastructure.
Singapore
Singapore's Maritime and Port Authority mandates solar-powered aids to navigation for all new offshore terminal developments, driving specification-grade LED beacon procurement. The country's national maritime regulator enforces updated IALA maritime safety codes that require zero-maintenance autonomous lighting systems. The Tuas Port development zone concentrates installation activity as contractors retrofit channel markers for expanded vessel traffic capacity.
United States
The US Coast Guard maintains separate approval processes for private aids to navigation, creating dual-track certification requirements for solar beacon manufacturers. The FAA regulates solar-powered airport edge lighting for remote airstrips under Part 139 certification standards. Gulf of Mexico offshore platform operators specify lithium iron phosphate chemistry for multi-year autonomous operation, eliminating helicopter-borne technician visits.
Sweden
Sweden's Maritime Administration completed fleet-wide battery chemistry transitions ahead of ECHA REACH substance restrictions on nickel-cadmium chemistries. The European Chemicals Agency's 2024 candidate list update restricts cadmium content in marine equipment sold within EU member states. Scandinavian and Baltic Sea installations anchor Northern European demand for compliant photovoltaic beacon systems.
Indonesia
The Directorate General of Sea Transportation is tendering for over two thousand unlit aids to navigation across remote island chains lacking grid connectivity. The country's national maritime safety agency prioritizes autonomous solar units for archipelago-wide channel marking. Java Sea shipping lanes and Eastern Indonesia port clusters concentrate deployment timelines as inter-island trade volumes expand.
Vietnam
The Vietnam Maritime Administration's national tendering platform has consolidated previously fragmented lighthouse district purchasing decisions through centralized government procurement portals. Harbor masters in Ho Chi Minh City and Cai Mep-Thi Vai issue technical specifications requiring vendor pre-qualification. The Mekong Delta and Northern port zones concentrate installation activity as container throughput drives aids-to-navigation modernization.
Solar Navigation Light Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated manufacturers with captive photovoltaic panel production and dedicated marine certification expertise. Specialist beacon fabricators compete against diversified industrial lighting conglomerates with broader portfolio breadth. Two strategic archetypes dominate: lighthouse authority-focused certification specialists and offshore platform-oriented zero-maintenance solution providers. Competitive dynamics center on IALA pre-qualification speed and multi-year service contract bundling rather than unit price competition.
Among North American specialists, Carmanah Technologies Corporation exemplifies the vertically integrated archetype with pricing control across coastal installations. Sealite Pty Ltd anchors Australasian supply through dedicated distributor networks serving harbor masters and maritime safety agencies. Pharos Marine Automatic Power Inc. occupies a position within the offshore platform specification tier, where programmable beacon systems reduce operator spare parts inventory burdens.
| Leading Market Players |
|---|
| Carmanah Technologies Corporation |
| Sealite Pty Ltd |
| Pharos Marine Automatic Power Inc. |
| Tideland Signal Corporation |
| Sabik Marine |
| Orga BV |
| Zeni Lite Buoy Co., Ltd. |
| Ryokuseisha Corporation |
| JFC Marine |
| Others |
Pricing and Supply Chain Analysis
Jiangsu Province's monocrystalline silicon wafer fabs anchor upstream photovoltaic cell supply, with capacity utilization swings in this manufacturing cluster transmitting directly into module pricing power for downstream beacon integrators. Chinese photovoltaic manufacturers control approximately four-fifths of global cell production, concentrating procurement cost leverage among East Asian port authorities and offshore platform operators.
Pricing Analysis
Volume-discount tiering structures separate national lighthouse authority fleet procurements from single-unit marine vessel carriage requirements, with IALA certification grade and after-sales service bundling as primary price differentiation drivers. Pricing pressure stems from Chinese photovoltaic module oversupply and trade policy volatility, compressing margins most acutely for mid-tier distributors lacking direct manufacturer relationships. Recreational boating segment buyers exhibit highest price sensitivity, while offshore platform operators prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard contracting practice as Chinese photovoltaic module manufacturers compete for beacon integrator loyalty. Upstream production concentrates in China, South Korea, and Taiwan, with nickel-metal hydride and lithium iron phosphate battery chemistries drawing from specialized Japanese and South Korean cell suppliers. Single-source vulnerability in monocrystalline silicon wafer supply creates structural exposure to tariff disruption. Distribution runs through government procurement portals in East Asian markets and specialized marine equipment distributors in European and North American coastal jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
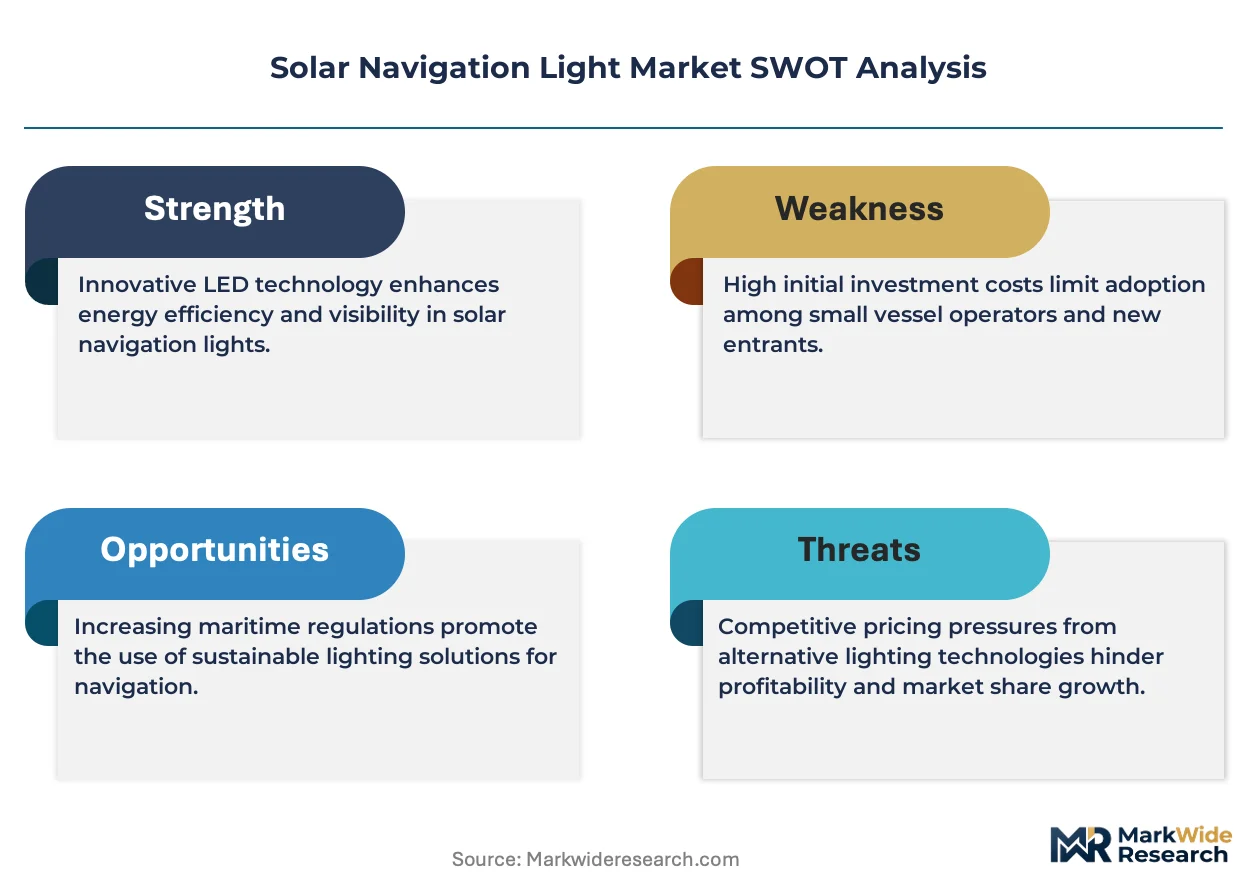
This market functions as a defensive-moat story where regulatory entrenchment protects incumbent positions. IALA certification timelines and national maritime administration pre-qualification requirements create switching costs that lock in approved vendors across multi-year replacement cycles.
For Market Incumbents: Entrench market position by accelerating IALA pre-qualification for AIS-integrated programmable beacon systems before emerging semiconductor manufacturers displace legacy electromechanical suppliers. Deepen backward integration into lithium iron phosphate battery pack assembly to capture chemistry transition margins and reduce exposure to Chinese cell supplier concentration. Prioritize predictive maintenance platform development to transform equipment sales into recurring service revenue streams. For New Entrants and Emerging Players: Indonesian archipelago unlit aids-to-navigation tenders represent the most penetrable entry point for new vendors lacking established lighthouse authority relationships. Vietnam's centralized procurement portal consolidation creates a single-channel access mechanism for harbor master specifications. Target portable rapid-deployment units for temporary construction zone marking where certification requirements remain less stringent than permanent fixed installations. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture infrastructure play because maritime safety mandates create non-discretionary replacement demand with limited demand elasticity. Acquisition target archetype: mid-cap beacon fabricators with existing IALA certification and captive photovoltaic panel sourcing relationships. Monitor Indonesian Directorate General of Sea Transportation tender award velocity as inflection indicator for archipelago-wide deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IALA Certification Acceleration | Pre-qualification speed determines access to Singapore Maritime and Port Authority fleet procurement. |
| Lithium Iron Phosphate Chemistry Transition | REACH compliance ahead of ECHA deadlines captures Scandinavian lighthouse authority replacement cycles. |
| Remote Monitoring Platform Development | Cellular and satellite telemetry integration enables predictive maintenance contract bundling. |
| Indonesian Archipelago Market Entry | Directorate General of Sea Transportation tenders for 2,000+ unlit aids to navigation. |
| Software-Defined Light Control Investment | Microcontroller-based IALA character generation displaces mechanical chopper disk inventory. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with harbor masters, lighthouse authority technical directors, offshore platform maintenance engineers, marine equipment procurement officers, and photovoltaic system integrators. Secondary validation drew from IMO SOLAS convention documentation, IALA recommendation guidelines, US Coast Guard private aids-to-navigation approval records, ECHA REACH substance restriction updates, and national maritime administration tender databases. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across the analysis window.
Calibration anchored historical shipment data to installed base replacement cycles and regulatory compliance deadlines, with segmentation modeling across product architecture, application environment, installation physics, and end-user procurement channel. CAGRs derived from regression analysis against port modernization spending, offshore platform capital expenditure, and photovoltaic module cost curves. Industry-specific forecast inputs incorporated lithium battery chemistry transition timelines and IALA guideline revision schedules.
Macroeconomic conditions sit as an overlay; deviation in container shipping volumes, crude oil prices affecting offshore platform operator capital allocation, or Chinese photovoltaic export policy would shift the trajectory. Forecasts reflect documented assumptions around regulatory compliance deadlines and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Tree Market
Renewable Energy
Rectenna Market
Renewable Energy
Portugal Renewable Energy Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
Wind Turbine Inspection Services Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Thailand Renewable Energy Market
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
Solar Watch Market
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
Turkey Renewable Energy Market