
 Tunisia Renewable Energy Market | 2026-2036
Tunisia Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Tunisia Renewable Energy Market Analytics
Utility procurement is decoupling from single-buyer dependence as industrial users and agricultural cooperatives enter direct power purchase negotiations. TotalEnergies SE leverages its integrated project development model across North African solar portfolios. STEG sustains grid interconnection monopoly while navigating independent producer integration mandates. Scatec ASA anchors its regional presence through utility-scale photovoltaic engineering expertise.
Tunisia renewable energy encompasses electricity generation systems harnessing solar irradiance, wind kinetic energy, organic biomass combustion, and hydraulic flow to produce grid-compliant power with carbon intensity below fossil baselines. Photovoltaic modules in southern installations achieve capacity factors exceeding twenty percent due to insolation levels surpassing two thousand kilowatt-hours per square meter annually. Solar power dominates capacity additions under ANME auction rounds, while off-grid installations serve remote agricultural pumping stations beyond STEG transmission reach. Wind energy competes in northern Cap Bon corridors where mean wind velocities support turbine economics. Financing services capture margin pools as development risk persists in currency-exposed project structures.
ANME administers competitive bidding rounds under renewable energy law frameworks, while STEG governs grid connection standards and purchase obligation enforcement. The country's national energy regulator oversees tariff methodologies balancing investor returns with consumer protection. Stakeholders must monitor auction design evolution and dinar hedging instrument availability as project pipelines mature.
Market Dynamics
Industrial self-generation is decoupling from STEG's single-buyer monopoly as captive solar installations proliferate under revised renewable energy law frameworks. This structural shift redistributes offtake risk and accelerates merchant power development in high-irradiance governorates.
Growth Catalysts
- ANME competitive bidding rounds:Auction mechanisms under Tunisia's renewable energy law revisions allocate development rights to lowest-cost bidders. Industrial offtakers secure long-term power purchase agreements at tariffs below grid parity.
- Southern governorate solar irradiance:Tataouine and Kébili installations achieve capacity factors exceeding twenty percent due to annual insolation surpassing two thousand kilowatt-hours per square meter. Developers concentrate pipelines in these zones.
- STEG grid-access reforms:Interconnection standard revisions reduce technical approval timelines for independent producers. Grid connection certainty improves project bankability for utility-scale photovoltaic arrays.
Market Restraints
- Dinar currency exposure:Euro-denominated equipment procurement against dinar-denominated revenue streams creates foreign exchange mismatch. Project finance structures lack depth in local hedging instruments.
- Transmission infrastructure gaps:STEG's southern network reinforcement lags behind generation pipeline concentration. Curtailment risk rises in Tataouine zones without parallel substation upgrades.
- Biomass feedstock scarcity:Organic waste collection systems remain underdeveloped outside coastal urban corridors. Agricultural residue supply chains fail to achieve scale for combustion plant economics.
Strategic Opportunities
- Agricultural cooperative direct contracting:Remote pumping stations beyond STEG transmission reach represent unserved demand. Off-grid photovoltaic installations with battery storage displace diesel generator dependence.
- Green hydrogen pilot zones:ANME incentive schemes target electrolyzer deployment using curtailed solar output. Industrial off-takers in chemical and fertilizer sectors anchor offtake demand.
- Cap Bon wind corridor expansion:Northern governorate mean wind velocities support turbine economics at sites unconnected to southern solar concentration. Geographic diversification reduces portfolio irradiance risk.
Industry Challenges
- EPC contractor scarcity:Utility-scale photovoltaic engineering expertise concentrates among a limited pool of international developers. Local construction workforce lacks specialized electrical installation certification.
- Land tenure complexity:State-owned desert parcels require multi-agency coordination for solar lease conversion. Administrative delays extend pre-construction timelines beyond financing commitment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunisia Renewable Energy Market |
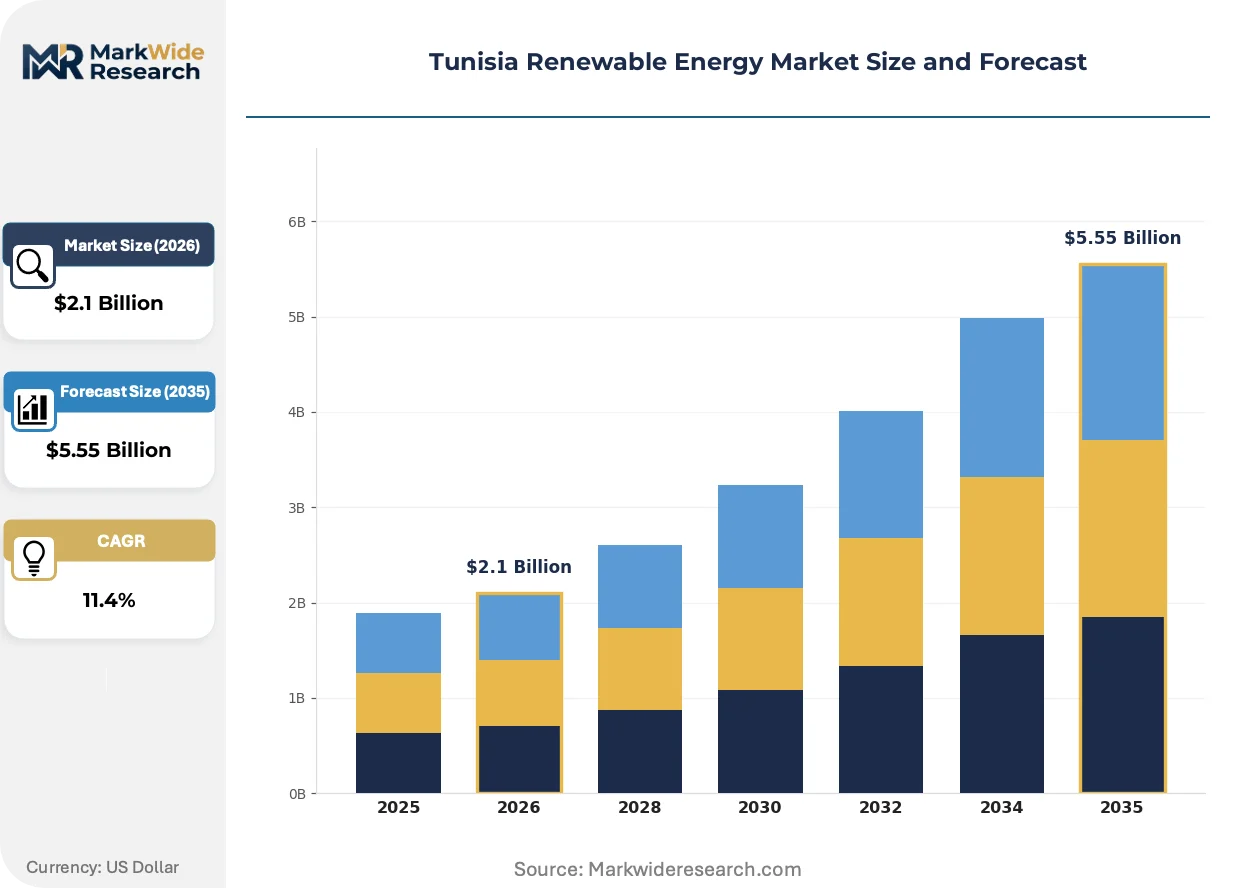
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar Power, Wind Energy, Biomass, Hydropower End User: Residential, Commercial, Industrial, Government Installation Type: On-Grid, Off-Grid, Hybrid, Community Service Type: Consulting, Installation, Maintenance, Financing |
| Companies Covered | TotalEnergies SE, Voltalia, Société Tunisienne de l'Électricité et du Gaz (STEG), General Electric Company, Qair, Eni SpA, Nur Energie Ltd, Ansaldo Energia SpA, Scatec ASA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunisia Renewable Energy Market Evolving Landscape
Technology convergence and procurement model evolution are compressing development cycles while redistributing value capture across the project stack. These shifts alter competitive positioning for developers and equipment suppliers alike.
Bifacial photovoltaic modules are overtaking monofacial designs in utility-scale tenders. These dual-sided panels capture reflected irradiance from desert surfaces, boosting yield in Tataouine installations by fifteen percent. STEG's revised grid codes now explicitly recognize bifacial output profiles in interconnection studies.
ANME's renewable energy law revisions introduced technology-neutral auction rounds that displace previous technology-specific quotas. This regulatory shift forces wind and solar developers to compete directly on levelized cost metrics. Northern Cap Bon wind projects now secure contracts against southern photovoltaic arrays in the same bidding window.
Industrial offtakers are abandoning traditional STEG wheeling arrangements for direct bilateral contracts with independent producers. This procurement evolution concentrates credit risk assessment on single-counterparty industrial balance sheets rather than utility payment guarantees. Cement and phosphate processing facilities in Gabès and Gafsa governorates pioneered this structure.
Tunisia Renewable Energy Market Segmentation
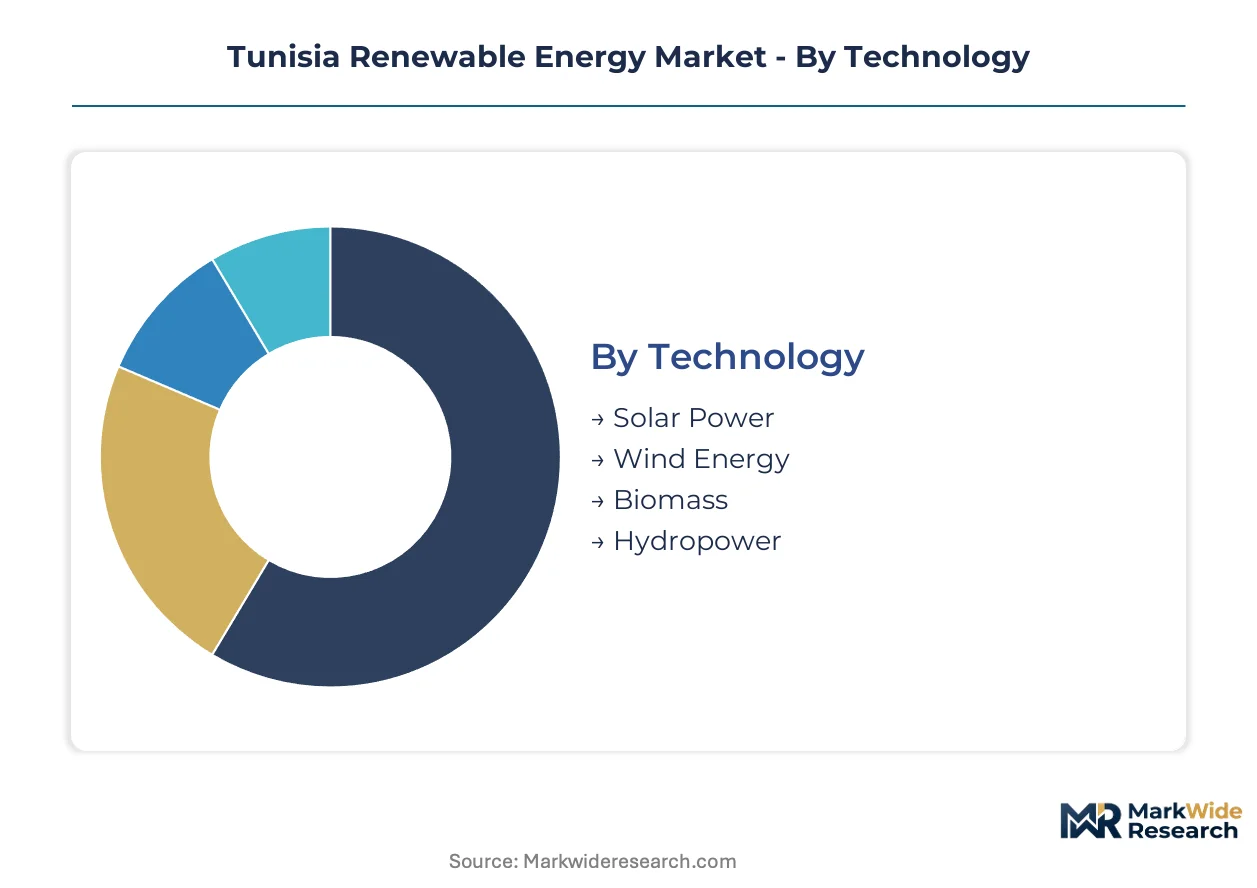
Segmentation in Tunisia's renewable energy market reveals how technology choices, customer profiles, and delivery models interact with ANME incentive structures and STEG grid-access reforms. Each dimension carries distinct financing requirements and regulatory compliance pathways that shape project economics.
Technology:
Solar power functions as standalone utility-scale arrays requiring dedicated land parcels and grid interconnection, while wind and biomass technologies embed into existing industrial or agricultural operations with lower infrastructure intensity.
- Solar Power:Photovoltaic modules capture direct and reflected irradiance across Tataouine and Kébili governorates. Capacity factors exceed twenty percent where annual insolation surpasses two thousand kilowatt-hours per square meter. Industrial offtakers in phosphate and cement sectors anchor procurement demand under revised renewable energy law frameworks.
- Wind Energy:Horizontal-axis turbines exploit mean wind velocities in northern Cap Bon corridors. Grid connection in these zones avoids transmission bottlenecks constraining southern solar concentration. ANME's technology-neutral auctions now force direct cost competition with photovoltaic arrays.
- Biomass:Organic residue combustion plants cluster near coastal urban waste collection systems. Agricultural feedstock supply chains remain underdeveloped outside Sahel governorates.
- Hydropower:Run-of-river installations exploit existing irrigation infrastructure in northern watersheds. STEG integration mandates limit independent producer development in this category.
Volume placements concentrate in Solar Power; the faster expansion belongs to Wind Energy as Cap Bon sites secure auction contracts against southern photovoltaic competition.
End User:
Cost tier stratification separates residential rooftop systems with high per-watt soft costs from industrial captive installations achieving scale economies through direct bilateral contracting.
- Industrial:Cement, phosphate processing, and chemical facilities deploy multi-megawatt captive arrays under power purchase agreements bypassing STEG wheeling tariffs. Credit assessment concentrates on single-counterparty balance sheets rather than utility payment guarantees.
- Commercial:Retail and hospitality operators in Tunis and Sfax metropolitan zones adopt rooftop photovoltaic with net metering arrangements. ANME simplified permitting reduced approval timelines for sub-one-megawatt commercial installations.
- Residential:Single-family rooftop systems rely on STEG grid-tie programs with limited financing instrument availability. Dinar-denominated loan products constrain uptake in middle-income segments.
- Government:Public building mandates under national energy efficiency directives drive municipal solar procurement. Budget execution delays persist across governorate-level implementation.
Revenue concentration sits with Industrial offtakers; Commercial installations are climbing the fastest as simplified permitting unlocks metropolitan demand.
Installation Type:
Geography determines feasibility as on-grid systems require STEG interconnection availability while off-grid configurations serve transmission-deficient zones.
- On-Grid:Utility-scale photovoltaic arrays connect to STEG transmission infrastructure under standardized technical codes. Southern governorate concentration strains substation capacity without parallel network reinforcement.
- Off-Grid:Standalone battery-coupled systems serve agricultural pumping stations beyond transmission reach. Diesel generator displacement drives demand in remote Kébili and Tozeur agricultural cooperatives.
- Hybrid:Grid-tied systems with islanding capability provide industrial facilities with backup power during STEG outage events. Premium equipment costs limit adoption to large commercial and industrial segments.
- Community:Shared solar installations aggregate residential subscribers under collective metering arrangements. Regulatory frameworks for shared ownership remain under ANME consultation.
Project pipelines concentrate in On-Grid installations; Off-Grid deployments are gaining share fastest as agricultural cooperative financing instruments mature.
Service Type:
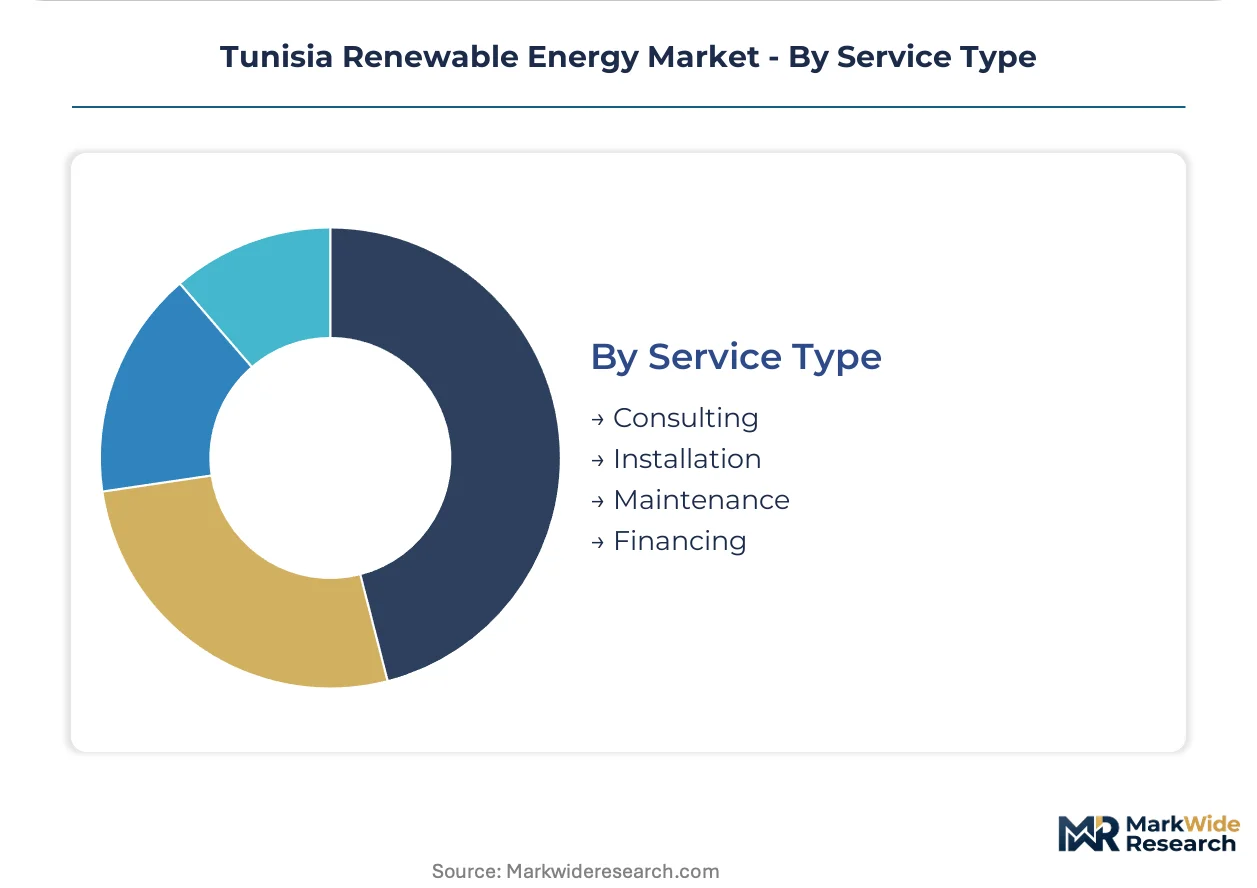
Margin structure varies across the project lifecycle with development-phase consulting capturing risk premiums and operational-phase maintenance generating recurring revenue streams.
- Installation:EPC contractors execute civil works, electrical installation, and commissioning for utility-scale arrays. International developer concentration limits local workforce participation without specialized certification programs.
- Financing:Project finance structures address currency mismatch between euro-denominated equipment and dinar-denominated revenue. Hedging instrument scarcity elevates development risk pricing.
- Consulting:Technical advisory services support site selection, resource assessment, and permitting navigation. ANME auction preparation drives demand spikes preceding bidding round deadlines.
- Maintenance:Operations and maintenance contracts cover module cleaning, inverter replacement, and performance monitoring. Long-term service agreements accompany utility-scale project financings.
Value capture concentrates in Installation services; Financing advisory is expanding most quickly as project pipelines mature and currency risk management demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in southern governorates where solar irradiance peaks, while northern regions exploit wind corridors. Tataouine and Kébili anchor utility-scale development. Policy reforms redistribute project pipelines across sub-national zones.
Tataouine Governorate
Phosphate processing facilities and cement plants anchor industrial offtake demand. ANME competitive bidding rounds allocate development rights to lowest-cost bidders in this zone. TotalEnergies SE leverages integrated project development models across installations achieving capacity factors exceeding twenty percent.
Kébili Governorate
Agricultural cooperatives drive off-grid photovoltaic demand for remote pumping stations. STEG grid-access reforms reduce technical approval timelines for independent producers. Diesel generator displacement accelerates as battery-coupled systems achieve cost parity with fossil alternatives.
Gabès Governorate
Chemical and fertilizer processing facilities pioneer direct bilateral power purchase agreements. The national energy regulator oversees tariff methodologies balancing investor returns with consumer protection. Industrial self-generation decouples from STEG's single-buyer monopoly through captive solar installations.
Gafsa Governorate
Phosphate mining operations anchor multi-megawatt captive array deployment. ANME incentive schemes target electrolyzer deployment using curtailed solar output for green hydrogen pilot zones. Land tenure complexity extends pre-construction timelines across state-owned desert parcels.
Cap Bon Region
Mean wind velocities in northern corridors support turbine economics unconnected to southern solar concentration. ANME's technology-neutral auctions force wind developers to compete directly against photovoltaic arrays. Geographic diversification reduces portfolio irradiance risk for utility-scale developers.
Tunisia Renewable Energy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue merchant power development and agricultural off-grid segments. The vendor base concentrates among integrated European energy majors and specialized North African developers. Three archetypes dominate: utility-scale engineering specialists, captive industrial installers, and hybrid technology-neutral bidders. Competitive moves center on auction preparation capabilities and dinar hedging instrument structuring.
Within the integrated energy major tier, TotalEnergies SE and Eni SpA exemplify project development models spanning North African solar portfolios. Scatec ASA occupies a position among utility-scale photovoltaic engineering specialists. These entities anchor competitive dynamics through auction round participation and bilateral industrial contracting.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Voltalia |
| Société Tunisienne de l'Électricité et du Gaz (STEG) |
| General Electric Company |
| Qair |
| Eni SpA |
| Nur Energie Ltd |
| Ansaldo Energia SpA |
| Scatec ASA |
| Others |
Value Network & Pricing Analysis
Polysilicon spot price indices from Bloomberg New Energy Finance cascade through Tunisia's renewable energy supply chain, compressing module procurement costs for utility-scale developers while elevating margin pressure on EPC contractors locked into fixed-price construction contracts.
Pricing Analysis
Volume placements concentrate in utility-scale arrays where thin development margins compete on levelized cost metrics, while premium pricing attaches to hybrid installations with islanding capability serving industrial offtakers. Price differentiation hinges on certification tier—projects securing ANME auction contracts command standard tariffs, whereas direct bilateral agreements with phosphate and cement facilities capture premium rates reflecting credit risk transfer from STEG guarantees to single-counterparty balance sheets. Cost compression in module supply is intensifying as Chinese manufacturers expand export capacity, though EPC scarcity in North Africa limits full pass-through to developers. Agricultural cooperatives in Kébili exhibit highest price sensitivity, while chemical processors in Gabès demonstrate lowest sensitivity due to diesel displacement economics.
Supply Chain Analysis
Direct-to-utility procurement channels handle hyperscale photovoltaic demand from ANME auction winners, while specialized EPC contractors serve industrial captive installations through bilateral contracting relationships. Module supply concentrates in China, with inverter sourcing split between Chinese and European manufacturers, and structural steel components drawn from Turkish mills. Raw material dependencies center on polysilicon feedstock, aluminum framing, and high-purity copper conductors. Single-source vulnerability persists in bifacial glass supply where Chinese producers dominate thin-film coating capacity. Distribution runs through STEG-governed interconnection queues for on-grid projects, while off-grid deployments bypass utility infrastructure entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
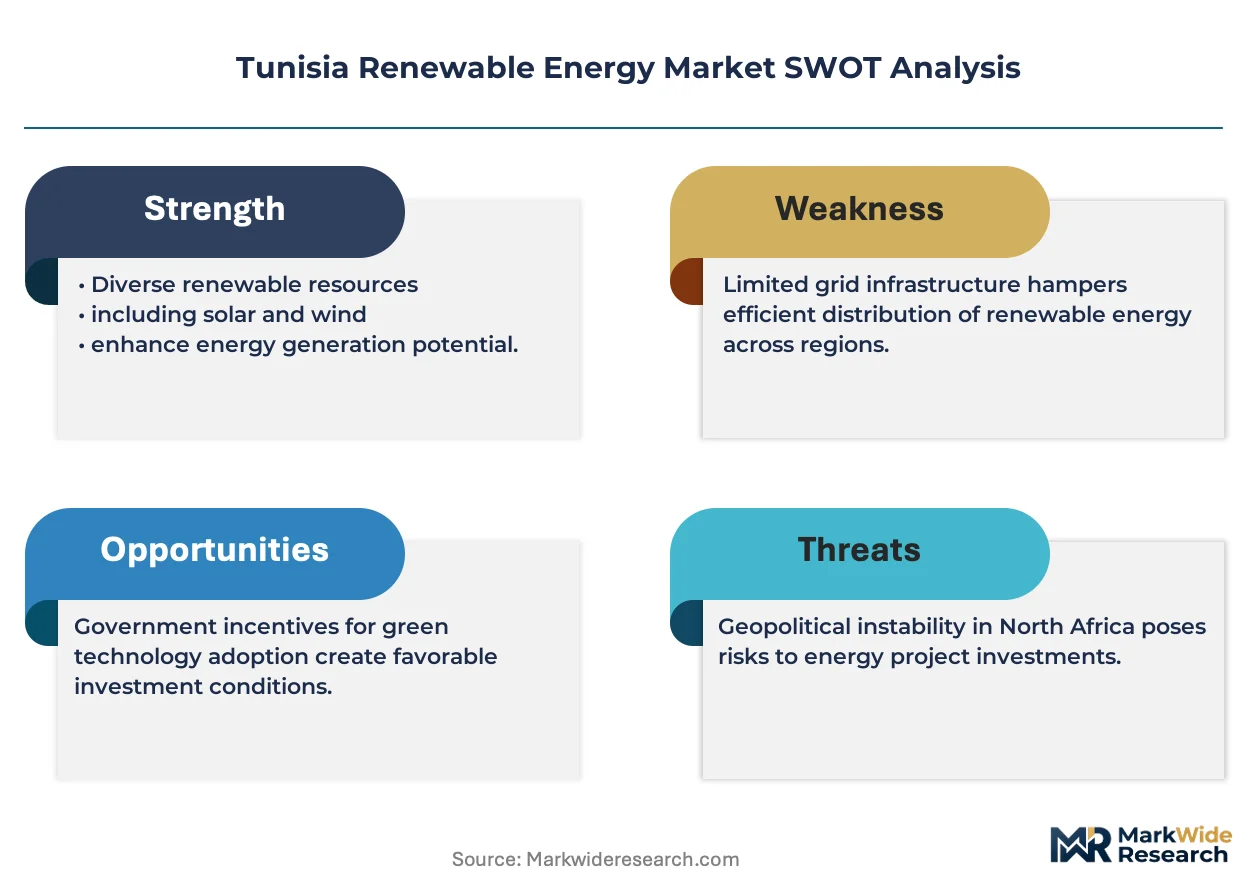
Tunisia's renewable energy market functions as a cost-of-compliance story where ANME's renewable energy law revisions erect regulatory moats favoring developers with established auction preparation capabilities and dinar hedging instrument access.
For Market Incumbents: Cement auction round dominance by deepening technical advisory capabilities for ANME bidding preparation and securing long-term EPC partnerships with certified electrical installation workforces. Threat concentration sits with emerging European energy majors pursuing merchant power development in Tataouine. Vertical integration into module supply chains mitigates currency mismatch exposure. For New Entrants and Emerging Players: Begin with agricultural cooperative off-grid deployments in Kébili and Tozeur where STEG transmission gaps create unserved demand white space. Green hydrogen pilot zones in Gafsa offer second-mover entry points as electrolyzer supply chains mature. Direct contracting with phosphate processing facilities bypasses auction competition entirely. For Investors and Strategic Acquirers: Distressed-cycle entries favor utility-scale photovoltaic engineering specialists with established North African presence as EPC contractor scarcity elevates acquisition premiums. Long-term viability hinges on regulatory continuity across multiple ANME auction rounds. Signal to watch: STEG grid-access reform implementation velocity in southern governorates.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | Direct bilateral contracts with Gabès chemical facilities displace STEG wheeling dependence. |
| Capacity Buildout | Tataouine utility-scale arrays exploit capacity factors exceeding twenty percent. |
| Technology Licensing | Bifacial module deployment rights transfer yield advantages to southern installations. |
| Backward Integration | In-house electrical installation certification reduces EPC contractor scarcity exposure. |
| Green Certification Program | ANME auction qualification requires compliance with revised renewable energy law frameworks. |
Research Methodology
Independent corroboration across ANME auction documentation, STEG grid interconnection filings, and EPC contractor performance records underwrites the qualitative findings. Primary interviews engaged utility planning officers at STEG, IPP project developers active in Tataouine, and procurement leads at phosphate processing facilities. Secondary validation drew from IEA renewable energy investment databases, World Bank project finance disclosures, and Tunisian customs import records for photovoltaic equipment. Bottom-up project pipeline aggregation triangulates against top-down market sizing from national energy regulator capacity forecasts.
Rate-of-change decomposition separates volume growth from tariff evolution across the projection horizon. Segmentation dimensions modeled include technology type, end-user category, installation configuration, and service delivery model, with geographic irradiance differentials as an energy-specific overlay. CAGRs derive from compound growth path analysis rather than linear extrapolation. Forecast inputs incorporate ANME auction round frequency assumptions and STEG transmission reinforcement timelines.
Underlying measurement precision varies by segment; utility-scale on-grid installations carry tighter precision than off-grid agricultural deployments due to documentation density. Forecasts reflect assumptions regarding regulatory continuity, currency hedging instrument availability, and transmission infrastructure execution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Southern Africa Renewable Energy Market
Renewable Energy
South America Renewable Energy Market
Renewable Energy
Solar Highway Market
Renewable Energy
Point Absorber Market
Renewable Energy
Mexico Renewable Energy Market
Renewable Energy
Solar Cooker Market
Renewable Energy
Europe IoT in Renewable Energy Market
Renewable Energy
South Africa Renewable Energy Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Europe Biomethane Market
Renewable Energy
Europe Solar Tracker Market
Renewable Energy
Philippines Power Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
Southeast Asia Renewable Energy Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
China Wind Power Market