
 Naphtha Market | 2026-2036
Naphtha Market Size, Share, and Industry Trends Forecast 2026-2036
Naphtha Market Analysis
The EU Green Deal is rebalancing naphtha trade flows by embedding carbon border adjustments into feedstock procurement decisions. Saudi Aramco leverages its upstream integration to sustain cost-advantaged exports into European crackers. Shell plc competes through its Singapore and Rotterdam trading hubs, while Indian Oil Corporation Limited anchors domestic supply for its Paradip and Panipat petrochemical complexes.
Naphtha denotes a volatile, liquid hydrocarbon mixture typically boiling between 30°C and 200°C, composed primarily of C5-C12 aliphatic and aromatic compounds produced through crude oil distillation or natural gas liquids fractionation. Its principal purpose centers on steam cracking to yield ethylene, propylene, and butadiene for polymer production. Petrochemical naphtha dominates volume flows as crackers prioritize light, paraffinic feedstock for higher olefin yields. Chemical manufacturing applications absorb the largest value share, though fuel blending retains structural importance in markets with limited ethylene demand. Heavy naphtha and reformate segments serve catalytic reforming units producing high-octane gasoline components and aromatics.
The EPA enforces benzene content limits under the Clean Air Act that constrain naphtha composition in U.S. fuel pools, while REACH and the EU F-Gas Regulation shape feedstock certification requirements for European petrochemical buyers. China's MEE implements dual carbon goals that tighten refinery emission standards and naphtha import quality protocols. Stakeholders must monitor how carbon border mechanisms and national decarbonization timelines reshape feedstock sourcing economics and cracker investment decisions.
Market Dynamics
Refinery-petrochemical integration is compressing merchant naphtha availability as integrated operators divert light distillates to captive crackers, tightening spot market liquidity and amplifying price volatility for independent buyers.
Growth Catalysts
- Polyethylene capacity expansion:Petrochemical complexes in China and India are commissioning new steam crackers that absorb naphtha feedstock at scale, pulling volumes from regional refining hubs.
- EU Green Deal carbon border adjustments:European importers now face embedded carbon accounting for naphtha shipments, redirecting procurement toward Middle Eastern suppliers with lower upstream intensity.
- Light feedstock preference:Paraffinic naphtha yields superior ethylene output compared to heavier alternatives, sustaining demand for specific gravity cuts in cracker optimization.
Market Restraints
- Crude price volatility:Naphtha pricing tracks Brent and Dubai benchmarks with minimal lag, exposing crackers to margin compression when oil spikes.
- Middle East supply concentration:Saudi Arabia, Qatar, and Kuwait control substantial export volumes, creating chokepoint risk for Asian and European buyers.
- Ethane substitution:North American crackers with access to cheap shale ethane are displacing naphtha feedstock, shrinking the addressable market in that geography.
Strategic Opportunities
- India petrochemical buildout:Paradip and Panipat complexes are expanding cracking capacity, creating captive demand that reduces import dependency.
- Circular feedstock certification:Cracker operators in Germany and the Netherlands are piloting mass-balance accounting for recycled naphtha to meet EU packaging mandates.
- Digital trading platforms:Singapore and Rotterdam hubs are adopting blockchain-based cargo tracking, compressing settlement timelines and reducing documentary fraud.
Industry Challenges
- Carbon accounting expertise:Procurement teams lack personnel trained in lifecycle assessment methodologies required for EU CBAM declarations.
- Cracker feedstock flexibility:Retrofitting units to process mixed feeds demands capital expenditure that many operators deferred during low-margin periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naphtha Market |
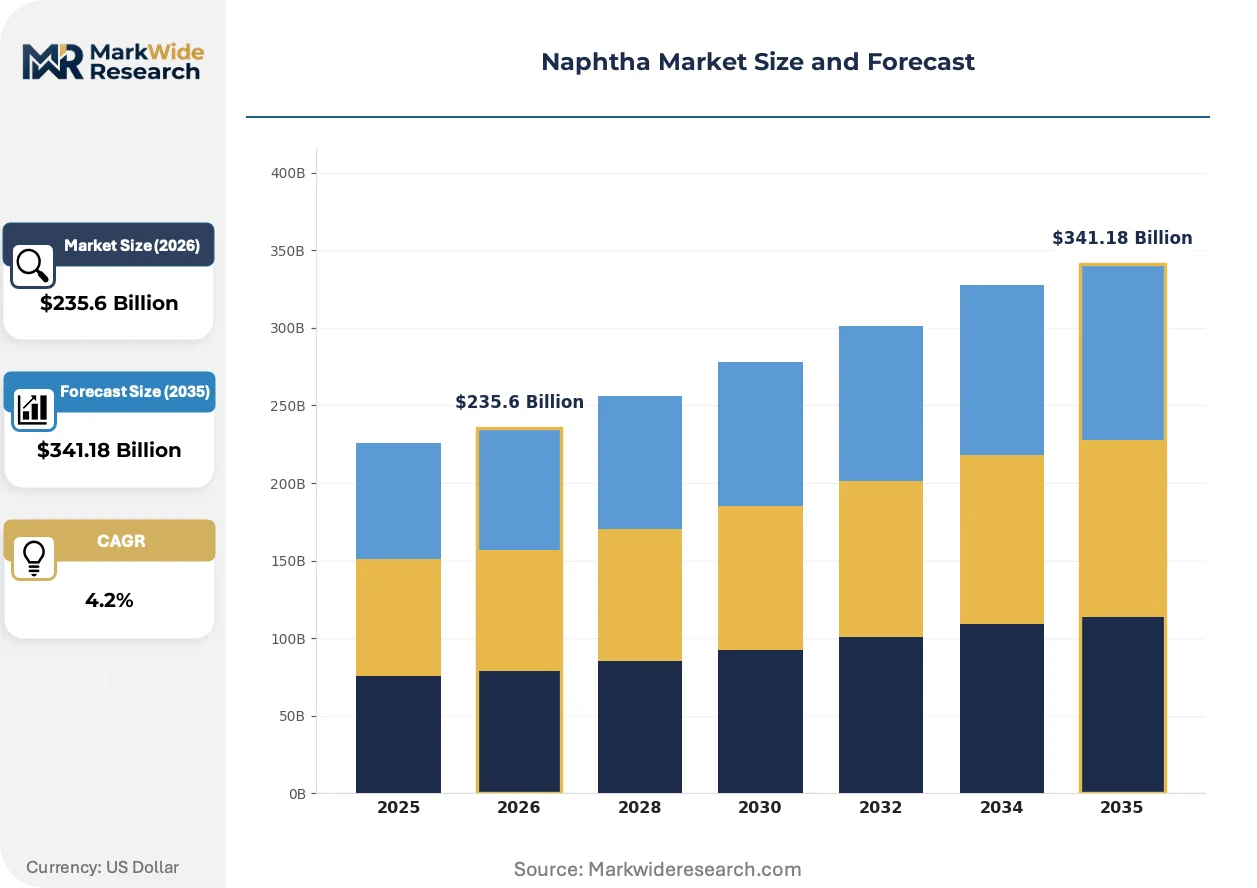
| Market Size in 2026 | $235.6 Billion |
| Market Size in 2035 | $341.18 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Petrochemical Naphtha, Light Naphtha, Heavy Naphtha, Reformate Application: Chemical Manufacturing, Fuel, Solvent, Feedstock Distribution Channel: Direct Sales, Distributors, Wholesalers, Retailers End User: Refineries, Petrochemical Industry, Automotive, Aerospace |
| Companies Covered | China Petroleum & Chemical Corporation, BP p.l.c., Saudi Aramco, PetroChina Company Limited, Chevron Corporation, Shell plc, Exxon Mobil Corporation, Indian Oil Corporation Limited, TotalEnergies SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naphtha Market Emerging Trajectories
Advanced analytics and molecular characterization tools are reshaping how naphtha is graded, traded, and consumed, shifting value capture toward laboratories and away from traditional assay-based contracting.
High-resolution gas chromatography combined with machine learning classification is rewriting how refiners and traders assess naphtha quality. Major crackers in South Korea and Taiwan now require detailed PIONA analysis for every cargo, compressing the premium for unspecified parcels. This technology is enabling spot price discovery that reflects actual olefin yield potential rather than broad boiling-range categories.
REACH substance registration requirements are tightening disclosure obligations for naphtha importers into the European Economic Area. ECHA's updated guidance on complex substance identification demands compositional data that many Middle Eastern exporters previously omitted. Petrochemical buyers in Antwerp and Rotterdam are responding by pre-qualifying suppliers through extended audit programs.
Long-term offtake contracting is fragmenting as integrated refiners prefer shorter tenors with price reopeners. Chinese state-owned enterprises, historically the anchor buyers for term volumes, are now splitting procurement across multiple suppliers and layering in spot purchases. This behavioral shift is most pronounced in Dalian and Ningbo, where inventory carrying costs have fallen and terminal capacity expanded.
Naphtha Market Segmentation
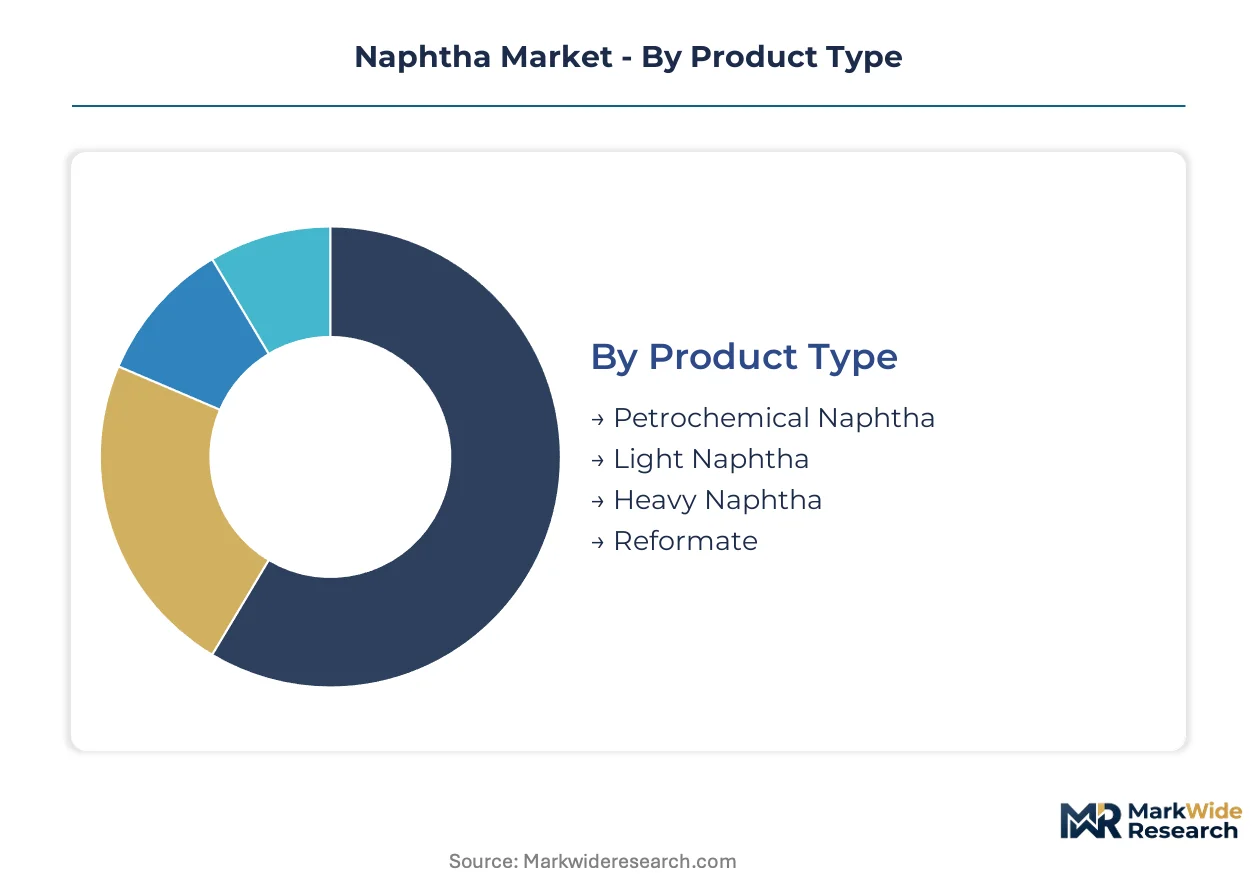
Naphtha segmentation tracks how molecular weight distribution and paraffinic content determine cracker economics across steam cracking, catalytic reforming, and fuel blending applications. Buyers select grades based on olefin yield potential, sulfur specifications, and carbon intensity credentials required by destination markets.
Product Type:
Cost tier separates integrated refiners from merchant buyers, with premium paraffinic cuts commanding yield-based premiums in Asian cracking hubs.
- Petrochemical Naphtha:Light, paraffinic distillate optimized for steam cracking with high ethylene and propylene yields. Demand concentrates in South Korea and Taiwan where crackers specify PIONA analysis for every cargo, with EU carbon border adjustments now embedding upstream intensity into procurement decisions.
- Light Naphtha:C5-C7 fraction with superior olefin conversion rates compared to heavier cuts. Chinese state-owned enterprises at Dalian and Ningbo terminals are splitting procurement across multiple suppliers and layering spot purchases, reducing long-term offtake tenors.
- Heavy Naphtha:C8-C12 range serving catalytic reforming units for high-octane gasoline and aromatics production.
- Reformate:Catalytic reforming output rich in benzene, toluene, and xylene for gasoline blending and chemical feedstock.
Volume sits with petrochemical naphtha; growth tilts toward light naphtha as crackers optimize for maximum olefin output.
Application:
Application splits reflect divergent margin structures between commodity polymer chains and regulated fuel pools.
- Chemical Manufacturing:Steam cracking to ethylene, propylene, and butadiene for polyethylene and polypropylene production. Paradip and Panipat complexes in India are expanding cracking capacity, creating captive demand that reduces import dependency for merchant volumes.
- Fuel:Gasoline blending component subject to benzene limits under EPA Clean Air Act in the United States and fuel quality directives in Europe.
- Solvent:Industrial degreasing and extraction applications requiring controlled aromatic content.
- Feedstock:General refinery and petrochemical input category covering non-specified chemical synthesis routes.
Chemical manufacturing absorbs the largest value share; fuel blending retains structural importance in markets with limited ethylene demand.
Distribution Channel:
Channel selection tracks buyer scale and credit access, with integrated refiners bypassing intermediaries entirely.
- Direct Sales:Term contracts between integrated refiners and petrochemical complexes. Saudi Aramco leverages upstream integration to sustain cost-advantaged exports into European crackers through direct long-term agreements.
- Distributors:Intermediate traders managing logistics and credit for mid-sized buyers. Shell plc competes through Singapore and Rotterdam trading hubs that aggregate volumes for regional distribution.
- Wholesalers:Bulk handlers serving fuel blending terminals and smaller chemical processors.
- Retailers:Limited channel for specialty solvent grades and small-volume industrial applications.
Direct sales dominate volume flows; distributors are gaining share fastest as procurement fragmentation increases spot market participation.
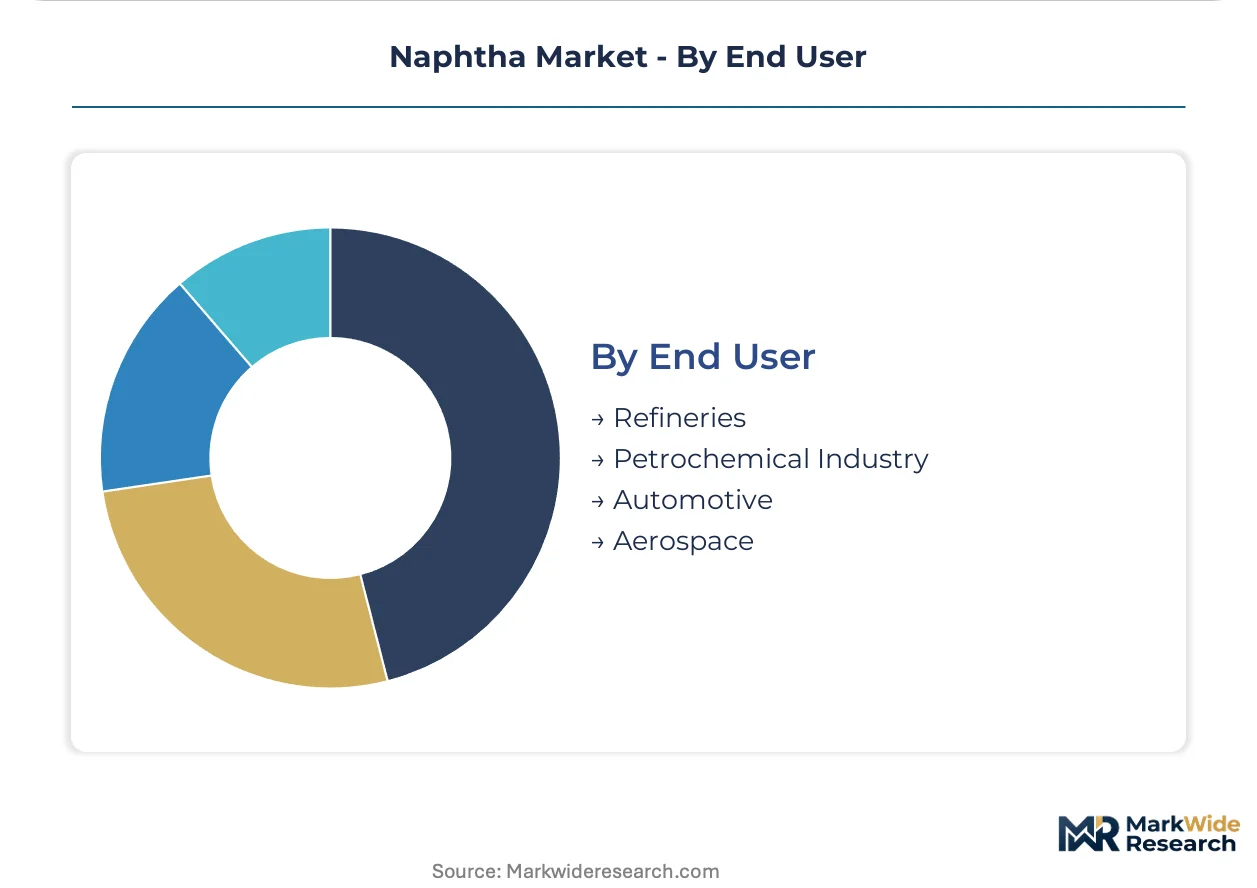
End User:
End-user concentration follows refinery-petrochemical integration depth, with captive consumption displacing merchant spot purchases.
- Petrochemical Industry:Steam crackers and aromatics extraction units consuming naphtha as primary feedstock. Indian Oil Corporation Limited anchors domestic supply for its Paradip and Panipat complexes, while Chinese crackers absorb regional refining output.
- Refineries:Internal circulation for catalytic reforming and gasoline pool optimization.
- Automotive:Indirect consumption through reformate blending into finished gasoline.
- Aerospace:Minimal direct consumption; limited specialty solvent applications.
Petrochemical industry holds the volume base; refineries are expanding fastest as integration deepens and captive cracking capacity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's petrochemical corridor channels European naphtha flows through the continent's largest refining and trading hub. The city's integrated terminals and crackers process volumes from Middle Eastern exporters adjusting to EU carbon border requirements.
China
Dalian and Ningbo terminals absorb expanding steam cracker capacity from state-owned enterprises splitting procurement across multiple suppliers. MEE dual carbon goals tighten refinery emission standards and import quality protocols for feedstock shipments. Yangtze River Delta crackers specify PIONA analysis for every cargo, compressing premiums for unspecified parcels.
India
Paradip and Panipat complexes anchor domestic supply expansion reducing merchant import dependency for petrochemical feedstock. PLI scheme incentives support refinery-petrochemical integration deepening captive consumption patterns. Gujarat's refining cluster diverts light distillates to integrated crackers, tightening spot market liquidity for independent buyers.
United States
Gulf Coast crackers with shale ethane access displace naphtha feedstock, shrinking addressable market volume in North American steam cracking. EPA Clean Air Act benzene limits constrain naphtha composition in domestic fuel pools. Texas refining complexes optimize gasoline pool blending while petrochemical operators assess mixed-feed retrofit economics.
South Korea
Yeosu and Ulsan industrial zones specify detailed molecular characterization for every naphtha cargo, enabling yield-based spot price discovery. MFDS chemical registration requirements align with REACH-equivalent disclosure standards for import certification. Korean crackers lead adoption of machine learning classification for PIONA analysis, shifting value capture toward laboratory services.
Germany
Antwerp-Rotterdam-Rhine-Ruhr corridor faces embedded carbon accounting requirements redirecting procurement toward lower upstream intensity suppliers. ECHA REACH substance registration demands compositional data previously omitted by Middle Eastern exporters. Ludwigshafen and Cologne crackers pilot mass-balance accounting for recycled naphtha to meet EU packaging mandates.
Naphtha Market Vendor Landscape
Premium-margin players sit above commodity-margin players across upstream integration depth and carbon intensity certification. State-controlled national oil companies leverage captive crude access to sustain cost-advantaged export positions into European and Asian cracking hubs. Integrated refining-petrochemical conglomerates, independent merchant traders, and specialized regional distributors constitute three strategic archetypes. Capacity expansion in Middle Eastern export terminals and backward integration into captive cracking capacity represent dominant competitive moves reshaping supply availability.
Among integrated state-controlled suppliers, Saudi Aramco anchors the low-carbon-intensity export tier into European crackers adjusting to EU Green Deal procurement standards. Shell plc occupies a position across Singapore and Rotterdam trading hubs aggregating volumes for regional distribution. Indian Oil Corporation Limited exemplifies domestic supply anchoring through refinery-petrochemical integration at Paradip and Panipat complexes.
| Leading Market Players |
|---|
| China Petroleum & Chemical Corporation |
| BP p.l.c. |
| Saudi Aramco |
| PetroChina Company Limited |
| Chevron Corporation |
| Shell plc |
| Exxon Mobil Corporation |
| Indian Oil Corporation Limited |
| TotalEnergies SE |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed national oil companies anchor naphtha supply discipline through upstream integration that insulates export pricing from spot volatility. Saudi Aramco, QatarEnergy, and Kuwait Petroleum Corporation leverage captive crude access to sustain term-contract premiums while Middle Eastern export terminals compress delivery differentials for Asian and European crackers navigating EU carbon border adjustments.
Pricing Analysis
Yield-based pricing tied to PIONA analysis anchors naphtha valuation as South Korean and Taiwanese crackers specify detailed molecular characterization for every cargo. Pricing stratifies across premium paraffinic grades, standard unspecified parcels, and heavy reformate cuts based on olefin conversion potential and carbon intensity certification. Cost compression in standard-grade spot markets is intensifying because Chinese state-owned enterprises are fragmenting procurement across multiple suppliers and layering spot purchases. Independent merchant buyers exhibit highest price sensitivity due to margin exposure during crude spikes, while integrated refiners with captive cracking capacity demonstrate lowest sensitivity through internal transfer pricing.
Supply Chain Analysis
Dual-sourcing requirements from European crackers facing EU Green Deal carbon accounting are redirecting procurement toward Middle Eastern suppliers with pre-qualified lower upstream intensity. Supply concentrates in Saudi Arabia, Qatar, and Kuwait as primary export hubs feeding Asian cracking centers, while the United States draws from domestic Gulf Coast refining output. Raw material dependencies rest on Brent and Dubai crude benchmarks, natural gas liquids fractionation yields, and catalytic reforming unit throughput. Single-source vulnerability emerges from Middle Eastern export concentration creating chokepoint risk during regional supply disruptions. Distribution runs through Singapore and Rotterdam trading hubs that aggregate volumes for regional redistribution to independent buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
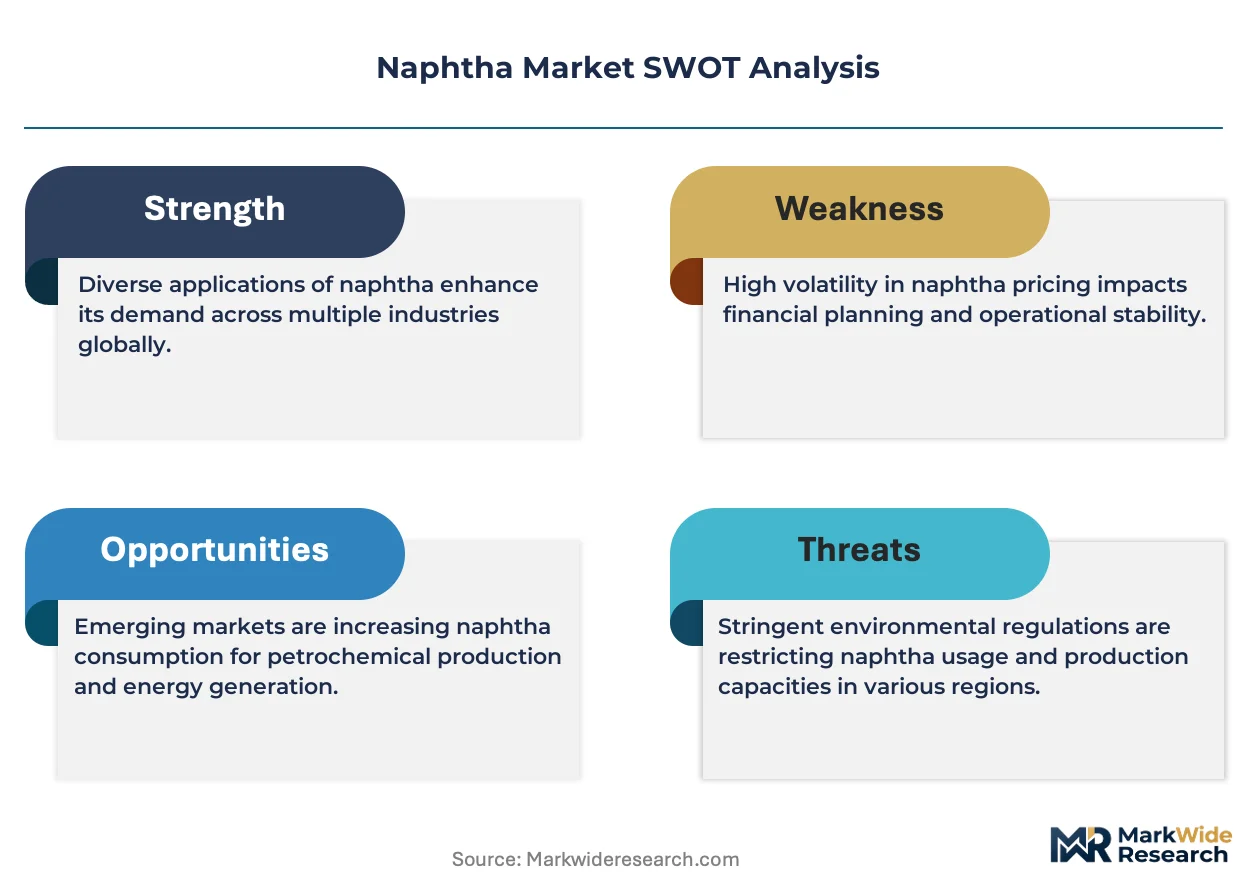
The naphtha market reads as a cost-of-compliance story where EU REACH substance registration requirements and carbon border adjustment mechanisms erect barrier-to-entry moats for players with pre-qualified supply chains and lifecycle assessment capabilities.
For Market Incumbents: Cement feedstock security through backward integration into captive cracking capacity at Paradip, Panipat, or Yangtze River Delta complexes. Lock in long-term offtake agreements with Middle Eastern exporters holding verified low-carbon-intensity credentials before EU CBAM phase-in tightens procurement standards. Shale ethane substitution in North American crackers represents the priority threat requiring mixed-feed retrofit evaluation.
For New Entrants and Emerging Players: Mid-sized European chemical processors lacking carbon accounting expertise present an underserved buyer archetype for certified naphtha brokerage services. White-space targets include circular feedstock certification consulting for German and Dutch crackers piloting mass-balance accounting, and digital cargo tracking platforms for Singapore-Rotterdam hub transactions. The most penetrable entry point sits with blockchain-based settlement services compressing documentary timelines for spot market participants.
For Investors and Strategic Acquirers: Indian Oil Corporation Limited's refinery-petrochemical integration model is the leading indicator that state-controlled upstream-downstream convergence will dominate competitive positioning across emerging Asian markets. Long-term viability over the next decade hinges on carbon intensity certification capabilities and regional hub access. Acquisition targets should prioritize integrated operators with pre-qualified EU supply chains. The signal to monitor is ECHA guidance updates on complex substance identification demanding compositional data disclosure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cracking | Indian Oil Corporation Limited's Paradip and Panipat complexes reduce merchant import dependency through refinery-petrochemical convergence. |
| Carbon Intensity Certification Investment | Saudi Aramco leverages upstream integration to sustain cost-advantaged exports into European crackers adjusting to EU Green Deal standards. |
| Digital Trading Platform Deployment | Singapore and Rotterdam hubs adopt blockchain-based cargo tracking compressing settlement timelines and reducing documentary fraud exposure. |
| Circular Feedstock Pilot Programs | Ludwigshafen and Cologne crackers pilot mass-balance accounting for recycled naphtha to meet EU packaging mandates. |
| Dual-Sourcing Supplier Qualification | Antwerp and Rotterdam petrochemical buyers pre-qualify Middle Eastern suppliers through extended audit programs responding to REACH disclosure obligations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this naphtha market assessment. Primary interviews with refinery operations managers, petrochemical procurement leads, steam cracker technical directors, and trading hub logistics coordinators were cross-referenced against ECHA REACH guidance documents, EPA Clean Air Act enforcement records, and China MEE emission standard protocols. Bottom-up capacity installation tracking and top-down regional demand estimation were reconciled to triangulate volume and value outputs.
Data-stream reconciliation across supply-side capacity announcements, demand-side cracker commissioning schedules, and trade-flow customs documentation shaped the analytical framework. Segmentation dimensions modeled include product type tier, application end-use, distribution channel structure, and regional production hub classification. CAGRs were derived from installed capacity expansion trajectories weighted against feedstock substitution elasticities and carbon border adjustment implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU CBAM phase-in stringency, shale ethane price differentials, and refinery-petrochemical integration depth in India and China. Deviation in Middle Eastern export terminal capacity utilization or REACH substance registration enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Helical Submerged Arc Welded Pipe Market
Petroleum Products
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Uganda Petroleum Products Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Oil Refining Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
West Africa Refined Petroleum Products Market
Petroleum Products
Base Oil Market
Petroleum Products
Oil Refinery Market
Petroleum Products
South Africa Petroleum Market
Petroleum Products
Oil Shale Market
Petroleum Products
Asia Pacific Base Oil Market
Petroleum Products
Balanos Oil Market
Petroleum Products
Longitudinal Submerged-Arc Welded (LSAW) Pipes Market
Petroleum Products
South Africa Refined Petroleum Products Market