
 Remote Weapon Systems Market | 2026-2036
Remote Weapon Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Weapon Systems Market Analytics
Defense procurement concentration is decoupling from traditional prime contractor relationships as smaller NATO allies establish direct vendor relationships with specialized remote weapon system manufacturers. Rheinmetall AG leverages its integrated automotive and defense electronics divisions to anchor German Army modernization programs. Elbit Systems competes through vertical control over electro-optical payload supply chains. Kongsberg Gruppen dominates Nordic and Polish land vehicle retrofit markets with its family of Protector weapon stations.
Remote weapon systems combine stabilized gun mounts, electro-optical sensors, and fire-control computers to enable operators to acquire and engage targets from protected positions inside armored vehicles. These systems typically incorporate day/night cameras, laser rangefinders, and ballistic computers processing target data at refresh rates exceeding 60 Hz to maintain firing accuracy across moving platforms. Electromechanical drive technology leads product type segmentation due to superior precision and reduced maintenance compared to hydraulic alternatives. Military application channels sustain the largest revenue share, though border patrol end-user demand is accelerating fastest in Eastern Europe and the Indo-Pacific. RCWS configurations occupy the premium tier of product architecture, integrating heavier caliber weapons and active protection interfaces.
US ITAR regulations constrain cross-border technology transfer for fire-control software and thermal imaging components, compelling non-US buyers to seek ITAR-free alternatives from European and Israeli suppliers. EU REACH chemical restrictions and CE marking requirements for electromagnetic compatibility shape component sourcing decisions across NATO supply chains. The US Department of Defense Cybersecurity Maturity Model Certification program is forcing subsystem vendors to harden digital architectures against electronic warfare threats. Stakeholders must monitor evolving sovereign content requirements as France, Germany, and Italy advance European defense industrial base consolidation initiatives.
Market Dynamics
Electromechanical stabilization architectures are displacing legacy hydraulic drive systems across NATO armored vehicle modernization programs, compressing supplier qualification timelines while tightening sovereign content mandates.
Growth Catalysts
- ITAR-Free Procurement Mandates:Non-US defense ministries in Poland, Norway, and the Czech Republic now specify ITAR-free fire-control architectures to bypass US State Department technology transfer restrictions.
- Active Protection System Integration:Hard-kill defensive suites on German Leopard 2A8 and US M1E3 Abrams variants require RCWS platforms with hardened data buses and millisecond-response slew rates.
- Eastern European Border Hardening:NATO's Enhanced Forward Presence in Estonia, Latvia, and Lithuania drives demand for vehicle-mounted remote weapon stations with 12.7mm and 40mm configurations.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium-iron-boron permanent magnets for precision torque motors concentrate in Chinese processing facilities, exposing European and Israeli actuator manufacturers to supply interruption risk.
- US ITAR Compliance Burden:Fire-control software and thermal imaging cores classified under USML Category XV impose multi-year licensing timelines on cross-border subsystem transfers.
- Electromechanical Actuator Cost Premium:Ball-screw and direct-drive motor assemblies command 40-60% higher unit costs than equivalent hydraulic alternatives, stretching procurement budgets in mid-tier defense forces.
Strategic Opportunities
- Unmanned Ground Vehicle Payload Expansion:Robotic combat platforms such as the US Army's Robotic Combat Vehicle program demand miniaturized RCWS configurations under 400kg total system weight.
- Indo-Pacific Maritime Security:Coastal patrol vessels in the Philippines, Vietnam, and Indonesia require stabilized weapon mounts with corrosion-resistant coatings and integrated electro-optical tracking.
- EU Defence Fund Acceleration:The European Defence Industrial Programme channels capital toward collaborative armored vehicle programs, creating preference for continental subsystem suppliers with certified sovereign production lines.
Industry Challenges
- Cybersecurity Certification Bottlenecks:The US Department of Defense Cybersecurity Maturity Model Certification program forces subsystem vendors to re-architect digital interfaces, extending qualification cycles by 12-18 months.
- Electro-Optical Payload Integration Complexity:Fire-control computers must synchronize data from third-party thermal imagers, laser designators, and ballistic solvers across proprietary communication protocols.
- Legacy Vehicle Retrofit Engineering:Cold War-era armored personnel carriers in Polish and Romanian inventories lack electrical generation capacity and digital backbone infrastructure for full RCWS integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Weapon Systems Market |
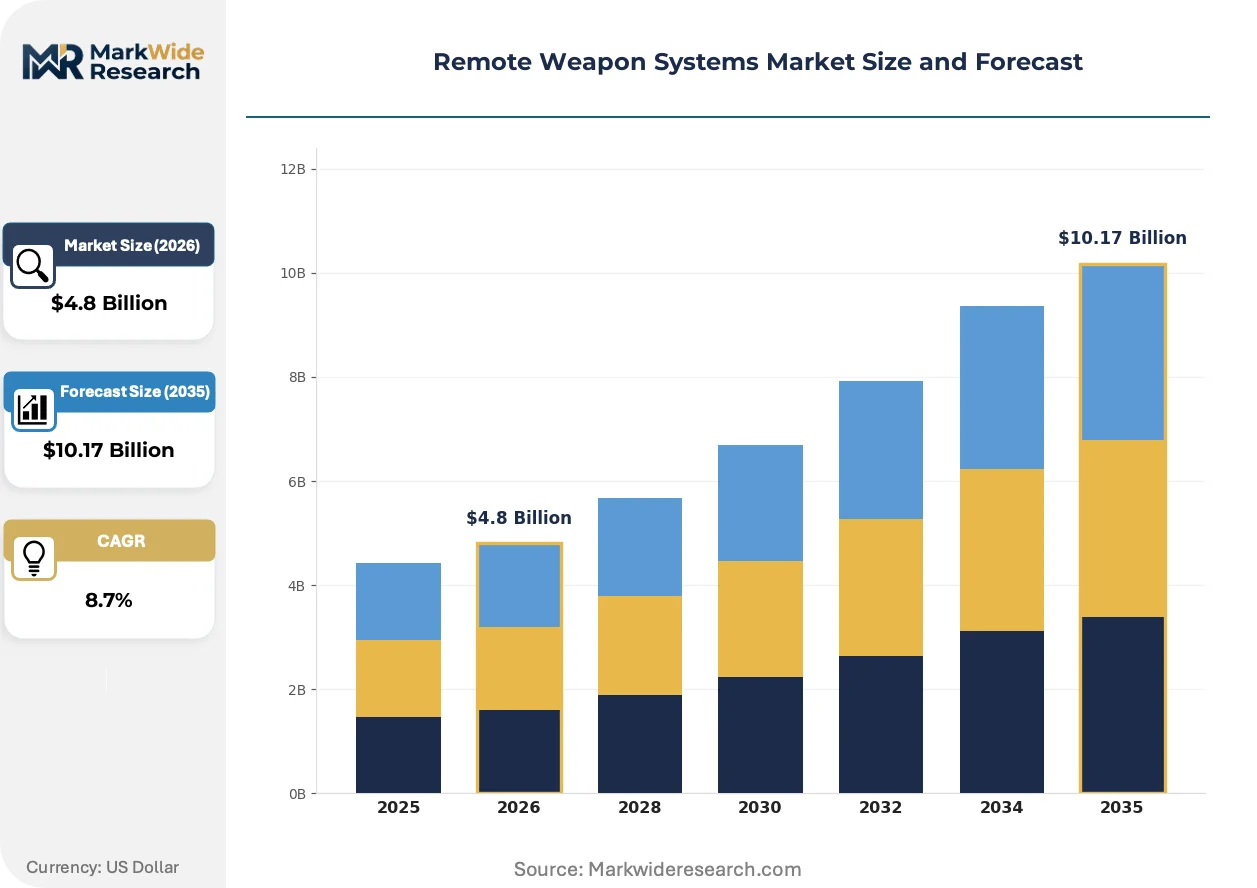
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RCWS, RWS, UAV, UGV Technology: Laser, Electromechanical, Hydraulic, Pneumatic Application: Military, Security, Border Patrol, Counter-Terrorism End User: Defense Forces, Law Enforcement, Private Security, Government Agencies |
| Companies Covered | Rheinmetall AG, Elbit Systems, Kongsberg Gruppen, Rafael Advanced Defense Systems, Thales Group, Leonardo S.p.A., BAE Systems, Raytheon Technologies, General Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Weapon Systems Market Evolving Landscape
Weapon station architectures are fragmenting into modular subsystems that permit field-reconfigurable caliber changes and sensor swaps without depot-level overhaul.
Electromechanical drive trains with integrated torque sensors and brushless DC motors is modularizing the traditional monolithic gun mount into standardized elevation and azimuth modules. Armored vehicle OEMs in Germany and Israel now specify these units as line-replaceable items. This architecture compresses maintenance intervals from 500 to 2,000 operating hours while enabling theater-level reconfiguration between 7.62mm and 30mm weapons.
The US Department of State ITAR regulations now classify fire-control source code and thermal imaging core algorithms as defense articles requiring individual export licenses. European system integrators respond by developing parallel software stacks and cooled infrared detectors outside US technology transfer jurisdiction. Israeli suppliers accelerate this decoupling through captive electro-optical foundries and indigenous ballistic computation libraries.
Defense procurement offices in NATO's eastern flank now mandate sovereign maintenance and software update capabilities as contract prerequisites. Polish and Romanian land forces require domestic depot access to fire-control firmware and spare actuator assemblies. This behavioral shift fragments the traditional prime contractor service model and creates direct vendor relationships between component manufacturers and national maintenance depots.
Remote Weapon Systems Market Segmentation
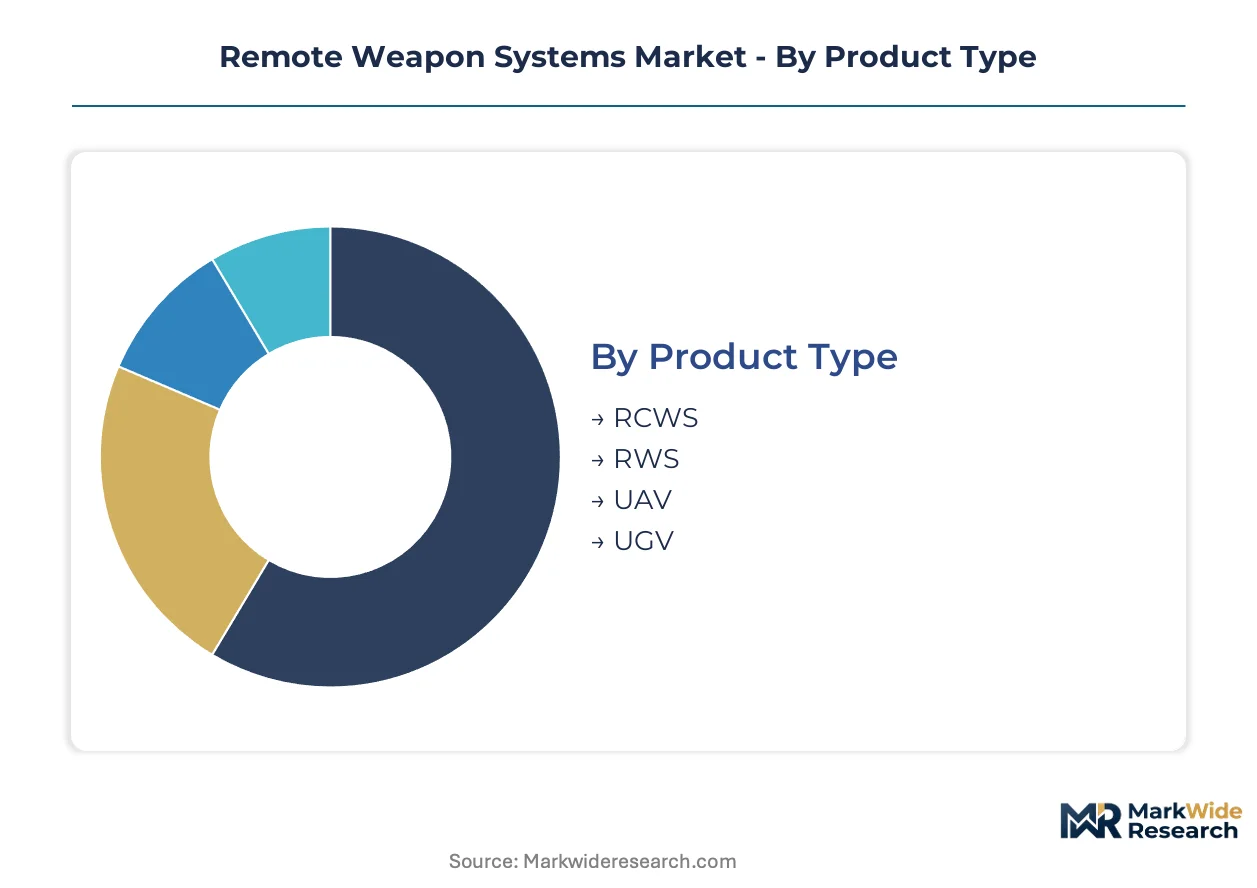
Remote weapon systems fragment across four distinct category axes, each reflecting divergent procurement priorities between sovereign defense ministries and commercial security operators. Technology choices separate NATO modernization programs from legacy fleet upgrades, while end-user distinctions reveal how ITAR compliance and sovereign content mandates reshape vendor selection criteria.
Product Type:
Defense procurement offices distinguish these configurations by weapon caliber integration depth and platform mobility requirements.
- RCWS:These systems integrate stabilized gun mounts, electro-optical sensors, and fire-control computers for protected-position target engagement from armored vehicles. German Leopard 2A8 and US M1E3 Abrams programs specify RCWS platforms with hardened data buses for active protection system integration.
- RWS:Remote weapon stations mount lighter calibers on tactical vehicles with simplified stabilization and reduced power demands. Polish and Romanian land forces prioritize RWS retrofits for Cold War-era armored personnel carriers lacking electrical generation capacity for full RCWS integration.
- UAV:Unmanned aerial vehicle payload stations demand miniaturized configurations under 400kg total system weight for robotic combat platforms. The US Army's Robotic Combat Vehicle program drives specifications for reduced-size electromechanical drives.
- UGV:Unmanned ground vehicle weapon mounts require autonomous target acquisition capabilities and hardened cyber architectures against electronic warfare threats. US Department of Defense Cybersecurity Maturity Model Certification mandates force subsystem re-architecture.
Volume sits with RWS for legacy vehicle retrofits; growth tilts toward RCWS for next-generation armored vehicle programs.
Technology:
Actuation mechanisms differentiate precision maintenance profiles and export control compliance pathways.
- Electromechanical:Ball-screw and direct-drive motor assemblies deliver superior precision with refresh rates exceeding 60 Hz for moving platform firing accuracy. These systems compress maintenance intervals from 500 to 2,000 operating hours but command 40-60% cost premiums over hydraulic alternatives.
- Hydraulic:Legacy hydraulic actuators persist in mid-tier defense forces with constrained procurement budgets. Eastern European border hardening programs balance capability requirements against unit cost limitations.
- Laser:Directed energy weapon integration demands specialized thermal management and power conditioning subsystems. Experimental programs in Israel and Germany explore laser weapon station feasibility for active protection applications.
- Pneumatic:Compressed gas actuation serves training systems and non-lethal weapon deployment with reduced mechanical complexity. Limited operational deployment restricts market presence.
Procurement concentrates on electromechanical architectures; hydraulic retains share in budget-constrained segments.
Application:
Mission profiles determine sensor payload complexity and rules of engagement software requirements.
- Military:Armored vehicle modernization programs across NATO member states sustain the largest revenue channel. These applications integrate day/night cameras, laser rangefinders, and ballistic computers processing target data at high refresh rates.
- Border Patrol:Eastern European and Indo-Pacific coastal security drives fastest expansion for stabilized weapon mounts with 12.7mm and 40mm configurations. Corrosion-resistant coatings and integrated electro-optical tracking address maritime environments.
- Security:Critical infrastructure protection and convoy escort missions require rapid deployment capabilities and reduced collateral damage profiles. Private operators seek ITAR-free alternatives from European suppliers.
- Counter-Terrorism:Urban operations demand compact profiles with positive target identification protocols and restrictive firing authorization chains. Software stacks emphasize de-escalation decision support.
Revenue weight rests with military applications; border patrol climbs fastest on regional security investments.
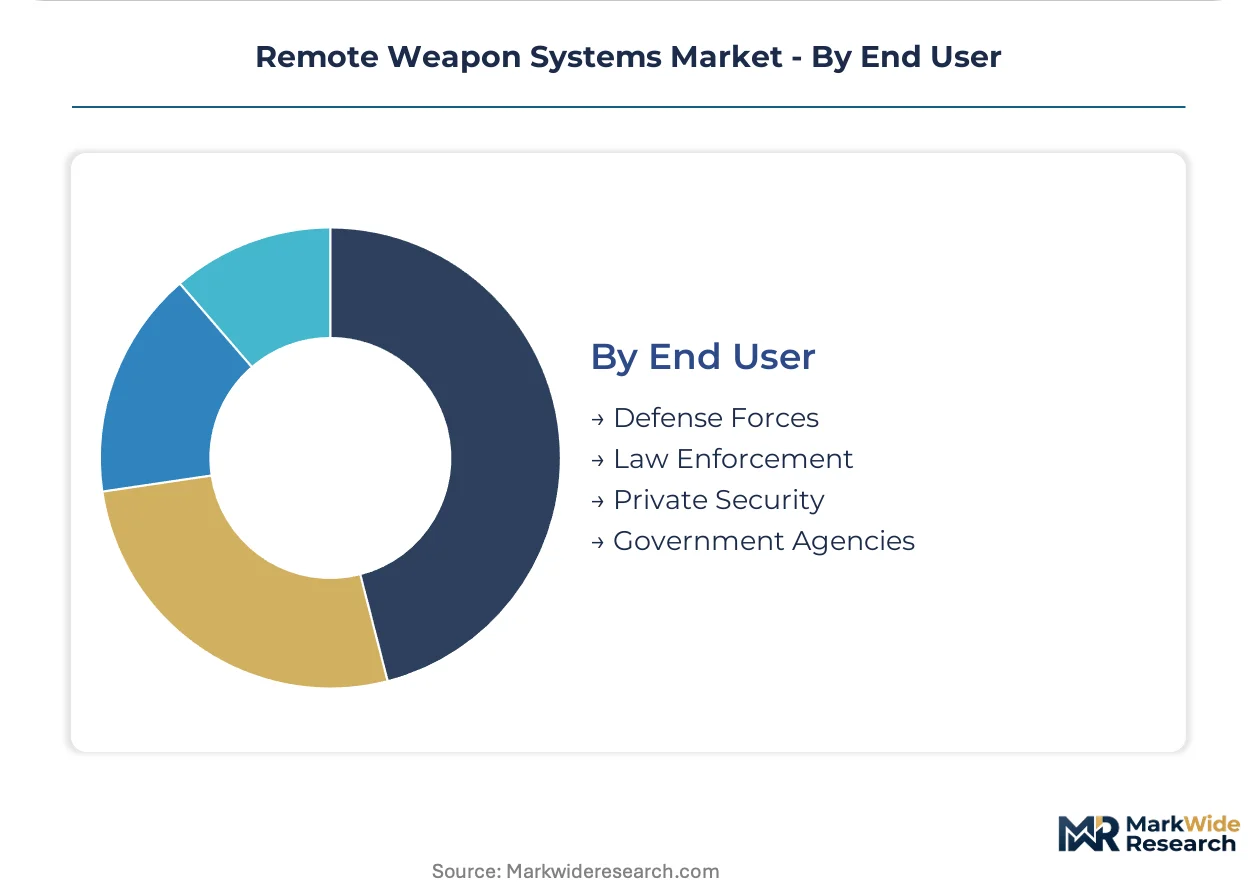
End User:
Contracting authority shapes sovereign content requirements and technology transfer compliance frameworks.
- Defense Forces:National armies specify ITAR-free fire-control architectures to bypass US State Department restrictions. Polish, Norwegian, and Czech defense ministries mandate domestic depot access to firmware and spare actuator assemblies.
- Law Enforcement:Police tactical units prioritize reduced-lethality options and civilian environment operational constraints. Procurement volumes trail military counterparts significantly.
- Private Security:Commercial operators face stringent licensing for weapon-mounted systems and concentrate demand on non-lethal configurations. Market presence remains limited by regulatory barriers.
- Government Agencies:Coast guard and border control organizations drive maritime-stabilized mount specifications. Philippines, Vietnam, and Indonesian coastal patrol vessels require corrosion-resistant integrated electro-optical tracking.
Defense forces dominate contract value; government agencies expand on maritime security investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentrates in NATO member states with sovereign production lines, where ITAR-free mandates and active protection system integration reshape vendor selection. Germany, the United States, and Israel anchor demand through armored vehicle modernization programs.
United States
The US Army's M1E3 Abrams program and Robotic Combat Vehicle initiative drive specifications for hardened data buses and miniaturized electromechanical drives. US Department of State ITAR regulations classify fire-control software and thermal imaging cores under USML Category XV, compelling domestic primes to maintain sovereign supply chains. Michigan and Ohio defense corridors concentrate final assembly and subsystem integration for active protection interfaces.
Germany
The Leopard 2A8 modernization and European Main Battle Tank program sustain demand for RCWS platforms with millisecond-response slew rates. KBA vehicle certification requirements and EU REACH chemical restrictions shape component sourcing for electromagnetic compatibility. Bavaria and Baden-Württemberg host integrated automotive-defense electronics clusters producing electromechanical stabilization modules.
Israel
Indigenous active protection development and captive electro-optical foundries anchor ITAR-free export positioning. Israeli suppliers accelerate software stack decoupling through indigenous ballistic computation libraries and cooled infrared detector production. Tel Aviv and Haifa metropolitan areas concentrate electro-optical payload engineering and fire-control algorithm development.
Poland
Eastern European border hardening under NATO's Enhanced Forward Presence drives 12.7mm and 40mm vehicle-mounted station procurement. Polish defense ministries mandate sovereign maintenance depot access to firmware and spare actuator assemblies as contract prerequisites. Warsaw and Poznań industrial zones host emerging subsystem integration facilities serving regional retrofit markets.
Norway
Arctic-capable vehicle programs and coastal patrol vessel specifications demand corrosion-resistant stabilized mounts with integrated electro-optical tracking. Norwegian procurement offices specify ITAR-free fire-control architectures to bypass US technology transfer restrictions. Kongsberg and Oslo defense technology clusters anchor Nordic land vehicle retrofit supply chains.
Remote Weapon Systems Market Competitive Landscape
United States producers anchor one tier through ITAR-constrained prime contractor relationships; European and Israeli specialists hold parallel ITAR-free positioning for NATO eastern flank markets. Market structure fragments across three strategic tiers: integrated automotive-defense conglomerates with captive electronics divisions, electro-optical payload specialists with vertical sensor supply chains, and modular subsystem vendors supplying line-replaceable actuator assemblies. Competitive moves concentrate on sovereign production line certification and cybersecurity-hardened digital architecture development.
Among integrated defense conglomerates, Rheinmetall AG exemplifies the automotive-electronics convergence archetype through cross-divisional coordination. Elbit Systems and Kongsberg Gruppen occupy positions within the electro-optical and modular specialization tiers respectively, representing alternative pathways to ITAR-free market access. These three entities anchor distinct competitive positioning vectors without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Rheinmetall AG |
| Elbit Systems |
| Kongsberg Gruppen |
| Rafael Advanced Defense Systems |
| Thales Group |
| Leonardo S.p.A. |
| BAE Systems |
| Raytheon Technologies |
| General Dynamics |
| Others |
Value Network & Pricing Analysis
Electro-optical engineering talent concentration in Tel Aviv and Haifa anchors labor-cost differentials that separate ITAR-compliant premium tiers from ITAR-free standard offerings, compressing margins for mid-tier European suppliers competing on sovereign-content value propositions.
Pricing Analysis
Volume concentrates in legacy RWS retrofits for Eastern European armored vehicle fleets, while margins concentrate in RCWS platforms integrating active protection system interfaces for German and US next-generation programs. Three-tier pricing structure across premium, standard, and economy levels differentiates by ITAR compliance status and sovereign maintenance depot access certification. Price erosion runs through hydraulic actuator segments as electromechanical architectures capture NATO modernization budgets. Mid-tier defense forces in Poland and Romania exhibit highest price sensitivity, constrained by legacy vehicle electrical generation limitations and compressed procurement timelines.
Supply Chain Analysis
Refurbishment flows for fire-control computers and electro-optical payloads concentrate in Polish and Romanian sovereign maintenance depots, creating reverse-logistics infrastructure that reduces lifecycle costs for ITAR-free procurement programs. Neodymium-iron-boron permanent magnet processing draws from Chinese facilities, while precision torque motor assembly rests on German and Israeli manufacturing clusters. Single-source vulnerability in rare earth magnet supply exposes European actuator manufacturers to interruption risk. Distribution runs through national defense procurement offices with direct vendor relationships to component manufacturers, bypassing traditional prime contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where US ITAR regulations and EU cybersecurity certification requirements erect barrier-to-entry moats favoring incumbents with sovereign production lines and hardened digital architectures.
For Market Incumbents: Hedge against ITAR-free European and Israeli competition by accelerating captive electro-optical foundry investments and indigenous ballistic computation library development. Secure sovereign maintenance depot certifications in Poland, Norway, and Czech Republic to defend against direct vendor relationship fragmentation. Prioritize Cybersecurity Maturity Model Certification compliance to extend qualification cycle advantages over emerging subsystem vendors. For New Entrants and Emerging Players: Capture unmanned ground vehicle payload expansion in the US Army Robotic Combat Vehicle program, where miniaturized configurations under 400kg total system weight remain underpenetrated by established RCWS suppliers. Target Indo-Pacific maritime security applications for coastal patrol vessels requiring corrosion-resistant stabilized mounts with integrated electro-optical tracking. Pursue ITAR-free positioning through European Defence Industrial Programme consortium participation as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with modular subsystem vendors supplying line-replaceable electromechanical actuator assemblies given NATO's shift toward field-reconfigurable weapon station architectures. Long-term viability favors suppliers with certified sovereign production lines and vertical control over electro-optical payload supply chains. Monitor EU Defence Fund allocation acceleration and Polish sovereign depot access mandate enforcement as inflection indicators for ITAR-free market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ITAR-Free Software Stack Development | Parallel fire-control architectures bypass US State Department licensing timelines for NATO eastern flank procurement. |
| Electromechanical Actuator Miniaturization | Reduced-size drives under 400kg enable robotic combat platform integration for US Army modernization programs. |
| Sovereign Maintenance Depot Certification | Domestic firmware access and spare assembly availability satisfy Polish and Romanian contract prerequisites. |
| Active Protection System Interface Hardening | Millisecond-response slew rates and hardened data buses meet Leopard 2A8 and M1E3 Abrams specifications. |
| Cybersecurity Maturity Model Certification | Digital architecture hardening against electronic warfare threats extends qualification cycle advantages over competitors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with defense procurement officers, RCWS platform engineers, electro-optical payload specialists, and sovereign depot maintenance directors. US Department of State ITAR licensing databases, EU Defence Fund allocation disclosures, and NATO armored vehicle modernization program documentation provided secondary validation. Bottom-up unit economics for electromechanical actuator assemblies and top-down defense budget allocation triangulation reconciled market sizing across the analysis window.
Data-stream reconciliation combined production volume tracking from Bavarian and Baden-Württemberg automotive-defense electronics clusters with procurement pipeline visibility from Polish, Norwegian, and Czech defense ministries. Segmentation modeling incorporated product type, technology architecture, application mission profile, and end-user contracting authority dimensions. CAGRs derived from defense expenditure trajectory analysis and platform replacement cycle timing, with electromechanical adoption curves and ITAR-free procurement mandate penetration serving as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth magnet supply disruption, US ITAR regulation expansion, and European defence industrial base consolidation initiatives. Forecasts reflect documented assumptions regarding NATO armored vehicle modernization program execution and sovereign content mandate enforcement trajectories. Practitioners should monitor Chinese rare earth processing policy shifts and EU Defence Fund acceleration signals for early indicators of supply constraint or demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Micro Tactical Ground Robot Market
Unmanned Systems
North America Hyperloop Technology Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market
Unmanned Systems
Asia-Pacific Unmanned Systems Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Japan Autonomous Navigation Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Tethered Manned Submersible Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Military Robotics Market
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
Europe Aerostat Systems Market