
 Global Ground Control Station Market | 2026-2036
Global Ground Control Station Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ground Control Station Market Foresight
Project finance and operational leasing for unmanned systems infrastructure is narrowing the competitive field to primes with balance-sheet capacity for multi-year performance contracts. General Atomics leverages captive financing arms to bundle ground station hardware with airframe service agreements. Northrop Grumman sustains its position through classified program access and integration with national satellite constellations. Elbit Systems competes by anchoring export contracts in allied defense frameworks with localized maintenance obligations.
A ground control station constitutes the terrestrial command-and-control element for unmanned aerial, surface, and submersible vehicles, integrating mission planning consoles, communication uplink terminals, and payload data processing suites operating across C-band through Ku-band frequencies. Its primary commercial and defense purpose centers on beyond-line-of-sight vehicle operation, real-time sensor exploitation, and flight safety assurance through redundant telemetry links. Fixed ground stations dominate military surveillance applications where hardened facilities support persistent operations, while portable configurations represent the fastest-expanding segment as disaster response agencies and agricultural firms deploy rapidly emplaced networks. Transportable systems concentrate margin pools in NATO interoperability programs requiring STANAG-compliant hardware swap capabilities.
FAA Part 107 waivers and EASA U-space framework development shape civil ground station deployment timelines and spectrum allocation priorities. NATO STANAG 4671 and national encryption mandates from the US NSA and Israel's C4I Directorate dictate hardware certification pathways and foreign market access restrictions. Stakeholders must monitor evolving spectrum harmonization negotiations between defense and commercial regulators to anticipate communication technology substitution cycles.
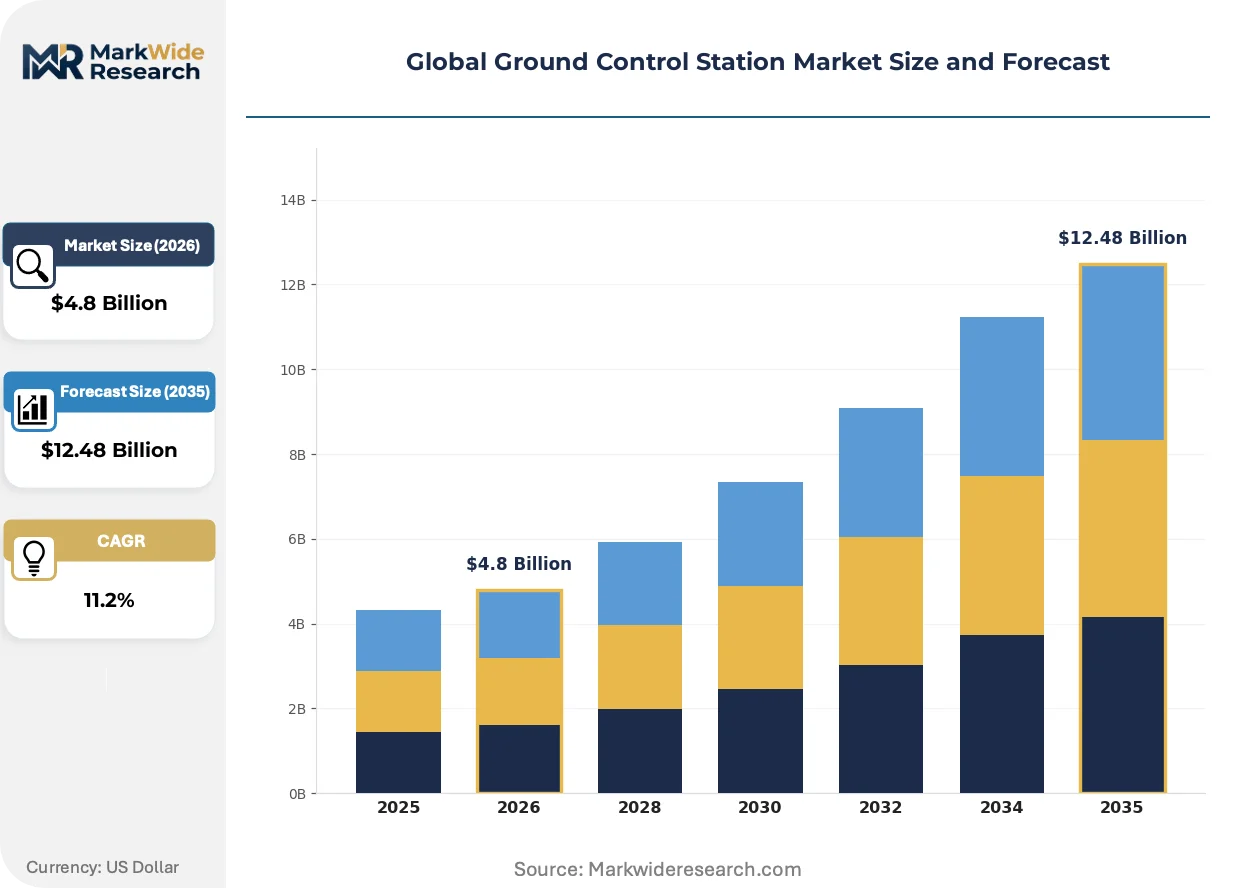
Market Dynamics
Defense procurement cycles are compressing as NATO STANAG 4671 mandates force hardware refresh timelines, while software-defined radio architectures enable firmware-upgradable platforms that extend operational lifespans without full system replacement.
Growth Catalysts
- NATO STANAG 4671:The interoperability standard mandates compliant ground stations across member states, creating synchronized procurement windows and standardizing hardware specifications for cross-border drone operations.
- Beyond-line-of-sight agriculture:Precision farming operators in Australia and Brazil deploy portable ground stations to command crop-spraying UAV fleets across vast landholdings, expanding commercial addressable demand.
- Ku-band spectrum allocation:Civil aviation regulators in the United States and Germany release protected frequency blocks for unmanned traffic management, enabling higher-bandwidth telemetry links for commercial drone services.
Market Restraints
- Gallium nitride component costs:High-power amplifier modules for C-band through Ku-band transmission rely on specialized semiconductor foundries concentrated in Taiwan and South Korea, creating input cost volatility and supply concentration risk.
- US NSA encryption mandates:National Security Agency Type 1 certification requirements for military ground stations impose multi-year development timelines and restrict foreign component sourcing, limiting vendor flexibility.
- Satellite communication substitution:Commercial satellite direct-to-drone links from providers like Starlink and OneWeb bypass terrestrial ground station infrastructure for certain mission profiles, compressing addressable market scope in long-range applications.
Strategic Opportunities
- India defense modernization:The country's armed forces lack indigenous ground station manufacturing capacity, creating white space for licensed production partnerships under offset obligations tied to foreign military sales.
- Dual-use maritime surveillance:Coast guard agencies in Indonesia and Vietnam seek transportable ground stations for Exclusive Economic Zone patrol, blending defense and fisheries enforcement budgets.
- EASA U-space framework:The European Union's unmanned traffic management regulations mandate ground-based detect-and-avoid infrastructure in urban air mobility corridors, creating regulatory tailwind for certified station deployments.
Industry Challenges
- Embedded systems cybersecurity certification:Ground stations require Common Criteria EAL4+ or equivalent evaluation for military contracts, with assessor backlog extending validation timelines by 12-18 months.
- Legacy analog radio integration:Defense operators maintain mixed fleets with Vietnam-era communication architectures, forcing ground station vendors to support obsolete waveform protocols alongside modern digital standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ground Control Station Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Fixed Ground Stations, Transportable Ground Stations, Mobile Ground Stations, Portable Ground Stations Communication Technology: Satellite Link, Radio Frequency, TCP/IP Network, Cellular Network, Microwave Link Application: Military Surveillance, Environmental Monitoring, Disaster Management, Agricultural Surveying, Maritime Security End User: Defense Organizations, Research Institutes, Agricultural Firms, Maritime Authorities |
| Companies Covered | General Atomics, Northrop Grumman, Raytheon Technologies, Lockheed Martin, General Dynamics, Elbit Systems, Thales Group, BAE Systems, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ground Control Station Market Shifts & Advancements
Software architectures are displacing dedicated hardware functions across ground station design, compressing physical footprints while expanding reconfigurability for multi-platform drone command.
Containerized mission software is virtualizing payload data processing and flight control functions that previously required rack-mounted computing hardware. Agricultural service providers and disaster response agencies adopt these reduced-form-factor stations for rapid deployment scenarios. The shift is virtualizing margin structures away from proprietary hardware toward recurring software licensing models.
REACH chemical restrictions in the European Union constrain flame-retardant materials in ground station enclosures, forcing enclosure manufacturers toward halogen-free thermoplastic compounds. The regulation accelerates material qualification costs for vendors serving NATO and EU defense markets simultaneously. Station builders with pre-qualified supply chains capture accelerated procurement timelines in Germany and France.
Performance-based logistics contracts now bundle ground station availability with airframe mission rates, displacing traditional hardware purchase plus separate maintenance agreements. Defense primes in Israel and the United States structure these consolidated offerings to lock out component-level competitors. The contractual innovation concentrates most visibly in long-endurance surveillance programs where downtime penalties apply across integrated system availability.
Global Ground Control Station Market Segmentation
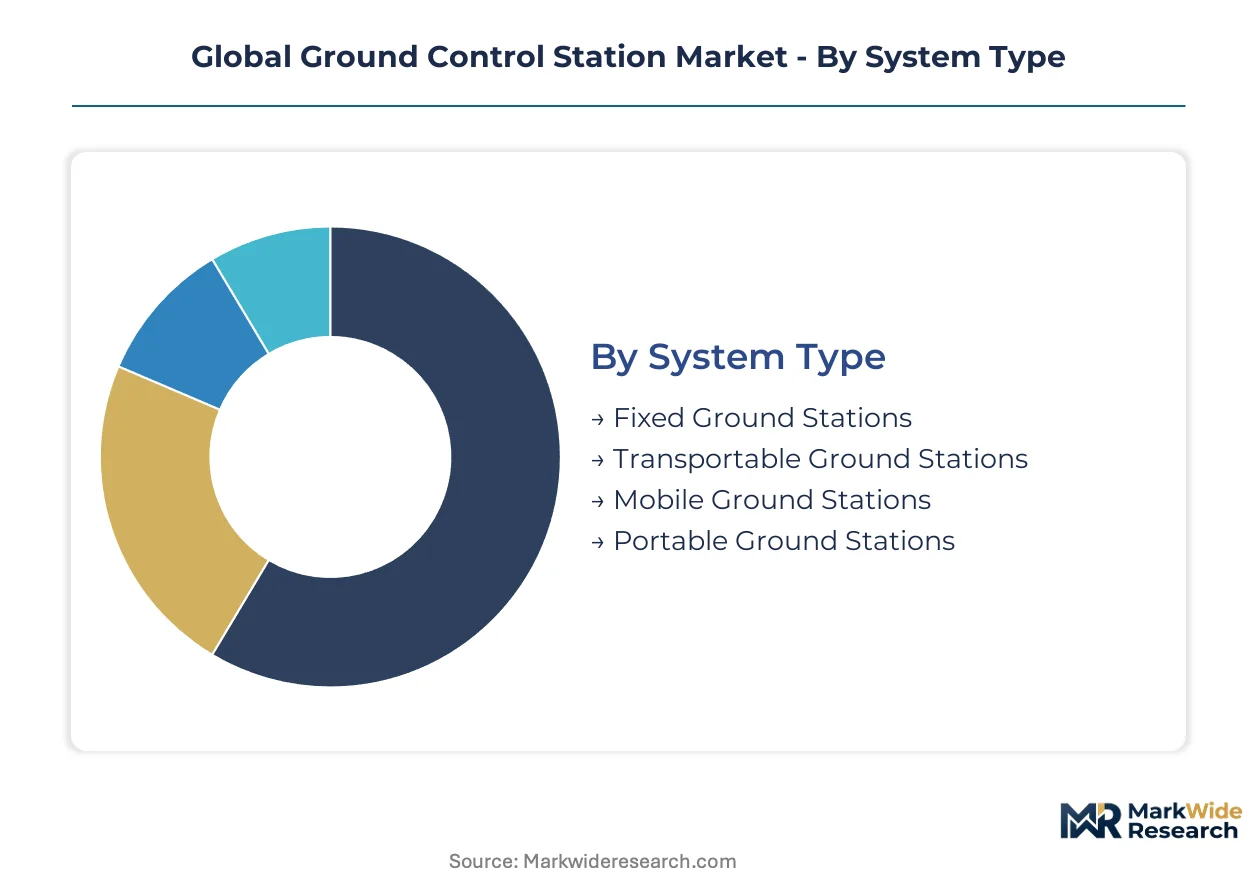
Ground control station architectures fragment across mobility requirements, spectrum choices, mission profiles, and procurement authority. Each segmentation axis carries distinct margin structures, certification burdens, and competitive dynamics that shape vendor positioning.
System Type:
Mature hardened facilities anchor defense surveillance contracts while emerging portable configurations unlock commercial expansion vectors.
- Fixed Ground Stations:Hardened facilities with redundant power and environmental protection support persistent military surveillance operations. NATO member states in France and Germany concentrate procurement for border monitoring and air defense integration, with STANAG compliance extending refresh cycles.
- Transportable Ground Stations:Modular containerized architectures enable rapid emplacement and hardware swap capabilities for expeditionary forces. Demand clusters in United States Pacific Command theaters and Polish forward deployment zones, driven by interoperability mandates.
- Mobile Ground Stations:Vehicle-mounted command elements integrate with tactical vehicle fleets for maneuver warfare support. Israeli Defense Forces and Australian Army programs define specification benchmarks.
- Portable Ground Stations:Backpack or suitcase-form-factor units command small UAV swarms in austere environments. Brazilian agricultural operators and Indonesian coast guard units drive civil adoption.
Fixed stations retain volume leadership; portable configurations hold the steepest expansion curve.
Communication Technology:
Cost tier stratification separates sovereign-spectrum military systems from commercial cellular and satellite alternatives.
- Satellite Link:Beyond-line-of-sight command via dedicated military constellations or commercial leases enables global reach for intelligence missions. United States Space Force and French CNES anchor demand for protected anti-jam waveforms.
- Radio Frequency:Software-defined radio architectures across C-band through Ku-band dominate tactical line-of-sight operations. Gallium nitride amplifier costs constrain margin expansion for hardware vendors.
- TCP/IP Network:Internet-protocol command links integrate ground stations into broader C4ISR architectures. Network-centric warfare doctrines in United Kingdom and Japan shape procurement specifications.
- Cellular Network:Commercial 4G/5G infrastructure commands short-range commercial drones in urban air mobility corridors. EASA U-space framework compliance in Germany and Netherlands creates certification pathways.
- Microwave Link:Point-to-point high-bandwidth transmission supports payload data exfiltration from remote sensor platforms. Australian maritime surveillance and South Korean coastal defense programs concentrate demand.
Radio frequency systems retain volume leadership; cellular network integration gains share fastest.
Application:
Customer type concentration separates classified defense budgets from dual-use and purely commercial deployments.
- Military Surveillance:Intelligence, reconnaissance, and target acquisition missions require encrypted command links and sovereign payload control. United States, Israel, and Turkey operate the largest installed bases.
- Environmental Monitoring:Atmospheric and ecological sensing missions command scientific payloads over protected areas. Brazilian INPE and Canadian Environment Agency operate networked station architectures.
- Disaster Management:Rapidly emplaced command infrastructure coordinates search-and-rescue UAV fleets following seismic or weather events. FEMA in United States and Japan's Fire and Disaster Management Agency define operational concepts.
- Agricultural Surveying:Precision farming operators deploy portable stations for crop health monitoring and targeted input application. Australian wheat belt and Brazilian soy frontier concentrate commercial demand.
- Maritime Security:Exclusive Economic Zone patrol and port protection integrate surface and aerial unmanned assets. Indonesian Bakamla and Vietnam Coast Guard drive transportable system procurement.
Military surveillance retains volume leadership; agricultural surveying climbs the fastest.
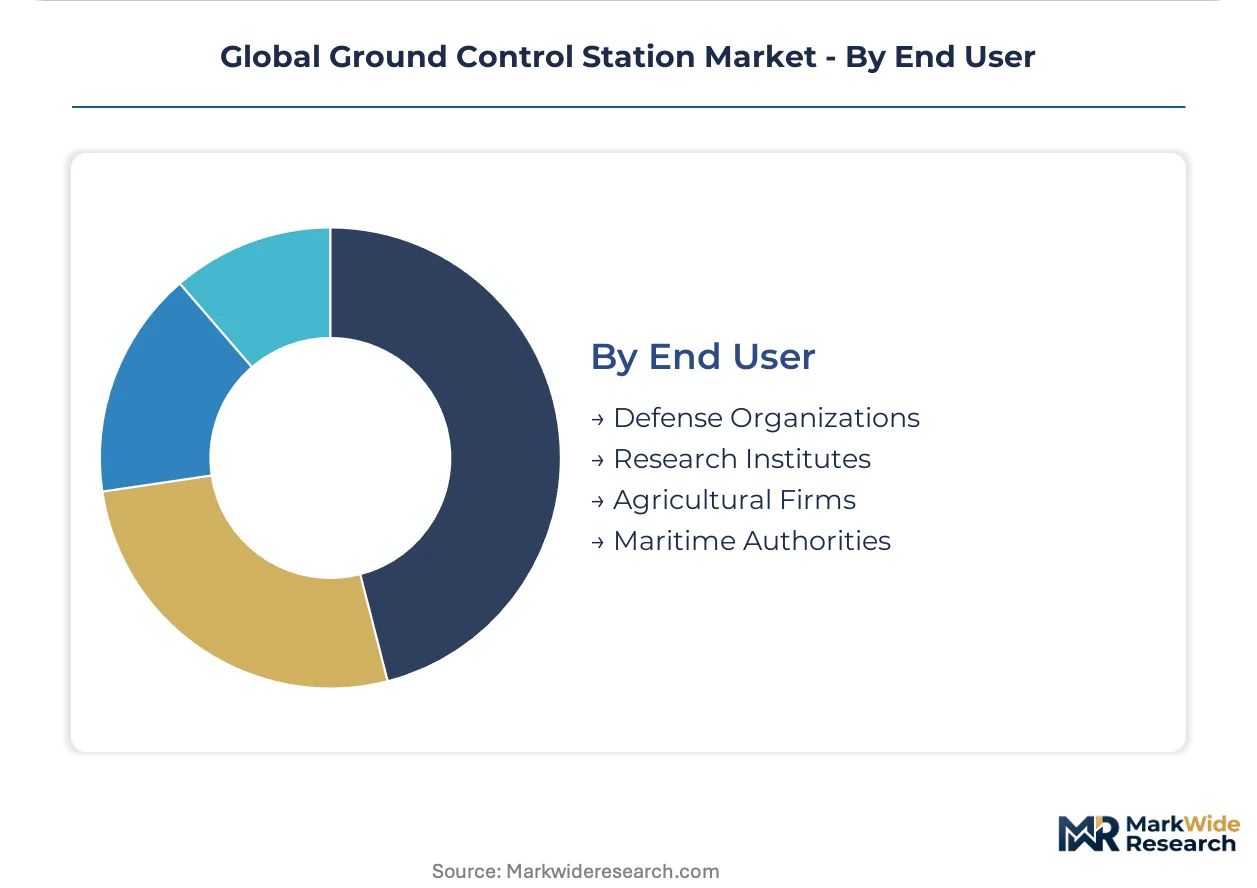
End User:
Geographic procurement authority separates national defense establishments from institutional and commercial buyers with diverging contracting mechanisms.
- Defense Organizations:National military services and alliance command structures procure through classified programs and NATO cooperative frameworks. Multi-year availability contracts predominate in United States and Israeli procurement.
- Research Institutes:Academic and government laboratories operate experimental ground stations for platform and payload development. German DLR and NASA centers maintain specialized testbed configurations.
- Agricultural Firms:Large-scale farming operations and agricultural service providers lease or purchase portable command infrastructure. Australian corporate farming entities and Brazilian agribusiness cooperatives lead commercial adoption.
- Maritime Authorities:Coast guard and fisheries enforcement agencies command mixed fleets for border and resource protection. Indonesian and Vietnamese agencies blend defense and civil budget sources.
Defense organizations retain volume leadership; agricultural firms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli primes extract 40% price premiums over NATO-compliant hardware sourced from French or German vendors. The United States maintains parallel procurement tracks for classified programs versus STANAG-certified alliance sales.
United States
US Space Force and SOCOM drive demand for satellite-linked command infrastructure with protected anti-jam waveforms. FAA Part 107 waivers and BVLOS exemption pathways shape civil ground station deployment timelines. General Atomics and Northrop Grumman anchor production clusters in California and Maryland, bundling hardware with multi-year availability contracts.
Israel
IDF tactical requirements for vehicle-mounted and portable configurations set global specification benchmarks. The C4I Directorate mandates national encryption standards that restrict foreign component sourcing. Elbit Systems and Rafael maintain integrated design-to-deployment facilities in Haifa and Beersheba, serving domestic and export markets simultaneously.
Germany
Bundeswehr border surveillance and NATO forward deployment zones concentrate demand for transportable STANAG-compliant systems. EASA U-space framework development and REACH chemical restrictions on enclosure materials impose dual certification burdens. Thales and Rheinmetall operate engineering centers in Düsseldorf and Munich, leveraging pre-qualified halogen-free supply chains.
France
CNES satellite constellation integration and naval aviation requirements sustain fixed and transportable station procurement. ANSM cybersecurity certification timelines and NATO interoperability mandates compress vendor selection windows. Thales Group and Safran anchor manufacturing in Toulouse and Paris-Saclay, serving Scorpion program modernization.
India
Army, Navy, and Air Force lack indigenous ground station manufacturing capacity across all mobility tiers. Defence Acquisition Procedure offset obligations and licensed production mandates create entry pathways for foreign primes. Hindustan Aeronautics and Bharat Electronics partner with Israeli and US vendors in Bengaluru and Hyderabad for technology transfer arrangements.
Global Ground Control Station Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in radio frequency and power amplifier modules. The vendor base stratifies between primes with classified program access and mid-tier challengers competing on STANAG-certified hardware refresh cycles. Two archetypes dominate: aerospace conglomerates with captive financing arms, and defense-electronics specialists with allied defense framework anchoring. Competitive moves concentrate on performance-based logistics bundling and localized maintenance obligation structuring.
Within the aerospace conglomerate tier, General Atomics and Northrop Grumman exemplify platform integrators leveraging balance-sheet capacity for multi-year availability contracts. Elbit Systems occupies a position among defense-electronics specialists competing through export contract anchoring in allied frameworks. Raytheon Technologies and Lockheed Martin represent the scale-driven segment with classified program integration capabilities. Thales Group and BAE Systems sit within the European prime archetype serving NATO interoperability requirements. L3Harris Technologies exemplifies the communications-technology specialist position in tactical radio and network-centric integration.
| Leading Market Players |
|---|
| General Atomics |
| Northrop Grumman |
| Raytheon Technologies |
| Lockheed Martin |
| General Dynamics |
| Elbit Systems |
| Thales Group |
| BAE Systems |
| L3Harris Technologies |
| Others |
Supply & Pricing Matrix
Gallium nitride foundry capacity in Taiwan and South Korea concentrates upstream power amplifier supply, anchoring margin capture in downstream system integration rather than component manufacturing. NATO STANAG certification requirements and NSA Type 1 encryption mandates create tiered pricing power for vendors with pre-qualified hardware architectures, while commercial agricultural buyers face commoditized portable station pricing.
Pricing Analysis
Configured-to-order transportable stations for defense interoperability programs command substantial premiums over standard portable units sold to commercial agricultural operators. Three-tier pricing structure across STANAG-certified, national-encryption-compliant, and commercial-off-the-shelf levels reflects certification burden and foreign component restriction compliance. Pricing pressure stems from software-defined radio architectures enabling firmware upgrades that extend hardware lifecycles and compress replacement demand. Defense organizations exhibit lowest price sensitivity due to mission-critical availability requirements, while Brazilian and Australian agricultural cooperatives drive hardest bargain on portable station leases.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for enclosure manufacturers and printed circuit board fabricators serving NATO dual-use markets. High-power amplifier modules draw from Taiwan Semiconductor Manufacturing and South Korean foundries, while hardened enclosure aluminum alloys source from German and French metallurgical suppliers. Single-source vulnerability concentrates in gallium nitride wafer supply for Ku-band transmission components. Distribution runs through defense primes with captive logistics arms in Israel and United States, bypassing independent component distributors for classified program deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified assessor scarcity for Common Criteria EAL4+ cybersecurity certification creates bottlenecks that extend vendor validation timelines and concentrate contract awards among incumbents with established evaluation relationships. This capability gap rewards early certification investment and punishes late entrants lacking assessor queue priority.
For Market Incumbents: Harden software-defined radio architecture roadmaps against satellite direct-to-drone substitution threats from Starlink and OneWeb by embedding proprietary waveform protocols that terrestrial stations alone can manage. Deepen backward integration into gallium nitride amplifier supply through long-term offtake agreements with Taiwan and South Korean foundries. Lock in multi-year performance-based logistics contracts with NATO procurement offices before STANAG 4671 refresh windows synchronize competitive bidding. For New Entrants and Emerging Players: Indian defense modernization lacks indigenous ground station manufacturing across all mobility tiers, creating licensed production partnership opportunities under Defence Acquisition Procedure offset obligations. Indonesian and Vietnamese coast guard dual-use maritime surveillance programs blend defense and civil fisheries enforcement budgets, offering lower certification barriers than pure military procurement. Pursue EASA U-space framework certification for urban air mobility ground infrastructure in Germany and Netherlands as entry pathway into European detect-and-avoid station deployments. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined radio specialists with NATO STANAG pre-qualification and containerized mission software virtualization capabilities. Long-term viability rests on recurring software licensing models displacing proprietary hardware margins across the analysis window. Watch for satellite direct-to-drone link penetration rates in long-range agricultural and maritime applications as inflection signal for terrestrial station addressable market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Architecture Investment | Virtualizes payload processing functions and extends hardware refresh cycles for NATO STANAG-compliant vendors. |
| Licensed Production Partnership in India | Captures offset-obligated demand from Army, Navy, and Air Force lacking indigenous manufacturing capacity. |
| EASA U-space Framework Certification | Unlocks urban air mobility ground infrastructure deployment in Germany and Netherlands regulatory corridors. |
| Performance-Based Logistics Contracting | Bundles station availability with airframe mission rates, locking out component-level competitors in Israel and United States. |
| Halogen-Free Enclosure Supply Chain Qualification | Accelerates procurement timelines in Germany and France under REACH chemical restriction compliance. |
Research Methodology
Cross-validation between primary interviews with ground station program managers at defense primes and secondary validation through NATO procurement databases anchors the qualitative findings. Stakeholder consultations encompassed systems engineers at Israeli and US platform integrators, procurement officers at French and German defense ministries, agricultural fleet operators in Australia and Brazil, and cybersecurity certification assessors. Secondary sources included FAA Part 107 waiver filings, EASA U-space regulatory development documents, STANAG 4671 specification releases, and customs trade data for gallium nitride component flows. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Calibration against historical procurement cycle timing and technology substitution patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass system mobility tier, communication technology spectrum choice, application mission profile, and end-user procurement authority. CAGRs derived from fitted growth curves adjusted for regulatory mandate synchronization effects and software-defined radio lifecycle extension impacts. Industry-specific inputs included NATO STANAG compliance rollout schedules, EASA U-space implementation timelines, and gallium nitride foundry capacity expansion announcements.
Practitioners should monitor encryption mandate revisions, satellite direct-to-drone link commercialization rates, and REACH chemical restriction enforcement intensity for early signals of forecast deviation. Forecasts reflect assumptions regarding STANAG 4671 adoption timelines and software-defined radio penetration curves. Macroeconomic defense budget contraction, regulatory harmonization failure between FAA and EASA, or gallium nitride supply disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Drone Tethered Stations Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
Military Robotics Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Dismounted Soldier Systems Market
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
North America Hyperloop Technology Market
Unmanned Systems
Drone Parachute System Market
Unmanned Systems
Rotary-Wing Lidar Drone Market