
 Asia-Pacific Military Unmanned Vehicles Market | 2026-2036
Asia-Pacific Military Unmanned Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Military Unmanned Vehicles Market Outlook
Naval surveillance is repositioning procurement priorities across Asia-Pacific defense ministries. Korea Aerospace Industries leverages its KUS-series UAV lineage to anchor South Korea's maritime patrol modernization. Elbit Systems Ltd competes through Hermes-family systems with proven over-water endurance. China Aerospace Science and Technology Corporation dominates domestic supply through its Rainbow and Wing Loong portfolios, extending reach into Southeast Asian export channels.
Asia-Pacific military unmanned vehicles encompass autonomous or remotely operated platforms operating across aerial, terrestrial, and maritime domains, typically incorporating GPS navigation, sensor fusion architectures, and encrypted command links with operational ranges exceeding 200 nautical miles for strategic systems. Their primary purpose spans intelligence collection, force protection, and logistics distribution in contested environments. Fixed-wing UAVs sustain the largest revenue share due to endurance advantages in wide-area ocean surveillance, while rotary-wing variants capture growing interest for shipboard deployment and urban terrain operations. Ground robots occupy specialized niches in explosive ordnance disposal and perimeter security where human exposure carries unacceptable risk.
India's Defence Research and Development Organisation and Australia's Defence Science and Technology Group shape national certification pathways, while Japan's Ministry of Economy, Trade and Industry coordinates dual-use export controls under its arms trade framework. These regulators constrain technology transfer timelines and mandate local assembly quotas that fragment supplier economics. Stakeholders must monitor evolving submarine detection requirements and undersea communication relay specifications as underwater vehicles transition from experimental to operational status.
Market Dynamics
Maritime domain awareness requirements are compressing platform development cycles across Asia-Pacific defense procurement offices. Littoral states now prioritize over-the-horizon endurance over payload flexibility, forcing suppliers to reconfigure airframe architectures around fuel efficiency and satellite relay compatibility.
Growth Catalysts
- Japan's METI dual-use framework:Relaxed export controls on sensor subsystems enable Japanese manufacturers to supply maritime radar packages to regional allies, expanding component market access.
- Submarine detection:Magnetic anomaly detection payloads on long-endurance UAVs address undersea surveillance gaps in contested waters around the Philippines and Vietnam.
- India's PLI scheme:Production-linked incentives for defense manufacturing attract foreign OEMs to establish local assembly lines for tactical drone systems.
Market Restraints
- GaN semiconductor supply:Gallium nitride components for phased-array radars concentrate in Chinese and US fabrication facilities, exposing regional primes to export restriction volatility.
- Australia's DSTG certification:Extended electromagnetic interference testing protocols delay platform deployment by 18-24 months beyond initial delivery schedules.
- Swarming coordination algorithms:Autonomous collaborative engagement software remains immature for contested electronic warfare environments, limiting operational trust.
Strategic Opportunities
- Indonesia's outer island chain:Archipelagic geography creates distributed surveillance requirements that favor medium-altitude long-endurance platforms over satellite alternatives.
- AI-enabled predictive maintenance:Machine learning diagnostics applied to turbine engine health monitoring reduce logistics tail requirements for forward-deployed units.
- Thailand's defense modernization:Royal Thai Armed Forces restructuring prioritizes unmanned systems for border monitoring along the Myanmar frontier.
Industry Challenges
- Flight control software verification:Autonomy certification standards vary between Australia's DSTG, India's DRDO, and Japan's Acquisition, Technology and Logistics Agency, fragmenting development roadmaps.
- Secure datalink integration:National encryption protocols prevent interoperability between allied platforms during multilateral exercises, forcing redundant communication hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Military Unmanned Vehicles Market |
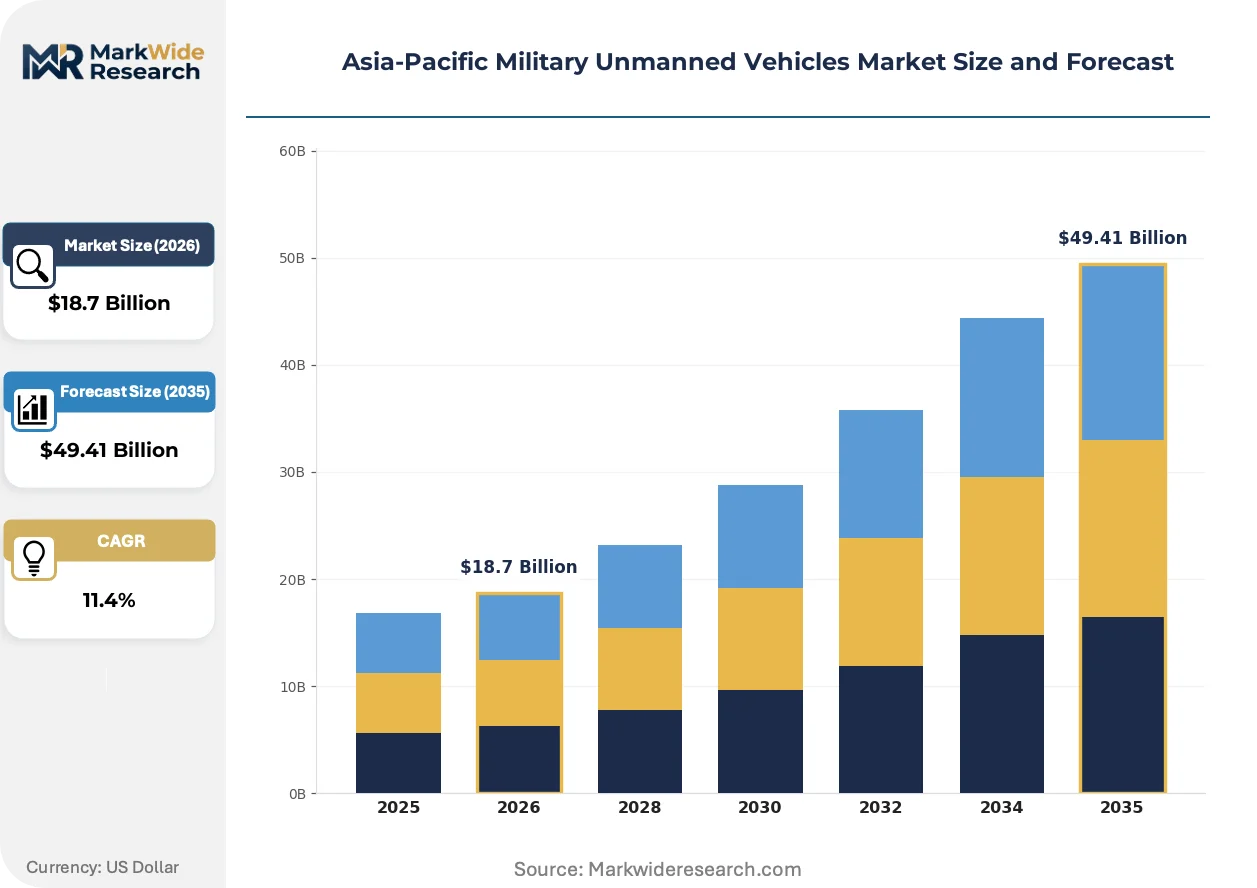
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing UAVs, Rotary-Wing UAVs, Ground Robots, Underwater Vehicles Technology: GPS Navigation, Autonomous Control, Remote Piloted, Sensor Fusion End User: Defense Forces, Military Contractors, Research Institutions, Security Agencies Application: Surveillance, Reconnaissance, Cargo Transport, Target Acquisition |
| Companies Covered | Korea Aerospace Industries, Elbit Systems Ltd, China Aerospace Science and Technology Corporation, ST Engineering, The Boeing Company, Hindustan Aeronautics Limited, Defence Research and Development Organisation, General Atomics, Mitsubishi Heavy Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Military Unmanned Vehicles Market Strategic Shifts
Autonomy architectures are displacing remote-piloted paradigms across maritime patrol missions. Platform developers now embed decision-support algorithms that reduce operator workload during extended ocean surveillance sorties.
Hyperspectral imaging payloads are converging with synthetic aperture radar on single airframes. Republic of Korea Navy procurement officers specify these fused sensor packages for East Sea maritime patrol contracts. This convergence compresses the distinction between dedicated ISR and targeting platforms, forcing suppliers to design modular payload bays rather than mission-specific configurations.
Australia's Defence Trade Controls Act amendments tighten technology transfer scrutiny for unmanned vehicle subsystems. Foreign primes seeking to supply the Royal Australian Navy must now demonstrate sovereign maintenance capabilities for encrypted command modules. Naval helicopter replacement programs absorb the most regulatory attention, with local content thresholds rising for maintenance, repair, and overhaul contracts.
Consolidated fleet contracts are displacing platform-by-platform acquisition across Southeast Asian defense ministries. Indonesian and Malaysian procurement offices now bundle air, surface, and subsurface unmanned requirements into single tender documents. This pattern concentrates vendor selection authority within centralized defense acquisition agencies, reducing individual service branch discretion over specification development.
Asia-Pacific Military Unmanned Vehicles Market Segmentation
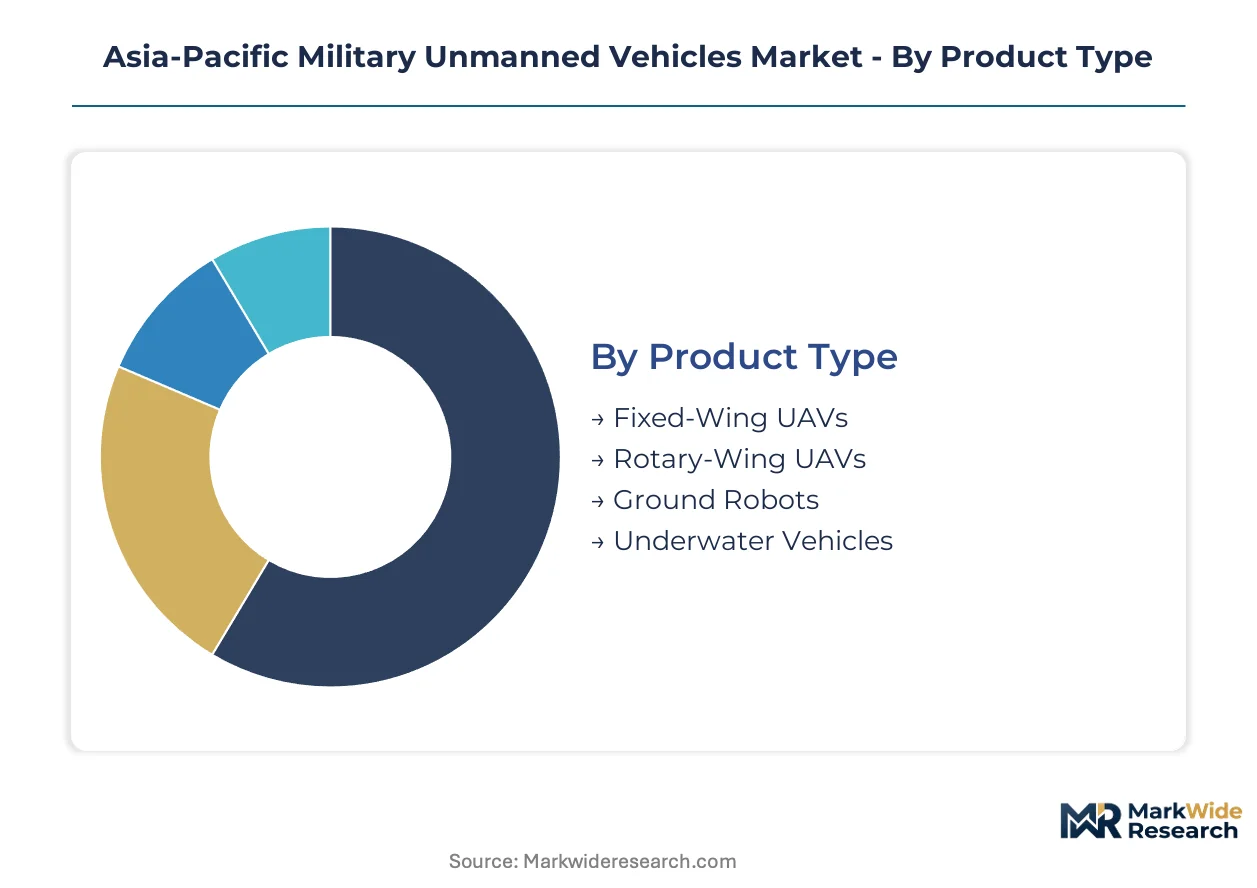
Segmentation in Asia-Pacific military unmanned vehicles reveals how procurement offices balance standardized platforms against mission-specific configurations. Each dimension—product architecture, control systems, buyer type, and operational role—carries distinct certification requirements and supply chain implications.
Product Type:
Customization intensity varies sharply across this category, with some platforms requiring extensive airframe modification while others deploy as standardized units.
- Fixed-Wing UAVs:Extended-range airframes with high-aspect-ratio wings dominate ocean surveillance missions across Australia's northern approaches and Indonesia's outer island chain. Australia's offshore patrol programs and Vietnam's maritime surveillance initiatives drive concentrated demand for satellite-relay-compatible endurance platforms.
- Rotary-Wing UAVs:Vertical-takeoff configurations with foldable rotor systems address shipboard deck constraints and urban canyon operations. Republic of Korea Navy helicopter replacement programs and Japan's Maritime Self-Defense Force destroyer deployments prioritize these for over-the-horizon targeting.
- Ground Robots:Tracked and wheeled platforms with manipulator arms serve explosive ordnance disposal in India's border regions and perimeter security at Thai military installations.
- Underwater Vehicles:Autonomous underwater vehicles with magnetic anomaly detection payloads address submarine surveillance gaps in Philippine and Vietnamese littoral waters.
Leading the category by volume: Fixed-Wing UAVs. Expanding most quickly: Underwater Vehicles as submarine detection requirements mature.
Technology:
Cost tier separation distinguishes legacy remote-piloted systems from autonomous architectures requiring advanced software verification.
- GPS Navigation:Multi-constellation receivers integrating GPS, GLONASS, and BeiDou signals provide resilient positioning in contested electromagnetic environments. India's DRDO mandates indigenous receiver modules for tactical systems, compressing supplier margins through local assembly quotas.
- Autonomous Control:Decision-support algorithms with collision-avoidance protocols reduce operator workload during extended maritime patrol sorties. Australia's DSTG certification protocols impose 18-24 month electromagnetic interference testing delays, constraining deployment timelines for autonomous platforms.
- Remote Piloted:Line-of-sight radio links with encrypted command modules remain standard for tactical drones below strategic endurance thresholds.
- Sensor Fusion:Synthetic aperture radar and hyperspectral imaging convergence on single airframes addresses Republic of Korea Navy East Sea patrol specifications.
Commanding the highest certification burden: Autonomous Control. Gaining share fastest: Sensor Fusion as multi-spectral requirements consolidate.
End User:
Volume concentration clusters with defense forces, while research institutions and contractors occupy specialized procurement channels with distinct contracting mechanisms.
- Defense Forces:National military services with consolidated fleet procurement authority dominate platform acquisition across Indonesia's and Malaysia's centralized defense acquisition agencies. India's Defence Research and Development Organisation enforces indigenous content thresholds that reshape supplier economics.
- Military Contractors:Private firms operating under government contract provide operational support and maintenance services, particularly for Australia's sovereign maintenance requirements under Defence Trade Controls Act amendments.
- Research Institutions:Australia's Defence Science and Technology Group and Japan's Acquisition, Technology and Logistics Agency fund experimental autonomy and undersea vehicle programs.
- Security Agencies:Border control and coast guard services in Thailand and the Philippines deploy tactical systems for frontier monitoring without full military certification.
Procurement volume concentrates with: Defense Forces. Steepest expansion trajectory: Research Institutions as experimental platforms transition toward operational status.
Application:
Margin structure separates surveillance missions with sustained platform utilization from cargo transport requiring specialized payload integration.
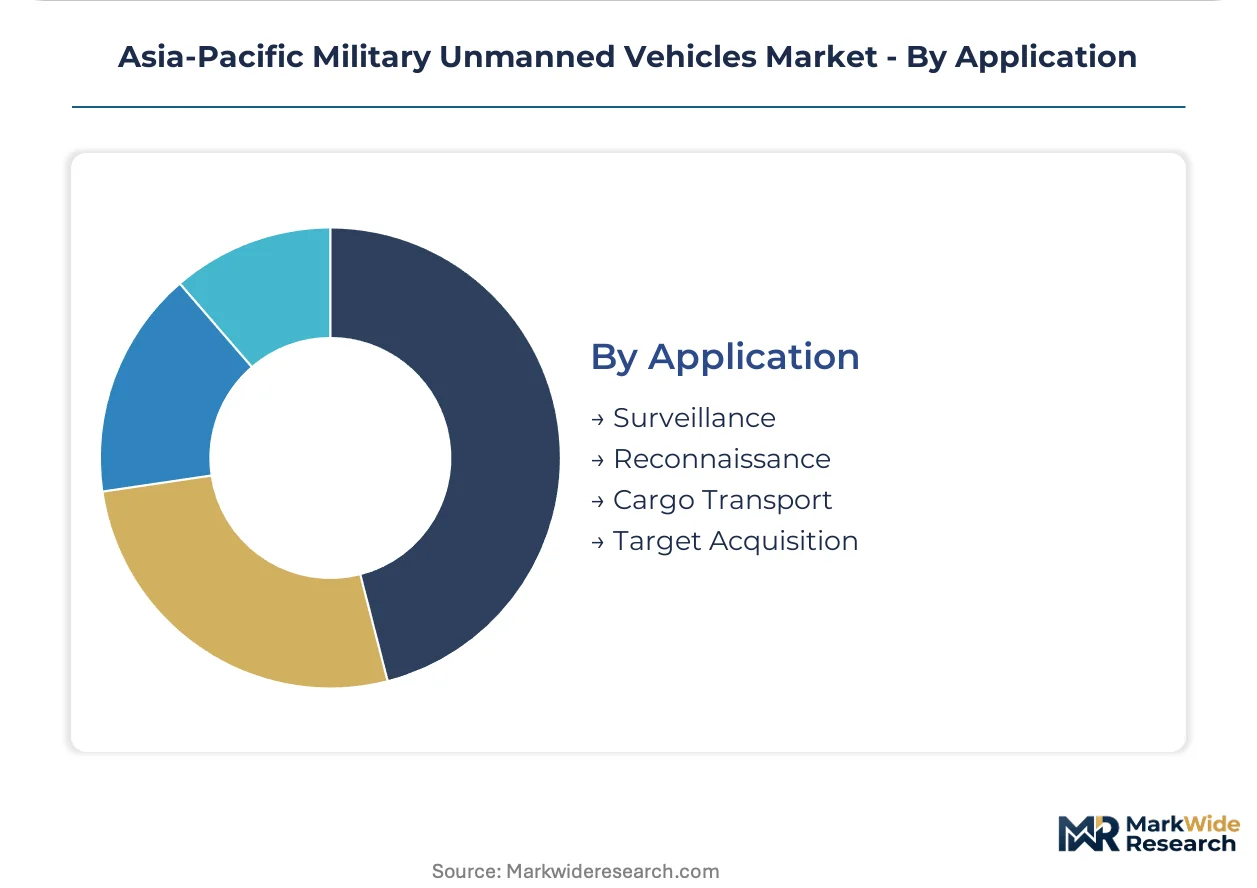
- Surveillance:Wide-area ocean monitoring with electro-optical and radar payloads absorbs the largest platform deployment across Southeast Asian littoral states. Indonesia's archipelagic geography creates distributed requirements favoring medium-altitude long-endurance systems over satellite alternatives.
- Reconnaissance:Time-sensitive target identification with penetrating sensor packages supports forward-deployed units in contested environments. Japan's METI dual-use framework enables maritime radar subsystem exports to regional allies, expanding component access.
- Cargo Transport:Logistical resupply drones with heavy-lift rotors address last-mile distribution to remote island garrisons.
- Target Acquisition:Laser designator and rangefinder integration for precision strike coordination occupies specialized mission profiles.
Platform hours concentrate in: Surveillance. Climbing the fastest: Cargo Transport as distributed logistics requirements mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in South Korea, China, and Israel, while consumption spreads across littoral states from Australia to Vietnam. Defense ministries in consuming nations compress procurement timelines to address maritime surveillance gaps. Local assembly mandates reshape supplier economics throughout the region.
Australia
Offshore patrol programs and northern territory monitoring absorb the largest platform deployment in the region. The Defence Trade Controls Act amendments tighten technology transfer scrutiny for encrypted command modules, forcing foreign primes to demonstrate sovereign maintenance capabilities. Defence Science and Technology Group certification protocols in Canberra impose extended electromagnetic interference testing that delays deployment by 18-24 months.
India
Border surveillance and indigenous platform development drive concentrated demand for tactical and strategic systems. The Defence Research and Development Organisation enforces tightened indigenous content requirements through production-linked incentives that attract foreign OEM assembly lines. Bangalore and Hyderabad host emerging maintenance clusters where local firms absorb subsystem integration work previously executed offshore.
South Korea
Maritime patrol modernization and East Sea surveillance requirements anchor procurement volume. Korea Aerospace Industries leverages its KUS-series UAV lineage to capture naval helicopter replacement contracts. The Acquisition, Technology and Logistics Agency coordinates dual-use export frameworks that enable maritime radar subsystem sales to regional allies.
Japan
Shipboard deployment and urban terrain operations drive rotary-wing platform interest across the Maritime Self-Defense Force. The Ministry of Economy, Trade and Industry relaxed export controls on sensor subsystems, expanding component market access for regional partners. Nagoya and Yokohama manufacturing clusters specialize in high-reliability avionics for contested electronic warfare environments.
Vietnam
Submarine detection and littoral surveillance gaps in the South China Sea compress platform acquisition timelines. Magnetic anomaly detection payloads on long-endurance UAVs address undersea surveillance requirements that satellite alternatives cannot satisfy. Da Nang and Ho Chi Minh City serve as maintenance hubs where regional contractors integrate imported airframes with locally sourced ground control stations.
Asia-Pacific Military Unmanned Vehicles Market Competitive Environment
Top-tier vendors anchor sovereign defense industrial bases, while mid-tier specialists occupy component and subsystem niches. The market structure reflects national security imperatives that privilege domestic primes for complete platform delivery. Three archetypes dominate: state-owned aerospace conglomerates with captive military markets, defense-electronics specialists with sensor-integration expertise, and diversified industrial groups leveraging dual-use manufacturing capabilities. Competitive positioning hardens around local assembly quotas and sovereign maintenance mandates rather than pure technology differentiation.
Within the state-owned tier, China Aerospace Science and Technology Corporation and Hindustan Aeronautics Limited exemplify the vertically integrated model where platform development, manufacturing, and military certification concentrate under single corporate umbrellas. Korea Aerospace Industries and Mitsubishi Heavy Industries occupy a distinct position as export-oriented primes serving both domestic forces and regional allies. Elbit Systems Ltd and ST Engineering represent the defense-electronics specialist archetype, anchoring competitive positioning on sensor fusion and command-and-control integration rather than complete airframe production. These groupings illustrate how national industrial policy shapes competitive boundaries more than technical performance metrics alone.
| Leading Market Players |
|---|
| Korea Aerospace Industries |
| Elbit Systems Ltd |
| China Aerospace Science and Technology Corporation |
| ST Engineering |
| The Boeing Company |
| Hindustan Aeronautics Limited |
| Defence Research and Development Organisation |
| General Atomics |
| Mitsubishi Heavy Industries |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between sovereign-qualified platforms and import-dependent systems manifests in both procurement premiums and supply chain localization mandates. India's PLI scheme and Australia's DSTG protocols compress margins on foreign OEMs while elevating pricing power for domestic assemblers meeting indigenous content thresholds.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid certification turnaround with contract premiums, while extended DSTG electromagnetic testing timelines force discounting on delayed deliveries. Three-tier pricing structure across sovereign-maintained, locally assembled, and fully imported systems reflects Australia's Defence Trade Controls Act compliance costs alongside India's DRDO assembly quotas. Pricing pressure stems from gallium nitride component supply volatility concentrated in Chinese and US fabrication facilities. Defense acquisition agencies exhibit lowest price sensitivity for autonomous maritime platforms with magnetic anomaly detection payloads, while border security agencies drive hardest bargaining on tactical rotary-wing systems.
Supply Chain Analysis
Certification gating through Australia's DSTG, India's DRDO, and Japan's Acquisition, Technology and Logistics Agency fragments supplier qualification pathways and extends component validation cycles. GaN semiconductor fabrication concentrates in China and the United States, while high-reliability avionics cluster in Nagoya and Yokohama manufacturing hubs. Raw material dependencies span carbon fiber airframes, encrypted command modules, and multi-constellation GPS receivers. Single-source vulnerability in phased-array radar substrates exposes regional primes to export restriction volatility. Distribution runs through sovereign maintenance depots in Bangalore, Da Nang, and Canberra where local firms absorb subsystem integration previously executed offshore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform delivery timelines stretch under certification bottlenecks, with electromagnetic interference testing protocols propping pricing for qualified suppliers. Sovereign maintenance mandates constrain capacity expansion and sustain margin premiums for compliant vendors.
For Market Incumbents: Lock in sovereign maintenance contracts before Australia's Defence Trade Controls Act amendments tighten further, and secure gallium nitride supply agreements to hedge against Chinese export restriction volatility. Korea Aerospace Industries and Elbit Systems face margin compression from India's PLI scheme attracting foreign OEM assembly lines, requiring backward integration into encrypted command module production to preserve differentiation. For New Entrants and Emerging Players: Enter via Indonesia's outer island chain distributed surveillance requirements, where medium-altitude long-endurance platforms face limited satellite competition and centralized defense acquisition agencies bundle multi-domain unmanned tenders. Thailand's border monitoring modernization along the Myanmar frontier offers the most penetrable entry point, with shipboard rotary-wing deployments for urban terrain operations providing a follow-on expansion vector. For Investors and Strategic Acquirers: Exit pathways concentrate in defense-electronics specialists with sensor fusion capabilities rather than airframe manufacturers facing local content mandates. Long-term viability over a five-to-ten-year window hinges on autonomy algorithm maturity for contested electronic warfare environments. Acquisition targets should demonstrate proven over-water endurance and sovereign maintenance infrastructure. The signal to watch is submarine detection payload integration transitioning from experimental to operational status across Philippine and Vietnamese naval procurement offices.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Maintenance Capability Buildout | Australia's Defence Trade Controls Act amendments mandate encrypted command module servicing within national borders. |
| GaN Semiconductor Supply Agreement | Phased-array radar production hinges on fabrication access concentrated in Chinese and US facilities. |
| Autonomy Algorithm Certification Investment | DSTG, DRDO, and ATLA protocol fragmentation demands redundant software verification roadmaps. |
| Archipelagic Surveillance Platform Deployment | Indonesia's outer island chain creates distributed requirements favoring medium-altitude long-endurance systems. |
| Submarine Detection Payload Integration | Magnetic anomaly detection on long-endurance UAVs addresses undersea surveillance gaps in Philippine and Vietnamese littoral waters. |
Study Parameters
Multi-period observation of procurement timelines, certification protocol amendments, and platform deployment schedules anchored the trend analysis, supplemented by interviews with defense acquisition officers, UAV program managers, electromagnetic testing engineers, and sovereign maintenance facility directors. Secondary validation drew from defense ministry budget disclosures, tender documentation from Indonesia's centralized defense acquisition agency, India's PLI scheme administrative records, and customs data on GaN semiconductor trade flows. Bottom-up platform delivery tracking and top-down defense expenditure allocation modeling were triangulated to reconcile volume estimates.
Segment-weighting across fixed-wing, rotary-wing, ground robot, and underwater vehicle architectures informed value distribution modeling throughout the projection horizon. Technology tiers separating GPS navigation, autonomous control, remote piloted, and sensor fusion systems were cross-referenced against end-user categories spanning defense forces, military contractors, research institutions, and security agencies. Application segmentation across surveillance, reconnaissance, cargo transport, and target acquisition missions shaped utilization-rate assumptions. CAGRs were derived from procurement pipeline analysis and indigenous content threshold implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden export restriction imposition on GaN components or accelerated submarine detection payload maturation. Forecasts reflect assumptions regarding electromagnetic interference testing timeline stability and PLI scheme continuity. A model refresh is warranted upon material change in Australia's Defence Trade Controls Act enforcement posture or India's DRDO indigenous content requirement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
US Autonomous Navigation Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Tethered Manned Submersible Market
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
North America ROV Market
Unmanned Systems
North America Hyperloop Technology Market
Unmanned Systems
North America AUV Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
Europe Military Unmanned Vehicles Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Anti-UAV Defence System (AUDS) Market
Unmanned Systems
Automated Weapon System Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Global Anti-Drone System Market