
 Asia-Pacific Unmanned Surface Vehicle (USV) Market | 2026-2036
Asia-Pacific Unmanned Surface Vehicle (USV) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Unmanned Surface Vehicle (USV) Market Outlook
Software-defined mission payloads is pivoting vendor economics from hardware sales to recurring capability upgrades. China Aerospace Science and Technology Corporation leverages its state-backed vertical integration to dominate domestic naval tenders. Elbit Systems Ltd. competes through combat-proven autonomous navigation suites. Mitsubishi Heavy Industries anchors its position via shipyard-scale manufacturing and JIS-certified quality systems.
An Unmanned Surface Vehicle (USV) is a self-propelled watercraft operating without onboard crew, typically spanning two to fifteen meters in hull length and integrating GPS waypoint navigation with real-time sensor fusion for maritime task execution. These platforms perform mine countermeasures, hydrographic survey, and littoral zone patrol where crewed operations carry excessive risk or cost. Autonomous Surface Vehicles command premium pricing due to AI-driven collision avoidance and reduced operator burden, while Sonar Systems represents the fastest-growing technology segment as seabed mapping demands intensify across the Pacific Rim. Defense end users generate the dominant revenue share, though Environmental Monitoring applications are expanding fastest as coral reef and pollution tracking programs multiply.
Japan's METI enforces maritime robotics safety protocols through JIS standards certification, while Australia's TGA-equivalent functional regulator for marine equipment mandates electromagnetic compatibility testing for coastal operations. China's SAMR and MIIT jointly oversee USV product registration, creating a dual-approval pathway that extends market entry timelines for foreign suppliers. Stakeholders must monitor evolving certification reciprocity agreements between Japan, South Korea, and Australia, as harmonized standards will reshape competitive access across the region's procurement pipelines.
Market Dynamics
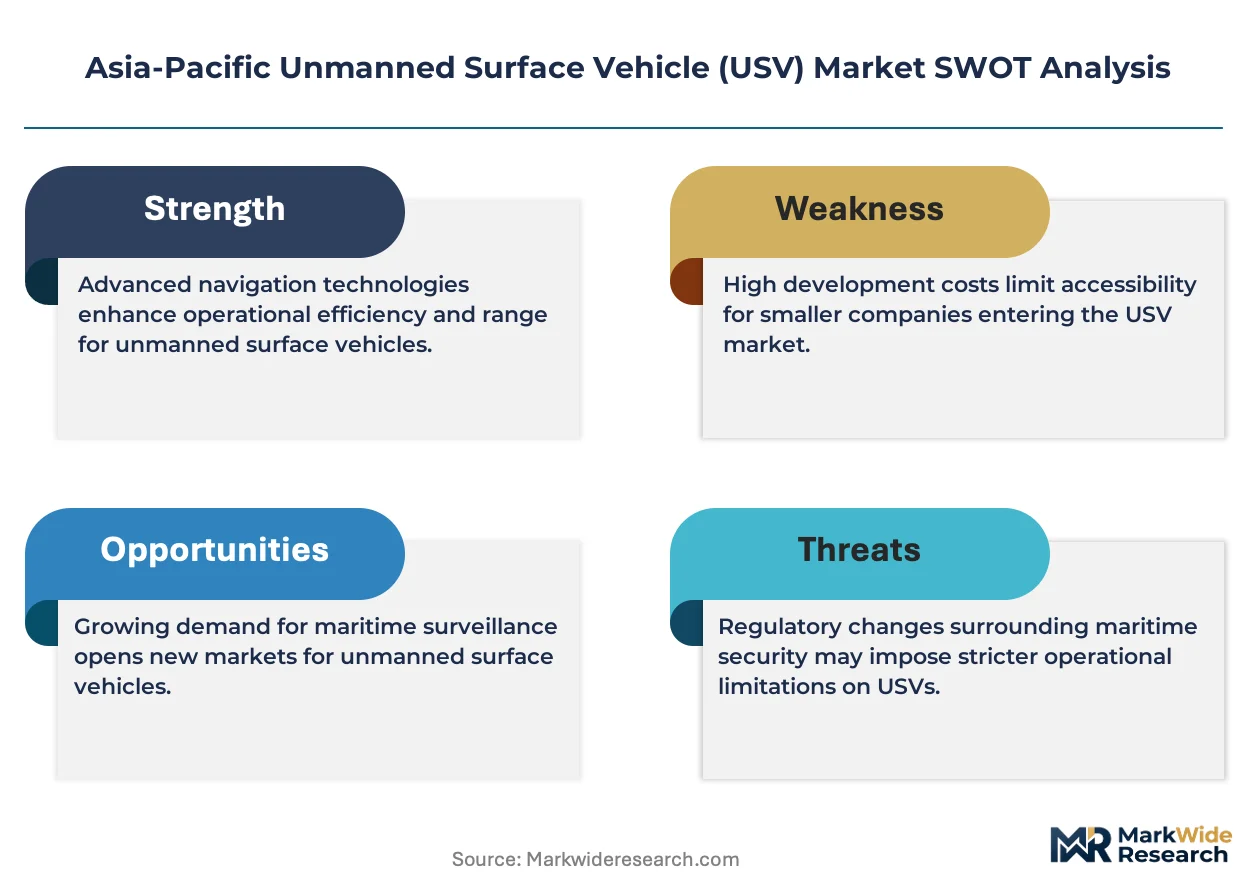
Software-defined mission payloads are compressing hardware replacement cycles across Asia-Pacific naval fleets, forcing vendors to build recurring revenue through over-the-air capability upgrades rather than hull sales.
Growth Catalysts
- MIIT Certification Mandates:China's tightening maritime drone product standards under MIIT and SAMR dual-approval pathways are filtering subscale suppliers and consolidating procurement toward certified domestic producers.
- Offshore Energy Expansion:Australia's Browse Basin and Scarborough field developments require persistent seabed survey coverage that crewed vessels cannot economically provide.
- AI Collision Avoidance:Machine-vision-based navigation suites are reducing operator burden per vessel, allowing single shore stations to manage larger autonomous fleets.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cathode precursor processing concentrates in Chinese chemical hubs, exposing non-Chinese hull integrators to input cost volatility and export licensing risk.
- JIS Certification Timelines:Japan's METI enforcement of maritime robotics safety protocols through JIS standards extends product validation to 18-24 months for foreign suppliers.
- Crewed Patrol Craft Substitution:Manned fast attack craft remain cost-competitive for short-duration littoral missions under 12 nautical miles, limiting USV addressable share in coastal defense budgets.
Strategic Opportunities
- Vietnam's Spratly Infrastructure:Hanoi is expanding maritime domain awareness spending across Cam Ranh and Phu Quy, creating first-mover advantage for sonar-integrated surface drones.
- Coral Reef Monitoring:Australia's Great Barrier Reef Marine Park Authority is scaling autonomous water quality sampling, opening recurring service contracts for environmental monitoring specialists.
- South Korea-Australia Reciprocity:Harmonized electromagnetic compatibility testing standards between MFDS and Australia's functional marine regulator would compress dual-market entry costs for sensor suppliers.
Industry Challenges
- Autonomy Software Talent Scarcity:Maritime path-planning algorithm development requires hybrid naval architecture and machine learning expertise that concentrates in Singapore and Sydney talent pools.
- Legacy Fleet Integration:ASEAN navies operating 1970s-era command-and-control infrastructure face datalink incompatibility with IP-based USV communication protocols.
- Seawater Corrosion Certification:Extended salt spray testing for carbon-fiber hulls adds 8-12 months to product qualification cycles under Japan's JIS B 7725 standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Unmanned Surface Vehicle (USV) Market |
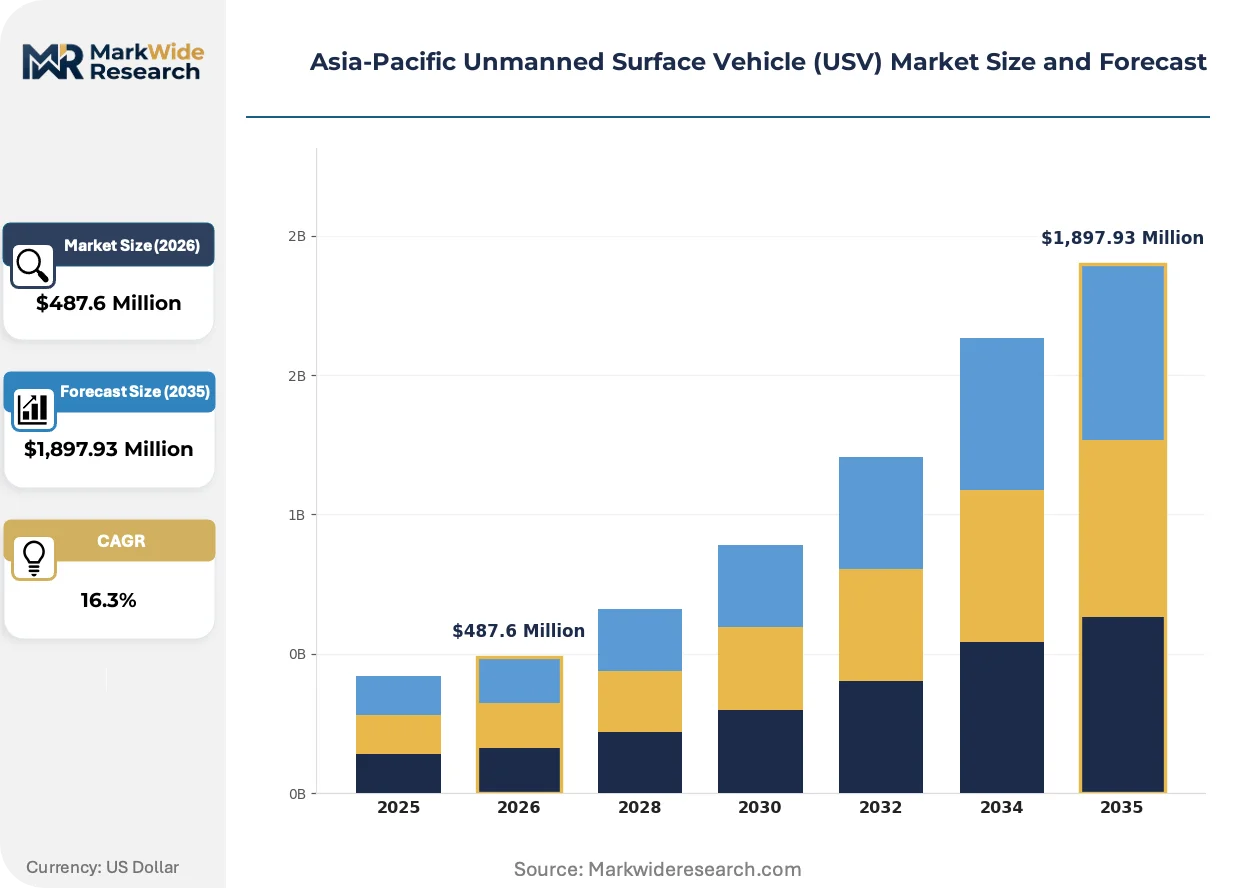
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,897.93 Million |
| CAGR (2026 – 2036) | 16.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote-Controlled Boats, Autonomous Surface Vehicles, Hybrid USVs, Unmanned Underwater Vehicles End User: Defense, Fisheries, Oceanographic Research, Environmental Monitoring Technology: GPS Navigation, LiDAR, Sonar Systems, Communication Technologies Application: Search and Rescue, Surveillance, Cargo Transport, Data Collection |
| Companies Covered | China Aerospace Science and Technology Corporation, Hindustan Aeronautics Limited, Elbit Systems Ltd., Mitsubishi Heavy Industries, Korea Aerospace Industries, L3Harris Technologies, Inc., China North Industries Group Corporation, ST Engineering, Exail Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Unmanned Surface Vehicle (USV) Market Strategic Shifts
Payload modularity and regulatory harmonization are converging to reshape how Asia-Pacific navies contract for maritime autonomous capability, compressing traditional shipyard-led procurement cycles.
Edge-deployed neural networks for real-time object classification are unifying previously separate sonar, electro-optical, and radar processing streams into single onboard inference engines. Royal Australian Navy mine countermeasures units are field-testing these integrated perception stacks during 2024-2025 exercises. This convergence is unifying sensor subsystem procurement under single-vendor payload contracts, marginalizing standalone sonar suppliers.
METI's 2023 revision to JIS C 1010 maritime electrical safety standards now mandates redundant kill-switch architectures for autonomous vessels operating beyond visual line of sight. Japanese shipyards are redesigning power distribution networks to accommodate failsafe isolation circuits. The change most affects sub-7-meter inspection-class USVs, where form-factor constraints previously precluded dual-redundant safety systems.
Defense procurement officers across Southeast Asia are bundling 10-year through-life support into initial hull acquisitions, displacing traditional spot-maintenance contracting. Malaysia's Maritime Enforcement Agency and Indonesia's Bakamla have both issued multi-year service-integrated tenders since 2023. This pattern is most visible in mine countermeasures programs, where seabed mapping algorithm updates must keep pace with evolving threat signatures.
Asia-Pacific Unmanned Surface Vehicle (USV) Market Segmentation
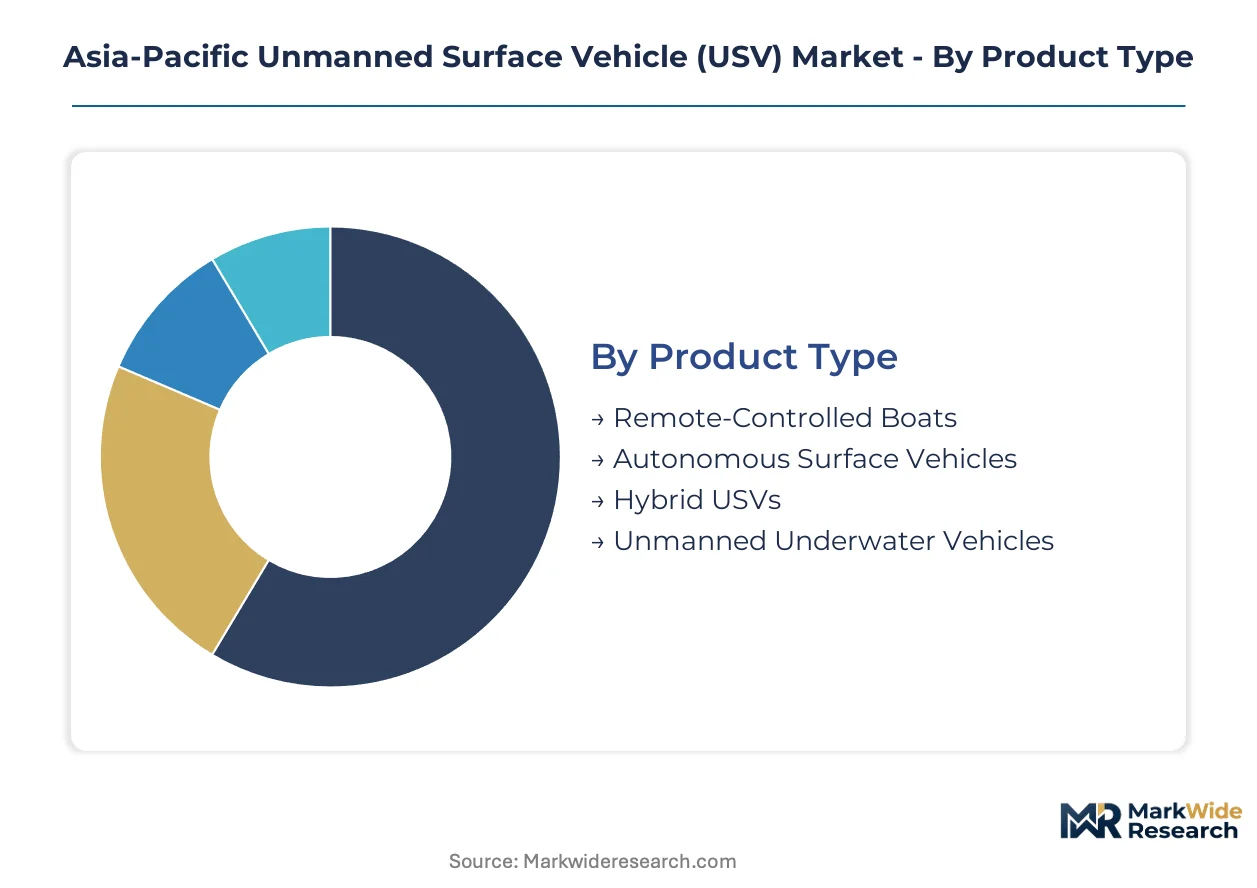
USV procurement patterns diverge sharply across Asia-Pacific defense ministries and commercial operators, with certification requirements and mission endurance specifications filtering supplier access. Segmentation reveals how hardware specifications, end-use mandates, and sensor architectures reshape competitive positioning across the region's procurement pipelines.
Product Type:
Autonomous capability tiers define procurement budgets and operator training requirements across naval and commercial fleets.
- Autonomous Surface Vehicles:These platforms integrate AI-driven collision avoidance with multi-sensor fusion, commanding premium pricing from defense ministries prioritizing reduced operator burden. Japan's Maritime Self-Defense Force specifications for beyond-visual-line-of-sight operations concentrate demand here.
- Remote-Controlled Boats:Tethered operator control via radio or satellite link dominates nearshore inspection and harbor security applications. Cost sensitivity among Southeast Asian coast guards restricts addressable share despite lower unit prices.
- Hybrid USVs:Switchable autonomy modes accommodate contested electromagnetic environments where jamming threatens continuous command links.
- Unmanned Underwater Vehicles:Subsurface propulsion systems serve seabed cable inspection and mine countermeasures in Australia's offshore energy corridor.
Autonomous Surface Vehicles leads on scale; Hybrid USVs leads on momentum.
End User:
Procurement authority structures determine contract size and technology access tiers across the region.
- Defense:Mine countermeasures and littoral patrol dominate naval budgets, with Australia's Royal Australian Navy and Japan's Maritime Self-Defense Force driving multi-vessel program awards. Classification requirements and secure datalink mandates elevate barriers for non-domestic suppliers.
- Environmental Monitoring:Autonomous water quality sampling and coral reef tracking programs are expanding most quickly across Australia's Great Barrier Reef Marine Park Authority and Indonesia's marine protected areas.
- Oceanographic Research:University consortia and national science agencies deploy persistent survey platforms for seabed mapping and current profiling.
- Fisheries:Illegal fishing patrol and stock assessment applications concentrate in Vietnam and Philippines coastal enforcement budgets.
Defense commands procurement volume; Environmental Monitoring shows steepest expansion trajectory.
Technology:
Sensor integration architectures determine platform mission flexibility and through-life upgrade economics.
- Sonar Systems:Multibeam and side-scan configurations serve seabed classification and mine detection, with Australia's Browse Basin energy developments requiring persistent coverage. Real-time bathymetric processing demands edge-computing payloads that compress hardware replacement cycles.
- GPS Navigation:Differential and RTK-corrected positioning enables precise waypoint following for survey corridors and patrol patterns.
- LiDAR:Above-waterline 3D mapping supports shoreline erosion monitoring and port infrastructure inspection.
- Communication Technologies:Mesh radio, satellite, and acoustic modem suites enable command continuity across contested or deep-water operating areas.
Sonar Systems leads on scale; Communication Technologies leads on momentum.
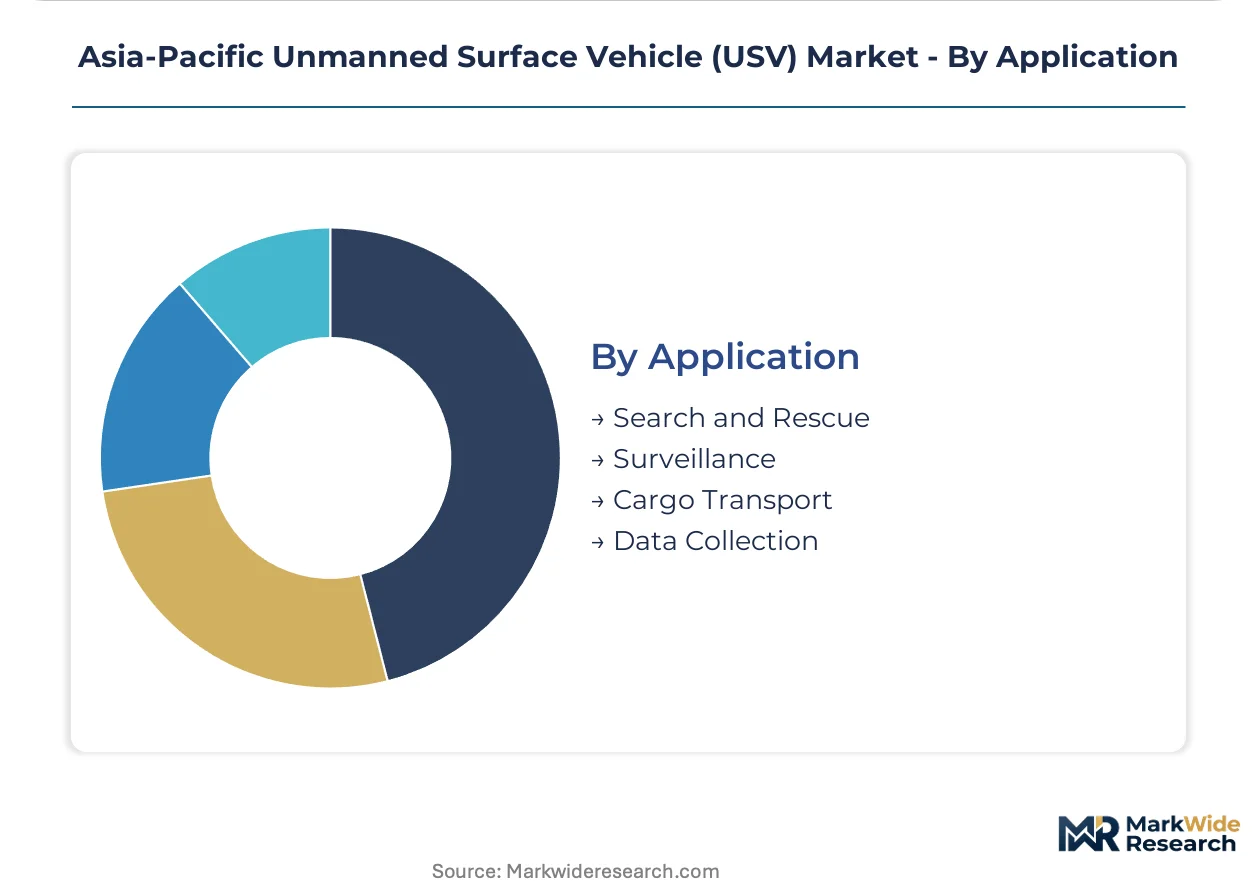
Application:
Mission duration and payload modularity requirements segment procurement across operational use cases.
- Surveillance:Persistent maritime domain awareness missions across Vietnam's Cam Ranh and Indonesia's Natuna Islands require extended-endurance hulls with electro-optical and radar payloads. Crewed patrol craft substitution economics favor autonomous platforms beyond 12-nautical-mile zones.
- Search and Rescue:Rapid deployment specifications and thermal imaging integration concentrate demand among coast guards and maritime safety agencies.
- Data Collection:Hydrographic survey and oceanographic sensor hosting support commercial energy and scientific research contracts.
- Cargo Transport:Short-haul logistics trials in Singapore and Japan port complexes test autonomous supply chain integration.
Surveillance leads on scale; Data Collection leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates naval procurement volume while Australia drives commercial seabed survey demand, creating divergent certification pathways across the Asia-Pacific USV landscape.
China
MIIT and SAMR dual-approval pathways for maritime drones filter foreign suppliers while consolidating procurement toward certified domestic producers. State-backed vertical integration dominates naval tender awards. Qingdao and Shanghai clusters anchor hull manufacturing and sensor subsystem production.
Japan
METI enforces JIS C 1010 maritime electrical safety standards with redundant kill-switch mandates for beyond-visual-line-of-sight operations. Maritime Self-Defense Force specifications concentrate demand for premium autonomous platforms. Nagoya shipyards redesign power distribution networks to accommodate failsafe isolation circuits.
Australia
Browse Basin and Scarborough field developments require persistent seabed survey coverage that crewed vessels cannot economically provide. The functional marine equipment regulator mandates electromagnetic compatibility testing for coastal operations. Perth anchors offshore energy corridor procurement.
South Korea
MFDS electromagnetic compatibility standards position Seoul for reciprocity agreements with Australian regulators. Defense procurement bundles through-life support into initial hull acquisitions. Busan-Ulsan shipbuilding clusters integrate autonomous navigation suites into existing naval construction workflows.
Vietnam
Hanoi expands maritime domain awareness spending across Cam Ranh and Phu Quy, creating first-mover advantage for sonar-integrated surface drones. Coastal enforcement budgets concentrate on illegal fishing patrol applications. Da Nang shipyards explore hybrid autonomy mode integration for contested electromagnetic environments.
Asia-Pacific Unmanned Surface Vehicle (USV) Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with defense procurement favoring integrated platform providers while commercial survey contracts fragment among sensor-agnostic hull integrators. State-affiliated conglomerates anchor naval tender awards through captive certification access. Three archetypes dominate: vertically integrated aerospace-defense conglomerates, shipyard-scale manufacturers with JIS-certified quality systems, and combat-proven autonomy suite specialists. Competitive moves concentrate on regulatory reciprocity lobbying and payload modularity roadmaps.
Within the state-affiliated tier, China Aerospace Science and Technology Corporation exemplifies vertical integration advantages in domestic certification pathways. Elbit Systems Ltd. and Mitsubishi Heavy Industries occupy positions bridging defense-proven autonomy with shipyard-scale production capacity. These three anchors represent distinct competitive vectors: state-backed certification access, combat-tested navigation software, and JIS-certified manufacturing scale.
| Leading Market Players |
|---|
| China Aerospace Science and Technology Corporation |
| Hindustan Aeronautics Limited |
| Elbit Systems Ltd. |
| Mitsubishi Heavy Industries |
| Korea Aerospace Industries |
| L3Harris Technologies, Inc. |
| China North Industries Group Corporation |
| ST Engineering |
| Exail Technologies |
| Others |
Value Chain & Pricing Dynamics
Japan's METI-mandated redundant kill-switch architectures under JIS C 1010 standards gate qualified supply for beyond-visual-line-of-sight autonomous vessels, compressing premium-tier pricing access to shipyards with certified failsafe isolation circuits and dual-redundant safety system integration capabilities.
Pricing Analysis
Capacity additions in South Korean shipbuilding clusters are reshaping price floors for autonomous navigation suites as Busan-Ulsan yards integrate USV production into existing naval workflows. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified defense platforms from commercial survey hulls and harbor inspection craft. Cost compression in the standard tier intensifies because Chinese hull integrators leverage cathode precursor supply advantages. Environmental monitoring agencies exhibit highest price sensitivity, while Japan's Maritime Self-Defense Force specifications tolerate premium positioning for redundant safety architectures.
Supply Chain Analysis
China's domestic-content mandates under MIIT and SAMR dual-approval pathways are reshaping sourcing patterns for foreign sensor suppliers seeking naval tender access. Lithium-ion battery cell production concentrates in China, South Korea, and Japan, with cathode precursor processing anchored in Chinese chemical hubs. Carbon-fiber hull fabrication draws from Japanese and South Korean composite suppliers, while edge-computing chipsets hinge on Taiwanese foundry output. Single-source vulnerability runs through concentrated cathode chemical processing. Distribution runs through defense procurement offices for naval programs and energy sector contractors for commercial seabed survey.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where MIIT certification mandates and JIS safety protocol revisions continuously elevate compliance barriers, with China's 2023 tightening of maritime drone product standards driving sustained demand for certified platform providers.
For Market Incumbents: Anticipate margin compression from state-backed Chinese vertical integration by accelerating JIS certification reciprocity lobbying across South Korea and Australia. Prioritize payload modularity roadmaps that lock in through-life service contracts, as Malaysia's Maritime Enforcement Agency and Indonesia's Bakamla displace spot-maintenance procurement with bundled 10-year support agreements.
For New Entrants and Emerging Players: Shipyard partnerships in Vietnam's Da Nang cluster offer the most penetrable entry channel for hybrid autonomy mode integration targeting contested electromagnetic environments. Target Hanoi's expanding maritime domain awareness spending across Cam Ranh and Phu Quy with sonar-integrated surface drone offerings. Pursue environmental monitoring service contracts through Australia's Great Barrier Reef Marine Park Authority as a recurring revenue beachhead.
For Investors and Strategic Acquirers: Roll-up economics work for combat-proven autonomy suite specialists because defense procurement bundling favors integrated platform providers over standalone sensor vendors. Five-to-ten-year viability centers on regulatory reciprocity harmonization between Japan, South Korea, and Australia compressing dual-market entry costs. Watch for South Korea-Australia electromagnetic compatibility testing standard alignment as the inflection signal for sensor supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| JIS Certification Reciprocity Lobbying | Harmonized standards between METI and MFDS compress dual-market entry timelines for foreign suppliers. |
| Payload Modularity Roadmap Investment | Software-defined mission payloads displace hardware replacement cycles with recurring capability upgrade revenue. |
| Shipyard Partnership in Vietnam | Da Nang clusters exploring hybrid autonomy modes create first-mover positioning for contested environment applications. |
| Through-Life Service Contract Bundling | Malaysia's Maritime Enforcement Agency tenders since 2023 favor multi-year support-integrated procurement patterns. |
| Environmental Monitoring Service Specialization | Great Barrier Reef Marine Park Authority scaling autonomous water quality sampling opens recurring contract streams. |
Study Parameters
Multiple input streams — naval procurement officer interviews, shipyard production data, and regulatory filing analysis — were reconciled across primary fieldwork with defense ministry planners, commercial energy survey contractors, maritime robotics engineers, and certification compliance specialists. Secondary validation drew from MIIT product registration databases, JIS standards revision notices, Australian electromagnetic compatibility test reports, and customs trade records for hull and sensor subsystem flows. Bottom-up vessel deployment counts and top-down defense budget allocation analysis provided cross-referencing discipline.
Historical procurement volume patterns were cross-referenced against panel input from platform integrators and end-user specification evolution across the projection horizon. Segmentation modeling spanned autonomy tier, end-use mandate, sensor architecture, and regional certification pathway. CAGRs were derived from installed base expansion rates and unit economics trajectories. Forecast inputs incorporated seabed survey intensity from Australia's Browse Basin developments and littoral patrol substitution economics beyond 12-nautical-mile zones.
Revisions become necessary when regulatory reciprocity agreements materialize ahead of projected timelines or when lithium-ion battery export licensing regimes shift abruptly. Forecasts reflect documented assumptions on certification timeline stability and defense budget continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market
Unmanned Systems
Military Autonomous Robot Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
Aerostat System Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
North America Unmanned Surface Vehicle (USV) Market
Unmanned Systems
North America Hyperloop Technology Market
Unmanned Systems
Dismounted Soldier Systems Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
Military Robotics Market
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market