
 UAV Parachute Recovery Systems Market | 2026-2036
UAV Parachute Recovery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Parachute Recovery Systems Market Analysis
FAA Part 107 waivers and EASA's Specific Category certification is consolidating the competitive landscape around proven airworthiness credentials. ParaZero Ltd. leverages its Israeli aviation heritage to sustain certification momentum across European jurisdictions. BRS Aerospace anchors the North American market through decades of manned-aircraft parachute expertise repurposed for unmanned platforms. Drone Rescue Systems GmbH competes on precision-guided deployment architectures tailored to multirotor geometries.
UAV parachute recovery systems are pyrotechnic or pneumatically activated descent-control apparatuses comprising a packed canopy, deployment mortar or compressed-gas launcher, and an automatic trigger system sensing attitude anomalies or commanded failures; they function to arrest terminal velocity and protect ground assets and personnel from uncontrolled falling drones. Fixed-wing configurations dominate current procurement volumes due to higher kinetic energy at stall and greater payload values at risk. Ballistic deployment methods lead the technology hierarchy for sub-five-second activation requirements, while guided canopy systems represent the fastest-growing segment as urban drone density intensifies precision-landing demands. Nylon remains the baseline material for cost-sensitive civilian applications, whereas Kevlar and composite blends command premium positioning in military and tactical end-use categories where abrasion resistance and packing density constrain design trade-offs.
FAA, EASA, and ISO 21384-3 collectively shape product standards by mandating independent flight-termination systems and documenting recovery-system performance under declared failure modes. Military end-users impose supplemental STANAG or MIL-STD qualifications that extend development cycles but create substantial barriers to unauthorized supply. Stakeholders must monitor evolving overflight liability regimes and pre-position certification assets before jurisdictional thresholds tighten.
Market Dynamics
Ballistic deployment architectures are compressing activation timelines below four seconds, forcing manufacturers to re-engineer mortar geometries and sensor fusion algorithms or lose military procurement eligibility.
Growth Catalysts
- EASA Specific Category mandates:Fail-safe parachute systems are now compulsory for drone operations above populated European urban zones, creating immediate retrofit demand across existing commercial fleets.
- Military kinetic-energy thresholds:Fixed-wing UAV programs in the United States require ballistic recovery for stall speeds exceeding sixty knots, locking in specification requirements for defense contractors.
- Kevlar-composite packing density:Abrasion-resistant canopy materials are enabling smaller mortar diameters without sacrificing load ratings, opening installation options for compact multirotor airframes.
Market Restraints
- Pyrotechnic actuator supply concentration:European mortar initiator production clusters in Germany's aerospace corridor around Munich, creating single-source vulnerability for non-European assemblers.
- Nylon feedstock volatility:Cost-sensitive civilian applications depend on petroleum-derived baseline materials exposed to polymer commodity price swings.
- STANAG qualification timelines:NATO standardization protocols extend military product development cycles by eighteen to thirty-six months versus commercial equivalents.
Strategic Opportunities
- Urban air mobility corridors:Precision-guided canopy systems for eVTOL passenger vehicles represent unpenetrated demand in emerging Dubai and Singapore regulatory frameworks.
- FAA Part 135 equivalent certification:Commercial drone delivery waivers beyond visual line of sight are mandating redundant recovery systems for package-carrying platforms.
- Sensor-canopy convergence:Integration of lidar-guided descent with autonomous inflation timing is creating performance differentiation in high-density European airspace.
Industry Challenges
- Aerodynamic simulation talent scarcity:Computational fluid dynamics expertise for ballistic deployment modeling concentrates in established aviation engineering hubs, constraining new entrant hiring.
- Multi-jurisdictional certification stacking:Simultaneous FAA, EASA, and ISO 21384-3 compliance requires parallel documentation streams that exhaust mid-cap development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Parachute Recovery Systems Market |
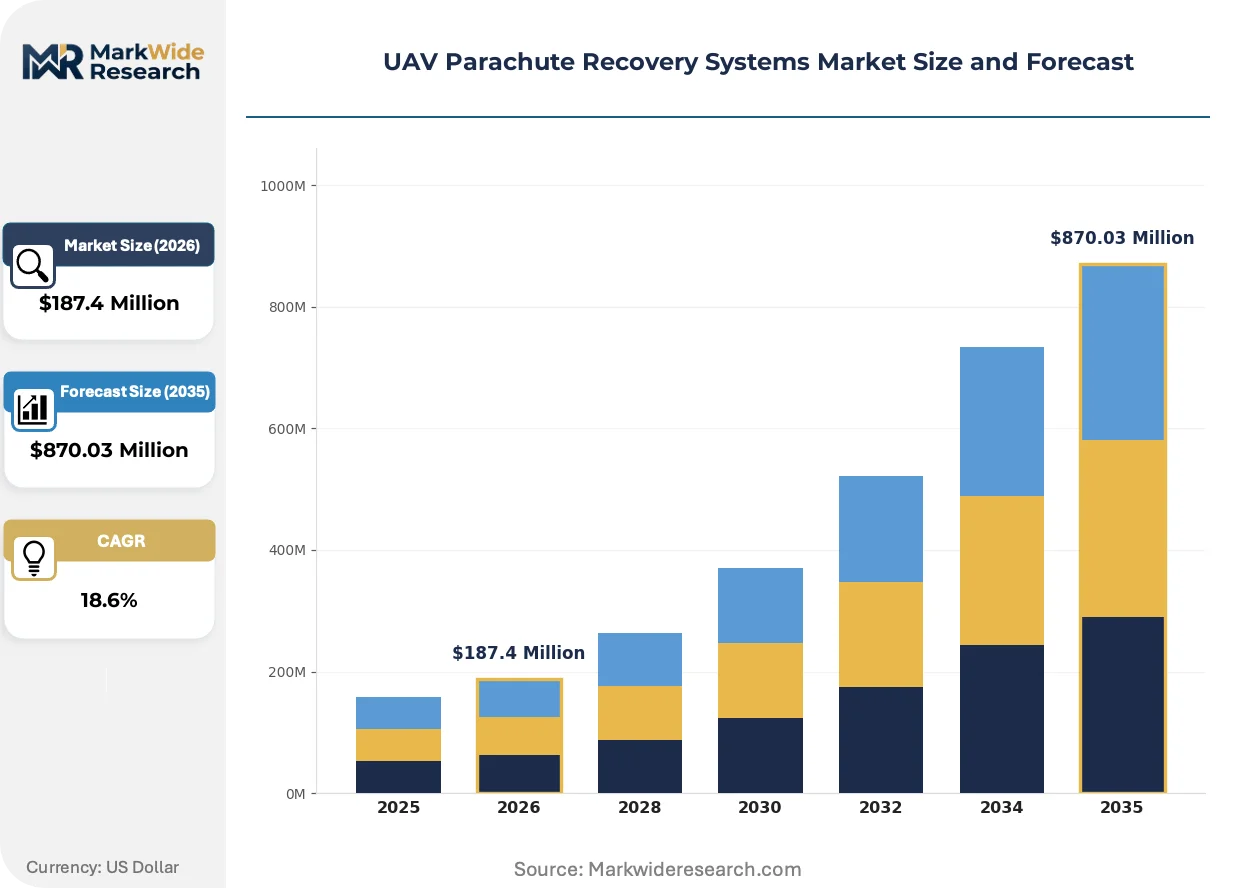
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Wing, Rotary Wing, Hybrid, Tactical Deployment Method: Ballistic, Guided, Automatic, Manual End User: Military, Civilian, Commercial, Research Material: Nylon, Kevlar, Polyester, Composite |
| Companies Covered | Indemnis, Galaxy GRS, ParaZero Ltd., CIMSA Ingeniería de Sistemas S.A., BRS Aerospace, Butler Parachute Systems, Fruity Chutes, EKOFASTBA S.L., Drone Rescue Systems GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Parachute Recovery Systems Market Emerging Trajectories
Autonomous trigger logic and precision landing algorithms are redefining performance benchmarks, compressing the gap between military reliability requirements and civilian cost constraints.
Electro-pneumatic launcher systems are automating deployment sequence calibration through real-time pressure modulation based on altitude and attitude telemetry. Agricultural spraying operators in Australia's Queensland corridor are retrofitting these units to heavy-lift hexacopters ahead of the 2025 harvest certification deadline. The technology is automating what previously required manual pre-flight mortar pressure settings, reducing ground crew training from days to hours.
EASA's drone certification framework is mandating independent flight-termination architectures with documented mean-time-between-failure calculations for operations over European urban centers. Manufacturers must now submit parachute performance data under declared failure modes including total power loss and control surface jam. Fixed-wing cargo platforms operating between German distribution hubs face the steepest compliance curve due to higher kinetic energy at operational altitude.
Certification-driven procurement is consolidating buyer preference around airworthiness credential holders rather than specification-matching vendors. European logistics operators are bypassing uncertified component suppliers entirely, directing contracts toward EASA-notified-body-approved system integrators. This pattern is most visible in Germany's Munich-Augsburg aerospace manufacturing cluster, where procurement departments now embed parachute recovery clauses into every platform RFP regardless of intended operational airspace.
UAV Parachute Recovery Systems Market Segmentation
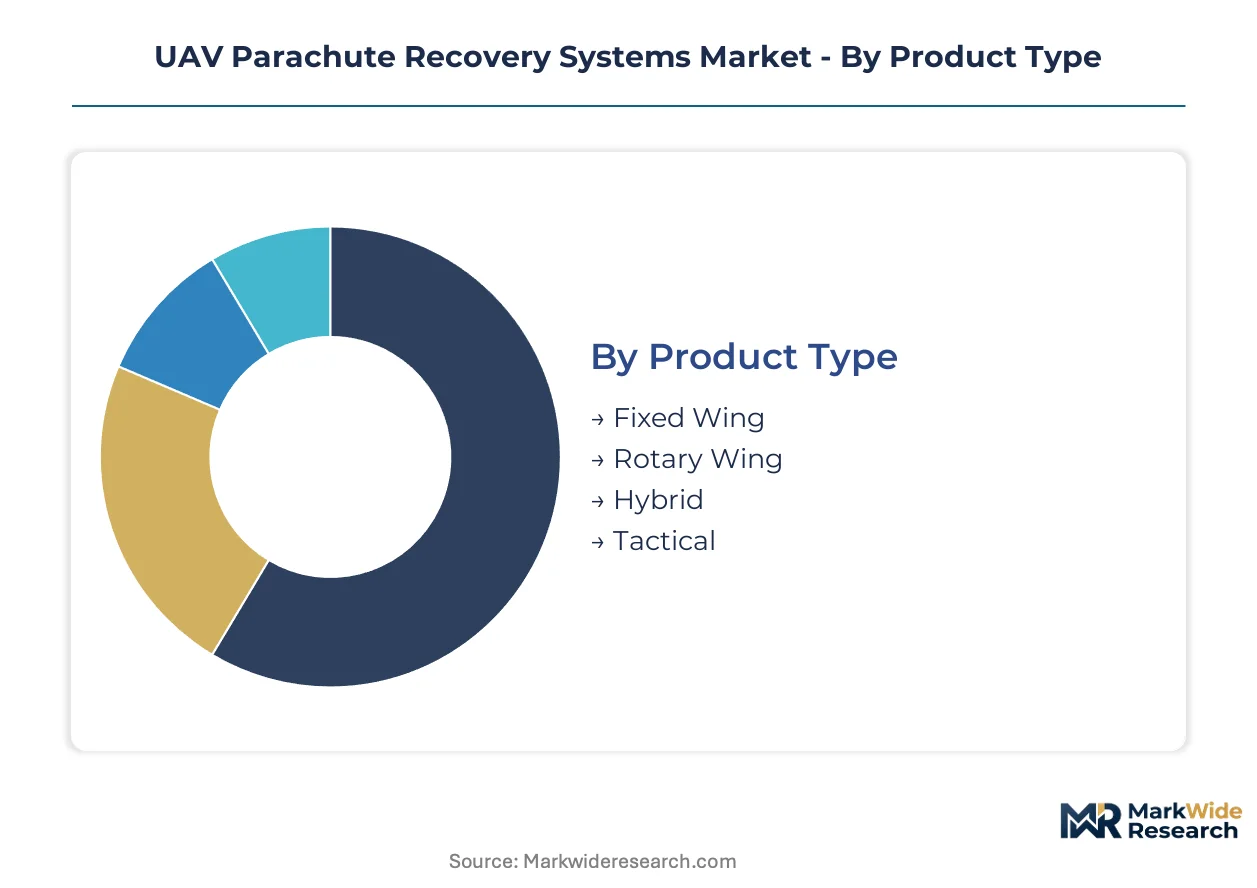
Segmentation in UAV parachute recovery systems reveals how capital allocation, regulatory pressure, and platform physics concentrate procurement decisions. Platform geometry and kinetic energy profiles dictate mortar specifications, while certification requirements filter supplier eligibility across end-use categories.
Product Type:
Capital intensity peaks where platform mass and stall speeds demand reinforced mortar housings and redundant trigger architectures.
- Fixed Wing:High-aspect-ratio platforms generate substantial kinetic energy at stall, necessitating ballistic mortars with reinforced carbon-fiber housings and dual-redundant pyrotechnic initiators. United States military procurement channels dominate volume, with defense contractors specifying STANAG-qualified systems for surveillance platforms exceeding fifty-knot approach speeds.
- Rotary Wing:Multirotor geometries impose tight payload budgets and center-of-gravity constraints, driving demand for compact electro-pneumatic launchers with real-time pressure modulation. German logistics operators in the Munich-Augsburg corridor are mandating these units for urban delivery fleets under EASA Specific Category compliance.
- Hybrid:Tilt-rotor and transitional configurations require adaptive deployment logic switching between fixed-wing ballistic and rotary-wing guided modes based on real-time flight phase detection.
- Tactical:Hand-launched and tube-deployed platforms prioritize minimal weight and silent deployment, employing compressed-gas systems with sub-three-second activation thresholds for special operations units.
Fixed Wing absorbs the bulk of installed capacity; Rotary Wing is expanding most quickly.
Deployment Method:
Engineering complexity and sensor fusion requirements stratify development budgets across activation architectures.
- Ballistic:Pyrotechnic mortar systems achieve sub-four-second canopy inflation through high-impulse propellant charges, with EASA mandating documented mean-time-between-failure calculations for urban overflight certification. Military kinetic-energy thresholds in NATO procurement specifications lock in this method for fixed-wing programs.
- Guided:Steerable canopy systems integrate lidar terrain mapping and GPS waypoint navigation, enabling precision landing in confined urban corridors. Singapore and Dubai regulatory frameworks for eVTOL passenger services are driving qualification programs for these architectures.
- Automatic:Attitude-sensor-triggered deployment eliminates pilot response latency, with ISO 21384-3 compliance requiring independent flight-termination system validation.
- Manual:Commanded activation persists in research and developmental flight testing, where operators retain override authority for experimental platform evaluation.
Ballistic deployment retains the largest installed base; Guided systems are climbing the fastest as urban air mobility corridors mature.
End User:
Qualification timelines and liability exposure create divergent procurement economics across customer categories.
- Military:STANAG and MIL-STD qualification protocols extend development cycles by eighteen to thirty-six months, but secure multi-year procurement contracts with substantial barriers to unauthorized supply. United States defense programs anchor volume through fixed-wing surveillance and strike platform mandates.
- Civilian:Agricultural spraying operators in Australia's Queensland corridor are retrofitting electro-pneumatic units ahead of harvest certification deadlines, prioritizing ground-crew training reduction over maximum performance margins.
- Commercial:Last-mile delivery operators face EASA and FAA waiver requirements for beyond-visual-line-of-sight operations, embedding parachute recovery clauses into every platform RFP regardless of intended airspace.
- Research:University and government laboratory programs drive experimental demand for manual-override systems and custom mortar geometries in atmospheric sensing and geophysical survey applications.
Military end-use commands the deepest procurement pipelines; Commercial applications are gaining share fastest as delivery waivers proliferate.
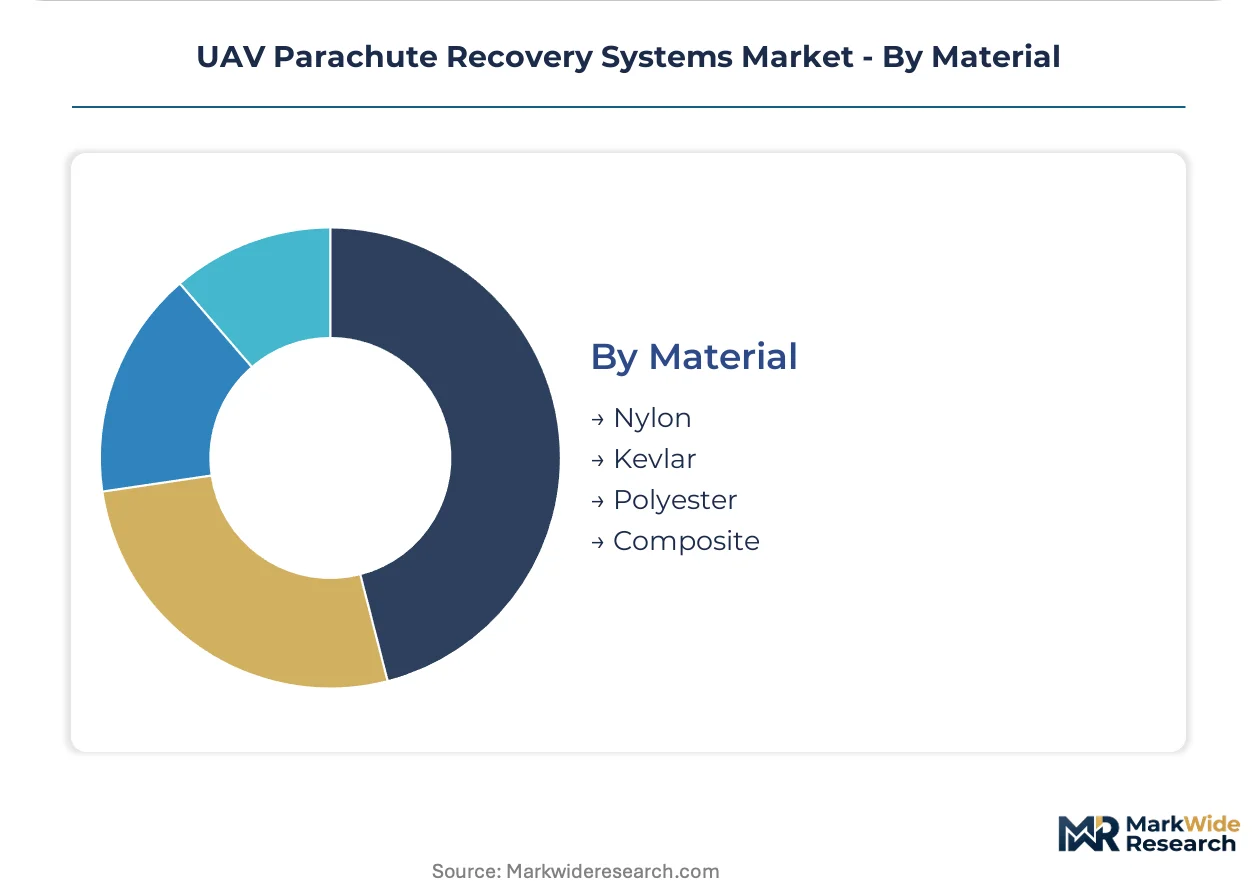
Material:
Raw material selection directly determines packing density, abrasion resistance, and supply chain vulnerability to commodity volatility.
- Nylon:Petroleum-derived polymer remains the cost-sensitive civilian baseline, with feedstock price swings compressing margins for high-volume agricultural and commercial operators.
- Kevlar:Aramid fiber composites enable reduced mortar diameters without load rating sacrifice, opening installation options for compact multirotor airframes where every gram of payload capacity matters.
- Polyester:UV-stabilized variants serve coastal and maritime UAV operations where salt spray and solar degradation accelerate canopy aging.
- Composite:Hybrid aramid-carbon weaves command premium positioning in tactical and high-altitude platforms where extreme temperature cycling and mechanical packing stress converge.
Nylon retains the broadest installed base; Kevlar formulations are expanding most quickly as urban density intensifies payload optimization demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's aerospace manufacturing corridor around Munich and Augsburg operates as a special-economic-zone equivalent for parachute recovery systems, concentrating pyrotechnic actuator production and EASA certification expertise. Military procurement in the United States and commercial mandates across European urban centers are redistributing demand across three continents.
United States
FAA Part 107 waivers for beyond-visual-line-of-sight operations are mandating redundant recovery systems for commercial drone delivery platforms. Military fixed-wing UAV programs require ballistic recovery for stall speeds exceeding sixty knots, locking in defense contractor specifications. The Southwest defense corridor in Texas and Arizona hosts prime contractor integration facilities for surveillance and strike platforms.
Germany
EASA Specific Category certification mandates fail-safe parachute systems for drone operations above populated urban zones, creating immediate retrofit demand across existing commercial fleets. STANAG qualification protocols extend development cycles but secure multi-year NATO procurement contracts. The Munich-Augsburg aerospace cluster concentrates mortar initiator production and notified-body approval capacity.
Israel
Israeli aviation heritage sustains certification momentum across European jurisdictions for ballistic-deployed recovery units. Military drone programs leverage decades of unmanned platform expertise to penetrate export markets. Tel Aviv-area engineering centers specialize in sensor fusion algorithms for sub-four-second activation timelines.
Australia
Agricultural spraying operators in Queensland are retrofitting electro-pneumatic launcher systems ahead of 2025 harvest certification deadlines. CASA regulations mirror FAA trajectory on beyond-visual-line-of-sight waivers for heavy-lift hexacopters. Brisbane-based distributors are automating deployment sequence calibration to reduce ground crew training from days to hours.
Singapore
Urban air mobility regulatory frameworks for eVTOL passenger services are driving qualification programs for precision-guided canopy systems. The Civil Aviation Authority of Singapore mandates documented mean-time-between-failure calculations for operations over dense metropolitan corridors. Seletar Aerospace Park hosts integration facilities for lidar-guided descent technologies.
UAV Parachute Recovery Systems Market Vendor Landscape
United States producers anchor the defense-contractor tier; European specialists hold the civilian certification tier. The vendor base stratifies between airworthiness credential holders and specification-matching component suppliers. Three archetypes dominate: legacy manned-aircraft parachute repurposers, precision-guided deployment architects, and electro-pneumatic automation specialists. Competitive moves concentrate on geographic expansion through EASA-notified-body partnerships and technology licensing for sensor-canopy convergence.
Within the Israeli heritage tier, ParaZero Ltd. exemplifies certification momentum across multiple European jurisdictions. BRS Aerospace occupies a position among North American repurposers of manned-aircraft expertise. Drone Rescue Systems GmbH sits within the German precision-architecture cluster, representing the Munich-Augsburg concentration of mortar geometry specialization.
| Leading Market Players |
|---|
| Indemnis |
| Galaxy GRS |
| ParaZero Ltd. |
| CIMSA Ingeniería de Sistemas S.A. |
| BRS Aerospace |
| Butler Parachute Systems |
| Fruity Chutes |
| EKOFASTBA S.L. |
| Drone Rescue Systems GmbH |
| Others |
Supply Flow & Price Mechanics
Computational fluid dynamics talent clustering in Tel Aviv-area engineering centers and Munich-Augsburg aerospace corridors feeds labor-cost differentials that widen pricing-tier spreads between STANAG-qualified military systems and cost-sensitive civilian retrofit units.
Pricing Analysis
Short lead-time premiums for STANAG-qualified ballistic mortars command substantial markups over spot-inventory nylon-canopy units sourced from distributors. Three-tier pricing structure across STANAG-certified, EASA-notified-body-approved, and uncertified component levels separates defense contractors from European logistics operators and agricultural retrofitters. Cost compression in the nylon-canopy tier intensifies because petroleum-derived feedstock volatility squeezes margins for high-volume Queensland spraying operators. Agricultural retrofitters exhibit the highest price sensitivity; United States defense programs demonstrate the least.
Supply Chain Analysis
Workforce availability for pyrotechnic actuator engineering concentrates in Germany's Munich-Augsburg corridor, Israel's Tel Aviv metro, and the United States Southwest defense belt. Raw material flows draw from aramid fiber suppliers in the United States, petroleum-derived nylon polymer producers in Asia, and carbon-fiber composite weavers in Japan. Single-source vulnerability for European mortar initiator production creates structural risk for non-European assemblers. Distribution runs through EASA-notified-body-approved system integrators for European urban operators and prime contractor integration facilities for United States military procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: EASA Specific Category mandates for fail-safe parachute systems over populated urban zones erect a barrier-to-entry moat that rewards airworthiness credential holders and excludes specification-matching component vendors.
For Market Incumbents: Lock in certification momentum across multiple European jurisdictions before jurisdictional thresholds tighten further. Deepen backward integration into pyrotechnic actuator production to mitigate single-source vulnerability in Germany's aerospace corridor. Prioritize sensor-canopy convergence R&D to differentiate against emerging electro-pneumatic automation specialists. For New Entrants and Emerging Players: Direct-to-operator digital channels for agricultural retrofit kits in Australia's Queensland corridor bypass incumbent distributor markups and accelerate market penetration. Precision-guided canopy architectures for Singapore and Dubai urban air mobility corridors represent the most penetrable white space. Target electro-pneumatic automation for heavy-lift hexacopters where ground-crew training reduction commands premium pricing. For Investors and Strategic Acquirers: Re-rating potential sits with EASA-notified-body-approved system integrators given accelerating procurement department mandates embedding parachute recovery clauses into every platform RFP. Long-term viability over the next decade hinges on certification asset pre-positioning before regulatory thresholds tighten. Monitor FAA Part 135 equivalent certification progress for commercial drone delivery waivers as the inflection indicator for redundant recovery system mandates.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Notified Body Partnership | Unlocks European urban overflight certification for non-European manufacturers seeking market access. |
| Sensor-Canopy Convergence R&D | Integrates lidar-guided descent with autonomous inflation timing for high-density European airspace differentiation. |
| Backward Integration into Pyrotechnics | Captive supply of mortar initiators mitigates Munich-Augsburg single-source concentration risk. |
| Electro-Pneumatic Automation Scale-Up | Automated deployment calibration reduces agricultural operator ground-crew training from days to hours. |
| STANAG Qualification Investment | Eighteen-to-thirty-six-month development cycles secure multi-year United States defense procurement contracts. |
Methodological Framework
Independent corroboration across primary interviews with UAV platform engineering directors, EASA certification consultants, defense procurement officers, and agricultural operator fleet managers underwrites the qualitative findings. Secondary validation draws from FAA Part 107 waiver databases, EASA Specific Category guidance documents, STANAG qualification protocols, and ISO 21384-3 performance standards. Bottom-up segmentation modeling triangulates against top-down market sizing from defense budget disclosures and commercial drone delivery operator fleet expansion announcements.
Comparable-period anchoring to historical military fixed-wing UAV procurement cycles and European commercial retrofit waves establishes the forecast window baseline. The analytical framework segments across platform geometry, deployment method, end-use category, and material composition throughout the projection horizon. CAGRs derive from installation-base growth rates calibrated to regulatory mandate timelines and kinetic-energy threshold specifications. Industry-specific inputs include ballistic mortar activation timelines and electro-pneumatic pressure modulation adoption curves.
The model holds under sustained EASA and FAA regulatory tightening; deviation in pyrotechnic actuator supply disruptions or petroleum polymer price spikes would shift volume trajectories. Forecasts reflect documented assumption sets regarding certification timeline adherence and urban air mobility corridor activation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
Drone Docking Station Market
Unmanned Systems
Drone Parachute System Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
Military Robotics Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
US Autonomous Navigation Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
Europe Unmanned Surface Vehicle (USV) Market