
 Japan Autonomous Navigation Market | 2026-2036
Japan Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Autonomous Navigation Market Insights
Japan's amended Road Traffic Act is repositioning the liability framework for Level 4 autonomous operations, forcing new compliance investments across the supply chain. Toyota Motor Corporation leverages its domestic manufacturing scale to integrate LIDAR and radar suites in-house, reducing supplier dependency. Honda Motor Company anchors its strategy in motorcycle autonomy, a segment where it competes with limited direct rivalry. Nissan Motor Company specializes in urban robo-taxi architectures, positioning its ProPilot technology for fleet operator trials in designated zones.
Autonomous navigation encompasses sensor fusion systems that synthesize LIDAR point clouds, computer vision feeds, and differential GPS signals to generate real-time positional estimates within centimeter-scale tolerances. These systems execute path planning and obstacle avoidance for mobile platforms operating without continuous human oversight across structured and semi-structured environments. Computer vision and LIDAR technologies dominate current procurement volumes, though edge-computing delivery modes are capturing margin pools as latency requirements tighten for collision-critical decisions. Logistics applications lead deployment counts, while public transportation trials in rural municipalities represent the fastest-growing application segment as labor shortages intensify.
METI's safety certification protocols intersect with JIS standards for autonomous machinery, creating a dual-layer compliance environment that filters out non-domestic component suppliers. PMDA oversight extends to medical-grade autonomous transport within hospital campuses, adding a specialized regulatory channel. Fleet operators and OEMs must monitor prefectural ordinance variations, as Osaka and Aichi have enacted stricter operational zone restrictions than national baselines require.
Market Dynamics
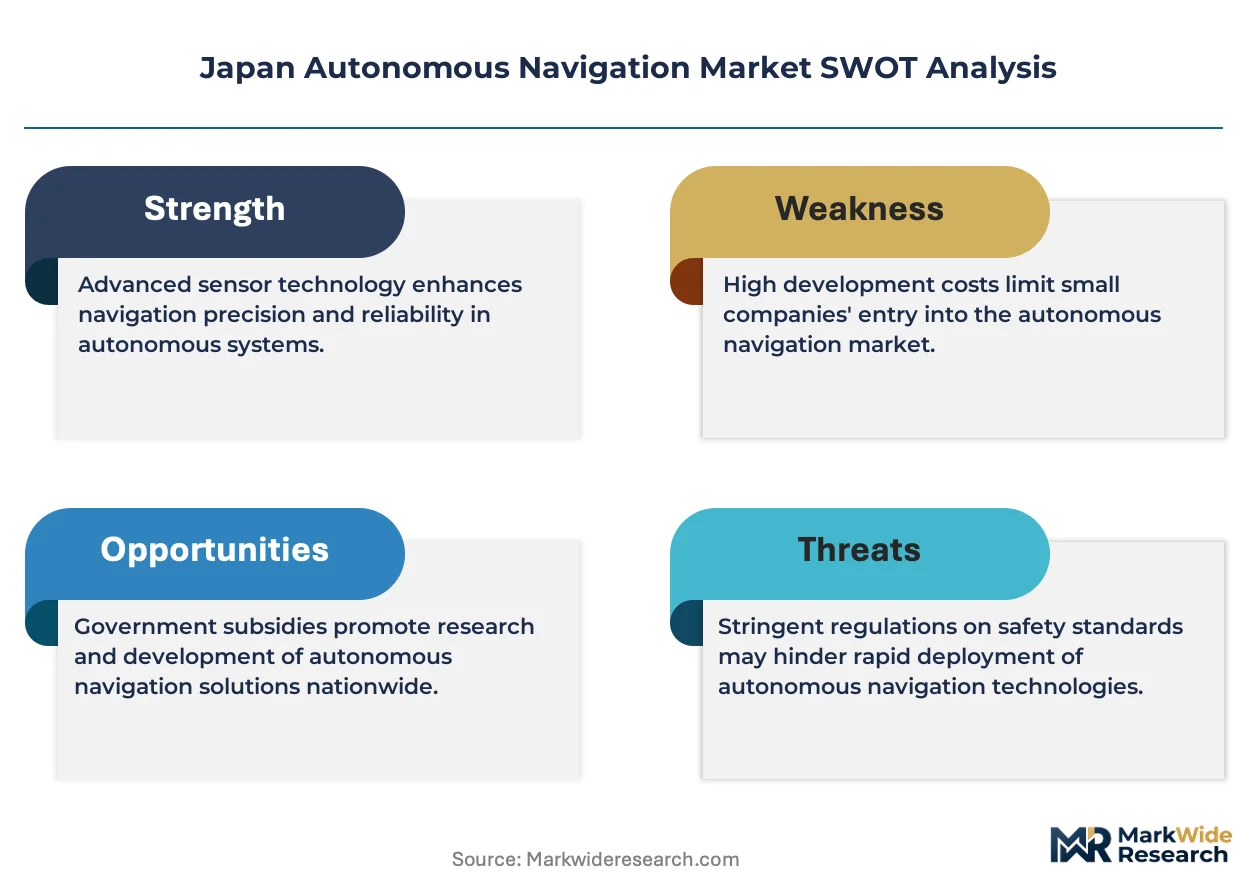
METI's updated safety certification framework is compressing deployment timelines for domestic developers while intensifying compliance investment requirements across the autonomous navigation supply chain. The regulatory acceleration is reshaping competitive positioning toward vertically integrated OEMs with captive certification capabilities.
Growth Catalysts
- Kanto Industrial Corridor Density:Tokyo and Yokohama harbor concentrated automotive OEM and robotics integrator clusters that accelerate technology transfer and pilot program execution. Logistics operators leverage this proximity for rapid system iteration.
- Amended Road Traffic Act:Japan's repositioned liability framework for Level 4 operations is unlocking fleet operator trials in designated urban zones. Municipal governments in rural prefectures are prioritizing autonomous transit to address driver shortages.
- Edge Computing Architectures:Latency-critical collision avoidance decisions are migrating processing from cloud to vehicle-embedded systems. This shift reduces bandwidth dependency and enables real-time path recalculation in tunnel and dense urban environments.
Market Restraints
- LIDAR Sensor Cost Concentration:High-precision optical component supply concentrates among a limited set of specialized manufacturers, creating input cost volatility for system integrators without backward integration into sensor production.
- JIS-METI Dual Compliance:The intersection of industrial standards and safety certification protocols filters out non-domestic component suppliers, constraining sourcing flexibility and extending qualification timelines for foreign technology providers.
- Prefectural Ordinance Fragmentation:Osaka and Aichi enforce stricter operational zone restrictions than national baselines require, creating regulatory friction for fleet operators seeking standardized deployment across multiple jurisdictions.
Strategic Opportunities
- Rural Municipal Transit:Aging demographics and driver shortages in Japan's peripheral prefectures are accelerating public transportation trials. Local governments offer operational subsidies for autonomous shuttle services connecting remote communities to regional hubs.
- Medical-Grade Campus Transport:PMDA oversight of hospital autonomous delivery systems creates a specialized regulatory channel with premium pricing potential. Pharmaceutical and supply chain automation within healthcare campuses represents an underpenetrated application layer.
- Sensor Fusion Convergence:The integration of computer vision feeds with differential GPS and radar inputs is enabling redundant navigation architectures. This technology convergence reduces single-point-of-failure risk and expands operability across weather conditions.
Industry Challenges
- Embedded Systems Engineering Scarcity:Real-time operating system programming and sensor calibration expertise concentrates among a limited talent pool. Robotics integrators compete with automotive OEMs for specialized firmware developers.
- Legacy Fleet Integration Complexity:Warehouse management systems and existing material handling infrastructure require extensive middleware development to interface with autonomous navigation platforms. Retrofit economics strain mid-scale logistics operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Autonomous Navigation Market |
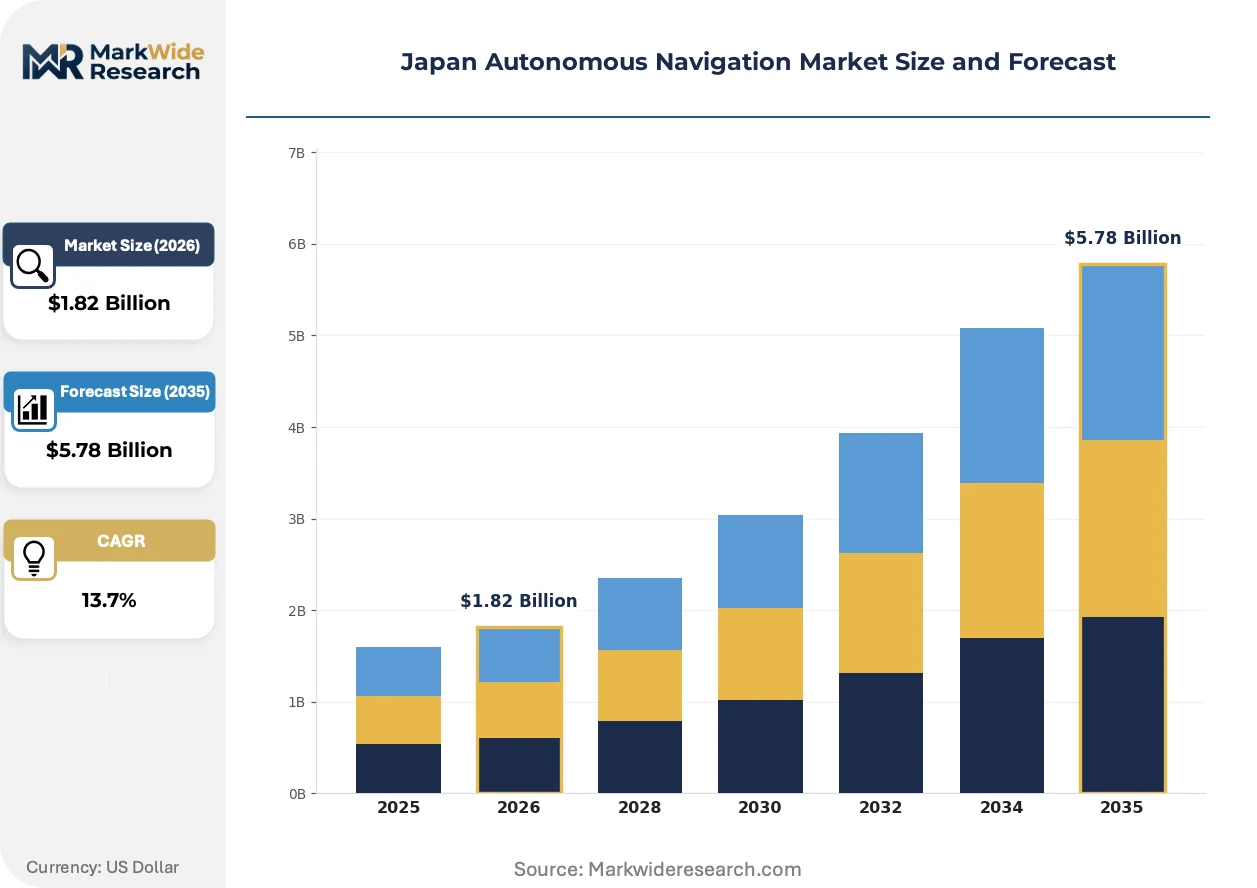
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LIDAR, Computer Vision, Radar, GPS Application: Logistics, Agriculture, Public Transportation, Personal Vehicles End User: OEMs, Tier-1 Suppliers, Fleet Operators, Researchers Delivery Mode: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Toyota Motor Corporation, Honda Motor Company, Nissan Motor Company, Omron Corporation, ABB, Honeywell International, L3Harris Technologies, Northrop Grumman Corporation, Safran, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Autonomous Navigation Market Trends and Innovations
Technology trajectories in Japan's autonomous navigation sector center on computational architecture migration, regulatory pathway clarification, and procurement model restructuring toward performance-based contracting.
Edge computing platforms are converging with 5G network slicing to enable sub-50-millisecond decision loops for collision-critical maneuvers. Tier-1 logistics operators in the Kanto corridor are piloting these architectures for high-density warehouse environments. The technology convergence is compressing cloud dependency and shifting margin capture toward hardware-integrated system vendors with proprietary processing units.
METI's safety certification protocols are intersecting with JIS standards to create a dual-layer compliance environment that filters market participation. Domestic technology developers with established certification track records are capturing disproportionate trial program allocations. Foreign component suppliers face extended qualification timelines, reshaping procurement patterns toward Japan-certified subsystem providers.
Fleet operators are restructuring procurement around availability-based service contracts rather than capital equipment acquisition. Third-party logistics providers in designated autonomous zones are contracting for guaranteed uptime rather than purchasing navigation platforms outright. This behavioral shift is most visible in last-mile delivery trials where operational risk transfer to technology vendors accelerates deployment decisions.
Japan Autonomous Navigation Market Segmentation
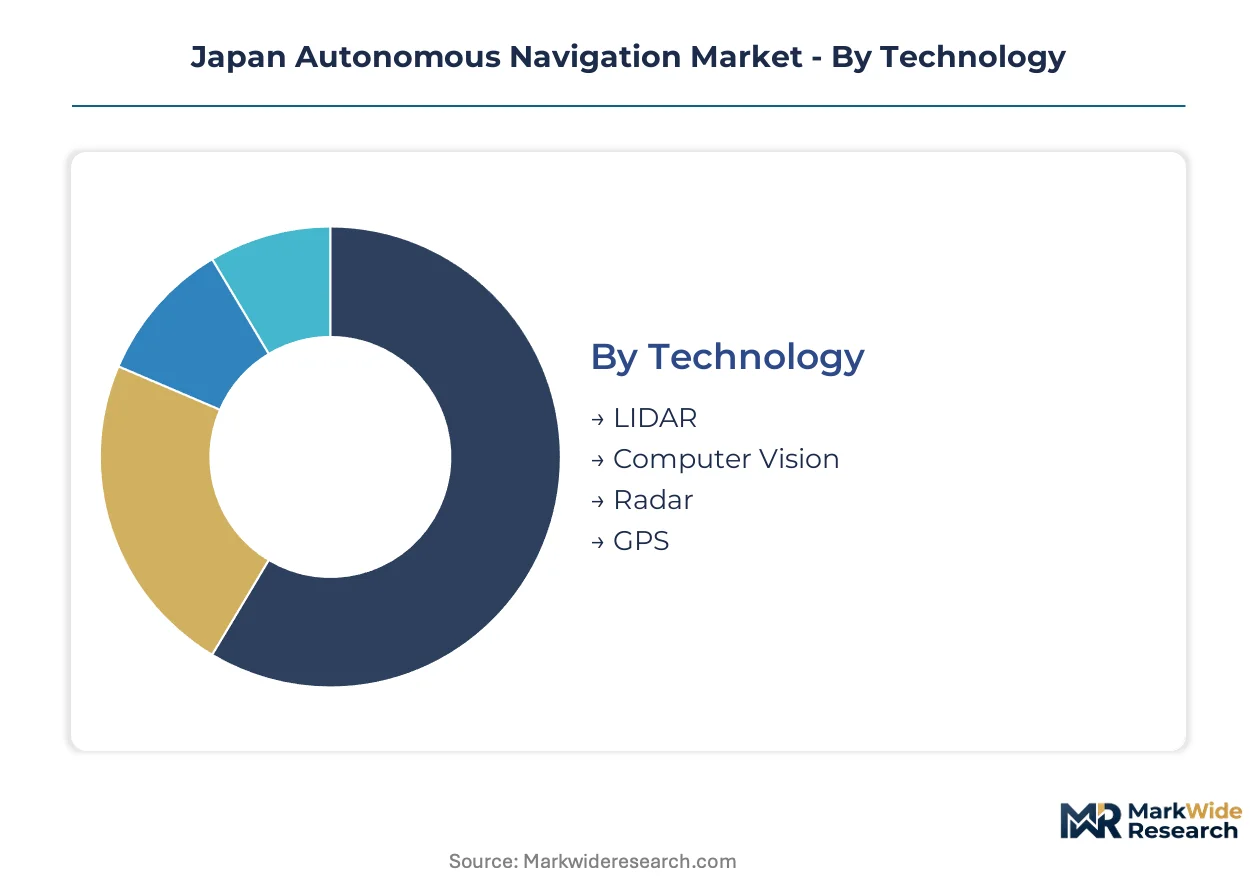
Japan's autonomous navigation market fragments across four structural dimensions that determine integration complexity and procurement patterns. Technology selection dictates sensor fusion architectures, while application context shapes regulatory compliance requirements and operational constraints.
Technology:
Standalone sensing modules dominate warehouse and controlled-environment deployments, whereas embedded multi-sensor arrays penetrate automotive OEM supply chains demanding tighter subsystem integration.
- LIDAR:High-precision optical distance measurement generates dense 3D point clouds for centimeter-scale localization. Procurement concentrates among Kanto corridor logistics operators retrofitting high-density storage facilities; METI safety certification timelines filter non-domestic suppliers and extend qualification cycles.
- Computer Vision:Convolutional neural networks process camera feeds for object classification and lane detection. Automotive OEMs in Tokyo and Yokohama anchor demand as ProPilot-equivalent systems require visual redundancy alongside ranging sensors; edge-computing migration reduces cloud latency for collision-critical decisions.
- Radar:Radio-frequency ranging penetrates precipitation and low-light conditions where optical sensors degrade. Embedded in motorcycle autonomy architectures where Honda anchors development, offering weather-resilient navigation for two-wheeled platforms.
- GPS:Differential satellite positioning provides absolute reference frames for map-matched localization. Rural municipal transit trials in peripheral prefectures leverage this cost-effective baseline for geofenced shuttle routes.
Volume placements concentrate in Computer Vision; the faster expansion belongs to LIDAR as precision requirements tighten for Level 4 operations.
Application:
Cost-tier stratification separates capital-intensive fleet retrofits from subsidized public service deployments, with margin structures diverging sharply across these contexts.
- Logistics:Warehouse AGVs and last-mile delivery platforms execute path planning across structured environments with minimal human oversight. Kanto-based third-party logistics providers pilot availability-based service contracts rather than equipment purchases, transferring operational risk to technology vendors.
- Public Transportation:Autonomous shuttles connect remote communities to regional transit hubs in driver-shortage prefectures. Local governments offer operational subsidies; rural municipalities represent the segment climbing fastest as demographic pressures intensify.
- Agriculture:GPS-guided tractors and harvesters navigate crop rows with sub-meter accuracy. Adoption concentrates in Hokkaido grain operations where field regularity suits automated steering.
- Personal Vehicles:Consumer-grade driver assistance systems operate below Level 3 autonomy thresholds. OEM integration into mass-market platforms depends on JIS-METI dual compliance completion.
Procurement value concentrates in Logistics; the steepest expansion trajectory belongs to Public Transportation as prefectural subsidy programs scale.
End User:
Customer-type stratification reveals divergent technical capabilities, with captive engineering resources determining in-house development versus outsourced subsystem procurement.
- OEMs:Toyota and Nissan maintain vertical integration into sensor fusion software and LIDAR-radar suites, reducing supplier dependency. Certification capabilities accelerate trial program allocations under METI protocols.
- Fleet Operators:Third-party logistics providers contract for guaranteed uptime in designated autonomous zones. Risk transfer to technology vendors compresses deployment timelines for last-mile trials.
- Tier-1 Suppliers:Subsystem integrators serve mid-scale operators lacking embedded systems engineering capacity. Middleware development for legacy warehouse management interfaces strains margins.
- Researchers:University and national laboratory programs advance algorithmic architectures under METI-funded consortia. Procurement volumes remain limited but influence standard-setting pathways.
Contract value concentrates among OEMs; the fastest volume growth belongs to Fleet Operators as availability-based contracting proliferates.
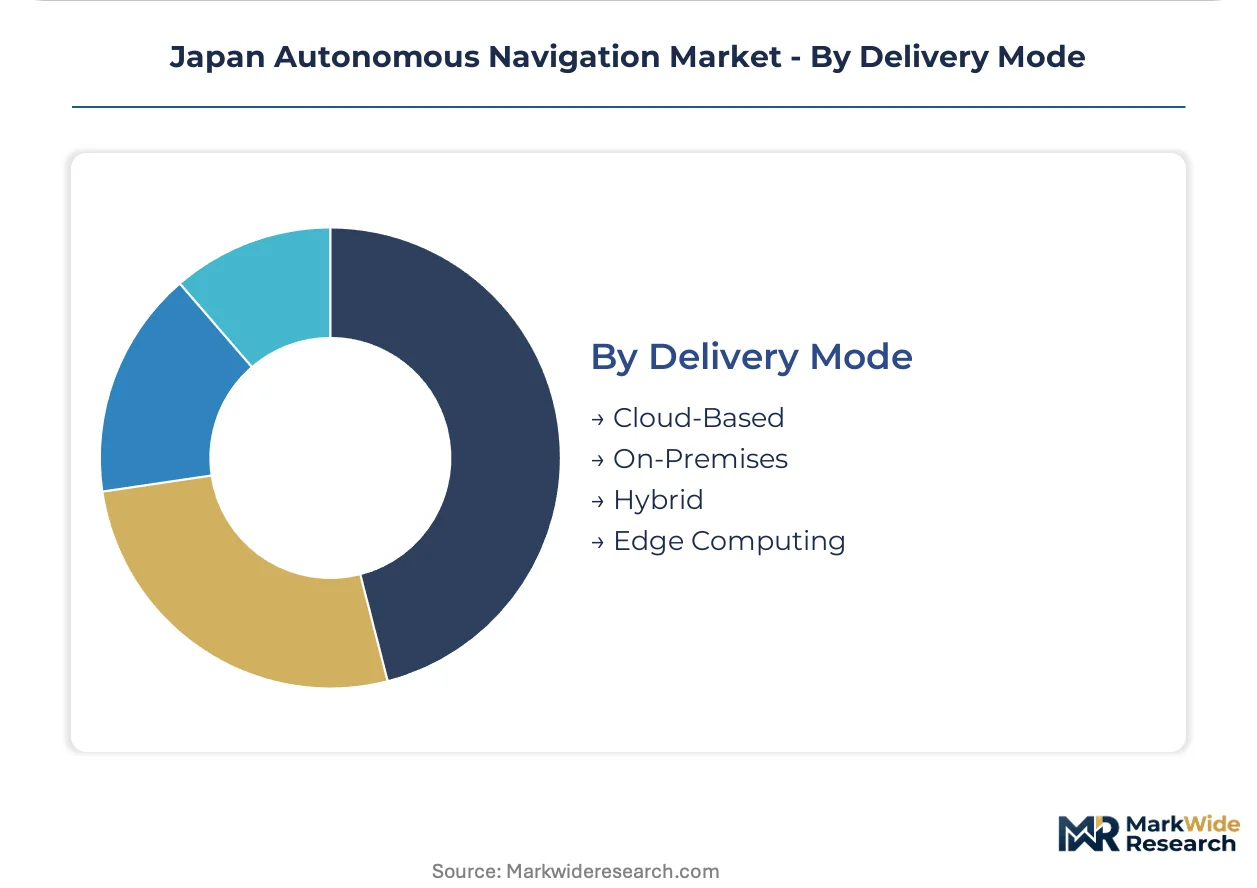
Delivery Mode:
Maturity-stage differentiation separates established cloud architectures from emerging edge-computing deployments, with latency requirements driving migration patterns.
- Edge Computing:Vehicle-embedded processing units execute sub-50-millisecond collision avoidance without network dependency. 5G network slicing convergence enables real-time path recalculation in tunnel and dense urban environments across Tokyo logistics hubs.
- Cloud-Based:Centralized processing supports fleet-scale route optimization and map updates. Bandwidth constraints and latency limitations restrict deployment to non-critical decision layers.
- Hybrid:Partitioned architectures assign time-critical functions to edge nodes and strategic planning to cloud infrastructure. Mid-scale operators adopt this transitional configuration during infrastructure migration.
- On-Premises:Dedicated server installations within facility boundaries address data sovereignty concerns. Hospital campuses under PMDA oversight favor this mode for medical-grade transport systems.
Deployment counts concentrate in Cloud-Based systems; the fastest share gain belongs to Edge Computing as latency requirements tighten for Level 4 operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kanto Special Economic Zone concentrates Japan's autonomous navigation development through METI-backed tax incentives for advanced mobility R&D facilities.
Kanto/Tokyo
Tokyo and Yokohama harbor dense clusters of automotive OEMs and robotics integrators that accelerate technology transfer. METI's safety certification framework receives its strictest interpretation here, filtering non-domestic suppliers. Logistics operators in the capital region pilot edge-computing architectures for warehouse AGVs with sub-50-millisecond collision avoidance.
Kansai/Osaka
Osaka enforces stricter operational zone restrictions than national METI baselines require, creating regulatory friction for fleet standardization. Prefectural ordinances mandate additional geofencing for Level 4 trials in urban cores. Automotive suppliers in the Osaka-Kobe corridor specialize in sensor fusion middleware for legacy warehouse management integration.
Chubu/Nagoya
Toyota's headquarters proximity anchors captive LIDAR and radar production in the Aichi industrial belt. The prefecture matches Osaka's restrictive operational zone policies while offering streamlined JIS-METI dual compliance pathways. Tier-1 suppliers cluster here to service OEM demand for vertically integrated navigation subsystems.
Kyushu
Rural municipalities in Fukuoka and surrounding prefectures prioritize autonomous transit trials to address acute driver shortages. Local governments offer operational subsidies for shuttle services connecting remote communities to regional rail hubs. METI's amended Road Traffic Act enables Level 4 fleet trials in designated zones with reduced population density.
Hokkaido
Grain operations in Hokkaido deploy GPS-guided tractors with sub-meter accuracy across regularized field geometries. Agricultural automation concentrates here due to land flatness and farm scale. The prefecture's demographic profile—aging faster than national averages—accelerates labor substitution investments in autonomous machinery.
Japan Autonomous Navigation Market Competitive Landscape
Kanto-based producers anchor the premium tier; European and North American specialists hold mid-market positions through subsystem supply. The market structure tilts toward consolidated domestic OEMs with captive certification capabilities, filtering smaller foreign component vendors. Three archetypes dominate: vertically integrated automotive manufacturers, tier-1 subsystem integrators, and foreign technology licensors. Competitive moves center on backward integration into sensor production and strategic partnerships for edge-computing hardware.
Within the integrated automotive tier, Toyota Motor Corporation and Honda Motor Company exemplify the certification-accelerated archetype, while Nissan Motor Company occupies a position emphasizing urban robo-taxi architectures. Among diversified industrial technology providers, Omron Corporation represents the tier-1 subsystem integrator model. Foreign specialists including ABB and Honeywell International sit within the technology-licensing segment, facing extended qualification timelines under JIS-METI protocols.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Honda Motor Company |
| Nissan Motor Company |
| Omron Corporation |
| ABB |
| Honeywell International |
| L3Harris Technologies |
| Northrop Grumman Corporation |
| Safran |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers in Japan's autonomous navigation sector anchor supply discipline through METI-funded consortia, translating certification advantages into pricing power over foreign component vendors facing extended JIS qualification timelines. This ownership pattern concentrates margin capture among domestic OEMs with captive sensor production while forcing tier-1 integrators into cost-absorbing middleware development.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with premium tiers attaching to sub-90-day sensor delivery and spot inventory trading at discounts. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified systems from provisional JIS compliance and uncertified imports. Cost compression in standard tiers is intensifying because tier-1 suppliers compete for fleet operator contracts with availability-based service models. Logistics operators show highest price sensitivity, while medical-grade campus buyers under PMDA oversight accept premium positioning for compliance certainty.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Toyota and Nissan, bypassing distribution layers for LIDAR and radar subsystem procurement. Geographic supply concentrates in Japan, Germany, and the United States for precision optical components, with raw material dependencies spanning rare-earth magnet feeds, high-purity silicon substrates, and specialized laser diode packages. Single-source vulnerability in gallium arsenide wafer supply creates chokepoint exposure for edge-computing processor fabrication. Distribution runs through tier-1 subsystem integrators for mid-scale operators lacking in-house engineering capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's autonomous navigation sector sits in a technology-transition phase, with edge-computing architectures displacing cloud-dependent legacy systems across logistics and transit applications.
For Market Incumbents: Anticipate margin compression from foreign sensor vendors achieving JIS-METI dual compliance breakthroughs. Toyota and Honda should deepen backward integration into edge-processor design to defend component cost positions. Certification investment in rural prefectural trials offers channel control leverage against emerging fleet operator consortia. For New Entrants and Emerging Players: METI's amended Road Traffic Act in Japan opens a window for specialized rural transit operators to capture subsidized municipal shuttle deployments. Medical-grade campus transport under PMDA oversight represents the most penetrable segment, with premium pricing tolerance and limited incumbent saturation. A go-to-market angle targeting Hokkaido agricultural automation leverages GPS-guided tractor retrofit demand with minimal direct rivalry from integrated OEMs. For Investors and Strategic Acquirers: Distressed-cycle entries favor tier-1 subsystem integrators with established JIS certification track records in the Aichi industrial belt. Long-term viability over a 5-10 year window hinges on edge-computing hardware integration capabilities rather than pure software plays. The signal to watch is METI trial program allocation announcements, which indicate which certification pathways unlock fleet operator procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Combines LIDAR, radar, and computer vision feeds into unified navigation architectures for redundancy. |
| Edge Computing Hardware Investment | Embeds sub-50-millisecond processing units in vehicle platforms, reducing cloud dependency for collision-critical decisions. |
| JIS-METI Dual Certification Pathway | Accelerates trial program allocations by demonstrating compliance with industrial standards and safety protocols. |
| Rural Municipal Transit Partnership | Captures prefectural subsidy flows for autonomous shuttle services connecting remote communities to regional hubs. |
| Medical-Grade Campus Deployment | Addresses PMDA oversight requirements for hospital autonomous delivery systems with premium pricing potential. |
Research Methodology
Ministry filings, automotive production databases, and METI safety certification records formed the secondary backbone of this analysis. Primary interviews with robotics integrators, fleet procurement directors, OEM platform engineers, and PMDA regulatory affairs specialists were combined with secondary validation. Bottom-up and top-down triangulation cross-checked sensor shipment volumes against fleet deployment counts and trial program allocations.
Historical trendline analysis established baseline adoption patterns across logistics, public transportation, agriculture, and personal vehicle applications. The forecast framework modeled technology type, application context, end-user archetype, and delivery mode dimensions over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions, with edge-computing migration rates and METI certification timeline acceleration serving as key sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for edge-computing convergence with 5G network slicing would alter the outlook. Forecasts reflect assumptions about regulatory acceleration, LIDAR cost curves, and prefectural subsidy program scaling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Military Robots Market
Unmanned Systems
Autonomous Drone Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Asia-Pacific Aerospace Robotics Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
Autonomous Technology Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
Autonomous Military Weapon Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market
Unmanned Systems
United States Aerostat Systems Market
Unmanned Systems
Global Remote Firing System Market
Unmanned Systems
Aerostat System Market
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
Anti-UAV Defence System (AUDS) Market
Unmanned Systems
Asia-Pacific Unmanned Systems Market