
 Asia-Pacific Unmanned Systems Market | 2026-2036
Asia-Pacific Unmanned Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Unmanned Systems Market Outlook
Australian defense manufacturing capacity is shifting toward sovereign unmanned platform production under the AUKUS security framework. SZ DJI Technology Co., Ltd. dominates commercial drone supply chains across the region through its Shenzhen manufacturing base. Singapore Technologies Engineering Ltd. anchors Southeast Asian military procurement with specialized naval unmanned surface vessels. Elbit Systems Ltd. competes in tactical drone segments through its established Asia-Pacific support infrastructure.
Asia-Pacific unmanned systems encompass aerial, ground, and underwater platforms operating without onboard human pilots, typically integrating GPS waypoint navigation, lithium-polymer power systems, and mesh communication relays for beyond-line-of-sight command. These systems execute reconnaissance, payload delivery, and hazardous environment inspection across defense, resource extraction, and civil infrastructure sectors. Airborne drones lead current procurement volumes, though underwater vehicles for subsea pipeline inspection represent the fastest-expanding margin pool as offshore energy operators automate asset monitoring. Ground robots for warehouse logistics sustain mature demand in Japan and South Korea, where labor shortages accelerate autonomous forklift deployment.
Japan's METI safety certification framework and Australia's CASA remotely piloted aircraft regulations shape product standards and airspace access across the region. India's BIS drone quality control orders and China's MIIT radio frequency allocation rules further segment market entry requirements by national jurisdiction. Stakeholders must monitor evolving type-certification reciprocity agreements between national aviation authorities to anticipate cross-border platform deployment feasibility.
Market Dynamics
Defense procurement across Southeast Asian militaries is expanding unmanned aerial vehicle fleets for maritime patrol, while India's DGFT export control reforms and domestic PLI scheme for drones are reshaping local manufacturing capabilities. This dual pressure from sovereign capability building and cross-border security requirements is compressing technology transfer timelines and fragmenting supplier relationships across the region.
Growth Catalysts
- AUKUS security framework:Australian defense manufacturing capacity is shifting toward sovereign unmanned platform production, accelerating domestic supply chain development for tactical systems.
- Maritime patrol requirements:Southeast Asian navies are procuring long-endurance unmanned aerial vehicles for exclusive economic zone surveillance, creating sustained demand for beyond-line-of-sight platforms.
- Mining automation:Autonomous haul trucks and survey drones reduce operational exposure in remote Pilbara operations, driving replacement cycles for legacy equipment.
Market Restraints
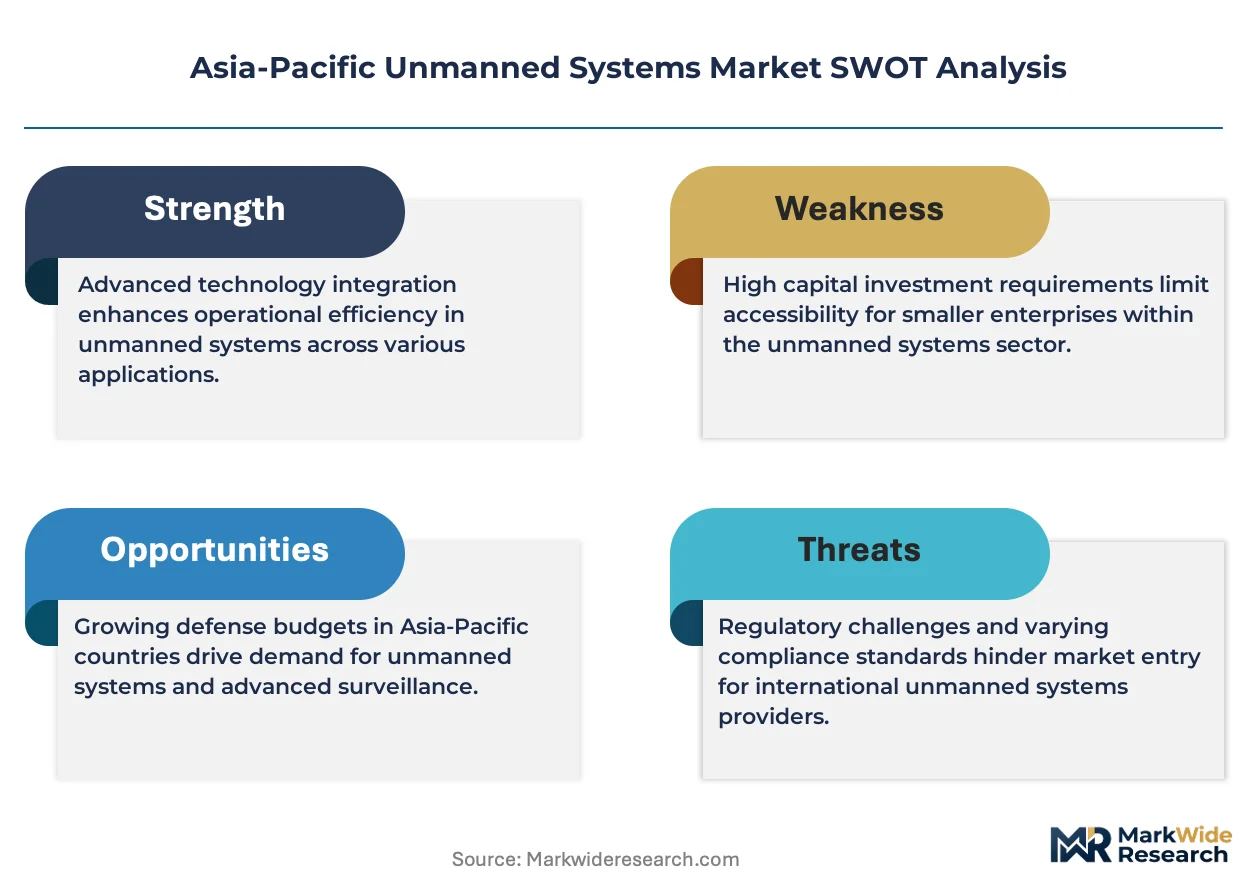
- Lithium-polymer supply concentration:Battery cell production clusters in China create input cost volatility and geopolitical exposure for platform assemblers across the region.
- Type-certification fragmentation:Japan's METI safety certification framework and Australia's CASA remotely piloted aircraft regulations lack reciprocity, forcing redundant compliance spending.
- Mesh communication relay limitations:Beyond-line-of-sight command infrastructure remains underdeveloped in archipelagic geographies, constraining operational radius for maritime applications.
Strategic Opportunities
- Underwater vehicle penetration:Subsea pipeline inspection for offshore energy operators in Australian and Southeast Asian waters represents an emerging margin pool with limited incumbent competition.
- Ground logistics automation:Labor shortages in Japan and South Korea are accelerating autonomous forklift deployment, creating aftermarket service opportunities for warehouse robotics.
- India's PLI scheme:Domestic component manufacturing incentives are attracting foreign subsystem suppliers to establish captive production for export to Middle Eastern and African markets.
Industry Challenges
- Avionics software certification:India's BIS drone quality control orders and China's MIIT radio frequency allocation rules impose divergent testing protocols, extending product launch timelines by 8-14 months.
- Integration complexity:Legacy mining and defense platforms require bespoke retrofitting for autonomous command interfaces, inflating deployment costs and delaying operational handover.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Unmanned Systems Market |
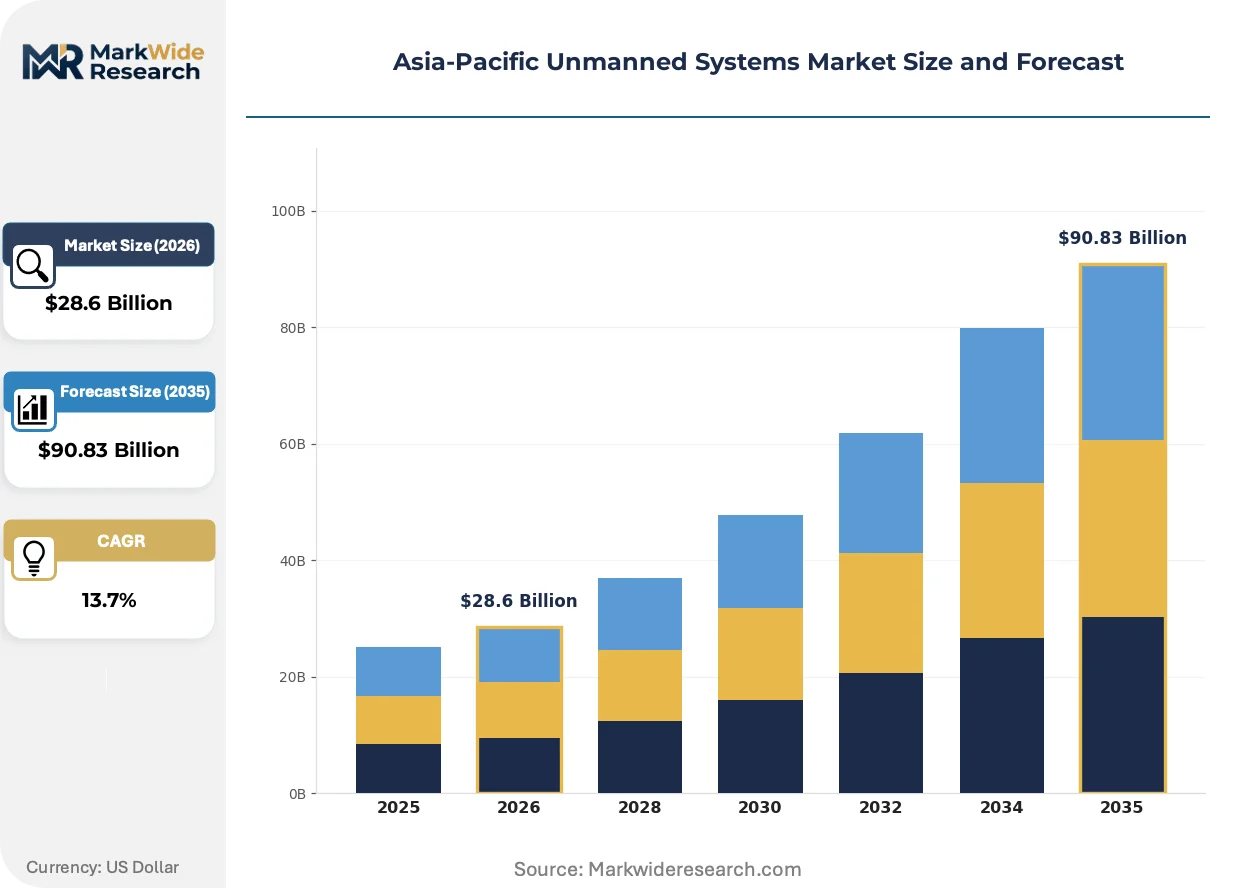
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $90.83 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airborne Drones, Ground Robots, Underwater Vehicles, Hybrid Systems Technology: Autonomous Navigation, Remote Control, AI Integration, Sensor Fusion End User: Defense, Agriculture, Logistics, Surveillance Application: Reconnaissance, Delivery Services, Environmental Monitoring, Disaster Management |
| Companies Covered | Defence Research and Development Organisation (DRDO), SZ DJI Technology Co., Ltd., Singapore Technologies Engineering Ltd., Elbit Systems Ltd., Israel Aerospace Industries Ltd., Lockheed Martin Corp, Northrop Grumman Corp, Boeing Co, Thales SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Unmanned Systems Market Strategic Shifts
Platform autonomy is advancing through sensor fusion and edge computing deployment, while regulatory frameworks are hardening around airspace access and data sovereignty. Procurement patterns are simultaneously fragmenting as national security concerns override cost efficiency in vendor selection.
Artificial intelligence-enabled target recognition is converging with synthetic aperture radar payloads for all-weather maritime surveillance. Royal Australian Navy procurement officers are specifying these capabilities for future unmanned aerial vehicle acquisitions. This convergence is compressing the operational gap between crewed patrol aircraft and unmanned alternatives in contested airspace environments.
Australia's CASA remotely piloted aircraft regulations now mandate encrypted command links for commercial operations above 400 feet, following similar moves by Japan's METI. Industrial consequence includes accelerated obsolescence of legacy radio frequency modules in existing fleets. Agricultural spraying operators in Queensland and Victoria are retrofitting platforms ahead of compliance deadlines to avoid operational grounding.
Defense buyers across Southeast Asia are unbundling platform procurement from maintenance contracts, demanding sovereign control over sustainment infrastructure. This behavior disrupts traditional integrated supplier relationships that bundled training, spares, and technical support. The shift is most visible in Indonesian and Vietnamese naval procurement, where local state-owned enterprises are capturing maintenance revenue previously retained by foreign original equipment manufacturers.
Asia-Pacific Unmanned Systems Market Segmentation
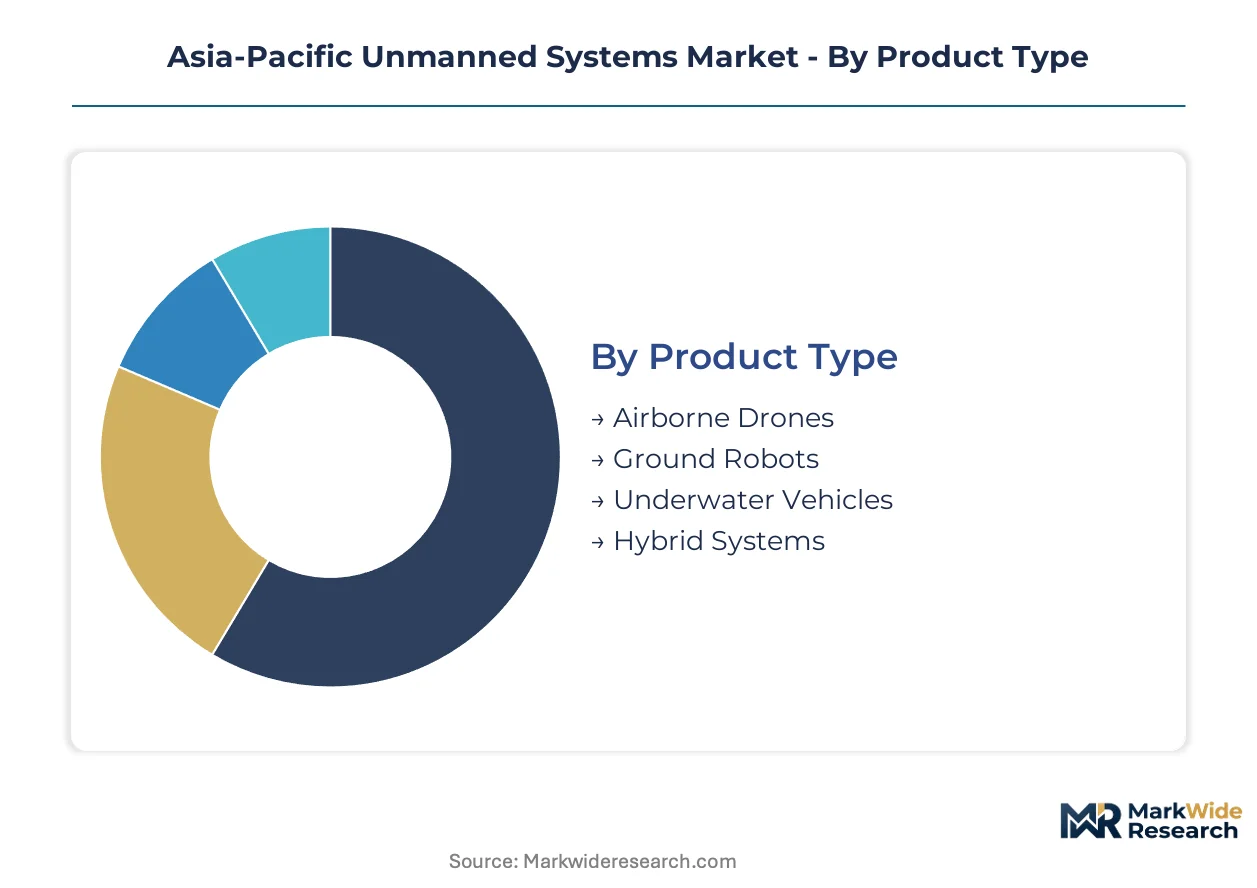
Platform architecture determines operational envelope and regulatory pathway across Asia-Pacific unmanned systems procurement. Segmentation by propulsion environment, command autonomy, end-use sector, and mission profile reveals how supplier specialization and national industrial policy intersect in this market.
Product Type:
Propulsion environment shapes battery chemistry selection, communication architecture, and certification jurisdiction for platform manufacturers.
- Airborne Drones:Fixed-wing and multirotor configurations dominate defense procurement volumes across Southeast Asian navies and Australian maritime patrol programs. Australia's CASA mandates encrypted command links above 400 feet, accelerating fleet retrofit cycles for agricultural operators in Queensland and Victoria.
- Ground Robots:Autonomous haul trucks and warehouse logistics systems integrate GPS waypoint navigation with mesh communication relays for beyond-line-of-sight command. Japan and South Korea deploy these platforms most intensively where labor shortages accelerate autonomous forklift adoption.
- Underwater Vehicles:Subsea pipeline inspection systems for offshore energy operators in Australian and Southeast Asian waters represent limited-incumbent competition zones.
- Hybrid Systems:Amphibious platforms combining aerial and surface capabilities serve specialized maritime patrol requirements in Indonesian and Vietnamese naval programs.
Mature deployment sits with Airborne Drones. Newer deployment is concentrated in Underwater Vehicles.
Technology:
Command architecture determines supplier value capture and sovereign control priorities for defense buyers.
- Autonomous Navigation:GPS waypoint systems with lithium-polymer power systems enable beyond-line-of-sight operations. Mining automation in Australia's Pilbara region depends on these capabilities for reduced operational exposure.
- Remote Control:Direct radio frequency links remain prevalent in commercial agriculture and civil infrastructure inspection. China's MIIT radio frequency allocation rules and India's BIS drone quality control orders impose divergent testing protocols on module suppliers.
- AI Integration:Target recognition algorithms converge with synthetic aperture radar for all-weather maritime surveillance. Royal Australian Navy procurement officers specify these capabilities for contested airspace environments.
- Sensor Fusion:Edge computing deployment advances platform autonomy through integrated LiDAR, thermal, and optical payloads.
Volume concentration rests with Remote Control. Margin expansion is fastest in AI Integration.
End User:
Customer procurement authority determines contract structure, with defense buyers unbundling platform and sustainment contracts.
- Defense:Southeast Asian militaries expand unmanned aerial vehicle fleets for exclusive economic zone surveillance. Indonesian and Vietnamese state-owned enterprises now capture maintenance revenue previously retained by foreign original equipment manufacturers.
- Agriculture:Spraying operators across Australia's eastern states retrofit platforms to meet CASA compliance deadlines for encrypted command links.
- Logistics:Warehouse robotics sustain mature demand in Japan and South Korea where autonomous forklift deployment accelerates.
- Surveillance:Civil infrastructure and border security applications require mesh communication relay infrastructure that remains underdeveloped in archipelagic geographies.
Contract value aggregates in Defense. Procurement flexibility is greatest in Logistics.
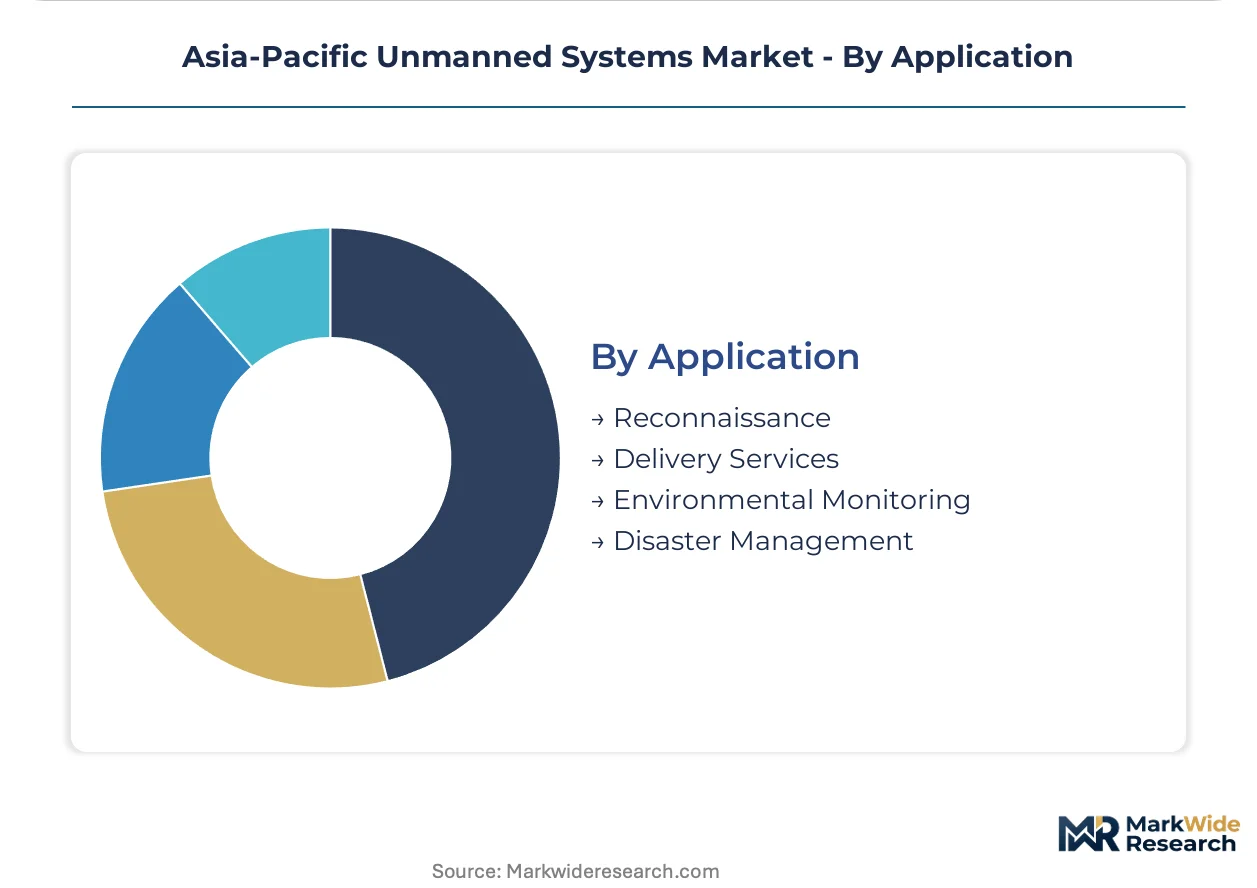
Application:
Mission profile dictates payload integration, endurance requirements, and operational tempo for platform operators.
- Reconnaissance:Long-endurance platforms with synthetic aperture radar and electro-optical payloads serve maritime patrol missions. Australia's AUKUS framework accelerates sovereign production capacity for these systems.
- Delivery Services:Last-mile logistics applications confront airspace access restrictions under Japan's METI safety certification framework and Australia's CASA regulations lacking reciprocity.
- Environmental Monitoring:Survey drones support mining automation and offshore energy asset inspection across remote operations.
- Disaster Management:Rapid deployment requirements favor portable ground robots and short-range aerial platforms for hazardous environment inspection.
Capability investment prioritizes Reconnaissance. Regulatory clearance lags most in Delivery Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's lithium-polymer battery cell production anchors regional platform manufacturing, with supply chain nodes extending through maritime Southeast Asia and Australian resource extraction zones.
China
MIIT radio frequency allocation rules govern command link certification for commercial drone fleets. SZ DJI Technology Co., Ltd. maintains its Shenzhen manufacturing base as the dominant supply source for multirotor platforms across Southeast Asian agriculture and infrastructure inspection markets. The Pearl River Delta concentration supports vertical integration from battery cell production to flight controller assembly.
Australia
CASA remotely piloted aircraft regulations now mandate encrypted command links above 400 feet, triggering retrofit cycles for Queensland and Victoria agricultural operators. The AUKUS security framework redirects defense manufacturing capacity toward sovereign unmanned platform production for tactical maritime systems. Pilbara mining automation sustains demand for autonomous haul trucks and survey drones in remote iron ore operations.
India
DGFT export control reforms and the domestic PLI scheme for drones are attracting foreign subsystem suppliers to establish captive production facilities. BIS drone quality control orders impose testing protocols that extend product launch timelines for platform assemblers. Maharashtra and Karnataka industrial corridors host emerging component manufacturing clusters serving Middle Eastern and African export markets.
Japan
METI safety certification frameworks shape airspace access standards that lack reciprocity with Australian CASA regulations. Labor shortages in Kanto and Kansai manufacturing belts accelerate autonomous forklift deployment for warehouse logistics. Tokyo-Osaka industrial demand concentrates in ground robotics for aging workforce replacement.
Singapore
Singapore Technologies Engineering Ltd. anchors Southeast Asian naval procurement with specialized unmanned surface vessels for exclusive economic zone surveillance. The city-state's port automation requirements sustain demand for autonomous maritime platforms. Defense buyers here unbundle platform procurement from maintenance contracts, transferring sustainment revenue to local state-linked enterprises.
Asia-Pacific Unmanned Systems Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue sovereign manufacturing partnerships and subsystem specialization. The vendor base separates into defense primes with integrated sustainment offerings, commercial platform specialists with Shenzhen supply chain leverage, and regional engineering houses capturing maintenance revenue from unbundled contracts. Competitive positioning hinges on M&A activity targeting autonomy software capabilities and capacity expansion into India's PLI-subsidized manufacturing zones.
Within the defense prime tier, Lockheed Martin Corp and Northrop Grumman Corp exemplify integrated platform-sustainment providers serving AUKUS-aligned procurement. Among Asia-Pacific commercial specialists, SZ DJI Technology Co., Ltd. occupies a position representing Shenzhen-based manufacturing scale, while Singapore Technologies Engineering Ltd. anchors Southeast Asian naval unmanned surface vessel supply. Elbit Systems Ltd. sits within the tactical drone segment through established regional support infrastructure.
| Leading Market Players |
|---|
| Defence Research and Development Organisation (DRDO) |
| SZ DJI Technology Co., Ltd. |
| Singapore Technologies Engineering Ltd. |
| Elbit Systems Ltd. |
| Israel Aerospace Industries Ltd. |
| Lockheed Martin Corp |
| Northrop Grumman Corp |
| Boeing Co |
| Thales SA |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed defense primes and Shenzhen-centered commercial specialists anchor platform production, with warranty bundling and sustainment contract structures determining margin capture across Australian mining automation and Southeast Asian naval procurement.
Pricing Analysis
Warranty and service bundling separates defense procurement from commercial agriculture segments, with Australian AUKUS-aligned programs demanding integrated sustainment while Indonesian state-owned enterprises unbundle maintenance for local capture. Three-tier pricing structure across premium certified-grade, standard commercial-grade, and economy retrofit tiers reflects CASA and METI certification divergence. Cost compression in the economy tier intensifies as agricultural operators in Queensland retrofit legacy fleets ahead of encrypted command-link deadlines. Defense buyers exhibit lowest price sensitivity due to sovereign capability requirements, while smallholder spraying contractors in Vietnam face acute margin pressure from battery input volatility.
Supply Chain Analysis
Freight cost exposure from Shenzhen lithium-polymer cell production to Australian Pilbara operations and Indonesian archipelagic deployment constrains just-in-time inventory strategies for platform assemblers. Manufacturing gravity centers on China's Pearl River Delta for battery cells and flight controllers, South Korea for precision servo motors, and Japan for sensor payloads. Raw material dependencies span lithium carbonate from Australian hard-rock mines, rare earth magnets from Chinese separation facilities, and carbon-fiber composites from Japanese Toray production lines. Single-source vulnerability in encrypted radio frequency modules under China's MIIT allocation rules threatens fleet retrofit timelines. Distribution runs through defense procurement offices for maritime patrol systems and agricultural equipment dealers for commercial spraying platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform manufacturing capacity is supply-constrained by lithium-polymer cell allocation and sovereign certification bottlenecks, with battery input scarcity propping pricing discipline across the forecast window.
For Market Incumbents: Cement control over sustainment infrastructure by acquiring regional service networks in Indonesia and Vietnam before state-owned enterprises consolidate maintenance revenue. Prioritize backward integration into battery pack assembly through partnerships with South Korean cell suppliers, as lithium-polymer concentration in Shenzhen creates margin vulnerability for pure-platform assemblers exposed to input cost spikes. For New Entrants and Emerging Players: Launch via subsystem specialization targeting India's PLI-subsidized component corridors in Maharashtra and Karnataka, exporting to Middle Eastern and African markets with lower certification barriers. Underwater vehicle inspection systems for Australian offshore energy operators represent the most penetrable white space, with limited incumbent competition and project-based procurement flexibility absent from defense segments. For Investors and Strategic Acquirers: Distressed-cycle entries favor autonomy software specialists with sensor fusion capabilities in Australian and Japanese industrial corridors, where mining automation and warehouse robotics demand outpaces qualified engineering supply. Long-term viability hinges on regulatory reciprocity between CASA and METI frameworks enabling cross-border platform deployment. Watch for type-certification mutual recognition agreements as the inflection signal for scaled regional expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Mitigates Shenzhen cell price volatility for Australian mining automation fleet suppliers. |
| Autonomy Software Acquisition | Captures AI-enabled target recognition demand from Royal Australian Navy maritime patrol programs. |
| PLI Corridor Manufacturing Establishment | Accesses Indian subsidy infrastructure for component export to Middle Eastern defense buyers. |
| Encrypted Command-Link Certification | Secures CASA compliance for Queensland agricultural operator retrofit cycles ahead of deadlines. |
| Sovereign Sustainment Partnership | Transfers maintenance revenue to Indonesian state-owned enterprises under unbundled procurement. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews of defense procurement officers at Southeast Asian navies, CASA certification specialists, Pilbara mining automation engineers, and agricultural equipment distributors. Secondary sources encompassed DGFT export control notifications, BIS quality control orders, MIIT radio frequency allocations, METI safety certification frameworks, and CASA remotely piloted aircraft regulations. Bottom-up platform shipment aggregation and top-down defense budget allocation analysis cross-validated market sizing.
Granularity-level modeling deployed platform-type splits by propulsion environment, command autonomy tier, and end-use sector across country-level regulatory clusters. Technology segmentation captured remote control, autonomous navigation, AI integration, and sensor fusion penetration rates. CAGRs derived from logistic curve fitting to defense procurement pipelines and mining automation replacement cycles, with cross-reference to lithium-polymer battery demand forecasts and sovereign manufacturing capacity buildouts under AUKUS and PLI frameworks.
Regulatory reciprocity failure between CASA and METI, lithium supply disruption from hard-rock mining constraints, and sovereign capability localization mandates are the dominant revision risks to platform deployment timelines and cross-border trade assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
North America AUV Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
Low-Noise Drone Propulsion Systems Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Autonomous Military Weapon Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
Drone Battery System Market
Unmanned Systems
Drone Tethered Stations Market
Unmanned Systems
Military Robotics Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
Europe Military Unmanned Vehicles Market
Unmanned Systems
Loitering Munition System Market