
 Tethered Manned Submersible Market | 2026-2036
Tethered Manned Submersible Market Size, Share, and Industry Trends Forecast 2026-2036
Tethered Manned Submersible Market Analytics
Composite pressure hull fabrication is fragmenting legacy steel-dominated supply chains as carbon-reinforced designs penetrate deeper-rated vessels. SEAmagine leverages proprietary acrylic sphere technology to sustain competitive positioning in the tourist and research segments. Lockheed Martin anchors military-grade tethered programs through classified defense contracts with the US Navy. Triton Submarines specializes in ultra-deep-rated configurations that occupy the premium certification tier above 3,000 meters.
A tethered manned submersible is a human-occupied underwater vehicle connected to a surface platform by an umbilical cable that transmits power, communications, and life support, typically rated for depths from 200 meters to over 6,000 meters depending on hull material and viewport configuration. Research submersibles dominate institutional procurement budgets while inspection variants for offshore energy infrastructure represent the fastest-growing product category as subsea asset integrity programs expand. Electric propulsion systems are displacing hydraulic architectures in new builds, with government agencies and research institutions collectively absorbing the majority of end-user demand through multi-year fleet modernization cycles.
The US Coast Guard and ABS classification society enforce structural and operational standards that shape certification timelines and market access for new entrants. IMO guidelines on submersible safety and national flag-state regulations in Japan and Australia further constrain design parameters and operational envelopes. Stakeholders must monitor evolving classification requirements for battery-electric architectures and pressure-boundary materials as regulatory bodies assimilate lessons from recent deep-submergence incidents.
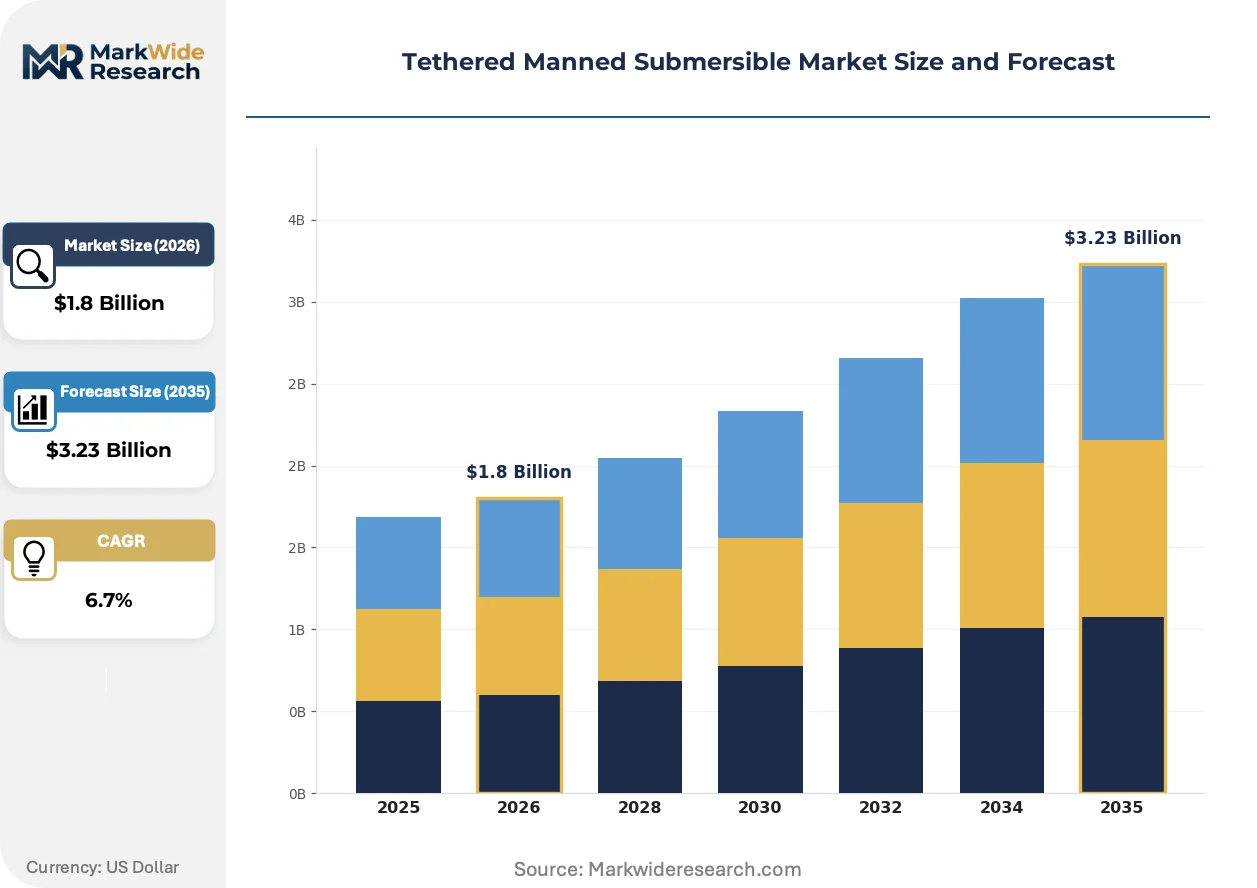
Market Dynamics
Composite pressure hull fabrication is fragmenting legacy steel-dominated supply chains as carbon-reinforced designs penetrate deeper-rated vessels and reshape procurement criteria across institutional fleets.
Growth Catalysts
- Deep-sea research expansion:Academic institutions and oceanographic agencies are accelerating fleet modernization programs. Multi-year capital allocations for manned submersible procurement are expanding across Pacific Rim research clusters.
- Subsea asset integrity mandates:Offshore energy operators face intensified inspection requirements for aging subsea infrastructure. Regulatory pressure from classification societies is institutionalizing tethered systems as standard practice for critical infrastructure assessment.
- Electric propulsion maturation:Battery-electric architectures are displacing hydraulic systems in new builds. Government agencies are absorbing technology transition costs through dedicated research vessel procurement budgets.
Market Restraints
- Titanium alloy supply concentration:Pressure hull fabrication depends on specialized titanium suppliers concentrated in Japan and Russia. Geopolitical friction and export control regimes are extending lead times for critical raw materials.
- Certification timeline compression:ABS and DNV classification protocols require multi-year validation cycles for novel pressure-boundary materials. Regulatory conservatism delays market entry for composite hull innovators.
- ROV substitution pressure:Advanced remotely operated vehicles are capturing inspection missions previously requiring human presence. Cost differentials favor unmanned alternatives for routine infrastructure monitoring.
Strategic Opportunities
- Extended-range tourism vessels:Acrylic sphere technology is enabling shallow-depth recreational operations in marine protected areas. Coastal economies in Australia and Japan are licensing commercial submersible tourism concessions.
- Integrated survey platforms:Convergence of multibeam sonar, photogrammetry, and manipulator systems is creating hybrid research-inspection configurations. Universities are consolidating vessel procurement around multi-mission flexibility.
- Defense maritime security programs:Classified submarine rescue and seabed warfare initiatives are generating dedicated procurement streams. National security agencies are funding development of specialized tethered platforms.
Industry Challenges
- Deep-submergence pilot certification scarcity:Training pipelines for manned submersible operators remain constrained to a handful of naval and institutional programs. Commercial operators face recruitment bottlenecks for qualified personnel.
- Legacy hydraulic system obsolescence:Transitioning installed fleets to electric architectures requires platform-specific engineering retrofits. Maintenance organizations must sustain dual competency across incompatible propulsion generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tethered Manned Submersible Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Research Submersibles, Tourist Submersibles, Military Submersibles, Inspection Submersibles Application: Marine Exploration, Underwater Research, Surveillance, Environmental Monitoring End User: Government Agencies, Research Institutions, Private Companies, Educational Organizations Technology: Hybrid Propulsion, Electric Propulsion, Hydraulic Systems, Control Systems |
| Companies Covered | SEAmagine, Lockheed Martin, OceanGate, DeepFlight, M Subs Ltd, Triton Submarines, Uboat Worx, China Shipbuilding Industry, DOER Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tethered Manned Submersible Market Evolving Landscape
Digital twin technology is virtualizing vessel development workflows and compressing design-validation cycles across the tethered submersible sector. Three convergent developments are restructuring competitive positioning.
Real-time hull monitoring systems are virtualizing structural health assessment through distributed fiber-optic strain sensing. Research institutions in Norway and the United States are piloting continuous pressure-boundary telemetry that eliminates periodic dry-dock inspection intervals. The technology is virtualizing maintenance scheduling and extending operational availability windows for high-utilization science platforms.
Japan's METI has issued revised industrial safety guidelines for deep-submergence pressure vessels that mandate redundant life-support architectures. The framework is accelerating adoption of closed-circuit rebreather backup systems and dual-hull configurations. Domestic shipyards are restructuring production lines to accommodate the enhanced certification tier, with export implications for vessels bound for Australian and Southeast Asian operators.
Consolidated fleet procurement is displacing single-vessel acquisitions among oceanographic consortia. Research institutions are pooling capital through multi-operator agreements that standardize platform specifications and share operational infrastructure. The model is most visible across United States university fleets, where regional science consortia are negotiating collective maintenance contracts and crew certification programs.
Tethered Manned Submersible Market Segmentation
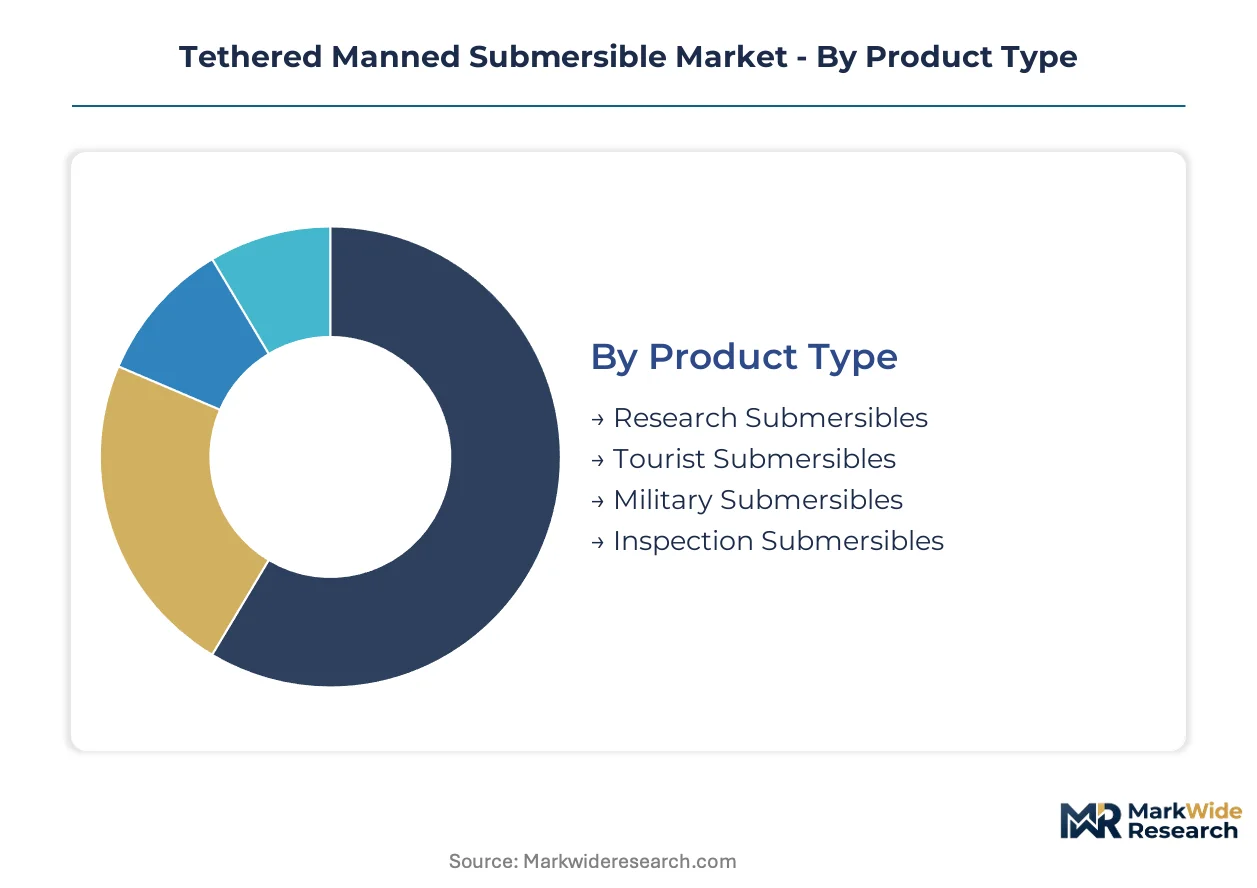
Segmentation in the tethered manned submersible market reveals divergent procurement cycles across institutional, commercial, and defense channels. Hull certification timelines and mission-specific equipment configurations create distinct replacement rhythms that reshape vendor priorities.
Product Type:
Research submersibles operate on decade-long replacement cycles driven by grant funding windows, while inspection variants refresh faster as offshore operators commercialize new sensor payloads.
- Research Submersibles:Acrylic and titanium pressure hull configurations rated for 1,000-6,500 meters dominate academic fleet procurement. Demand concentrates at Woods Hole Oceanographic Institution, Japan Agency for Marine-Earth Science and Technology, and Australian research clusters pursuing hadal zone access.
- Inspection Submersibles:Carbon-composite hulls optimized for 200-1,000 meter operations with integrated manipulator arms and multibeam sonar. Offshore energy operators in the Gulf of Mexico and North Sea are standardizing tethered systems for subsea asset integrity programs.
- Tourist Submersibles:Shallow-depth acrylic sphere designs certified for recreational operations in marine protected areas.
- Military Submersibles:Classified programs for submarine rescue and seabed warfare with specialized tether configurations.
Research submersibles dominate installed base. Inspection submersibles are where expansion concentrates.
Application:
Marine exploration commands premium vessel specifications, while environmental monitoring applications drive standardization around modular sensor architectures.
- Marine Exploration:Deep-rated platforms with extended dive endurance for trench mapping and benthic ecosystem discovery. Pacific Rim governments are anchoring national oceanographic strategies around dedicated exploration fleets.
- Underwater Research:Mid-depth configurations supporting biological sampling, geological coring, and hydrothermal vent study. University consortia in the United States are pooling procurement around multi-mission flexibility.
- Surveillance:Covert infrastructure inspection and seabed cable monitoring for national security agencies.
- Environmental Monitoring:Standardized platforms for long-term oceanographic data collection and climate baseline establishment.
Underwater research anchors institutional procurement volumes. Marine exploration is climbing the fastest as hadal zone programs accelerate.
End User:
Government agencies sustain multi-year capital programs, while private companies concentrate demand in shorter-cycle inspection services.
- Government Agencies:National oceanographic institutes and defense maritime commands with dedicated fleet modernization budgets. Japan's METI and the United States' Office of Naval Research are anchoring procurement pipelines.
- Research Institutions:University-based science consortia sharing operational infrastructure and crew certification programs. Regional clusters in California, Massachusetts, and Queensland are consolidating purchasing power.
- Private Companies:Offshore energy operators and commercial survey contractors.
- Educational Organizations:Museums and marine science centers with shallow-depth tourism concessions.
Government agencies dominate long-cycle procurement. Research institutions are gaining share fastest through collective purchasing models.
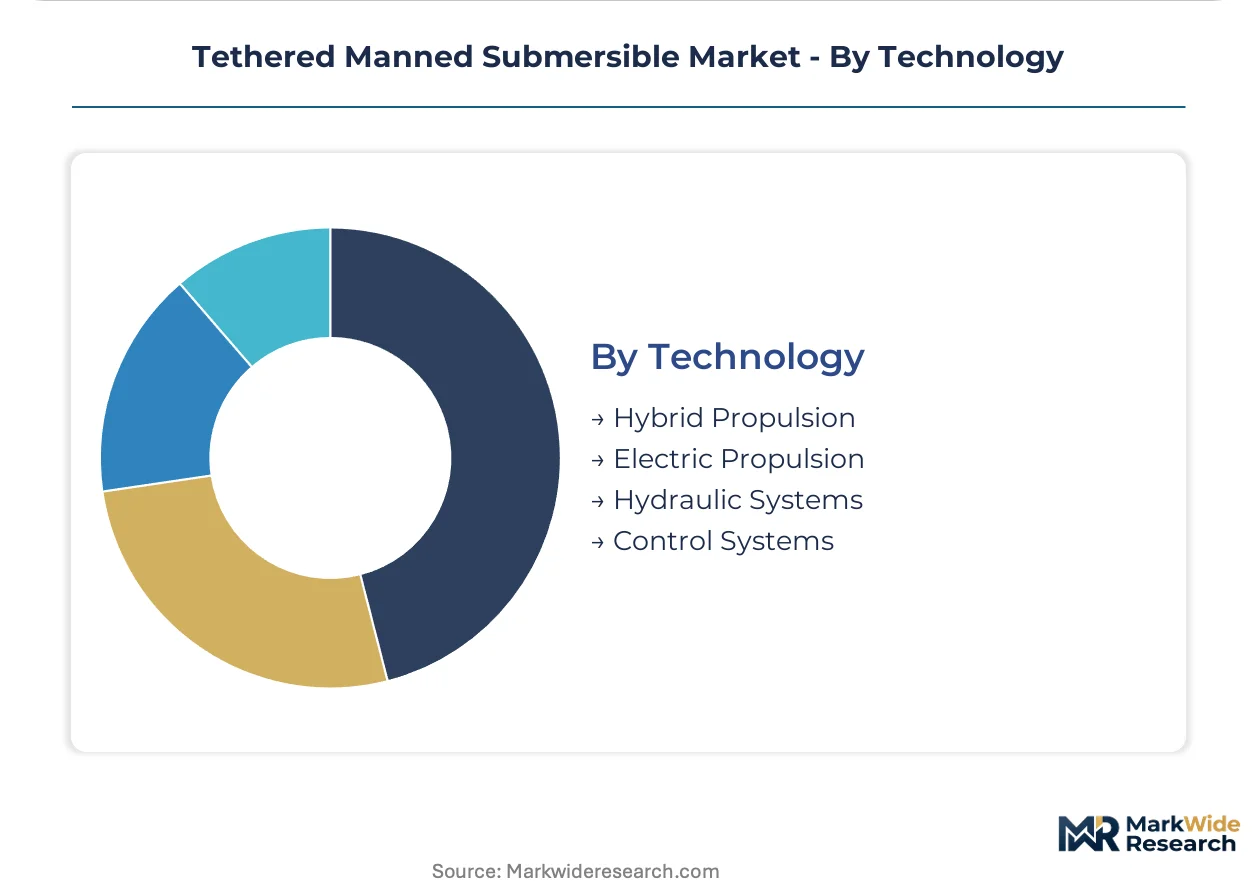
Technology:
Electric propulsion systems are displacing legacy hydraulic architectures, with hybrid configurations bridging the transition for operators with mixed fleet requirements.
- Electric Propulsion:Battery-electric architectures with distributed thruster control and reduced acoustic signature. ABS classification protocols for battery-electric pressure vessels are accelerating adoption in new builds.
- Hybrid Propulsion:Dual-mode systems combining electric maneuvering with hydraulic power for heavy manipulator operations. Transitional configurations appeal to operators with legacy infrastructure investments.
- Hydraulic Systems:Legacy architectures with proven deep-submergence reliability.
- Control Systems:Digital fly-by-wire interfaces with real-time hull monitoring and automated depth-keeping.
Hydraulic systems retain installed base dominance. Electric propulsion is where vendor R&D concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese titanium suppliers export specialized pressure-hull alloys to Australian shipyards and US defense contractors, anchoring a Pacific Rim trade corridor that sustains fabrication capacity for deep-rated vessels.
United States
The Office of Naval Research funds classified submarine rescue programs while Woods Hole Oceanographic Institution modernizes its academic fleet. ABS classification protocols for battery-electric pressure vessels are accelerating adoption timelines. Regional science consortia in Massachusetts and California are pooling procurement around collective maintenance contracts.
Japan
METI industrial safety guidelines mandate redundant life-support architectures for deep-submergence vessels. Domestic shipyards are restructuring production lines to accommodate enhanced certification tiers. The Japan Agency for Marine-Earth Science and Technology anchors hadal zone exploration programs in Yokosuka research clusters.
Australia
Queensland and New South Wales research clusters pursue trench mapping initiatives with Pacific Rim partners. The country's national maritime safety regulator enforces flag-state standards that align with Japanese certification frameworks. Marine protected area tourism concessions in the Great Barrier Reef are licensing shallow-depth acrylic sphere operations.
China
China Shipbuilding Industry consolidates state-directed production of titanium pressure hulls for institutional research fleets. The Ministry of Industry and Information Technology coordinates standards alignment with international classification societies. Deep-sea research programs in Qingdao and Guangzhou are expanding fleet procurement through multi-year capital allocations.
United Kingdom
Academic institutions in Scotland and Southwest England participate in European oceanographic consortia for shared vessel operations. The national maritime regulator enforces structural standards that exceed baseline IMO guidelines. Plymouth Marine Laboratory and Scottish Association for Marine Science are negotiating collective crew certification programs.
Tethered Manned Submersible Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that fragments between defense-anchored primes, research-focused fabricators, and tourism-oriented specialists. Consolidation pressure concentrates in the deep-rated certification tier above 3,000 meters where hull material expertise creates entry barriers. Three archetypes dominate: titanium-alloy pressure hull specialists, acrylic sphere tourism operators, and electric propulsion system integrators. Strategic moves center on M&A for hull fabrication capacity and technology licensing for battery-electric architectures.
Among US-based defense contractors, Lockheed Martin anchors classified military programs while Triton Submarines occupies the premium certification tier for ultra-deep-rated configurations. SEAmagine exemplifies the tourism-research hybrid archetype through proprietary acrylic sphere deployment. These three entities represent distinct competitive vectors: defense-funded development, extreme-depth engineering, and recreational market access.
| Leading Market Players |
|---|
| SEAmagine |
| Lockheed Martin |
| OceanGate |
| DeepFlight |
| M Subs Ltd |
| Triton Submarines |
| Uboat Worx |
| China Shipbuilding Industry |
| DOER Marine |
| Others |
Value Network & Pricing Analysis
Yokosuka research clusters in Japan anchor titanium-alloy fabrication capacity for deep-rated pressure hulls, concentrating upstream supply power among a handful of specialized metallurgical suppliers. This geographic concentration translates into asymmetric pricing leverage for hull material procurement, with downstream vessel integrators absorbing cost volatility through long-term offtake agreements.
Pricing Analysis
Electric-hydraulic propulsion pricing gaps structure vessel quotations, with battery-electric architectures commanding certification premiums over legacy hydraulic systems. Three-tier pricing separates hadal-rated titanium hulls from mid-depth carbon-composite configurations from shallow acrylic tourism spheres. Price differentiation centers on ABS certification grade and dive endurance specifications. Cost compression in inspection-class vessels is intensifying because offshore energy operators are consolidating fleet procurement around standardized sensor payloads. Research institutions exhibit lowest price sensitivity due to grant-funded capital allocations, while commercial tourism operators face acute margin pressure from seasonal demand fluctuations.
Supply Chain Analysis
Tariff exposure between Japan and Russia dominates raw material risk profiles for titanium sponge and alloy billet sourcing. Pressure hull fabrication draws from Japanese metallurgical suppliers, Russian titanium feedstock processors, and Australian carbon-fiber preform manufacturers. Single-source vulnerability concentrates in specialized viewport acrylic casting and fiber-optic strain sensing systems. Distribution runs through defense procurement channels for classified programs and institutional fleet modernization contracts for research consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where crew certification programs and integrated maintenance contracts expand faster than hull hardware sales. Recurring revenue from operational support layers now exceeds standalone vessel margins for established platform operators.
For Market Incumbents: Pre-empt ROV substitution pressure by embedding real-time hull monitoring and predictive maintenance analytics into standard service agreements. Backward integration into titanium alloy recycling and carbon-fiber preform fabrication secures supply continuity against export control disruptions. Lockheed Martin's defense-anchored positioning demonstrates how classified program access creates switching costs that insulate pricing power. For New Entrants and Emerging Players: Pursue marine protected area tourism concessions in Australia and Japan where licensing frameworks favor shallow-depth acrylic sphere operators with local stakeholder relationships. The most penetrable segment sits in university consortia seeking multi-mission research-inspection hybrids with pooled procurement structures. A direct go-to-market angle targets collective maintenance contract bundling alongside vessel delivery. For Investors and Strategic Acquirers: Long-term, this sits as a defense-civilian dual-use play because seabed warfare and submarine rescue programs generate procurement stability independent of academic funding cycles. Acquisition targets should display composite pressure hull fabrication expertise paired with ABS certification track records. The signal to watch is METI guideline harmonization with Australian flag-state standards, which would accelerate Pacific Rim fleet standardization and consolidate vendor selection criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Hull Certification Investment | ABS validation for carbon-reinforced architectures above 3,000 meters unlocks premium tier access. |
| Electric Propulsion Retrofit Program | Battery-electric conversions of legacy hydraulic fleets capture institutional modernization budgets. |
| Regional Crew Certification Consortium | Shared training pipelines across Queensland and California clusters reduce operator recruitment bottlenecks. |
| Integrated Sensor Platform Partnership | Multibeam sonar and photogrammetry bundling differentiates inspection-class offerings for Gulf of Mexico operators. |
| Titanium Alloy Recycling Integration | In-house recovery of pressure hull material mitigates Japanese-Russian supply concentration risk. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with submersible pilots, fleet maintenance directors, university procurement officers, and defense maritime program managers. Secondary validation drew from ABS classification protocols, METI industrial safety guidelines, IMO submersible safety circulars, and customs trade data for titanium alloy shipments. Bottom-up vessel delivery tracking and top-down institutional budget allocation analysis were triangulated to reconcile procurement volume estimates.
Calibration against historical fleet replacement cycles and observed grant funding windows anchored the projection framework across the analysis window. Segmentation dimensions modeled include pressure hull material grade, propulsion architecture, end-user category, and regional regulatory cluster. CAGRs were derived from trend extrapolation of institutional capital allocation patterns and offshore energy inspection mandate expansion. Industry-specific inputs incorporated observed certification timeline compression effects and composite material adoption curves from pilot programs in Norway and the United States.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-directed shipbuilders or accelerated ROV capability convergence would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Autonomous Drone Market
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
Anti-UAV Defence System (AUDS) Market
Unmanned Systems
Asia-Pacific Aerospace Robotics Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
Vetronics Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
Europe Military Unmanned Vehicles Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
Aerostat System Market
Unmanned Systems
Low-Noise Drone Propulsion Systems Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
Explosive Ordnance Disposal (EOD) Robot Market