
 High Altitude Long Endurance Market | 2026-2036
High Altitude Long Endurance Market Size, Share, and Industry Trends Forecast 2026-2036
High Altitude Long Endurance Market Intelligence
Military-grade endurance specifications above 30 days continuous flight is redrawing supplier hierarchies in stratospheric aviation. Lockheed Martin Corporation leverages its Skunk Works heritage to anchor classified ISR programs with multi-week loiter capability. Airbus competes through Zephyr solar-electric development, sustaining record-breaking flight demonstrations that differentiate its civilian-military hybrid positioning. Northrop Grumman dominates the Global Hawk legacy segment, extending proven high-altitude architecture into next-generation autonomous frameworks.
High Altitude Long Endurance refers to unmanned or minimally crewed platforms operating above 60,000 feet for durations exceeding 24 hours, typically employing solar-electric, fuel cell, or hybrid propulsion with wingspans exceeding 70 feet to achieve favorable lift-to-drag ratios at low atmospheric density. These systems serve persistent intelligence, surveillance, and reconnaissance missions alongside telecommunications relay and atmospheric research where satellite coverage proves uneconomical or unavailable. Solar-powered platforms lead current operational deployments due to demonstrated multi-week endurance, while fuel cell technology represents the fastest-growing segment as energy density improvements unlock heavier payloads and adverse-weather resilience. Military deployment models command the largest margin pools given classified requirements and sole-source contracting, though civil meteorological applications are expanding fastest as national weather services seek stratospheric data continuity.
FAA certification pathways for unmanned systems above Class A airspace, combined with ITAR export controls administered by the US State Department, create significant barriers to foreign platform entry into allied defense programs. EASA regulatory development for drone operations beyond visual line of sight shapes European competitive dynamics, favoring indigenous developers like Airbus against US incumbents. Stakeholders must monitor evolving spectrum allocation decisions for stratospheric relay services, as national regulators balance commercial telecommunications access against military communications security requirements.
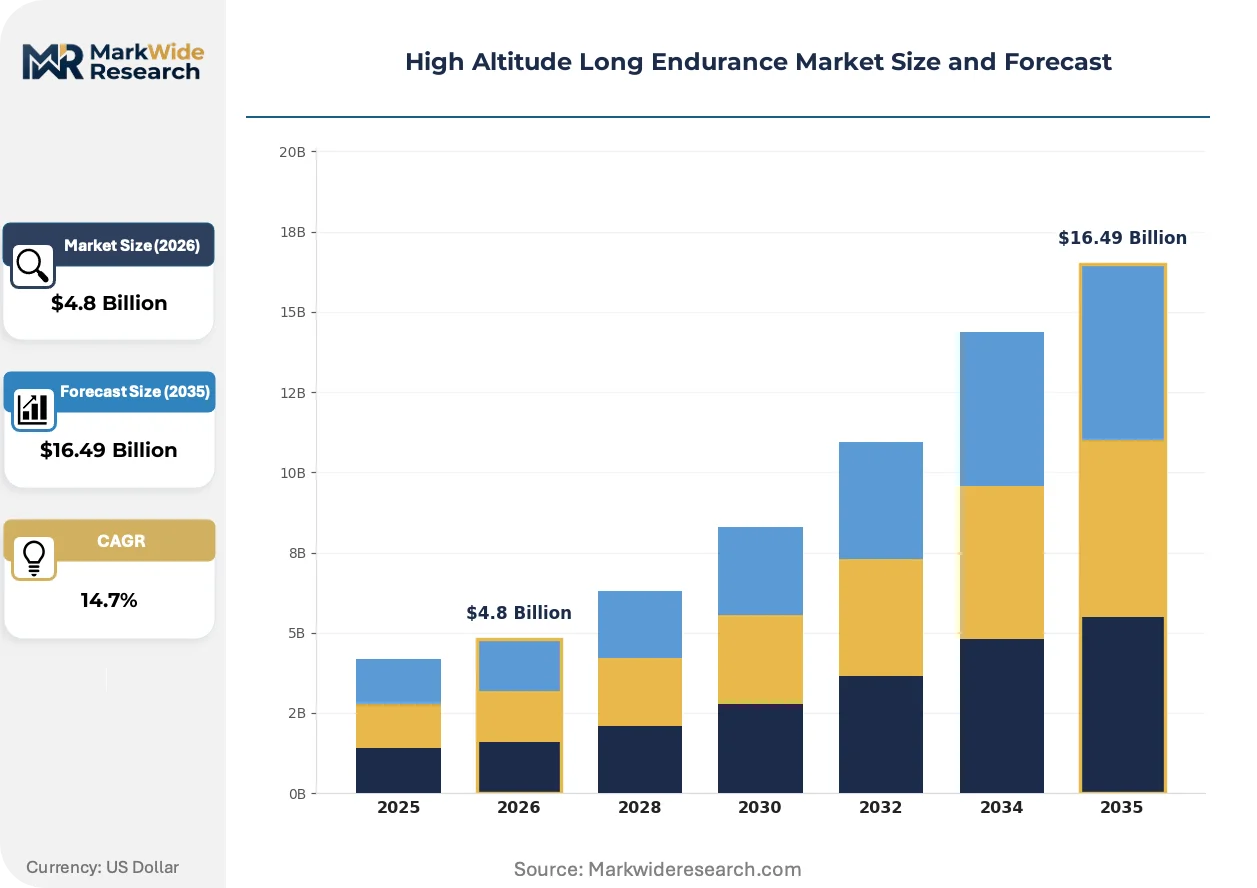
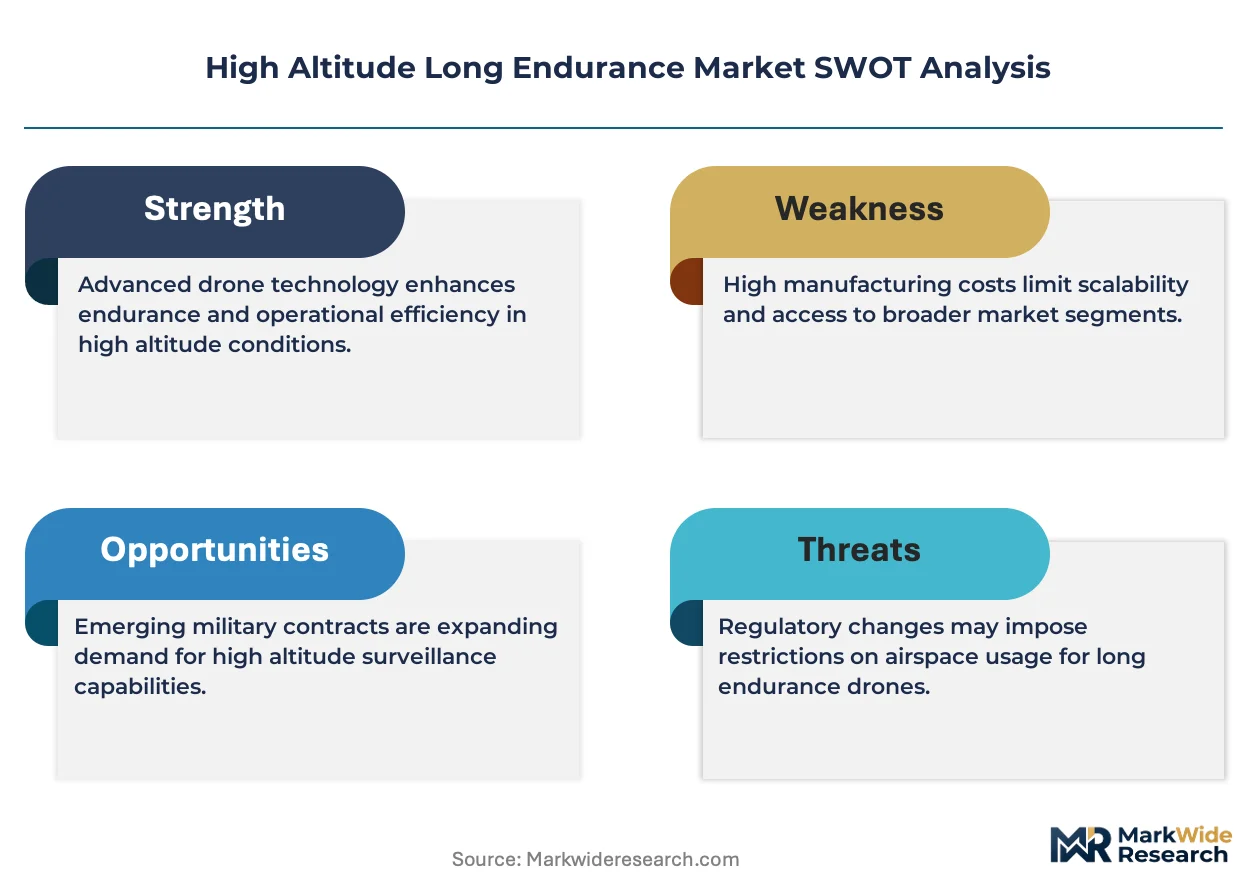
Market Dynamics
Defense procurement offices are consolidating multi-year stratospheric ISR contracts around platforms demonstrating 60-plus day endurance, compressing supplier qualification timelines and elevating technical barriers for new entrants.
Growth Catalysts
- Thin-film photovoltaic efficiency gains:Laboratory demonstrations exceeding 30% conversion efficiency at stratospheric irradiance levels are extending loiter durations without payload trade-offs. Solar-electric architectures now dominate platform development roadmaps.
- NATO persistent surveillance mandates:Alliance members are formalizing requirements for continuous stratospheric coverage over contested regions, creating dedicated budget lines for HALE platform acquisition and operations.
- FAA beyond-visual-line-of-sight rulemaking:Proposed Class A airspace integration pathways for unmanned systems above 60,000 feet are reducing regulatory uncertainty for commercial operators and defense contractors alike.
Market Restraints
- ITAR export control stringency:US State Department classification of stratospheric platform subsystems as defense articles blocks technology transfer to non-allied nations, fragmenting addressable markets.
- Lightweight composite supply concentration:High-modulus carbon fiber prepregs for ultra-long wingspans source predominantly from Japanese and US suppliers, creating single-source vulnerability.
- Stratospheric weather unpredictability:Sudden polar vortex disruptions and seasonal wind shear patterns force mission aborts or altitude deviations, degrading operational availability metrics.
Strategic Opportunities
- Indian defense modernization:The country's armed forces are evaluating HALE platforms for Himalayan border surveillance, with indigenous development programs creating partnership entry points for foreign subsystem suppliers.
- Emergency telecommunications relay:Natural disaster response agencies are piloting stratospheric cellular backhaul to restore connectivity when terrestrial infrastructure fails, opening civilian revenue streams.
- Hydrogen fuel cell convergence:Integration of solid-oxide fuel cells with solar-electric architectures promises night-time endurance without battery mass penalties, enabling heavier sensor payloads.
Industry Challenges
- Stratospheric flight certification timelines:FAA and EASA airworthiness standards for unmanned systems above Class A airspace remain under development, stretching program schedules and freezing procurement decisions.
- Autonomous flight control software validation:Multi-week missions with minimal ground intervention demand formal verification of decision algorithms, requiring specialized aerospace software engineering talent pools that remain shallow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Altitude Long Endurance Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.49 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: UAV, Balloon, Airship, Solar Aircraft Deployment Model: Military, Civil, Research, Commercial Technology: Solar Power, Hybrid Systems, Electric Propulsion, Fuel Cell End User: Defense, Meteorological Services, Telecommunications, Surveillance |
| Companies Covered | AeroVironment, Inc., Airbus, Thales Group, Lockheed Martin Corporation, BAE Systems, Northrop Grumman, Raytheon Technologies Corporation, General Atomics, SoftBank Group Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Altitude Long Endurance Market Strategic Shifts & Innovations
Platform developers are racing to demonstrate endurance records that redefine operational concepts, while regulators struggle to keep pace with autonomous system capabilities.
Perovskite-silicon tandem solar cells are supplanting conventional gallium arsenide arrays on experimental HALE platforms. Defense research agencies are funding rapid transition from laboratory cells to flight-qualified modules. This technology compression is collapsing the cost-per-watt gap between space-grade and stratospheric photovoltaics.
EASA regulatory development for drone operations beyond visual line of sight is mandating detect-and-avoid system interoperability across European airspace. Manufacturers must now certify platforms against evolving sense-and-avoid standards before commercial deployment. Civil-military dual-use developers face the steepest compliance burden as they pursue both certification pathways simultaneously.
Buyer organizations are unbundling platform acquisition from sensor integration and flight operations, creating discrete contract vehicles for each capability layer. Defense agencies now procure airframes through traditional acquisition channels while contracting sensor packages and mission crews through separate performance-based agreements. This fragmentation is most visible in US special operations commands, where rapid capability insertion demands flexible contracting mechanisms.
High Altitude Long Endurance Market Segmentation
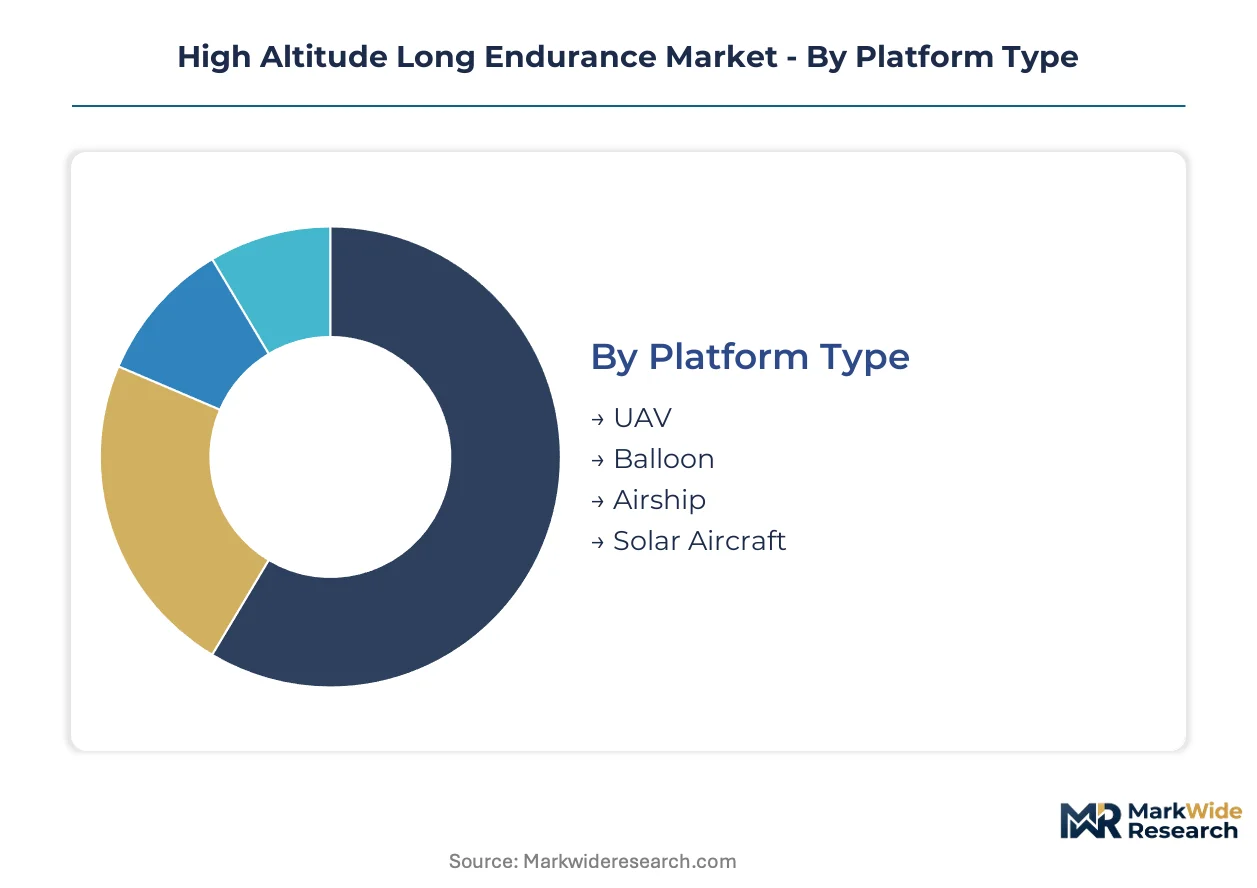
Stratospheric platform procurement splits sharply across mission profiles and endurance requirements. Procurement offices weight technology readiness against payload flexibility when segmenting addressable demand.
Platform Type:
Balloon systems face acute substitution pressure from solar-electric aircraft as endurance records extend beyond 90 days.
- UAV:Fixed-wing autonomous systems dominate classified ISR contracts through proven multi-week loiter capability. Defense agencies in the United States and NATO member states concentrate procurement around platforms exceeding 60,000 feet operational ceiling with modular sensor bays.
- Solar Aircraft:Photovoltaic-powered platforms achieve the longest demonstrated endurance through regenerative energy cycles. Record-breaking flight demonstrations by Airbus Zephyr programs anchor civilian-military hybrid positioning for telecommunications relay missions.
- Balloon:High-altitude balloon systems offer rapid deployment for temporary surveillance coverage. Meteorological services leverage legacy infrastructure for atmospheric sampling where extended loiter is unnecessary.
- Airship:Lighter-than-air rigid structures accommodate heavier payloads through buoyancy lift. Research organizations pilot hybrid airship configurations for stratospheric payload testing.
UAV platforms anchor the volume base while solar aircraft gains share at the steepest rate.
Deployment Model:
Cost tier differentiation separates sole-source military contracts from competitive commercial tenders.
- Military:Classified requirements command premium pricing through sole-source contracting mechanisms. Multi-year stratospheric ISR programs in NATO member states consolidate around platforms demonstrating 60-plus day endurance.
- Commercial:Telecommunications relay services pursue performance-based agreements with flexible termination clauses. Cellular backhaul providers pilot stratospheric coverage where terrestrial infrastructure proves uneconomical.
- Civil:National weather services seek stratospheric data continuity through recurring service contracts rather than platform ownership. FAA beyond-visual-line-of-sight rulemaking reduces regulatory uncertainty for civil operators.
- Research:Academic and government laboratories procure experimental platforms for atmospheric science missions. Funding cycles favor modular systems permitting rapid sensor reconfiguration.
Military deployment anchors the margin base while commercial applications expand most quickly.
Technology:
Supply concentration in photovoltaic manufacturing favors solar power architectures for cost-sensitive programs.
- Solar Power:Thin-film photovoltaic arrays exceeding 30% conversion efficiency extend loiter without payload trade-offs. Laboratory demonstrations of perovskite-silicon tandem cells are collapsing the cost-per-watt gap between space-grade and stratospheric applications.
- Fuel Cell:Solid-oxide fuel cells promise night-time endurance without battery mass penalties. Hydrogen storage integration unlocks heavier sensor payloads for adverse-weather resilience.
- Hybrid Systems:Combined solar-electric and fuel cell architectures balance endurance with payload flexibility. Defense research agencies fund rapid transition from experimental configurations to flight-qualified modules.
- Electric Propulsion:Battery-dependent systems serve short-duration missions where rapid redeployment matters. Lightweight composite airframes maximize energy density for tactical surveillance applications.
Solar power anchors the installed base while fuel cell configurations climb the fastest.
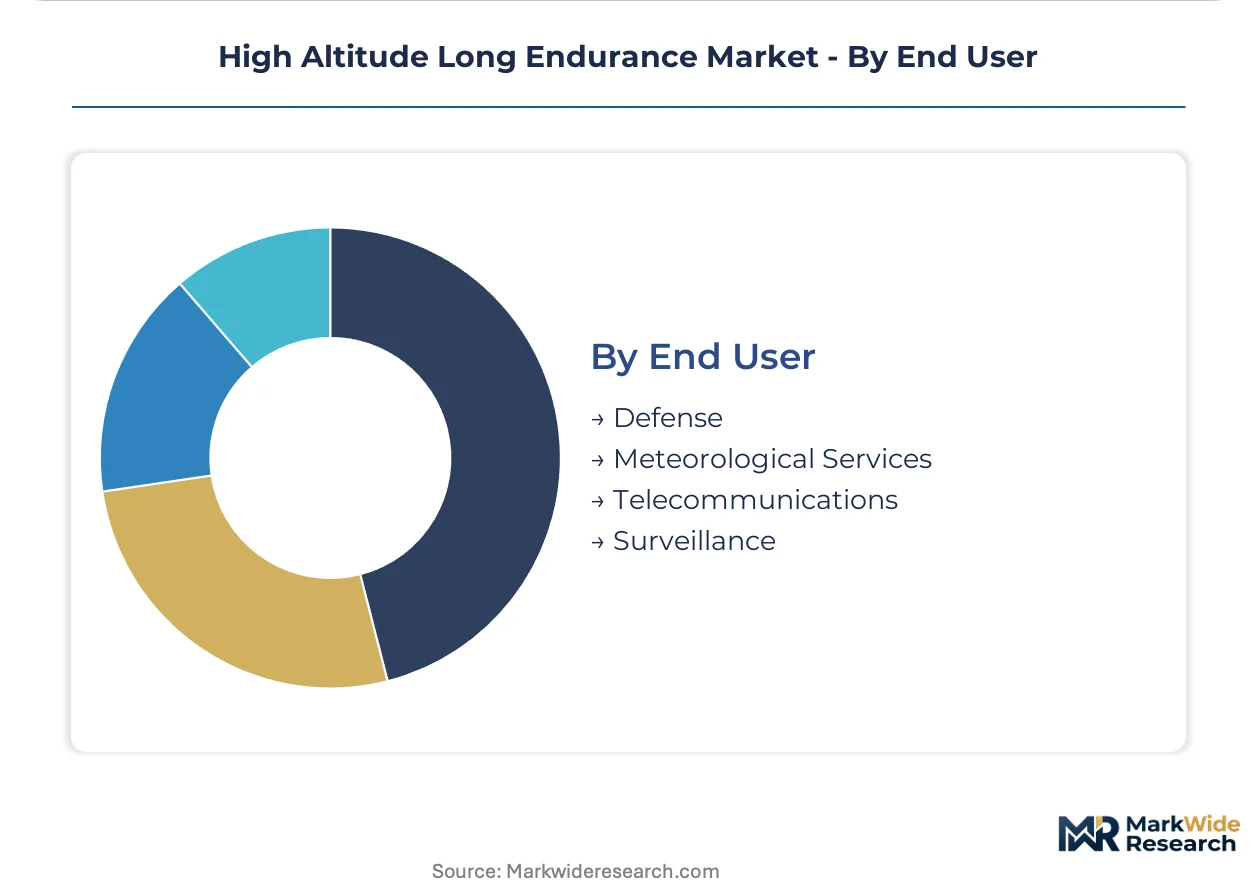
End User:
Customer type fragmentation unbundles platform acquisition from sensor integration and flight operations.
- Defense:Persistent ISR mandates drive procurement of stratospheric platforms with classified communications relay capability. US special operations commands fragment contracting into discrete vehicles for airframes, sensors, and mission crews.
- Telecommunications:Natural disaster response agencies pilot stratospheric cellular backhaul to restore connectivity when terrestrial infrastructure fails. Spectrum allocation decisions by national regulators balance commercial access against military security requirements.
- Surveillance:Border security agencies evaluate HALE platforms for continuous coverage of contested regions. Indian defense modernization programs create partnership entry points for foreign subsystem suppliers.
- Meteorological Services:National weather agencies seek stratospheric data continuity where satellite coverage proves uneconomical. EASA regulatory development for beyond-visual-line-of-sight operations shapes European competitive dynamics.
Defense anchors the revenue base while telecommunications applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export controls on stratospheric platform subsystems flow predominantly from the United States toward NATO allies and partner nations, while import demand concentrates in defense modernization programs across the Indo-Pacific. Technology transfer restrictions fragment procurement patterns, with indigenous development programs emerging in countries facing ITAR barriers.
United States
Defense agencies fund persistent ISR and communications relay programs through classified multi-year contracts. FAA beyond-visual-line-of-sight rulemaking for Class A airspace above 60,000 feet reduces regulatory uncertainty for domestic operators. The Skunk Works heritage in Palmdale, California anchors development of platforms demonstrating 60-plus day endurance for special operations commands.
United Kingdom
Stratospheric surveillance requirements for North Atlantic and Arctic coverage drive evaluation of solar-electric platforms. Ministry of Defence procurement offices consolidate around NATO persistent surveillance mandates for contested region monitoring. The Farnborough aerospace cluster hosts integration facilities for Zephyr-based telecommunications relay demonstrations.
Germany
Bundeswehr programs seek stratospheric platforms for border surveillance and electronic intelligence collection. EASA regulatory development for drone operations beyond visual line of sight shapes certification timelines for civil-military dual-use systems. The Munich-Stuttgart aerospace corridor concentrates subsystem suppliers for lightweight composite airframes and autonomous flight control modules.
India
Armed forces evaluate HALE platforms for Himalayan border surveillance against Chinese infrastructure development. Indigenous development programs through Defence Research and Development Organisation create partnership entry points for foreign subsystem suppliers facing export control restrictions. The Bengaluru-Hyderabad defense technology corridor hosts flight testing facilities for stratospheric platform prototypes.
Japan
Maritime surveillance requirements for East China Sea coverage drive interest in persistent stratospheric platforms. METI funding for dual-use aerospace technologies supports development of detect-and-avoid systems for EASA-equivalent certification. The Nagoya aerospace cluster integrates thin-film photovoltaic arrays from domestic suppliers into experimental HALE configurations.
High Altitude Long Endurance Market Key Industry Players
Listed leaders compete with private specialists across defense contracting access, with public companies dominating classified procurement while private entities capture experimental technology development. The supplier base stratifies around sole-source military relationships and competitive commercial tenders. Three archetypes anchor positioning: legacy defense primes with Skunk Works heritage, European aerospace conglomerates with civilian-military hybrid platforms, and specialist unmanned systems developers. Competitive moves concentrate on multi-year ISR contract consolidation and rapid technology transition from laboratory to flight-qualified modules.
Among US-based defense primes, Lockheed Martin Corporation and Northrop Grumman occupy positions anchored by proven high-altitude architectures and classified program heritage. Airbus represents the European conglomerate archetype, leveraging record-breaking flight demonstrations to differentiate civilian-military hybrid positioning. AeroVironment, Inc. exemplifies the specialist unmanned systems developer, sitting within the tier focused on rapid capability insertion for defense research agencies.
| Leading Market Players |
|---|
| AeroVironment, Inc. |
| Airbus |
| Thales Group |
| Lockheed Martin Corporation |
| BAE Systems |
| Northrop Grumman |
| Raytheon Technologies Corporation |
| General Atomics |
| SoftBank Group Corp. |
| Others |
Cost & Logistics Intelligence
Perovskite-silicon tandem solar cell adoption is displacing gallium arsenide arrays as the dominant photovoltaic technology, simultaneously shifting procurement geography toward East Asian module manufacturers and collapsing the cost-per-watt differential between space-grade and stratospheric applications. This substitution dynamic redistributes supplier power toward thin-film specialists while compressing margins for legacy array providers locked into long-term defense contracts.
Pricing Analysis
Defense procurement offices anchor contract structures around sole-source multi-year agreements for platforms exceeding 60-day endurance specifications. Three-tier pricing stratification separates classified ISR configurations from civilian-military hybrid systems and experimental research prototypes, with certification grade and payload integration complexity as primary differentiation drivers. Pricing pressure stems from buyer unbundling of airframe acquisition from sensor packages and flight operations, forcing platform OEMs to absorb integration costs. Commercial telecommunications operators exhibit highest price sensitivity due to performance-based agreement structures with flexible termination clauses.
Supply Chain Analysis
Strategic stockpiling of high-modulus carbon fiber prepregs dominates inventory strategy given single-source concentration among Japanese and US suppliers. Manufacturing draws from Japan, the United States, and Germany for ultra-lightweight composite airframes, with thin-film photovoltaic arrays sourcing predominantly from South Korea and Taiwan. Hydrogen storage systems and solid-oxide fuel cell stacks create additional dependencies on specialized chemical processing capabilities. Tariff exposure on aerospace-grade materials constitutes the primary structural risk. Distribution runs through defense prime contractor integration facilities and direct government procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in stratospheric aviation hinge on detect-and-avoid interoperability standards mandated by EASA and FAA rulemaking, creating ecosystem lock-in effects where early certification investments compound into sustained competitive moats.
For Market Incumbents: Shield classified program franchises by deepening backward integration into lightweight composite manufacturing and captive thin-film photovoltaic production. Accelerate FAA certification timelines for beyond-visual-line-of-sight operations to preempt European competitors from achieving reciprocal EASA approvals. Vertical integration into hydrogen fuel cell stack manufacturing addresses emerging payload-flexibility requirements.
For New Entrants and Emerging Players: Civilian emergency telecommunications relay services represent the most penetrable white-space segment, as defense procurement offices consolidate around established primes for ISR contracts. Target meteorological services in Indo-Pacific markets seeking stratospheric data continuity without platform ownership. Pursue partnership entry points with Indian DRDO programs as subsystem suppliers circumventing ITAR restrictions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private unmanned systems specialists holding experimental fuel cell architectures and perovskite solar cell flight qualifications. Five-to-ten-year viability hinges on successful navigation of dual-use certification pathways. Monitor FAA-EASA regulatory harmonization progress as the critical inflection signal for commercial scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Solar Cell Flight Qualification | Collapses cost-per-watt gap between space-grade and stratospheric photovoltaics for HALE platforms. |
| Hydrogen Fuel Cell Architecture Integration | Unlocks night-time endurance without battery mass penalties for heavier sensor payloads. |
| FAA Class A Airspace Certification | Reduces regulatory uncertainty for commercial operators pursuing beyond-visual-line-of-sight deployments. |
| Detect-and-Avoid System Interoperability | Mandates EASA-compliant sense-and-avoid standards before European commercial deployment authorization. |
| Indian Defense Modernization Partnership | Creates entry points for foreign subsystem suppliers facing US State Department ITAR export restrictions. |
Research Approach
Initial hypotheses were tested against primary input from defense procurement officers, platform engineering directors, regulatory affairs specialists at FAA and EASA, and telecommunications relay service operators, then refined through secondary validation against SEC 10-K filings, defense contract award databases, and thin-film photovoltaic industry association reports. Bottom-up platform deployment estimates triangulated with top-down defense budget allocation analysis across NATO member states.
Variance decomposition across the projection horizon isolates technology adoption curves, regulatory timeline uncertainty, and procurement cycle phasing as primary forecast drivers. Segmentation dimensions span platform type, deployment model, propulsion technology, and end-user category, with endurance specification thresholds and payload flexibility indices as HALE-specific modeling inputs. CAGRs derive from logistic diffusion curves fitted to historical program award patterns and technology readiness level transitions.
Underlying assumptions cover FAA-EASA regulatory harmonization progress, thin-film photovoltaic efficiency trajectories, and defense budget continuity across NATO members, with deviation risk concentrated in ITAR policy stringency and stratospheric weather pattern volatility. Revision becomes warranted when detect-and-avoid certification timelines or hydrogen fuel cell energy density improvements cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Drone Battery System Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market
Unmanned Systems
Integrated Range Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
Aerostat System Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
Tethered Manned Submersible Market
Unmanned Systems
Autonomous Drone Market
Unmanned Systems
Drone Parachute System Market