
 North America Hyperloop Technology Market | 2026-2036
North America Hyperloop Technology Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hyperloop Technology Market Intelligence
Aftermarket service revenue for pod maintenance and tube integrity monitoring is rewriting how infrastructure investors evaluate project lifecycle returns. Virgin Hyperloop leverages its early test-track data to anchor proprietary maintenance protocols. Hyperloop Transportation Technologies competes through open-source engineering alliances that lower barrier costs for regional consortia. TransPod specializes in linear induction motor refinement for cold-climate corridors across the Canadian prairies.
North America hyperloop technology deploys sealed vacuum tubes with magnetic levitation pods operating at partial atmospheric pressure, typically below 100 pascals, to eliminate aerodynamic drag and enable ground speeds exceeding aircraft on short-haul routes. The primary commercial purpose centers on displacing intercity aviation and long-haul trucking through sub-hour connections between metropolitan pairs under 1,500 kilometers. Maglev systems currently absorb the dominant share of R&D capital, while cargo transport applications in dedicated freight lines generate the fastest-growing segment of feasibility studies. Mixed-use systems combining passenger and freight operations concentrate margin pools where infrastructure costs amortize across dual revenue streams.
The US Department of Transportation coordinates with Transport Canada and Mexico's Secretariat of Infrastructure, Communications and Transportation to align cross-border safety standards for evacuated-tube transport. The Federal Railroad Administration's evolving guidance on high-speed ground transportation shapes pod structural requirements and emergency egress protocols that vendors must satisfy before commercial certification. Stakeholders must monitor which corridor secures the first full environmental impact statement approval, as this precedent will cascade through subsequent project financing structures across the continent.
Market Dynamics
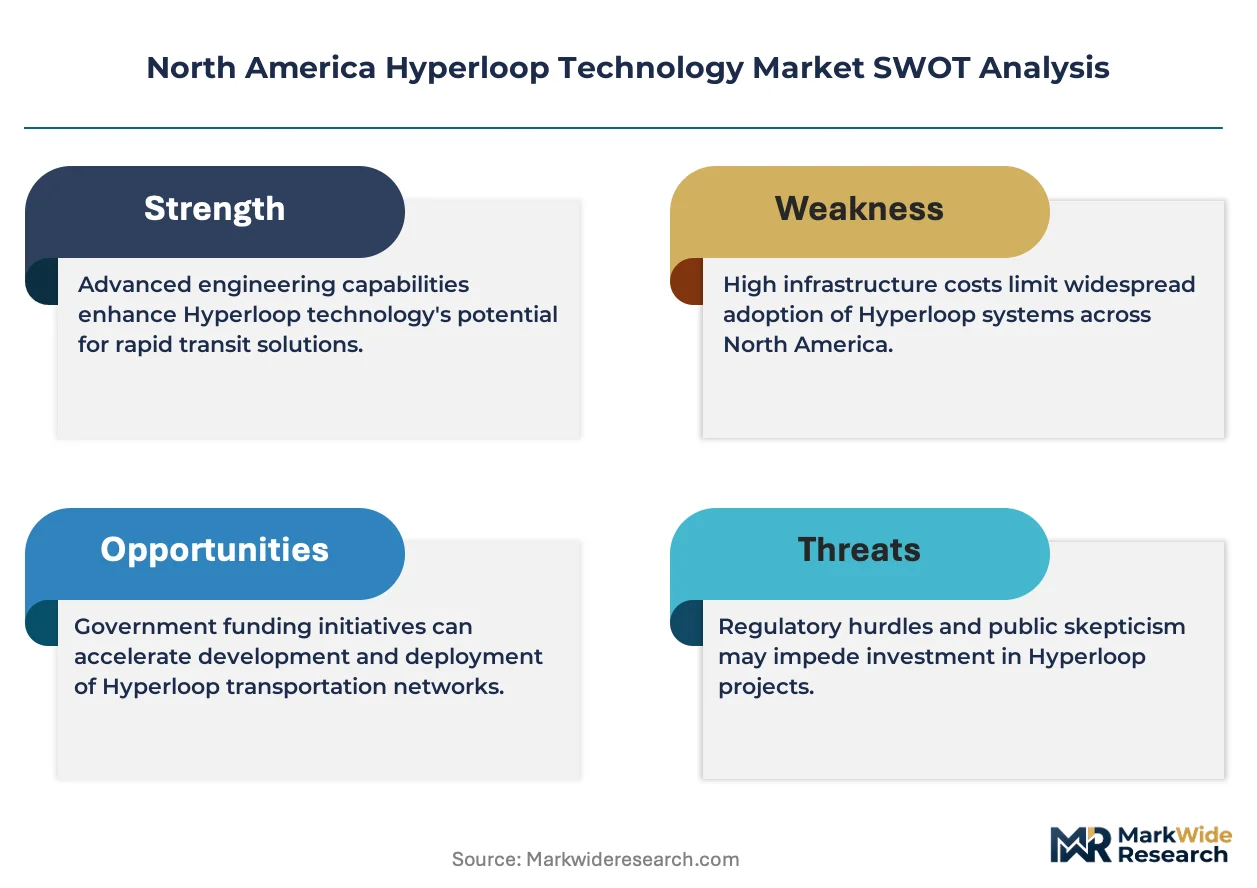
The Federal Railroad Administration's evolving guidance on high-speed ground transportation is compressing certification timelines and forcing pod manufacturers to front-load safety documentation. This regulatory momentum is redrawing how infrastructure consortia structure their capital deployment across the continent.
Growth Catalysts
- USDOT Framework Alignment:The Department of Transportation's emerging guidance for evacuated-tube transport accelerates environmental review sequencing for cross-state corridors.
- Freight Density Concentration:Texas-California cargo volumes justify dedicated tube infrastructure where trucking congestion imposes measurable economic drag.
- Magnetic Levitation Maturation:Linear induction motor efficiency gains above 500 km/h reduce per-kilometer energy costs below aviation equivalents on sub-1,500 km routes.
Market Restraints
- Steel Input Volatility:Tube fabrication requires specialized low-hydrogen steel grades subject to North American mill capacity constraints and tariff exposure.
- Vacuum Pump Supply Concentration:Industrial turbomolecular pump production concentrates in German and Japanese specialty manufacturers, creating procurement bottlenecks.
- Aviation Substitution Stickiness:Established airline route networks and loyalty programs retain passenger preference for sub-500 km segments where hyperloop targets entry.
Strategic Opportunities
- Canadian Prairie Corridors:Flat terrain and sparse population density between Calgary-Edmonton reduce land acquisition costs and environmental opposition relative to US routes.
- Port-Interior Freight Links:Dedicated cargo tubes connecting Los Angeles-Long Beach port complex to inland distribution centers bypass highway chokepoints.
- Cross-Border Standardization:US-Canada-Mexico regulatory harmonization under the Federal Railroad Administration's coordination framework creates first-mover certification advantages.
Industry Challenges
- Vacuum Engineering Talent Scarcity:The specialized skill set combining cryogenics, structural dynamics, and high-speed controls exceeds current North American university pipeline output.
- Pod Certification Timeline Compression:Proving structural integrity across pressure cycling, thermal expansion, and emergency egress scenarios requires test-track data that extends capital lockup periods.
- Utility Integration Complexity:Grid interconnection for linear motor power demands at 100+ MW per tube segment encounters transmission planning delays from regional system operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hyperloop Technology Market |
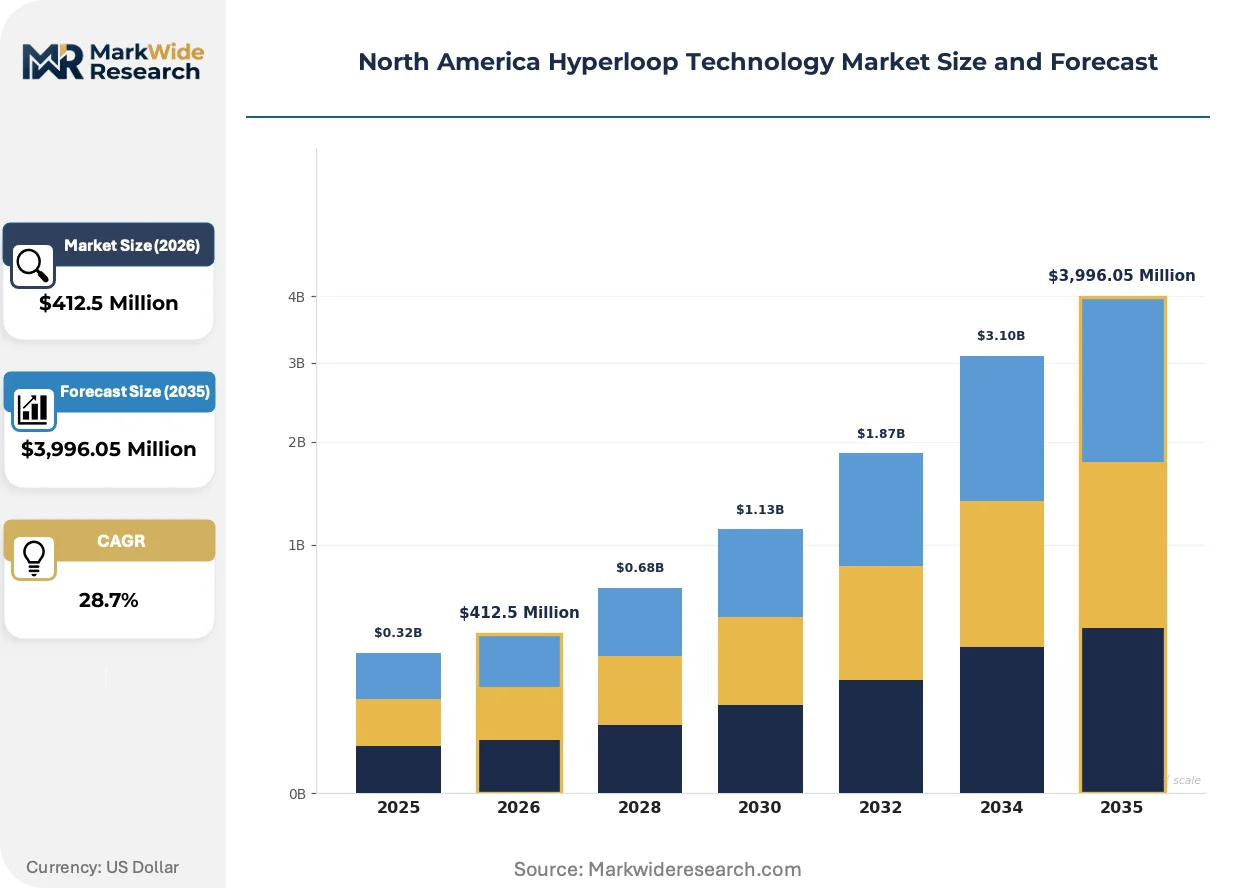
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $3,996.05 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Maglev, Vacuum Tube, Linear Induction, Air Bearings, Passive Magnetic Suspension Application: Intercity Travel, Cargo Transport, Emergency Response, Tourism, Corporate Transit Deployment Type: Public Networks, Private Corridors, Mixed-Use Systems, Dedicated Freight Lines, Research Pilots End User: Transportation Authorities, Logistics Providers, Tourism Operators, Emergency Services, Research Institutes |
| Companies Covered | Virgin Hyperloop, Hyperloop Transportation Technologies, Hyperloop One, Space Exploration Technologies Corp, AECOM, TransPod, Dinclix Groundworks, Tesla, Hardt Hyperloop, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hyperloop Technology Market Strategic Shifts & Innovations
Digital twin architectures are displacing physical prototyping as the primary validation layer for pod and tube subsystem integration. This shift compresses development cycles while expanding the data assets infrastructure operators can monetize post-deployment.
Passive magnetic levitation systems using permanent magnet arrays are virtualizing active electromagnet control complexity. Freight operators in the Texas triangle are piloting these configurations to reduce maintenance headcount. The technology is virtualizing the traditional trade-off between capital intensity and operational staffing levels.
The Federal Railroad Administration's forthcoming rulemaking on evacuated-tube emergency egress mandates redundant pressure-sealed evacuation chambers every 10 kilometers. Pod manufacturers must redesign interior layouts to accommodate these specifications. California test-track operators are absorbing the highest compliance costs as they retrofit early prototypes.
Shipper procurement of hyperloop capacity is fragmenting from long-term dedicated contracts toward spot-market mechanisms resembling aviation cargo charters. Third-party logistics providers are inserting themselves as aggregation intermediaries. This pattern is most visible in cross-border automotive parts movements between Michigan and Ontario assembly plants.
North America Hyperloop Technology Market Segmentation
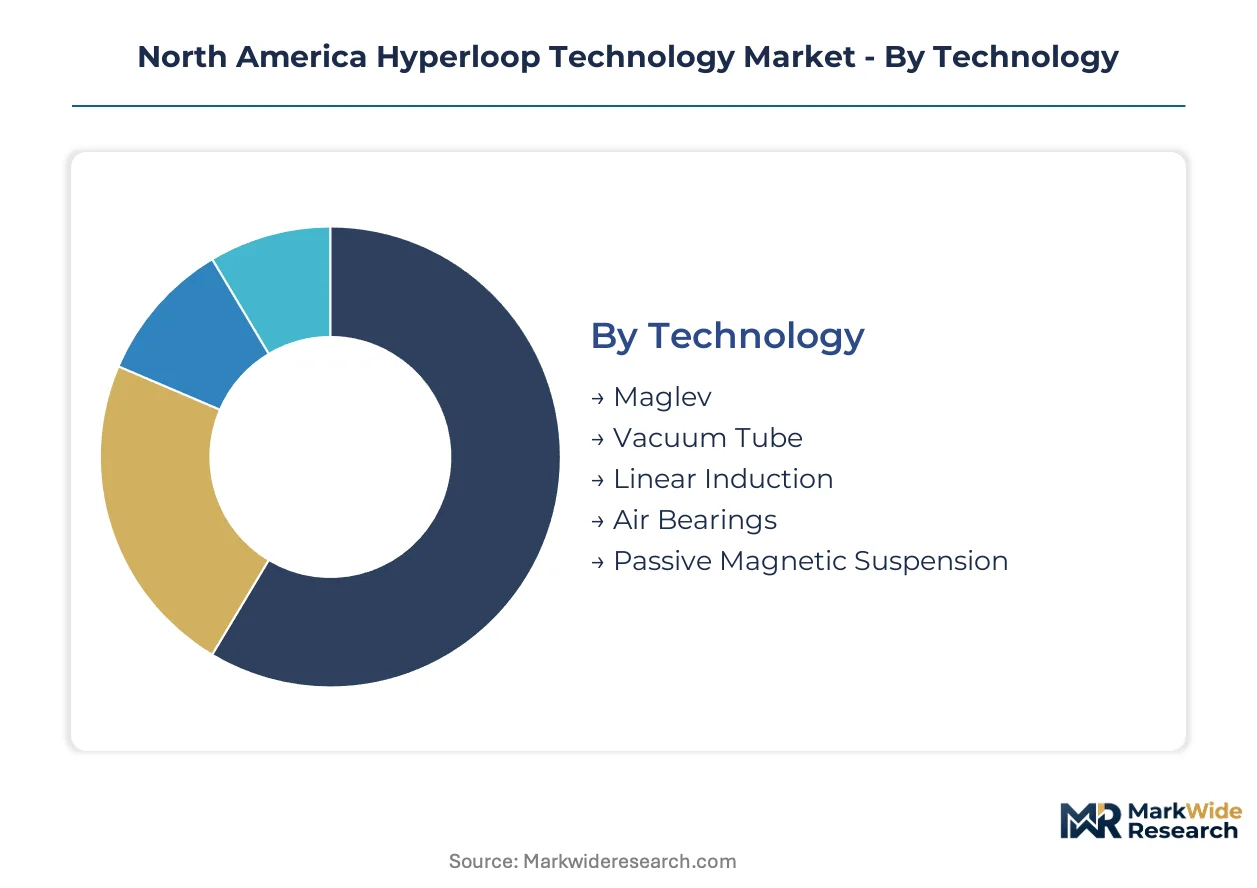
Segmentation in the North America hyperloop technology market reveals how capital allocation diverges between proven magnetic levitation platforms and experimental propulsion architectures. Infrastructure investors weigh technology maturity against corridor-specific performance requirements when selecting deployment configurations.
Technology:
The use-case spectrum stretches from high-speed passenger corridors demanding precise magnetic control to freight routes tolerating simpler air-bearing configurations.
- Maglev:Active electromagnetic suspension systems dominate California test-track deployments where pod stability at 1,000+ km/h is non-negotiable. Texas-California freight corridors anchor near-term procurement volumes as the Federal Railroad Administration certifies structural protocols.
- Vacuum Tube:Sealed evacuated environments below 100 pascals eliminate aerodynamic drag across all commercial routes. Canadian prairie corridors between Calgary-Edmonton exploit flat terrain to minimize tube fabrication complexity.
- Linear Induction:Propulsion via traveling magnetic fields powers acceleration without physical contact. Cold-climate Canadian routes favor this technology for reduced mechanical wear.
- Air Bearings:Pressurized air cushions support pod weight using ambient tube atmosphere. Research pilots in the US Southwest test these for low-speed cargo applications.
- Passive Magnetic Suspension:Permanent magnet arrays eliminate active control systems and reduce maintenance headcount. Freight operators in the Texas triangle pilot these for cost-sensitive dedicated lines.
Established volume favors Maglev; emerging adoption favors Passive Magnetic Suspension.
Application:
Customer archetypes range from time-sensitive corporate travelers to bulk cargo shippers seeking highway bypass capacity.
- Intercity Travel:Sub-hour connections between metropolitan pairs under 1,500 kilometers target aviation substitution. California's corridor development absorbs the dominant share of passenger-focused R&D.
- Cargo Transport:Dedicated freight tubes displace long-haul trucking through automated pod scheduling. Los Angeles-Long Beach port links to inland distribution centers generate the steepest expansion trajectory among feasibility studies.
- Emergency Response:Rapid medical supply and personnel movement during infrastructure disruption. Mountain West corridors test these for wildfire evacuation scenarios.
- Tourism:Premium passenger experiences leveraging novel transport technology. Nevada test-track operators explore adjacent hospitality revenue.
- Corporate Transit:Dedicated employee transport between headquarters and remote facilities. Texas energy sector campuses pilot closed-loop systems.
Freight density concentrates procurement decisions; passenger experience commands premium pricing.
Deployment Type:
Financing structures diverge sharply between public infrastructure bonds and private capital deployment.
- Public Networks:State-backed corridors integrating with existing transit authorities. California and Texas transportation departments lead environmental review sequencing.
- Private Corridors:Corporate-funded tubes serving single-tenant logistics needs. E-commerce fulfillment networks between Midwest distribution hubs anchor early commitments.
- Mixed-Use Systems:Combined passenger and freight operations amortizing infrastructure across dual revenue streams. These configurations maximize margin pools where capital costs demand rapid utilization.
- Dedicated Freight Lines:Single-purpose cargo tubes optimized for automated loading and scheduling. Port-interior connections bypass highway chokepoints.
- Research Pilots:Short-track validation facilities for subsystem certification. Nevada and California host competing test-bed operations.
Mixed-use architectures attract infrastructure fund capital; research pilots consume grant financing.
End User:
Procurement authority fragments across public agencies, private logistics platforms, and specialized operators.
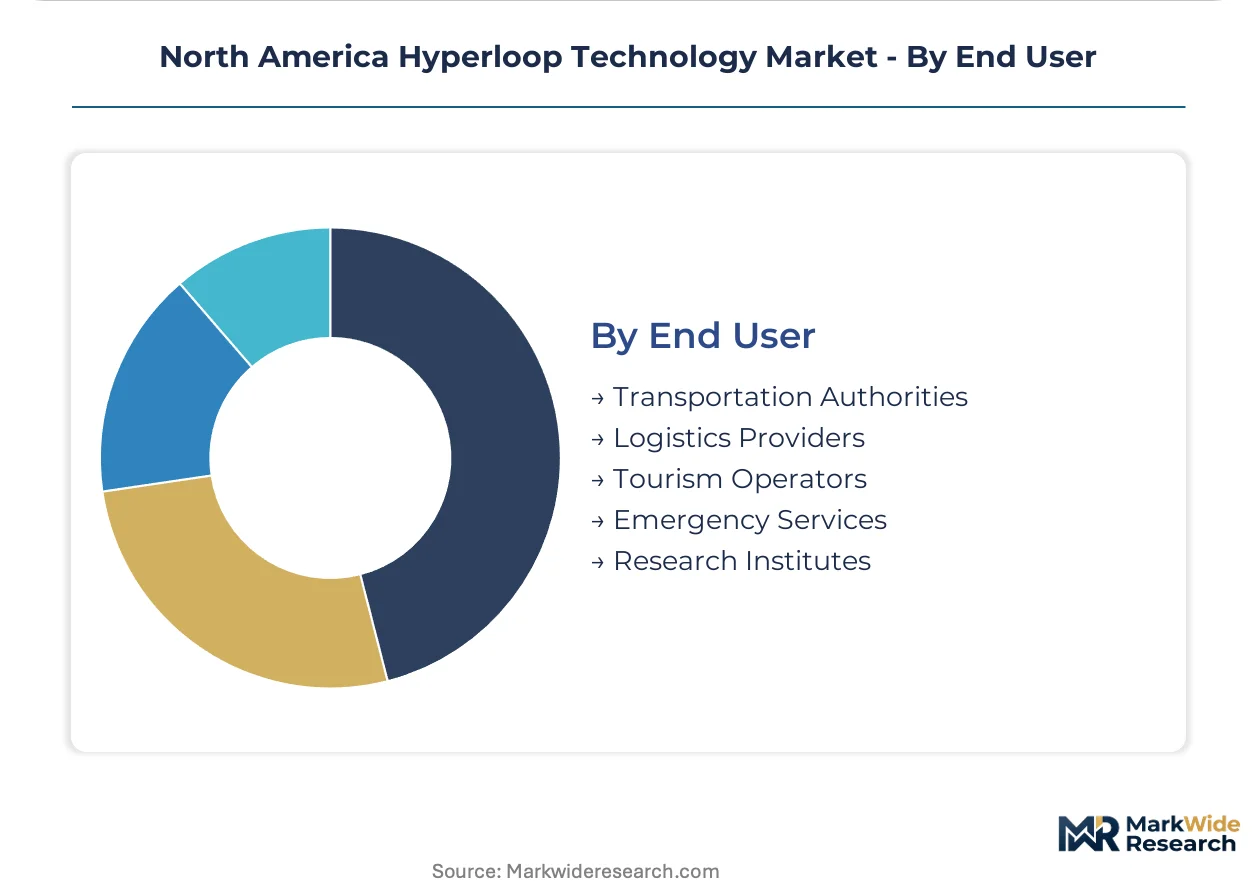
- Transportation Authorities:State and municipal agencies controlling right-of-way and environmental approvals. The Federal Railroad Administration coordinates certification requirements across jurisdictions.
- Logistics Providers:Third-party freight aggregators contracting tube capacity for shipper networks. Cross-border automotive parts movements between Michigan and Ontario demonstrate procurement patterns.
- Tourism Operators:Experience-focused ventures packaging hyperloop transit with destination programming. Nevada and California hospitality investors evaluate adjacent revenue.
- Emergency Services:Federal and state disaster response agencies requiring guaranteed priority access. Mountain West corridor planning incorporates evacuation protocols.
- Research Institutes:Universities and national laboratories advancing vacuum engineering and materials science. Canadian and US energy departments fund cold-climate propulsion studies.
Logistics providers drive volume contracting; research institutes shape technology roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North America. The United States prioritizes passenger corridor development between major metropolitan pairs. Canada concentrates on cold-climate freight applications across flat prairie terrain. Mexico explores cross-border logistics integration with US distribution networks.
United States
California's test-track corridor development anchors passenger-focused R&D investment. The Federal Railroad Administration's evolving guidance on high-speed ground transportation compresses certification timelines for pod manufacturers. Texas-California freight corridors generate the dominant share of near-term deployment feasibility studies.
Canada
Flat terrain and sparse population density between Calgary-Edmonton reduce land acquisition costs for tube infrastructure. Transport Canada coordinates with the Federal Railroad Administration to align cross-border safety standards for evacuated-tube transport. Prairie corridor development favors linear induction motor refinement for cold-climate operation.
Mexico
Cross-border cargo volumes between manufacturing centers and US distribution hubs drive corridor feasibility analysis. Mexico's Secretariat of Infrastructure, Communications and Transportation participates in trilateral standardization efforts with US and Canadian regulators. Northern border states concentrate preliminary route planning for port-interior freight links.
North America Hyperloop Technology Market Key Industry Players
Capability concentration sits with technology developers holding proprietary test-track data; scale advantage sits with infrastructure engineering conglomerates possessing cross-border project execution experience. The market structure separates into three tiers: integrated system developers, component specialists, and engineering-procurement-construction partners. Dominant competitive moves include strategic alliances between technology developers and regional infrastructure consortia, plus vertical integration into maintenance and lifecycle service revenue streams.
Within the integrated system developer tier, Virgin Hyperloop and Hyperloop Transportation Technologies occupy positions as archetype representatives of divergent strategic approaches. TransPod anchors the cold-climate specialization vector with Canadian prairie corridor focus. AECOM exemplifies the engineering-procurement-construction partnership model that infrastructure investors require for capital deployment at scale.
| Leading Market Players |
|---|
| Virgin Hyperloop |
| Hyperloop Transportation Technologies |
| Hyperloop One |
| Space Exploration Technologies Corp |
| AECOM |
| TransPod |
| Dinclix Groundworks |
| Tesla |
| Hardt Hyperloop |
| Others |
Cost & Logistics Intelligence
Texas-California freight corridors anchor cost dynamics where specialized steel procurement and vacuum pump sourcing concentrate supplier power, forcing downstream price stratification between dedicated freight contracts and mixed-use passenger systems.
Pricing Analysis
Long-term offtake agreements dominate corridor financing, with dedicated freight lines commanding fixed-rate structures that insulate shippers from steel input volatility. Price differentiation hinges on certification grade under Federal Railroad Administration protocols and volume scale across tube segments. Cost compression in passenger-facing tiers intensifies as aviation substitution stickiness forces competitive positioning against established airline loyalty programs. Logistics providers exhibit highest price sensitivity due to thin margins on automotive parts movements, while tourism operators absorb premium pricing for experiential packaging.
Supply Chain Analysis
Extended payment terms from German and Japanese turbomolecular pump manufacturers strain working capital for tube fabrication consortia. Steel sourcing draws from domestic mills in the United States and specialized European producers, while linear induction motor components originate from East Asian precision manufacturers. Single-source vulnerability in vacuum engineering talent compounds procurement risk. Distribution runs through engineering-procurement-construction partnerships that coordinate cross-border project execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American hyperloop development sits in early-cycle expansion as Federal Railroad Administration guidance compression accelerates project approvals beyond historical infrastructure timelines.
For Market Incumbents: Harden proprietary maintenance protocol advantages derived from California test-track data against open-source engineering alliances that erode service revenue moats. Deepen backward integration into specialized low-hydrogen steel supply through captive offtake agreements with domestic mills, insulating fabrication costs from tariff exposure.
For New Entrants and Emerging Players: Pursue Canadian prairie corridor opportunities where flat terrain and sparse population density reduce land acquisition barriers relative to contested US routes. Target cold-climate linear induction motor specialization as the most penetrable technology vector, leveraging Transport Canada's coordination with US regulators for cross-border certification advantages.
For Investors and Strategic Acquirers: Component specialists with vacuum engineering and cryogenic control capabilities offer acquisition exposure to bottlenecked technical talent pools. Long-term viability across a multi-decade infrastructure horizon depends on which corridor secures first full environmental impact statement approval, as this precedent will cascade through subsequent project financing structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Test-Track Data Monetization | Virgin Hyperloop's proprietary maintenance protocols create recurring revenue streams from infrastructure operators. |
| Open-Source Engineering Alliance | Hyperloop Transportation Technologies lowers barrier costs for regional consortia through shared R&D burden. |
| Cold-Climate Propulsion Specialization | TransPod's linear induction motor refinement targets Calgary-Edmonton prairie corridors with reduced mechanical wear. |
| Cross-Border Regulatory Harmonization | US-Canada-Mexico trilateral coordination under Federal Railroad Administration frameworks accelerates certification timelines. |
| Digital Twin Architecture Deployment | Virtual validation layers compress development cycles while expanding post-deployment data monetization opportunities. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with infrastructure engineering directors, vacuum system procurement leads, Federal Railroad Administration policy officers, tube fabrication plant managers, and logistics provider contract specialists. Secondary validation drew from US Department of Transportation guidance documents, Transport Canada technical bulletins, SEC filings from engineering-procurement-construction partners, customs data on steel and pump imports, and project development databases tracking environmental review sequencing. Bottom-up corridor feasibility assessments triangulated against top-down infrastructure investment flow analysis.
Calibration against historical infrastructure deployment patterns and cross-modal transport substitution elasticities shaped the analytical framework across the analysis window. Segmentation dimensions modeled include technology type, application purpose, deployment financing structure, and regional regulatory cluster. CAGRs derived from corridor-specific capital deployment schedules and utilization ramp assumptions. Forecast inputs incorporated Federal Railroad Administration rulemaking timelines and steel mill capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in long-term interest rate trajectories and infrastructure bond market liquidity would shift the trajectory of project financing viability. Forecasts reflect documented assumptions regarding regulatory approval sequencing and cross-border standardization progress. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
Drone Tethered Stations Market
Unmanned Systems
Autonomous Pods Market
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Micro Tactical Ground Robot Market
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
Europe Military Unmanned Vehicles Market
Unmanned Systems
Military Robots Market
Unmanned Systems
Drone Battery System Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
Integrated Range Market
Unmanned Systems
Rotary-Wing Lidar Drone Market