
 Unmanned Surface Vehicle Market | 2026-2036
Unmanned Surface Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Unmanned Surface Vehicle Market Outlook
Project finance and operational leasing for autonomous maritime fleets is narrowing the capital barrier between defense primes and mid-tier system integrators. Textron Systems Corporation leverages its military contracting infrastructure to sustain long-term service agreements with naval customers. L3Harris Technologies, Inc. anchors its position through proprietary communication architectures that dominate command-and-control linkages for remote vessels. Elbit Systems Ltd. competes by integrating electro-optical payloads with autonomous navigation stacks for littoral combat applications.
An unmanned surface vehicle is a self-propelled craft operating on water without onboard human crew, typically measuring 2 to 16 meters in length and integrating GPS navigation, hydrographic surveying suites, and encrypted communication systems for remote or fully autonomous mission execution; its primary commercial and industrial purpose spans marine exploration, coastal patrolling, and subsea infrastructure inspection. Autonomous boats currently occupy the largest product category due to proven reliability in defense logistics and port security. Surface drones represent the fastest-expanding technology segment as offshore energy operators deploy them for persistent environmental monitoring. The application dimension shows patrolling and search and rescue commanding the deepest margin pools because defense budgets prioritize mission-ready platforms over research-grade configurations.
The U.S. Coast Guard and FAA coordinate air-sea interoperability standards for mixed autonomous operations in domestic waters, while the EU Maritime Safety Agency enforces certification requirements under the EU Green Deal framework for low-emission autonomous craft. These regulatory layers shape demand by dictating sensor redundancy, cybersecurity protocols, and emissions benchmarks that determine market access for platform developers. Stakeholders must monitor evolving liability frameworks for autonomous collisions and decide whether to pursue type-certification early or adapt retrofit strategies as rules crystallize.
Market Dynamics
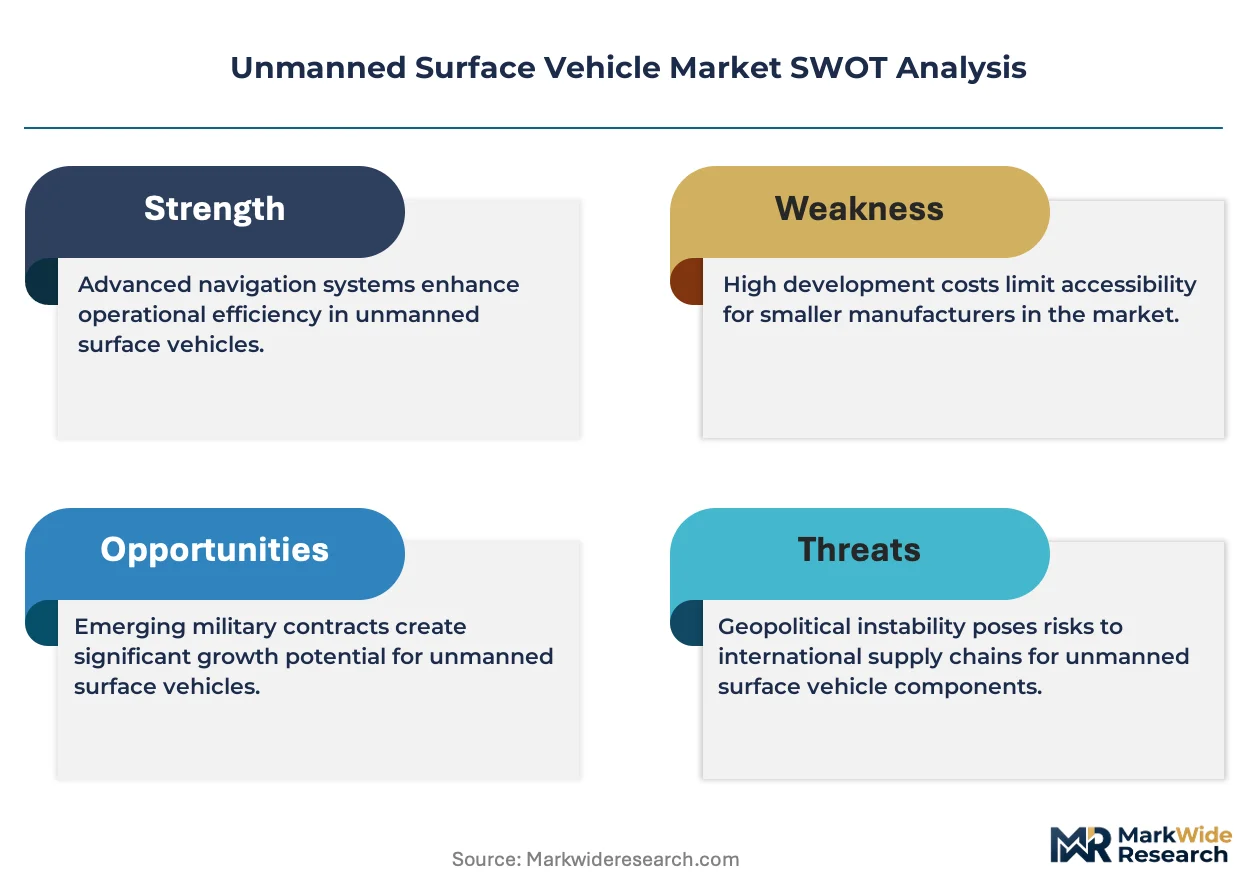
NATO naval procurement is compressing development cycles for autonomous patrol platforms while IMO collision-avoidance mandates force sensor redundancy upgrades across all commercial deployments.
Growth Catalysts
- IMO Safety Protocols:Mandatory encrypted command links and redundant collision-avoidance systems are creating baseline demand for certified platform architectures across international shipping lanes.
- Offshore Energy Monitoring:Persistent environmental surveillance requirements from North Sea oil operators are pulling surface drones into daily operational workflows.
- Norway:Kongsberg-led hydrographic clustering concentrates R&D infrastructure and attracts defense procurement contracts for mine-countermeasure missions.
Market Restraints
- Lithium-Ion Battery Supply:Raw material volatility in cobalt and nickel processing constrains platform production scaling and extends lead times for high-endurance craft.
- Sensor Integration Complexity:Fusing radar, lidar, and electro-optical streams into unified navigation stacks demands specialized engineering talent that remains scarce in most maritime clusters.
- FAA-Coast Guard Coordination Gaps:Unclear jurisdictional boundaries for mixed air-sea autonomous operations create certification delays and operational uncertainty in US domestic waters.
Strategic Opportunities
- Baltic States:Estonia, Latvia, and Lithuania are expanding coastal surveillance budgets without established domestic suppliers, creating first-mover windows for platform vendors.
- Subsea Cable Inspection:Telecommunications and energy infrastructure operators are migrating from crewed vessels to persistent autonomous monitoring for seabed asset integrity.
- EU Green Deal Certification:Low-emission autonomous craft mandates are privileging electric and hydrogen fuel-cell propulsion architectures over conventional diesel systems.
Industry Challenges
- Maritime AI Engineering Talent:Shortages in autonomous navigation algorithm development and sensor fusion expertise bottleneck platform verification timelines.
- Type-Certification Backlogs:National maritime safety agencies lack standardized testing protocols for fully autonomous vessels, extending approval cycles and freezing deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unmanned Surface Vehicle Market |
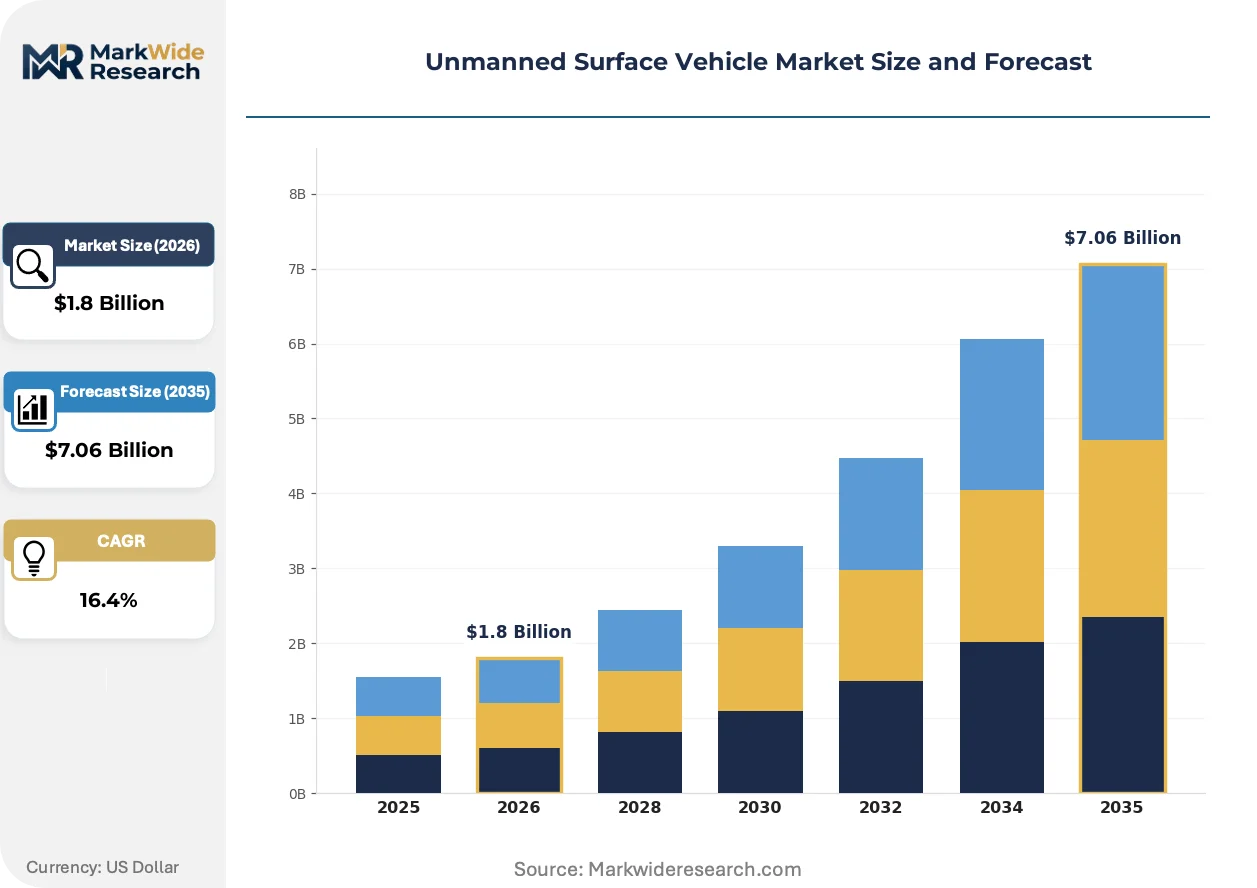
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wave Gliders, Autonomous Boats, Surface Drones, Unmanned Craft Technology: GPS Navigation, Hydrographic Surveying, Communication Systems, Remote Sensing End User: Defense, Environmental Monitoring, Research Institutions, Oil & Gas Application: Marine Exploration, Search & Rescue, Fisheries Management, Patrolling |
| Companies Covered | ECA Group, Textron Systems Corporation, L3Harris Technologies, Inc., Israel Aerospace Industries Ltd., Exail Technologies, Elbit Systems Ltd., Teledyne Technologies Inc., Thales Group, Kongsberg Gruppen ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unmanned Surface Vehicle Market Strategic Shifts
Autonomous navigation architectures are fragmenting competitive advantage away from hull manufacturing toward software-defined mission systems and encrypted command infrastructure.
Edge-computing sensor fusion is rendering obsolete centralized shore-based processing for real-time obstacle detection and path planning. Offshore energy operators in the North Sea are deploying these architectures for persistent platform monitoring without continuous satellite uplink dependency. The shift is compressing latency requirements and privileging vendors with in-house AI stack development over hardware-assembly specialists.
EU Green Deal low-emission mandates are restructuring propulsion procurement criteria for autonomous craft operating in European Economic Area waters. Certification pathways now prioritize hydrogen fuel-cell and battery-electric architectures with documented lifecycle carbon footprints. Defense and commercial buyers are responding by embedding emissions benchmarks into platform RFP specifications.
Leasing-based fleet financing is displacing outright purchase for mid-tier system integrators seeking operational flexibility without capital lock-in. Maritime logistics providers in Scandinavian waters are adopting this model to scale autonomous patrol capacity against seasonal demand fluctuations. The pattern concentrates revenue stability with platform-as-a-service vendors while fragmenting traditional shipbuilder customer relationships.
Unmanned Surface Vehicle Market Segmentation
Platform differentiation in unmanned surface vehicles hinges on payload modularity, endurance architecture, and command-link encryption standards. Procurement patterns diverge sharply between defense primes seeking mission-ready systems and commercial operators prioritizing sensor flexibility over hull performance.
Product Type:
Cost tier structures across hull architectures separate premium defense-grade platforms from commercial survey configurations with stripped-down navigation stacks.
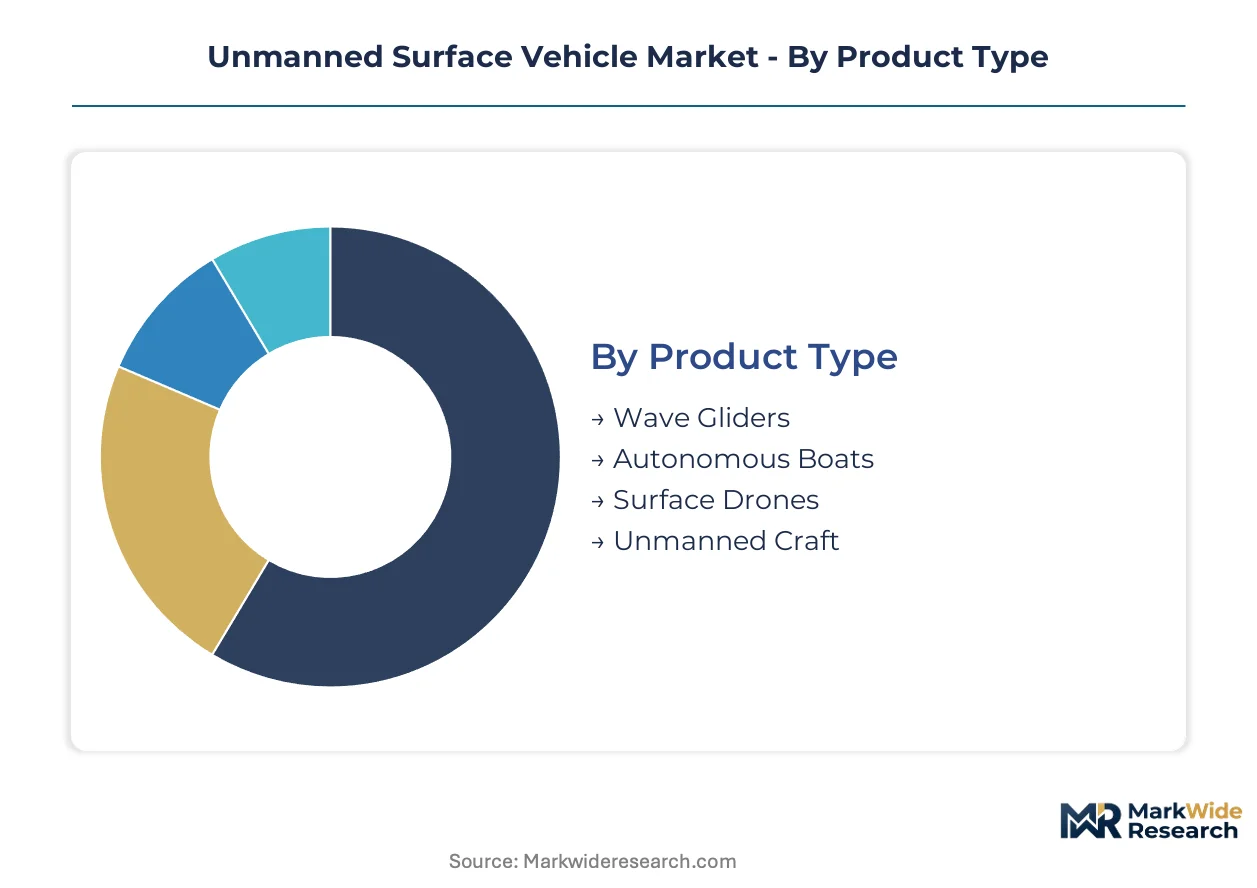
- Autonomous Boats:Self-propelled vessels measuring 4 to 12 meters integrate diesel-electric or battery-electric propulsion with modular payload bays for mine countermeasures or logistics transport. NATO naval procurement in Norway and the Baltic States concentrates orders for patrol-configured variants with redundant collision-avoidance systems mandated by IMO protocols.
- Surface Drones:Compact platforms under 6 meters deploy persistent environmental monitoring for North Sea offshore energy operators, leveraging edge-computing sensor fusion to reduce satellite uplink dependency. EU Green Deal low-emission mandates are restructuring procurement criteria toward hydrogen fuel-cell and battery-electric architectures with documented lifecycle carbon footprints.
- Wave Gliders:Wave-powered platforms harvest surface motion for propulsion, enabling multi-month oceanographic data collection without refueling.
- Unmanned Craft:General-purpose hulls serve research institutions and coast guards with configurable mission modules.
Autonomous boats command the established base. The steepest expansion runs through surface drones.
Technology:
Application requirements determine which sensor and command layers dominate platform specification sheets.
- Communication Systems:Encrypted command links with frequency-hopping architectures dominate defense procurement, with L3Harris proprietary protocols establishing de facto standards for NATO remote vessel operations. FAA-Coast Guard coordination gaps in US domestic waters create certification delays for mixed air-sea autonomous deployments.
- GPS Navigation:Multi-constellation receivers integrating Galileo, GPS, and GLONASS signals provide redundancy for littoral combat missions where jamming risks escalate.
- Hydrographic Surveying:Multibeam sonar and sub-bottom profiler integration anchors Kongsberg-led clustering in Norway for seabed mapping contracts.
- Remote Sensing:Electro-optical and infrared payload fusion supports persistent surveillance without continuous shore-based processing.
Communication systems anchor defense procurement volumes. GPS navigation is climbing fastest as commercial operators demand jamming resilience.
End User:
Customer type fragmentation separates budget-certain defense programs from cyclical commercial deployment schedules.
- Defense:Naval procurement across NATO members accelerates platform orders for autonomous patrol and mine-countermeasure missions, with leasing-based fleet financing displacing outright purchase for mid-tier system integrators seeking operational flexibility.
- Environmental Monitoring:North Sea oil operators deploy surface drones for persistent emissions and water-quality surveillance, pulling vendors into daily operational workflows.
- Oil & Gas:Subsea infrastructure inspection budgets are migrating from crewed vessels to persistent autonomous monitoring for seabed asset integrity.
- Research Institutions:Academic and governmental oceanographic programs prioritize data precision over mission endurance, funding smaller hull configurations.
Defense commands the established base. Environmental monitoring is gaining share fastest as offshore energy operators scale autonomous patrol capacity.
Application:
Maturity gradients across mission profiles separate proven operational workflows from experimental deployment categories.
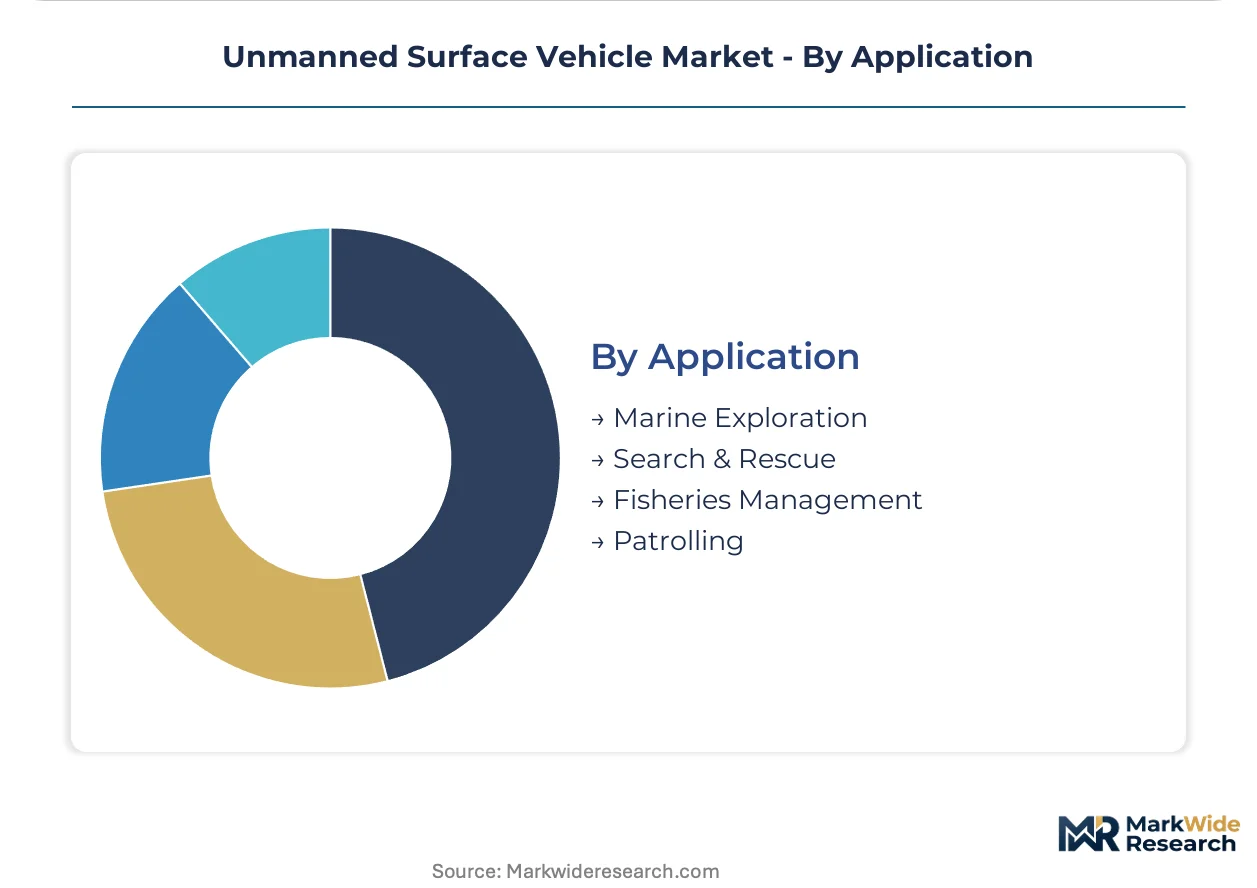
- Patrolling:Coastal surveillance and harbor security missions command the deepest margin pools because defense budgets prioritize mission-ready platforms over research-grade configurations, with Estonia, Latvia, and Lithuania expanding budgets without established domestic suppliers.
- Search & Rescue:Autonomous platforms reduce response latency in maritime distress scenarios, though liability frameworks for autonomous collisions remain unresolved across most jurisdictions.
- Marine Exploration:Deep-water hydrographic mapping contracts concentrate with Kongsberg-led Norwegian clustering.
- Fisheries Management:Illegal fishing detection and stock assessment applications remain nascent, constrained by sensor integration complexity and scarce maritime AI engineering talent.
Patrolling commands the established base. Search and rescue shows the steepest expansion trajectory as coast guards validate operational concepts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices and offshore energy operators concentrate autonomous vessel orders in maritime clusters with established hydrographic engineering infrastructure and permissive testing waters.
Norway
NATO mine-countermeasure contracts and North Sea oil operator demand pull platform orders toward Kongsberg-led clustering in Horten and Kongsberg. The Norwegian Maritime Authority enforces redundant collision-avoidance certification under IMO protocols. Bergen anchors subsea technology integration for persistent seabed monitoring missions.
United States
Naval Research Program funding and Coast Guard interoperability requirements drive autonomous patrol platform development. FAA coordination with the Coast Guard creates certification complexity for mixed air-sea operations in domestic waters. Textron Systems leverages military contracting infrastructure from facilities in Louisiana and Massachusetts to sustain service agreements.
United Kingdom
Royal Navy autonomous mine-hunting programs and offshore wind farm inspection contracts concentrate demand in Scottish and southern English ports. The Maritime and Coastguard Agency implements IMO-mandated encrypted command link standards for commercial deployments. Plymouth hosts a defense-focused cluster integrating sonar payloads with autonomous navigation stacks.
France
Naval Group procurement and English Channel maritime security operations sustain platform orders for littoral combat configurations. ANSM and maritime prefectures enforce cybersecurity protocols for remote vessel command links under EU Green Deal low-emission mandates. Brest concentrates hydrographic survey vessel integration with autonomous mission systems.
Estonia
Baltic Sea coastal surveillance expansion and absence of domestic suppliers create first-mover windows for platform vendors. The Estonian Maritime Administration adopts IMO collision-avoidance standards while building autonomous vessel testing capacity. Tallinn anchors a nascent cluster attracting Nordic defense technology partnerships.
Unmanned Surface Vehicle Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. Defense primes leverage military contracting infrastructure to sustain long-term service agreements, while mid-tier system integrators pursue operational leasing models to narrow capital barriers. Three archetypes dominate: full-stack platform developers, payload-agnostic hull manufacturers, and command-link encryption specialists. Competitive moves concentrate on strategic partnerships for sensor fusion capabilities and geographic expansion into Baltic coastal surveillance markets.
Within the full-stack defense tier, Kongsberg Gruppen ASA represents Norwegian hydrographic clustering, while Textron Systems Corporation exemplifies military contracting infrastructure sustaining service agreements. L3Harris Technologies, Inc. occupies a position anchoring encrypted command-link standards for NATO remote vessel operations. These three exemplify how proprietary communication architectures and integrated mission systems separate premium defense procurement from commercial survey configurations.
| Leading Market Players |
|---|
| ECA Group |
| Textron Systems Corporation |
| L3Harris Technologies, Inc. |
| Israel Aerospace Industries Ltd. |
| Exail Technologies |
| Elbit Systems Ltd. |
| Teledyne Technologies Inc. |
| Thales Group |
| Kongsberg Gruppen ASA |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Norwegian hull manufacturing is tightening supplier leverage and compressing procurement timelines for NATO defense contracts. Platform vendors are responding with indexed cost-plus structures that pass through lithium-ion battery volatility while locking in multi-year service margins.
Pricing Analysis
Cost-plus contracts with cobalt and nickel indexation dominate NATO defense procurement, insulating vendors from raw material swings while capping buyer exposure. Three-tier pricing structure across mission-ready defense systems, commercial survey configurations, and research-grade hulls separates certification-grade redundancy from stripped-down navigation stacks. Pricing pressure stems from Baltic States coastal surveillance programs demanding budget-tier platforms without domestic supplier alternatives. Commercial offshore operators exhibit highest price sensitivity due to cyclical energy capex cycles, while defense primes absorb premiums for encrypted command-link architectures.
Supply Chain Analysis
Extended payment terms from Norwegian and UK defense procurement offices are forcing mid-tier integrators toward supply-chain finance facilities anchored by platform-as-a-service revenue streams. Manufacturing concentrates in Norway, the United States, and France, with Kongsberg-led clustering in Horten and Brest anchoring hydrographic payload integration. Production draws from lithium-ion cell supply out of South Korea and Japan, plus specialized maritime AI engineering talent concentrated in Scandinavian clusters. Single-source vulnerability in encrypted command-link chipsets creates procurement risk for NATO-aligned programs. Distribution runs through military contracting infrastructure for defense segments and operational leasing networks for commercial energy operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in Baltic coastal surveillance procurement, where Estonia, Latvia, and Lithuania are expanding budgets without established domestic platform suppliers. This demand-side shift creates niche entry windows for specialized vendors.
For Market Incumbents: Entrench proprietary communication architectures as de facto NATO standards through long-term service agreements with naval procurement offices. Deepen backward integration into edge-computing sensor fusion stacks to defend margin position against software-defined mission system competitors. Priority lever: certification investment under IMO collision-avoidance protocols to freeze out retrofit-dependent challengers. For New Entrants and Emerging Players: Build out operational leasing infrastructure targeting North Sea offshore energy operators seeking seasonal autonomous patrol flexibility without capital lock-in. Most penetrable white-space: hydrogen fuel-cell propulsion architectures for EU Green Deal compliance. Go-to-market angle: platform-as-a-service bundling persistent environmental monitoring with seabed asset integrity verification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across surface drone manufacturing as leasing models displace outright purchase and fragment shipbuilder customer relationships. Long-term viability favors full-stack platform developers with in-house AI navigation stacks over hardware-assembly specialists. Acquisition target archetype: mid-tier system integrators with established Baltic States procurement relationships. Signal to watch: FAA-Coast Guard coordination resolution for mixed air-sea certification pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Platform-as-a-Service Expansion | Leasing models concentrate revenue stability with vendors while fragmenting traditional shipbuilder relationships across Scandinavian waters. |
| Encrypted Command-Link Certification | Proprietary communication architectures establish de facto NATO standards that lock in long-term defense procurement contracts. |
| Hydrogen Fuel-Cell Propulsion Development | EU Green Deal low-emission mandates privilege zero-carbon architectures over conventional diesel systems in European Economic Area waters. |
| Edge-Computing Sensor Fusion Integration | In-house AI stack development privileges vendors over hardware-assembly specialists by compressing latency for real-time obstacle detection. |
| Baltic States Market Entry | First-mover positioning in Estonia, Latvia, and Lithuania captures coastal surveillance expansion without established domestic supplier competition. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of NATO procurement databases, IMO regulatory filings, offshore energy operator capex disclosures, and maritime safety agency certification records. Primary interviews engaged naval program officers, autonomous vessel platform engineers, coast guard procurement leads, and hydrographic survey contract managers. Secondary validation drew from EU Maritime Safety Agency enforcement guidelines, national maritime authority type-certification protocols, and customs data for autonomous platform trade flows. Bottom-up hull production estimates triangulated against top-down defense budget allocation analysis.
Forecast inputs include platform order backlogs, IMO protocol implementation timelines, offshore energy operator deployment schedules, and lithium-ion battery supply constraints. Segmentation dimensions span product type, technology layer, end-user category, and application mission profile, with additional modeling of regional regulatory cluster effects across NATO, EU Green Deal, and FAA-Coast Guard jurisdictional boundaries. CAGRs derive from production capacity scaling curves and procurement contract velocity analysis. Industry-specific inputs incorporate mine-countermeasure mission readiness requirements and persistent environmental monitoring duty-cycle specifications.
The forecast holds incumbent behavior within observed patterns; aggressive moves by full-stack platform developers or hydrogen propulsion specialists would shift outcomes. Macroeconomic deviation in offshore energy investment cycles, regulatory acceleration in autonomous collision liability frameworks, or breakthroughs in solid-state battery endurance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Autonomous Drone Platform Market
Unmanned Systems
Automated Weapon System Market
Unmanned Systems
United States ROV Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
North America ROV Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Tethered Manned Submersible Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
Military Robots Market
Unmanned Systems
Military Autonomous Robot Market