
 Rehabilitation Robot Gloves Market | 2026-2036
Rehabilitation Robot Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Rehabilitation Robot Gloves Market Insights
CE-marked medical device certification is reorganizing competitive tiers as manufacturers invest in clinical validation and quality management systems. Neofect leverages its software-hardware integration to sustain recurring revenue from digital therapy platforms. Bioservo Technologies anchors its position through proprietary SEMG sensor technology that differentiates its powered glove portfolio from commodity alternatives.
Rehabilitation robot gloves are wearable electromechanical devices that combine actuators, force sensors, and control algorithms to assist or resist hand movements during therapeutic exercises, typically delivering precise torque ranges of 0.5 to 5 Nm per digit to restore motor function after neurological injury. Their primary purpose is to automate repetitive task-specific training that would otherwise require continuous therapist supervision, reducing labor intensity while standardizing dose metrics. Soft robotic gloves command premium positioning in homecare channels where patient comfort and portability override clinical-grade force output, while exoskeleton variants dominate hospital procurement budgets through higher reimbursement codes and measurable outcome documentation. Artificial intelligence integration represents the fastest-growing technology layer as machine learning algorithms adapt resistance profiles to real-time electromyography signals, though haptic feedback modules still capture the largest installed base due to lower per-unit costs.
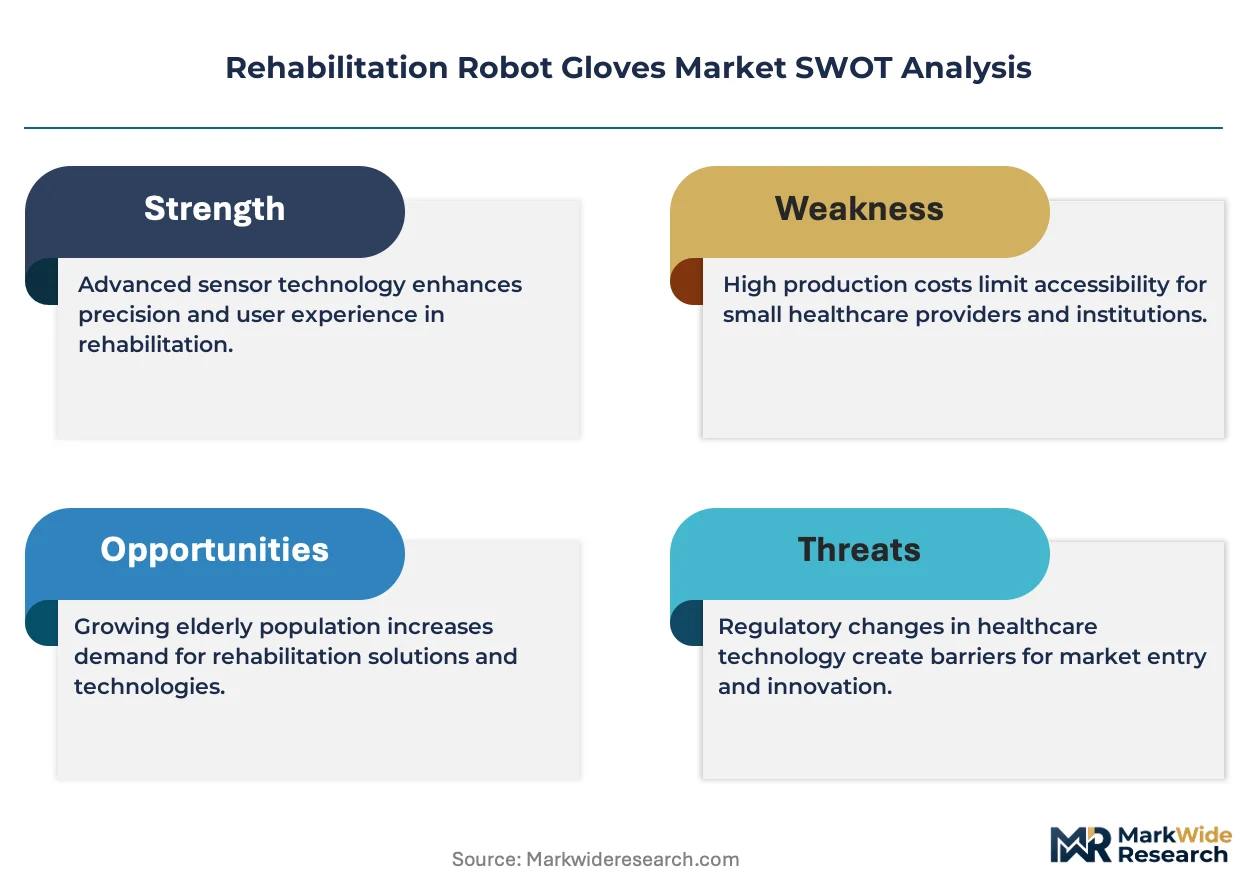
FDA 510(k) clearances shape United States market access by requiring substantial equivalence demonstrations for powered rehabilitation devices, while the EU Medical Device Regulation mandates clinical evaluation reports and post-market surveillance systems for CE marking eligibility. Japan's PMDA enforces QMS ministerial ordinances that extend approval timelines but reward compliant manufacturers with preferential coverage under the public health insurance fee schedule. Stakeholders must monitor evolving reimbursement decisions from national health technology assessment bodies, as these determinations will separate commercially viable indications from self-pay niche applications.
Market Dynamics
Reimbursement code expansion for powered orthotic devices is compressing sales cycles and forcing manufacturers to restructure clinical evidence packages around functional outcome metrics rather than hardware specifications alone.
Growth Catalysts
- Japan's PMDA QMS pathway:Preferential coverage under the public health insurance fee schedule rewards compliant manufacturers with accelerated market access for stroke rehabilitation indications.
- Soft pneumatic actuators:Advances in fabric-based artificial muscle technology reduce per-unit weight below 200 grams, enabling homecare deployment without sacrificing grip force precision.
- Germany's DiGAs framework:Digital health application fast-track approval creates reimbursement precedent for AI-integrated therapy platforms that pair hardware with remote monitoring software.
Market Restraints
- Neodymium magnet supply concentration:China's dominance in rare earth processing creates input cost volatility for brushless motor assemblies that power high-torque exoskeleton variants.
- FDA 510(k) substantial equivalence:Powered glove devices without predicate clearances face 18-24 month review timelines that freeze capital deployment for early-stage manufacturers.
- Therapist labor substitution limits:Regulatory bodies in multiple jurisdictions restrict unsupervised home use to passive assist modes, capping addressable session volume.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import duty exposure for components while opening access to government hospital procurement tenders.
- EMG-EEG sensor fusion:Converging electromyography with brain-computer interfaces enables intention-detection gloves for spinal cord injury patients previously excluded from robotic rehabilitation.
- Direct-to-patient subscription:Hardware-as-a-service models bypass traditional durable medical equipment distribution, capturing recurring revenue from home-based stroke survivors.
Industry Challenges
- ISO 13485 quality management implementation:Small manufacturers struggle to maintain document control and risk management file integrity across distributed software-hardware release cycles.
- Legacy EMR integration complexity:Hospital IT departments resist API connections to proprietary therapy data clouds, fragmenting outcome evidence collection across incompatible systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rehabilitation Robot Gloves Market |
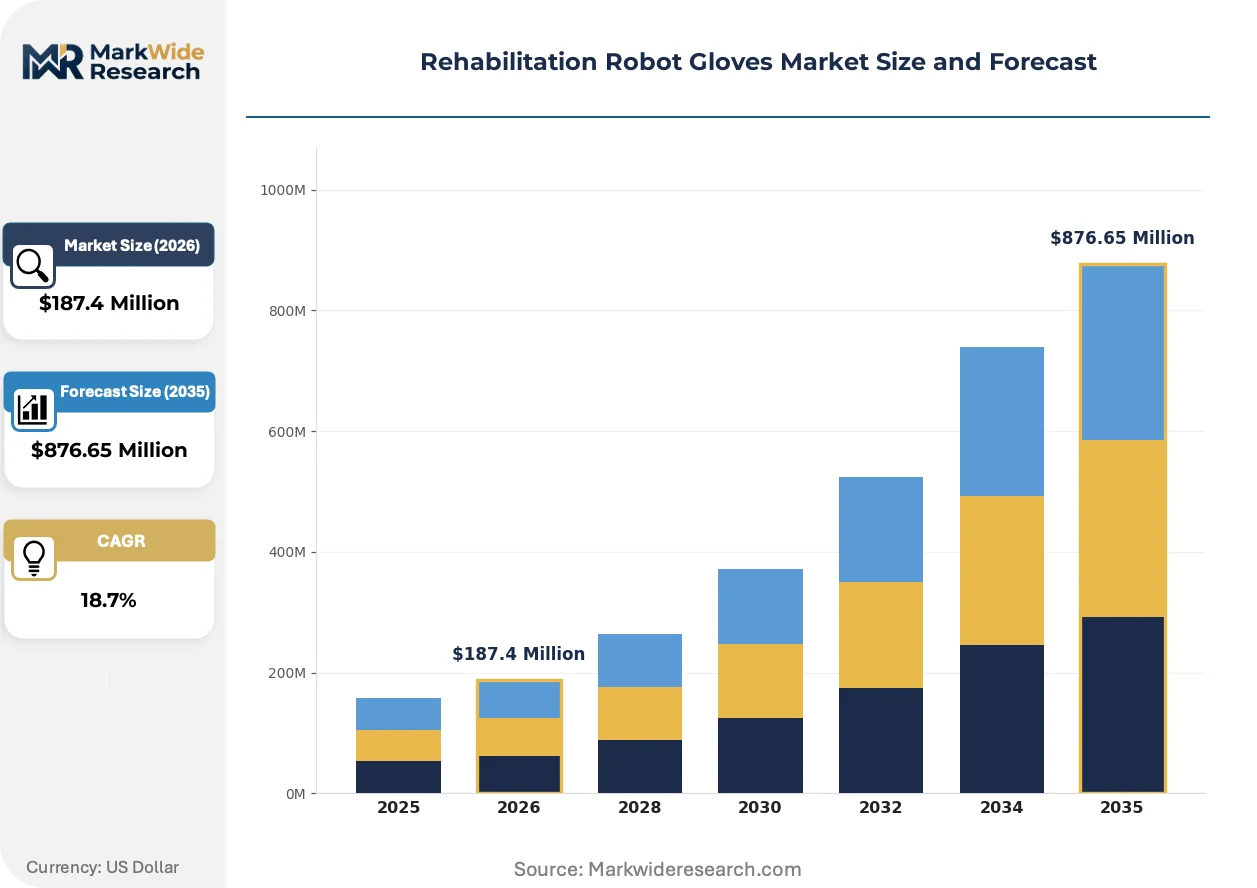
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exoskeleton Gloves, Soft Robotic Gloves, Powered Gloves, Adaptive Glove Systems End User: Clinics, Hospitals, Rehabilitation Centers, Homecare Settings Technology: Haptic Feedback, Motion Tracking, Artificial Intelligence, Sensor Integration Application: Post-Stroke Recovery, Orthopedic Rehabilitation, Neurological Disorders, Hand Function Restoration |
| Companies Covered | Syrebo, HandyRehab, Neofect, Walnut Medical, Siyi Intelligent Technology, Gloreha, Saebo, NUADA, Bioservo Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rehabilitation Robot Gloves Market Trends and Innovations
Actuator technology convergence with textile manufacturing is dissolving the boundary between medical devices and wearable consumer electronics, forcing regulatory reclassification debates and new quality management protocols.
Dielectric elastomer actuators are miniaturizing force generation into sub-millimeter polymer films that integrate directly into knit glove structures. Homecare providers in Germany and Japan are piloting these systems for nocturnal wear protocols. The technology is miniaturizing power electronics into textile-embedded flexible PCBs that eliminate rigid housing requirements.
The EU Medical Device Regulation's post-market surveillance mandates are forcing manufacturers to deploy over-the-air telemetry for real-world performance tracking. Clinical evaluation report requirements now extend to software updates, creating documentation friction for AI-driven therapy adaptation algorithms. Class IIa device manufacturers are responding by freezing algorithm versions until post-approval change management procedures mature.
Hospital procurement committees are unbundling hardware acquisition from software licensing, treating therapy platforms as separate capital and operational expenditures. This bifurcation pressures vendors to demonstrate standalone software value through CPT code stacking for remote therapeutic monitoring. The United States exhibits the most pronounced shift, with IDN consolidated sourcing agreements increasingly excluding bundled service contracts.
Rehabilitation Robot Gloves Market Segmentation
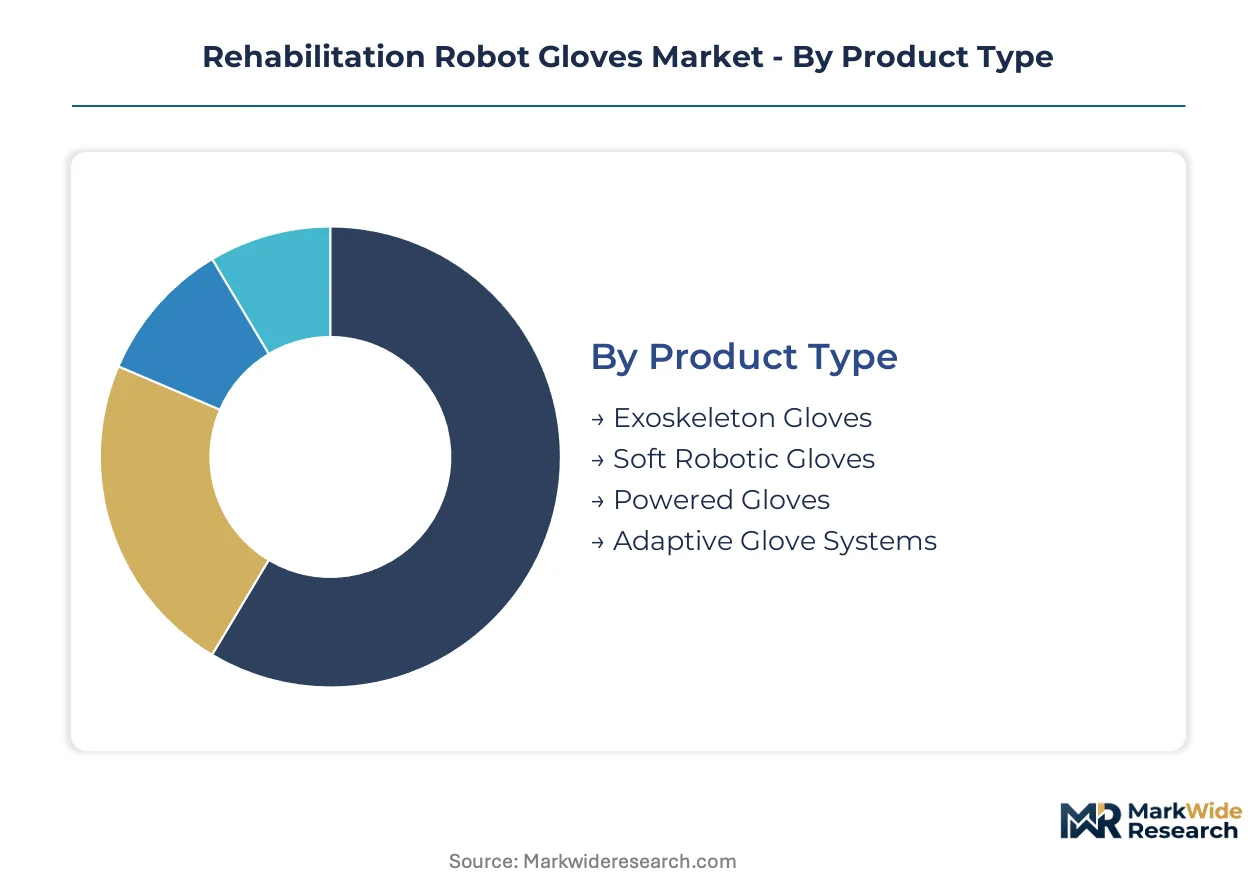
Segmentation in rehabilitation robot gloves reveals how regulatory pathways, reimbursement codes, and care setting economics allocate demand across hardware configurations. Manufacturers must align product architecture with specific approval requirements and purchasing authority structures.
Product Type:
FDA 510(k) substantial equivalence requirements and EU MDR clinical evaluation reports create divergent compliance burdens across powered versus passive architectures.
- Exoskeleton Gloves:Rigid linkages with brushless motors deliver 2-5 Nm torque per digit for severe motor deficit cases. Hospital procurement in the United States and Germany concentrates here due to higher reimbursement codes and measurable outcome documentation requirements.
- Soft Robotic Gloves:Fabric-based pneumatic or tendon-driven actuators reduce weight below 300 grams for patient comfort. Japan's homecare reimbursement expansion and Germany's DiGAs fast-track pathway accelerate deployment outside institutional settings.
- Powered Gloves:Electromechanical systems with integrated force sensors and control algorithms occupy the clinical-grade middle tier. CE marking and FDA clearance timelines shape competitive positioning.
- Adaptive Glove Systems:Modular architectures allowing hardware-software reconfiguration across multiple indications. Emerging category with concentrated development activity in Swiss and Japanese research clusters.
Exoskeleton gloves handle the majority of hospital procurement volume; soft robotic gloves are expanding most quickly into homecare channels.
End User:
Purchasing authority and reimbursement eligibility fragment demand across institutional versus decentralized care models.
- Hospitals:IDN consolidated sourcing agreements and capital equipment budgets dominate high-torque exoskeleton acquisition. Stroke rehabilitation program expansion in the United States and Japan drives volume concentration.
- Rehabilitation Centers:Specialized outpatient facilities with dedicated neurorehabilitation units. Germany's structured rehabilitation phase (Reha-Phase) mandates create predictable replacement cycles.
- Clinics:Smaller patient volumes and leasing-preferred procurement. CPT code stacking for remote therapeutic monitoring is reshaping software-hardware bundling decisions.
- Homecare Settings:Direct-to-patient subscription models and passive assist mode regulatory limits constrain unsupervised deployment. Soft pneumatic actuator advances enable nocturnal wear protocols in German and Japanese pilot programs.
Hospitals retain the dominant installed base; homecare settings are gaining share fastest as reimbursement frameworks adapt.
Technology:
Cost tier and clinical validation requirements stratify adoption across basic feedback mechanisms versus adaptive algorithmic systems.
- Sensor Integration:Force, position, and EMG sensor arrays providing closed-loop control. Foundational layer across all product categories with established ISO 13485 quality management protocols.
- Artificial Intelligence:Machine learning algorithms adapting resistance profiles to real-time electromyography signals. EU MDR post-market surveillance mandates and software update documentation requirements create compliance friction for vendors.
- Haptic Feedback:Vibrotactile or force-feedback modules delivering sensory cues during movement training. Lowest per-unit cost technology with the largest current installed base.
- Motion Tracking:Optical, inertial, or magnetic tracking systems quantifying range of motion and movement quality. Integration with hospital EMR systems remains fragmented due to proprietary API resistance from IT departments.
Haptic feedback maintains the broadest deployment; artificial intelligence shows the steepest expansion trajectory despite regulatory documentation burdens.
Application:
Clinical evidence requirements and reimbursement specificity concentrate manufacturer investment in stroke and orthopedic indications.
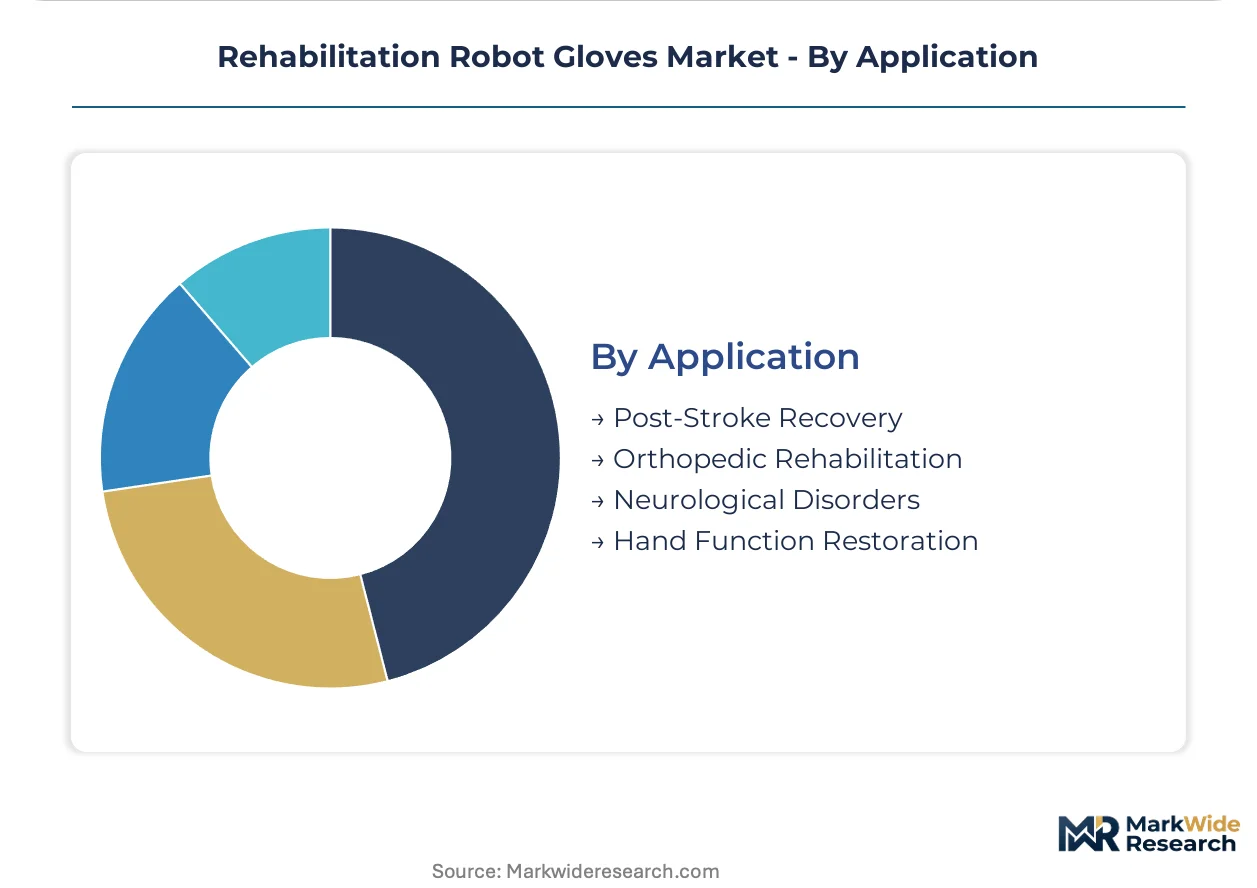
- Post-Stroke Recovery:Task-specific repetitive training for hemiparetic upper extremity dysfunction. Largest addressable population with established CPT and DRG reimbursement codes in the United States.
- Orthopedic Rehabilitation:Tendon repair, fracture fixation, and joint replacement postoperative protocols. Shorter treatment durations and clearer functional outcome metrics support faster procurement decisions.
- Neurological Disorders:Parkinson's disease, multiple sclerosis, and traumatic brain injury applications. Smaller evidence base and indication-specific regulatory pathways limit commercial scale.
- Hand Function Restoration:Peripheral nerve injury and complex regional pain syndrome cases. Niche application with concentrated specialist center demand in Germany and Japan.
Post-stroke recovery commands the majority of clinical trial investment; orthopedic rehabilitation is climbing fastest on procedural volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component supply for brushless motor assemblies and soft pneumatic actuators clusters in East Asian manufacturing corridors, while clinical validation and regulatory approval capacity concentrates in North American and Western European medical device hubs. This bifurcation shapes regional competitive positioning across the value chain.
United States
Hospital procurement committees at integrated delivery networks dominate exoskeleton glove acquisition through consolidated sourcing agreements. FDA 510(k) clearance pathways for powered orthotic devices compress commercialization timelines for manufacturers with predicate device references. The Boston-Cambridge medical device corridor hosts concentrated startup activity in adaptive glove systems.
Germany
Structured rehabilitation phase mandates create predictable replacement cycles for rehabilitation centers across Bavaria and North Rhine-Westphalia. The DiGAs fast-track approval framework for digital health applications establishes reimbursement precedent for AI-integrated therapy platforms. Stuttgart's industrial automation cluster feeds component supply for precision actuator manufacturing.
Japan
Aging demographics and stroke incidence rates drive homecare reimbursement expansion for soft robotic gloves under public health insurance fee schedules. PMDA QMS ministerial ordinances extend approval timelines but reward compliant manufacturers with preferential coverage status. The Kansai region around Osaka anchors domestic production of textile-embedded sensor arrays.
China
Domestic manufacturing scale for rare earth magnet processing supports cost positioning in brushless motor assemblies, though export control volatility creates input price uncertainty. NMPA medical device registration reforms are streamlining Class II approval pathways for rehabilitation robotics. Shenzhen's hardware ecosystem concentrates contract manufacturing for soft pneumatic actuator prototypes.
Switzerland
Precision engineering heritage and Swissmedic regulatory efficiency attract adaptive glove system development from multinational research clusters. Geneva and Zurich host concentrated clinical trial infrastructure for neurological rehabilitation indications. The country's medical technology export orientation leverages CE marking mutual recognition agreements across adjacent European markets.
Rehabilitation Robot Gloves Market Competitive Landscape
Concentration sits with mid-cap specialists possessing integrated software-hardware capabilities rather than pure-play component suppliers. The vendor landscape stratifies across three tiers: established medical device conglomerates with rehabilitation portfolios, venture-backed robotics startups with FDA-cleared platforms, and Asian contract manufacturers scaling private-label production. Strategic differentiation runs through clinical evidence generation and reimbursement code capture rather than hardware specification alone. Competitive moves center on portfolio diversification into adjacent upper-limb rehabilitation devices and geographic expansion through distributor partnerships in German and Japanese homecare channels.
Among Asia-Pacific-based developers, Syrebo, Neofect, and Siyi Intelligent Technology exemplify the software-integrated archetype that dominates emerging competitive tiers. These companies occupy positions where digital therapy platform revenue supplements hardware margins. European specialists including Bioservo Technologies and NUADA anchor the sensor-technology tier with proprietary electromyography integration. Saebo represents the clinical-channel incumbent archetype with established therapist training infrastructure. The competitive perimeter is compressing as hardware-as-a-service subscription models bypass traditional durable medical equipment distribution networks.
| Leading Market Players |
|---|
| Syrebo |
| HandyRehab |
| Neofect |
| Walnut Medical |
| Siyi Intelligent Technology |
| Gloreha |
| Saebo |
| NUADA |
| Bioservo Technologies |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with rare earth processors lock in neodymium magnet supply access and stabilize input cost visibility for brushless motor assemblies. These contractual structures insulate high-torque exoskeleton manufacturers from China's export control volatility while compressing procurement lead times for hospital procurement committees.
Pricing Analysis
FDA 510(k) substantial equivalence requirements dictate the pricing tier structure across powered rehabilitation devices. Pricing stratifies across premium CE-marked clinical systems, standard FDA-cleared hospital units, and economy-grade homecare passive assist models. Cost compression in soft pneumatic actuator manufacturing is intensifying because fabric-based artificial muscle technology scales production volumes. Rehabilitation centers exhibit the highest price sensitivity due to leasing-preferred procurement and smaller patient volumes, while integrated delivery networks demonstrate lower sensitivity through consolidated capital equipment budgets.
Supply Chain Analysis
Container availability constraints on East Asian trade lanes elevate inbound logistics costs for textile-embedded sensor arrays and precision actuator components. Manufacturing concentrates in China for rare earth processing and soft pneumatic prototyping, Japan for textile-embedded electronics, and Germany for precision brushless motor assemblies. Brushless motor production draws from neodymium magnets, copper windings, and Hall effect sensors. Single-source vulnerability in Chinese rare earth processing creates structural supply risk. Distribution runs through durable medical equipment wholesalers and direct-to-patient subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rehabilitation robot gloves market builds defensive moats through regulatory entrenchment, where FDA clearance timelines and CE marking clinical evaluation requirements create multi-year barriers to competitive replication.
For Market Incumbents: Consolidate software-hardware integration capabilities to deepen recurring revenue from digital therapy platforms. Acquire EMG-EEG sensor fusion technology to preempt spinal cord injury market entry by emerging brain-computer interface startups. Expand ISO 13485 quality management infrastructure to capture Japan's PMDA preferential coverage status before reimbursement code expansion accelerates. For New Entrants and Emerging Players: Anchor in India's PLI scheme for medical devices to bypass import duty exposure and access government hospital procurement tenders. Target homecare settings in Germany and Japan where DiGAs fast-track approval and soft robotic glove reimbursement expansion create the most penetrable regulatory pathways. Pursue hardware-as-a-service subscription models to circumvent entrenched durable medical equipment distribution relationships. For Investors and Strategic Acquirers: Software-integrated mid-cap specialists with FDA-cleared platforms and active digital therapy user bases represent the optimal acquisition target archetype. These entities combine regulatory entrenchment with recurring revenue visibility that pure hardware manufacturers cannot replicate. Monitor NMPA medical device registration reform implementation in China as the inflection indicator for manufacturing cost repositioning opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Substantial equivalence demonstrations compress commercialization timelines for powered orthotic devices in United States hospital procurement. |
| CE Marking Clinical Evaluation | EU MDR post-market surveillance mandates force telemetry deployment for real-world performance tracking across Class IIa device portfolios. |
| Hospital System Partnership | IDN consolidated sourcing agreements dominate exoskeleton glove acquisition through capital equipment budget control. |
| Software Companion Development | AI-integrated therapy platforms capture DiGAs fast-track approval precedent in Germany's digital health application framework. |
| Reimbursement Strategy | CPT code stacking for remote therapeutic monitoring reshapes software-hardware bundling decisions in United States clinics. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with rehabilitation clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EU MDR clinical evaluation reports, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, technology, and application segmentation dimensions.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmented adoption curves for exoskeleton gloves, soft robotic systems, and adaptive architectures. CAGRs were derived from installed base expansion rates and replacement cycle dynamics in stroke rehabilitation programs. Key inputs included PMDA approval timeline distributions, DiGAs reimbursement precedent velocity, and neodymium magnet price volatility coefficients.
Material uncertainties — reimbursement code reversals, rare earth export restrictions, and AI algorithm regulatory reclassification — sit outside the modeled envelope. Forecasts reflect documented assumptions about clinician acceptance thresholds and homecare regulatory relaxation trajectories. Recalibration cycles align with material shifts in national health technology assessment body determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Consumer Robotics Market
Robotics and Automation
Global Demolition Robots Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Consumer and Office Robot Market
Robotics and Automation
Latin America Autonomous Mobile Robot Market
Robotics and Automation
Robot As a Service Market
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
Short-Range Drone Package Delivery Market
Robotics and Automation
Laboratory Robotics Market
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
Harvesting Robot Market
Robotics and Automation
Eldercare-Assistive Robots Market
Robotics and Automation
AGV Dispatch Management Platforms Market