
 Brain-Computer Interface System Market | 2026-2036
Brain-Computer Interface System Market Size, Share, and Industry Trends Forecast 2026-2036
Brain-Computer Interface System Market Insights
Healthcare applications is expanding as the dominant end-use vertical for brain-computer interface systems, with hospitals and rehabilitation centers replacing gaming as the primary commercialization pathway. Neuralink leverages its full-stack implantable platform to dominate surgical BCI development in the United States. Synchron competes through its endovascular stent-electrode approach, eliminating open-brain surgery requirements. Blackrock Neurotech anchors decades of Utah array expertise to sustain leadership in invasive neural recording for research institutions.
A brain-computer interface system constitutes a direct communication pathway between the central nervous system and external computational hardware, typically capturing neural signals through electroencephalography, electrocorticography, or intracortical microelectrode arrays with sampling rates exceeding 30 kHz for spike-resolution recording. Its primary commercial purpose centers on restoring motor function, augmenting human-computer interaction, and enabling neuroprosthetic control for paralyzed patients. Invasive product types command the highest margin pools due to surgical complexity and regulatory barriers, while non-invasive EEG-based systems lead unit volume through consumer and research accessibility. ECoG technology occupies a critical middle ground, balancing signal fidelity with reduced tissue disruption for clinical adoption.
The FDA breakthrough device program and EU MDR framework shape demand by compressing clinical trial timelines and mandating biocompatibility validation for long-term implantables. ISO 14155 standards for clinical investigation of medical devices govern trial conduct across jurisdictions, while HIPAA in the United States imposes strict neural data privacy requirements that influence system architecture. Stakeholders must monitor reimbursement pathway decisions by CMS and comparable national health authorities, as coding approvals for BCI-assisted procedures will determine commercial scalability ahead of widespread clinical deployment.
Market Dynamics
Neural signal decoding fidelity now dictates competitive positioning as hospitals demand real-time motor restoration capabilities that legacy EEG systems cannot deliver. This technical threshold is concentrating procurement decisions around invasive and semi-invasive platforms with proven spike-resolution recording.
Growth Catalysts
- FDA Breakthrough Device Program:Compressed clinical trial timelines accelerate commercial validation for implantable neural interfaces in the United States.
- Rehabilitation center infrastructure:Specialized motor restoration facilities are expanding dedicated BCI surgical suites and neural decoding training programs.
- Electrocorticography maturation:ECoG electrode arrays balance signal fidelity with reduced tissue disruption, bridging the gap between research-grade invasiveness and clinical feasibility.
Market Restraints
- Biocompatible materials scarcity:Specialized polymers and noble metal electrodes for long-term neural implants face concentrated supply from limited medical-grade foundries.
- Surgical complexity premium:Craniotomy requirements for Utah array implantation restrict addressable patient populations to specialized neurosurgical centers.
- HIPAA neural data architecture:Strict privacy mandates impose costly system redesigns for cloud-connected signal processing pipelines.
Strategic Opportunities
- Endovascular delivery paradigms:Stent-electrode approaches eliminate open-brain surgery requirements, expanding treatable patient demographics.
- EU MDR harmonization:Streamlined conformity assessment pathways accelerate cross-border deployment for CE-marked neural implants.
- Consumer neurofeedback convergence:Gaming and wellness applications create volume demand for non-invasive EEG headsets with research-grade channel density.
Industry Challenges
- Neural engineering talent scarcity:Cross-trained specialists combining neurophysiology, signal processing, and embedded systems command premium compensation and extended recruitment cycles.
- ISO 14155 trial execution:Multi-site clinical investigations for long-term implantables require coordinated ethical review across jurisdictions with divergent neural tissue research standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain-Computer Interface System Market |
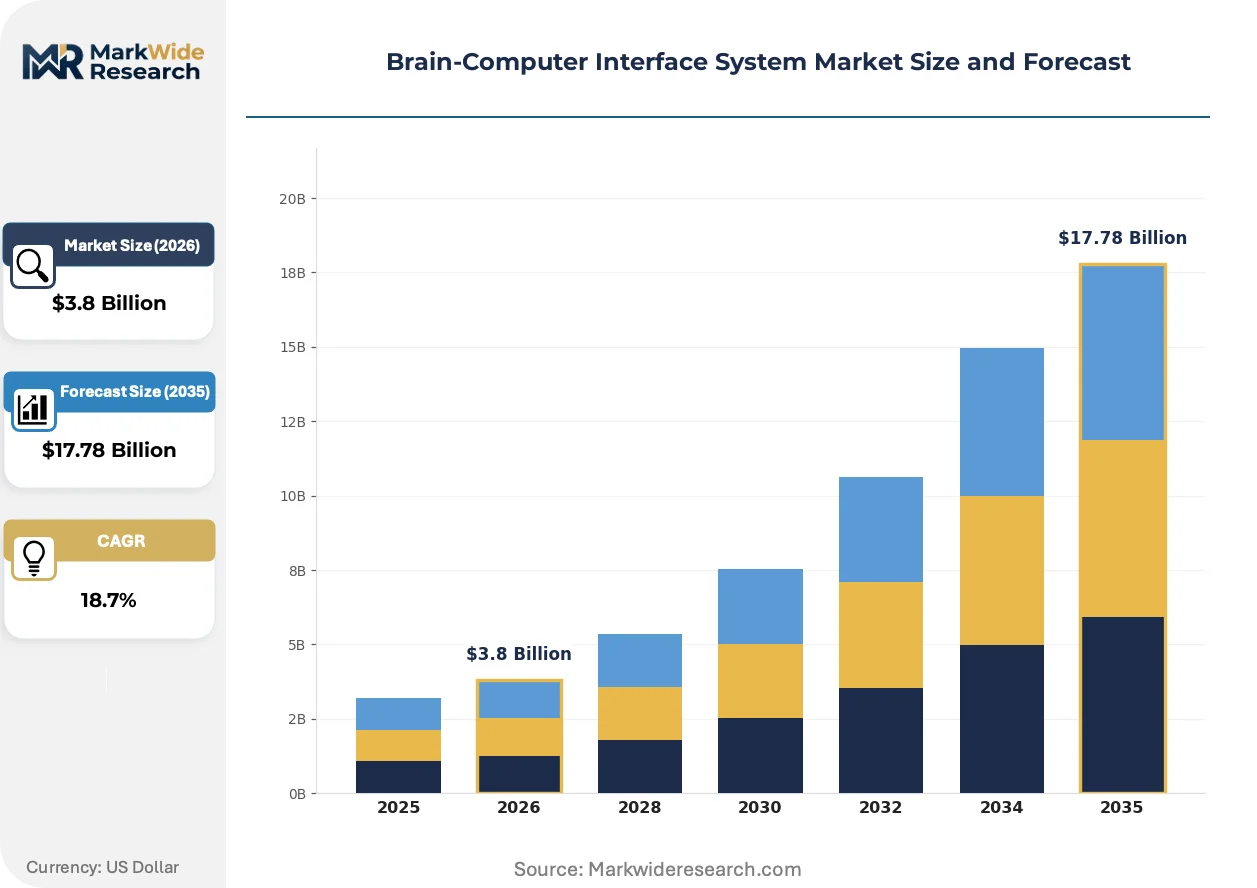
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive, Non-invasive, Semi-invasive, Wearable Technology: EEG, fNIRS, ECoG, MRI Application: Healthcare, Gaming, Education, Military End User: Research Institutions, Hospitals, Gaming Companies, Rehabilitation Centers |
| Companies Covered | Neuralink, Synchron, Blackrock Neurotech, Emotiv, g.tec medical engineering, Paradromics, Neurable, Kernel, OpenBCI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain-Computer Interface System Market Trends and Innovations
Signal processing architectures are rewriting how neural data translates into actionable motor commands. Three convergent developments are compressing development cycles and expanding treatable indications.
High-density microelectrode arrays with sampling rates exceeding 30 kHz are rewriting the standard for spike-resolution recording in motor cortex applications. Research institutions and tier-one neurosurgical centers are adopting these platforms for real-time neuroprosthetic control. The technology is rewriting competitive barriers by concentrating expertise around surgical implantation protocols and closed-loop decoding algorithms.
EU MDR biocompatibility validation mandates are accelerating materials science investment for long-term neural implants. Manufacturers must demonstrate 10-year implantation durability under accelerated aging protocols. Invasive product categories face the steepest compliance burden, driving consolidation around vertically integrated materials capabilities.
Hospital procurement committees are consolidating vendor relationships around full-stack platform providers capable of surgical training, signal processing software, and ongoing neural calibration support. Device-only suppliers are losing access to integrated delivery networks that prefer single-accountability contracts. This concentration is most visible in United States academic medical centers with established functional neurosurgery departments.
Brain-Computer Interface System Market Segmentation
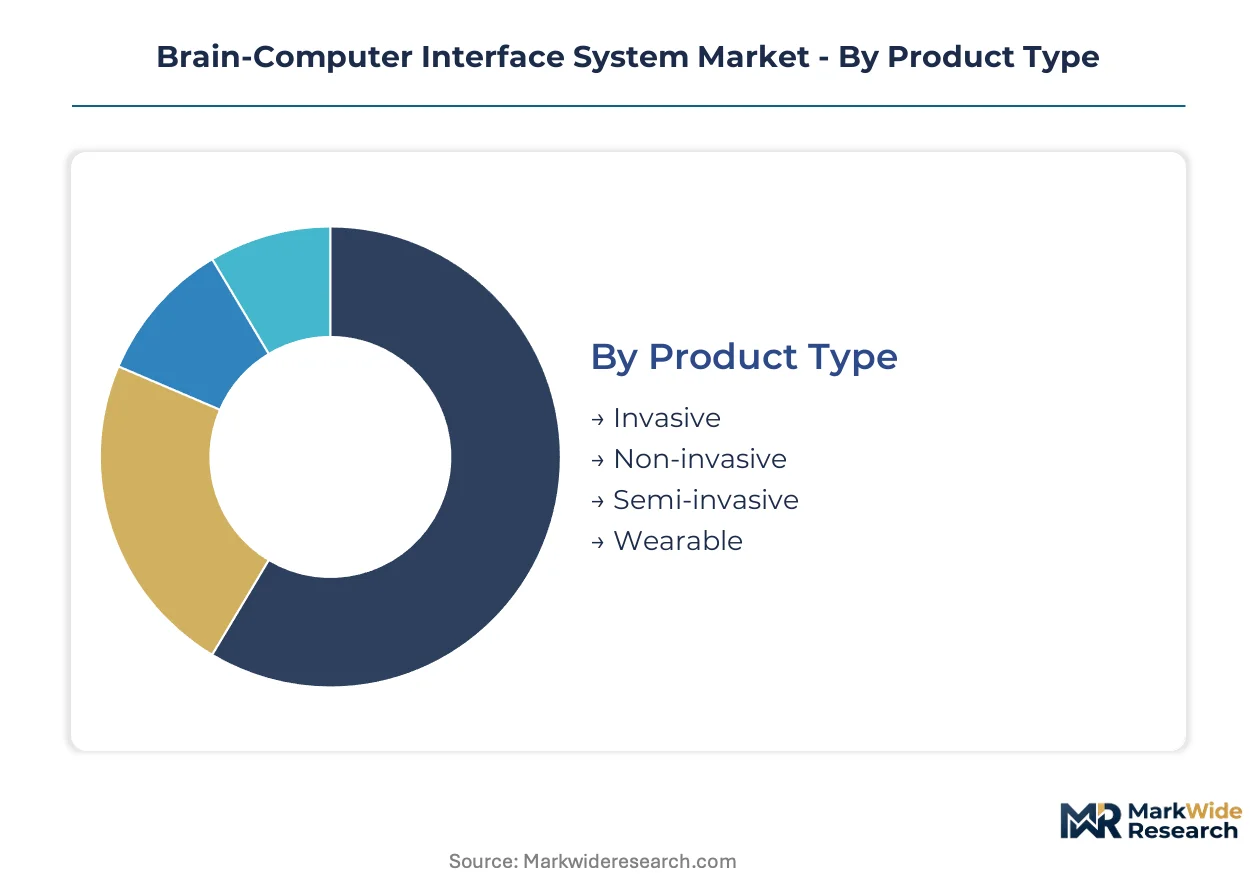
Segmentation in brain-computer interface systems reveals how technical specifications, signal fidelity requirements, and regulatory pathways fragment procurement decisions across healthcare, research, and consumer domains. Understanding these divisions exposes where margin pools concentrate and which configurations face scaling constraints.
Product Type:
Customization intensity varies sharply across this category, from fully bespoke surgical implants to mass-produced wearable headsets with standardized sensor configurations.
- Invasive:Utah array and electrocorticography platforms capture neural signals at spike resolution through direct cortical contact. Demand clusters in United States academic medical centers with functional neurosurgery departments, driven by FDA breakthrough device designations that compress clinical validation timelines. Biocompatible materials scarcity and craniotomy requirements restrict addressable patient populations to specialized centers.
- Non-invasive:Electroencephalography headsets with dry or gel-based electrodes dominate unit volume through consumer accessibility and research-grade channel density. Gaming companies and wellness application developers in the United States drive procurement, though signal fidelity limitations exclude these systems from motor restoration applications requiring real-time decoding.
- Semi-invasive:Electrocorticography arrays balance signal quality with reduced tissue disruption via epidural or subdural placement. ECoG technology occupies a critical middle ground for clinical adoption where spike resolution matters but open-brain surgery poses unacceptable risk.
- Wearable:Consumer-oriented EEG headsets with simplified form factors target neurofeedback and attention-monitoring applications. Education technology vendors and direct-to-consumer wellness platforms represent primary demand channels for this segment.
Most installed capacity flows through Non-invasive systems. Expansion is steepest in Invasive platforms as rehabilitation centers build dedicated surgical infrastructure.
Technology:
Cost tier separation in this category runs from research-grade functional neuroimaging installations exceeding seven figures to sub-thousand-dollar consumer headsets with limited channel counts.
- EEG:Electroencephalography systems sample electrical activity through scalp electrodes at rates up to 30 kHz in research configurations. Non-invasive accessibility drives volume leadership, though signal attenuation through skull and tissue limits spatial resolution for precise motor decoding.
- fNIRS:Functional near-infrared spectroscopy measures hemodynamic response through optical absorption changes. Research institutions deploy hybrid EEG-fNIRS configurations to combine temporal and spatial resolution advantages in cognitive neuroscience studies.
- ECoG:Electrocorticography arrays placed directly on cortical surface deliver superior signal fidelity without penetrating brain tissue. Hospitals with established epilepsy monitoring units leverage existing surgical infrastructure for motor restoration applications, gaining share fastest among semi-invasive modalities.
- MRI:Functional magnetic resonance imaging provides whole-brain spatial resolution for research protocols but lacks real-time capability for neuroprosthetic control. Academic medical centers with existing neuroimaging suites represent concentrated demand for BCI research applications.
Procurement volume concentrates in EEG for accessibility reasons. Steepest expansion trajectory belongs to ECoG as clinical validation matures for motor restoration.
Application:
Customer maturity in this category spans decades of peer-reviewed research in healthcare against emerging experimental deployments in gaming and defense contexts.
- Healthcare:Motor restoration for paralyzed patients, epilepsy monitoring, and stroke rehabilitation constitute primary clinical indications. United States rehabilitation centers are expanding dedicated BCI surgical suites and neural decoding training programs under CMS reimbursement pathway development.
- Gaming:Neurofeedback-based attention training and immersive control interfaces drive consumer headset demand. Gaming companies experiment with EEG-based input modalities, though commercial traction remains limited by signal reliability in uncontrolled environments.
- Education:Attention-monitoring systems for cognitive training and learning optimization attract institutional procurement. Research institutions pilot classroom deployments with limited scale due to privacy concerns and unproven efficacy claims.
- Military:Cognitive load monitoring and hands-free control systems for high-workload environments represent defense research priorities. United States defense research programs fund invasive and non-invasive platforms for operator performance augmentation.
Healthcare absorbs the majority of installed surgical capacity. Gaming applications are climbing the fastest as consumer hardware costs decline.
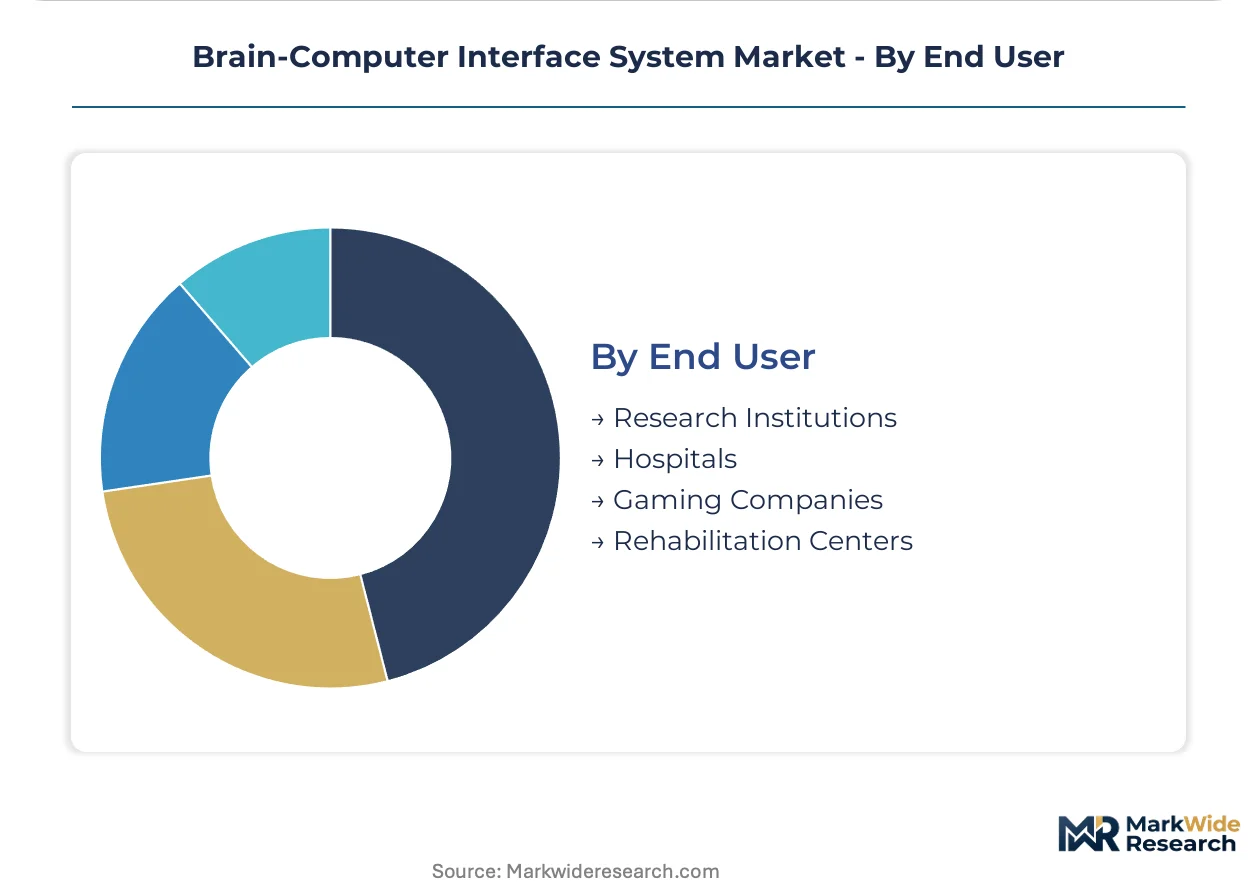
End User:
Supply concentration in this category favors integrated platform providers capable of spanning hardware, software, and clinical training against device-only suppliers losing procurement access.
- Research Institutions:Universities and neuroscience centers drive demand for high-channel-count invasive arrays and multimodal neuroimaging configurations. Blackrock Neurotech and similar suppliers anchor decades of Utah array expertise to sustain leadership in this segment.
- Hospitals:Academic medical centers with functional neurosurgery departments consolidate vendor relationships around full-stack providers. FDA breakthrough device designations and EU MDR pathways shape procurement decisions by accelerating clinical validation timelines.
- Gaming Companies:Consumer entertainment developers experiment with EEG-based input modalities for immersive experiences. Volume demand concentrates in standardized headset configurations with limited customization requirements.
- Rehabilitation Centers:Specialized motor restoration facilities represent the fastest-expanding demand channel as clinical validation matures for neuroprosthetic applications. United States centers lead infrastructure investment with dedicated BCI surgical suites.
Research Institutions hold the deepest installed base of invasive recording systems. Rehabilitation Centers are gaining share fastest as clinical deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting BCI manufacturing and clinical trial investment toward jurisdictions with streamlined neurotechnology approval pathways and concentrated neurosurgical infrastructure. Cost-of-compliance gaps between the FDA breakthrough program and EU MDR timelines are redistributing early-stage commercialization activity.
United States
Academic medical centers in Boston and the San Francisco Bay Area anchor the world's deepest invasive BCI surgical infrastructure. FDA breakthrough device designations compress clinical validation timelines for Utah array and electrocorticography platforms. Neuralink and Synchron anchor substantial research ecosystems in Austin and New York respectively, drawing venture concentration toward FDA-cleared commercial pathways.
Germany
The country's functional neurosurgery departments in Heidelberg and Berlin drive ECoG adoption for epilepsy-to-motor-restoration indication expansion. EU MDR biocompatibility validation mandates accelerate materials science investment from Freiburg-based medical-grade foundries. Tübingen and Munich clusters concentrate neural engineering talent for signal processing algorithm development.
Switzerland
Swissmedic's streamlined neurotechnology assessment procedures attract implantable device developers seeking European market entry ahead of broader EU MDR harmonization. The Lake Geneva region concentrates microfabrication expertise for high-density electrode array production. Zurich and Lausanne university hospitals host multi-site clinical investigations under ISO 14155 protocols.
China
NMPA innovation approval pathways for breakthrough medical devices accelerate domestic BCI platform development in Shanghai and Beijing. The Yangtze River Delta concentrates electrocorticography manufacturing for regional hospital procurement. Shenzhen's electronics ecosystem supports non-invasive EEG headset production for education technology exports.
United Kingdom
NHS England's specialized commissioning frameworks for neuroprosthetic procedures concentrate demand in London and Oxford academic medical centers. MHRA post-Brexit regulatory autonomy enables tailored neurotechnology assessment timelines distinct from EU MDR. Cambridge and Imperial College research clusters anchor multimodal neuroimaging BCI development.
Brain-Computer Interface System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack platform providers commanding hospital procurement relationships while component suppliers serve research institutional demand. The vendor base concentrates around three strategic archetypes: vertically integrated implantable developers, modular EEG hardware specialists, and signal processing software houses. Competitive dynamics center on M&A activity targeting neural engineering talent pools and strategic partnerships bridging surgical training with ongoing neural calibration support.
Among invasive platform developers, Neuralink and Synchron exemplify divergent technical approaches to cortical signal acquisition, while Blackrock Neurotech anchors decades of Utah array expertise within research institutional supply relationships. These three entities occupy distinct competitive positions: Neuralink represents full-stack surgical platform integration, Synchron exemplifies endovascular delivery paradigm innovation, and Blackrock Neurotech sits within the research-grade invasive recording tier. Non-invasive and semi-invasive segments fragment across Emotiv, g.tec medical engineering, and OpenBCI, with each occupying modular hardware or software-specialist archetypes.
| Leading Market Players |
|---|
| Neuralink |
| Synchron |
| Blackrock Neurotech |
| Emotiv |
| g.tec medical engineering |
| Paradromics |
| Neurable |
| Kernel |
| OpenBCI |
| Others |
Pricing and Supply Chain Analysis
Platinum group metal spot indices cascade through medical-grade electrode foundries into tiered BCI hardware pricing, with iridium and platinum cost volatility compressing margins at the invasive implant tier while non-invasive headset assemblers in Shenzhen buffer component exposure through volume procurement.
Pricing Analysis
Distributor markups on Utah arrays and ECoG platforms concentrate margin capture at the hospital procurement tier, with three-tier pricing structure across premium, standard, and economy levels differentiating by FDA breakthrough designation status and surgical training bundling. Price differentiation hinges on biocompatibility certification tier and channel integration depth. Cost compression in research-grade microelectrode arrays is intensifying because materials scarcity forces foundry allocation premiums. Rehabilitation centers exhibit highest price sensitivity due to CMS reimbursement uncertainty, while academic medical centers absorb premium tier pricing for full-stack platform contracts.
Supply Chain Analysis
Domestic-content mandates under China's NMPA innovation pathways and India's PLI scheme for medical electronics are reshaping sourcing patterns for electrode microfabrication and signal processing ASICs. Supply concentrates in the United States for Utah array manufacturing, Switzerland for high-density ECoG substrates, and China for consumer EEG headset assembly. Raw material dependencies center on iridium wire for invasive electrodes, medical-grade silicone for biocompatible encapsulation, and indium tin oxide for transparent ECoG arrays. Single-source vulnerability in noble metal refining creates supply chain risk. Distribution runs through specialized neurotechnology distributors serving hospital IDNs and direct OEM relationships for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in brain-computer interface systems rests on materials substitution in long-term implantables and the shift toward premium-tier full-stack platform contracts that bundle surgical training with hardware procurement.
For Market Incumbents: Cement platform stickiness by embedding neural calibration software into hospital EMR workflows and capturing exclusive supply agreements with rehabilitation center IDNs. Threat from endovascular delivery paradigms demands defensive patent positioning around stent-electrode geometries. Backward integration into medical-grade polymer foundries secures allocation priority during materials scarcity events. For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass incumbent distributor relationships for non-invasive EEG systems in education technology and wellness applications. White-space targets include ECoG platforms for epilepsy-to-motor-restoration indication expansion and consumer neurofeedback headsets with research-grade channel density. Go-to-market angle centers on SaaS-tiered neural decoding software licensing to hardware-agnostic research institutions. For Investors and Strategic Acquirers: Consolidation pressure builds where neural engineering talent scarcity intersects with FDA breakthrough designation backlogs for early-stage implantable developers. Long-term viability favors vertically integrated platform providers with captive surgical training infrastructure over device-only suppliers losing hospital procurement access. Acquisition target archetype: ECoG electrode microfabrication specialists with EU MDR biocompatibility validation. Signal to watch: CMS reimbursement coding decisions for BCI-assisted motor restoration procedures as inflection indicator for commercial scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Compresses clinical validation timelines for invasive neural implants in United States academic medical centers. |
| EU MDR CE Marking Pathway | Unlocks cross-border deployment for long-term implantables through harmonized biocompatibility validation. |
| Hospital System Partnership | Secures exclusive vendor status within integrated delivery networks preferring single-accountability contracts. |
| Software Companion Development | Enables recurring revenue through cloud-connected neural calibration and signal processing subscriptions. |
| Reimbursement Strategy | Determines commercial scalability for motor restoration applications through CMS coding pathway development. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with functional neurosurgeons, hospital purchasing committee members, biomedical engineers at rehabilitation centers, and GPO contracts managers with secondary validation against FDA 510(k) and breakthrough device filings, EU MDR notified body decisions, CMS reimbursement coding databases, and hospital procurement records. Bottom-up and top-down triangulation cross-checked unit volume estimates against value-based market sizing.
Historical reference periods anchored the forecast window through verified installed base counts and replacement cycle analysis for invasive and non-invasive platforms. Segmentation dimensions modeled include product type, signal acquisition technology, clinical versus consumer application, and end-user category across research institutions, hospitals, and rehabilitation centers. CAGRs derived from logistic diffusion curves for clinical adoption and price elasticity-adjusted volume projections. Industry-specific inputs incorporated FDA breakthrough designation timelines and EU MDR biocompatibility validation durations.
The model assumes a particular technology adoption path; alternative pathways for endovascular stent-electrode delivery would alter the outlook for invasive platform market share. Forecasts reflect assumptions regarding regulatory approval velocity, materials science advancement for long-term implant durability, and reimbursement pathway development timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Software Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Security Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Supply Chain Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
AI Platform Market
Artificial Intelligence (AI)
Global Voice Assistant Market
Artificial Intelligence (AI)
Aiops Market
Artificial Intelligence (AI)
Supermarket AI-Powered Checkout Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
AI Consulting Services Market
Artificial Intelligence (AI)
Conversation Intelligence Software Market