
 Global Demolition Robots Market | 2026-2036
Global Demolition Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Demolition Robots Market Analysis
Procurement strategy is shifting from equipment ownership toward fleet leasing and service-based contracting across major demolition contractors. Brokk dominates compact electric units for confined-space interior work, while Husqvarna leverages its power-tool distribution network to anchor wheeled robotic systems in municipal infrastructure maintenance. Hitachi Construction Machinery sustains crawler-platform R&D intensity for heavy reinforced-concrete applications, competing with STANLEY Infrastructure's hydraulic breaker attachments.
Demolition robots are self-propelled, teleoperated or semi-autonomous machines engineered to dismantle concrete, masonry, and steel structures through hydraulic breakers, crushers, or diamond-wire saws, typically operating at arm reaches of three to six meters and power ratings between 15 kW and 45 kW; their primary purpose is to execute precision deconstruction in hazardous environments while eliminating direct human exposure to falling debris, respirable crystalline silica, and structural instability. Remote-controlled product types command the dominant revenue share due to proven reliability in nuclear decommissioning and petrochemical retrofit projects, while electric technology segments are expanding fastest as battery energy density improvements enable cord-free operation in enclosed building interiors where diesel emissions are prohibited. Application demand pools heavily in interior demolition where floor-loading constraints and spatial restrictions prevent conventional excavator deployment.
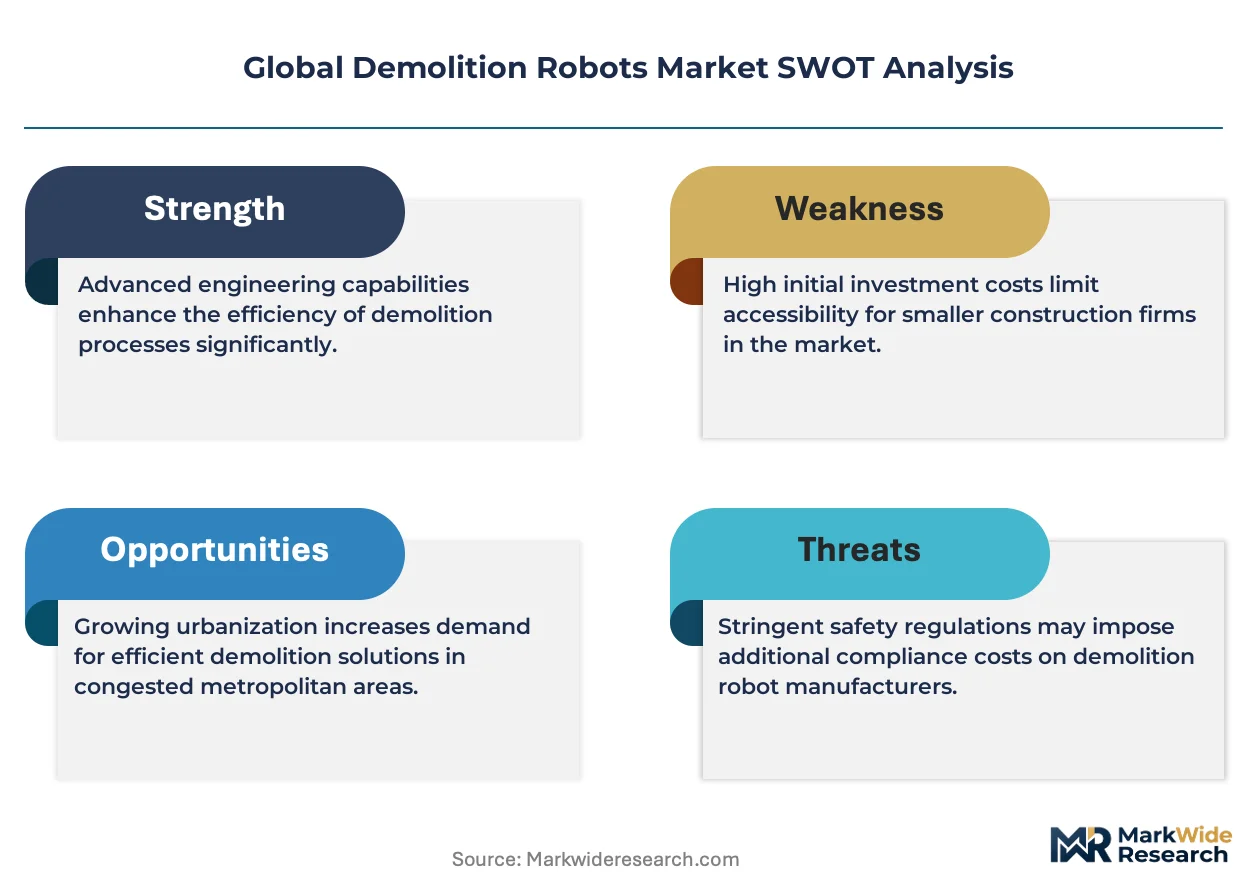
OSHA silica standards and the EU Machinery Directive (2006/42/EC) mandate dust suppression integration and emergency stop redundancy, compelling manufacturers to redesign control architectures and certify systems for Category 3 safety performance. Japan's Ministry of Economy, Trade and Industry (METI) promotes robotic construction equipment through productivity-focused subsidies, accelerating domestic adoption for 2025 Osaka Expo venue preparation and subsequent legacy facility removal. Stakeholders must monitor how evolving carbon-border adjustments and embodied-carbon accounting for demolished materials reshape equipment specification criteria and aftermarket service expectations.
Market Dynamics
OSHA silica enforcement and EU Machinery Directive safety mandates are compressing acceptable human exposure windows, forcing demolition contractors to accelerate robotic fleet deployment ahead of scheduled equipment replacement cycles.
Growth Catalysts
- OSHA Respirable Crystalline Silica Standard:Tightened permissible exposure limits in the United States compel contractors to eliminate manual concrete breaking, redirecting capital toward remote-controlled demolition units with integrated dust suppression.
- Japan METI Construction Robot Subsidies:Productivity-focused incentive programs accelerate domestic procurement for Osaka Expo 2025 venue preparation and subsequent legacy facility dismantling.
- Aging Reinforced Concrete Stock:Germany's post-war infrastructure portfolio requires precision decommissioning where structural integrity uncertainties prohibit conventional mechanical demolition.
Market Restraints
- High-Voltage Battery Cost Volatility:Lithium-ion cell price fluctuations compress margins for electric demolition robot manufacturers targeting cord-free interior applications.
- Hydraulic Component Supply Concentration:Precision valve and pump sourcing clusters in German and Japanese industrial districts, creating single-source vulnerability for tier-two assemblers.
- Category 3 Safety Certification Burden:EU Machinery Directive emergency-stop redundancy requirements extend product development timelines and inflate third-party validation costs.
Strategic Opportunities
- India Urban Renewal Pipeline:Smart Cities Mission demolition requirements in Mumbai, Delhi, and Bangalore remain underserved by robotic solutions, presenting first-mover positioning for compact electric units.
- Nuclear Decommissioning Convergence:Integration of semi-autonomous navigation with radiation-hardened teleoperation opens specialized procurement channels in France and the United Kingdom.
- Carbon Border Adjustment Mechanism:EU embodied-carbon accounting for demolished materials creates specification pull for equipment vendors offering material-sorting attachments and downstream recycling documentation.
Industry Challenges
- Teleoperation Skill Scarcity:Experienced equipment operators require 200+ hours of simulator training for spatial precision in confined-space demolition, constraining fleet utilization rates.
- Legacy Excavator Integration Friction:Demolition contractors face workflow reconfiguration costs when introducing robotic units alongside conventional hydraulic breaker fleets on multi-phase projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Demolition Robots Market |
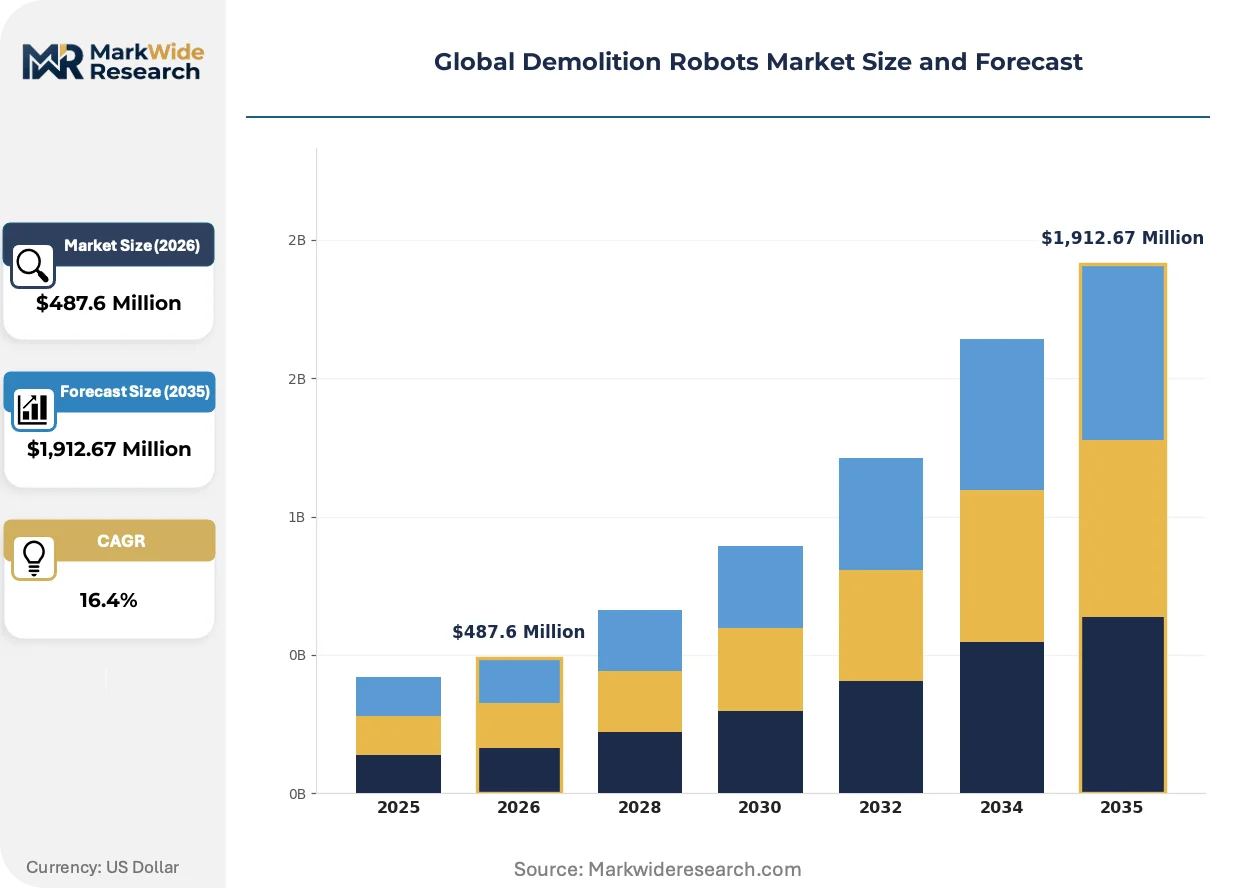
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,912.67 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote-Controlled, Mini, Crawler, Wheeled End User: Construction Firms, Demolition Contractors, Municipalities, Industrial Sites Technology: Hydraulic, Electric, Robotic, Pneumatic Application: Interior Demolition, Exterior Demolition, Material Handling, Site Clearance |
| Companies Covered | Hitachi Construction Machinery, TopTec Benelux, Brokk, McCann Industries, Keman, Husqvarna, Conjet, SHERPA Mineloders, STANLEY Infrastructure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Demolition Robots Market Emerging Trajectories
Semi-autonomous perception systems and battery-electric powertrains are compressing the performance gap between remote-controlled and conventional mechanical demolition, while regulatory carbon-accounting requirements reshape equipment specification criteria.
Machine vision and LiDAR-based obstacle detection is automating spatial mapping for demolition robots in cluttered interior environments. Municipal infrastructure maintenance divisions in Japan and Germany are piloting these systems for overnight bridge-deck removal where traffic closure windows are compressed. The technology is automating operator workload reduction in scenarios where direct line-of-sight is obstructed by dust or structural elements.
EU Machinery Directive amendments incorporating ISO 10218-2 robotic safety standards are mandating force-limiting control architectures and collaborative workspace monitoring. Manufacturers must redesign hydraulic breaker trigger logic and arm velocity governors to achieve CE marking for mixed human-robot demolition sites. Heavy reinforced-concrete applications face the steepest compliance redesign burden due to high-impact energy requirements.
Contracting models are unbundling equipment ownership from demolition service delivery. German and US metropolitan contractors are adopting fleet leasing with guaranteed uptime clauses, transferring maintenance liability to OEM service networks. Japan's metropolitan renewal zones exhibit the most advanced adoption, with Osaka Expo preparation projects specifying outcome-based deconstruction metrics rather than hourly equipment rental.
Global Demolition Robots Market Segmentation
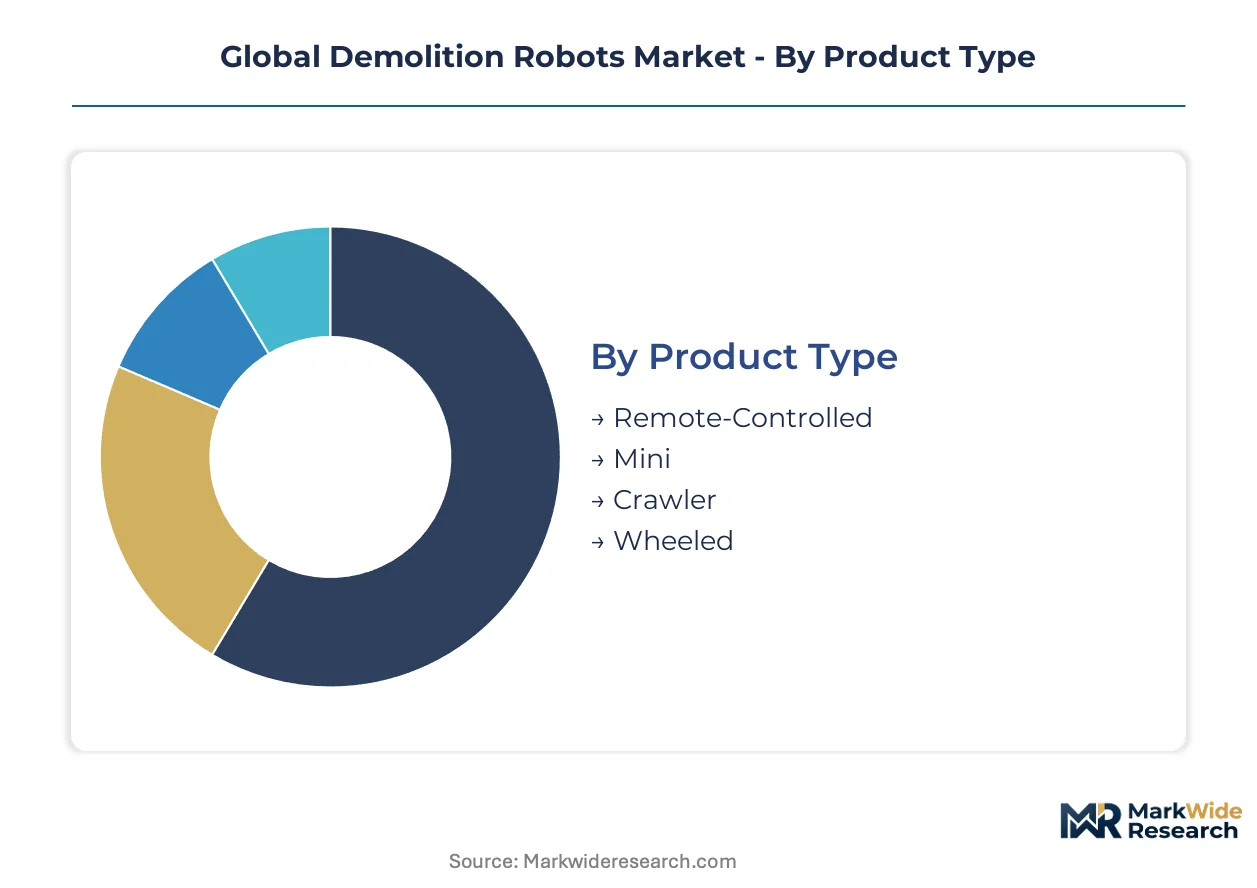
Demolition robot specifications diverge sharply across operating environments, power systems, and structural applications. Equipment selection hinges on spatial constraints, debris composition, and regulatory exposure limits rather than generic capacity metrics.
Product Type:
Arm reach and chassis configuration determine deployment feasibility across confined-space versus open-site demolition.
- Remote-Controlled:Teleoperated units with 3-6 meter arm reach dominate nuclear decommissioning and petrochemical retrofit projects where human proximity is prohibited. OSHA silica enforcement and EU Machinery Directive safety mandates accelerate procurement for interior concrete breaking in the United States and Germany.
- Mini:Compact electric units under 1.5 tons navigate floor-loading restrictions in high-rise building interiors. Japan's METI construction robot subsidies concentrate demand in Osaka Expo venue preparation where diesel emissions are banned.
- Crawler:Tracked platforms distribute weight across uneven debris fields for heavy reinforced-concrete applications. Germany's post-war infrastructure portfolio requires precision decommissioning where structural integrity uncertainties prohibit wheeled alternatives.
- Wheeled:Municipal infrastructure maintenance divisions in Japan and Germany deploy these for bridge-deck removal and overnight roadwork where traffic closure windows are compressed.
Remote-Controlled leads on scale; Mini leads on momentum.
End User:
Procurement authority and project risk allocation shape equipment specification and contracting terms.
- Construction Firms:Urban renewal contractors in Germany, Japan, and the United States are shifting from equipment ownership toward fleet leasing with guaranteed uptime clauses.
- Demolition Contractors:Specialized operators face workflow reconfiguration costs when integrating robotic units alongside conventional hydraulic breaker fleets on multi-phase projects.
- Municipalities:Public works departments in Japan pilot semi-autonomous perception systems for overnight infrastructure maintenance where traffic closure windows are compressed.
- Industrial Sites:Petrochemical and nuclear facilities mandate remote-controlled units with integrated dust suppression for confined-space decommissioning.
Demolition Contractors lead on scale; Municipalities lead on momentum.
Technology:
Powertrain selection balances emission constraints, energy density, and impact force requirements.
- Hydraulic:High-pressure fluid systems deliver 15-45 kW impact force for heavy reinforced-concrete applications. Precision valve and pump sourcing clusters in German and Japanese industrial districts, creating single-source vulnerability.
- Electric:Battery-powered units enable cord-free operation in enclosed building interiors where diesel emissions are prohibited. Lithium-ion cell price volatility compresses margins for manufacturers targeting this segment.
- Robotic:Semi-autonomous navigation with machine vision and LiDAR automates spatial mapping in cluttered interior environments where direct line-of-sight is obstructed.
- Pneumatic:Compressed-air systems serve specialized applications in explosive atmospheres where electrical ignition risks are prohibitive.
Hydraulic leads on scale; Electric leads on momentum.
Application:
Spatial constraints and debris composition dictate chassis selection and attachment configuration.
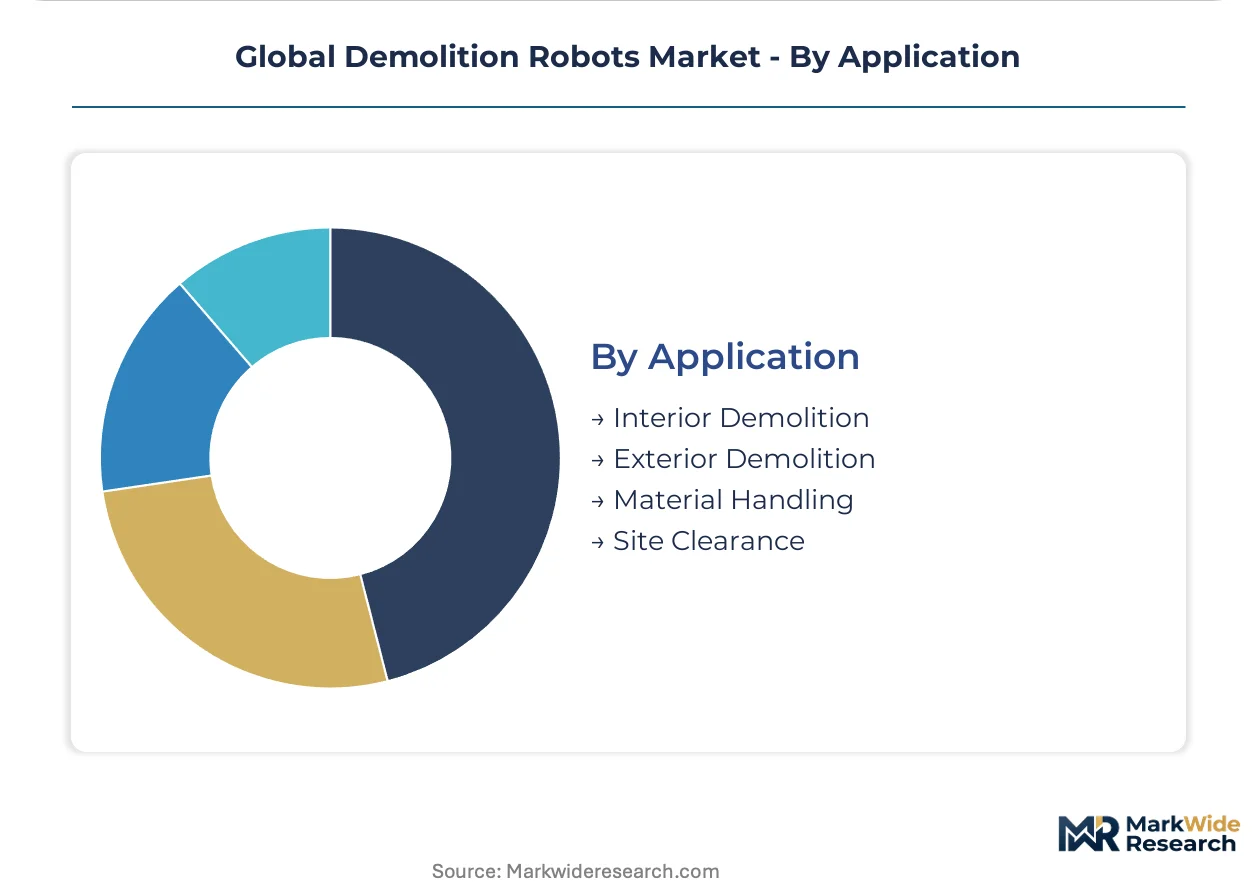
- Interior Demolition:Floor-loading constraints and spatial restrictions prevent conventional excavator deployment in high-rise building renovation. Demand concentrates in Germany, Japan, and the United States where aging commercial stock requires precision deconstruction.
- Exterior Demolition:Open-site applications accommodate larger crawler platforms for structural steel and reinforced concrete dismantling.
- Material Handling:Sorting attachments and downstream recycling documentation gain specification pull from EU embodied-carbon accounting requirements.
- Site Clearance:Post-demolition debris removal and site preparation for redevelopment.
Interior Demolition leads on scale; Material Handling leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor concentrates precision hydraulic component manufacturing for demolition robotics, with component suppliers clustered around Dortmund and Essen feeding assembly operations across Western Europe.
United States
Urban renewal contractors in Chicago, Detroit, and New York City are accelerating fleet procurement of remote-controlled demolition units. OSHA silica enforcement compresses acceptable human exposure windows for manual concrete breaking. Texas and California municipal infrastructure agencies pilot semi-autonomous systems for overnight bridge maintenance.
Germany
Post-war reinforced concrete infrastructure in North Rhine-Westphalia and Bavaria requires precision decommissioning where structural integrity uncertainties prohibit conventional mechanical demolition. EU Machinery Directive Category 3 safety mandates compel control architecture redesigns. Stuttgart and Munich host the dominant hydraulic valve and pump supplier clusters for European OEMs.
Japan
Osaka Expo 2025 venue preparation and subsequent legacy facility dismantling concentrate demand in the Kansai region. METI construction robot subsidies accelerate domestic procurement of compact electric units for diesel-restricted interiors. Tokyo and Nagoya metropolitan renewal zones exhibit the most advanced outcome-based deconstruction contracting models.
United Kingdom
Nuclear decommissioning programs at Sellafield and Dounreay mandate radiation-hardened teleoperation systems for confined-space dismantling. The Environment Agency's embodied-carbon reporting requirements for demolition waste create specification pull for material-sorting attachments. Manchester and Birmingham urban regeneration projects drive demand for floor-loading-constrained mini units.
India
Smart Cities Mission demolition requirements in Mumbai, Delhi, and Bangalore remain underserved by robotic solutions, presenting first-mover positioning opportunities for compact electric equipment. Central Pollution Control Board dust emission norms for construction sites tighten enforcement. Gujarat and Maharashtra industrial corridors host emerging distributor networks for imported demolition systems.
Global Demolition Robots Market Vendor Landscape
Global majors compete with regional champions across hydraulic component sourcing and safety certification pathways. The vendor base organizes around three tiers: integrated construction equipment conglomerates with captive demolition divisions, specialized robotics manufacturers focused on confined-space applications, and regional fabricators serving municipal maintenance markets. Dominant competitive moves include strategic partnerships for battery-electric powertrain integration and geographic expansion through distributor network acquisitions in underserved Asian markets.
Within the specialized robotics tier, Brokk and Husqvarna exemplify contrasting platform strategies—Brokk anchoring compact electric units for interior demolition while Husqvarna leverages power-tool distribution density for wheeled municipal applications. Hitachi Construction Machinery occupies a position among integrated conglomerates sustaining crawler-platform R&D intensity for heavy reinforced-concrete applications. STANLEY Infrastructure represents the attachment-specialist archetype, competing through hydraulic breaker integration rather than complete system manufacturing.
| Leading Market Players |
|---|
| Hitachi Construction Machinery |
| TopTec Benelux |
| Brokk |
| McCann Industries |
| Keman |
| Husqvarna |
| Conjet |
| SHERPA Mineloders |
| STANLEY Infrastructure |
| Others |
Supply Flow & Price Mechanics
Family-owned German hydraulic component specialists anchor tier-two supply channels, concentrating pricing power among integrated OEMs while compressing margins for electric-platform assemblers facing lithium-ion cell cost volatility.
Pricing Analysis
Input-cost pass-through from precision valve and pump sourcing clusters in Dortmund and Essen runs through hydraulic-system pricing, with three-tier pricing structure across premium CE-certified Category 3 systems, standard remote-controlled units, and economy-grade mini platforms. Price differentiation hinges on certification tier and after-sales service bundling. Cost compression in electric segments is intensifying because battery energy density improvements outpace cell price declines. Municipal fleet buyers exhibit highest price sensitivity; nuclear decommissioning contractors show lowest.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese hydraulic component districts feeding European and Asian assembly operations. Precision valve manufacturing draws from North Rhine-Westphalia and Nagoya industrial corridors, while lithium-ion cell supply rests on South Korean and Chinese producers. Tariff exposure on battery imports creates margin risk for electric-platform manufacturers. Distribution runs through OEM captive service networks and specialized demolition equipment distributors in metropolitan renewal zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in electric-platform segments where battery cost curves and METI subsidy eligibility create dual tailwinds for certified-system vendors.
For Market Incumbents: Hedge against hydraulic-component supply concentration by securing long-term valve and pump offtake agreements with Ruhr corridor suppliers or qualifying secondary Japanese sources. Defend position against Chinese electric-platform entrants by accelerating CE Category 3 certification for compact units targeting EU urban renewal. Vertical integration into battery pack assembly offers margin capture if cell supply stabilizes. For New Entrants and Emerging Players: OSHA silica enforcement in the United States opens a window for dust-suppression-integrated remote-controlled units in Chicago, Detroit, and New York City urban renewal corridors. India's Smart Cities Mission demolition requirements in Mumbai and Bangalore present first-mover positioning for compact electric platforms under 1.5 tons. Go-to-market through municipal fleet leasing partnerships with guaranteed uptime clauses transfers maintenance liability and accelerates reference-account acquisition. For Investors and Strategic Acquirers: Valuations sit cheapest among tier-two hydraulic component assemblers lacking captive demolition-robot OEM relationships. Long-term viability over the next decade favors specialists with certified-system portfolios spanning nuclear decommissioning and petrochemical retrofit applications. Watch METI subsidy renewal decisions and EU carbon-border adjustment implementation timelines as inflection indicators for electric-platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Platform Certification | CE Category 3 marking unlocks EU urban renewal procurement channels previously diesel-restricted. |
| Hydraulic Component Backward Integration | Captive valve manufacturing in Dortmund-Essen corridor insulates margins from single-source vulnerability. |
| Outcome-Based Deconstruction Contracting | Osaka Expo preparation projects specify debris-removal metrics rather than hourly equipment rental. |
| Semi-Autonomous Perception System Development | LiDAR-based obstacle detection automates overnight bridge-deck removal for Japanese municipal agencies. |
| Material-Sorting Attachment Integration | EU embodied-carbon accounting creates specification pull for recycling-documentation-enabled equipment vendors. |
Methodological Framework
Direct dialogue with demolition contractors, municipal fleet managers, nuclear decommissioning procurement officers, and hydraulic component manufacturing engineers grounded qualitative findings in operational workflow realities. Secondary validation drew from EU Machinery Directive certification databases, OSHA enforcement action records, METI subsidy program disclosures, and customs trade data on hydraulic valve imports. Bottom-up equipment shipment tallies and top-down construction expenditure flows were triangulated to anchor market sizing.
Bottom-up modeling segmented volume and value across product type, powertrain technology, application environment, and end-user procurement authority throughout the forecast period. CAGRs were derived from regression analysis against regulatory enforcement timelines and infrastructure replacement cycles. Industry-specific forecast inputs included silica exposure limit compliance deadlines and Osaka Expo venue preparation project schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium-ion supply disruption or accelerated EU carbon-border adjustment implementation. Projections reflect assumptions on METI subsidy continuity and OSHA enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Rotary Gripper Module Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Market
Robotics and Automation
Asia-Pacific Robotics and Automation Actuators Market
Robotics and Automation
North America Data Center Robotics Market
Robotics and Automation
Bionic Glove's Market
Robotics and Automation
Japan Articulated Robot Market
Robotics and Automation
Japan Cloud Robotics Market
Robotics and Automation
Eldercare-Assistive Robots Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
North America Service Robotics Market
Robotics and Automation
Global Soft Robotics Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market
Robotics and Automation
South America AUV Market
Robotics and Automation
Smart Worker Market