
 Short-Range Drone Package Delivery Market | 2026-2036
Short-Range Drone Package Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Short-Range Drone Package Delivery Market Analysis
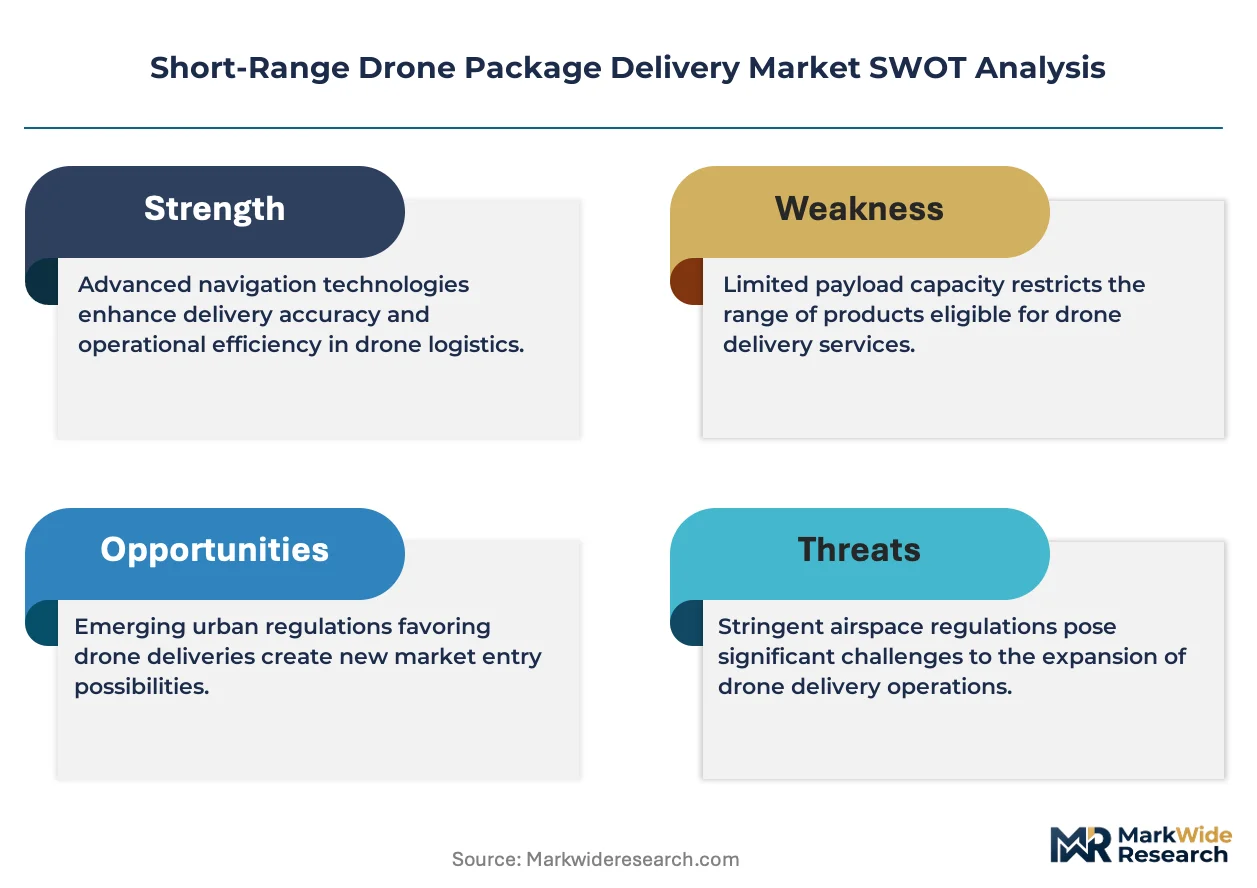
Modular payload configurations is hardening as the dominant buyer choice architecture, with operators configuring drone fleets around interchangeable delivery pods versus fixed-frame designs. Amazon.com Inc. leverages its captive logistics network to sustain vertically integrated drone operations from warehouse to doorstep. Wing Aviation LLC differentiates through regulatory-first market entry, securing operational approvals across multiple jurisdictions before scaling hardware deployment.
Short-range drone package delivery encompasses autonomous or remotely piloted unmanned aerial systems engineered for last-mile freight transport, typically operating within visual line-of-sight or extended visual line-of-sight parameters up to approximately 15 kilometers, utilizing electric multirotor or fixed-wing hybrid propulsion with payload bays rated from under 2 kg to over 10 kg. The primary commercial purpose centers on reducing per-package delivery cost and transit time in dense urban and suburban environments where ground congestion erodes conventional courier economics. Delivery Drones occupy the dominant revenue position among product types, though Surveillance Drones configured for delivery corridor monitoring represent an emerging adjacent revenue stream. Healthcare Providers constitute the fastest-growing end-user category as hospital networks and pharmaceutical distributors deploy temperature-controlled drone logistics for time-critical medical supplies.
The FAA's Part 135 certification framework and the EU's U-space regulatory package under EASA collectively shape airworthiness standards, pilot qualification requirements, and operational altitude ceilings that determine market access timelines across North America and Europe. China's CAAC drone traffic management trials and Australia's CASA beyond-visual-line-of-sight approvals add regulatory diversity that operators must navigate for multi-country fleet deployment. Stakeholders should monitor evolving noise ordinances and privacy litigation trends in municipal jurisdictions, as these localized constraints increasingly determine where drone corridors achieve sustainable community acceptance and operational density.
Market Dynamics
Modular payload architectures are compressing fleet refresh cycles across the short-range drone package delivery sector, forcing operators to abandon fixed-frame capital commitments in favor of interchangeable pod systems that adapt to shifting payload requirements.
Growth Catalysts
- FAA Part 135 Certification:The United States air carrier framework is accelerating commercial deployment timelines by establishing clear operational parameters for beyond-visual-line-of-sight flights in designated corridors.
- Healthcare Logistics Networks:Hospital systems and pharmaceutical distributors are deploying temperature-controlled drone infrastructure for time-critical medical supply chains, creating dedicated demand pools insulated from e-commerce volatility.
- Lithium-Silicon Battery Chemistry:Advanced cell architectures are extending flight endurance thresholds, enabling payload-range combinations that previously required fixed-wing platforms.
Market Restraints
- Aviation-Grade Component Concentration:Precision motor controllers and redundant flight computers rely on concentrated semiconductor fabrication capacity in East Asian foundries, exposing fleet operators to supply disruption risk.
- Municipal Noise Ordinances:Local jurisdictions across Australia and Germany are imposing decibel ceilings and curfew restrictions that constrain operational windows in dense suburban corridors.
- Ground-Based Courier Substitution:Electric cargo bicycles and micro-fulfillment centers offer comparable last-mile economics in urban cores below certain density thresholds, capping addressable market expansion.
Strategic Opportunities
- EU U-Space Regulatory Package:EASA's unified air traffic management framework is creating cross-border operational continuity that enables multi-country fleet deployment without jurisdiction-by-jurisdiction certification.
- Rural Healthcare Access:Underserved regions in Australia and the United States present white-space demand for medical supply drones operating outside ground infrastructure networks.
- Sensor-Fusion Navigation:Convergence of computer vision and differential GPS is enabling autonomous landing in unstructured environments without dedicated vertiport investment.
Industry Challenges
- Certified Remote Pilot Scarcity:FAA and EASA qualification requirements for commercial drone operators are outpacing training pipeline capacity, creating crew availability bottlenecks during fleet scaling phases.
- Legacy Warehouse Integration:Existing fulfillment center layouts and WMS architectures require retrofitting to accommodate autonomous aerial vehicle docking, charging, and payload handoff workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short-Range Drone Package Delivery Market |
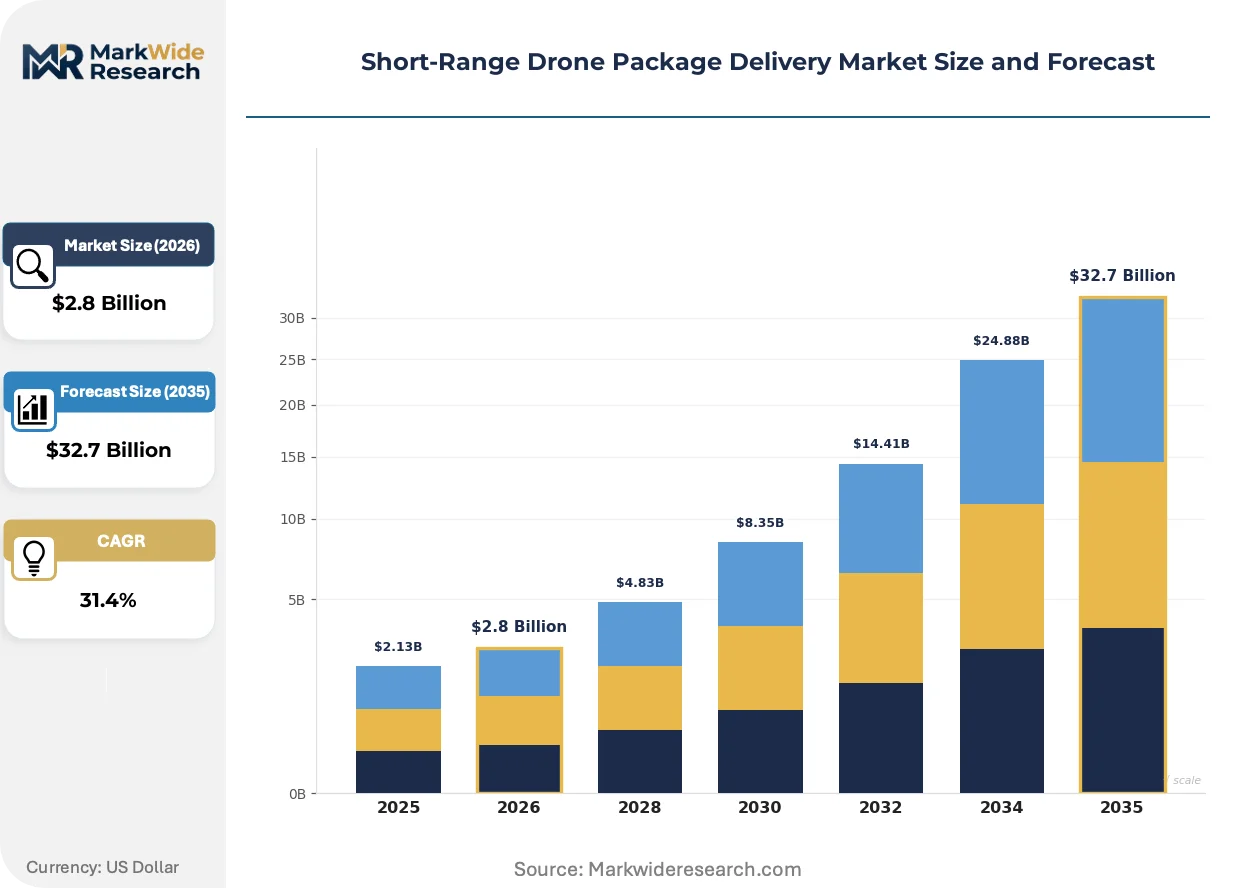
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $32.7 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Delivery Drones, Surveillance Drones, Agricultural Drones, Inspection Drones End User: Retailers, E-commerce Providers, Logistics Companies, Healthcare Providers Payload Capacity: Up to 2 Kg, 2 to 5 Kg, 5 to 10 Kg, Over 10 Kg Technology: GPS Navigation, Computer Vision, AI-Based Routing, Autonomous Flight |
| Companies Covered | Zipline International Inc., Wing Aviation LLC, Matternet Inc., Alphabet Inc., United Parcel Service Inc., Wingcopter, Flytrex Inc., Manna Drone Delivery, Amazon.com Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short-Range Drone Package Delivery Market Emerging Trajectories
Autonomous decision systems are displacing human-in-the-loop command structures across flight operations, compressing response latency and enabling density levels that manual oversight cannot sustain.
Multi-sensor perception stacks is integrating lidar, radar, and optical cameras into unified hazard detection architectures. Healthcare logistics operators in Germany are deploying these systems for autonomous landing at hospital helipads without ground-based infrastructure. The technology is integrating real-time obstacle avoidance with predictive path planning, enabling operations in GPS-denied urban canyons that previously required visual line-of-sight oversight.
EASA's U-space regulatory framework is mandating networked identification and geofencing capabilities for all commercial drone operations above specified mass thresholds. Industrial consequence includes forced retirement of legacy aircraft lacking broadcast remote identification modules. Logistics providers across the Netherlands, France, and Spain are consolidating fleet procurement around U-space-ready platforms to avoid stranded asset risk during the 2026 compliance deadline phase-in.
Hospital procurement departments are unbundling drone logistics from traditional courier contracts, creating direct vendor relationships with specialized aerial operators. This channel disintermediation is displacing incumbent ground-based freight forwarders from temperature-critical medical supply chains. The shift is most visible in Australian metropolitan networks, where state health systems are establishing dedicated aerial corridors linking pathology laboratories to regional treatment facilities.
Short-Range Drone Package Delivery Market Segmentation
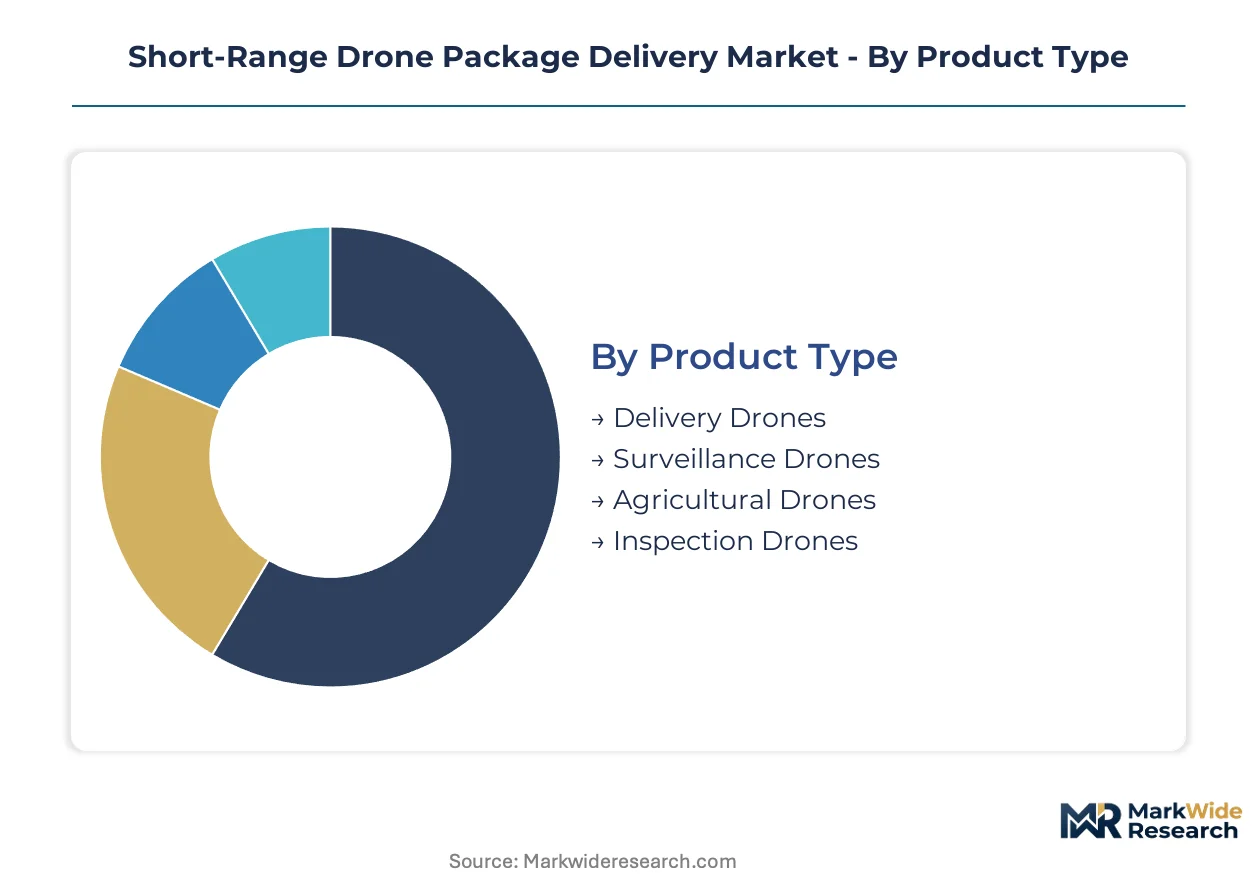
Segmentation in short-range drone package delivery reveals divergent capital requirements across hardware configurations and operational models. Payload capacity and technology architecture determine whether operators deploy commodity platforms or pursue bespoke certification pathways.
Product Type:
Capital intensity varies sharply across product categories, with multi-sensor platforms demanding substantially higher upfront investment than single-purpose airframes.
- Delivery Drones:Multirotor and fixed-wing hybrid platforms engineered for parcel transport with payload bays rated from 2 kg to over 10 kg. E-commerce providers in Germany and the United States are concentrating procurement around modular pod systems that adapt to shifting package profiles without fleet replacement.
- Surveillance Drones:Configured for delivery corridor monitoring with integrated optical and thermal sensors. Australian logistics operators deploy these systems for beyond-visual-line-of-sight oversight along designated urban airways where ground-based tracking proves inadequate.
- Agricultural Drones:Specialized crop-spraying and monitoring platforms with extended flight endurance. These units absorb limited share of package delivery capital budgets due to divergent airworthiness certification requirements.
- Inspection Drones:Deployed for infrastructure assessment along delivery routes, particularly in dense urban canyons where vertiport structural integrity requires regular verification.
Delivery Drones absorb the bulk of installed capacity; Surveillance Drones are expanding most quickly as corridor density mandates redundant monitoring layers.
End User:
Customer type dictates procurement scale and integration complexity, with healthcare networks presenting the steepest operational learning curves.
- Healthcare Providers:Hospital systems and pharmaceutical distributors deploying temperature-controlled logistics for time-critical medical supplies. German metropolitan health networks are establishing dedicated aerial corridors linking pathology laboratories to regional treatment facilities, insulating this demand from e-commerce volatility.
- E-commerce Providers:Vertically integrated operators controlling fulfillment-to-doorstep workflows. These buyers prioritize fleet standardization across multiple jurisdictions to simplify maintenance and pilot certification pipelines.
- Logistics Companies:Third-party courier services adding drone capacity to existing ground networks. Their procurement emphasizes interoperability with legacy warehouse management systems and last-mile handoff protocols.
- Retailers:Brick-and-mortar chains experimenting with store-to-customer delivery from micro-fulfillment locations. Capital deployment remains constrained by uncertain regulatory timelines in suburban municipalities.
E-commerce Providers command the largest fleet orders; Healthcare Providers are climbing the fastest as procurement departments unbundle aerial logistics from traditional courier contracts.
Payload Capacity:
Weight class determines motor specification, battery chemistry, and regulatory classification, with heavier thresholds triggering more stringent airworthiness scrutiny.
- 2 to 5 Kg:Dominant configuration for standard parcel delivery, accommodating the majority of e-commerce shipments without requiring enhanced structural certification. Operators in Australia concentrate procurement here to maximize fleet utilization rates across mixed package profiles.
- 5 to 10 Kg:Emerging category for consolidated multi-item orders and pharmaceutical batch shipments. Lithium-silicon battery advances are extending endurance thresholds for this weight class, previously the domain of fixed-wing platforms.
- Up to 2 Kg:Document and small-item delivery with minimal regulatory friction. Limited growth trajectory as payload economics favor consolidation into larger categories.
- Over 10 Kg:Specialized medical equipment and bulk pharmaceutical transport. FAA Part 135 certification requirements impose substantial compliance burdens that restrict this segment to established air carriers.
The 2 to 5 Kg bracket captures the majority of active fleet hours; 5 to 10 Kg platforms are gaining share fastest as battery technology compresses range-payload tradeoffs.
Technology:
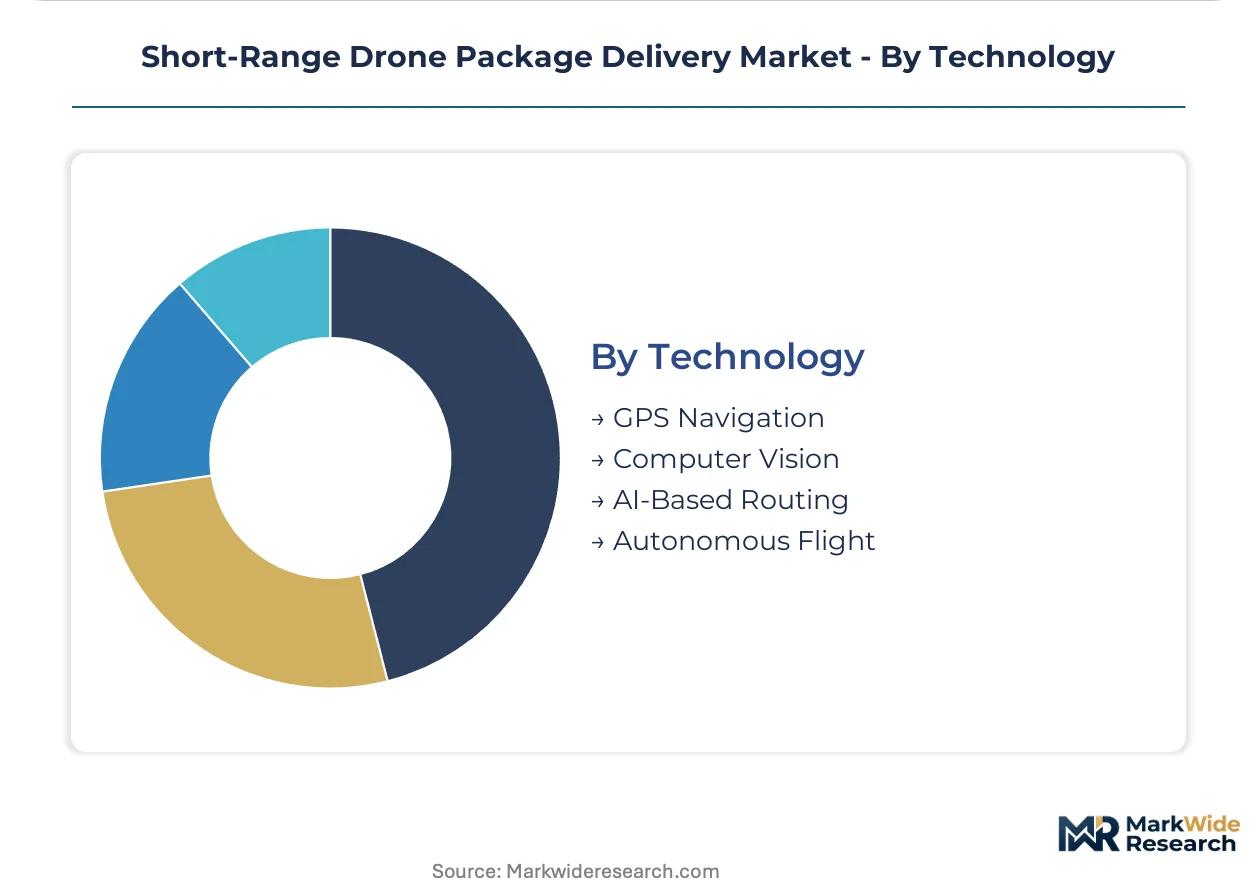
Navigation and autonomy architecture separates commodity hardware from defensible operational capabilities, with sensor fusion commanding premium pricing.
- Computer Vision:Optical camera arrays enabling real-time obstacle detection and precision landing in unstructured environments. German hospital operators deploy these systems for autonomous helipad approaches without dedicated ground infrastructure investment.
- Autonomous Flight:Fully automated mission execution without human-in-the-loop oversight. EASA's U-space framework is mandating networked identification capabilities that accelerate adoption of certified autonomous platforms across the Netherlands, France, and Spain.
- GPS Navigation:Standard differential positioning adequate for open-sky corridors. Incumbent technology facing displacement as urban canyon operations demand redundant sensor stacks.
- AI-Based Routing:Machine learning optimization of flight paths for weather, traffic, and energy consumption. Integration complexity limits deployment to operators with substantial software engineering capacity.
Computer Vision dominates current procurement budgets; Autonomous Flight is on the steepest expansion trajectory as regulatory frameworks mature and pilot scarcity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware manufacturing concentrates in Chinese industrial clusters while operational deployment and regulatory certification advance fastest in the United States, Germany, and Australia where airspace management frameworks have achieved operational maturity.
United States
E-commerce fulfillment networks and hospital logistics systems drive fleet procurement across Texas, California, and the Northeast Corridor. FAA Part 135 air carrier certification establishes clear operational parameters for beyond-visual-line-of-sight flights in designated urban corridors. Amazon.com Inc. anchors vertically integrated operations from warehouse to doorstep in the Seattle metropolitan cluster.
Germany
Healthcare networks and pharmaceutical distributors deploy temperature-controlled drone infrastructure for time-critical medical supply chains. EASA's U-space regulatory package mandates networked identification and geofencing capabilities for commercial operations above specified mass thresholds. Metropolitan health systems in Bavaria and North Rhine-Westphalia establish dedicated aerial corridors linking pathology laboratories to regional treatment facilities.
Australia
Rural healthcare access and suburban e-commerce fulfillment create dual demand pools for fleet operators. CASA beyond-visual-line-of-sight approvals enable corridor density in Queensland and New South Wales that ground-based tracking cannot sustain. Wing Aviation LLC secures operational approvals across multiple jurisdictions before scaling hardware deployment.
China
Domestic logistics operators trial last-mile aerial delivery in Shenzhen and Hangzhou metropolitan clusters. CAAC drone traffic management trials add regulatory diversity that operators must navigate for multi-country fleet deployment. Precision motor controller and redundant flight computer fabrication concentrates in East Asian foundries serving international fleet operators.
Short-Range Drone Package Delivery Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the short-range drone package delivery sector, creating a tiered structure where capital depth separates scalable platform operators from regional service providers. Technology conglomerates leverage captive cloud infrastructure and artificial intelligence development capacity to sustain vertically integrated operations. Logistics specialists concentrate procurement around modular pod systems that adapt to shifting package profiles without fleet replacement. The dominant competitive moves include regulatory-first market entry securing operational approvals across multiple jurisdictions, and strategic partnerships with healthcare networks establishing dedicated aerial corridors insulated from e-commerce volatility.
Within the technology conglomerate tier, Alphabet Inc. and Amazon.com Inc. exemplify divergent strategic postures toward captive logistics infrastructure. Zipline International Inc. and Matternet Inc. occupy specialist positions in healthcare logistics networks where temperature-controlled payload configurations and autonomous landing systems command premium positioning. United Parcel Service Inc. represents incumbent ground-based freight forwarders adapting legacy networks to accommodate aerial vehicle docking and charging workflows.
| Leading Market Players |
|---|
| Zipline International Inc. |
| Wing Aviation LLC |
| Matternet Inc. |
| Alphabet Inc. |
| United Parcel Service Inc. |
| Wingcopter |
| Flytrex Inc. |
| Manna Drone Delivery |
| Amazon.com Inc. |
| Others |
Supply Flow & Price Mechanics
Lithium-silicon battery cells flow from East Asian fabrication plants through three pricing tiers before reaching fleet operators, with aviation-grade semiconductor scarcity compressing margins at the mid-tier while premium autonomous platforms capture certification premiums.
Pricing Analysis
Cost-down pressure on mid-tier delivery platforms accelerates because semiconductor supply constraints force operators toward premium sensor-fusion architectures that command higher unit economics. Three-tier pricing structure across premium autonomous, standard remote-piloted, and economy visual-line-of-sight levels separates buyers by operational complexity and regulatory clearance. Healthcare networks show lowest price sensitivity due to temperature-controlled payload requirements and liability thresholds, while suburban e-commerce providers drive hardest bargain negotiations on per-delivery rates.
Supply Chain Analysis
Freight costs from Chinese precision motor controller foundries to German assembly facilities absorb disproportionate working capital as operators stockpile redundant flight computers against single-source vulnerability. Distribution runs through tier-one aerospace component distributors in Shenzhen, Singapore, and Hamburg before final integration at regional fleet depots. Semiconductor fabrication concentrates in Taiwan and South Korea, with lithium-silicon cell production anchored in China and Japan, exposing procurement pipelines to tariff exposure on aviation-grade electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over battery chemistry development and autonomous navigation software separates scalable platform operators from regional service providers dependent on third-party component sourcing.
For Market Incumbents: Lock in regulatory-first market entry by securing FAA Part 135 and EASA U-space operational approvals ahead of fleet scaling phases, while backward integration into lithium-silicon battery cell sourcing insulates against East Asian foundry concentration risk. Defensive patent positioning around sensor-fusion landing systems creates switching costs for healthcare network contracts. For New Entrants and Emerging Players: Hospital procurement departments unbundling aerial logistics from traditional courier contracts represent the most penetrable entry vector, particularly in Australian rural health networks and German metropolitan pathology laboratory corridors. White-space demand for temperature-controlled medical supply drones operating outside ground infrastructure networks offers first-mover positioning before incumbent fleet redeployment. For Investors and Strategic Acquirers: FAA Part 135 certification milestones achieved by specialized healthcare logistics operators are the leading indicator that regulatory arbitrage windows are closing and consolidation premiums will shift toward autonomous navigation software assets. Acquisition targets should concentrate on mid-cap specialists with proven beyond-visual-line-of-sight operational density in at least two jurisdictions, with sensor-fusion intellectual property as the primary value anchor.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory-First Market Entry | FAA Part 135 and EASA U-space approvals ahead of hardware deployment secure operational density in designated corridors. |
| Backward Integration into Battery Chemistry | In-house lithium-silicon cell development reduces exposure to East Asian semiconductor foundry concentration risk. |
| Healthcare Network Partnership | Dedicated aerial corridors linking pathology laboratories to regional treatment facilities insulate revenue from e-commerce volatility. |
| Autonomous Navigation Acquisition | Sensor-fusion software assets enable GPS-denied urban canyon operations without dedicated vertiport infrastructure investment. |
| Multi-Jurisdiction Fleet Standardization | Modular pod systems adaptable across FAA, EASA, and CASA regulatory frameworks simplify maintenance and pilot certification pipelines. |
Methodological Framework
Independent corroboration across fleet operations directors at Wing Aviation and Zipline International, regulatory affairs leads at FAA and EASA, and hospital procurement managers at Australian state health systems underwrites the qualitative findings. Primary interview data triangulates against secondary validation from FAA Part 135 certification filings, EASA U-space regulatory documentation, and CASA beyond-visual-line-of-sight approval records. Bottom-up fleet deployment estimates and top-down addressable market sizing converge across the analysis window.
Comparable-period anchoring to historical certification timelines and fleet deployment trajectories shapes the forecast framework across product type, end user, payload capacity, and technology architecture dimensions. Modeled CAGRs derive from segment-specific adoption curves for autonomous flight systems and healthcare logistics penetration rates, with lithium-silicon battery energy density improvements and municipal noise ordinance diffusion as key forecast inputs throughout the projection horizon.
Several conditions sit outside the modeled scope, including unanticipated regulatory reversals on beyond-visual-line-of-sight operations, breakthrough battery chemistries displacing lithium-silicon architectures, and municipal privacy litigation blocking corridor density in key suburban markets. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Delta Robots Market
Robotics and Automation
Robotics Software Platforms Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Global Security Robots Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
North America Data Center Robotics Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
Autonomous Polishing Machine Market
Robotics and Automation
Restaurant Delivery Robot Market
Robotics and Automation
Robot Market
Robotics and Automation
Underwater Rescue Robot Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
Global Wafer Handling Robots Market
Robotics and Automation
Robotics-Ready Fulfillment Center Design and Integration Services Market
Robotics and Automation
Wearable Robots and Exoskeletons Market