
 Europe Automated Liquid Handling Market | 2026-2036
Europe Automated Liquid Handling Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automated Liquid Handling Market Foresight
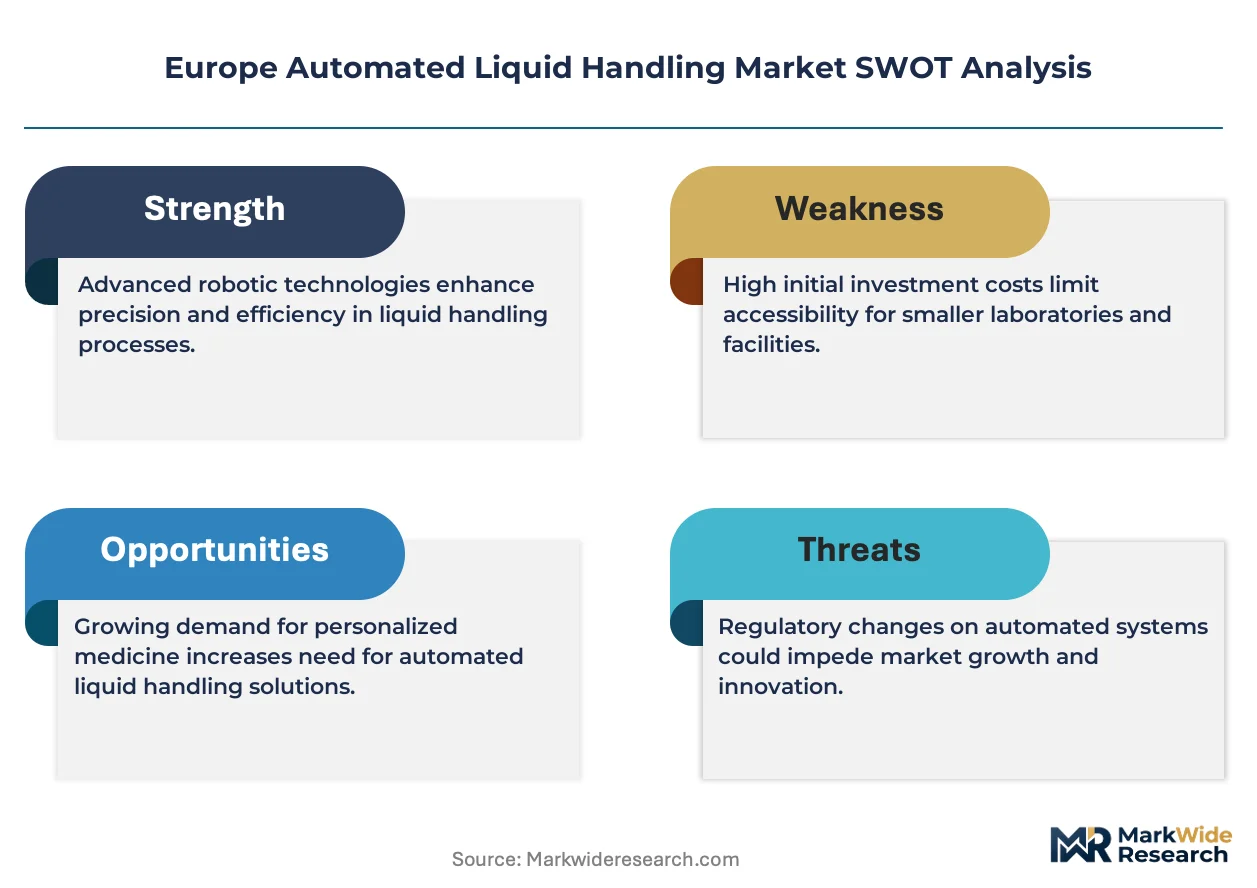
The capital-intensity divergence between high-throughput platform developers and modular workstation suppliers is reorganizing competitive tiers across the European landscape. Tecan Group leverages its integrated platform architecture to dominate large-scale pharmaceutical contracts in Basel and Munich. Hamilton Company sustains its position through precision syringe-drive technology leadership in clinical diagnostics applications.
Automated liquid handling encompasses electromechanical systems that transfer precise microliter-to-milliliter volumes through programmable pipetting, dispensing, and plate-handling operations, typically achieving accuracy within one percent coefficient of variation for volumes below ten microliters. These systems serve primarily to eliminate human error, accelerate throughput, and ensure reproducibility in quantitative laboratory workflows across drug discovery and molecular diagnostics. Robotic systems and integrated platforms command the largest installed base owing to their deployment in centralized pharmaceutical development facilities, while portable solutions represent the fastest-expanding delivery mode as point-of-care molecular testing decentralizes across European hospital networks. Genomic research applications generate premium margins due to the complexity of nucleic acid handling protocols, whereas environmental testing remains a price-sensitive segment served by tabletop configurations.
The EU In Vitro Diagnostic Regulation and Medical Device Regulation are elevating validation documentation requirements for clinical diagnostic liquid handlers, directly shaping procurement criteria across contract research organizations and hospital laboratories. EMA guidelines on bioanalytical method validation further constrain system selection for pharmaceutical development end users, favoring vendors with established quality management systems. REACH compliance for contact materials and electronics components adds a secondary compliance layer affecting platform design and supplier qualification. Stakeholders must weigh modular upgrade pathways against integrated platform lock-in as regulatory validation cycles lengthen and total cost of ownership calculations shift toward lifecycle compliance management.
Market Dynamics
The EU In Vitro Diagnostic Regulation is compressing validation timelines while pharmaceutical R&D clusters demand higher throughput, forcing vendors to reconcile modular flexibility with integrated platform compliance architecture.
Growth Catalysts
- EMA bioanalytical validation guidelines:Pharmaceutical developers in Basel and Munich now require liquid handlers with documented quality management systems, filtering procurement toward certified platform vendors.
- High-throughput screening workflows:Biotechnology firms across Germany are deploying robotic pipetting systems to compress compound screening cycles in early-stage drug discovery.
- Point-of-care molecular testing:Hospital networks in Switzerland and the United Kingdom are decentralizing nucleic acid diagnostics, creating demand for portable automated dispensing units.
Market Restraints
- Precision component supply concentration:Syringe-drive motors and optical sensors rely on specialized German and Swiss component suppliers, exposing lead times to single-source fragility.
- REACH compliance costs:Contact materials and electronics components require extensive substance documentation, elevating platform development overhead and supplier qualification burdens.
- Manual pipetting persistence:Small environmental testing laboratories continue using handheld systems for price-sensitive contaminant assays, capping automated penetration in this segment.
Strategic Opportunities
- Central and Eastern Europe expansion:Contract research organizations in Poland and the Czech Republic are building capacity without legacy platform investments, creating greenfield demand for mid-tier workstations.
- AI-assisted protocol optimization:Machine learning algorithms for liquid class detection and tip touch-off calibration are converging with robotic hardware, enabling self-optimizing platforms that reduce method development time.
- EU Green Deal procurement incentives:Public hospital tenders increasingly weight energy consumption and consumable waste reduction, favoring vendors with modular, upgradeable architectures over disposable-intensive alternatives.
Industry Challenges
- Cross-disciplinary talent scarcity:Field service engineers must combine mechanical troubleshooting with bioanalytical method validation knowledge, a skill intersection that commands premium compensation and extends hiring cycles.
- Legacy LIMS integration friction:Pharmaceutical facilities running decade-old laboratory information management systems face data format incompatibilities when connecting new liquid handlers, requiring costly middleware development.
- Extended MDR certification timelines:Clinical diagnostic liquid handlers now face eighteen-to-twenty-four-month conformity assessment periods, compressing product refresh cycles and straining R&D pipeline planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automated Liquid Handling Market |
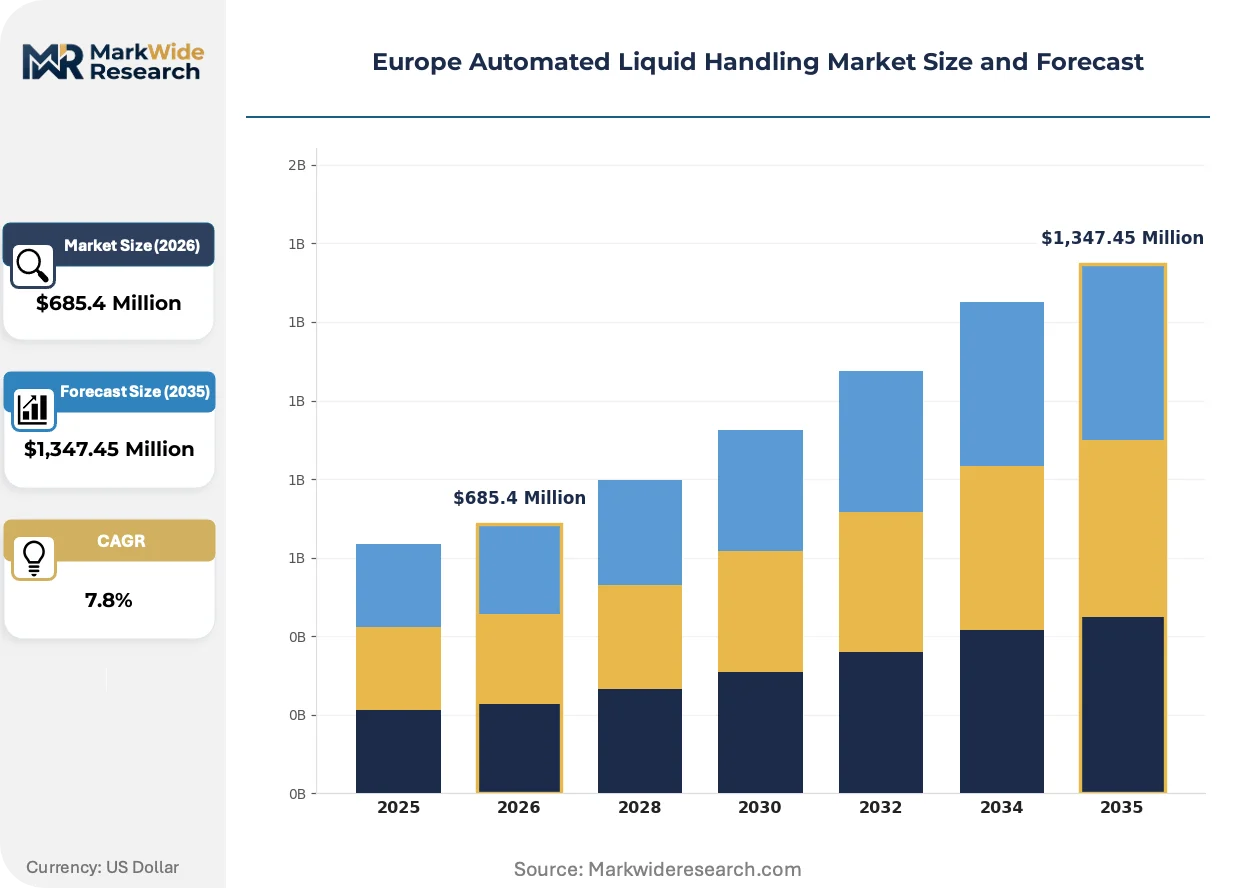
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,347.45 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Pipetting Workstations, Dispenser Modules, Automated Sample Handlers Application: Pharmaceutical Development, Clinical Diagnostics, Genomic Research, Environmental Testing End User: Biotechnology Firms, Academic Institutions, Contract Research Organizations, Clinical Labs Delivery Mode: Tabletop Systems, Integrated Platforms, Floor-Standing Units, Portable Solutions |
| Companies Covered | Tecan Group, Agilent Technologies, Thermo Fisher Scientific, Mettler-Toledo International, PerkinElmer, Eppendorf, QIAGEN, Corning, Hamilton Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automated Liquid Handling Market Shifts & Advancements
Electromechanical precision is converging with intelligent software control, reshaping how European laboratories balance throughput demands against regulatory documentation burdens and total cost of ownership calculations.
Acoustic droplet ejection technology is supplanting traditional tip-based pipetting in high-value genomic applications. Core facilities at Max Planck Institute and similar research centers in Germany are adopting acoustic dispensers to eliminate cross-contamination in nucleic acid workflows. This shift is compressing the addressable market for conventional robotic pipettors in premium segments while opening adjacent service revenue streams for calibration and liquid class library development.
REACH substance restrictions are forcing redesigns of contact materials in disposable tips and reagent reservoirs. Manufacturers must now document compliance for perfluorinated compounds and phthalate alternatives across complex multi-tier supply chains. Diagnostic platform vendors serving clinical laboratories face the steepest adaptation costs, as MDR technical documentation must incorporate updated material safety data sheets and biocompatibility testing protocols.
Leasing and reagent rental agreements are displacing capital purchase models in mid-sized contract research organizations. European CROs in the United Kingdom and Netherlands now prioritize per-run operational expenditure over upfront platform investment, pressuring vendors to unbundle hardware margins from consumable and service revenue streams. This financing evolution is most pronounced among genomics service providers scaling nucleic acid extraction capacity without balance sheet expansion.
Europe Automated Liquid Handling Market Segmentation
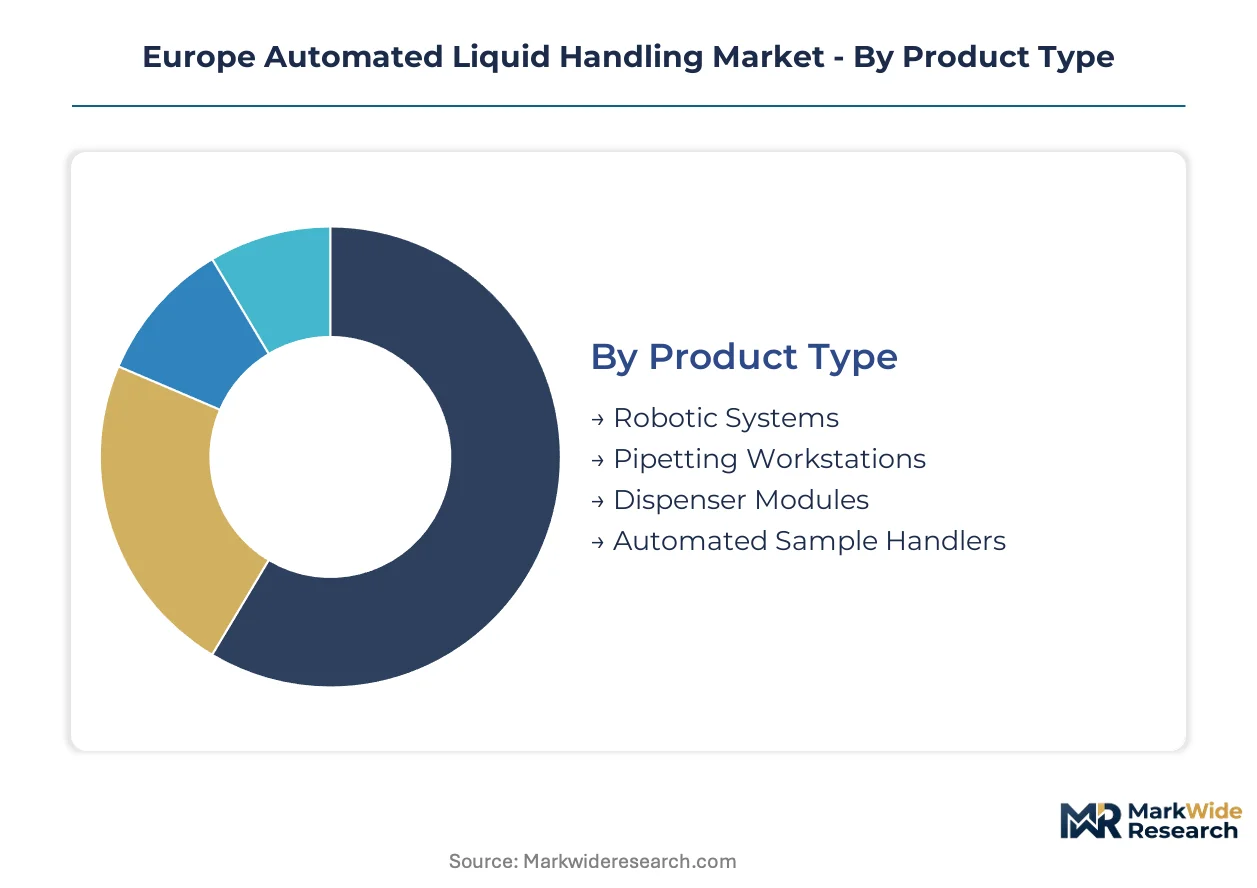
Segmentation in the Europe Automated Liquid Handling Market reveals distinct procurement patterns across pharmaceutical, diagnostic, and research end users. Each category channels hardware investment toward different performance tiers and compliance architectures.
Product Type:
Channel distribution varies sharply by product complexity, with integrated robotic systems flowing through direct vendor relationships while modular components penetrate via distributors.
- Robotic Systems:Multi-axis articulated arms with vision-guided tip positioning execute complex plate-handling sequences. Pharmaceutical development clusters in Basel and Munich deploy these platforms for high-throughput screening, driven by EMA bioanalytical validation requirements that favor documented quality management systems.
- Pipetting Workstations:Benchtop units with programmable liquid class libraries handle 96- and 384-well formats. Contract research organizations in the United Kingdom and Netherlands favor leasing models for these systems, compressing capital cycles into per-run operational expenditure.
- Dispenser Modules:Compact subsystems integrate into larger analytical workflows.
- Automated Sample Handlers:Pre-analytical processing units manage tube sorting and barcode verification.
By volume, Pipetting Workstations leads. By growth pace, Robotic Systems is ahead.
Application:
Margin structures diverge across applications, with genomic protocols commanding premium pricing for nucleic acid handling precision while environmental testing operates on constrained budgets.
- Pharmaceutical Development:Compound screening and ADME profiling demand sub-microliter accuracy with full audit trails. German biotechnology firms scale adoption to compress early-stage discovery timelines, though extended MDR certification cycles strain platform refresh planning.
- Genomic Research:Nucleic acid extraction and NGS library preparation require specialized liquid classes for viscous samples. Core facilities at Max Planck Institute and similar German centers are shifting toward acoustic droplet ejection to eliminate cross-contamination.
- Clinical Diagnostics:In vitro diagnostic workflows face tightening EU IVDR performance validation requirements.
- Environmental Testing:Contaminant assays in small laboratories persist with manual methods due to price sensitivity.
Pharmaceutical Development captures the largest revenue pool. Genomic Research posts the steepest expansion trajectory.
End User:
Procurement sophistication scales with organization size, from enterprise pharmaceutical quality systems to lean CRO operational expenditure models.
- Biotechnology Firms:Mid-cap drug developers in Germany and Switzerland prioritize modular upgrade pathways against integrated platform lock-in. These organizations balance high-throughput demands against lengthening regulatory validation cycles.
- Contract Research Organizations:European CROs in Poland and the Czech Republic represent greenfield demand without legacy platform investments, creating mid-tier workstation opportunity.
- Academic Institutions:Core facility budgets favor shared robotic platforms with multi-user scheduling software.
- Clinical Labs:Hospital networks in Switzerland and the United Kingdom decentralize molecular diagnostics, sourcing portable dispensing units.
Biotechnology Firms dominate absolute spend. Contract Research Organizations are expanding most quickly.
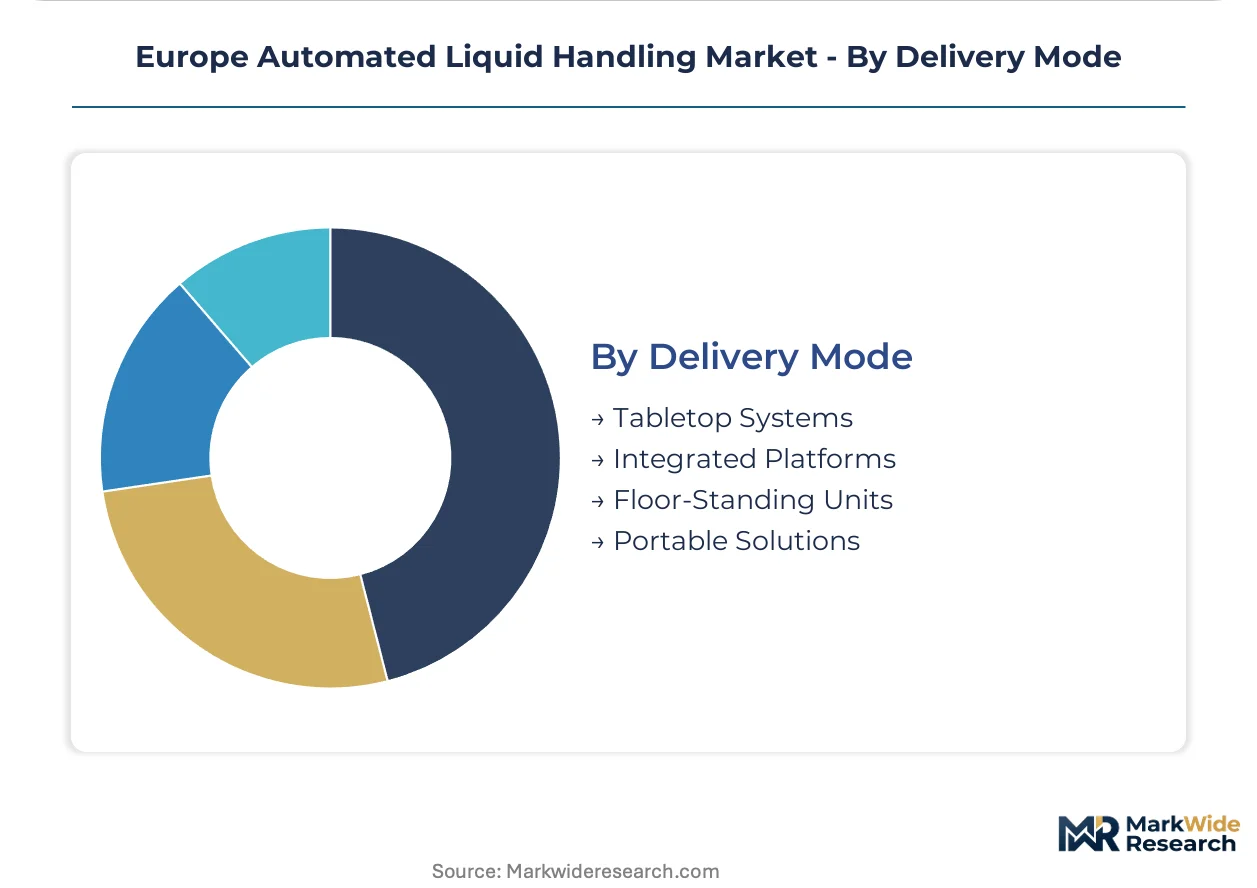
Delivery Mode:
Physical configuration determines deployment location, from centralized pharmaceutical facilities to distributed point-of-care settings.
- Integrated Platforms:Fully enclosed systems with robotic plate handling and environmental control anchor large-scale pharmaceutical contracts. Tecan Group leverages this architecture to dominate Basel and Munich procurement, though legacy LIMS integration friction adds middleware costs.
- Portable Solutions:Battery-operated units with wireless connectivity enable decentralized nucleic acid testing. Hospital networks across Switzerland and the United Kingdom drive demand as point-of-care molecular diagnostics expand.
- Tabletop Systems:Compact footprint units serve space-constrained environmental testing laboratories.
- Floor-Standing Units:High-capacity configurations support industrial-scale bioprocessing applications.
Integrated Platforms holds the installed base majority. Portable Solutions is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Central and Eastern Europe exhibit acute price sensitivity toward mid-tier workstations, while pharmaceutical clusters in Germany and Switzerland absorb premium pricing for validated integrated platforms without volume elasticity constraints.
Germany
Biotechnology firms in Munich and Heidelberg scale robotic pipetting systems for high-throughput screening workflows. EMA bioanalytical validation guidelines filter procurement toward vendors with documented quality management systems. The Max Planck Institute network anchors genomic research demand, shifting toward acoustic droplet ejection for nucleic acid protocols.
Switzerland
Basel's pharmaceutical development corridor commands premium automated platforms for compound screening and ADME profiling. Swissmedic oversight tightens performance documentation requirements for clinical diagnostic liquid handlers. Hospital networks in Zurich and Geneva decentralize molecular diagnostics, sourcing portable dispensing units for point-of-care deployment.
United Kingdom
Contract research organizations in Cambridge and Oxford prioritize leasing models that compress capital cycles into per-run operational expenditure. The Medicines and Healthcare products Regulatory Agency extends conformity assessment timelines for clinical diagnostic platforms. Genomics service providers scale nucleic acid extraction capacity without balance sheet expansion.
Poland
Contract research organizations in Warsaw and Kraków build greenfield capacity without legacy platform investments. EU funding programs accelerate laboratory infrastructure modernization across the region. Mid-tier workstation demand concentrates in emerging pharmaceutical service clusters seeking modular upgrade pathways.
Netherlands
Genomics service providers in Amsterdam and Rotterdam adopt reagent rental agreements to avoid upfront platform investment. The EU Green Deal shapes public hospital tender criteria, weighting energy consumption and consumable waste reduction. Leasing penetration exceeds regional averages among mid-sized CROs scaling nucleic acid workflows.
Europe Automated Liquid Handling Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision electromechanical specialists commanding premium positions while modular workstation suppliers compete on per-run economics. The vendor base organizes into three tiers: integrated platform architects serving centralized pharmaceutical facilities, precision component specialists dominating clinical diagnostics validation cycles, and mid-scale workstation fabricators capturing greenfield CRO demand. Consolidation pressure intensifies as extended MDR certification timelines favor incumbents with established quality infrastructure. Competitive moves center on modular architecture unbundling to capture leasing-oriented buyers and acoustic dispensing technology licensing to defend genomic research positioning.
Within the integrated platform tier, Tecan Group and Hamilton Company exemplify divergent specialization strategies. Tecan Group anchors large-scale pharmaceutical contracts through enclosed system architecture. Hamilton Company occupies the precision syringe-drive niche for clinical diagnostics applications. Agilent Technologies represents the diversified instrumentation conglomerate archetype, leveraging cross-portfolio bundling to penetrate mid-tier research accounts. These three players illustrate how vendor positioning stratifies across validation-intensive pharmaceutical development, compliance-driven clinical diagnostics, and price-sensitive contract research segments.
| Leading Market Players |
|---|
| Tecan Group |
| Agilent Technologies |
| Thermo Fisher Scientific |
| Mettler-Toledo International |
| PerkinElmer |
| Eppendorf |
| QIAGEN |
| Corning |
| Hamilton Company |
| Others |
Supply & Pricing Matrix
EU MDR and IVDR certification regimes gate both supplier qualification and price differentiation simultaneously, forcing vendors to absorb eighteen-to-twenty-four-month conformity costs while pharmaceutical buyers in Basel and Munich absorb premium pricing for validated platforms without volume elasticity.
Pricing Analysis
After-sales service contracts and consumable rental agreements now drive lifetime value capture, displacing upfront hardware margins across European CROs. Three-tier pricing structure across premium, standard, and economy levels separates EMA-validated integrated platforms from modular workstations and tabletop units. Cost compression in the mid-tier workstation segment is intensifying because Polish and Czech CROs prioritize per-run economics over capital deployment. Small environmental testing laboratories exhibit acute price sensitivity, while pharmaceutical development clusters in Germany and Switzerland show minimal elasticity for compliance-documented systems.
Supply Chain Analysis
Precision syringe-drive motor production in Germany and Switzerland creates a chokepoint that constrains platform assembly capacity across the continent. Optical sensor fabrication draws from specialized Bavarian and Swiss suppliers, while disposable tip molding rests on REACH-compliant polymer feedstocks sourced from Benelux and northern Italy. Single-source vulnerability in electromechanical component supply exposes lead times to disruption. Distribution runs through direct vendor relationships for integrated platforms and regional distributors for modular workstations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intersection of bioanalytical validation expertise and electromechanical field service capability is narrowing faster than training pipelines can replenish, creating persistent hiring bottlenecks that favor incumbents with established talent retention programs.
For Market Incumbents: Shield installed base relationships by embedding field service engineers within pharmaceutical development clusters in Basel and Munich, preempting substitution by acoustic droplet ejection vendors. Deepen backward integration into precision motor manufacturing to reduce exposure to German and Swiss component supplier concentration. Prioritize modular architecture roadmaps that accommodate EU Green Deal procurement weighting without triggering full revalidation cycles. For New Entrants and Emerging Players: Lead with AI-assisted protocol optimization software that reduces method development time for mid-tier CROs in Poland and the Czech Republic, avoiding direct hardware competition with entrenched platform vendors. Capture greenfield demand in Central and Eastern European contract research organizations by offering reagent rental agreements that mirror Netherlands leasing penetration. Deploy per-run pricing models that align with CRO operational expenditure preferences. For Investors and Strategic Acquirers: EU IVDR implementation reshapes the acquisition landscape by elevating quality management system documentation to primary due diligence criteria. Long-term viability hinges on vendors' capacity to sustain eighteen-to-twenty-four-month certification cycles without product refresh disruption. Target acquisition archetypes: precision component specialists with captive syringe-drive technology and established MDR technical files. Monitor EMA bioanalytical guideline revision timing as the critical inflection signal for platform replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Acoustic Dispensing Technology Licensing | Defends genomic research positioning against cross-contamination risks at Max Planck Institute facilities. |
| Modular Architecture Unbundling | Captures leasing-oriented CRO buyers in Cambridge and Oxford through per-run operational expenditure models. |
| REACH-Compliant Material Redesign | Enables continued EU market access as ECHA restrictions tighten on perfluorinated compounds in disposable tips. |
| AI-Assisted Liquid Class Detection | Reduces method development burden for biotechnology firms scaling high-throughput screening workflows. |
| Field Service Engineer Embedding | Locks in pharmaceutical contracts in Basel through direct bioanalytical validation support relationships. |
Research Methodology
Cross-validation between primary interviews with platform engineers, field service directors, and CRO procurement managers and secondary validation through EMA bioanalytical guidance documents, MDR technical file databases, and EU funding program disclosures anchors the qualitative findings. Bottom-up triangulation from installed base estimates and top-down validation from vendor revenue disclosures frame the quantitative boundaries.
Sensitivity analysis across the projection horizon tests demand elasticity for integrated platforms versus modular workstations under varying IVDR implementation timelines. Segmentation dimensions modeled include product architecture complexity, application protocol precision requirements, end-user organization scale, and regional regulatory cluster stringency. CAGRs derive from compound growth rate fitting across historical adoption curves and projected replacement cycles, incorporating nucleic acid testing decentralization rates and pharmaceutical R&D cluster expansion as industry-specific inputs.
Forecasts assume regulatory continuity in EU MDR, IVDR, and REACH enforcement regimes; material policy shifts would require re-modeling. Specific risk factors include extended conformity assessment timeline variability and acoustic droplet ejection substitution acceleration in genomic research. Practitioners should keep alternative scenarios live as EMA bioanalytical guideline revision timing and EU Green Deal procurement weighting evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Nanorobots in Healthcare Market
Robotics and Automation
Global Automotive Gesture Recognition System Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
Microsurgery Robot Market
Robotics and Automation
Deep Sea Robot Market
Robotics and Automation
Global Molecular Robotics Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
Agricultural Robots Market
Robotics and Automation
Disinfectant Robot Market
Robotics and Automation
APAC Robotic Process Automation (RPA) Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
Global Enterprise Robotic Process Automation Market
Robotics and Automation
Robot As a Service Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
AGV & AMR in Logistics Market
Robotics and Automation
Non-Medical Biomimetic Robots Market