
 Consumer and Office Robot Market | 2026-2036
Consumer and Office Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer and Office Robot Market Analytics
Aftermarket service revenue is tilting from hardware replacement toward software subscription and predictive maintenance contracts. iRobot Corporation leverages its installed base of autonomous vacuum systems to sustain recurring revenue through digital mapping services. Samsung Electronics anchors its position through in-house production of AI chipsets that power companion and security robot lines. ECOVACS Robotics differentiates by controlling direct-to-consumer channels across Asia and Europe.
Consumer and office robots encompass electromechanical systems integrating sensors, actuators, and embedded intelligence to perform physical tasks in domestic and workplace environments, typically operating on battery power with navigation accuracy within centimeter-scale tolerances. These machines serve commercial purposes spanning sanitation automation, perimeter monitoring, material transport, and human interface assistance. Vacuum bots and autonomous lawn mowers occupy the most mature margin pools where manufacturing scale drives cost compression, while delivery robots and AI-powered inventory management systems represent the fastest-expanding segments as small businesses and corporations deploy fleet-based logistics solutions. IoT-enabled functionality is deepening data monetization opportunities across all product categories.
The EU AI Act and CE marking requirements under the Machinery Directive are reshaping product standards for autonomous navigation systems sold in Europe, forcing redesign cycles for collision-avoidance algorithms. The US Federal Communications Commission regulates wireless communication protocols in connected robots, while China's Ministry of Industry and Information Technology enforces GB standards for battery safety and electromagnetic compatibility. Stakeholders must monitor how divergent certification timelines across these jurisdictions affect go-to-market sequencing and localization costs.
Market Dynamics
The Consumer and Office Robot Market is experiencing fundamental restructuring as Shenzhen's hardware ecosystem compresses prototyping cycles and manufacturing costs, while the EU AI Act forces algorithmic transparency redesigns across autonomous navigation systems.
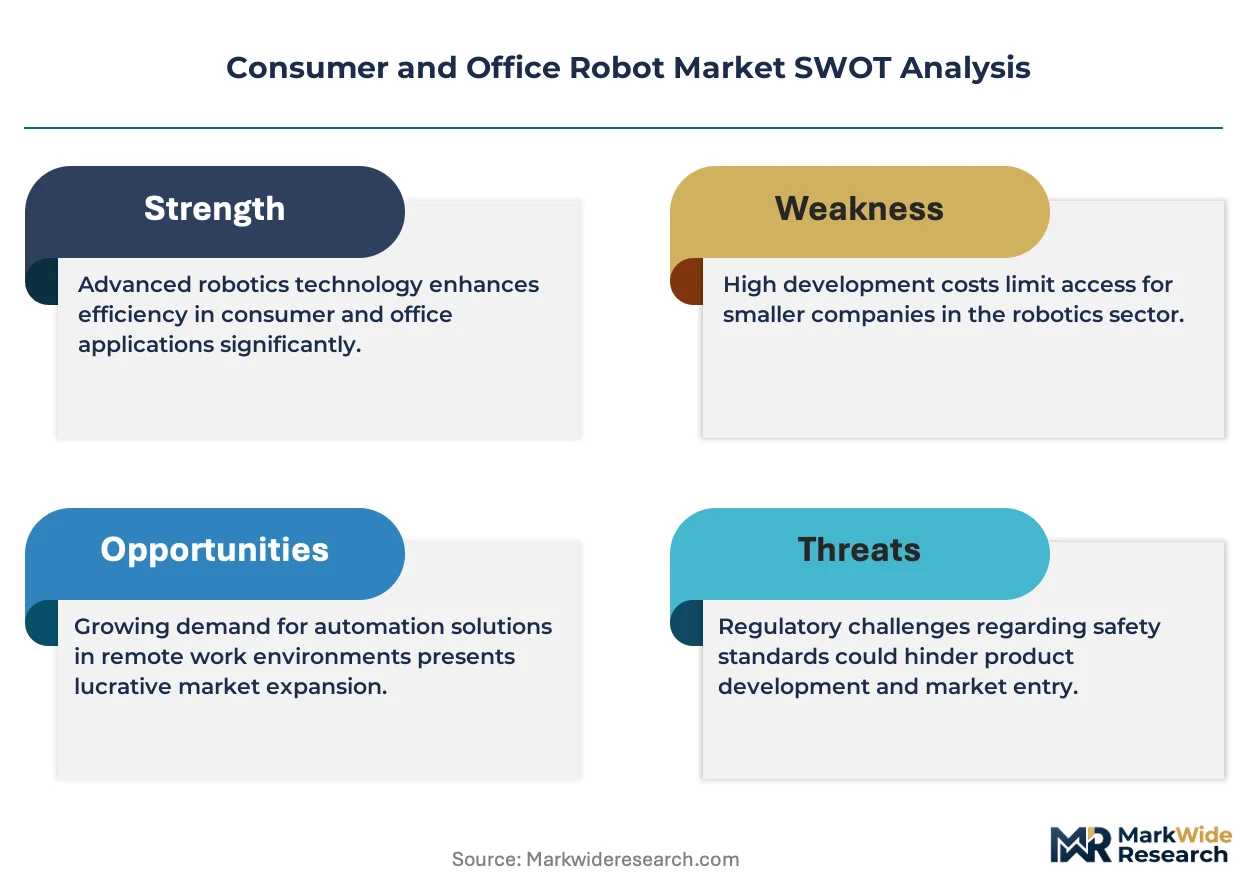
Growth Catalysts
- Algorithmic Transparency Mandates:The EU AI Act creates compliance-driven replacement cycles for legacy collision-avoidance systems. European distributors now prioritize certified autonomous platforms.
- Inventory Robotics:Small businesses across logistics and retail verticals deploy fleet-based material transport systems to offset warehouse labor constraints.
- Shenzhen Manufacturing Cluster:China's hardware ecosystem accelerates commercial robot prototyping and enables cost-efficient scaling of sensor-integrated platforms.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production concentrates in East Asian supply chains, exposing robot OEMs to input cost volatility and logistics bottlenecks.
- CE Marking Complexity:The Machinery Directive and EU AI Act impose divergent certification timelines across European member states, delaying product launches.
- Humanoid Substitutes:Low-cost telepresence platforms and remote-operated systems threaten price positioning of fully autonomous office assistants.
Strategic Opportunities
- Predictive Maintenance Contracts:IoT-enabled functionality allows vendors to monetize installed bases through software subscriptions rather than hardware replacement cycles.
- India Warehouse Automation:Underpenetrated logistics infrastructure and labor cost pressures create first-mover advantages for inventory management robot deployments.
- GB Standard Harmonization:China's MIIT battery safety and electromagnetic compatibility frameworks may accelerate regional certification mutual recognition.
Industry Challenges
- SLAM Engineering Scarcity:Simultaneous localization and mapping expertise remains concentrated among robotics specialists, constraining product development velocity.
- Legacy System Integration:Enterprise buyers demand API compatibility with existing warehouse management software, complicating go-to-market technical requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer and Office Robot Market |
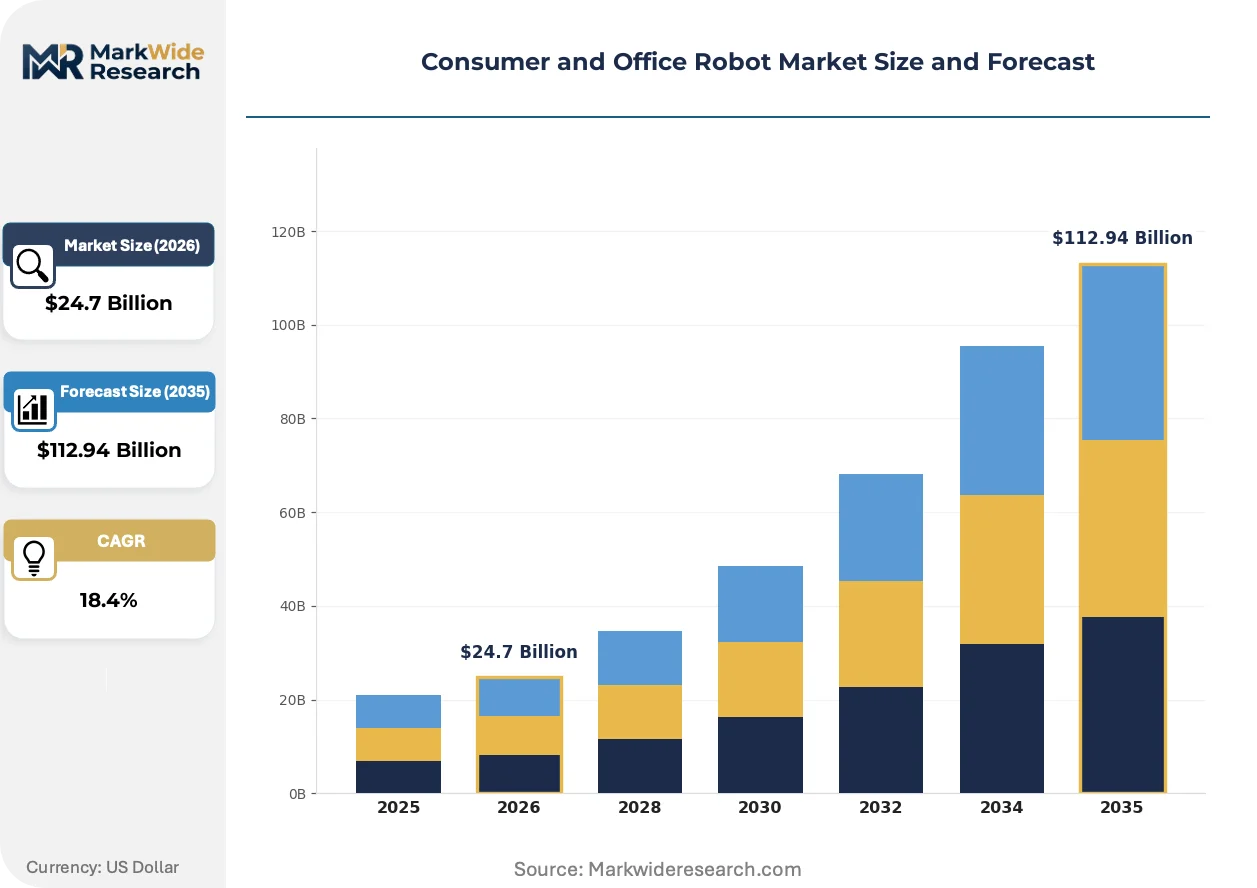
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $112.94 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Bots, Lawn Mowers, Companion Robots, Delivery Robots End User: Households, Small Businesses, Corporations, Educational Institutions Functionality: Cleaning, Security, Assistance, Inventory Management Technology: AI-Powered, Remote-Controlled, Autonomous, IoT-Enabled |
| Companies Covered | iRobot Corporation, Samsung Electronics, ECOVACS Robotics, Roborock Technology, LG Electronics, DJI Technology, Xiaomi Corporation, Robert Bosch GmbH, Maytronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer and Office Robot Market Evolving Landscape
Edge AI deployment and modular sensor architectures are compressing development timelines while regulatory divergence forces parallel certification tracks. Three developments merit particular attention.
Multimodal sensor fusion is collapsing the cost-performance tradeoff for navigation accuracy. Autonomous vacuum and lawn care OEMs now integrate LiDAR, visual SLAM, and tactile arrays at price points previously reserved for camera-only systems. The technology is collapsing differentiation between premium and mid-tier product tiers.
The EU AI Act's risk-based classification system imposes documentation burdens on autonomous decision-making algorithms. European robot vendors must now maintain technical files for collision-avoidance neural networks. Delivery robot fleets face the steepest compliance costs due to human proximity operating environments.
Small business buyers now favor robot-as-a-service contracts over capital purchases. Equipment financiers and OEM captive leasing units displace traditional distributor channels in warehouse automation. The shift is most visible in Germany's Mittelstand manufacturing sector, where monthly subscription models reduce balance sheet impact.
Consumer and Office Robot Market Segmentation
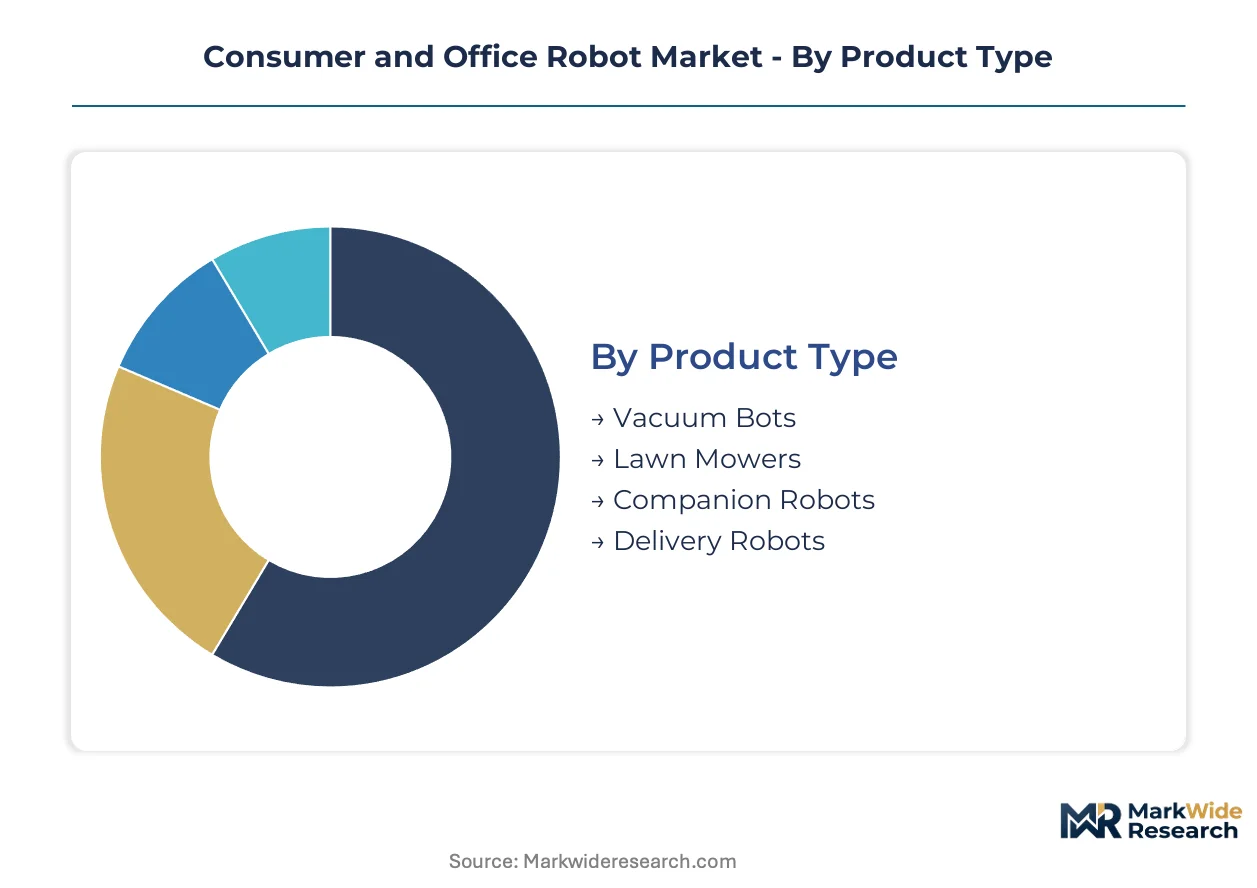
Segmentation in the Consumer and Office Robot Market reveals divergent replacement cycles and margin structures. Vacuum bots and lawn mowers operate on 3-5 year refresh timelines, while delivery and inventory systems compress to 18-24 months as software capabilities obsolete hardware faster.
Product Type:
Vacuum bots and lawn mowers turn inventory slowest with multi-year ownership horizons, whereas delivery robots and companion systems cycle faster as AI capabilities leapfrog hardware generations.
- Vacuum Bots:Lidar-visual SLAM fusion enables centimeter-grade navigation across floor plans. Demand clusters in German and Japanese households where aging demographics and dual-income constraints automate domestic maintenance. These systems anchor aftermarket revenue through mapping data subscriptions.
- Lawn Mowers:Boundary-wire and GPS-RTK variants dominate, with wire-free perimeter systems gaining traction in suburban US markets. Weather-sealed chassis and blade durability determine replacement timing, stretching typical ownership beyond five years in temperate climates.
- Companion Robots:Social interaction platforms integrate voice recognition and emotional response algorithms for eldercare and pediatric applications.
- Delivery Robots:Last-mile autonomous platforms face steep EU AI Act compliance costs due to human-proximity operating environments.
Vacuum bots dominate installed base. Delivery robots are where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive corporate deployments from subscription-accessible small business models, with educational institutions occupying a distinct procurement channel.
- Households:Direct-to-consumer channels and retail partnerships move price-sensitive volume, with premium tiers commanding 3x multiples for pet-hair specialization and self-emptying docks.
- Small Businesses:Robot-as-a-service contracts displace capital purchases in warehouse automation, particularly across Germany's Mittelstand manufacturing sector where monthly subscriptions reduce balance sheet impact.
- Corporations:Fleet-scale logistics deployments demand API compatibility with existing warehouse management software, complicating vendor selection and elongating sales cycles.
- Educational Institutions:STEM-focused procurement favors programmable platforms with open SDK access for curriculum integration.
Households anchor volume. Small businesses are climbing the fastest.
Functionality:
Application maturity varies sharply, with cleaning automation commoditized while inventory management commands premium pricing for SLAM engineering scarcity.
- Cleaning:Suction optimization and mopping integration have saturated differentiation, compressing margins toward sensor and motor component costs.
- Security:Perimeter monitoring robots combine thermal imaging with acoustic gunshot detection for corporate campuses and critical infrastructure.
- Assistance:Human interface platforms serve mobility-impaired users and reception automation in high-traffic commercial lobbies.
- Inventory Management:Autonomous mobile robots navigate warehouse aisles for cycle counting and restocking, with demand surging in India's underpenetrated logistics infrastructure.
Cleaning dominates installed base. Inventory management is where expansion concentrates.
Technology:
Customer type separates early adopters seeking AI-native platforms from cost-optimized buyers accepting remote-controlled or basic autonomous systems.
- AI-Powered:Neural network-driven decision-making requires technical file maintenance under EU AI Act risk classification, particularly for collision-avoidance algorithms in delivery applications.
- Remote-Controlled:Telepresence platforms threaten price positioning of fully autonomous office assistants through lower capital requirements and reduced regulatory exposure.
- Autonomous:SLAM-based navigation operates without continuous operator input, constrained by engineering talent concentration among robotics specialists.
- IoT-Enabled:Connectivity enables predictive maintenance contracts and data monetization, shifting vendor revenue from hardware replacement toward software subscriptions.
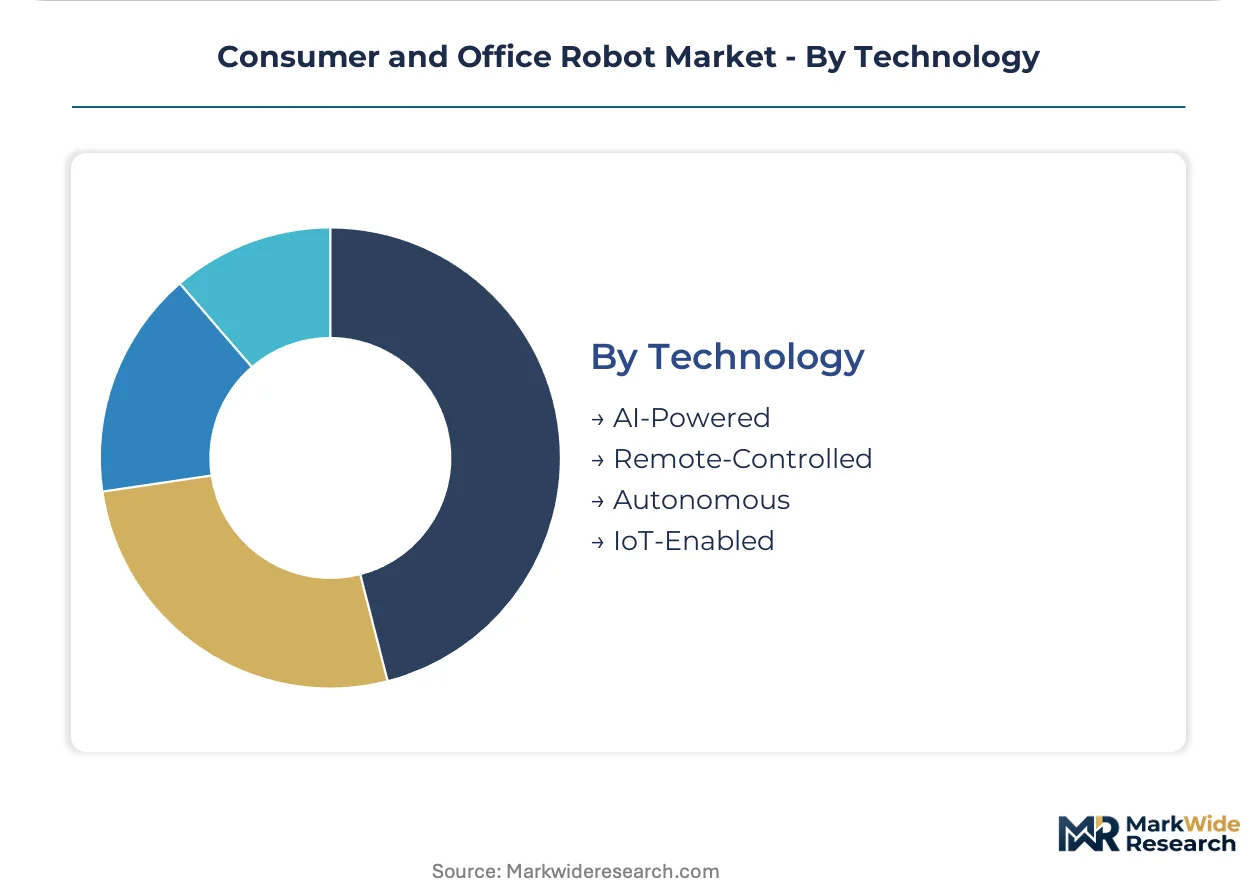
Autonomous systems dominate installed base. AI-powered platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Robot OEMs face divergent certification timelines across three major jurisdictions. Shenzhen's hardware ecosystem compresses prototyping cycles while the EU AI Act forces algorithmic transparency redesigns.
China
Shenzhen's Pearl River Delta cluster accelerates commercial robot prototyping through integrated sensor supply chains and contract manufacturing at scale. MIIT enforces GB standards for battery safety and electromagnetic compatibility that shape product design for domestic and export markets. The Yangtze River Delta region hosts autonomous mobile robot testing facilities serving warehouse automation demand.
Germany
Germany's Mittelstand manufacturing sector drives robot-as-a-service adoption for inventory management through monthly subscription models that reduce balance sheet impact. CE marking under the Machinery Directive and EU AI Act compliance requirements impose documentation burdens on collision-avoidance neural networks. Bavaria anchors industrial robot development with Stuttgart's automotive supply chain demanding fleet-scale logistics integration.
United States
US small businesses deploy delivery robots and autonomous vacuum systems through equipment financiers displacing traditional distributor channels. The FCC regulates wireless communication protocols in connected robots affecting product certification timelines. California's Silicon Valley concentrates SLAM engineering talent while Texas hosts warehouse automation pilot programs for logistics operators.
Japan
Japan's aging demographics and dual-income household constraints automate domestic maintenance through vacuum bot demand clustering in metropolitan Tokyo and Osaka. METI oversees industrial robot standards while JIS frameworks shape product safety requirements. Nagoya's Chubu region maintains precision manufacturing capabilities for sensor-integrated platforms.
India
India's underpenetrated logistics infrastructure and labor cost pressures create first-mover advantages for inventory management robot deployments in Maharashtra and Karnataka. BIS certification requirements and DGFT import regulations affect hardware sourcing strategies. The Delhi-NCR corridor hosts early warehouse automation pilots serving e-commerce fulfillment networks.
Consumer and Office Robot Market Competitive Landscape
Electronics conglomerates and pure-play robotics specialists split the market along vertical integration fault lines. The vendor base concentrates around three strategic archetypes: in-house semiconductor producers leveraging captive chip supply, direct-to-consumer channel operators controlling Asia-Europe distribution, and installed-base monetizers pivoting from hardware to software subscriptions. Competitive moves center on backward integration into AI chipsets and predictive maintenance contract expansion.
Within the installed-base monetization tier, iRobot Corporation exemplifies the pivot toward digital mapping service revenue. Samsung Electronics anchors the vertical integration archetype through in-house AI chipset production. ECOVACS Robotics occupies the direct-to-consumer channel position across Asian and European markets.
| Leading Market Players |
|---|
| iRobot Corporation |
| Samsung Electronics |
| ECOVACS Robotics |
| Roborock Technology |
| LG Electronics |
| DJI Technology |
| Xiaomi Corporation |
| Robert Bosch GmbH |
| Maytronics |
| Others |
Value Network & Pricing Analysis
East Asian lithium-ion cell manufacturing concentrates upstream supply leverage, anchoring margin pools in predictive maintenance software subscriptions and algorithmic transparency certification tiers rather than hardware assembly.
Pricing Analysis
Aftermarket service contracts now drive lifetime value across the installed base. Three-tier pricing structure across premium, standard, and economy levels separates AI-native SLAM systems from remote-controlled alternatives, with EU AI Act compliance costs widening the gap. Price erosion runs through mid-tier vacuum bots as Shenzhen manufacturing compresses sensor costs. Small businesses exhibit highest price sensitivity, favoring robot-as-a-service subscriptions over capital purchases, while corporate fleet buyers prioritize API compatibility over unit economics.
Supply Chain Analysis
Export-control regimes on advanced LiDAR sensors and AI accelerators limit technology flows between US and Chinese entities. Battery cell production draws from China, South Korea, and Japan, with sensor module assembly concentrated in Shenzhen's Pearl River Delta. Single-source vulnerability in solid-state LiDAR emitters threatens delivery robot OEMs. Distribution runs through direct-to-consumer channels in Asia and equipment financiers in Germany's Mittelstand sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive advantage as robot-as-a-service models displace transactional hardware sales, with API interoperability determining ecosystem lock-in across warehouse management software stacks.
For Market Incumbents: Harden installed-base monetization through predictive maintenance contracts and digital mapping service tiers. Deepen backward integration into AI chipsets to reduce exposure to export-control volatility. Prioritize CE marking and EU AI Act technical file maintenance to defend European channel position against compliance-weak challengers. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated warehouse automation sector where labor cost pressures outpace incumbent coverage. Target small business robot-as-a-service contracts through equipment leasing partnerships rather than distributor networks. Lead with open SDK platforms to capture educational institution procurement channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed warehouse automation specialists holding fleet-scale logistics contracts. Five-to-ten year viability hinges on software subscription conversion rates exceeding hardware replacement cycles. Monitor EU AI Act enforcement variance across member states as inflection indicator for compliance-cost arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contract Expansion | iRobot's mapping data subscriptions demonstrate recurring revenue conversion from hardware bases. |
| AI Chipset Backward Integration | Samsung's captive semiconductor production insulates margin from sensor supply volatility. |
| Direct-to-Consumer Channel Control | ECOVACS's Asia-Europe distribution bypass reduces intermediary cost extraction. |
| EU AI Act Compliance Investment | Technical file maintenance for collision-avoidance algorithms secures European market access. |
| Robot-as-a-Service Platform Launch | Germany's Mittelstand manufacturing sector adopts monthly subscriptions to reduce balance sheet impact. |
Research Methodology
A standing panel of robotics OEM product managers, warehouse automation procurement leads, SLAM engineering directors, and equipment leasing underwriters provided ongoing calibration. Primary interviews combined with secondary validation from MIIT GB standard filings, FCC equipment authorization databases, EU AI Act technical documentation, and Shenzhen customs export records. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing.
Scenario-bracketing framed projections across the analysis window, modeling product type segments including vacuum bots, lawn mowers, delivery robots, and inventory management systems alongside end user tiers and technology categories. CAGRs derived from logistic diffusion curves fitted to replacement cycle data and software capability obsolescence rates. Forecast inputs incorporated EU AI Act implementation timelines and Shenzhen manufacturing cost compression trajectories.
Stress conditions across lithium-ion supply volatility, CE marking approval delays, and SLAM engineering talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding algorithmic transparency enforcement and hardware ecosystem maturation. Material shifts in export-control regime stringency or battery chemistry substitution would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Inspection Robots Market
Robotics and Automation
UV-C Disinfection Robots Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
North America Service Robotics Market
Robotics and Automation
Smart Curtain Robot Market
Robotics and Automation
Cloud Robotics Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
South America Agricultural Robots and Mechatronics Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
Medical Rehabilitation Robotics Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Asia-Pacific Logistics Robotics Market
Robotics and Automation
Assistive Robotics Market
Robotics and Automation
North America Underwater Robotics Market
Robotics and Automation
Healthcare Robots Market